
 United States Flat Glass Market | 2026-2036
United States Flat Glass Market Size, Share, and Industry Trends Forecast 2026-2036
United States Flat Glass Market Intelligence
Low-iron silica sand is restructuring product economics across the United States flat glass value chain as solar-grade specifications displace conventional architectural formulations. Guardian Glass leverages backward integration into raw material beneficiation to sustain cost discipline at scale. Cardinal Glass Industries anchors its position through captive float lines dedicated to high-performance residential fenestration. Viracon specializes in oversized heat-treated units for commercial tower facades, occupying a premium niche that competitors struggle to replicate.
United States flat glass denotes soda-lime silica sheets manufactured through the float process, typically ranging from 2 mm to 25 mm in thickness, engineered for optical clarity, thermal performance, or structural safety in built environments and transportation applications. Tempered glass leads volume in automotive and code-mandated safety applications, while laminated glass commands superior margins in hurricane-zone commercial construction and acoustic insulation. Coated glass represents the fastest-expanding product category, driven by low-emissivity and anti-reflective specifications for solar panel covers and net-zero building envelopes.
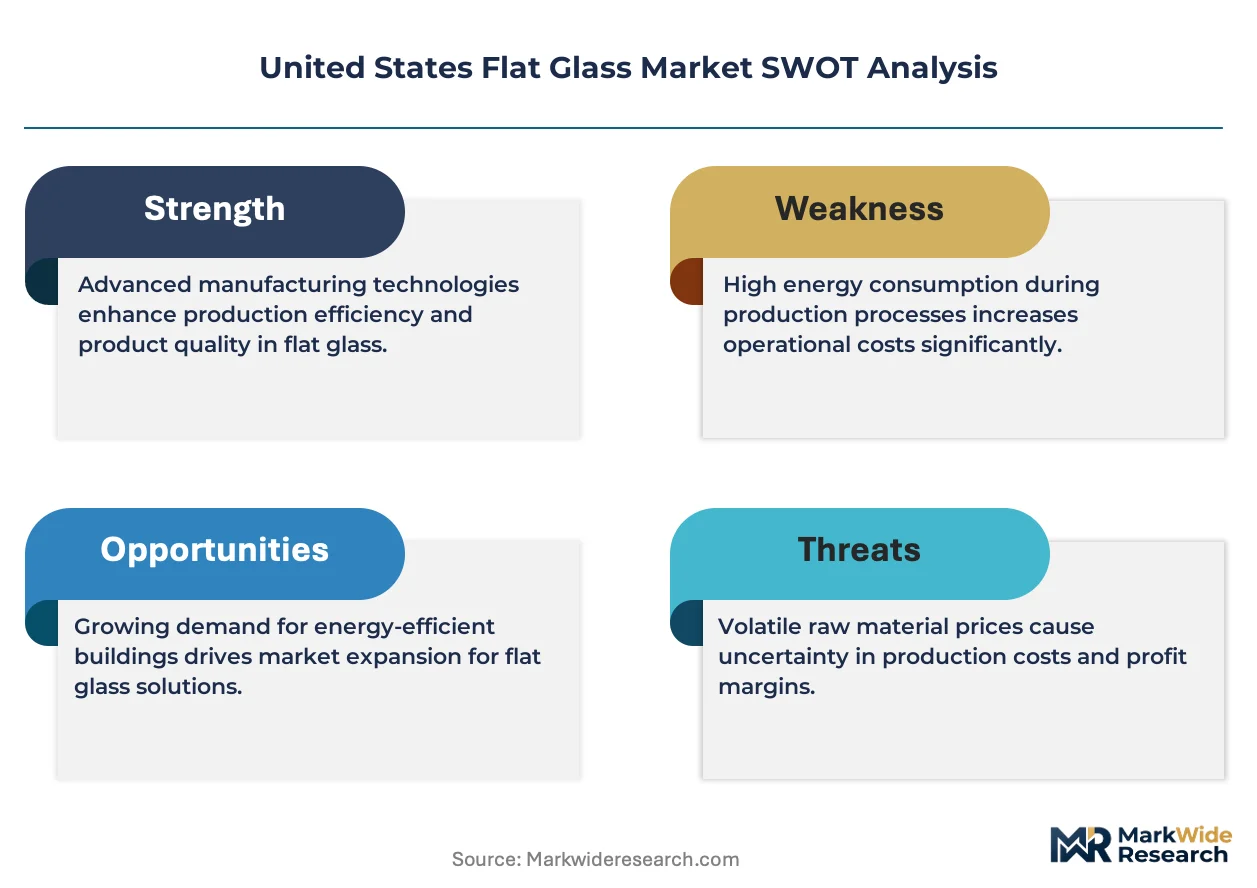
Federal energy codes, EPA emissions standards for glass melting furnaces, and OSHA silica exposure limits collectively shape capital intensity and product certification requirements across domestic manufacturing. State-level solar renewable portfolio standards in California, Texas, and Florida directly stimulate coated glass demand for photovoltaic module assembly. Stakeholders must monitor evolving furnace fuel-switching economics as natural gas-to-electric transitions interact with regional electricity rate structures and IRA clean manufacturing incentives.
Market Dynamics
The Inflation Reduction Act's manufacturing tax credits are restructuring capital deployment decisions across domestic flat glass production, pulling furnace investment toward states with favorable electricity rate structures and solar demand corridors.
Growth Catalysts
- IRA Clean Manufacturing Incentives:Section 45X advanced manufacturing credits offset capital costs for new float glass capacity sited near utility-scale solar clusters in Texas and California.
- Automotive Lightweighting Mandates:NHTSA fuel economy standards push OEMs toward thinner, chemically strengthened glass formulations for electric vehicle roof and windshield applications.
- Low-Iron Silica Beneficiation:Domestic mining operations in Wisconsin and Ohio are scaling high-purity sand output to feed solar-grade float specifications without import dependency.
Market Restraints
- Natural Gas Price Volatility:Float furnace operations remain tethered to Henry Hub pricing swings, compressing margins when regional gas basis differentials spike during winter demand periods.
- Furnace Refractory Supply Concentration:Specialty fused cast AZS blocks for glass-contact zones source predominantly from Chinese producers, exposing restart timelines to ocean freight bottlenecks.
- EPA MACT Emission Limits:Maximum Achievable Control Technology standards for glass melting particulate matter force costly baghouse upgrades or fuel-switching investments at legacy Ohio River valley plants.
Strategic Opportunities
- Southeast Automotive Corridor Expansion:New BMW, Hyundai, and Rivian assembly plants in South Carolina and Georgia create captive demand for laminated acoustic windshields within 300-mile radius.
- Building-Integrated Photovoltaics:Semi-transparent solar glazing for commercial facades merges fenestration with generation, opening premium specification channels beyond commodity architectural glass.
- Electrified Melting Technology:All-electric furnace pilots paired with Texas and Arizona utility green tariff programs position early adopters for zero-carbon product certification premiums.
Industry Challenges
- Float Process Engineering Talent Scarcity:Retirement waves among 1980s-era furnace operators outpace vocational pipeline output, forcing producers to internalize multi-year apprenticeship programs.
- OSHA Silica Compliance Burden:Respirable crystalline silica exposure monitoring and medical surveillance requirements add administrative overhead to sand handling and batch house operations.
- Heat-Treatment Capacity Bottlenecks:Tempering furnace lead times stretch 18-24 months for oversized architectural units, constraining commercial tower project schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Flat Glass Market |
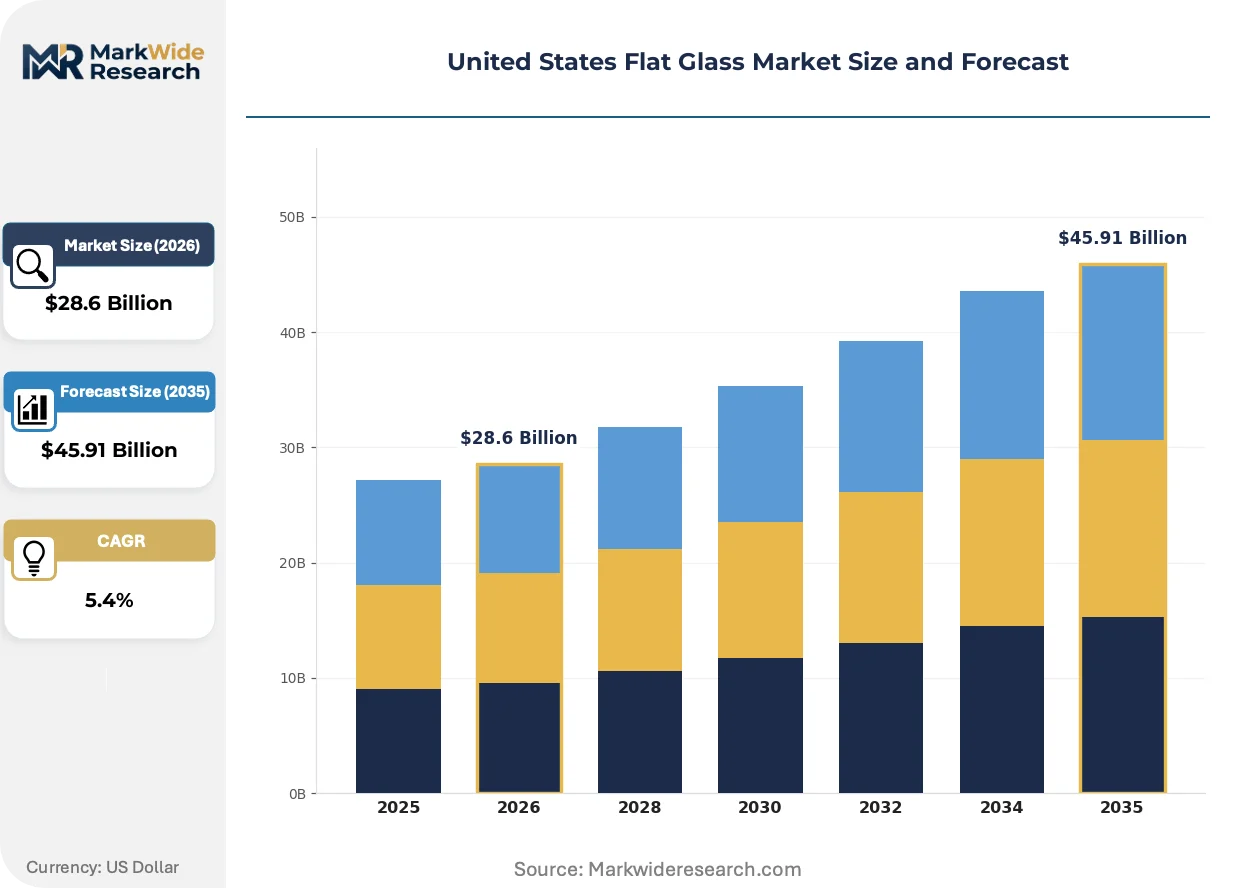
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $45.91 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tempered Glass, Laminated Glass, Coated Glass, Annealed Glass End User: Construction, Automotive, Consumer Electronics, Furniture Technology: Float Process, Sheet Glass Production, Vacuum Coating, Glass Modification Application: Windows, Facades, Doors, Solar Panels |
| Companies Covered | Saint-Gobain, Viracon, Guardian Glass, Şişecam, Nippon Sheet Glass, Vitro Glass, Cardinal Glass Industries, Trulite Glass & Aluminum Solutions, AGC Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Flat Glass Market Strategic Shifts & Innovations
Active chemistry and process control advances are compressing product development cycles while expanding the performance envelope of commodity flat glass into specialized energy and safety applications.
Vacuum deposition coating technology is unifying anti-reflective and low-emissivity functions into single-layer stacks that previously required sequential processing. Solar module manufacturers in California and Texas are qualifying these consolidated coatings for bifacial panel covers, reducing unit processing cost by eliminating handling between deposition stages. This unification is compressing the premium gap between commodity clear glass and high-transmission solar substrates.
EPA greenhouse gas performance standards for stationary sources are mandating furnace fuel-switching roadmaps or carbon capture feasibility studies at facilities exceeding 25,000 tons annual CO2 equivalent. Glass producers in the Ohio River valley and Pacific Northwest face compressed compliance timelines relative to Southeast greenfield sites, reshaping regional competitiveness. The regulation is accelerating partnerships between incumbent manufacturers and industrial electrification vendors to front-run 2030 benchmark dates.
Consolidated procurement by national homebuilder chains is compressing supplier qualification cycles and pushing volume guarantees onto regional float distributors. Builders FirstSource and Beacon Roofing Supply now specify direct mill relationships for high-performance residential fenestration, disintermediating traditional independent glass distributors in Sun Belt metro corridors. This concentration is most visible in Phoenix, Dallas-Fort Worth, and Atlanta, where production home construction cycles demand just-in-time delivery windows incompatible with multi-hop distribution.
United States Flat Glass Market Segmentation
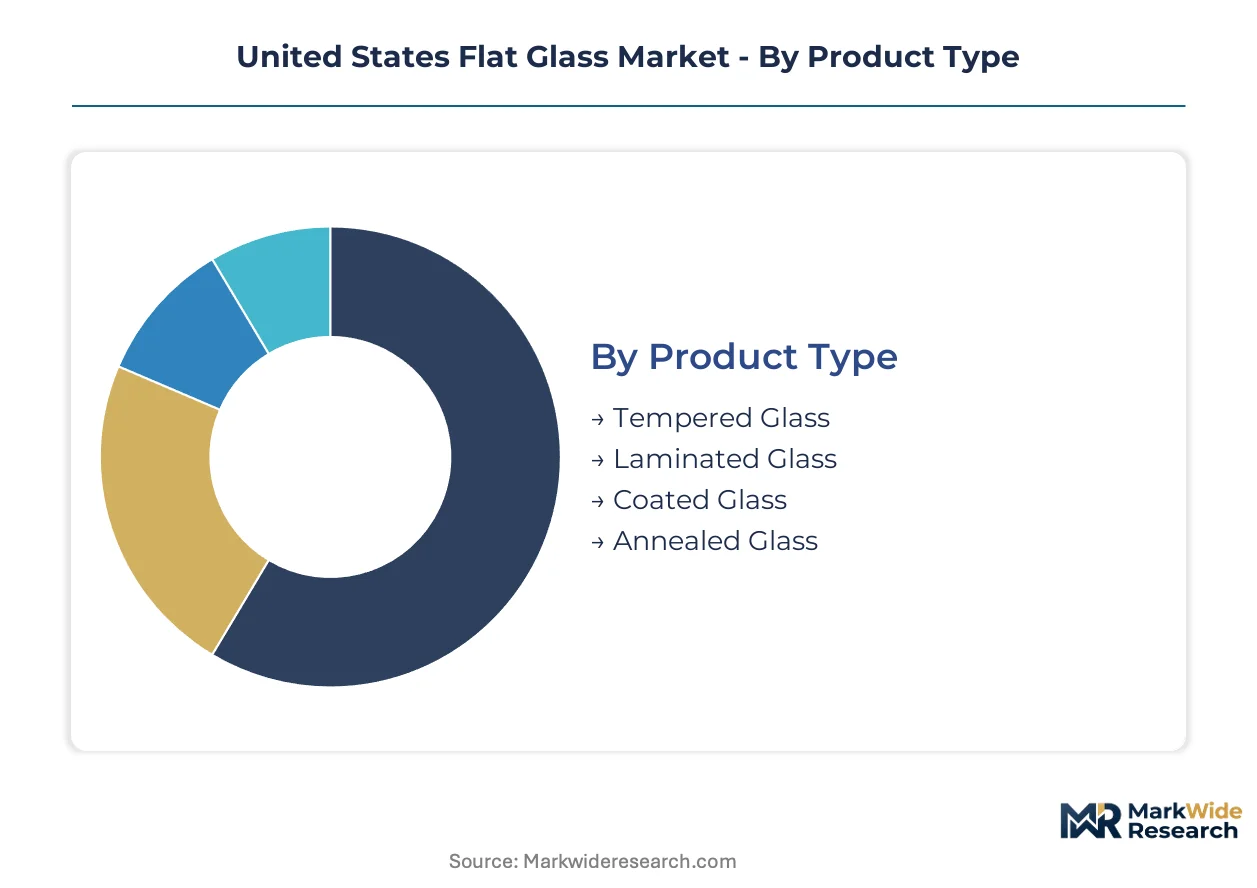
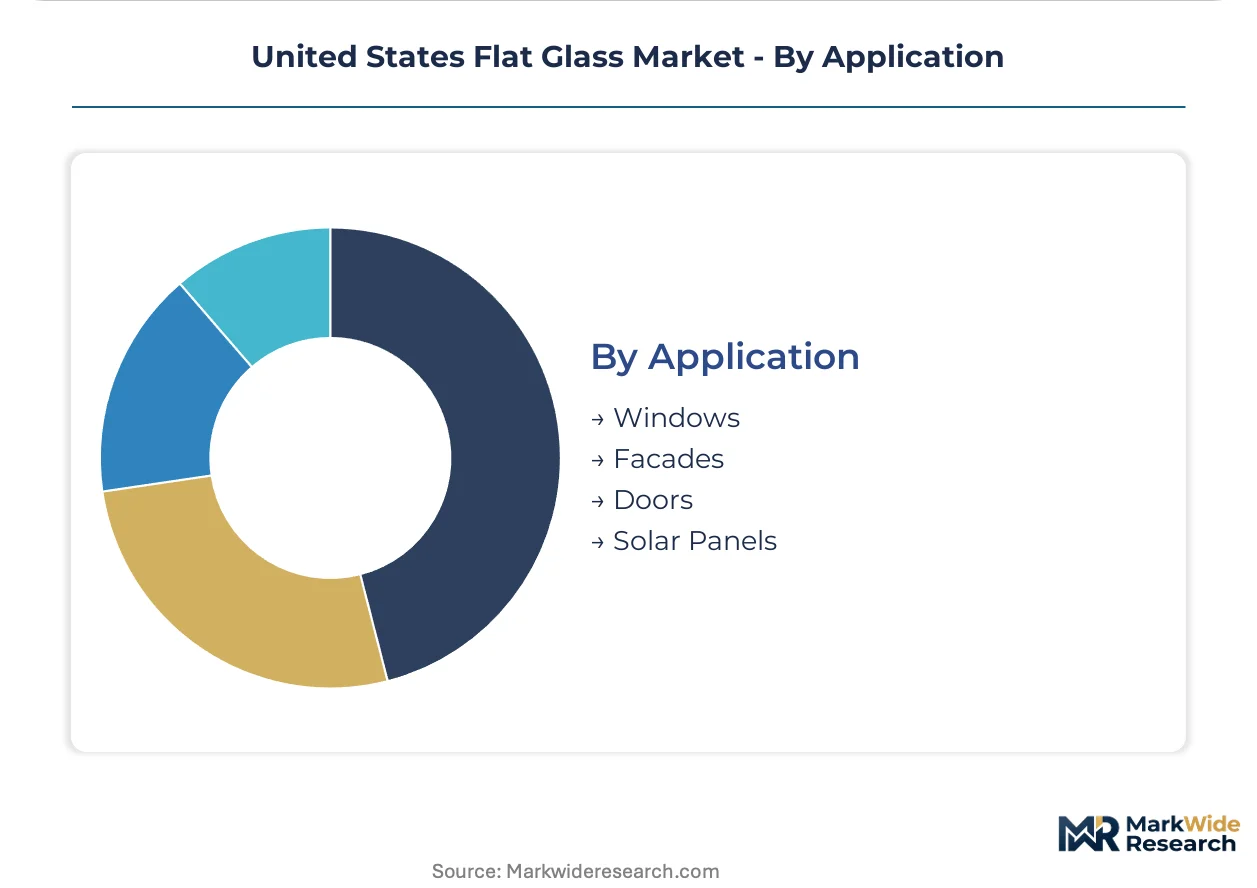
Flat glass purchasing decisions in the United States diverge sharply across end-use specifications, melting technology, and coating chemistry. Procurement teams in solar module assembly and automotive OEMs impose fundamentally different performance thresholds than residential fenestration buyers.
Product Type:
Cost tier determines specification breadth more than any other variable in domestic flat glass procurement.
- Tempered Glass:Thermally or chemically strengthened soda-lime sheets exhibiting 4-5x mechanical resistance versus annealed equivalents. Demand concentrates in automotive windshields and code-mandated safety glazing across California and Florida commercial construction, where seismic and hurricane loads drive specification. Tempering furnace capacity constraints in the Ohio River valley extend lead times for oversized architectural units.
- Coated Glass:Vacuum-deposited metal oxide stacks engineered for spectral selectivity, spanning low-emissivity architectural grades to anti-reflective solar substrates. Texas and California utility-scale solar clusters absorb expanding coated volume as IRA manufacturing credits reshape domestic float economics. Coated specifications are climbing fastest as bifacial panel covers displace commodity clear glass in photovoltaic assembly.
- Laminated Glass:Polyvinyl butyral interlayers bond multiple glass plies for acoustic dampening and post-breakage retention. Hurricane-zone commercial towers in Miami and Houston specify thick interlayers for debris impact resistance.
- Annealed Glass:Untempered float sheets for interior partitions and secondary glazing where thermal shock resistance is non-critical. Cost-sensitive residential retrofits in Sun Belt metros sustain residual volume.
Volume sits with tempered glass across automotive and safety mandates; growth tilts toward coated glass as solar manufacturing expands.
End User:
Application environment dictates certification depth and supply chain proximity requirements.
- Construction:Encompasses commercial facades, residential fenestration, and interior systems subject to IECC energy codes and ASTM safety standards. Southeast automotive corridor proximity is pulling laminated windshield demand toward South Carolina and Georgia float capacity.
- Automotive:OEMs specify acoustic laminated windshields and chemically strengthened roof glass for electric vehicle lightweighting mandates. NHTSA fuel economy standards compress thickness tolerances while expanding transmission requirements.
- Consumer Electronics:Cover glass for displays and touch interfaces demands ion-exchange strengthened substrates with optical-grade surface finishes. Device manufacturers qualify domestic suppliers for tariff resilience.
- Furniture:Tabletops, shelving, and decorative panels utilize tempered or annealed sheets with aesthetic clarity specifications. Batch size fragmentation limits dedicated furnace allocation.
Construction commands the deepest specification stack; automotive is gaining share fastest as electric vehicle platforms multiply.
Technology:
Melting and forming method locks in capital intensity and emission profile for decades.
- Float Process:Molten glass ribbon floats on molten tin bath to achieve fire-polished surfaces without grinding. The dominant US manufacturing method, now retrofitting for electrified melting pilots in Arizona and Texas green tariff zones.
- Vacuum Coating:Sputter deposition of metal oxides in controlled atmosphere chambers enables single-stack low-emissivity and anti-reflective functions. California and Texas solar module manufacturers are qualifying consolidated coating architectures to eliminate handling stages.
- Sheet Glass Production:Vertical or horizontal drawing methods for specialty thicknesses outside float standard ranges. Limited domestic capacity serves niche optical and scientific applications.
- Glass Modification:Post-forming thermal or chemical treatments including tempering, laminating, and edge working. Heat-treatment capacity bottlenecks stretch lead times for oversized architectural units.
Float process anchors installed capacity; vacuum coating is expanding most quickly as solar specifications multiply.
Application:
Installation environment determines thermal, structural, and optical performance thresholds.
- Windows:Residential and commercial fenestration specifying low-emissivity coated glass for IECC climate zone compliance. National homebuilder consolidation is compressing supplier qualification cycles in Phoenix, Dallas-Fort Worth, and Atlanta corridors.
- Facades:Curtain wall and storefront systems for commercial towers, often combining laminated safety plies with high-performance coatings. Hurricane-zone projects in Miami and Houston drive thick interlayer specifications.
- Doors:Entry and interior systems requiring tempered or laminated safety glass per IBC impact standards. Retail and hospitality renovation cycles sustain replacement demand.
- Solar Panels:Photovoltaic module covers and substrates demanding high transmission, low iron content, and anti-reflective surface treatment. Utility-scale projects in Texas and California are accelerating demand for solar-grade float specifications.
Windows retain the broadest installation base; solar panels are climbing the fastest as IRA incentives reshape domestic manufacturing economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flat glass demand concentrates in the Southeast, Texas, and California corridors, where automotive assembly, utility-scale solar, and residential construction cycles intersect with new float furnace capacity.
Southeast
BMW, Hyundai, and Rivian assembly plants in South Carolina and Georgia generate captive laminated windshield demand within 300-mile radius. NHTSA fuel economy standards push OEMs toward thinner acoustic glass formulations. New float furnaces near Spartanburg and Savannah anchor supply proximity to automotive clusters.
Texas
Utility-scale solar installations across West Texas absorb expanding high-transmission coated glass volume. IRA Section 45X manufacturing tax credits pull furnace investment toward ERCOT zones with favorable industrial electricity rates. Float capacity in the Dallas-Fort Worth corridor serves both photovoltaic module assembly and residential fenestration demand.
California
Bifacial solar panel manufacturers in the Central Valley qualify anti-reflective coated substrates for utility-scale projects. Title 24 building energy codes mandate low-emissivity glazing for net-zero commercial construction. Los Angeles and San Diego metro areas concentrate curtain wall specification for high-rise facades.
Ohio River Valley
Legacy float plants face compressed EPA MACT compliance timelines for particulate matter emissions. Natural gas price volatility at Henry Hub compresses margins during winter demand spikes. Pittsburgh and Cincinnati retain heat-treatment capacity for tempered architectural units serving Midwest commercial construction.
Pacific Northwest
Green tariff electricity programs in Oregon and Washington attract electrified furnace pilot investments. Residential fenestration demand concentrates in Seattle and Portland metro corridors. EPA greenhouse gas performance standards force carbon capture feasibility studies at facilities exceeding 25,000 tons annual CO2 equivalent.
United States Flat Glass Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated float producers dominating volume and regional fabricators capturing value-added processing. The market structure tilts toward consolidation at the melting stage and fragmentation in distribution. Three archetypes anchor competitive positioning: backward-integrated raw material owners, captive float lines dedicated to residential fenestration, and premium niche specialists in oversized architectural units. Capacity expansion and strategic partnerships constitute the dominant competitive moves as producers secure sand beneficiation and coating technology access.
Among integrated manufacturers, Guardian Glass, Cardinal Glass Industries, and Viracon exemplify distinct strategic positions. Guardian Glass represents backward integration into low-iron silica sand beneficiation for cost discipline at scale. Cardinal Glass Industries anchors the residential fenestration segment through captive float line dedication. Viracon occupies a premium niche in oversized heat-treated commercial tower facades that competitors struggle to replicate.
| Leading Market Players |
|---|
| Saint-Gobain |
| Viracon |
| Guardian Glass |
| Şişecam |
| Nippon Sheet Glass |
| Vitro Glass |
| Cardinal Glass Industries |
| Trulite Glass & Aluminum Solutions |
| AGC Inc. |
| Others |
Cost & Logistics Intelligence
Solar-grade versus architectural-grade bifurcation splits the United States flat glass value chain into divergent margin structures and sourcing configurations. Premium high-transmission coated substrates command sustained pricing power through captive beneficiation and qualification timelines, while commodity clear glass faces compression from consolidated homebuilder procurement and spot silica sand markets.
Pricing Analysis
Volume-margin separation concentrates in tempered safety glass versus coated solar substrates. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth: solar-grade float with anti-reflective stacks sustains superior returns, architectural low-emissivity coatings occupy mid-tier stability, and uncoated annealed sheets face erosion from national distributor consolidation. Cost compression in commodity architectural tiers intensifies because Builders FirstSource and Beacon Roofing Supply now mandate direct mill relationships. Residential fenestration buyers exhibit highest price sensitivity; solar module manufacturers prioritize transmission performance over unit cost.
Supply Chain Analysis
Low-iron silica sand supply rests on domestic mining operations in Wisconsin and Ohio scaling beneficiation capacity to displace imported feedstock. Float furnace refractories draw from Chinese fused cast AZS block producers, exposing restart timelines to ocean freight bottlenecks. Natural gas pricing at Henry Hub creates margin volatility during winter demand spikes. Distribution runs through regional fabricators serving automotive OEMs within 300-mile radius and national homebuilder chains demanding just-in-time delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States flat glass market functions as a vertical-integration race where sand beneficiation and coating technology access determine competitive survival. Players securing captive low-iron silica supply and consolidated vacuum deposition capabilities capture structural margin advantages.
For Market Incumbents: Deepen backward integration into Wisconsin and Ohio sand mining to lock in solar-grade feedstock economics before qualification windows close. Expand heat-treatment capacity in the Southeast automotive corridor to capture BMW, Hyundai, and Rivian laminated windshield demand. Electrified furnace pilots in Texas and Arizona green tariff zones preempt EPA MACT compliance costs. For New Entrants and Emerging Players: The premium-economy price gap in oversized architectural heat-treated units offers white-space entry. Viracon's niche in commercial tower facades demonstrates replicable specialization. Target building-integrated photovoltaics semi-transparent glazing for commercial facades, where fenestration-generation convergence outpaces commodity competition. Qualify through California Title 24 net-zero commercial codes to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Re-rating potential sits with electrified furnace operators given IRA Section 45X manufacturing credits and zero-carbon product certification premiums. Long-term viability favors producers with sand beneficiation assets and coating technology partnerships rather than pure-play fabricators. Watch EPA greenhouse gas performance standard enforcement timelines as inflection indicator for Ohio River valley legacy asset stranded risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Beneficiation | Guardian Glass secures solar-grade feedstock economics through captive Wisconsin mining operations. |
| Electrified Furnace Pilot Deployment | Texas and Arizona producers front-run EPA MACT compliance through utility green tariff partnerships. |
| Consolidated Coating Technology Partnership | California solar manufacturers qualify single-stack anti-reflective architectures to eliminate handling stages. |
| Southeast Automotive Corridor Capacity Expansion | South Carolina and Georgia float lines capture laminated windshield demand from BMW and Hyundai assembly. |
| Direct Mill Relationship with National Homebuilders | Cardinal Glass Industries bypasses independent distributors through Builders FirstSource volume guarantees. |
Research Approach
Independent corroboration across float plant managers, solar module procurement leads, automotive OEM glass engineers, and national homebuilder supply chain directors underwrites the qualitative findings. Secondary validation draws from EPA MACT emission filings, EIA industrial electricity rate data, SEC 10-K disclosures by listed glass producers, and IRA Section 45X credit utilization records. Bottom-up capacity and demand modeling triangulates against top-down construction spending and vehicle production forecasts.
Rate-of-change decomposition separates volume growth from value expansion across tempered, coated, laminated, and annealed product tiers. Segmentation dimensions span glass modification technology, end-use application, coating chemistry specification, and regional production hub economics. CAGRs derive from installed float capacity utilization, solar panel deployment trajectories, and automotive lightweighting content trends. Forecast inputs incorporate NHTSA fuel economy standard stringency and state-level solar renewable portfolio standard adoption.
Underlying measurement precision varies by segment; solar panel and automotive applications carry tighter precision than furniture and interior partitioning. Forecasts reflect documented assumptions regarding IRA credit continuity, natural gas price normalization, and furnace electrification capital cost curves. EPA enforcement intensity, silica sand import tariff structures, and heat-treatment capacity expansion timelines warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Porous Glass Market
Glass
Low Iron Glass Market
Glass
Glass Mat Market
Glass
Antibacterial Glass Market
Glass
GCC Flat Glass Market
Glass
Laboratory Glassware Market
Glass
Global Anti-Reflective Glass Market
Glass
Global Self-Cleaning Glass Market
Glass
Glass Mat Thermoplastic Market
Glass
North America and Australia Silica Market
Glass
Glass Polishing Powder Market
Glass
Solar PV Glass Market
Glass
Ultra Violet Glass Bottles Market
Glass
Asia-Pacific Silica Sand Market
Glass
China Flat Glass Market
Glass
Global Vacuum Insulated Glass Market