
 Glass Block Market | 2026-2036
Glass Block Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Block Market Foresight
Digital design-to-fabrication workflows are reconfiguring how glass block assemblies are specified, modeled, and prefabricated for complex facade geometries. Seves Group leverages proprietary molding technology to sustain leadership in large-format structural glass blocks across European infrastructure projects. Saint-Gobain Glass anchors its position through integrated float-glass supply chains that feed captive block production with consistent raw material quality. Pittsburgh Corning differentiates via specialized hollow-glass formulations that compete on thermal insulation performance in North American climate zones.
Glass blocks are hollow or solid masonry units manufactured from soda-lime silica glass, typically pressed or cast into standardized dimensions with nominal thicknesses of 80 to 100 millimeters, designed to transmit diffused daylight while providing structural compression resistance and thermal insulation in building envelopes. Their primary commercial purpose spans non-load-bearing partition walls, exterior curtain walls, and overhead glazing where fire rating, acoustic dampening, or privacy screening is required alongside luminous transmission. Clear glass blocks dominate volume in utilitarian applications such as basement windows and industrial skylights where maximum visible light transfer governs specification. Textured and frosted variants command margin premiums in hospitality and healthcare interiors where diffused illumination must satisfy visual privacy requirements without sacrificing spatial brightness.
Building codes enforced by the EPA and OSHA in the United States, alongside REACH and CE marking requirements administered by ECHA in Europe, shape product compliance pathways for glass block manufacturers seeking market access across multiple jurisdictions. These frameworks mandate limits on heavy-metal content in colored glass formulations, structural safety testing for overhead applications, and thermal performance documentation for energy-efficient building certification. Stakeholders must monitor evolving fire-resistance classification standards and embodied-carbon disclosure rules that will determine which manufacturing configurations retain specification viability in public-sector construction procurement.
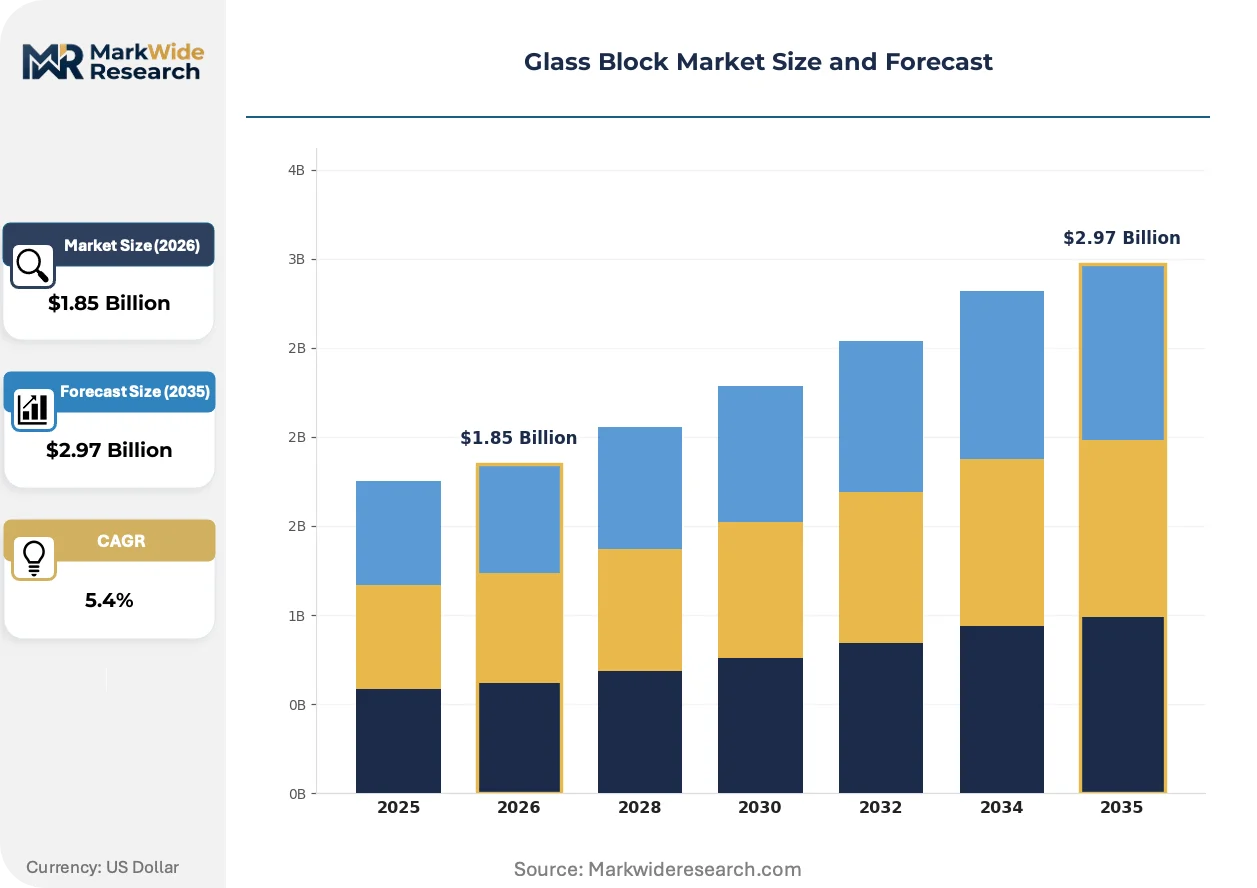
Market Dynamics
Energy-efficiency mandates in Germany and California are collapsing the thermal-performance threshold that conventional glass block formulations must meet, forcing manufacturers to reformulate hollow-glass compositions or surrender specification share to high-performance alternatives.
Growth Catalysts
- California Title 24:The state's building energy code tightens thermal transmittance limits for envelope materials, compelling commercial developers to specify insulated glass block assemblies for daylighting compliance.
- Hospitality interior retrofit:Hotel operators in Southeast Asia are replacing solid partitions with textured glass blocks to satisfy privacy requirements while reducing artificial lighting loads.
- Digital prefabrication:BIM-to-CNC workflows enable contractors to order dimensionally precise glass block modules for complex facade geometries without field cutting.
Market Restraints
- Soda ash price volatility:Energy costs at glass melting furnaces fluctuate with natural gas benchmarks, compressing margin stability for block manufacturers without captive energy hedging.
- Float-glass supply concentration:Captive supply chains at integrated majors limit third-party block producers' access to consistent raw material quality at scale.
- Polycarbonate panel substitution:Lightweight translucent glazing systems compete for skylight and partition applications where structural compression resistance is not required.
Strategic Opportunities
- Indonesia commercial construction:Retail and hotel developers in Jakarta and Bali are specifying climate-responsive glass block facades for passive cooling and daylight harvesting.
- EU Green Deal taxonomy:Embodied-carbon disclosure requirements create preference for domestically manufactured blocks with verified lifecycle data in public procurement.
- Photovoltaic integration:Building-integrated solar manufacturers are partnering with glass block producers to embed thin-film cells within hollow block cavities for net-zero envelopes.
Industry Challenges
- Fire-resistance certification timelines:Extended testing protocols for overhead glazing applications delay product launches and tie up R&D capital for 18-24 month cycles.
- Skilled masonry labor scarcity:Specialized installation techniques for structural glass block assemblies face declining trade apprenticeship enrollment in North American and European construction markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Block Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Glass Blocks, Textured Glass Blocks, Colored Glass Blocks, Patterned Glass Blocks, Frosted Glass Blocks Application: Interior Wall Partitions, Exterior Facades, Skylights, Decorative Elements, Bathroom Walls Installation Method: Mortar Installation, Sealant Installation, Dry-Stack Installation, Frame Mounted Installation, Adhesive Installation End User: Construction Contractors, Residential Builders, Commercial Developers, Interior Designers, Specialty Fabricators |
| Companies Covered | Seves Group, Allegion Public Ltd. Co., Saint-Gobain Glass, Corning Inc., Pittsburgh Corning, Bormioli Rocco SA, PT Mulia Industrindo Tbk, Bangkok Crystal Co. Ltd., Dezhou Jinghua Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Block Market Shifts & Advancements
Digital fabrication and material science advances are compressing the traditional tradeoff between luminous transmission and thermal performance in glass block specification.
Large-format structural glass blocks produced through proprietary isostatic pressing are collapsing the distinction between masonry infill and curtain wall systems. Infrastructure contractors in European transit hubs specify these units for load-bearing facade applications previously reserved for aluminum-framed glazing. The technology enables monolithic assemblies that reduce installation labor and thermal bridging.
REACH authorization requirements administered by ECHA restrict cadmium and lead content in colored glass formulations. Manufacturers reformulating chromophores to satisfy heavy-metal limits face raw material cost increases of 15-30 percent for specialty tints. Healthcare and hospitality segments in Northern Europe are absorbing these premiums to maintain specification for privacy-rated colored blocks.
Specification decisions increasingly flow through facade consultants and energy modelers rather than general contractors or distributors. Design-build firms in Thailand and Indonesia retain these specialists early in schematic design to validate glass block thermal performance against green building certification targets. This channel shift compresses the sales cycle but demands technical sales capabilities that traditional block distributors rarely possess.
Glass Block Market Segmentation
Glass block specification varies sharply by visual performance requirements, structural loading conditions, and installation labor availability. Manufacturers configure product lines around these dimensions to capture margin in premium architectural applications while maintaining volume in utilitarian segments.
Product Type:
Cost tier separates commodity formulations from specialty surfaces that command specification premiums in design-driven verticals.
- Clear Glass Blocks:Manufactured from soda-lime silica with maximum visible light transmission, these units dominate basement windows and industrial skylights where luminous performance outweighs privacy concerns. Demand concentrates in North American residential retrofits and Southeast Asian factory construction where natural daylighting reduces electrical loads.
- Textured Glass Blocks:Surface patterns diffuse incident light to obscure direct sightlines while maintaining spatial brightness. Hospitality developers in Indonesia and Thailand specify these for corridor partitions and guest room dividers where privacy compliance intersects with aesthetic objectives.
- Colored Glass Blocks:Chromophore-doped formulations satisfy healthcare and institutional color-coding requirements; REACH heavy-metal limits are forcing reformulation of traditional cadmium and lead tints.
- Patterned Glass Blocks:Geometric surface relief creates directional light diffusion for branded retail environments and signature architectural statements.
- Frosted Glass Blocks:Acid-etched or sandblasted surfaces deliver maximum privacy ratings for bathroom walls and clinical settings; surface treatment adds 20-35 percent to base material cost.
Clear glass blocks hold installed capacity across utilitarian applications. Textured variants are rotating up the share rankings as hospitality retrofit activity accelerates in Southeast Asia.
Application:
Structural function determines whether glass blocks compete against drywall, curtain wall systems, or specialty glazing products.
- Interior Wall Partitions:Non-load-bearing assemblies in commercial and healthcare settings leverage glass blocks for fire rating, acoustic dampening, and daylight penetration. Hotel operators in Jakarta and Bali are replacing solid gypsum partitions with textured glass block systems to reduce artificial lighting hours.
- Exterior Facades:Climate-responsive envelopes in tropical markets employ glass blocks for passive solar control and thermal mass; large-format structural units from European manufacturers are penetrating this segment.
- Skylights:Overhead glazing applications demand enhanced structural safety testing and extended fire-resistance certification timelines that compress manufacturer margins.
- Decorative Elements:Feature walls and signage applications in retail and hospitality prioritize surface pattern and color over thermal performance.
- Bathroom Walls:Wet-area installations specify frosted or textured blocks for moisture resistance and privacy compliance in residential and hospitality construction.
Interior partitions command the largest addressable volume. Exterior facade applications are climbing the fastest as building energy codes tighten daylighting requirements.
Installation Method:
Labor skill intensity and project schedule constraints drive specification between traditional masonry and prefabricated assembly systems.
- Mortar Installation:Conventional bed-joint construction with Portland cement mortar remains standard for structural applications; skilled masonry labor scarcity in North America and Europe is compressing contractor availability.
- Sealant Installation:Silicone or polyurethane joint systems accelerate installation and improve thermal movement accommodation; commercial developers in California specify these for Title 24 compliance on large envelope areas.
- Dry-Stack Installation:Precision-milled blocks with interlocking edges eliminate wet trades; BIM-to-CNC workflows enable prefabrication of complex geometries for transit hub projects in Germany.
- Frame Mounted Installation:Aluminum or steel perimeter frames accommodate thermal expansion in curtain wall integration; reduces field labor but increases material cost.
- Adhesive Installation:Structural adhesive systems for lightweight interior applications where compression loading is minimal; interior designers in hospitality segments favor these for speed of execution.
Mortar installation retains the deepest skilled labor base. Dry-stack systems are gaining share fastest as prefabrication workflows penetrate commercial construction.
End User:
Procurement authority and technical specification capability vary dramatically across the value chain.
- Construction Contractors:General and specialty contractors control specification for infrastructure and commercial projects; their purchasing prioritizes installed cost and schedule certainty over material aesthetics.
- Residential Builders:Production homebuilders specify clear glass blocks for basement windows and egress requirements; custom builders access textured and colored variants for high-end renovations.
- Commercial Developers:Retail and hotel developers in Indonesia and Thailand retain facade consultants early in design to validate thermal performance against green building certification targets.
- Interior Designers:Specification influencers in hospitality and healthcare segments prioritize surface finish and privacy ratings; limited technical authority over structural performance requirements.
- Specialty Fabricators:Prefabrication shops cutting glass block assemblies from BIM models serve as an emerging channel for complex facade geometries.
Construction contractors hold installed procurement volume. Commercial developers are rotating up the influence rankings as early-stage energy modeling reshapes specification workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial developers and hospitality operators drive specification concentration across distinct climate zones and regulatory environments. Procurement authority clusters with facade consultants in tropical markets and energy modelers in code-stringent jurisdictions.
United States
California Title 24 mandates tighten thermal transmittance limits for envelope materials, compelling developers in Los Angeles and San Francisco to specify insulated glass block assemblies for daylighting compliance. The EPA and OSHA frameworks govern heavy-metal content and structural safety testing for overhead applications. Construction activity concentrates in the Pacific Northwest and Southwest where passive solar design integrates glass block thermal mass.
Germany
Energy-efficient building codes administered at the federal and state levels collapse thermal-performance thresholds for transparent envelope materials. The EU Green Deal taxonomy and REACH requirements administered by ECHA restrict cadmium and lead content in colored formulations, forcing reformulation of traditional chromophores. Infrastructure contractors in Berlin and Munich specify large-format structural units for transit hub facades previously reserved for aluminum-framed glazing.
Indonesia
Retail and hotel developers in Jakarta and Bali specify climate-responsive glass block facades for passive cooling and daylight harvesting in tropical conditions. The national building code emphasizes thermal performance for commercial envelopes without harmonized federal energy standards. Commercial construction clusters in Java and Sumatra where foreign direct investment flows into hospitality and retail infrastructure.
Thailand
Design-build firms in Bangkok retain facade consultants early in schematic design to validate glass block thermal performance against green building certification targets. The country's building control regulations emphasize fire resistance and structural safety for overhead glazing applications. Hospitality retrofit activity concentrates in Phuket and Chiang Mai where hotel operators replace solid partitions with textured systems to reduce artificial lighting loads.
China
Commercial developers in the Yangtze River Delta and Pearl River Delta integrate glass block assemblies into climate-responsive retail and hotel projects. National standards under the GB framework govern building energy efficiency and material safety for envelope applications. Manufacturing capacity clusters in Shandong and Jiangsu provinces where soda-lime silica supply chains feed domestic block production.
Glass Block Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement pathways where facade consultants and energy modelers increasingly filter specification decisions. The vendor base spans integrated glass majors with captive raw material supply, regional block specialists with molding technology advantages, and emerging fabricators serving prefabrication workflows. Three archetypes dominate: integrated glass conglomerates with backward control over float-glass supply, specialized block manufacturers with proprietary pressing or hollow-glass formulations, and BIM-enabled prefabrication shops cutting assemblies from digital models. Competitive moves center on M&A to secure distribution channels and technology licensing to embed thermal performance improvements without captive R&D investment.
Among European-based integrated manufacturers, Seves Group and Saint-Gobain Glass occupy positions that exemplify the captive-supply archetype, leveraging in-house float-glass production to ensure consistent raw material quality at scale. Pittsburgh Corning represents the specialized-formulation tier, competing on thermal insulation performance in North American climate zones through differentiated hollow-glass compositions. PT Mulia Industrindo Tbk and Bangkok Crystal Co. Ltd. anchor the regional-fabricator segment in Southeast Asia, where proximity to hospitality and retail construction clusters in Jakarta and Bangkok shapes procurement relationships.
| Leading Market Players |
|---|
| Seves Group |
| Allegion Public Ltd. Co. |
| Saint-Gobain Glass |
| Corning Inc. |
| Pittsburgh Corning |
| Bormioli Rocco SA |
| PT Mulia Industrindo Tbk |
| Bangkok Crystal Co. Ltd. |
| Dezhou Jinghua Group |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp barge freight corridors for soda ash and silica sand feedstock govern landed cost differentials between European integrated manufacturers and Asian import-dependent fabricators, compressing margin buffers for block producers without captive mineral processing or long-term offtake agreements with German soda-lime suppliers.
Pricing Analysis
Cost-plus contracts with soda ash indexation to natural gas benchmarks dominate procurement between glass block manufacturers and raw material suppliers, exposing margin stability to energy price volatility. Pricing stratifies across premium, standard, and economy tiers based on thermal performance certification and surface treatment complexity. Cost compression in standard clear blocks is intensifying because polycarbonate panel substitution threatens volume in utilitarian skylight applications. Residential builders exhibit highest price sensitivity, while hospitality developers absorb premiums for textured and frosted variants.
Supply Chain Analysis
Export-control regimes on advanced isostatic pressing equipment limit technology transfer to Southeast Asian fabricators, preserving European manufacturers' lead in large-format structural units. Supply concentrates in Germany, Italy, and China, with captive float-glass production at integrated majors drawing from soda-lime silica feedstocks. Raw material dependencies center on soda ash, silica sand, and chromophore dopants for colored formulations. Single-source vulnerability for specialty molding equipment creates procurement bottlenecks. Distribution runs through facade consultants and prefabrication shops rather than traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification fragmentation across climate zones and certification tiers creates niche opportunities for differentiated entrants, as early-stage energy modeling by facade consultants fragments procurement authority away from consolidated general contractors.
For Market Incumbents: Insulate core positions by securing captive soda-lime supply through backward integration into German or Italian float-glass production, and accelerate fire-resistance certification pipelines to defend against polycarbonate substitution in overhead glazing applications. Channel control through BIM-enabled prefabrication partnerships represents the critical defensive lever against emerging fabrication shops. For New Entrants and Emerging Players: Indonesian commercial construction outside Jakarta presents the most penetrable white-space opportunity, where foreign direct investment flows into hospitality and retail infrastructure outpace local glass block supply capacity. Target climate-responsive facade applications in Bali and Sumatra with dry-stack installation systems that circumvent skilled masonry labor scarcity. Partner with European equipment licensors to bypass export-control barriers on isostatic pressing technology. For Investors and Strategic Acquirers: Regional fabricators with established facade consultant relationships and verified EU Green Deal lifecycle data represent the priority acquisition archetype for exposure to public procurement preference shifts. Long-term viability hinges on embodied-carbon disclosure capabilities and thermal performance differentiation rather than commodity volume. Monitor REACH authorization timelines for heavy-metal chromophore alternatives as the inflection signal for specialty colored block margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Soda-Lime Supply | Captive float-glass production at Seves Group and Saint-Gobain insulates margin from energy price volatility. |
| BIM-to-CNC Prefabrication Partnership | Dry-stack systems enable contractors in German transit hubs to execute complex geometries without field cutting. |
| Fire-Resistance Certification Acceleration | Extended testing protocols for overhead glazing compress margins; early completion captures specification share. |
| Photovoltaic Integration Development | Thin-film cell embedding within hollow block cavities addresses net-zero envelope demand from California Title 24 compliance. |
| REACH-Compliant Chromophore Reformulation | Heavy-metal-free colored formulations maintain access to Northern European healthcare and hospitality segments. |
Research Methodology
The analysis maps clear glass block, textured glass block, colored glass block, patterned glass block, and frosted glass block sub-sectors, each validated through primary interviews with facade consultants, energy modelers, hospitality procurement directors, glass block manufacturing plant managers, and construction contractors, combined with secondary validation from EPA and OSHA regulatory filings, ECHA REACH authorization databases, California Title 24 compliance documentation, and EU Green Deal taxonomy guidance, with bottom-up installation volume estimates triangulated against top-down construction spending data.
Assumptions held fixed include current California Title 24 thermal transmittance limits, REACH heavy-metal restrictions, and Southeast Asian hospitality retrofit intensity, while energy price trajectories and skilled masonry labor availability were varied across sensitivity scenarios. The analytical framework models product type, application, installation method, and end user segmentation dimensions over the projection horizon. CAGRs derive from regression against construction output indices and green building certification adoption curves, with glass block thermal performance coefficients and daylighting compliance thresholds as industry-specific forecast inputs.
Practitioners should monitor soda ash price volatility, REACH authorization expansions, and polycarbonate panel thermal performance improvements for early signals of forecast revision. Material shifts in German or California energy code stringency, or breakthroughs in lightweight translucent glazing systems, would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Europe Flat Glass Market
Glass
North America Industrial Silica Sand Market
Glass
East Africa Flat Glass Market
Glass
Global Glass Tempering System Market
Glass
Advanced Glass Market
Glass
Screen-Printing Glass Market
Glass
Global Glassware Market
Glass
Asia-Pacific Silica Sand Market
Glass
Optical Materials Market
Glass
Solar PV Glass Market
Glass
Glass Recycling Market
Glass
Glass Like Carbon Market
Glass
Glass Balustrade Lamination Market
Glass
Europe Silica Sand for Glass Making Market
Glass
Glazing Gel Market
Glass
Fiberglass Window Market