
 Patterned Glass Market | 2026-2036
Patterned Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Patterned Glass Market Outlook
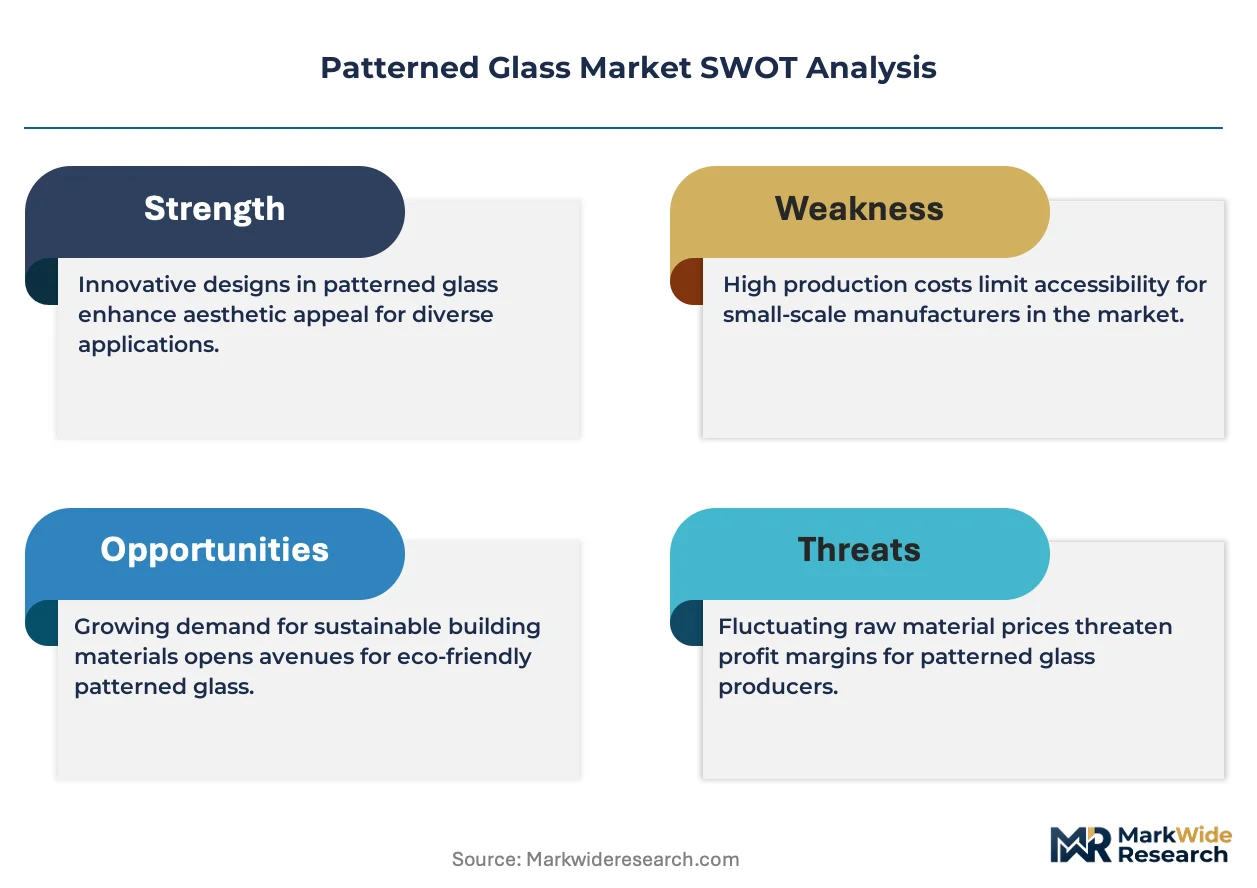
Capital-intensity divergence between float-glass heritage players and specialized patterned-glass fabricators is reorganizing competitive dynamics across the value chain. Guardian Glass leverages its integrated float-line network to sustain cost advantages in tempered patterned products. Şişecam anchors its position through vertical control over soda ash and silica sand supplies across Turkey and Europe. AGC Inc. differentiates via advanced coating technology leadership for architectural applications.
Patterned glass refers to flat glass sheets bearing embossed or rolled surface textures that scatter light, enhance privacy, and provide decorative effects while maintaining structural transparency; manufacturers produce it through the roll-pressing process where patterned rollers imprint designs onto molten glass during forming. Tempered patterned glass dominates volume due to safety-code mandates in commercial architecture, while laminated variants command premium positioning in facade applications where acoustic and security performance intersect. Etching technology leads the processing segment for high-end interior design, though coating applications are expanding fastest as low-emissivity and self-cleaning functionalities merge with aesthetic requirements.
Construction product safety regulators in the United States enforce ICC and ASTM standards that mandate tempered or laminated patterned glass in hazardous locations, while the EU Construction Products Regulation and CE marking govern thermal and mechanical performance claims across member states. China's SAMR and GB standards authorities are tightening energy-efficiency classifications for building-integrated glazing, directly shaping product development priorities for export-oriented manufacturers. Stakeholders must monitor evolving national building codes and energy-certification schemes to anticipate specification shifts before they reshape procurement criteria.
Market Dynamics
China's updated GB standards for building energy efficiency are tightening thermal performance requirements for decorative glazing products, forcing manufacturers to reconfigure coating and tempering investments across the value chain.
Growth Catalysts
- Commercial construction corridor in India:Mumbai, Bengaluru, and Hyderabad are concentrating demand for architectural facades and decorative interior installations. Specifiers in these cities are specifying patterned glass for premium office and hospitality projects.
- CE marking under EU Construction Products Regulation:Thermal and mechanical performance claims across member states are standardizing procurement criteria. This harmonization reduces cross-border specification friction for facade applications.
- Etching technology advancement:High-end interior design segments are adopting chemically etched patterned glass for bespoke aesthetic effects. This process enables finer surface detail than traditional roll-pressing methods.
Market Restraints
- Soda ash and silica sand supply concentration:Vertical control over these inputs by integrated heritage players limits fabricator margin flexibility. Independent patterned-glass specialists face input cost volatility.
- Flat glass float-line capital intensity:New tempered patterned glass capacity requires float-glass backward integration or long-term offtake agreements. This barrier protects incumbents but constrains specialist expansion.
- Laminated glass substitution in security-critical applications:Acoustic and security performance requirements in premium facades are pulling specification toward laminated variants. Tempered patterned glass loses share in these niches.
Strategic Opportunities
- Self-cleaning coating convergence:Low-emissivity and photocatalytic functionalities are merging with aesthetic requirements in commercial architecture. This technology pairing opens premium positioning for coated patterned products.
- Acoustic performance integration:Laminated patterned glass with interlayer sound-dampening is penetrating open-plan office and hospitality segments. Specifiers are paying premiums for combined privacy and noise control.
- India's building energy efficiency code adoption:State-level mandates in Maharashtra, Karnataka, and Telangana are tightening glazing performance standards. Export-oriented manufacturers can capture specification by pre-certifying to these codes.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous compliance with US ICC/ASTM standards, EU CE marking, and China GB classifications stretches technical resources. Product development cycles extend as testing protocols proliferate.
- Coating-tempering process integration:Combining advanced coating deposition with post-tempering thermal treatment requires capital reconfiguration. Fabricators must sequence investments to avoid stranded capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patterned Glass Market |
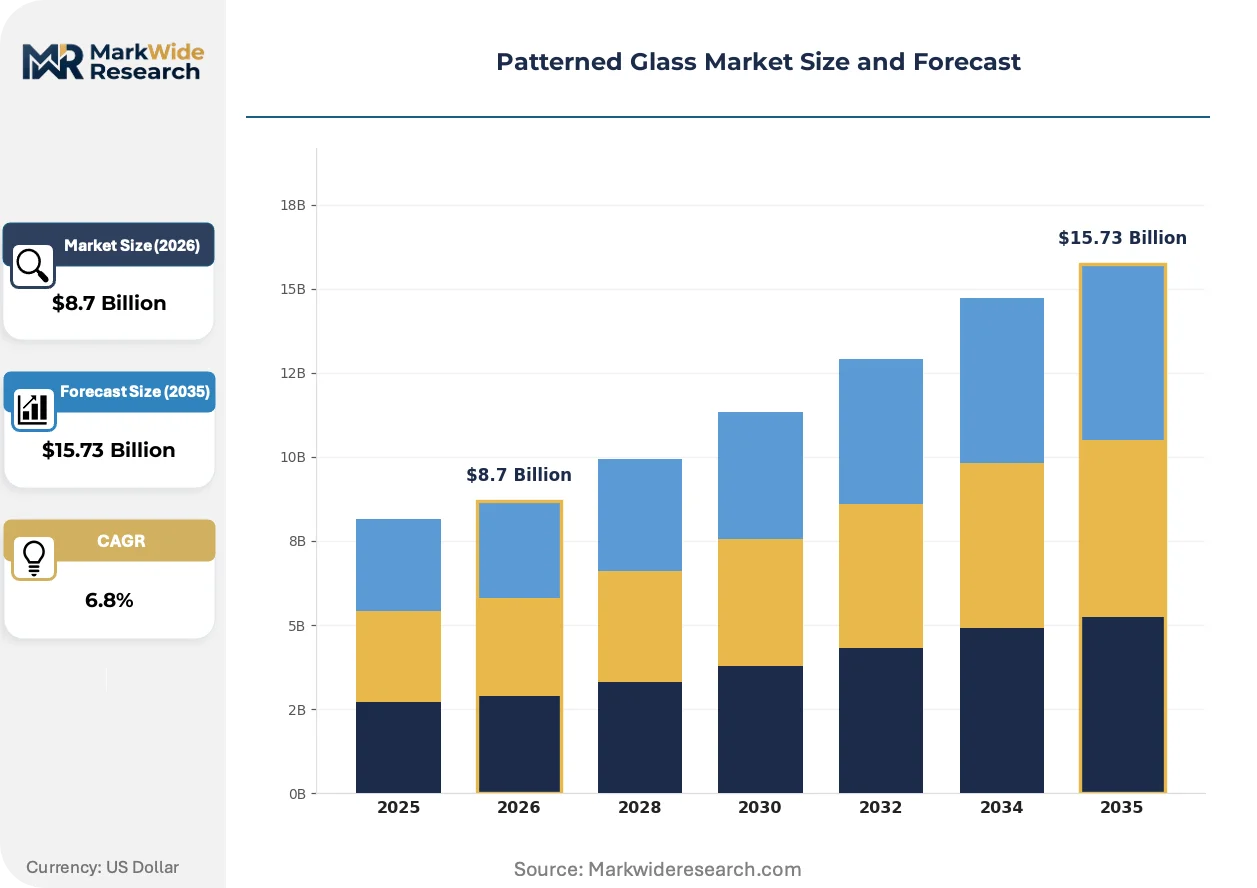
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tempered Glass, Laminated Glass, Insulated Glass, Wired Glass Application: Architecture, Automotive, Furniture, Interior Design End User: Residential, Commercial, Industrial, Retail Technology: Etching, Sandblasting, Printing, Coating |
| Companies Covered | Guardian Glass, Şişecam, AGC Inc., Jinjing Group, Xinyi Glass, Saint-Gobain, Vitro Architectural Glass, Central Glass Co., Ltd., NSG Group (Pilkington), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patterned Glass Market Strategic Shifts
Active coating technologies are merging with decorative glass surfaces, reshaping how architects specify patterned products for energy performance alongside aesthetics.
Digital ceramic printing on patterned glass substrates is supplanting traditional screen-printed decorative treatments in high-end commercial interiors. Hospitality and retail designers in Dubai and Singapore are specifying these digitally customized surfaces for branded environments. The technology is compressing minimum order quantities and enabling project-specific pattern variations without roller changeover costs.
China's SAMR enforcement of updated GB 50189 standards for public building energy efficiency is mandating lower U-values for curtain wall glazing. Patterned glass manufacturers serving export markets are reconfiguring low-emissivity coating lines to meet these thermal performance thresholds. The regulatory pressure is accelerating coated patterned glass adoption in commercial facade specifications across East Asian markets.
Architects are bundling acoustic, safety, and decorative performance into single specification packages for premium projects. This integrated procurement pattern is displacing component-by-component glazing selection in corporate headquarters and luxury hospitality developments. The shift is most visible in India's commercial construction corridor, where Mumbai and Bengaluru developers are issuing performance-based tenders rather than material-specific briefs.
Patterned Glass Market Segmentation
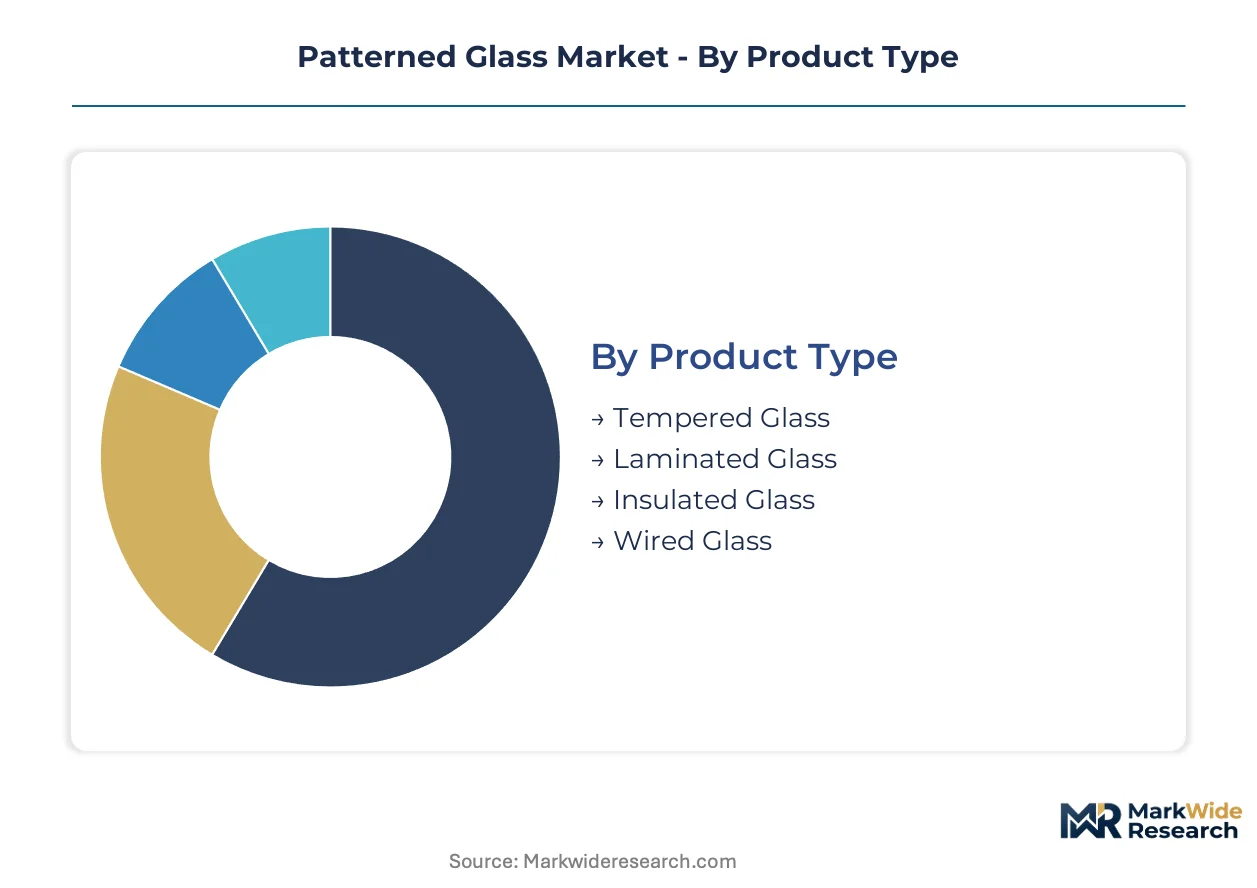
Segmentation in patterned glass reveals how channel economics, regulatory requirements, and aesthetic specifications fragment procurement across construction, automotive, and interior design verticals. Understanding these divides illuminates where coating investments, tempering capacity, and distribution relationships concentrate.
Product Type:
Tempered and laminated variants flow through distinct channel structures: tempered products dominate contractor-direct procurement for code-mandated safety applications, while laminated glass routes through facade specialists and acoustic consultants.
- Tempered Glass:Heat-treated to increase mechanical strength and shatter into granular fragments upon breakage, meeting ICC and ASTM safety mandates for hazardous locations in commercial architecture. Demand concentrates in India's commercial construction corridor—Mumbai, Bengaluru, and Hyderabad—where building codes mandate its use in high-traffic areas.
- Laminated Glass:Multiple glass layers bonded with interlayers provide acoustic dampening and post-breakage retention, commanding premium positioning in security-critical facades. Specifiers in corporate headquarters and luxury hospitality developments are bundling acoustic, safety, and decorative performance into integrated procurement packages.
- Insulated Glass:Multiple panes with gas-filled cavities deliver thermal performance for energy-efficient envelopes.
- Wired Glass:Embedded mesh provides fire-rated protection in institutional and heritage building retrofits.
By volume, tempered glass leads. By growth pace, laminated variants with acoustic interlayers are climbing the fastest.
Application:
Cost tiering separates specification patterns: premium architectural facades absorb coated and etched variants, while furniture and interior design segments prioritize aesthetic customization over thermal performance.
- Architecture:Curtain walls, skylights, and decorative facades integrate patterned glass for daylight diffusion and visual privacy. China's SAMR enforcement of updated GB 50189 standards is mandating lower U-values, accelerating coated patterned glass adoption in East Asian commercial specifications.
- Interior Design:Partitions, feature walls, and decorative surfaces employ chemically etched and digitally printed patterned glass for bespoke aesthetic effects. Hospitality and retail designers in Dubai and Singapore are specifying digitally customized surfaces for branded environments.
- Automotive:Decorative glazing for sunroofs and privacy glass applications.
- Furniture:Cabinet doors, tabletops, and display cases utilizing textured glass for visual interest.
Architecture generates the highest absolute volume. Interior design applications are gaining share fastest as digital printing compresses minimum order quantities.
End User:
Customer type determines specification authority and procurement cycle length: commercial developers issue performance-based tenders, while residential and retail segments route through distributor networks with shorter decision timelines.
- Commercial:Office towers, hospitality developments, and mixed-use projects specify patterned glass through performance-based procurement. State-level energy efficiency mandates in Maharashtra, Karnataka, and Telangana are tightening glazing standards for export-oriented manufacturers to capture.
- Residential:High-end housing and renovation projects prioritize privacy and decorative effects over thermal performance thresholds.
- Industrial:Manufacturing facilities and warehouses requiring natural light diffusion with minimal maintenance.
- Retail:Branded environments and flagship stores specifying digitally customized patterned surfaces.
Commercial end users dominate value capture. Residential segments show the steepest expansion trajectory as renovation activity accelerates.
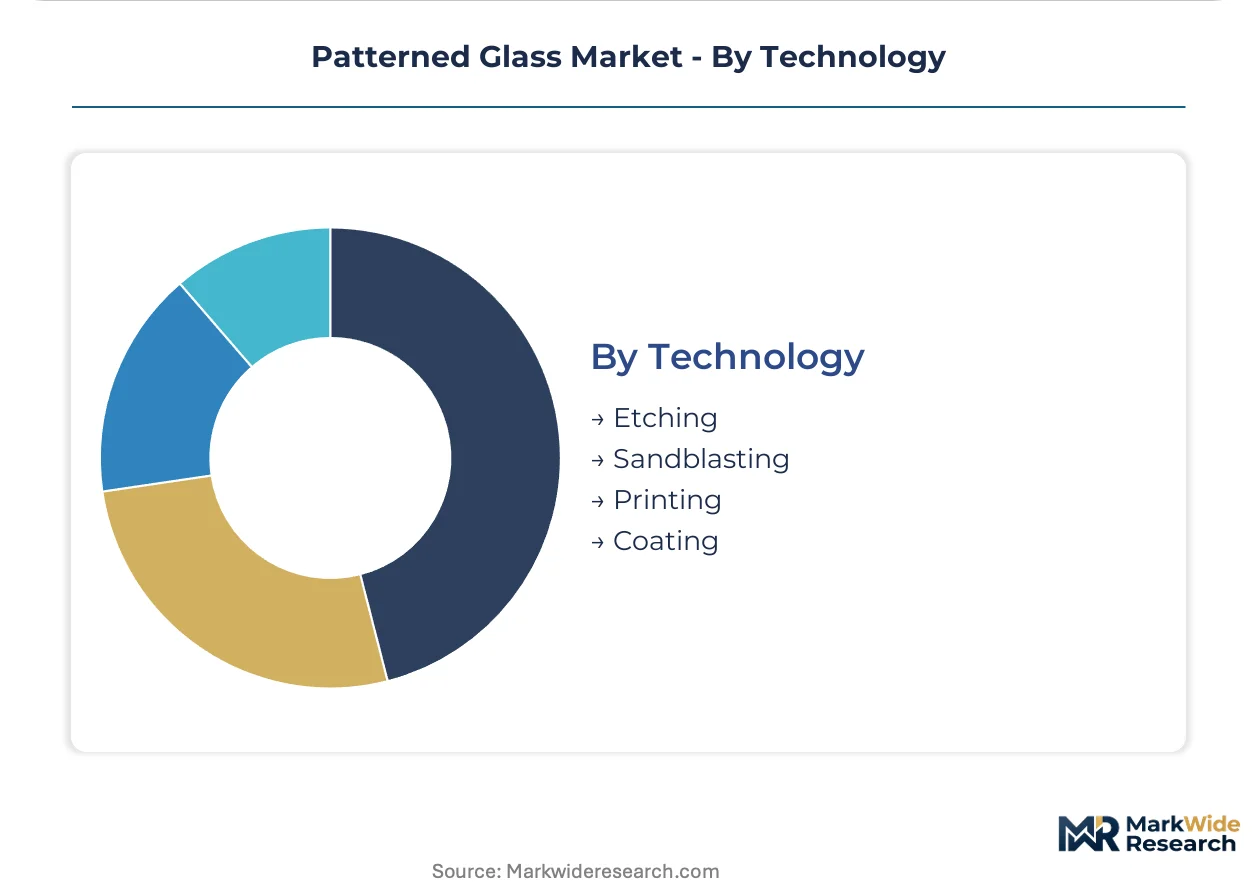
Technology:
Margin structure varies sharply by processing method: etching and coating command technology premiums, while sandblasting and printing compete on throughput and customization flexibility.
- Etching:Chemical or acid-based surface treatment creates fine-detail patterns unavailable through mechanical roll-pressing. High-end interior design segments in premium hospitality projects are adopting etched patterned glass for bespoke aesthetic differentiation.
- Coating:Low-emissivity and photocatalytic depositions merge energy performance with decorative requirements. Manufacturers serving export markets are reconfiguring coating lines to meet China's GB thermal performance thresholds.
- Sandblasting:Abrasive surface treatment for uniform matte finishes and privacy applications.
- Printing:Digital ceramic and screen-printed decorative treatments for project-specific customization.
Coating technology leads in value per square meter. Etching applications are expanding most quickly as architects specify finer surface detail than traditional forming methods permit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India's commercial construction corridor demonstrate the highest price elasticity, while specifiers in premium Middle Eastern hospitality projects absorb significant premiums for bespoke etched and digitally printed variants.
China
SAMR enforcement of updated GB 50189 standards is mandating lower U-values for curtain wall glazing in public buildings. Export-oriented manufacturers are reconfiguring low-emissivity coating lines to meet these thermal performance thresholds. Yangtze River Delta fabricators near Shanghai are capturing specification share in East Asian commercial facade projects.
India
Mumbai, Bengaluru, and Hyderabad are concentrating demand for architectural facades and decorative interior installations in premium office and hospitality developments. State-level energy efficiency mandates in Maharashtra, Karnataka, and Telangana are tightening glazing performance standards. Specifiers in these cities are issuing performance-based tenders rather than material-specific briefs.
United States
ICC and ASTM standards mandate tempered or laminated patterned glass in hazardous locations across commercial architecture. Commercial developers in Texas and Florida are driving volume for safety-code-compliant installations. Southeast construction corridors are absorbing tempered patterned products for high-traffic retail and hospitality developments.
Germany
EU Construction Products Regulation and CE marking govern thermal and mechanical performance claims across member states. German facade specialists are bundling acoustic, safety, and decorative performance into integrated procurement packages. Industrial clusters in North Rhine-Westphalia are serving premium corporate headquarters specifications across Northern Europe.
United Arab Emirates
Hospitality and retail designers in Dubai are specifying digitally customized patterned surfaces for branded environments. MOHAP building safety regulations intersect with international hospitality brand standards for decorative glazing. Premium developments on the Arabian Peninsula are absorbing the highest-value etched and ceramic-printed variants.
Patterned Glass Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence reorganizing competitive dynamics across the value chain. Heritage float-glass players leverage backward integration into soda ash and silica sand supplies to sustain cost advantages in tempered patterned products. Specialist fabricators compete on etching technology and coating customization for high-end interior applications. Dominant competitive moves include capacity reconfiguration to merge coating deposition with tempering processes, and geographic pre-certification to capture state-level energy code adoption in target markets.
Among integrated heritage players, Guardian Glass exemplifies the float-line network archetype, while Şişecam anchors the vertical supply control position across Turkey and Europe. AGC Inc. occupies the advanced coating technology leadership tier for architectural applications. These three represent distinct strategic postures: scale-driven manufacturing, upstream input security, and functional differentiation through surface engineering.
| Leading Market Players |
|---|
| Guardian Glass |
| Şişecam |
| AGC Inc. |
| Jinjing Group |
| Xinyi Glass |
| Saint-Gobain |
| Vitro Architectural Glass |
| Central Glass Co., Ltd. |
| NSG Group (Pilkington) |
| Others |
Value Chain & Pricing Dynamics
CE marking under the EU Construction Products Regulation gates both supply qualification and price differentiation simultaneously, mandating thermal and mechanical performance testing that only integrated manufacturers with captive laboratories can absorb without margin erosion. China's SAMR enforcement of updated GB standards for building energy efficiency imposes parallel certification burdens, compressing price realization for fabricators lacking coating-tempering integration while rewarding heritage players with pre-qualified product lines.
Pricing Analysis
After-sales revenue from warranty extensions and facade maintenance contracts drives lifetime value for tempered patterned glass installations in commercial developments. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and coating functionality, with low-emissivity variants capturing technology premiums. Pricing pressure stems from soda ash cost volatility concentrated among Turkish and European suppliers. Contractor-direct procurement for code-mandated safety applications demonstrates highest price sensitivity, while hospitality developers in Dubai absorb premiums for bespoke etched finishes.
Supply Chain Analysis
China and Turkey anchor flat glass float-line capacity, with Yangtze River Delta fabricators near Shanghai capturing specification share in East Asian commercial facade projects. Soda ash, silica sand, and natural gas feedstock dependencies tether margin structures to mining and energy commodity cycles. Single-source vulnerability concentrates in Turkish soda ash supplies controlled by vertically integrated heritage players. Distribution runs through facade specialists and acoustic consultants for laminated variants, while tempered products flow contractor-direct.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patterned glass sits in early-cycle expansion as India's commercial construction corridor concentrates demand for architectural facades and decorative interior installations ahead of state-level energy code adoption.
For Market Incumbents: Compound coating-tempering integration investments to capture specification share as China's GB 50189 standards tighten thermal performance thresholds. Deepen backward integration into soda ash and silica sand supplies to defend against input cost volatility eroding tempered product margins. Prioritize pre-certification to Maharashtra, Karnataka, and Telangana state codes before performance-based tenders reshape procurement criteria. For New Entrants and Emerging Players: Anchor in digitally printed patterned glass for hospitality and retail branded environments, where compressed minimum order quantities and project-specific pattern variations bypass roller changeover cost barriers. Target India's commercial construction corridor with acoustic-performance-integrated laminated products for open-plan office segments. Pursue specification partnerships with facade consultants bundling performance-based procurement packages. For Investors and Strategic Acquirers: China's SAMR enforcement of updated GB standards reshapes the acquisition landscape toward coating-capable fabricators with thermal performance testing infrastructure. Five-to-ten year viability favors specialists with etching technology leadership and geographic pre-certification breadth. Monitor state-level energy efficiency code adoption velocity across Indian states as inflection indicator for export-oriented manufacturing capacity deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Coating-Tempering Process Integration | Merges low-emissivity deposition with post-tempering thermal treatment to meet China's GB 50189 U-value mandates. |
| Geographic Pre-Certification Program | Captures specification share in India's state-level energy code adoption across Maharashtra, Karnataka, and Telangana. |
| Digital Ceramic Printing Deployment | Enables project-specific pattern variations for Dubai and Singapore hospitality designers without roller changeover costs. |
| Acoustic Interlayer R&D Partnership | Develops sound-dampening laminated products for open-plan office and hospitality segments in Bengaluru and Hyderabad. |
| Backward Integration into Soda Ash | Secures captive supply of critical raw material following Şişecam's vertical control model across Turkey and Europe. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with glass manufacturing executives, facade specification consultants, and commercial development procurement leads; and secondary validation through customs trade data, SEC filings of publicly traded glass manufacturers, and national building code regulatory databases. Bottom-up triangulation cross-referenced capacity announcements and coating line reconfigurations against top-down demand modeling from construction permit data across India's commercial construction corridor.
Across the analysis window, forecasts segmented by product type, application vertical, end-user category, and processing technology. Modeled dimensions included tempered versus laminated versus insulated glass variants, architectural facade versus interior design applications, and etching versus coating versus digital printing technologies. CAGRs derived from elasticity-adjusted volume projections against fixed investment cycles in float-line capacity. Industry-specific inputs incorporated thermal performance threshold trajectories under evolving GB and EU regulatory frameworks.
Decision-makers should treat outputs as directional under assumptions of continued state-level energy code adoption in India and sustained SAMR enforcement in China; material deviation in regulatory timelines or construction investment cycles would warrant model refresh. Recalibration cycles align with material shifts in national building code amendments and float-line capacity commissioning announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Optical Glass Market
Glass
Mirrored Glass Market
Glass
North America Glass Insulators Market
Glass
Antiglare Glass Market
Glass
GCC Flat Glass Market
Glass
Middle-East and Africa Flat Glass Market
Glass
Global Scratch Resistant Glass Market
Glass
Screen-Printing Glass Market
Glass
Glass Alternative Materials Market
Glass
Glass Prepreg Market
Glass
Heat Resistant Glass Market
Glass
3D Glass Market
Glass
Global Anti-Reflective Glass Market
Glass
Metallic Glass Market
Glass
Solar PV Glass Market
Glass
Glass Mason Jars Market