
 Europe Sapphire Glass Market | 2026-2036
Europe Sapphire Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sapphire Glass Market Intelligence
Subscription-based coating and surface treatment services is broadening what European sapphire glass suppliers monetize beyond the base material. SCHOTT AG leverages its fused silica heritage to anchor premium optical-grade sapphire contracts across German industrial accounts. Saint-Gobain Group sustains scale advantages through captive raw material sourcing and integrated melting operations in France. Crystran Ltd. specializes in precision-polished windows and domes for defense and aerospace buyers in the United Kingdom.
Europe sapphire glass consists of single-crystal aluminum oxide (Al₂O₃) grown through the Kyropoulos or heat exchange methods, achieving Mohs hardness of 9 and optical transmission from ultraviolet through mid-infrared wavelengths, primarily serving applications requiring scratch resistance, thermal stability, or chemical inertness. Monocrystalline sapphire dominates European volume due to established Kyropoulos capacity and watch industry heritage, while sapphire wafer formats are capturing R&D investment from semiconductor and LED substrate developers seeking larger diameters. Consumer electronics applications generate the highest absolute value but carry volatile order cycles tied to smartphone OEM procurement rhythms.
REACH compliance through ECHA governs chemical substance registration across EU manufacturing, while the EU Green Deal carbon border adjustments are reshaping energy-intensive crystal growth economics in Central European foundries. RoHS restrictions on hazardous substances limit certain dopants and process chemicals in consumer-facing sapphire components. Medical device manufacturers must navigate MDR certification pathways for implantable sapphire applications. Stakeholders should track how ETS carbon pricing and emerging CSRD disclosure mandates alter the cost structure of Verneuil and Kyropoulos furnace operations before committing capacity expansion decisions.
Market Dynamics
EU ETS carbon pricing is restructuring the economics of energy-intensive Kyropoulos furnace operations across Central European sapphire foundries, compressing margins for independent growers while favoring integrated energy players with captive renewable supply.
Growth Catalysts
- EU Green Deal carbon border adjustments:Domestic European sapphire producers gain cost advantage over imports from carbon-intensive Asian supply chains as CBAM phases in.
- Smartphone OEM procurement rhythms:German and French premium device manufacturers are expanding sapphire cover glass specifications for flagship launches.
- Switzerland's watchmaking corridor:Heritage demand for scratch-resistant sapphire crystals sustains baseline volume and process expertise transfer to optical applications.
Market Restraints
- High-purity alumina feedstock concentration:Ukrainian and Russian-origin raw material disruptions have tightened European supply routes.
- Energy cost volatility:Natural gas and electricity pricing swings directly impact Kyropoulos and Verneuil furnace operating economics.
- Synthetic quartz and chemically strengthened glass substitution:Lower-cost alternatives capture mid-tier consumer electronics applications.
Strategic Opportunities
- Poland and Czech Republic manufacturing zones:Lower ETS exposure and skilled labor pools attract sapphire wafer processing investment for semiconductor substrates.
- MDR-certified implantable sapphire:European medical device regulation pathways create premium pricing tiers for biocompatible optical components.
- Subscription-based surface treatment services:Coating and polishing capabilities are being unbundled from material supply into recurring revenue streams.
Industry Challenges
- Kyropoulos crystal growth technician scarcity:Decades-long apprenticeship requirements limit workforce expansion for precision optical-grade production.
- REACH chemical substance registration timelines:ECHA compliance documentation delays new dopant introductions and process modifications.
- Semiconductor-grade certification cycles:Extended qualification protocols with foundry customers lock up working capital for 18-24 month periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sapphire Glass Market |
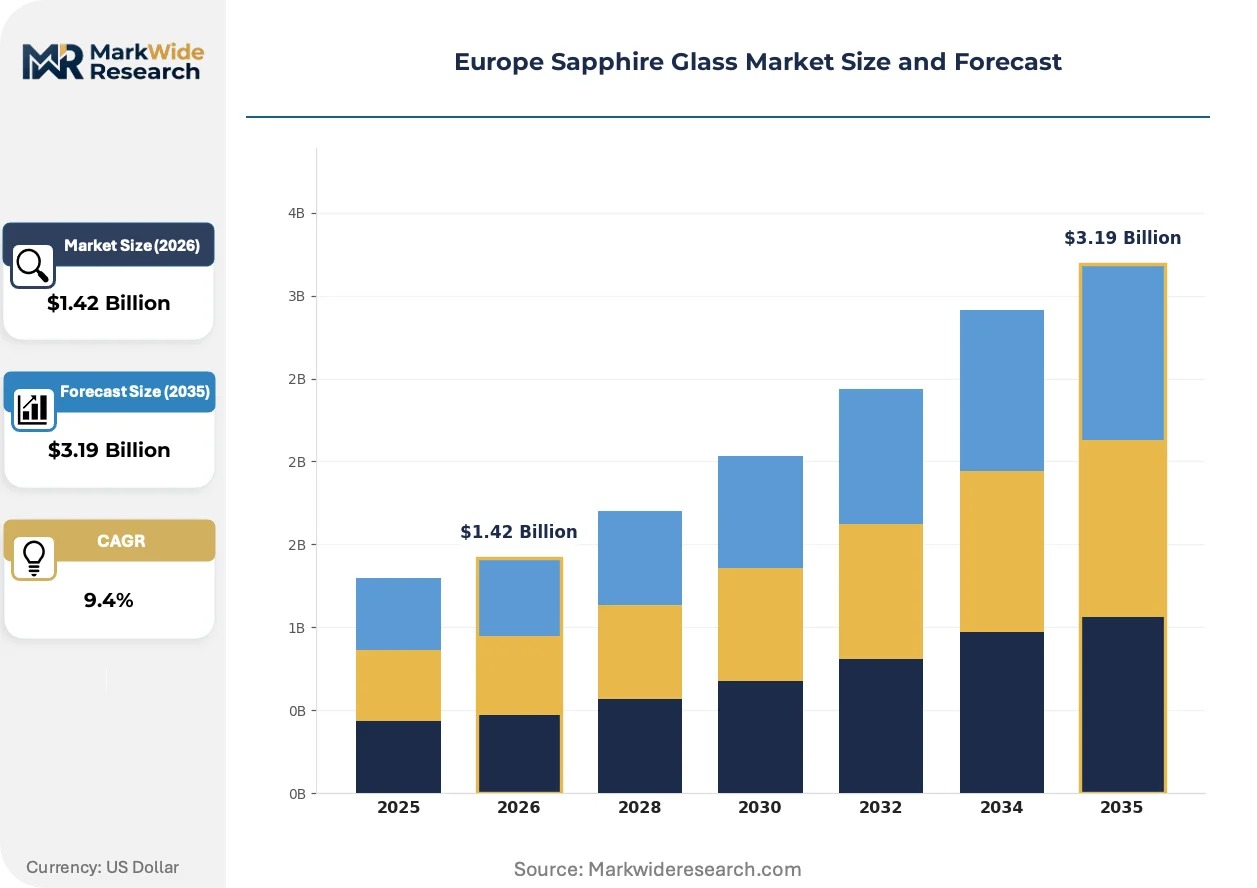
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.19 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Sapphire Substrate, Sapphire Wafer Application: Consumer Electronics, Jewelry, Aerospace, Medical Devices End User: Smartphone Manufacturers, Watchmakers, Aerospace Firms, Healthcare Providers Distribution Channel: Direct Sales, Online Retail, Specialty Stores, Distributors |
| Companies Covered | SCHOTT AG, Saint-Gobain Group, Crystran Ltd., Swiss Jewel Company, Monocrystal PLC, KYOCERA Corporation, Rubicon Technology Inc., Precision Sapphire Technologies Ltd., Rayotek Scientific Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sapphire Glass Market Strategic Shifts & Innovations
Heat exchange method crystal growth is displacing legacy Verneuil capacity for larger-diameter sapphire boules, while REACH-compliant process chemistry and coating-as-a-service business models are simultaneously reshaping how value is captured across the European value chain.
Edge-defined film-fed growth (EFG) technology is decentralizing sapphire wafer supply for LED and power electronics substrates. German industrial accounts are piloting EFG-sourced 6-inch and 8-inch diameters for silicon-on-sapphire (SOS) RF applications. This method is decentralizing production geography away from traditional Kyropoulos strongholds toward modular furnace deployments.
CSRD disclosure mandates are forcing Scope 3 emissions transparency across the sapphire value chain. Corporate sustainability reporting requirements now cover upstream alumina refining and downstream customer processing footprints. German and French publicly listed sapphire suppliers are restructuring supplier qualification criteria to meet audit-ready carbon accounting standards.
Equipment-as-a-service financing is displacing traditional capex purchase models for crystal growth furnaces. Polish and Czech precision optics clusters are accessing Kyropoulos capacity through operational lease structures rather than balance sheet investment. Switzerland's watch component suppliers remain the most concentrated buyers of outright furnace ownership, preserving process control over proprietary crystal recipes.
Europe Sapphire Glass Market Segmentation
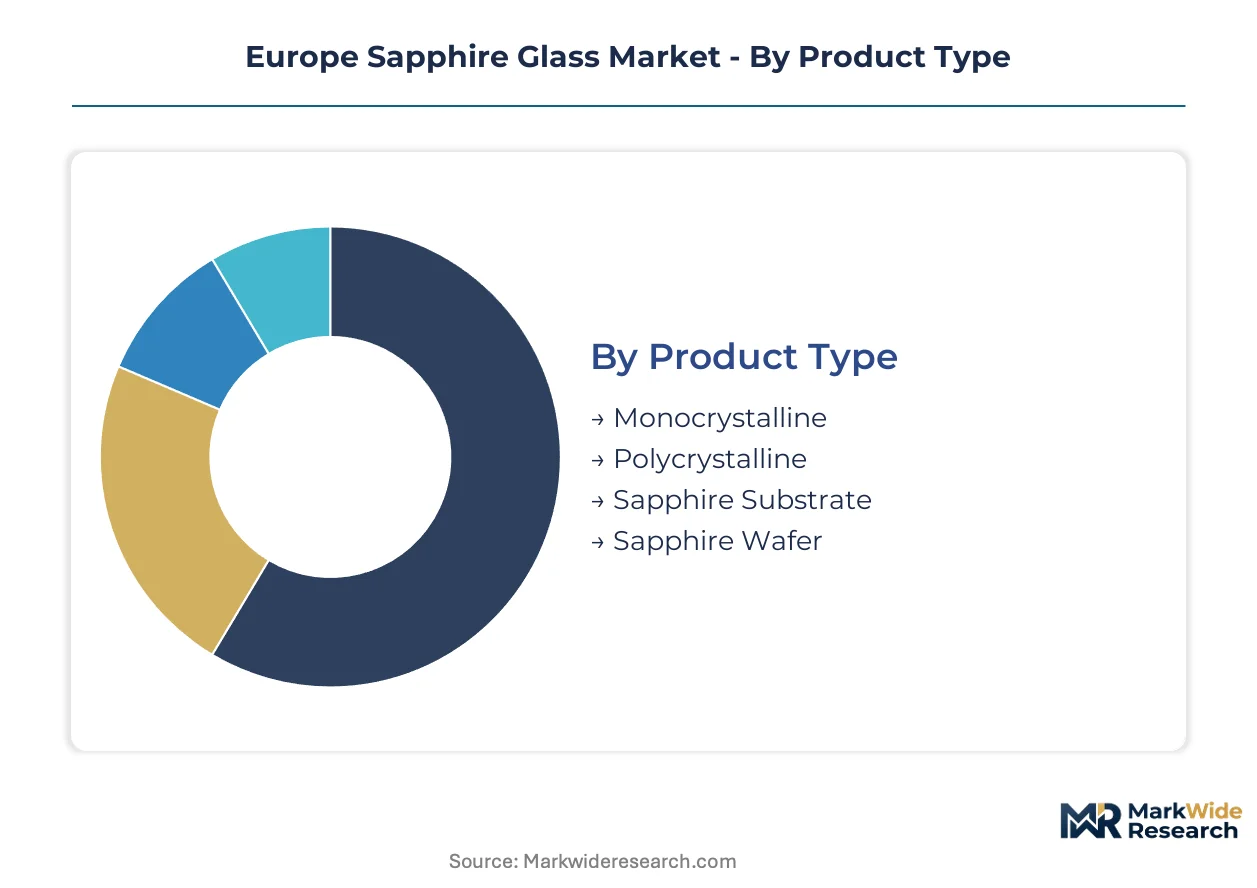
European sapphire glass buyers prioritize thermal stability and optical clarity specifications over base material cost, creating distinct procurement patterns across Kyropoulos-grown boules, precision-polished substrates, and finished components. Segmentation reveals how Switzerland's watchmaking heritage, Germany's precision optics cluster, and France's integrated melting operations each anchor different product and application tiers.
Product Type:
Material purity and crystal growth method determine pricing power and end-use qualification thresholds.
- Monocrystalline:Single-crystal aluminum oxide grown via Kyropoulos or heat exchange methods delivers Mohs hardness of 9 and ultraviolet-to-mid-infrared transmission. Demand concentrates in Switzerland's watchmaking corridor, where scratch-resistant crystals sustain heritage volume and process expertise transfers to optical applications.
- Sapphire Wafer:Precision-sliced substrates in 6-inch and 8-inch diameters serve silicon-on-sapphire RF applications and LED epitaxy. German semiconductor developers are piloting larger formats, though qualification cycles lock up working capital for 18-24 month periods.
- Polycrystalline:Multi-grain structures offer cost-efficient thermal and mechanical protection for industrial windows and furnace viewports.
- Sapphire Substrate:Intermediate-processed boules and blanks supply downstream polishers and coaters across Central European precision optics clusters.
Monocrystalline leads on scale; sapphire wafer leads on momentum.
Application:
End-use certification requirements and order cycle volatility separate premium contract tiers from spot-market procurement.
- Consumer Electronics:Cover glass and camera lens specifications for flagship smartphones drive absolute value but carry volatile OEM procurement rhythms tied to German and French premium device launches.
- Medical Devices:Implantable sapphire components for surgical instruments and optical probes command premium pricing through MDR-certified biocompatibility pathways.
- Aerospace:Infrared domes, missile windows, and sensor housings require defense-grade certification from United Kingdom and French aerospace primes.
- Jewelry:Scratch-resistant watch crystals and luxury accessories sustain baseline volume from Switzerland's heritage manufacturers.
Consumer electronics dominates absolute revenue; medical devices climbs fastest on regulatory premium capture.
End User:
Customer technical sophistication and captive processing capabilities determine whether suppliers sell raw boules, polished blanks, or coated finished goods.
- Smartphone Manufacturers:German and French OEMs specify optical-grade cover glass with anti-reflective and oleophobic coatings, driving subscription-based surface treatment services.
- Watchmakers:Switzerland's concentrated buyer base preserves proprietary crystal recipes through outright furnace ownership rather than operational leasing.
- Aerospace Firms:United Kingdom defense contractors and French aviation suppliers demand precision-polished windows with military-specification traceability.
- Healthcare Providers:European medical device manufacturers navigate MDR certification for implantable optical components, creating premium pricing tiers.
Watchmakers anchor stable demand; smartphone manufacturers generate highest absolute value volatility.
Distribution Channel:
Order size and technical service intensity dictate channel selection across the value chain.
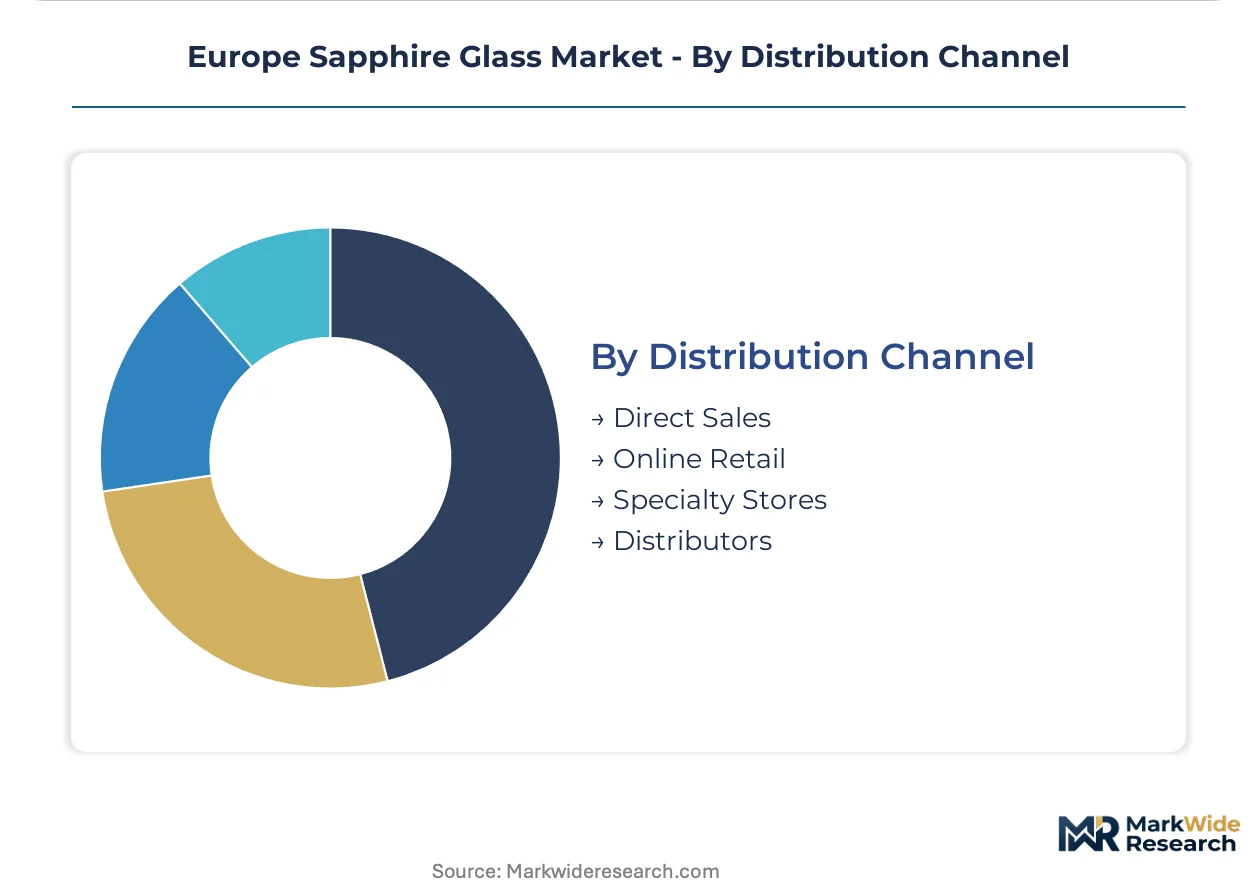
- Direct Sales:Long-term supply agreements with German industrial accounts and Swiss watch component suppliers bypass intermediaries for optical-grade and jewelry-grade volumes.
- Distributors:Regional stockists serve mid-tier Polish and Czech precision optics shops with standardized wafer formats and furnace spare parts.
- Specialty Stores:Small-lot procurement for research institutions and prototype developers across French and United Kingdom university clusters.
- Online Retail:Catalog sales for replacement watch crystals and DIY optical components, limited by REACH compliance documentation requirements.
Direct sales commands margin; distributors expand geographic reach fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting sapphire glass production toward jurisdictions with lower EU ETS exposure and streamlined REACH compliance pathways. Central European manufacturing zones attract wafer processing investment from cost-sensitive semiconductor substrate developers.
Germany
Precision optics clusters in Bavaria and Baden-Württemberg drive demand for Kyropoulos-grown boules with ultraviolet-to-mid-infrared transmission specifications. The EU Green Deal carbon border adjustments favor domestic producers over carbon-intensive imports. Munich-based industrial accounts anchor premium optical-grade contracts through direct supply agreements.
Switzerland
Geneva and Neuchâtel watchmaking corridors sustain heritage demand for scratch-resistant sapphire crystals with Mohs hardness of 9. Swissmedic regulates biocompatibility standards for implantable optical components. Jura region manufacturers preserve proprietary crystal recipes through outright furnace ownership rather than operational leasing.
France
Integrated melting operations in Auvergne-Rhône-Alpes leverage captive raw material sourcing for scale advantages. ANSM oversees medical device regulation pathways for surgical instrument applications. Lyon-area foundries supply precision-polished substrates to aerospace primes requiring military-specification traceability.
United Kingdom
Defense and aerospace buyers in England's Midlands and Scotland demand infrared domes and missile windows with defense-grade certification. REACH compliance through ECHA governs chemical substance registration for process modifications. Dorset-based precision optics shops specialize in finished components for research institutions.
Poland
Lower ETS exposure and skilled labor pools in Lower Silesia and Greater Poland attract sapphire wafer processing investment for LED and power electronics substrates. Polish precision optics clusters access Kyropoulos capacity through equipment-as-a-service financing. Wrocław-area facilities pilot 6-inch and 8-inch diameters for silicon-on-sapphire RF applications.
Europe Sapphire Glass Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated energy players and independent growers occupying distinct cost positions. The vendor base concentrates around three strategic archetypes: legacy optical glass conglomerates with fused silica heritage, specialty crystal growers with captive furnace ownership, and modular processing specialists serving semiconductor qualification cycles. M&A activity targets REACH-compliant process chemistry capabilities, while capacity expansion concentrates in Central European zones with favorable carbon pricing exposure.
Among Germany-based fabricators, SCHOTT AG represents the legacy optical conglomerate archetype, leveraging heritage positioning to anchor premium industrial accounts. Saint-Gobain Group exemplifies integrated scale advantages through its French melting operations and captive raw material sourcing. Crystran Ltd. occupies the specialist tier within United Kingdom-based precision optics, serving defense and aerospace buyers requiring finished window and dome configurations.
| Leading Market Players |
|---|
| SCHOTT AG |
| Saint-Gobain Group |
| Crystran Ltd. |
| Swiss Jewel Company |
| Monocrystal PLC |
| KYOCERA Corporation |
| Rubicon Technology Inc. |
| Precision Sapphire Technologies Ltd. |
| Rayotek Scientific Inc. |
| Others |
Cost & Logistics Intelligence
German and French smartphone OEM procurement concentration anchors contract-based long-term offtake pricing for optical-grade sapphire cover glass, with subscription-based surface treatment services layering recurring revenue atop base material transactions. This buyer archetype's flagship launch cycles create demand spikes that Kyropoulos furnace operators must absorb through capacity buffers or spot-market premiums.
Pricing Analysis
Capacity additions in Poland and the Czech Republic are reshaping price floors for sapphire wafer formats serving silicon-on-sapphire RF applications. Three-tier pricing structure across premium optical-grade, standard industrial-grade, and economy polycrystalline levels separates MDR-certified medical components from furnace viewport applications. Pricing pressure stems from synthetic quartz substitution in mid-tier consumer electronics, compressing margins for non-differentiated growers. Smartphone manufacturers exhibit highest price sensitivity due to bill-of-materials scrutiny, while Swiss watchmakers absorb premiums for proprietary crystal recipes.
Supply Chain Analysis
Kyropoulos crystal growth technician scarcity across Germany, Switzerland, and France constrains furnace utilization rates and extends lead times for precision optical-grade production. European sapphire supply draws from Ukrainian and Russian-origin high-purity alumina feedstock, with alternative Australian and Canadian routes gaining share after geopolitical disruptions. Single-source vulnerability concentrates in Central European foundries dependent on natural gas furnace heating. Distribution runs through direct sales agreements with Munich-based industrial accounts and Swiss watch component suppliers, bypassing intermediaries for qualified optical volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe sapphire glass market compounds steadily as EU Green Deal carbon border adjustments structurally favor domestic producers over carbon-intensive Asian imports. This regulatory force sustains pricing power for integrated European operators with renewable energy access.
For Market Incumbents: Deploy equipment-as-a-service financing to capture Polish and Czech precision optics clusters seeking Kyropoulos capacity without balance sheet investment. Deepen backward integration into captive alumina refining to offset Ukrainian and Russian-origin feedstock disruption risks. Prioritize REACH-compliant process chemistry acquisitions to accelerate new dopant introductions ahead of ECHA documentation timelines.
For New Entrants and Emerging Players: Capture MDR-certified implantable sapphire white space in French and United Kingdom medical device corridors, where biocompatibility premiums exceed standard industrial pricing. Target semiconductor substrate qualification cycles in German silicon-on-sapphire RF development programs as the most penetrable entry vector. Lead with coating-as-a-service business models to unbundle surface treatment from material supply and establish recurring revenue relationships.
For Investors and Strategic Acquirers: Integrated energy players with captive renewable supply are the most active acquirer in this space, seeking to deploy surplus power into energy-intensive crystal growth operations. Long-term viability rests on carbon pricing trajectory and CSRD disclosure mandate enforcement breadth. Monitor EU ETS allowance price movements as the inflection signal for Central European capacity expansion economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Refining | Secures feedstock autonomy against Ukrainian and Russian-origin supply disruptions. |
| MDR Certification Pathway Investment | Unlocks premium pricing tiers for implantable optical components in French medical device markets. |
| Equipment-as-a-Service Financing Launch | Enables Polish and Czech precision optics clusters to access Kyropoulos capacity without capex burden. |
| REACH-Compliant Process Chemistry Acquisition | Accelerates ECHA registration timelines for new dopants and coating formulations. |
| Carbon Border Adjustment Compliance Program | Preserves cost advantage over Asian imports as EU Green Deal CBAM phases in fully. |
Research Approach
Coverage spans Germany, Switzerland, France, the United Kingdom, Poland, and the Czech Republic, with primary inputs from each jurisdiction's precision optics clusters and regulatory authorities. Crystal growth furnace operators, smartphone OEM procurement leads, Swiss watch component suppliers, medical device regulatory affairs directors, and aerospace prime contractors provided qualitative ground-truth. Secondary validation drew from ECHA REACH registration databases, EU ETS carbon market disclosures, SEC filings of listed sapphire suppliers, and customs trade flow records. Bottom-up volume builds triangulated against top-down spending estimates across the analysis window.
Rate-of-change decomposition separated volume growth from price evolution across product type, application, and end user dimensions. The analytical framework modeled Kyropoulos boule diameter expansion, heat exchange method adoption curves, and EFG technology penetration for semiconductor substrates throughout the forecast period. CAGRs were derived from segment-level growth rate distributions weighted by base-year revenue contributions. Industry-specific inputs included EU ETS carbon price trajectory assumptions and MDR certification timeline distributions for implantable optical components.
Energy cost volatility, alumina feedstock supply disruption, and semiconductor-grade qualification cycle extensions are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding regulatory enforcement consistency and technology substitution thresholds. Material deviation in carbon pricing, REACH compliance timelines, or smartphone OEM procurement rhythms warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Tempered Glass Market
Glass
North America Glass Insulators Market
Glass
Recycled Glass Market
Glass
North America Industrial Silica Sand Market
Glass
UAE Silica Sand Market
Glass
Coated Solar Control Glass Market
Glass
Glass Grade Dolomite Market
Glass
Global Energy Efficient Glass Market
Glass
Double Glazing Glass Market
Glass
Glass Forming Machine Market
Glass
Glass Alternative Materials Market
Glass
Advanced Glass Market
Glass
Silica Sand Market
Glass
Solar Reflective Glass Market
Glass
Flexible Glass Market
Glass
Europe Silica Sand for Glass Making Market