
 China Flat Glass Market | 2026-2036
China Flat Glass Market Size, Share, and Industry Trends Forecast 2026-2036
China Flat Glass Market Insights
Buyer concentration among solar panel manufacturers and large-scale property developers is expanding as procurement scales toward integrated energy-efficient building projects. China National Building Material Group Corporation leverages its state-backed vertical integration across raw material sourcing and float glass production to dominate volume supply. Fuyao Glass Industry Group Co. Ltd anchors automotive glazing demand through specialized tempered and laminated product lines for electric vehicle OEMs. Xinyi Glass Holdings Limited competes on solar glass specialization, extending its capacity to serve photovoltaic module producers in Jiangsu and Anhui provinces.
Flat glass comprises silica sand, soda ash, and limestone melted at approximately 1500°C and formed through the float process onto molten tin baths, yielding uniform sheets for architectural glazing, vehicle windows, and electronic displays. Float glass sustains the largest production volume base, though margin pools increasingly shift toward coated and low-emissivity variants driven by green building codes. Tempered glass leads safety-critical applications in automotive and high-rise construction, while laminated glass captures premium positioning in hurricane-resistant and acoustic insulation segments.
China's Ministry of Ecology and Environment enforces dual carbon targets that compel flat glass producers to retrofit furnaces and adopt cleaner fuels, while SAMR oversees GB standards compliance for thermal performance and product safety. The national building regulator mandates escalating energy efficiency coefficients that directly specify low-E and insulated glass configurations in new commercial and residential projects. Stakeholders must monitor provincial implementation timelines for carbon intensity caps and assess furnace upgrade cycles against evolving certification requirements.
Market Dynamics
China's dual carbon goals are forcing furnace retrofits and fuel-switching across the flat glass sector, compressing margins for producers while accelerating demand for low-emissivity and solar glass variants in construction and photovoltaic applications.
Growth Catalysts
- Building energy efficiency mandates:Updated GB standards issued by SAMR mandate low-E glass in new commercial and high-rise residential projects, pulling volume toward coated variants.
- Solar photovoltaic expansion:Photovoltaic panel manufacturing concentrates in Jiangsu and Anhui provinces, creating dedicated demand channels for ultra-clear solar glass with anti-reflective coatings.
- Yangtze River Delta clustering:Production capacity agglomerates across Shanghai, Jiangsu, and Zhejiang, reducing logistics costs for architectural glazing destined for eastern China's urban construction pipeline.
Market Restraints
- Soda ash price volatility:Raw material costs fluctuate with energy-intensive production of synthetic soda ash, squeezing float glass margins during fuel price spikes.
- Furnace emission retrofits:MEE enforcement of carbon intensity caps compels capital-intensive natural gas conversions or oxy-fuel upgrades, locking cash in long-cycle assets.
- Alternative glazing materials:Polycarbonate and advanced polymer composites penetrate select automotive and lightweight architectural segments where weight reduction outweighs optical clarity requirements.
Strategic Opportunities
- Western China greenfield capacity:Sichuan and Chongqing offer untapped natural gas reserves and lower carbon grid intensity for new low-carbon glass production serving interior markets.
- Building-integrated photovoltaics:Transparent solar glass converges photovoltaic generation with architectural glazing, opening premium positioning in net-zero commercial developments.
- Carbon credit monetization:China's national ETS expansion creates tradable offset potential for early furnace decarbonization adopters with verified emission reductions.
Industry Challenges
- Oxy-fuel combustion engineering shortage:Specialized furnace redesign expertise for emission reduction retrofits concentrates among a limited pool of European and domestic engineering contractors, extending project timelines.
- GB standard compliance lag:Testing laboratory capacity bottlenecks delay certification for new low-E coating formulations, holding back product launches against tightening thermal performance tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Flat Glass Market |
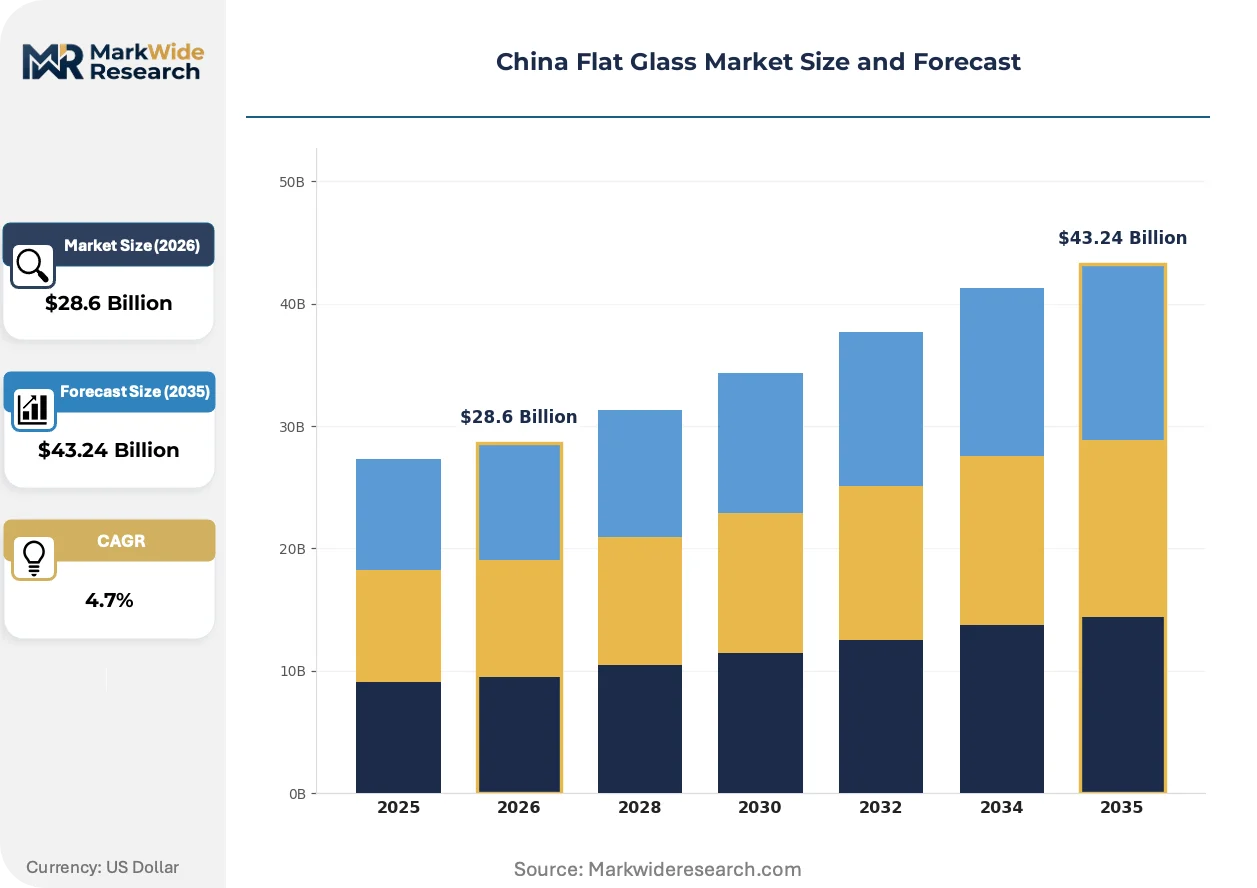
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Float Glass, Tempered Glass, Laminated Glass, Insulated Glass Application: Construction, Automotive, Electronics, Furniture End User: Architects, Manufacturers, Retailers, Installers Technology: Coating, Blowing, Casting, Cutting |
| Companies Covered | China National Building Material Group Corporation, Fuyao Glass Industry Group Co. Ltd, CSG Holding Co. Ltd, Qingdao REXI Industries Co.,Ltd, Taiwan Glass Ind. Corp., Xinyi Glass Holdings Limited, China Yaohua Glass Co. Ltd, Qingdao Laurel Glass Technology Co. Ltd, China Glass Holdings Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Flat Glass Market Trends and Innovations
Float glass production is absorbing digital process controls and advanced coating technologies that reshape product mix toward energy-efficient variants, while regulatory pressure on carbon intensity forces simultaneous fuel and equipment transitions.
Vacuum-insulated glass technology is absorbing market attention as a next-generation thermal barrier for ultra-low energy buildings. High-performance residential developers in Beijing and Shanghai specify triple-pane vacuum units to meet passive house criteria. This technology is absorbing share from conventional double-glazed insulated units in premium segments where space constraints limit cavity depth.
MEE enforcement of carbon intensity benchmarks compels fuel switching from heavy oil to natural gas or hydrogen-ready burners. Glass producers face 18-24 month furnace rebuild cycles to comply with provincial emission caps taking effect in sequential waves. Jiangsu-based manufacturers are most exposed given the province's earlier compliance deadlines and stricter local air quality targets.
Property developers are consolidating procurement through integrated energy-efficient building packages rather than discrete glass purchasing. Large-scale state-owned construction groups in the Yangtze River Delta now specify performance-based glazing contracts tied to whole-building energy modeling. This behavioral shift concentrates buyer power among top-tier developers and squeezes mid-scale fabricators unable to offer certified system integration.
China Flat Glass Market Segmentation
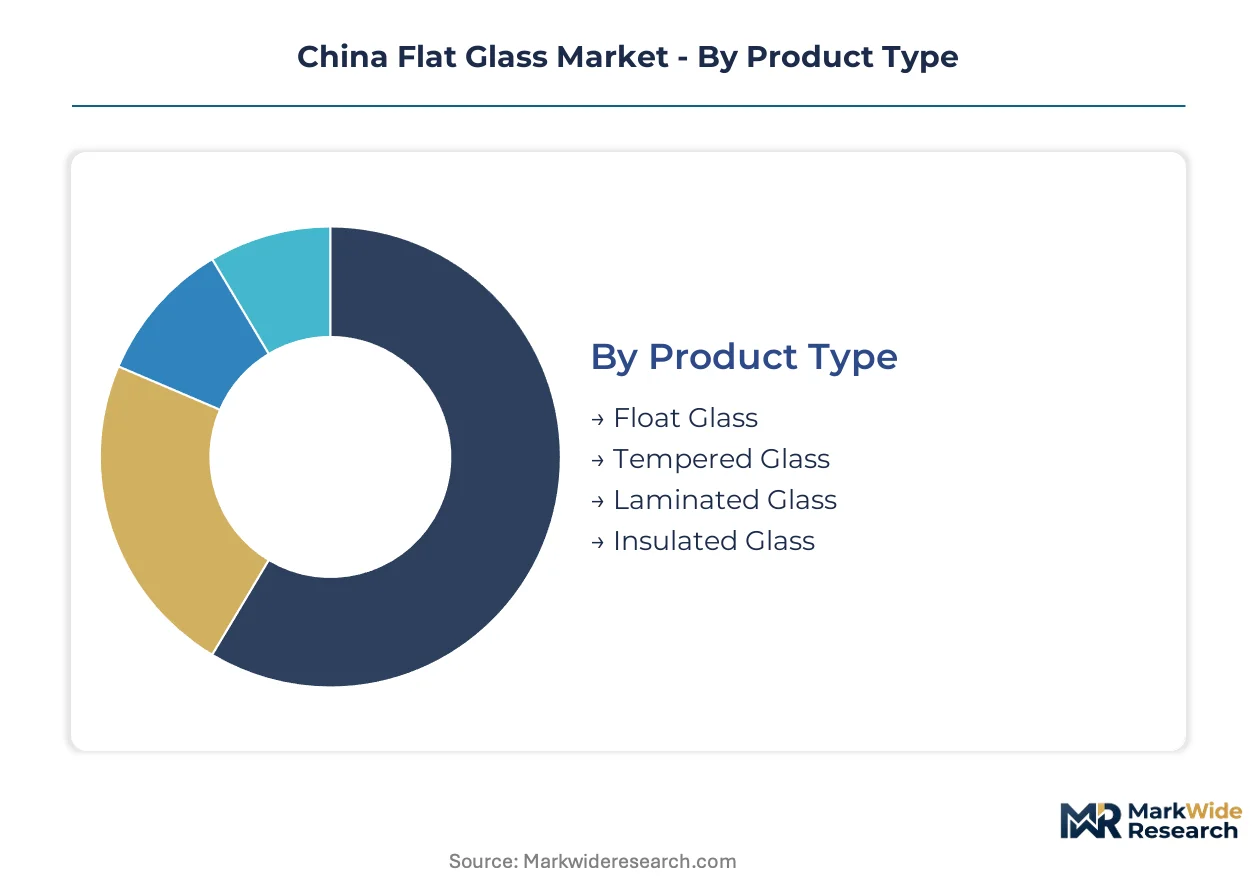
Flat glass segmentation in China reflects divergent certification pathways and thermal performance tiers. SAMR's escalating GB standards for building energy efficiency and MEE's carbon intensity enforcement create distinct compliance burdens across product categories.
Product Type:
GB standard compliance intensity varies sharply across product types, with low-emissivity and solar-rated variants facing extended certification timelines due to SAMR laboratory capacity constraints.
- Float Glass:Silica-sand, soda-ash, and limestone formulations melted at 1500°C and formed on molten tin baths yield uniform base sheets. Production concentrates in the Yangtze River Delta cluster spanning Shanghai, Jiangsu, and Zhejiang, where logistics costs to eastern construction markets remain compressed.
- Tempered Glass:Rapid thermal strengthening creates safety-critical fragmentation patterns. Demand anchors in automotive glazing for electric vehicle OEMs and high-rise construction where impact resistance is mandatory under updated building codes.
- Laminated Glass:Polyvinyl butyral interlayers bond glass plies for acoustic and hurricane-resistant applications. Premium positioning in net-zero commercial developments drives specification.
- Insulated Glass:Multiple panes with sealed air or gas cavities deliver thermal barriers. Vacuum-insulated variants absorb share in Beijing and Shanghai passive house projects where cavity depth is constrained.
Leading the category by volume: Float Glass. Expanding most quickly: Insulated Glass.
Application:
End-use concentration determines margin structure, with construction procurement consolidating through integrated energy-efficient building packages while automotive retains specialized technical specifications.
- Construction:Architectural glazing dominates volume absorption under dual carbon mandates. State-owned developers in the Yangtze River Delta now specify performance-based contracts tied to whole-building energy modeling.
- Automotive:Tempered and laminated configurations serve electric vehicle OEMs through specialized product lines. Weight reduction pressures from polycarbonate alternatives constrain optical-clarity segments.
- Electronics:Ultra-thin float variants supply display substrates. Jiangsu-based fabricators serve module producers with tight thickness tolerances.
- Furniture:Decorative and safety-rated glass penetrates interior applications. Smaller-scale procurement patterns resist consolidation seen in commercial construction.
Construction commands volume leadership. Electronics demonstrates steepest expansion trajectory as display manufacturing scales.
End User:
Procurement scale and technical specification authority separate end-user tiers, with architects and large manufacturers wielding disproportionate influence over product mix decisions.
- Architects:Design-phase specification of low-E and insulated configurations determines downstream demand. Beijing and Shanghai firms lead passive house adoption.
- Manufacturers:Solar panel producers in Jiangsu and Anhui provinces drive ultra-clear solar glass procurement at expanding scale. Photovoltaic module integration demands anti-reflective coating compatibility.
- Retailers:Replacement and renovation markets distribute through regional distribution networks. Price sensitivity exceeds new construction channels.
- Installers:Field execution quality affects warranty claims and thermal performance verification. Certification requirements lag manufacturing standards.
Manufacturers dominate procurement value. Architects represent the fastest-climbing influence tier as performance-based specifications tighten.
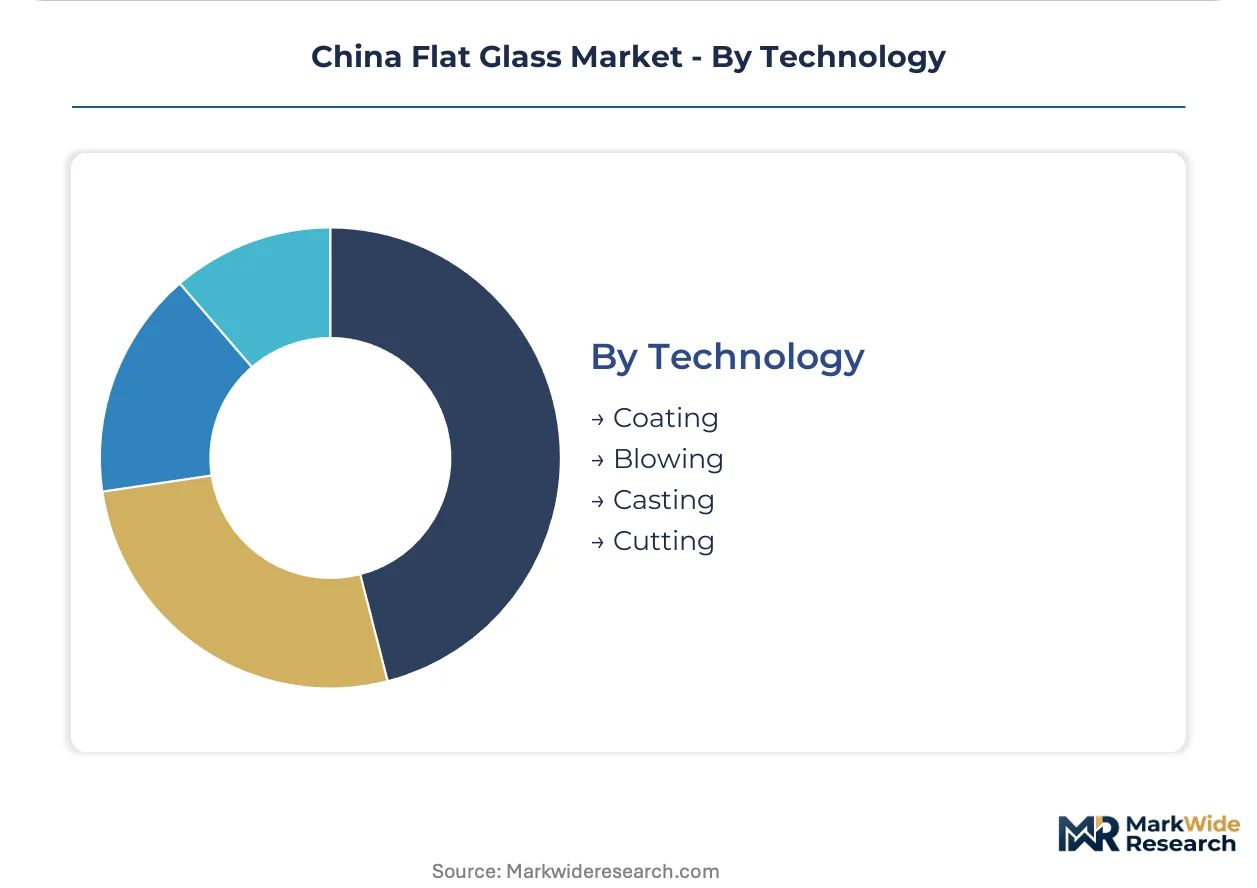
Technology:
Process technology differentiation separates commodity production from premium positioning, with coating capabilities absorbing disproportionate capital investment.
- Coating:Chemical vapor deposition and sputtering apply low-emissivity and anti-reflective layers. MEE carbon intensity caps accelerate natural gas and hydrogen-ready burner retrofits for coating lines.
- Blowing:Hollow glass formation serves specialized lighting and container applications. Limited penetration in flat glass mainstream.
- Casting:Rolled and patterned variants deliver textured surfaces for privacy and decorative functions. Lower capital intensity than float lines.
- Cutting:CNC and waterjet precision sizing serves downstream fabrication. Digital process controls reduce waste in high-volume architectural processing.
Coating technology anchors margin expansion. Cutting automation gains share fastest as fabricators respond to developer consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction procurement concentrates in eastern coastal provinces where state-owned developers drive specification of performance-based glazing contracts. Dual carbon mandates from MEE and SAMR's escalating GB standards reshape regional production priorities.
Yangtze River Delta
Shanghai, Jiangsu, and Zhejiang anchor architectural glazing demand through integrated energy-efficient building packages. MEE's carbon intensity caps compel furnace retrofits ahead of 2025 compliance deadlines. Jiangsu-based manufacturers face the strictest provincial air quality targets, accelerating natural gas conversions.
Pearl River Delta
Guangdong's electronics manufacturing cluster absorbs ultra-thin float variants for display substrates. SAMR laboratory capacity constraints delay low-E coating certifications for export-oriented fabricators. Shenzhen and Dongguan house downstream processing centers serving ASEAN module producers.
Beijing-Tianjin-Hebei
Passive house developers in Beijing specify vacuum-insulated glass for ultra-low energy buildings. The national building regulator mandates escalating thermal performance coefficients for commercial projects. Tianjin's port infrastructure supports coated glass exports to Northeast Asian markets.
Sichuan-Chongqing
Untapped natural gas reserves attract greenfield low-carbon glass production for interior markets. Western China's lower grid carbon intensity appeals to producers seeking ETS credit monetization. Chongqing's expanding automotive sector generates tempered glass demand from electric vehicle OEMs.
Shandong Peninsula
Soda ash production clusters in Shandong create raw material cost advantages for float glass manufacturers. Provincial emission standards align with national dual carbon timelines. Qingdao's port facilities enable solar glass exports to photovoltaic module producers in Southeast Asia.
China Flat Glass Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue solar specialization and automotive glazing integration. State-backed conglomerates dominate volume supply through captive raw material sourcing. Three archetypes define competitive positioning: vertically integrated building material groups, automotive glazing specialists, and solar glass pure-plays. Capacity expansion and furnace decarbonization represent the dominant competitive moves, with strategic partnerships linking fabricators to downstream energy-efficient building developers.
Among state-backed building material groups, China National Building Material Group Corporation exemplifies vertical integration across silica sand sourcing and float production. Fuyao Glass Industry Group Co. Ltd and Xinyi Glass Holdings Limited occupy distinct specialization vectors within the automotive and solar tiers respectively. These three entities represent the spectrum from commodity volume to premium niche positioning in a market where procurement consolidation favors scale-backed certification capabilities.
| Leading Market Players |
|---|
| China National Building Material Group Corporation |
| Fuyao Glass Industry Group Co. Ltd |
| CSG Holding Co. Ltd |
| Qingdao REXI Industries Co.,Ltd |
| Taiwan Glass Ind. Corp. |
| Xinyi Glass Holdings Limited |
| China Yaohua Glass Co. Ltd |
| Qingdao Laurel Glass Technology Co. Ltd |
| China Glass Holdings Limited |
| Others |
Pricing and Supply Chain Analysis
Soda ash, the energy-intensive alkali compound essential to glass melting chemistry, flows from Shandong's synthetic production clusters through pricing tiers that stratify across premium low-E coated, standard architectural float, and economy-grade unprocessed sheet glass. MEE carbon intensity enforcement compresses margins on heavy oil-fired float lines while SAMR certification bottlenecks for thermal performance grades concentrate pricing power among furnace-retrofitted producers serving Yangtze River Delta developers.
Pricing Analysis
Volume concentrates in commodity float glass where margins thin under fuel-switching compliance costs, while premium pools shift toward coated low-E and solar-rated variants. Pricing stratifies across certification tiers: GB-standard thermal performance grades command developer premiums, uncoated architectural base sheets compete on logistics efficiency, and spot-market salvage absorbs oversupply. Cost compression in standard float intensifies because natural gas retrofit capital locks cash in long-cycle assets. State-owned construction groups exhibit lowest price sensitivity through performance-based bundled procurement; regional fabricators and replacement retailers face acute margin pressure.
Supply Chain Analysis
Domestic-content mandates under China's dual carbon framework reshape sourcing toward captive silica sand deposits and provincial natural gas reserves. Supply concentrates in China, with production clustering in Jiangsu, Zhejiang, and Shandong provinces. Raw material dependencies rest on synthetic soda ash, high-purity silica sand, and limestone flux. Single-source vulnerability concentrates in European engineering contractors for oxy-fuel furnace retrofits. Distribution runs through integrated building material groups delivering performance-certified glazing packages to state-owned developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream control over captive soda ash and silica sand deposits separates margin-defensible producers from exposed commodity fabricators. Downstream, certification capabilities for GB-standard thermal performance tiers determine access to consolidated developer procurement.
For Market Incumbents: Acquire captive natural gas reserves and oxy-fuel engineering partnerships to secure furnace retrofit timelines ahead of Jiangsu's stricter MEE deadlines. Consolidate testing laboratory relationships to bypass SAMR certification bottlenecks for low-E coating formulations. Polycarbonate automotive glazing substitution and emerging solar glass pure-plays threaten specialized product lines without continuous coating R&D investment.
For New Entrants and Emerging Players: Launch via building-integrated photovoltaics transparent solar glass partnerships with net-zero commercial developers in Beijing and Shanghai. Western China greenfield capacity in Sichuan and Chongqing offers untapped natural gas access and lower grid carbon intensity for ETS credit positioning. White-space penetration targets vacuum-insulated glass for passive house specifications where cavity depth constraints limit incumbent double-glazed substitution.
For Investors and Strategic Acquirers: SAMR laboratory capacity expansion announcements are the leading indicator that certification-constrained low-E coating margins will compress toward commodity float levels. Long-term viability across the projection horizon favors producers with backward integration into raw materials and forward integration into performance-based developer contracts. Acquisition target archetype: mid-scale fabricators with GB-standard certification capabilities but lacking furnace scale, positioned for rollup into integrated building material groups.
| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Natural Gas Conversion | MEE carbon intensity caps in Jiangsu and Zhejiang compel heavy oil-to-gas fuel switching ahead of compliance deadlines. |
| Backward Integration into Soda Ash | Shandong-based synthetic production clusters offer raw material cost insulation against energy price volatility. |
| Low-E Coating Certification Investment | SAMR laboratory partnerships accelerate GB-standard thermal performance tier access for developer specification. |
| Building-Integrated Photovoltaics Development | Transparent solar glass converges photovoltaic generation with architectural glazing for net-zero commercial premiums. |
| Western China Greenfield Capacity | Sichuan and Chongqing natural gas reserves enable lower-carbon production with ETS credit monetization potential. |
Research Methodology
Trade customs data, China Building Materials Federation production statistics, and SAMR regulatory filings formed the secondary backbone of this analysis. Primary interviews with float glass plant managers, procurement leads at state-owned property developers, solar panel manufacturer technical directors, and MEE regional enforcement officers validated demand assumptions and compliance timelines. Bottom-up and top-down triangulation cross-checked provincial production capacity against end-use absorption in construction and photovoltaic manufacturing.
Bottom-up modeling built product-level forecasts from furnace capacity utilization, coating line throughput, and GB-standard certification rates across the projection horizon. Segmentation dimensions included product type, application, and technology tier. Top-down validation anchored aggregate market value to macro construction spending and photovoltaic installation trajectories. CAGRs derived from regression analysis of historical capacity expansion against dual carbon policy implementation intensity.
Policy enforcement delays, alternative glazing material substitution acceleration, and furnace retrofit engineering bottlenecks are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about MEE provincial timeline sequencing and SAMR laboratory capacity expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Glass Balustrade Lamination Market
Glass
Solar Reflective Glass Market
Glass
GCC Flat Glass Market
Glass
Europe Glass Insulators Market
Glass
Global Anti-Reflective Glass Market
Glass
Global Glassware Market
Glass
Coated Glass Market
Glass
Glazing Gel Market
Glass
Impact Resistant Glass Market
Glass
Sapphire Glass Market
Glass
Double Glazing Glass Market
Glass
Cellular Glass Market
Glass
Optical Materials Market
Glass
Optical Lens Material Market
Glass
Glass Block Market
Glass
Low Temperature Laminated Glass Market