
 Automotive Rubber Molded Components Market | 2026-2036
Automotive Rubber Molded Components Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Rubber Molded Components Market Intelligence
The substitution of traditional nitrile and EPDM rubber with advanced silicone and thermoplastic elastomers (TPEs) in high-temperature engine and electric vehicle applications is pivoting product economics. Freudenberg SE leverages its material science expertise to develop advanced sealing solutions for these new thermal and chemical resistance requirements. Continental AG competes by integrating these components into its broader automotive systems portfolio for OEMs. Hutchinson SA specializes in vibration control and fluid management systems, adapting its elastomer product lines for electrified powertrains.
Automotive rubber molded components are engineered elastomeric parts designed to absorb vibration, seal fluids and gases, and provide flexible connections within a vehicle. These components are produced via processes like injection molding or compression molding to achieve precise geometries and material properties, such as a specific durometer hardness for sealing effectiveness. Seals and gaskets represent a mature, high-volume category tied directly to engine and transmission production volumes. Hoses for fluid transfer, particularly for thermal management in EVs, constitute a high-growth application area for Tier-1 suppliers and aftermarket providers.
Global standards like ISO 9001 and material regulations including the EU's REACH framework govern component manufacturing and substance use. The US EPA's vehicle emissions standards and China's GB standards for automotive safety also impose strict performance and durability criteria on seals and gaskets. Navigating the divergent material requirements and performance characteristics between internal combustion engine vehicles and electric vehicles remains the central strategic challenge for component manufacturers.
Market Dynamics
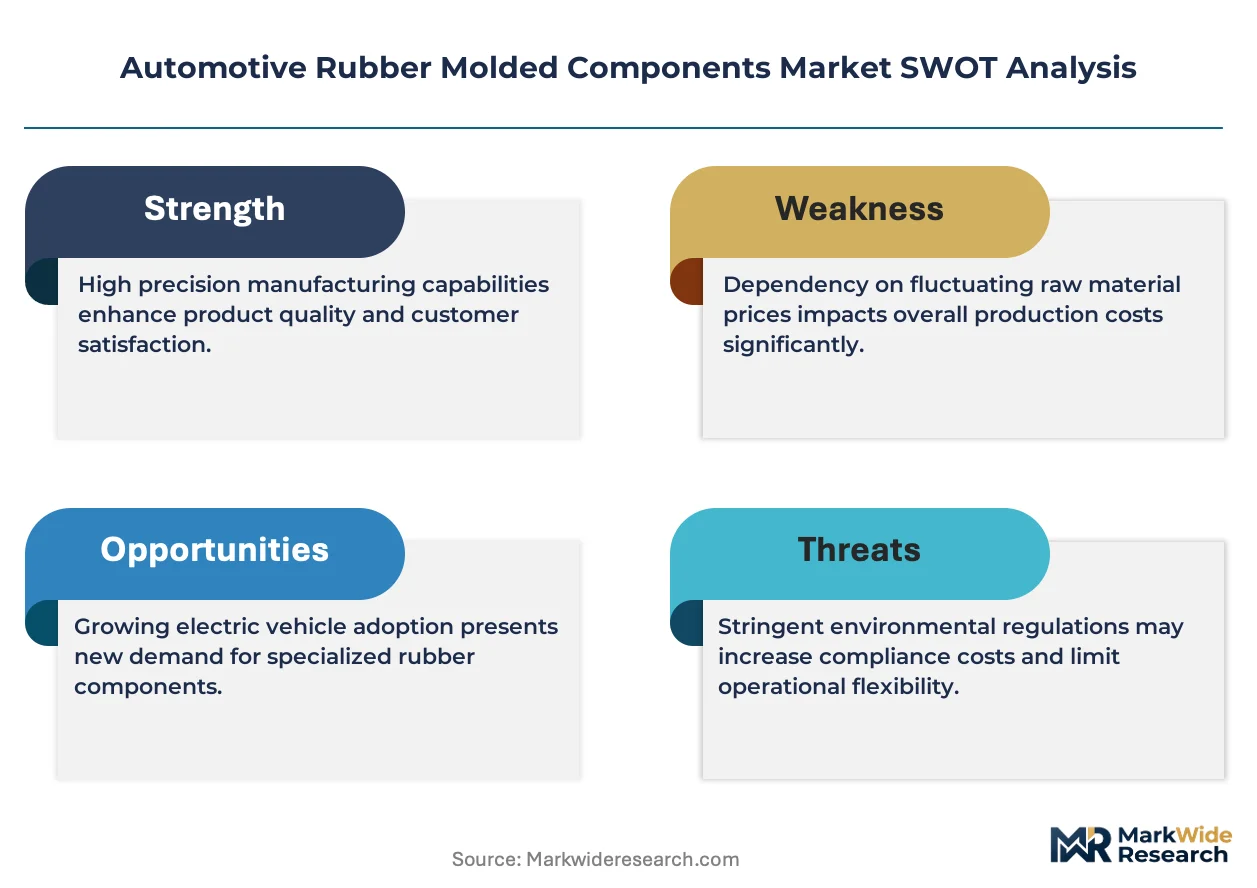
The central dynamic shaping the market is the bifurcation of demand between legacy internal combustion engine (ICE) vehicles and high-growth electric vehicles (EVs). This creates a dual-track manufacturing environment requiring distinct material science, engineering, and capital investment strategies.
Growth Catalysts
- Thermoplastic Elastomers (TPEs):The adoption of TPEs for applications like EV battery seals and thermal management hoses is accelerating due to their superior processing efficiency and design flexibility compared to traditional thermoset rubbers.
- Manufacturing Hub Concentration:Demand is intensifying within established automotive production centers, particularly in Germany and China, where large OEM and Tier-1 supplier ecosystems require a high volume of locally sourced molded components.
- Stringent Emissions Standards:Regulations such as the US EPA's vehicle emissions standards and China's GB safety standards mandate durable, high-performance sealing components, driving the use of advanced materials for gaskets and seals in powertrain systems.
Market Restraints
- Input Cost Volatility:Fluctuations in the prices of key raw materials, including synthetic rubber feedstocks and silicone precursors, directly compress manufacturer profit margins and complicate long-term supply contracts with OEMs.
- Substitution from Rigid Materials:In certain non-critical structural and sealing applications, molded rubber components face a substitution threat from engineered plastics or integrated metal parts that offer lower weight or cost advantages.
- Performance and Cost Trade-offs:The high cost of premium elastomers like fluorosilicone (FVMQ), needed for extreme chemical and thermal resistance, limits their use to critical applications, creating a persistent technical barrier for broader adoption.
Strategic Opportunities
- Advanced Battery Components:The development of components for next-generation battery architectures, including solid-state batteries, presents an opportunity for creating novel sealing and thermal management solutions with unique material properties.
- Sustainable Material Innovation:Formulating bio-based and recycled elastomers offers a path to meet OEM sustainability mandates and align with circular economy principles promoted by frameworks such as the EU Green Deal.
- Emerging Market EV Production:Expanding manufacturing capabilities in burgeoning automotive markets like India and Mexico allows suppliers to capture demand from new EV production facilities incentivized by government policies.
Industry Challenges
- Capital-Intensive Retooling:Shifting production from traditional compression molding of thermoset rubbers to advanced injection molding for TPEs requires significant capital investment in new machinery and process controls.
- Divergent Regulatory Compliance:Navigating the complex and often conflicting substance regulations between major economic blocs, such as the EU's REACH framework and US chemical safety rules, increases testing, validation, and administrative costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Rubber Molded Components Market |
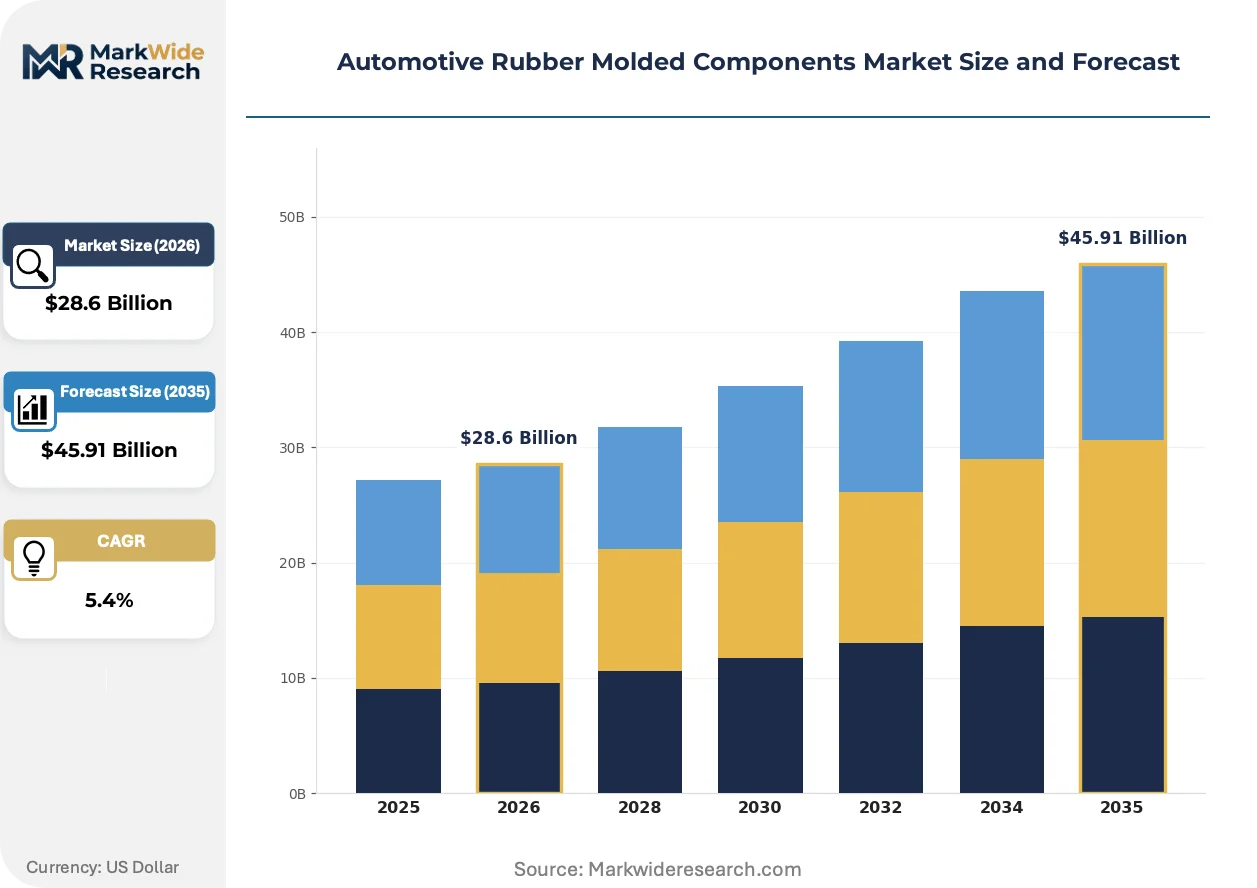
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $45.91 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seals, Gaskets, Hoses, Bushings Application: Engine, Suspension, Transmission, Interior Form: Vulcanized, Injection-Molded, Compression-Molded, Extruded End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | AB SKF, Freudenberg SE, NOK Corporation, Sumitomo Riko Company Limited, Hutchinson SA, Trelleborg AB, Cooper-Standard Automotive, Toyoda Gosei Co., Ltd., Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Rubber Molded Components Market Strategic Shifts & Innovations
Material science advancements are redefining component capabilities, particularly in response to the distinct thermal and chemical environments of electric vehicle powertrains. This pivot forces a re-evaluation of traditional product portfolios and manufacturing processes previously optimized for internal combustion engines.
Thermoplastic elastomers (TPEs) provide flexible sealing with enhanced recyclability and faster cycle times than conventional thermoset rubbers. Electric vehicle manufacturers are rapidly adopting TPEs for critical systems like battery pack gaskets, high-voltage cable jacketing, and thermal management tubing. This shift is consolidating the supply base around producers with expertise in polymer science and precision injection molding, marginalizing firms reliant on older compression molding techniques.
European Union regulations like REACH impose strict controls on chemical substances used in manufacturing. This framework restricts specific plasticizers and curing agents historically used in nitrile and EPDM rubber formulations, compelling suppliers to invest in material reformulation and revalidation. Gasket and hose manufacturers supplying the European automotive market are most affected, accelerating their migration toward compliant materials like advanced silicones and peroxide-cured elastomers.
A demand-side shift is underway as OEMs increasingly source integrated systems rather than discrete rubber components. This trend favors the procurement of complete, pre-validated modules, such as a full battery enclosure sealing system or a ready-to-install fluid transport assembly, over individual gaskets and hoses. This pattern is most pronounced in the German automotive sector, where major OEMs prioritize supply chain simplification and system-level performance assurance for EV platforms.
Automotive Rubber Molded Components Market Segmentation
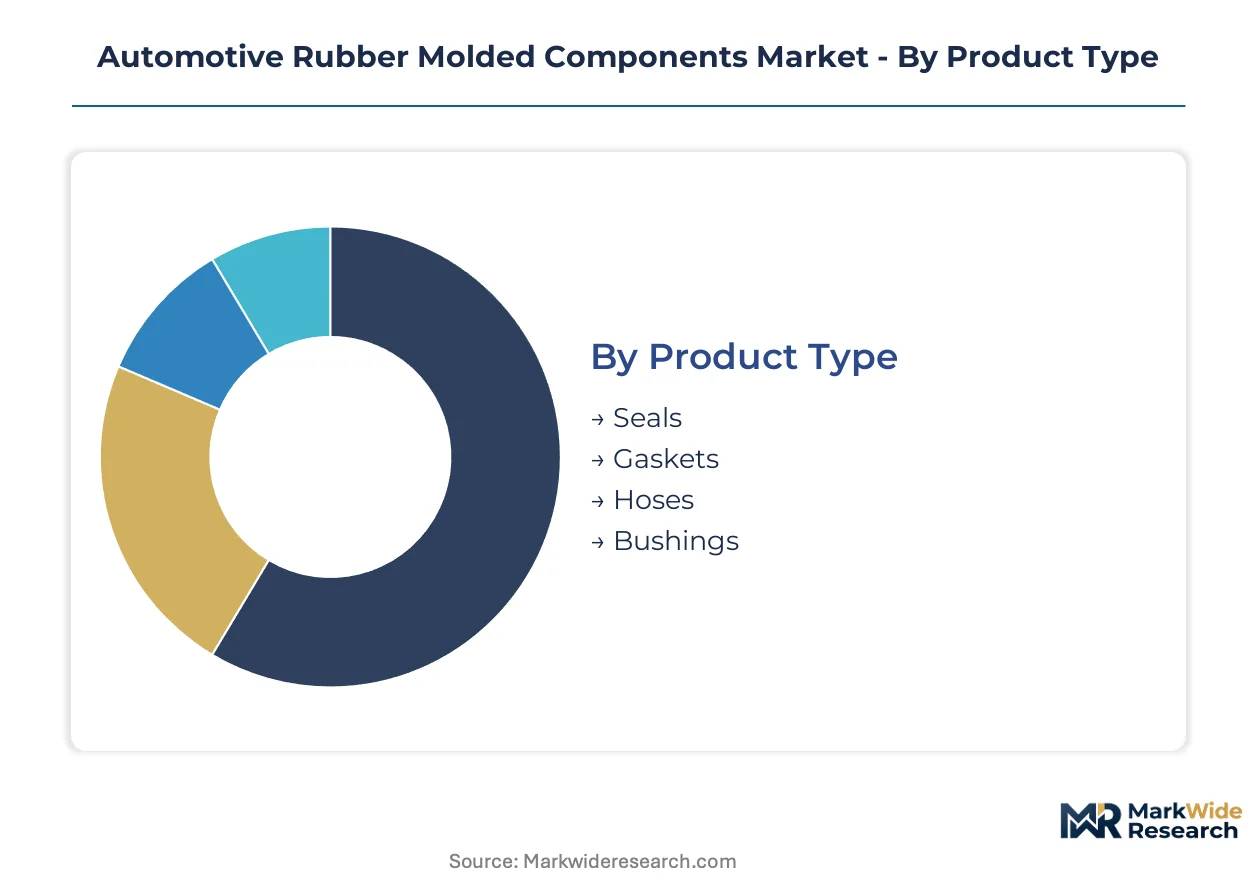
Market segmentation provides a granular view of component demand across diverse product specifications and end-use applications. Understanding these segments enables manufacturers to align production capabilities with evolving vehicle architectures and material requirements. This analysis identifies key areas for technological investment and strategic market penetration.
Product Type:
The product type segment distinguishes between high-volume, standard components and specialized, performance-driven solutions for critical vehicle functions.
- Seals:These elastomeric components prevent fluid or gas leakage and ingress of contaminants in static or dynamic applications. Seals are critical for maintaining system integrity in both internal combustion engines and electric vehicle battery packs, particularly in high-temperature environments.
- Hoses:Flexible conduits transport fluids and gases, essential for engine cooling, fuel delivery, and thermal management systems in electric vehicles. Their design requires resistance to chemical degradation and extreme temperature fluctuations, a demand concentrating in China's burgeoning EV manufacturing sector.
- Gaskets:Gaskets create a static seal between two mating surfaces, preventing leakage under compression. They are widely used in engine assemblies and transmission systems, requiring precise material formulations for durability.
- Bushings:These components absorb vibration and reduce friction between moving parts, commonly found in suspension and steering systems. Bushings often utilize natural rubber or EPDM for their damping properties.
Today's leader: Seals. Tomorrow's challenger: Hoses.
Application:
Application segmentation highlights component integration across distinct vehicle systems, impacting material selection and durability requirements.
- Engine:Components within the engine system manage heat, contain fluids, and dampen vibrations, requiring robust materials like FKM and silicone for high-temperature and chemical resistance. Demand for these parts is shifting with the transition from internal combustion engines to electric powertrains.
- Transmission:Rubber molded components in transmissions provide sealing for hydraulic fluids and dampen operational vibrations, necessitating materials with high oil resistance and mechanical strength. These components are critical for efficient power transfer in both traditional and hybrid vehicles.
- Suspension:Suspension components, including bushings and mounts, isolate road vibrations and noise from the cabin. EPDM and natural rubber are common choices for their excellent dynamic properties.
- Interior:Interior applications focus on comfort, aesthetics, and minor sealing functions, often utilizing softer elastomers for tactile feel and noise reduction. These include seals for windows and doors.
This category reflects the bifurcation of demand between traditional and electric vehicle architectures.
Form:
Manufacturing form delineates the technological maturity and capital intensity involved in component production.
- Injection-Molded:This process uses thermoplastic elastomers (TPEs) to create complex geometries with high precision and rapid cycle times. Injection molding is increasingly favored for EV battery seals and thermal management components due to TPEs' design flexibility and recyclability.
- Compression-Molded:Thermoset rubbers like EPDM and NBR are typically processed via compression molding, forming durable, heat-resistant components. This traditional method is capital-intensive and slower but produces parts with excellent physical properties for critical sealing applications.
- Vulcanized:Vulcanization enhances the elasticity and strength of natural and synthetic rubbers through a chemical process. This form provides superior mechanical properties and temperature resistance for demanding automotive applications.
- Extruded:Extrusion creates continuous profiles like hoses and weatherstrips by forcing rubber material through a die. This method is efficient for producing long, uniform components.
Injection molding techniques are gaining share fastest within this segment, driven by TPE adoption.
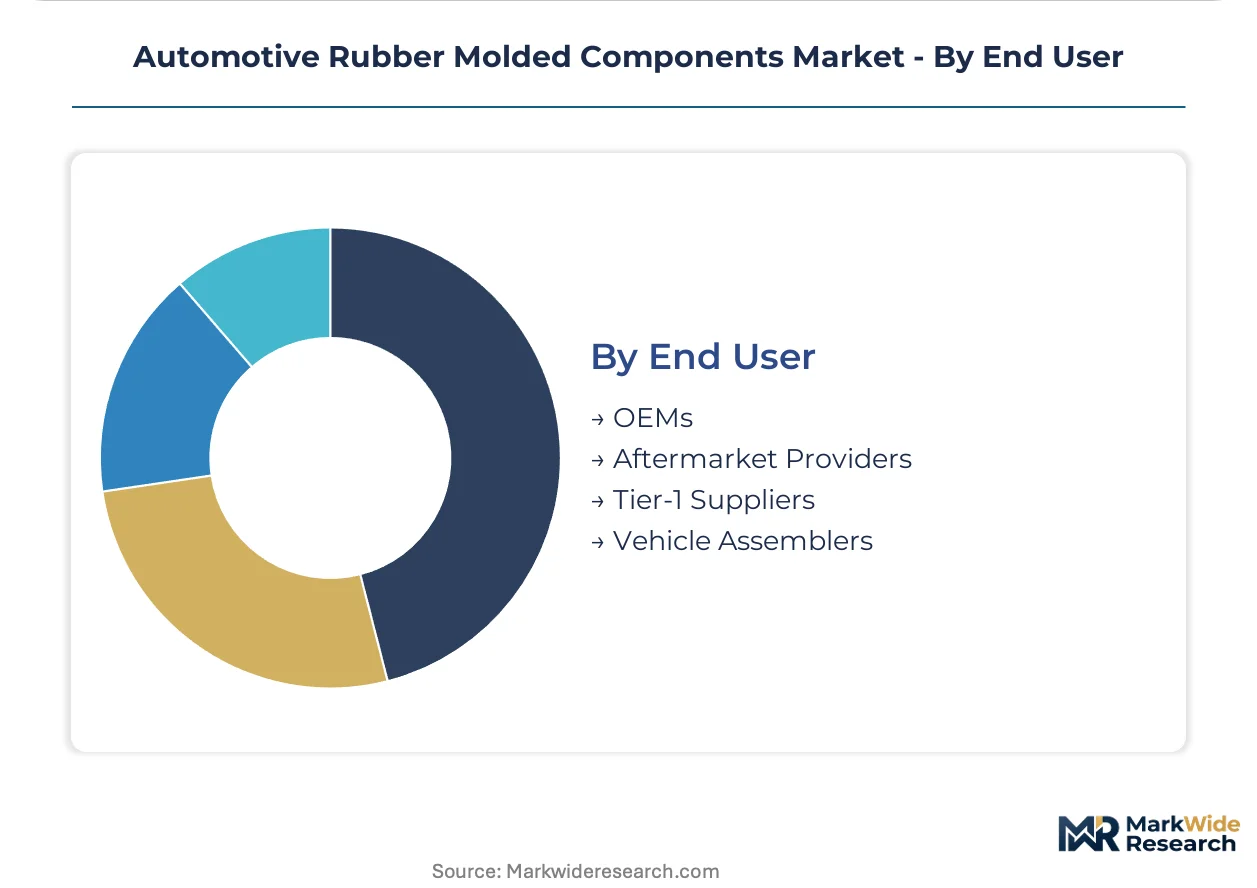
End User:
End user dynamics shape procurement patterns and the demand for integrated sub-assemblies versus discrete components.
- OEMs:Original Equipment Manufacturers directly integrate rubber molded components into new vehicle production lines. OEMs demand high volumes, stringent quality control, and often prefer integrated system solutions from Tier-1 suppliers.
- Tier-1 Suppliers:These suppliers provide complete sub-assemblies and systems to OEMs, incorporating rubber molded components from specialized manufacturers. Tier-1 suppliers act as critical intermediaries, consolidating demand and ensuring performance validation.
- Aftermarket Providers:This segment supplies replacement parts for vehicle repair and maintenance. Aftermarket demand is driven by vehicle aging and requires a broad product portfolio for various models.
- Vehicle Assemblers:Vehicle assemblers are the final stage integrators, procuring components and sub-assemblies for the assembly of finished vehicles. Their focus is on efficient logistics and just-in-time delivery.
OEMs and Tier-1 suppliers collectively dictate the majority of market volume and material specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's automotive manufacturing hubs drive significant demand for rubber molded components, reflecting the country's dominant position in global vehicle production. This market bifurcates between legacy internal combustion engine requirements and the rapidly expanding electric vehicle sector. Geographic concentration of automotive OEMs and Tier-1 suppliers influences component procurement patterns and material specification.
China
Robust demand for EV battery seals and thermal management hoses fuels component growth across China. The country's GB standards for automotive safety and performance mandate durable, high-quality elastomeric parts. The Yangtze River Delta automotive cluster, including Shanghai and Nanjing, focuses on new energy vehicle production, accelerating TPE adoption for critical EV systems.
Germany
OEM demand for integrated fluid management systems and advanced sealing solutions concentrates in Germany. The EU's REACH framework imposes strict material compliance for all automotive components sold within the European Union. Bavaria and Baden-Württemberg host major automotive OEMs and Tier-1 suppliers, developing next-generation EV platforms and requiring specialized rubber molded components.
United States
The United States experiences strong demand for high-performance seals and gaskets driven by stringent emissions standards and increasing EV production. The US EPA's vehicle emissions standards necessitate durable materials for powertrain sealing applications. Michigan's automotive corridor, including Detroit, drives innovation in advanced material components for both traditional ICE and electric vehicle applications.
Japan
Japanese automotive manufacturers require precision-engineered rubber molded components for hybrid and electric vehicle technologies. JIS standards for industrial products guide material selection and component performance. Aichi Prefecture's automotive manufacturing base, centered around Nagoya, emphasizes high-performance elastomer development for advanced powertrain systems and vehicle lightweighting initiatives.
India
Emerging EV production and government incentives for local manufacturing boost demand for rubber molded components in India. The PLI scheme for the automotive sector encourages domestic production of advanced components. Chennai's automotive hub expands capacity for rubber molded components, supporting both domestic vehicle assembly and export markets for various vehicle types.
Automotive Rubber Molded Components Market Key Industry Players
Capital investment in new machinery dominates the current landscape, particularly for transitioning from traditional thermoset rubber processing to advanced thermoplastic elastomer injection molding. The market exhibits a tiered structure with global material science specialists, integrated system providers, and regional component fabricators. Strategic partnerships for integrated solutions and technology licensing represent key competitive moves within this sector.
Specialists in material science and advanced sealing solutions include Freudenberg SE, a German company leveraging its expertise to develop components for high-temperature and chemical resistance. Continental AG, also a German company, occupies a position as an integrated systems provider, incorporating rubber molded components into broader automotive system offerings. French-based Hutchinson SA exemplifies a focus on vibration control and fluid management systems, adapting its elastomer product lines for electrified powertrains.
| Leading Market Players |
|---|
| AB SKF |
| Freudenberg SE |
| NOK Corporation |
| Sumitomo Riko Company Limited |
| Hutchinson SA |
| Trelleborg AB |
| Cooper-Standard Automotive |
| Toyoda Gosei Co., Ltd. |
| Continental AG |
| Others |
Cost & Logistics Intelligence
Outsourced manufacturing relationships anchor both the supply position and the pricing power for specialized automotive rubber molded components. This model allows OEMs to leverage supplier expertise in material science while maintaining cost control through competitive bidding and long-term contracts.
Pricing Analysis
Input cost pass-through remains a significant factor in component pricing, influenced by raw material fluctuations for synthetic rubber and silicone precursors. Pricing predominantly follows a contract-based long-term offtake model for OEM and Tier-1 suppliers. Price differentiation stems from material performance, such as the chemical resistance of FKM, and specific OEM certification levels. Pricing softness reflects intense competition for high-volume, standard components. Aftermarket providers demonstrate higher price sensitivity compared to OEMs procuring critical, performance-driven parts.
Supply Chain Analysis
Domestic-content mandates, like those in China's automotive sector, reshape sourcing strategies and encourage localized production of rubber molded components. Supply concentration for advanced elastomers centers in Germany, China, and Japan, reflecting established material science expertise and manufacturing infrastructure. The market depends on key raw materials such as synthetic rubber feedstocks and specialized additives. Commodity price volatility for these inputs presents a structural supply chain risk. Distribution runs through direct channels to OEMs and Tier-1 suppliers, alongside a robust aftermarket network for replacement parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a margin-expansion story, driven by the shift towards premium thermoplastic elastomers in electric vehicle applications and ongoing demand for high-performance sealing solutions.
For Market Incumbents:
Hedge against material substitution threats by aggressively investing in advanced TPE injection molding capacity. Secure long-term raw material supply contracts to mitigate input cost volatility. Develop specialized sealing solutions for next-generation EV battery architectures, ensuring compliance with evolving thermal and chemical resistance requirements. Pursue strategic partnerships with EV manufacturers in emerging markets like India to capture new production volumes.
For New Entrants and Emerging Players:
Begin with niche opportunities in the electric vehicle thermal management and battery sealing segments. Target emerging EV production hubs in India and Mexico where established supply chains are less entrenched. Focus on sustainable material innovation, such as bio-based elastomers, to align with OEM sustainability mandates. Offer integrated system solutions rather than discrete components to simplify procurement for smaller EV manufacturers.
For Investors and Strategic Acquirers:
Roll-up economics work for specialized component manufacturers because structural shifts towards EVs and TPEs favor scale and material science expertise. High-performance elastomeric components remain critical for vehicle integrity across all powertrain types, ensuring long-term viability. Target niche specialists with proprietary advanced material formulations or significant precision injection molding capabilities. A signal to watch is the announcement of major OEM long-term supply contracts for EV platforms, indicating validated technology and market acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Material R&D | Developing superior elastomers like TPEs and FVMQ enhances component performance for critical EV applications. |
| Precision Injection Molding Capacity Expansion | Increasing production capabilities for complex TPE geometries supports the growing demand from EV manufacturers. |
| Geographic Manufacturing Footprint Expansion | Establishing facilities in emerging EV production hubs like India captures new market demand and local content incentives. |
| Sustainable Material Innovation | Formulating bio-based and recycled elastomers meets OEM sustainability mandates and regulatory requirements. |
| Integrated System Solution Development | Offering complete modules, such as battery enclosure sealing systems, simplifies OEM procurement and ensures system-level performance. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region to capture diverse market dynamics. This analysis combines in-depth interviews with OEM platform engineers, Tier-1 procurement managers, material science R&D directors, and aftermarket distributors. Secondary data sources include vehicle production databases, material science journals, regulatory body reports from the EU REACH and US EPA, and industry association publications. The methodology triangulates findings through both bottom-up and top-down approaches.
The analytical framework decomposes the rate of change across the analysis window, considering various market forces. Segmentation dimensions modeled include product type, application, form, end user, and propulsion architecture (ICE/EV). Compound annual growth rates are derived from historical data, identified market growth drivers, and expert projections. Industry-specific forecast inputs include electric vehicle production forecasts and thermoplastic elastomer adoption rates across critical automotive systems.
Caveats apply where raw material price volatility, rapid shifts in EV battery technology, or unforeseen regulatory changes could materially shift the outlook. Forecasts reflect assumptions regarding technological progression and market acceptance. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Passenger Air Brake Market
Vehicle Components
Asia-Pacific Industrial Brakes Market
Vehicle Components
Electric Wheelbarrow Market
Vehicle Components
Tow Tractor Market
Vehicle Components
Railroad Equipment Manufacturing Market
Vehicle Components
Car Radiator Market
Vehicle Components
HCV Axles Market
Vehicle Components
Freight Railcar Parts Market
Vehicle Components
Exhaust Gas Recirculation (EGR) Valve Market
Vehicle Components
Electric Wheelchair Market
Vehicle Components
Global Automotive Constant Vehicle Joint Boots Market
Vehicle Components
Rear Axle Market
Vehicle Components
Towing Equipment Market
Vehicle Components
Aircraft and Marine Turbochargers Market
Vehicle Components
Automotive Displacement Sensor Market
Vehicle Components
Vehicle Radiator Market