
 Marine Wheel Bearings Market | 2026-2036
Marine Wheel Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Wheel Bearings Market Analytics
Ceramic hybrid materials is hardening cost-performance trade-offs for marine wheel bearings operating in saltwater environments. SKF Group leverages its Nordic marine heritage to sustain premium positioning in yacht and commercial segments. Schaeffler Group anchors European supply through specialized corrosion-resistant product lines. The Timken Company competes on tapered bearing configurations for heavy-load commercial applications.
Marine wheel bearings are precision rotational components, typically manufactured from stainless steel or bearing bronze with polymer cages, designed to transmit radial and axial loads while resisting seawater corrosion in propulsion and steering assemblies. Roller bearings dominate commercial vessel applications where load capacity outweighs precision requirements, while ball bearings lead recreational boat segments prioritizing smooth rotation and compact housing fit. Tapered bearings command margin pools in trailer and heavy-tow applications where combined load handling justifies higher unit pricing.
ISO 281 and ABMA standards govern fatigue life calculations and dimensional tolerances for marine-rated bearings, while the EPA's Vessel General Permit program shapes demand through mandatory equipment inspections that accelerate replacement cycles. The IMO's Energy Efficiency Existing Ship Index indirectly pressures bearing performance standards as operators seek mechanical efficiency gains. Stakeholders must monitor how emerging polymer composite formulations challenge traditional stainless steel economics without sacrificing regulatory compliance.
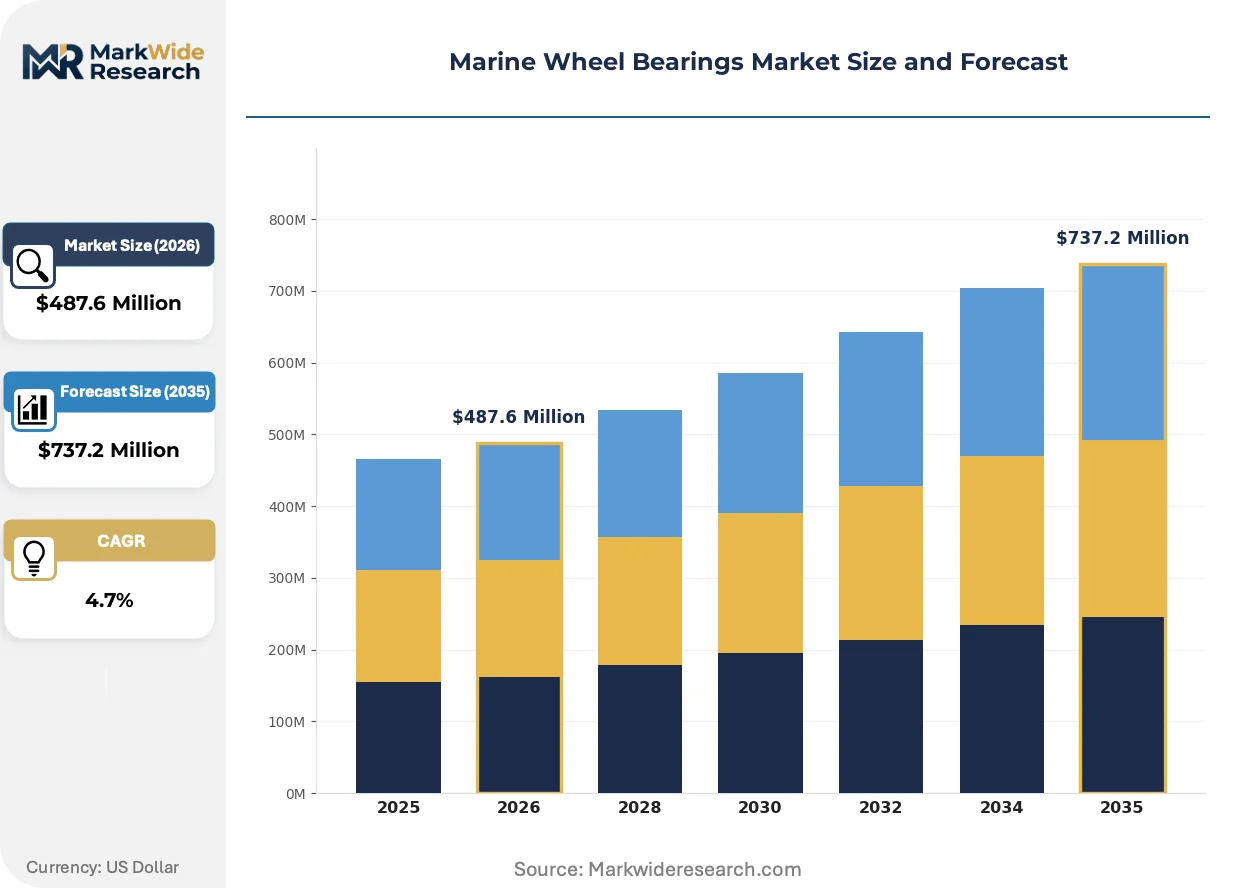
Market Dynamics
The International Maritime Organization's carbon intensity regulations are compressing replacement cycles across commercial fleets, forcing operators to prioritize mechanical efficiency upgrades in propulsion and steering systems ahead of scheduled maintenance windows.
Growth Catalysts
- IMO EEXI Compliance:The Energy Efficiency Existing Ship Index mandates operational upgrades that accelerate bearing replacements in older vessels to reduce frictional losses and improve fuel economy.
- Stainless Steel Supply Concentration:China's integrated steel mills around Shanghai and Guangzhou provide cost-competitive raw material access that lowers production costs for regional bearing manufacturers serving shipyards.
- Polymer Cage Technology:Advanced polymer formulations reduce corrosion-induced cage failures in saltwater environments, extending service intervals and lowering total cost of ownership for commercial operators.
Market Restraints
- Specialized Alloy Input Costs:Bearing-grade stainless steel and marine bronze face price volatility tied to nickel and copper commodity markets, squeezing margin stability for precision component fabricators.
- European Supply Concentration:Corrosion-resistant bearing production clusters heavily in Nordic and German manufacturing corridors, creating geographic vulnerability to regional energy cost shocks or logistics disruptions.
- Ceramic Hybrid Substitution Ceiling:Silicon nitride hybrid bearings remain cost-prohibitive for bulk commercial applications despite superior saltwater performance, limiting penetration beyond yacht and premium segments.
Strategic Opportunities
- India Shipbuilding Corridors:The country's expanding commercial vessel construction under the PLI scheme creates localized demand for marine-rated bearings with domestic certification pathways.
- Smart Bearing Integration:Convergence of embedded sensor arrays with traditional roller bearing architectures enables condition-based maintenance contracts that capture recurring revenue streams from fleet operators.
- Aftermarket Channel Digitization:Direct-to-fleet procurement platforms are disintermediating traditional distributor networks, allowing manufacturers to capture margin previously allocated to regional stocking intermediaries.
Industry Challenges
- Marine Metallurgy Talent Scarcity:Specialized knowledge in saltwater corrosion metallurgy and fatigue life modeling concentrates among aging engineering cohorts in established manufacturing regions, constraining production scaling.
- Multi-Standard Certification Complexity:Simultaneous compliance with ISO 281 fatigue calculations, ABMA dimensional tolerances, and classification society rules extends product qualification timelines for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Wheel Bearings Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $737.2 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Bearings, Roller Bearings, Tapered Bearings, Spherical Bearings Material: Stainless Steel, Bearing Bronze, Polymer, Aluminum End User: Boat Manufacturers, Repair Shops, OEMs, Distributors Application: Recreational Boats, Commercial Vessels, Trailers, Yachts |
| Companies Covered | SKF Group, Schaeffler Group, NSK Ltd., The Timken Company, NTN Corporation, JTEKT Corporation, RBC Bearings Incorporated, NACHI-Fujikoshi Corp., Regal Rexnord Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Wheel Bearings Market Evolving Landscape
Sensor-integrated bearing systems and advanced material formulations are redefining performance benchmarks across commercial and recreational marine segments. These developments compress maintenance intervals while enabling predictive operational models.
Ceramic hybrid bearing technology is automating condition monitoring protocols through embedded vibration and temperature sensors that transmit real-time data to shore-based analytics platforms. Commercial ferry operators in Scandinavian corridors are adopting these systems at accelerating rates to satisfy classification society digitalization requirements. The technology is automating fleet maintenance scheduling and reducing unplanned dry-dock incidents that disrupt route profitability.
The EPA's Vessel General Permit program mandates documented equipment inspection frequencies that accelerate bearing replacement cycles in US-flagged commercial vessels. This regulatory pressure forces operators to maintain detailed maintenance logs that favor traceable, certified component sourcing over gray-market alternatives. The recreational boat segment faces parallel documentation requirements that reshape procurement toward branded, warrantied products with established regulatory compliance histories.
Direct procurement from manufacturers is displacing traditional marine distributor networks as fleet operators consolidate purchasing through centralized technical procurement teams. Large commercial vessel operators now negotiate frame contracts that bypass regional stocking intermediaries entirely. This channel compression is most visible in China's state-owned shipping conglomerates, where technical specifications flow directly from engineering departments to approved manufacturer supply agreements.
Marine Wheel Bearings Market Segmentation
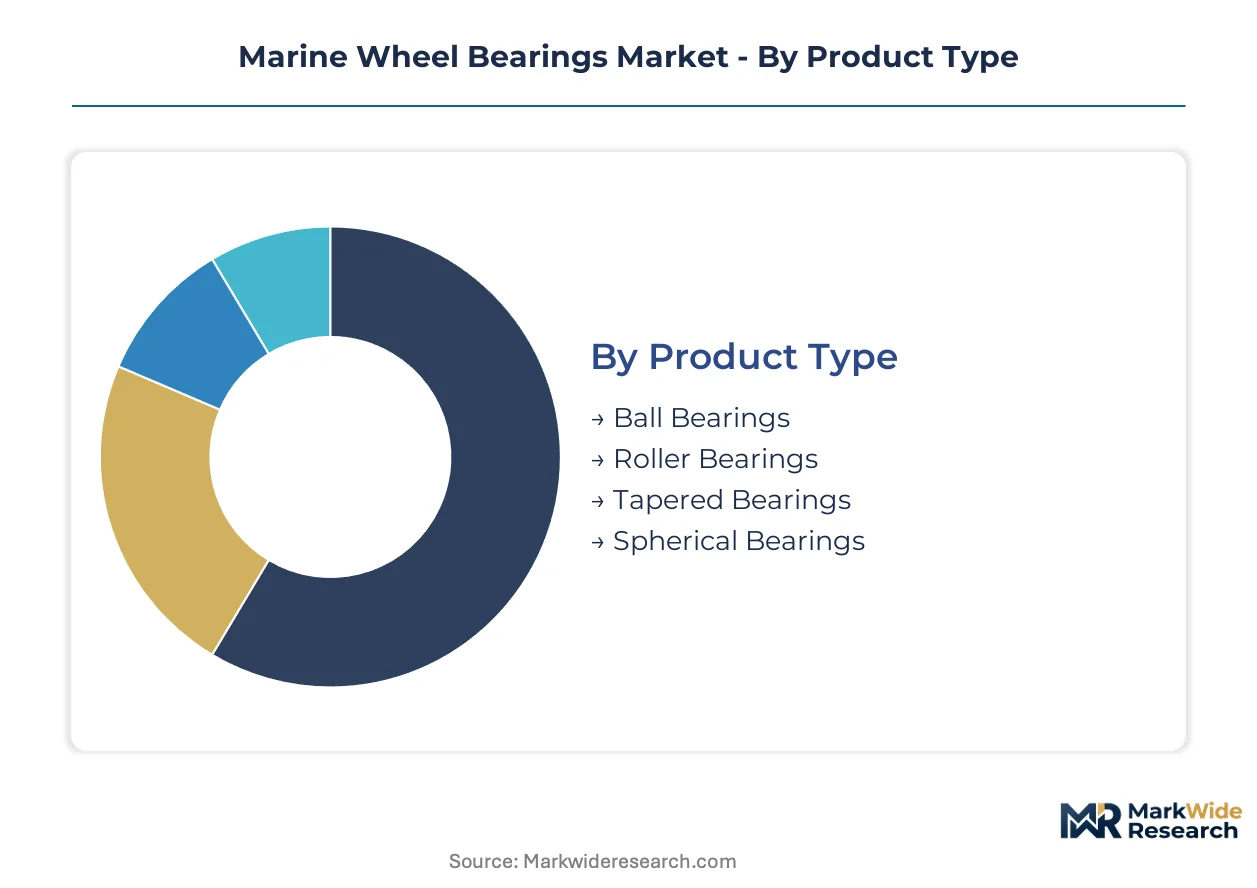
Marine wheel bearings serve divergent mechanical requirements across propulsion, steering, and trailer systems. Capital allocation patterns differ sharply between corrosion-resistant materials for saltwater exposure and precision configurations for recreational smoothness.
Product Type:
Capital intensity peaks in tapered and spherical bearing configurations where specialized grinding equipment and heat-treatment furnaces demand seven-figure upfront investment.
- Ball Bearings:Precision-ground raceways with polymer or brass cages enable smooth low-friction rotation in recreational steering assemblies. Demand clusters in yacht and recreational boat segments around Florida and Mediterranean marinas where handling precision outweighs load capacity.
- Roller Bearings:Cylindrical and needle configurations handle radial loads in commercial propulsion shafts with greater contact surface area than ball designs. Chinese shipyards around Shanghai specify these for bulk carrier and tanker newbuilds where fatigue life trumps rotational finesse.
- Tapered Bearings:Conical raceways manage combined radial and axial loads in trailer hubs and heavy-tow applications.
- Spherical Bearings:Self-aligning outer rings accommodate shaft misalignment in steering gear and stabilizer systems.
Most installed capacity flows through roller bearings. Expansion is steepest in tapered configurations.
Material:
Raw material sourcing strategies split between integrated stainless steel mills and specialized alloy foundries.
- Stainless Steel:AISI 440C and marine-grade 316L provide baseline corrosion resistance through chromium content above 16%. Norwegian and German manufacturers dominate this tier, supplying classification society-certified components to European shipyards facing EEXI compliance deadlines.
- Bearing Bronze:Copper-tin alloys with lead or bismuth additions offer superior galling resistance and embeddability for propeller shaft bearings. Demand concentrates in legacy commercial fleets and heritage vessel restorations where traditional metallurgy satisfies surveyor expectations.
- Polymer:PEEK and PTFE composite cages reduce galvanic corrosion failures while trimming weight in high-speed applications.
- Aluminum:Anodized alloys serve cost-sensitive trailer and utility boat segments where saltwater exposure is intermittent.
Stainless steel commands the largest installed base. Polymer composites are climbing the fastest as cage and liner materials.
End User:
Purchasing power concentrates in OEM technical procurement teams versus fragmented repair channel demand.
- Boat Manufacturers:Production boat builders in China, Poland, and the United States negotiate frame contracts for certified bearing lots with full traceability documentation.
- Repair Shops:Independent marine service facilities source replacement bearings through regional distributors with same-day availability requirements.
- OEMs:Engine and propulsion system manufacturers specify bearings in original equipment packages for major shipyards.
- Distributors:Stocking intermediaries maintain inventory depth across multiple brands for aftermarket fulfillment.
Volume flows primarily through boat manufacturers. Repair shops are expanding most quickly as fleet age extends replacement cycles.
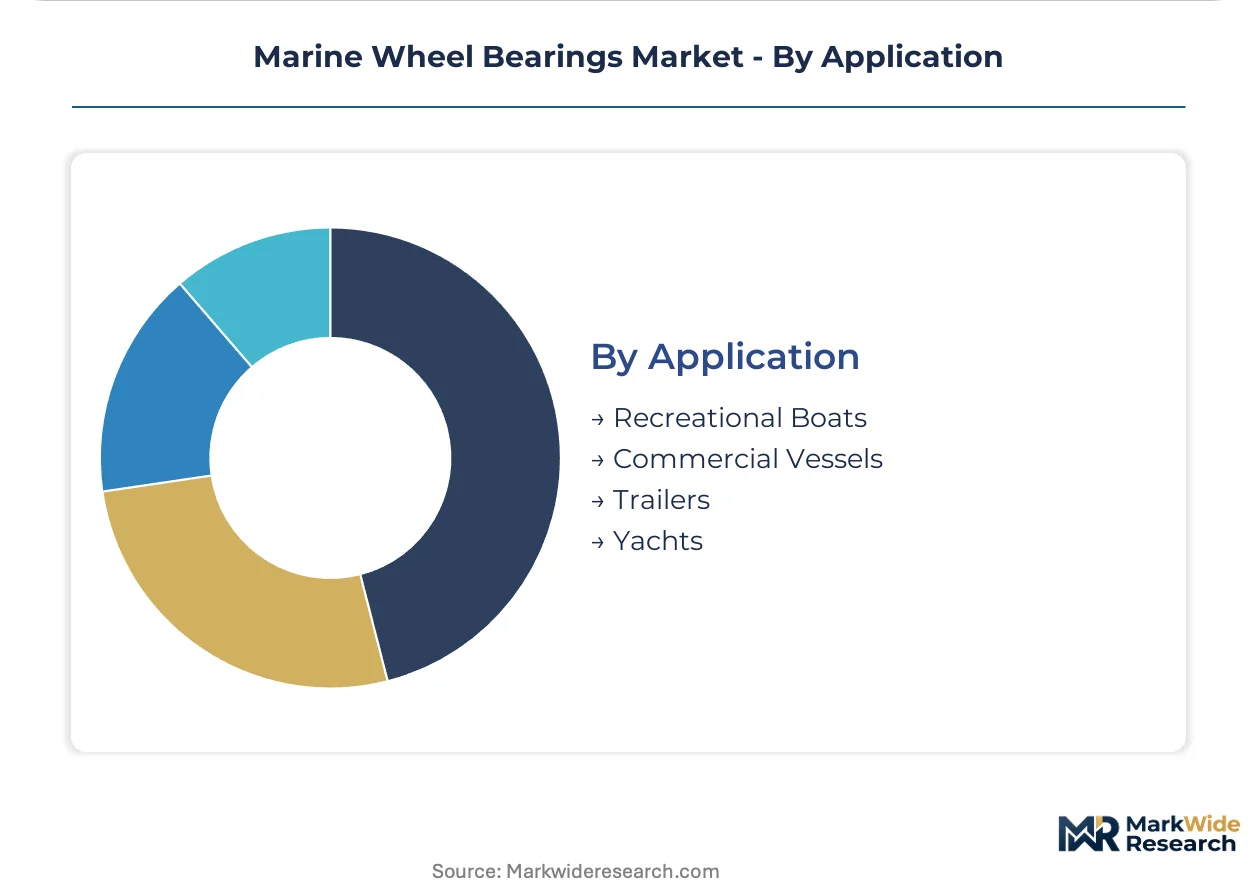
Application:
Operating environment severity ranges from freshwater trailer immersion to continuous saltwater propulsion duty.
- Commercial Vessels:Deep-sea and coastal cargo ships require classification society-certified bearings with documented fatigue life calculations under ISO 281. IMO carbon intensity regulations accelerate replacement schedules as operators chase mechanical efficiency gains.
- Recreational Boats:Outboard and sterndrive applications prioritize compact housing fit and smooth rotation over absolute load capacity. Demand tracks fiberglass boat production in the United States, Italy, and Australia.
- Trailers:Submerged hub assemblies face galvanic corrosion and grease washout in saltwater launch ramps.
- Yachts:Superyacht builders specify ceramic hybrid and precision angular contact bearings for reduced maintenance and vibration signature.
Commercial vessels absorb the greatest bearing volume. Yacht applications are expanding most quickly on per-unit value metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai and Guangzhou anchor the dominant shipbuilding corridors where marine wheel bearing demand concentrates most visibly. Chinese state-owned shipping conglomerates negotiate frame contracts that bypass traditional distributor networks entirely. Classification society-certified production clusters in Germany and Norway supply European yards facing EEXI compliance deadlines.
China
Integrated stainless steel mills around Shanghai and Guangzhou provide cost-competitive raw material access for regional bearing manufacturers. The MIIT's dual carbon goals pressure shipyards to accelerate mechanical efficiency upgrades in propulsion systems. Production concentrates in Jiangsu and Guangdong provinces where state-owned shipping conglomerates consolidate technical procurement.
Germany
Corrosion-resistant bearing fabrication clusters heavily in Baden-Württemberg and Bavaria manufacturing corridors. REACH compliance requirements and EU Green Deal carbon intensity targets extend product qualification timelines for new entrants. Stuttgart-based engineering teams specialize in fatigue life modeling for classification society certification.
United States
Recreational boat production in Florida and Great Lakes states drives precision ball bearing demand for steering assemblies. The EPA's Vessel General Permit program mandates documented equipment inspection frequencies that accelerate replacement cycles. Trailer bearing demand concentrates in saltwater launch ramp corridors across the Gulf Coast and Southeast.
Japan
Precision bearing technology for commercial propulsion shafts concentrates in Nagoya and Osaka industrial zones. METI's maritime decarbonization roadmaps pressure operators to prioritize mechanical efficiency gains. Kobe and Yokohama shipyards specify cylindrical roller configurations for bulk carrier newbuilds.
Norway
Stavanger and Bergen host specialized marine bearing engineering cohorts with deep saltwater corrosion metallurgy expertise. The country's national maritime regulator enforces strict classification society alignment with IMO carbon intensity standards. Nordic marine heritage sustains premium positioning in yacht and commercial segments.
Marine Wheel Bearings Market Competitive Landscape
Global majors compete with regional champions across certification pathways and raw material integration. The vendor base splits between consolidated European precision fabricators and fragmented Asian volume producers. Three archetypes dominate: integrated steel-to-bearing manufacturers, specialized corrosion-resistant specialists, and sensor-integrated smart bearing developers. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure classification society pre-qualification.
Among Nordic heritage manufacturers, SKF Group exemplifies premium-tier positioning across yacht and commercial segments. German-based Schaeffler Group occupies a position within the corrosion-resistant specialist tier. The Timken Company represents the heavy-load commercial configuration archetype with tapered bearing expertise.
| Leading Market Players |
|---|
| SKF Group |
| Schaeffler Group |
| NSK Ltd. |
| The Timken Company |
| NTN Corporation |
| JTEKT Corporation |
| RBC Bearings Incorporated |
| NACHI-Fujikoshi Corp. |
| Regal Rexnord Corporation |
| Others |
Value Network & Pricing Analysis
Nickel-bearing stainless steel inputs flow from Shanghai and Guangzhou integrated mills through three pricing tiers that separate classification society-certified European fabricators from volume producers serving Chinese state-owned shipping conglomerates. Cost pass-through mechanics favor manufacturers with captive raw material access or long-term offtake agreements with Nordic alloy suppliers.
Pricing Analysis
Input-cost pass-through from nickel and copper commodity markets compresses margins for bearing-grade stainless steel and marine bronze fabricators without vertical integration into raw material supply. Pricing stratifies across premium ceramic hybrid tiers for superyacht applications, standard stainless steel configurations for commercial fleets, and economy aluminum variants for trailer segments. Cost compression in the standard tier intensifies because Chinese integrated mills flood regional shipyards with cost-competitive output. Fleet operators consolidating through direct procurement exhibit lowest price sensitivity; independent repair shops sourcing single-unit replacements face acute cost pressure.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns as global manufacturers establish localized production to serve expanding shipbuilding corridors in Gujarat and Tamil Nadu. Geographic supply concentration centers on China for integrated steel-to-bearing production, Germany and Norway for corrosion-resistant precision fabrication, and Japan for cylindrical roller configurations in commercial propulsion. Raw material dependencies draw from nickel ore processing, bearing-grade chromium steel, and specialized copper-tin bronze alloys. Single-source vulnerability concentrates in European energy-intensive heat-treatment capacity. Distribution runs through direct frame contracts with state-owned shipping conglomerates, bypassing traditional regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The marine wheel bearings market functions as a stable compounder anchored by IMO regulatory mandates that force continuous mechanical efficiency upgrades across aging commercial fleets. Replacement cycle compression sustains predictable demand regardless of newbuild volatility.
For Market Incumbents: Deploy smart bearing sensor integration to capture recurring condition-based maintenance revenue from Scandinavian ferry operators facing classification society digitalization requirements. Deepen backward integration into nickel-bearing stainless steel supply through offtake agreements with Shanghai integrated mills. Counter ceramic hybrid substitution threats by extending polymer cage technology service intervals.
For New Entrants and Emerging Players: Distributors serving independent repair shops represent the most accessible channel for bypassing entrenched OEM procurement relationships. Target India's PLI-scheme shipbuilding corridors where domestic certification pathways lack established supplier relationships. Penetrate through specialized corrosion-resistant product lines for heritage vessel restorations where surveyor familiarity with traditional metallurgy creates stickier demand.
For Investors and Strategic Acquirers: Consolidation pressure builds where aging marine metallurgy engineering cohorts concentrate in Nordic and German manufacturing corridors, constraining production scaling for mid-cap specialists. Five-to-ten-year viability favors targets with classification society pre-qualification and direct procurement relationships with Chinese state-owned shipping conglomerates. Monitor EPA Vessel General Permit enforcement intensity as inflection indicator for US-flagged commercial vessel replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Bearing Sensor Integration | Embedded vibration arrays enable predictive maintenance contracts with Scandinavian ferry operators. |
| Backward Integration into Nickel Steel | Captive supply from Shanghai integrated mills insulates margin from commodity volatility. |
| India PLI Corridor Capacity Addition | Localized production satisfies domestic-content mandates for Gujarat shipbuilding expansion. |
| Ceramic Hybrid Technology Licensing | Silicon nitride formulations penetrate superyacht segments demanding reduced maintenance. |
| Direct Procurement Platform Development | Disintermediation captures margin from traditional marine distributor networks. |
Research Methodology
Coverage spans China, Germany, Norway, Japan, and the United States, with primary inputs from each regional cluster combining interviews with marine procurement directors at state-owned shipping conglomerates, technical specification engineers at classification societies, plant managers at integrated stainless steel mills, and aftermarket service heads at independent repair facilities. Secondary validation draws from IMO regulatory filings, EPA Vessel General Permit enforcement records, customs trade data for bearing-grade steel imports, and SEC 10-K disclosures from listed precision component fabricators. Bottom-up demand modeling triangulates against top-down macroeconomic indicators across the analysis window.
Granularity-level modeling disaggregates volume and value outputs by product type, material composition, end-user channel, and application severity across the projection horizon. CAGRs derive from regression analysis against fleet age distributions, regulatory compliance deadlines, and raw material cost indices. Industry-specific forecast inputs incorporate IMO EEXI implementation timelines and polymer cage technology adoption curves in saltwater environments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to nickel commodity volatility, European energy cost shocks affecting heat-treatment capacity, and ceramic hybrid cost-down trajectories. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and fleet modernization program continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Steering Gear Market
Vehicle Components
Global Bicycle Wheels Market
Vehicle Components
Injector Deposit-Resistant Fuel Injection Component Platforms Market
Vehicle Components
Rear Axle Market
Vehicle Components
Mobile Liquid Tanks Market
Vehicle Components
Wheel Loaders Market
Vehicle Components
Locomotive Pantographs Market
Vehicle Components
Rail Components Market
Vehicle Components
Hydraulic Actuators Market
Vehicle Components
Portable Wheel Jack Market
Vehicle Components
Navigation Light Market
Vehicle Components
Vehicle Pillar Market
Vehicle Components
Refrigerated Trailer Door Lock Market
Vehicle Components
Composite Bearings Market
Vehicle Components
Locomotive Lighting Batteries Market
Vehicle Components
Oil Filter Elements Market