
 Europe Automotive Connectors Market | 2026-2036
Europe Automotive Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Connectors Market Intelligence
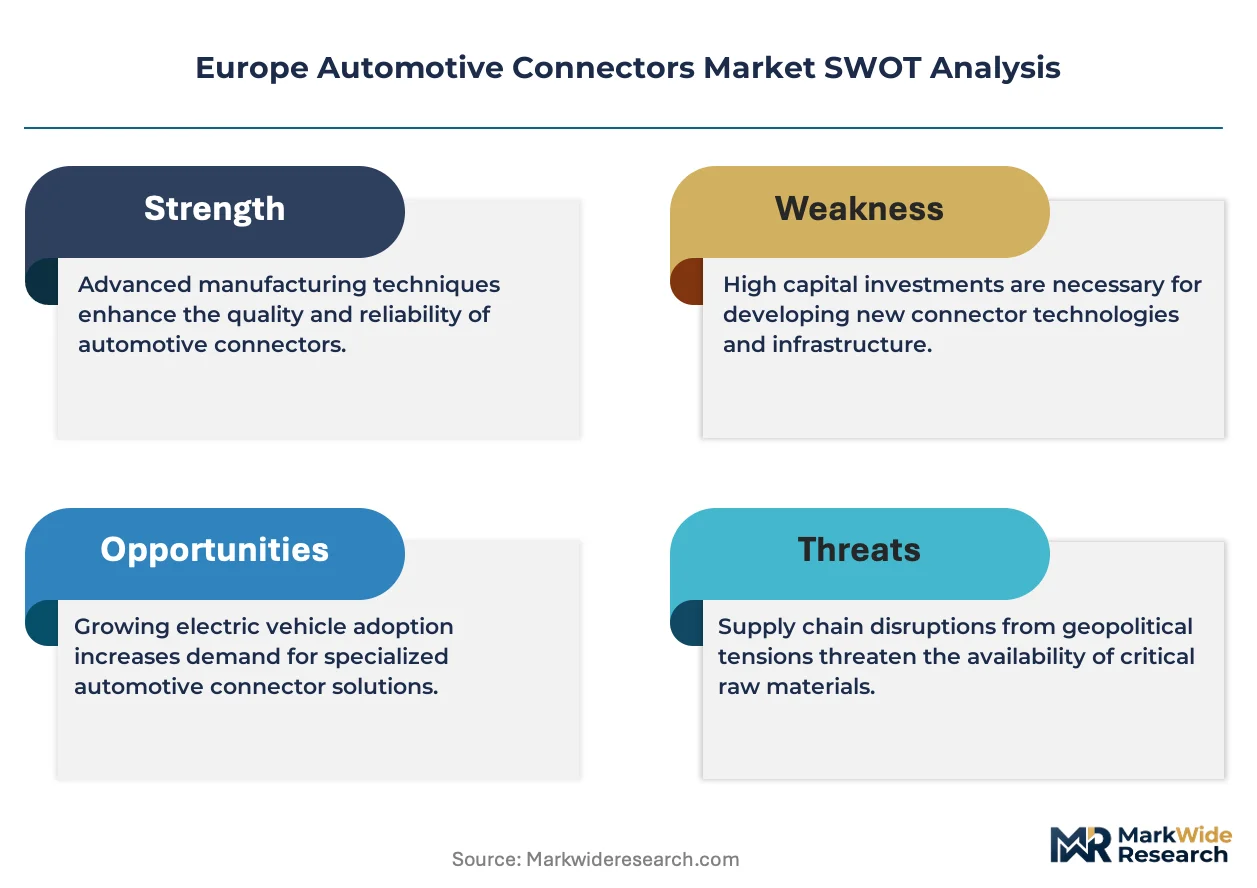
CE marking under the EU's Machinery Directive and automotive-specific IATF 16949 qualification is bifurcating the supplier landscape between certified tier-1 incumbents and excluded challengers. TE Connectivity leverages extensive European manufacturing footprints to sustain blanket supply agreements with German OEMs. HARTING Technology Group anchors its position through specialized high-voltage connector portfolios for commercial electric vehicles. ERNI International AG competes via precision board-to-board interconnects tailored to compact automotive control modules.
Automotive connectors are electromechanical devices engineered to establish reliable signal and power transmission between vehicle subsystems, typically rated for operating temperatures spanning minus 40 to 150 degrees Celsius and vibration resistance exceeding 10 g RMS. Their primary commercial purpose is ensuring electrical continuity across powertrains, infotainment architectures, and advanced driver-assistance sensor arrays. Wire-to-Wire connection types dominate volume shipments as harness complexity multiplies with electrification, while Board-to-Board segments capture concentrated margin pools in domain controller applications. Copper material grades command premium positioning due to conductivity requirements in 800-volt architectures, whereas Plastic housings face substitution pressure from bio-based polymer formulations.
EMA's extended REACH restrictions on halogenated flame retardants and the EU AI Act's forthcoming vehicle autonomy classifications are reshaping material specifications and validation protocols for connector manufacturers. Germany's KBA enforces type-approval standards that directly gate market access for non-compliant component suppliers. Stakeholders must monitor evolving battery connector interoperability standards and pre-position testing capabilities before regulatory deadlines crystallize.
Market Dynamics
Platform electrification across German and French OEMs is forcing connector architectures to absorb higher voltage loads while shrinking physical footprints for battery-integrated designs.
Growth Catalysts
- EU Green Deal:Binding carbon-neutrality targets for 2050 compel automakers to accelerate EV platform rollouts, multiplying high-voltage connector procurement from Tier-1 harness suppliers.
- 800-volt architectures:Premium EV drivetrains now demand copper-alloy connectors rated for elevated thermal cycling, expanding addressable spend per vehicle.
- Battery connector interoperability:Emerging industry consortia in Germany and Sweden are standardizing physical interfaces, reducing OEM validation costs and speeding supplier qualification.
Market Restraints
- Copper price volatility:LME copper fluctuations squeeze margin structures for connector manufacturers locked into annual blanket contracts with German OEMs.
- REACH compliance costs:ECHA's extended restrictions on halogenated flame retardants force reformulation of plastic housings, extending R&D timelines by 12-18 months.
- Domestic supply concentration:Germany's KBA type-approval requirements create regulatory moats that non-EU suppliers struggle to penetrate without local testing facilities.
Strategic Opportunities
- Poland and Czechia manufacturing:Lower labor costs and proximity to German assembly plants attract connector producers seeking to reconfigure European supply footprints.
- Commercial vehicle electrification:Heavy-duty truck platforms in France and Italy present underpenetrated demand for high-amperage charging connectors.
- F-Gas Regulation phase-down:Restrictions on fluorinated gases in manufacturing processes create first-mover advantage for suppliers with dry-process plating capabilities.
Industry Challenges
- IATF 16949 certification timelines:New entrants face 18-24 month qualification periods before supplying German OEMs, compressing effective market entry windows.
- Legacy 12-volt integration:Domain controllers must maintain backward compatibility with conventional harness architectures, multiplying validation matrices.
- High-voltage safety engineering talent:Scarce specialists in arc containment and touch-safe design command premium compensation, inflating R&D overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Connectors Market |
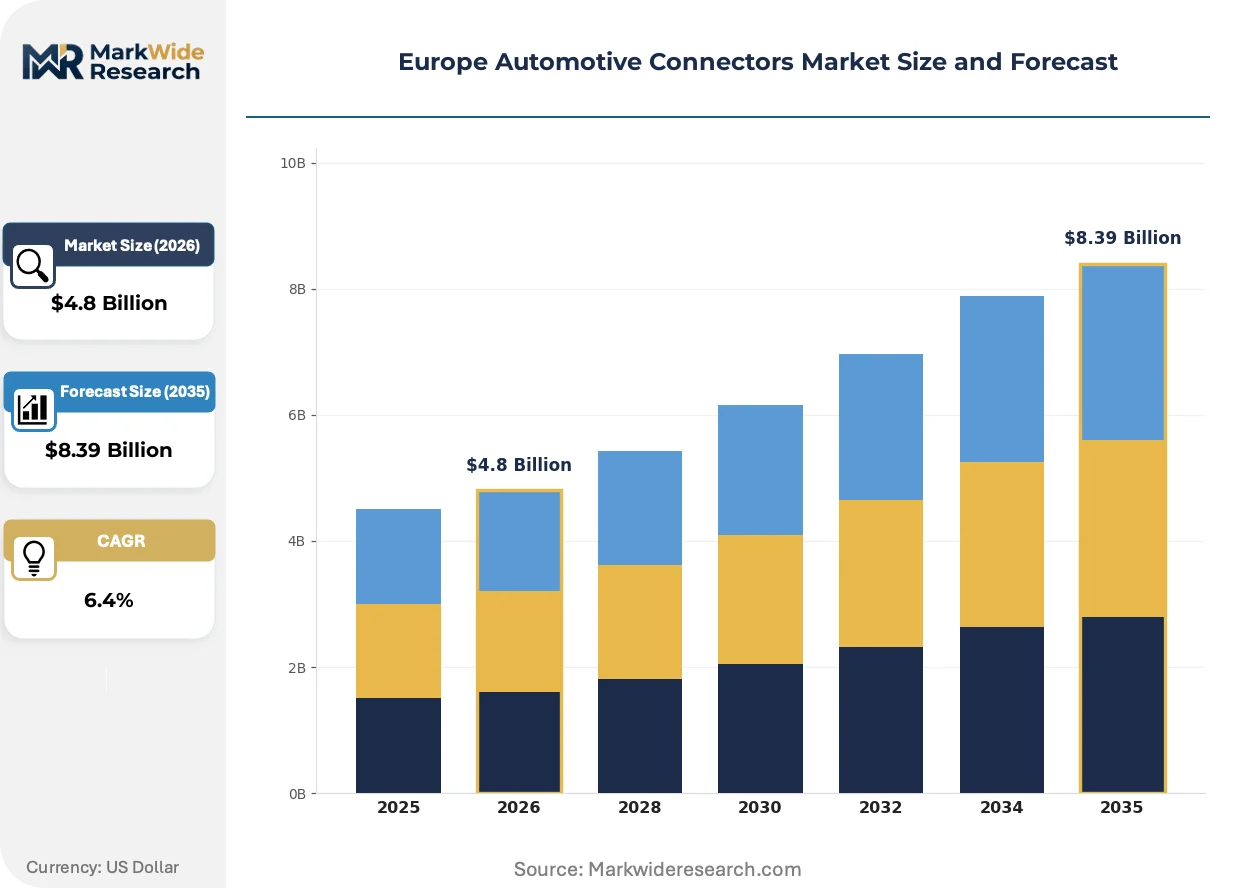
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Terminals, Connectors, Housings, Crimping Tools Material: Copper, Aluminum, Plastic, Rubber End User: OEMs, Tier-1 Suppliers, Dealerships, Repair Shops Connection Type: Wire-to-Wire, Wire-to-Board, Board-to-Board, Circular |
| Companies Covered | Yazaki Corporation, Sumitomo Electric Industries, TE Connectivity, ERNI International AG, Hirose Electric Co., Amphenol Corporation, Molex LLC, HARTING Technology Group, Aptiv PLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Connectors Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry restrictions are jointly redefining connector specifications across European automotive supply chains.
Copper-beryllium contact alloys are supplanting traditional brass in 800-volt applications due to superior conductivity and reduced insertion force requirements. German OEMs have accelerated adoption timelines from 2027 to 2025 model years. This material transition is compressing supplier qualification cycles while elevating performance benchmarks for incumbent connector portfolios.
EMA's extended REACH restrictions on halogenated flame retardants are prohibiting legacy plastic formulations in automotive housings. Connector manufacturers must validate bio-based polymer alternatives without compromising UL 94 flammability ratings. Italian and Spanish suppliers with established sustainable material partnerships are capturing accelerated qualification pathways.
Fleet operators in France and the Netherlands are consolidating connector procurement through long-term service agreements rather than discrete component purchases. Tier-1 harness suppliers are responding with integrated subsystem offerings bundling connectors, cabling, and predictive maintenance software. This contracting model shift is most visible in commercial electric vehicle deployments where uptime guarantees dominate purchasing criteria.
Europe Automotive Connectors Market Segmentation
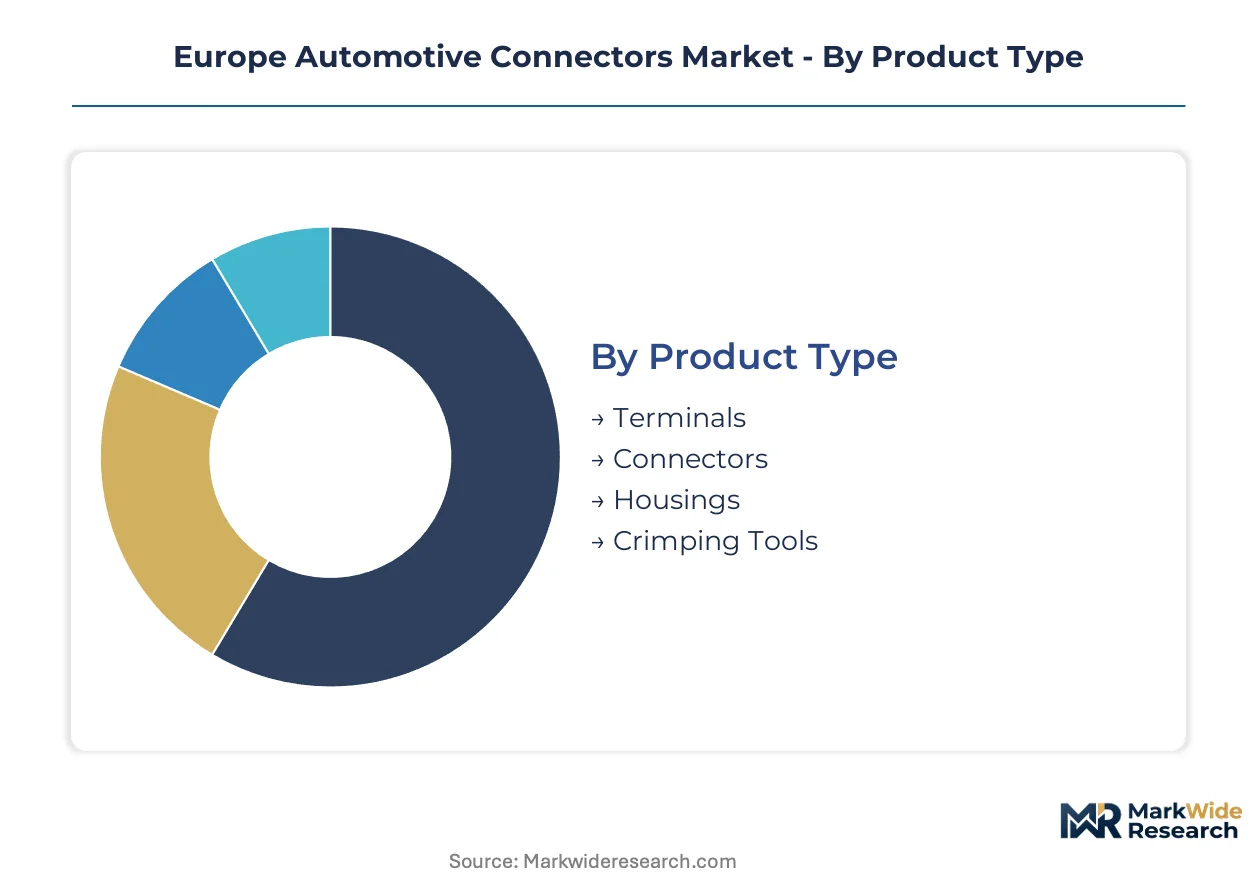
Connector specifications diverge sharply across European automotive applications, with voltage ratings and material certifications determining supplier qualification pathways. Segmentation reveals how electrification is restructuring procurement priorities across OEM and aftermarket channels.
Product Type:
CE marking under the EU Machinery Directive and IATF 16949 certification create tiered entry barriers that concentrate volume among qualified component categories.
- Terminals:Precision-machined conductive interfaces engineered for crimped or soldered wire attachment, typically manufactured from copper alloys with tin or silver plating. German OEM procurement of 800-volt-rated terminals is accelerating as EV platform production scales, though REACH compliance on plating chemistry extends qualification cycles.
- Connectors:Integrated electromechanical assemblies combining contacts, housings, and locking mechanisms into standardized interface units. French Tier-1 harness suppliers are consolidating connector specifications to reduce SKU complexity across multi-platform contracts, favoring modular designs with field-serviceable components.
- Housings:Structural enclosures providing mechanical protection and environmental sealing for contact assemblies.
- Crimping Tools:Specialized equipment for permanent wire-terminal attachment ensuring electrical continuity.
Established volume favors Terminals; emerging adoption favors Connectors.
Material:
Cost tiers stratify sharply between commodity metals and certified high-performance formulations required for electrified powertrains.
- Copper:High-conductivity base metal and alloys dominating current-carrying components, with oxygen-free grades specified for 800-volt architectures. Italian connector producers are securing long-term cathode supply agreements to hedge LME price volatility affecting annual OEM contracts.
- Plastic:Injection-molded housings and insulators requiring UL 94 flammability ratings and halogen-free formulations under extended REACH restrictions. Spanish compounders with bio-based polymer partnerships are capturing accelerated qualification pathways as ECHA deadlines approach.
- Aluminum:Lightweight conductive alternative for non-critical signal paths and cost-sensitive applications.
- Rubber:Elastomeric seals and grommets providing environmental protection in underhood and chassis locations.
Copper commands premium positioning in high-voltage segments; Plastic faces the steepest reformulation pressure from regulatory chemistry restrictions.
End User:
Customer type determines certification depth, with production-integrated channels requiring exhaustive validation compared to aftermarket replacement.
- OEMs:Vehicle manufacturers specifying connector systems at platform architecture stage, typically locking suppliers into 5-7 year model-cycle agreements. German OEM technical centers in Munich and Stuttgart are co-developing next-generation battery interconnect standards with qualified Tier-1 partners.
- Tier-1 Suppliers:Harness and subsystem integrators procuring connectors for assembly into vehicle-ready modules. French wiring specialists are vertically integrating connector manufacturing to capture margin pools previously allocated to component specialists.
- Dealerships:Authorized service channels sourcing replacement connectors for warranty and maintenance repairs.
- Repair Shops:Independent aftermarket operators requiring standardized connector assortments compatible with multi-brand vehicle populations.
OEM channel concentration rewards technical partnership depth; Repair Shop demand favors catalog breadth and interchangeability.
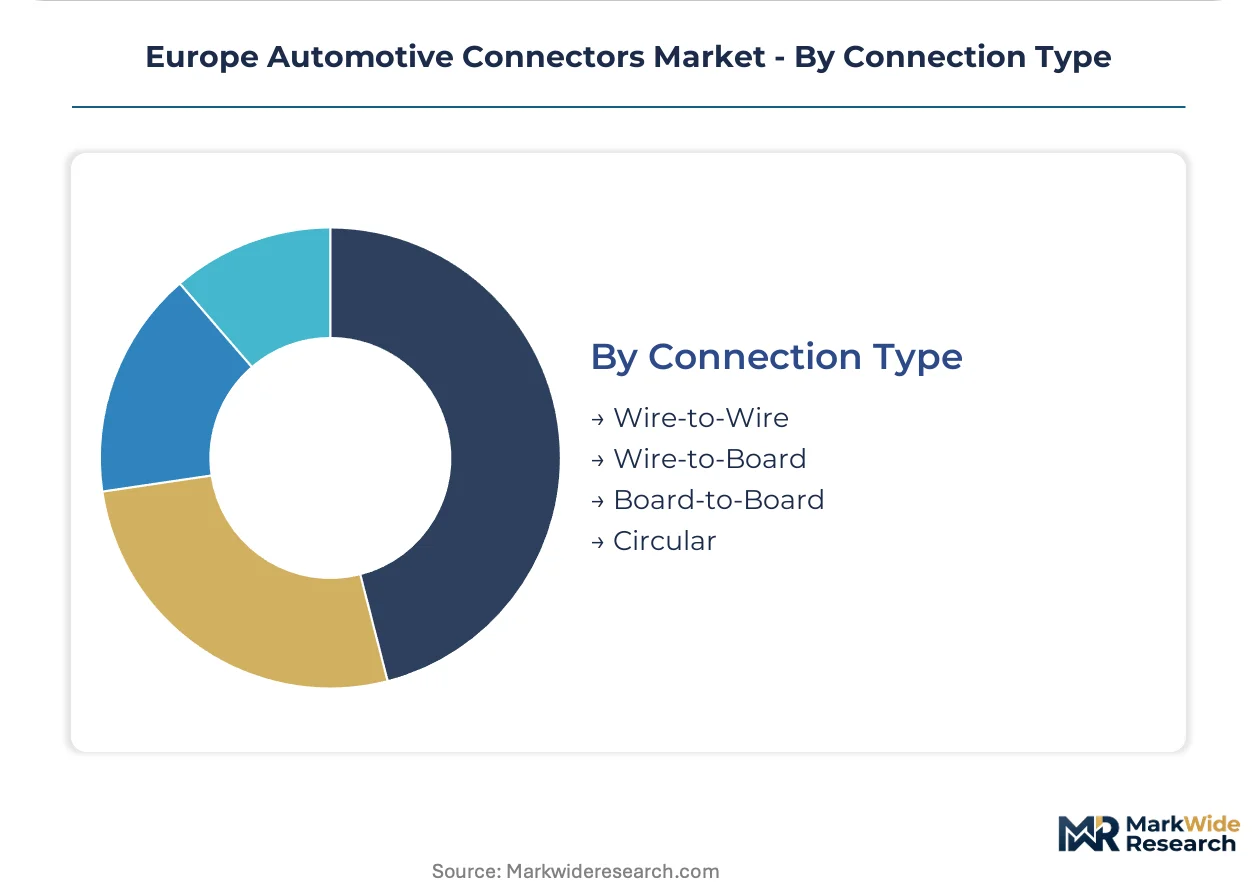
Connection Type:
Application requirements across powertrain, body electronics, and sensor architectures are diversifying interface geometries and performance specifications.
- Wire-to-Wire:In-line junctions joining cable assemblies without intermediate substrates, representing the dominant shipment volume as harness complexity multiplies with electrification. Czech harness producers are expanding wire-to-wire connector capacity to supply German assembly plants with just-in-sequence delivery.
- Board-to-Board:Direct PCB interconnects enabling compact domain controller architectures with minimal signal path length. Dutch automotive electronics specialists are qualifying high-density board-to-board connectors for ADAS sensor fusion modules.
- Wire-to-Board:Transition interfaces connecting harness assemblies to electronic control unit terminals.
- Circular:Cylindrical locking connectors specified for harsh-environment applications including powertrain and chassis locations.
Wire-to-Wire maintains volume leadership across production harnesses; Board-to-Board is gaining share fastest in domain controller applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German OEM technical centers concentrate procurement authority for high-voltage connector specifications. French Tier-1 harness suppliers and Italian component specialists anchor production networks across the continent. Poland and Czechia attract manufacturing investment from cost-sensitive producers seeking proximity to German assembly plants.
Germany
BMW, Mercedes-Benz, and Volkswagen Group drive demand for 800-volt-rated copper connectors across EV platform rollouts. KBA type-approval standards enforce rigorous validation protocols that gate market access for component suppliers. Stuttgart and Munich host technical centers where OEMs co-develop battery interconnect standards with qualified Tier-1 partners.
France
Renault and Stellantis electrification programs multiply procurement of high-amperage charging connectors for passenger and commercial vehicles. EU Green Deal carbon-neutrality targets compel accelerated EV platform investments by domestic automakers. The Paris-Saclay cluster houses wiring specialists vertically integrating connector manufacturing to capture margin pools.
Italy
Ferrari, Lamborghini, and Maserati premium electrification creates specialized demand for precision board-to-board interconnects in compact control modules. ECHA REACH restrictions on halogenated flame retardants push suppliers toward bio-based polymer formulations. Emilia-Romagna's automotive supplier corridor concentrates precision machining capacity for copper-alloy terminals.
Poland
Lower labor costs and EU structural funds attract connector producers reconfiguring European supply footprints. F-Gas Regulation phase-down restrictions on fluorinated gases favor suppliers with dry-process plating capabilities. The Silesian and Wielkopolska regions host expanding harness assembly operations supplying German plants with just-in-sequence delivery.
Czechia
Skoda Auto and Hyundai Motor Manufacturing drive wire-to-wire connector demand as harness complexity multiplies with electrification. CE marking under the EU Machinery Directive creates tiered entry barriers favoring certified incumbents. The Moravian automotive cluster around Ostrava concentrates capacity for high-volume terminal production.
Europe Automotive Connectors Market Key Industry Players
Player mix skews toward diversified electromechanical conglomerates with automotive-qualified manufacturing footprints. Incumbents leverage IATF 16949 certification and blanket supply agreements to defend position against challengers. Three archetypes dominate: integrated harness-Tier-1s with captive connector production, specialized connector houses with high-voltage portfolios, and diversified industrial component suppliers with automotive divisions. Competitive moves center on geographic expansion into lower-cost manufacturing zones and portfolio diversification toward 800-volt architectures.
Among diversified industrial specialists, TE Connectivity and HARTING Technology Group exemplify scale-driven archetypes with extensive European manufacturing presence. ERNI International AG occupies a position within the precision interconnect tier. Japanese conglomerates Yazaki Corporation, Sumitomo Electric Industries, and Hirose Electric Co. represent the Asia-origin supplier archetype serving European OEMs through regional technical centers and qualified production facilities.
| Leading Market Players |
|---|
| Yazaki Corporation |
| Sumitomo Electric Industries |
| TE Connectivity |
| ERNI International AG |
| Hirose Electric Co. |
| Amphenol Corporation |
| Molex LLC |
| HARTING Technology Group |
| Aptiv PLC |
| Others |
Cost & Logistics Intelligence
Annual blanket agreements indexed to LME copper futures lock German OEMs into predictable unit costs while simultaneously constraining Tier-1 suppliers' margin recovery during commodity spikes. These contracts concentrate pricing power with volume purchasers and force connector manufacturers to absorb volatility through inventory hedging and material substitution strategies.
Pricing Analysis
Cost-plus contracts with LME copper indexation dominate procurement between German OEMs and qualified Tier-1 harness suppliers. Pricing stratifies across IATF 16949-certified premium grades, CE-marked standard tiers, and economy grades for aftermarket channels. Cost compression in plastic housing formulations is intensifying because ECHA REACH restrictions on halogenated flame retardants force R&D-heavy reformulation cycles. Aftermarket repair shops exhibit highest price sensitivity due to catalog interchangeability requirements, while OEM platform engineering teams prioritize thermal performance over unit cost in 800-volt architectures.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg container terminals have elevated working capital requirements for Asian-origin component suppliers serving European assembly plants. Manufacturing concentrates in Germany, Poland, and Czechia for final assembly, with copper cathode feedstock drawn from Chilean and Zambian mining operations. Single-source vulnerability persists in oxygen-free copper alloy refining capacity. Distribution runs through just-in-sequence hubs co-located with German OEM assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized engineering talent in arc containment and touch-safe high-voltage design represents the critical bottleneck constraining supplier expansion across European EV platforms. This capability scarcity elevates compensation premiums and extends qualification timelines for new market entrants.
For Market Incumbents: Shield established supply positions by deepening captive production of copper-beryllium contact alloys and securing long-term cathode offtake agreements before commodity volatility intensifies. Accelerate dry-process plating capability investments to capture F-Gas Regulation phase-down advantages over competitors dependent on fluorinated gas processes. For New Entrants and Emerging Players: Anchor in Poland and Czechia manufacturing zones where lower labor costs and EU structural funds reduce capital barriers to IATF 16949 qualification. Commercial vehicle electrification in France and Italy presents the most penetrable white-space opportunity, with fleet operators consolidating procurement through integrated subsystem service agreements rather than discrete component sourcing. For Investors and Strategic Acquirers: Capital is best deployed toward precision board-to-board interconnect specialists with established bio-based polymer partnerships and accelerated ECHA qualification pathways. Over the extended automotive platform cycle, watch battery connector interoperability standardization announcements from German and Swedish industry consortia as the signal indicating which supplier technologies will achieve rapid OEM adoption versus prolonged validation delays.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | German OEM technical centers co-developing battery interconnect standards with Tier-1 partners reduce supplier qualification costs. |
| Backward Integration into Copper Alloys | Italian connector producers securing cathode supply agreements hedge LME price volatility affecting annual OEM contracts. |
| Geographic Manufacturing Footprint | Poland and Czechia attract producers seeking proximity to German assembly plants with just-in-sequence delivery. |
| Green Manufacturing Transition | Spanish compounders with bio-based polymer partnerships capture accelerated qualification pathways under ECHA deadlines. |
| Charging Infrastructure Partnership | French fleet operators consolidating procurement through long-term service agreements favor integrated subsystem offerings. |
Research Approach
A standing panel of Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and dealership operations managers provided ongoing calibration across primary interview cycles. Secondary validation drew from vehicle production databases, IHS Markit registration data, ECHA regulatory filings, and customs trade records. Bottom-up connector shipment estimates triangulated against top-down automotive production forecasts across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs throughout the forecast period. The analytical framework modeled segmentation across propulsion architecture, vehicle class, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from fitted growth curves incorporating battery electric vehicle penetration assumptions, copper price trajectory scenarios, and regulatory compliance timeline impacts.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Green Deal implementation and stable LME copper trading ranges; material deviation would warrant model refresh. Specific risk factors include accelerated REACH restriction timelines, battery connector standardization delays, and German KBA type-approval protocol changes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Towing Ropes Market
Vehicle Components
Steering Tie Rod Market
Vehicle Components
Refrigerated Trailer Hinges Market
Vehicle Components
Global Fuel Tank and Delivery System Market
Vehicle Components
South Africa Automotive Thermoplastic Polymer Composites Market
Vehicle Components
Limited Slip Differential (LSD) Market
Vehicle Components
Global Automotive Steering Torque Sensor Market
Vehicle Components
Composite Bearings Market
Vehicle Components
Locomotive Lighting Batteries Market
Vehicle Components
Electric Forklifts Market
Vehicle Components
GCC Automotive Connectors Market
Vehicle Components
Car Sunshade Market
Vehicle Components
Air Brake Reservoirs Market
Vehicle Components
Trailer Canopy Market
Vehicle Components
Sideloaders Market
Vehicle Components
Automotive Rubber Molded Components Market