

High Precision Heavy Load Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
High Precision Heavy Load Bearings Market Insights
Predictive maintenance subscriptions bundled with sensor-integrated bearing systems is expanding the addressable revenue per unit beyond hardware margins. SKF Group leverages its Rotating Equipment Performance contracts to lock in long-term aftermarket revenue streams. Schaeffler Group anchors its competitive position through backward integration into ceramic rolling element production. NSK Ltd. specializes in condition-monitoring algorithms that reduce unplanned downtime for wind energy customers.
High precision heavy load bearings are antifriction components engineered to sustain radial and axial loads exceeding standard industrial ratings, typically manufactured from vacuum-degassed chrome steel with dimensional tolerances within ISO P4/P2 grades for critical rotational accuracy. Their primary purpose is ensuring continuous operation in machinery where failure incurs catastrophic downtime costs across machine tools, wind turbines, and railway bogies. Cylindrical roller bearings dominate machine tool spindle applications where rigidity and speed capability determine machining throughput. Spherical roller bearings capture expanding margin pools in wind energy drivetrains as turbine ratings climb toward offshore scale. Ceramic hybrid variants command premium positioning in applications demanding thermal stability and electrical insulation.
ISO 281 and ISO 492 standards govern rolling bearing life calculations and dimensional tolerances that define market-access thresholds for precision-grade suppliers. The EU F-Gas Regulation and REACH compliance requirements from ECHA are reshaping lubricant formulations and sealing material selections across European supply chains. China's GB standards and NMPA-aligned quality certifications create parallel compliance pathways for market entry. Stakeholders must monitor how dual carbon goals in Beijing and the EU Green Deal's embodied carbon tracking will recalibrate material sourcing and energy-intensive heat treatment processes.
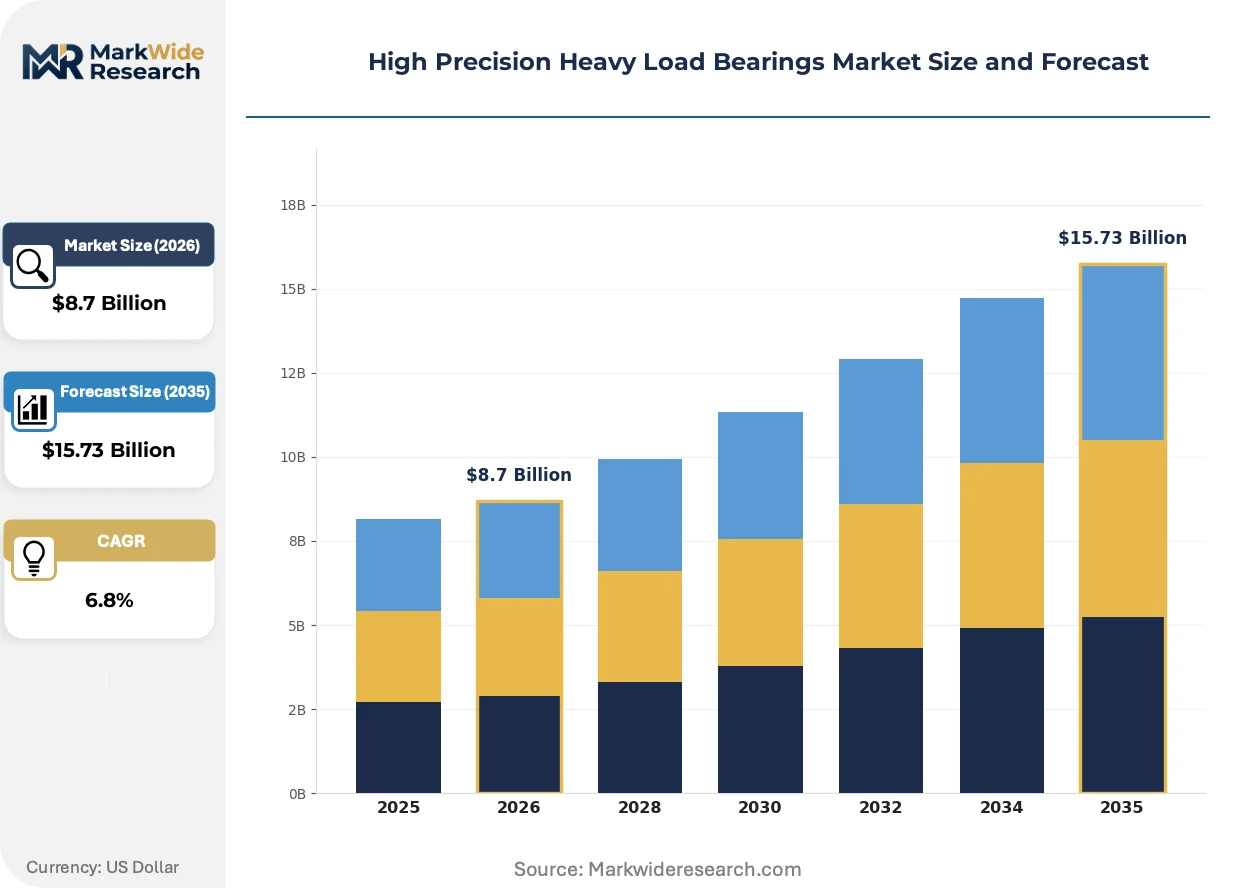
Market Dynamics
Wind turbine OEMs are consolidating procurement around spherical roller bearings rated for 10+ MW nacelle loads, compressing supplier qualification cycles and forcing heat treatment capacity investments across European and Asian supply bases.
Growth Catalysts
- EU F-Gas Regulation:Mandates for lower-GWP lubricants are accelerating R&D into fluorine-free greases compatible with ceramic hybrid bearing architectures in German precision manufacturing clusters.
- Offshore wind scale-up:Turbine ratings climbing toward 15 MW are driving specification upgrades for main shaft bearings with integrated condition monitoring in North Sea installations.
- Railway bogie modernization:Deutsche Bahn and SNCF refurbishment programs are concentrating demand for ISO P4-grade cylindrical roller bearings in axlebox applications.
Market Restraints
- Vacuum-degassed chrome steel concentration:Primary billet supply clusters in Sweden and Japan create input cost volatility when energy prices spike.
- REACH compliance friction:ECHA substance restrictions on certain sealing elastomers are forcing reformulation cycles that extend qualification timelines by 12-18 months.
- Magnetic bearing substitution:Active magnetic bearing systems are capturing niche applications in high-speed turbomachinery above 30,000 RPM where contact fatigue limits mechanical designs.
Strategic Opportunities
- India railway expansion:Dedicated freight corridors and metro buildouts in Mumbai, Delhi, and Bangalore are opening procurement channels for tapered roller bearings in traction motor applications.
- EU Green Deal embodied carbon tracking:Scope 3 disclosure requirements are creating first-mover advantage for suppliers with electric-arc furnace steel and renewable-powered heat treatment.
- Sensor-integrated bearing convergence:MEMS accelerometer and temperature sensor integration with edge analytics is unifying hardware and predictive maintenance revenue streams.
Industry Challenges
- Metallurgical engineering talent scarcity:Vacuum degassing and controlled atmosphere heat treatment expertise is concentrating among retiring specialists in German and Japanese supplier bases.
- ISO 492 P2 certification timelines:Dimensional tolerance verification for super-precision grades requires capital-intensive coordinate measuring machines and extended gauge R&R studies.
- Legacy wind farm retrofit complexity:Replacing main shaft bearings in operational turbines demands specialized crane logistics and nacelle disassembly protocols that disrupt OEM service schedules.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Precision Heavy Load Bearings Market Trends and Innovations
Digitalization of bearing lifecycle management is collapsing the traditional separation between component supply and aftermarket service, creating integrated performance contracts that tie supplier revenue to uptime outcomes.
Ceramic silicon nitride rolling elements are unifying thermal stability and electrical insulation properties in a single material platform. Machine tool spindle OEMs in Taiwan and Germany are adopting hybrid configurations at accelerating rates. This material transition is compressing the addressable market for conventional steel designs in high-speed precision applications.
China's GB standards alignment with NMPA quality certification pathways is recalibrating import substitution strategies. Domestic suppliers in Luoyang and Wafangdian are securing railway and wind energy qualifications previously held by European incumbents. Local content mandates in state-owned wind farm tenders are accelerating this displacement pattern.
Aftermarket service unbundling is disrupting traditional distribution channels. Wind farm operators in Denmark and Germany are negotiating direct sensor data access clauses in bearing supply contracts, bypassing distributor technical support layers. This behavioral shift concentrates margin capture with OEMs capable of remote diagnostics infrastructure.
High Precision Heavy Load Bearings Market Segmentation
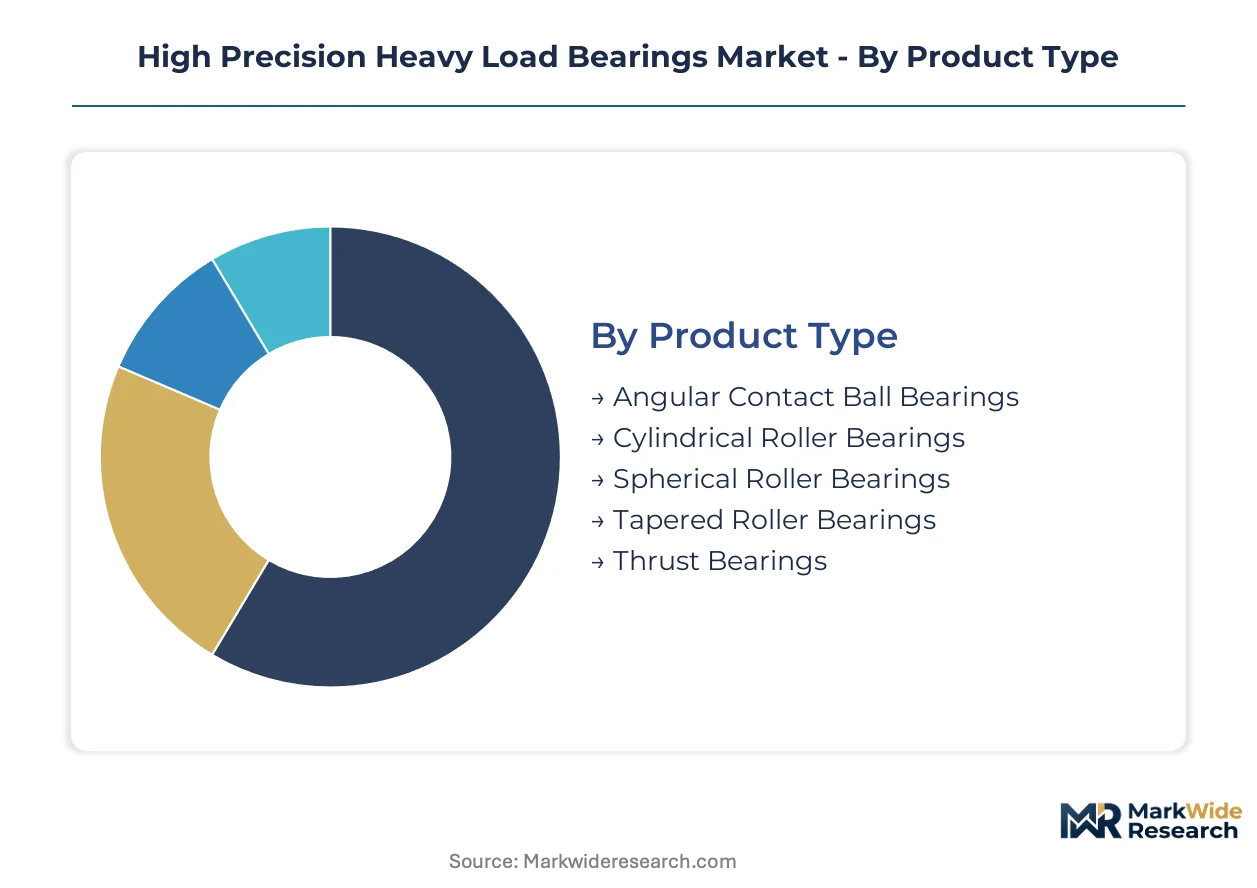
High precision heavy load bearings serve fundamentally different mechanical stresses across rotating equipment categories. Specification mismatches between product type and application torque ratings trigger premature fatigue failures. Procurement patterns diverge sharply between capital-intensive OEM installations and condition-driven aftermarket replacements.
Product Type:
Precision ratings and load vector handling separate competitive positioning across bearing architectures.
- Angular Contact Ball Bearings:These configurations manage combined radial and axial loads through raceway angle geometry, typically ISO P4-grade for machine tool spindles. Demand concentrates in German and Taiwanese precision manufacturing clusters where thermal stability during high-speed rotation determines machining accuracy. Heat generation from preload settings limits maximum speed thresholds in continuous-duty applications.
- Cylindrical Roller Bearings:Line contact geometry delivers exceptional radial load capacity with minimal friction coefficient. Railway bogie modernization across Deutsche Bahn and SNCF networks anchors procurement volumes for axlebox installations. Rigidity requirements in grinding machine spindles sustain parallel demand from metalworking OEMs.
- Spherical Roller Bearings:Self-aligning capability accommodates shaft deflection in multi-megawatt wind turbine main shafts. Offshore installations above 10 MW ratings specify these for nacelle load management.
- Tapered Roller Bearings:Conical geometry handles combined loads in railway traction motors and construction equipment final drives. Indian dedicated freight corridors are opening new procurement channels.
- Thrust Bearings:Axial-only load handling serves vertical pump shafts and marine propulsion systems. Limited growth exposure outside specialized heavy rotating equipment.
Mature deployment sits with cylindrical roller bearings in established railway and machine tool bases. Newer deployment is concentrated in spherical roller bearings scaling toward offshore wind dimensions.
Material:
Material selection trades fatigue life against corrosion resistance, thermal stability, and electrical insulation requirements.
- Chrome Steel:Vacuum-degassed AISI 52100 dominates standard precision applications through superior hardness retention after heat treatment. Supply concentration in Swedish and Japanese billet clusters creates input cost volatility during energy price spikes. REACH compliance on chromium compounds is forcing reformulation assessments for European-sourced material.
- Stainless Steel:Martensitic grades serve marine and food processing equipment where corrosion resistance outweighs fatigue life penalties. Premium positioning reflects nickel and molybdenum alloy costs.
- Ceramic:Silicon nitride rolling elements deliver thermal stability and electrical insulation in a single platform. Hybrid configurations are gaining share fastest in high-speed machine tool spindles above 20,000 RPM.
- Hybrid:Steel raceways paired with ceramic rolling elements balance cost and performance for electric vehicle motor bearings and precision turbomachinery.
- Carbon Steel:Case-hardened variants serve cost-constrained construction equipment with moderate precision requirements. Limited penetration in ISO P4-grade specifications.
Chrome steel retains volume leadership across legacy industrial machinery. Ceramic and hybrid architectures are climbing fastest in electrified and high-speed precision applications.
Application:
End-use sector dynamics reshape specification priorities and supplier qualification pathways.
- Wind Energy:Main shaft and gearbox bearings face 20-year life requirements under stochastic load spectra. Turbine OEMs are consolidating procurement around spherical roller designs rated for 15 MW offshore scale. Condition monitoring integration is becoming standard specification.
- Machine Tools:Spindle bearings demand ISO P2-grade dimensional tolerance for surface finish precision. Taiwanese and German OEMs are accelerating ceramic hybrid adoption for thermal stability during high-speed machining.
- Railway Equipment:Axlebox and traction motor bearings operate under shock loading with extended maintenance intervals. European refurbishment programs concentrate demand for cylindrical and tapered roller configurations.
- Construction Machinery:Lower precision grades tolerate contamination and impact loads. Replacement cycles track equipment utilization hours rather than calendar time.
- Marine Equipment:Propulsion shaft bearings require corrosion-resistant materials and specialized sealing against seawater ingress. Classification society approvals extend qualification timelines.
Machine tools anchor material technology advancement. Wind energy is expanding most quickly in absolute procurement volume.
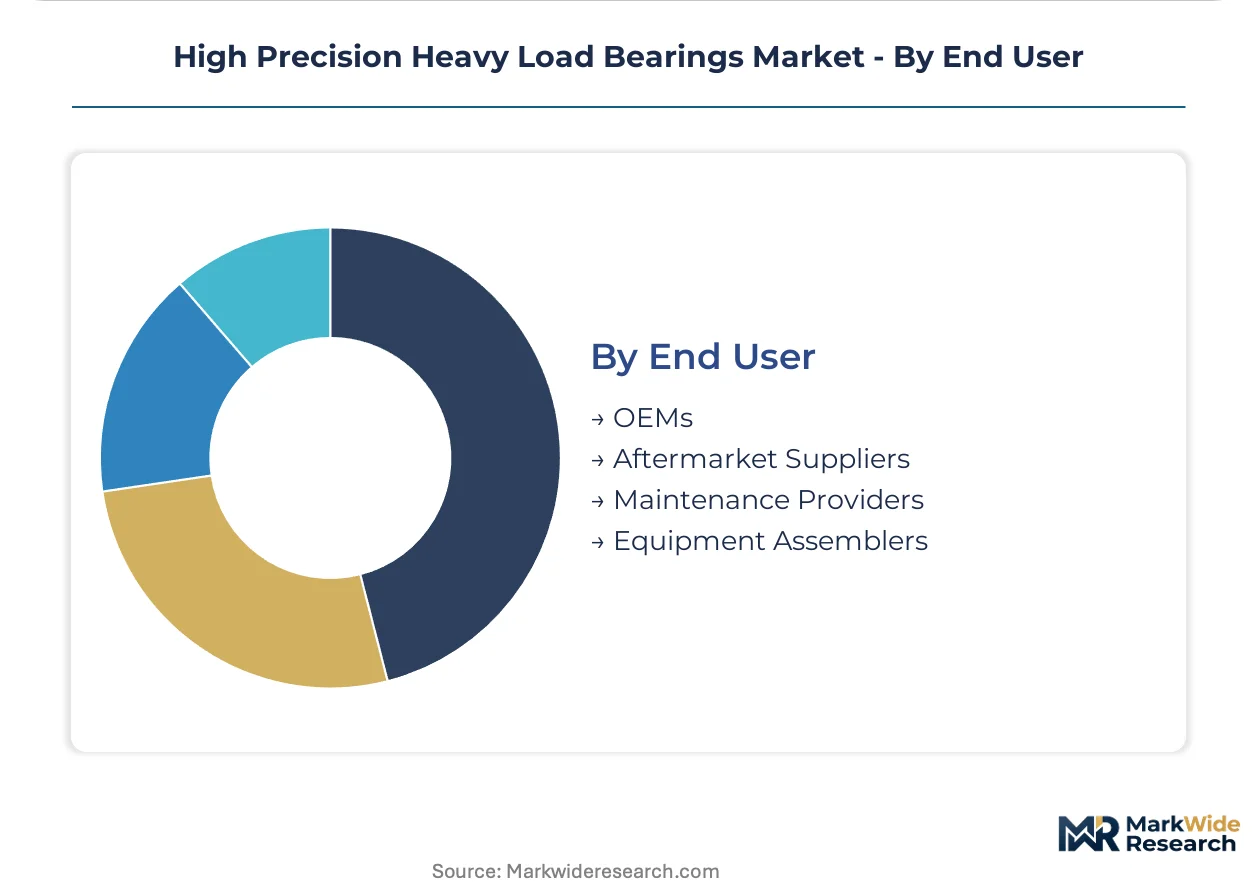
End User:
Channel structure determines margin capture and technical support intensity.
- OEMs:Original equipment manufacturers specify bearings during machine design with integrated condition monitoring. Long-term supply agreements lock in volume commitments across product lifecycles. Technical collaboration on custom geometries sustains supplier relationships.
- Aftermarket Suppliers:Independent distributors serve replacement demand with inventory breadth rather than engineering depth. Price competition intensifies for standard ISO dimension series.
- Maintenance Providers:Predictive maintenance contractors are negotiating direct sensor data access, bypassing traditional distribution layers. Revenue per unit expands through performance-based contracts.
- Equipment Assemblers:Subsystem integrators source bearings as part of purchased component modules. Limited specification influence compared to final equipment OEMs.
Direct OEM relationships concentrate technology development investment. Maintenance provider channels are restructuring margin distribution through outcome-based service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Schweinfurt anchors precision bearing manufacturing through its century-old industrial cluster, while procurement patterns diverge sharply across major demand centers responding to decarbonization mandates and infrastructure renewal timelines.
Germany
Deutsche Bahn's railway modernization and wind turbine OEM consolidation drive spherical roller bearing procurement. The EU F-Gas Regulation tightens lubricant compatibility requirements for precision manufacturing clusters. Schweinfurt and Stuttgart industrial corridors concentrate heat treatment capacity investments.
China
State-owned wind farm tenders with local content mandates accelerate import substitution in main shaft bearings. NMPA-aligned GB standards create parallel certification pathways for Luoyang and Wafangdian suppliers. Yangtze River Delta precision manufacturing zones scale ceramic hybrid production for machine tool spindles.
United States
Onshore wind repowering and Class I railway freight upgrades sustain cylindrical roller bearing demand. EPA industrial emissions tracking influences supplier qualification for federal infrastructure projects. Great Lakes manufacturing belt maintains vacuum-degassed steel processing for aerospace-qualified bearing grades.
Japan
Machine tool spindle OEMs in Nagoya and Tokyo accelerate ceramic hybrid adoption for thermal stability. METI carbon neutrality roadmaps recalibrate energy-intensive heat treatment operations. Kansai industrial corridor concentrates metallurgical engineering expertise for ISO P2-grade dimensional tolerance verification.
India
Dedicated freight corridors and metro buildouts in Mumbai, Delhi, and Bangalore open tapered roller bearing procurement channels. BIS certification requirements extend qualification timelines for traction motor applications. Gujarat and Maharashtra industrial zones attract heat treatment capacity investments from European suppliers.
High Precision Heavy Load Bearings Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a consolidated supplier base where three global groups control premium-tier positioning. Heat treatment capacity and metallurgical IP concentrate competitive differentiation. Strategic archetypes separate integrated steel-to-bearing manufacturers, ceramic material specialists, and predictive maintenance platform operators. Capacity expansion in Asian supply bases and sensor-integrated product development represent dominant competitive vectors.
Within the integrated manufacturing tier, SKF Group and Schaeffler Group exemplify European-origin suppliers with captive steel processing and rotating equipment service platforms. NSK Ltd. anchors Japanese precision engineering positioning through condition-monitoring algorithm development. These three groups collectively occupy positions spanning wind energy qualification, railway certification, and machine tool spindle specification.
| Leading Market Players |
|---|
| SKF Group |
| Schaeffler Group |
| NSK Ltd. |
| NTN Corporation |
| JTEKT Corporation |
| Timken Company |
| RBC Bearings |
| Nachi-Fujikoshi |
| THK Co. |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists in Germany and Japan anchor premium-tier pricing discipline through captive heat treatment capacity and multi-decade OEM relationships. Their ownership structure insulates pricing power from quarterly earnings pressure while concentrating supply-side investment in Schweinfurt and Kansai industrial corridors.
Pricing Analysis
Value-based pricing tied to uptime guarantees and predictive maintenance outcomes anchors premium positioning for sensor-integrated bearing systems. Three-tier pricing structure across ISO P2-grade precision, ISO P4-grade industrial, and standard-grade economy levels separates ceramic hybrid configurations from vacuum-degassed chrome steel variants. Cost compression in standard-grade segments is intensifying because Chinese domestic suppliers in Luoyang are undercutting European incumbents on railway certification contracts. Wind turbine OEMs exhibit lowest price sensitivity due to 20-year life requirements and catastrophic failure costs, while construction equipment distributors show highest sensitivity to per-unit procurement outlays.
Supply Chain Analysis
China's local-content mandates for state-owned wind farm tenders are reshaping sourcing patterns away from Swedish and Japanese billet dependencies. Vacuum-degassed chrome steel feedstock concentrates in Sweden, Japan, and select Great Lakes processing facilities, while silicon nitride ceramic powder draws from specialized producers in Germany and Japan. Single-source vulnerability sits with heat treatment capacity for ISO P2-grade dimensional tolerance verification, where coordinate measuring machine availability constrains throughput. Distribution runs through OEM direct channels for precision-grade specifications and independent distributors for standard replacement inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where REACH compliance friction and ISO P2 certification timelines force capital-constrained regional suppliers toward exit or acquisition. Metallurgical engineering talent scarcity accelerates this pressure as retiring specialists concentrate in incumbent organizations.
For Market Incumbents: Deploy predictive maintenance platform expansion to lock in aftermarket revenue streams before sensor-integrated bearing convergence commoditizes hardware margins. Magnetic bearing substitution in turbomachinery above 30,000 RPM threatens niche precision applications; counter this through ceramic hybrid R&D partnerships with Taiwanese machine tool spindle OEMs. Backward integration into electric-arc furnace steel sourcing secures EU Green Deal embodied carbon compliance advantage.
For New Entrants and Emerging Players: Begin with India's dedicated freight corridor buildouts where BIS certification barriers are lower than European railway qualification cycles. Tapered roller bearings for traction motor applications in Mumbai and Delhi metro systems represent the most penetrable procurement channel. Partner with European heat treatment specialists on joint-venture capacity in Gujarat industrial zones to bypass metallurgical expertise gaps.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap German suppliers with captive Schweinfurt heat treatment capacity and deferred maintenance backlogs from wind farm operators. Long-term viability hinges on sensor-integrated product development pipelines and rotating equipment performance contract capabilities. Watch for inflection when offshore wind turbine OEMs consolidate main shaft bearing procurement around 15 MW-rated spherical roller designs.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Hybrid Capacity Expansion | Taiwanese machine tool OEMs accelerate silicon nitride adoption for thermal stability above 20,000 RPM. |
| Backward Integration into Steel | Electric-arc furnace sourcing secures EU Green Deal Scope 3 disclosure compliance for European suppliers. |
| Predictive Maintenance Platform | SKF Group's Rotating Equipment Performance contracts unify hardware and service revenue streams. |
| Heat Treatment Joint Venture | Gujarat and Maharashtra zones attract European investment to serve Indian railway expansion demand. |
| Condition Monitoring Integration | MEMS sensor and edge analytics bundling collapses traditional component supply and aftermarket separation. |
Research Methodology
Independent corroboration across wind turbine OEM procurement directors, railway bogie engineering leads, machine tool spindle manufacturers, and precision bearing aftermarket service heads underwrites the qualitative findings. Primary interviews with maintenance contractors negotiating direct sensor data access clauses combined with secondary validation from SEC filings of listed suppliers, customs trade data on vacuum-degassed steel billet flows, and ISO certification registry records establish demand-side triangulation. Bottom-up unit economics and top-down industrial production indices cross-validate volume assumptions.
Comparable-period anchoring to historical railway refurbishment cycles and wind turbine installation waves structures the projection horizon across the analysis window. Segmentation dimensions modeled include bearing architecture, material platform, precision grade tier, end-use sector, and regional regulatory cluster. CAGRs derive from installed base expansion rates and replacement cycle compression in predictive maintenance adoption scenarios. Forecast inputs incorporate REACH compliance timeline extensions and F-Gas Regulation lubricant reformulation schedules.
Underlying measurement precision varies by segment; wind energy and machine tool applications carry tighter precision than construction equipment replacement demand due to specification documentation density. Forecasts reflect assumptions on OEM consolidation behavior and import substitution velocity in Chinese state-owned tenders. Supply-side concentration risk and metallurgical talent scarcity constitute primary revision factors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.