
 Forestry Trailers Market | 2026-2036
Forestry Trailers Market Size, Share, and Industry Trends Forecast 2026-2036
Forestry Trailers Market Intelligence
EU Stage V emissions compliance is broadening the cost-of-entry calculus for European trailer manufacturers, forcing investments in lighter chassis materials and refined hydraulic architectures. Pitts Trailers leverages its North American manufacturing scale to serve high-volume logging contractors across the southeastern United States. Palmse Mehaanikakoda Ou anchors its competitive position through specialized bunk trailer designs optimized for Baltic forest conditions. Kesla Oyj differentiates via integrated crane-trailer systems that reduce roadside loading cycle times.
Forestry trailers are heavy-duty transport implements, typically fabricated from high-strength steel with gross vehicle weight ratings exceeding 30 tonnes, designed to haul felled timber from extraction sites to roadside landings or mill facilities. Log trailers occupy the dominant revenue position due to universal applicability across softwood and hardwood operations, while forwarder trailers represent the fastest-expanding category as cut-to-length harvesting systems displace manual felling in Central European forests. Electronic controls command premium positioning within the technology dimension, though hydraulic systems sustain the largest installed base due to proven field durability and lower service complexity.
EMA machinery directives, EU F-Gas Regulation, and national roadworthiness frameworks in Sweden and Finland collectively shape product certification requirements and cross-border transport permissions. Finland's Traficom and Sweden's Transportstyrelsen enforce axle-load limits that directly influence trailer axle configurations and bogie designs sold in the Nordic region. Stakeholders must monitor pending EU machinery regulation revisions that will redefine brake system standards and operator visibility requirements before committing to next-generation platform investments.
Market Dynamics
Mechanized cut-to-length harvesting systems are displacing manual felling across Central European forests, forcing trailer manufacturers to redesign chassis geometries and hydraulic architectures for compatibility with forwarder-mounted cranes and grapple loaders.
Growth Catalysts
- EU F-Gas Regulation:Emissions limits on hydrofluorocarbon refrigerants in transport refrigeration are pushing fleet operators toward lighter, more aerodynamic trailer designs that reduce auxiliary power demands.
- Centralized timber procurement:Estonia's state forest management consolidation is standardizing trailer specifications across contractor fleets, creating volume demand for modular bogie configurations.
- High-strength steel adoption:Advanced metallurgy enables thinner wall sections without sacrificing payload ratings, allowing manufacturers to hit EU Stage V weight targets while maintaining structural integrity.
Market Restraints
- Axle component concentration:Nordic axle and suspension supply chains cluster in southern Sweden and western Finland, exposing manufacturers to localized production disruptions and extended lead times.
- EU machinery directive compliance costs:Revised brake system standards and operator visibility mandates require expensive platform redesigns before products can access cross-border transport permissions.
- Used equipment substitution:Secondary markets for refurbished hydraulic trailers in Poland and Romania absorb price-sensitive demand that might otherwise flow to new equipment purchases.
Strategic Opportunities
- Integrated crane-trailer systems:Converging electro-hydraulic control architectures with telematics-enabled load monitoring creates premium positioning for contractors seeking single-operator roadside efficiency.
- Romanian contractor fleet modernization:Underpenetrated mechanization rates in Carpathian basin hardwood operations present white space for cut-to-length compatible forwarder trailers.
- Digital procurement platforms:Timber marketing cooperatives in Finland are piloting specification-standardized fleet purchasing through centralized online tendering systems.
Industry Challenges
- Hydraulic technician scarcity:Specialized servicing capabilities for high-pressure crane circuits concentrate in regional service hubs, constraining contractor uptime in remote extraction zones.
- Legacy fleet integration:Retrofitting electronic load monitoring onto mechanically controlled trailers requires bespoke interface engineering that fragments aftermarket service offerings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forestry Trailers Market |
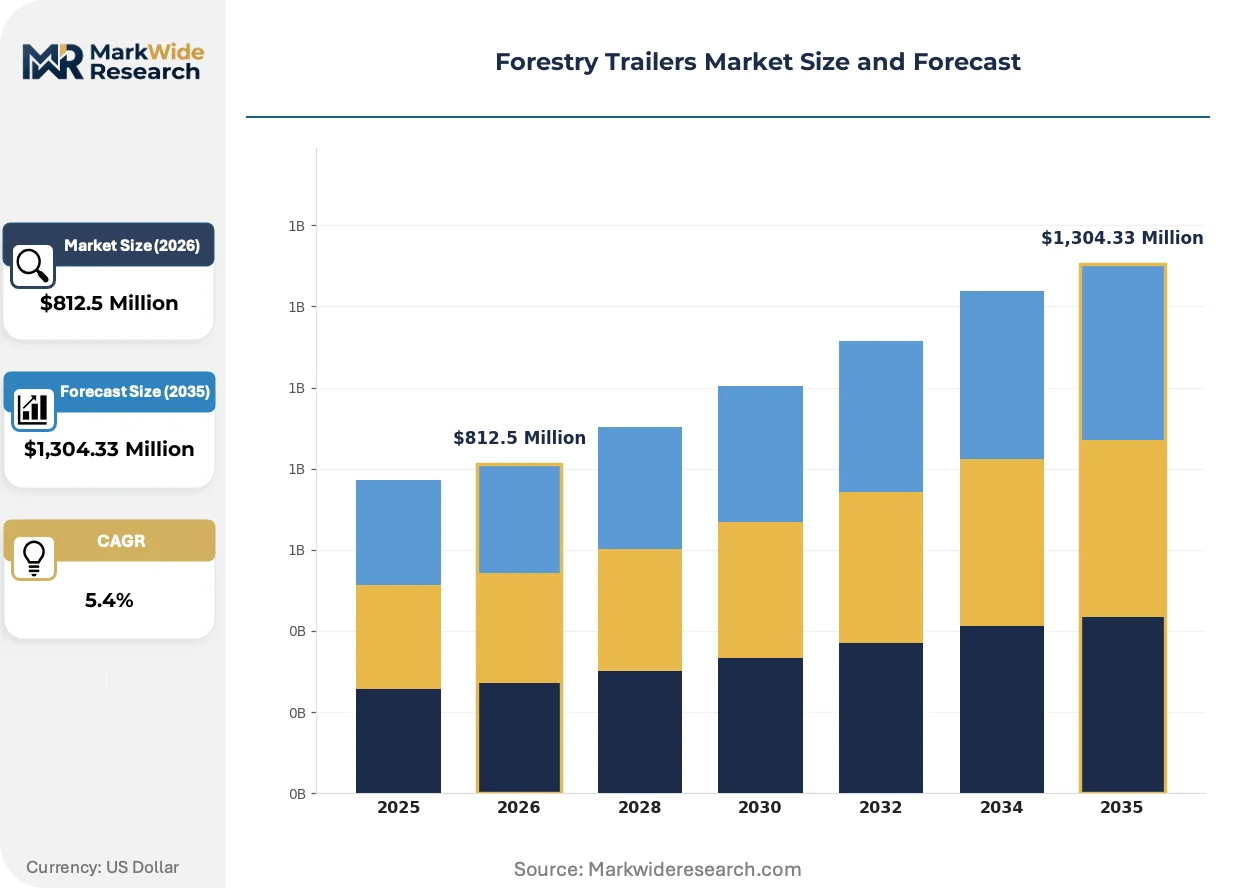
| Market Size in 2026 | $812.5 Million |
| Market Size in 2035 | $1,304.33 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Log Trailers, Forwarder Trailers, Bunk Trailers, Pole Trailers, Harvester Trailers Technology: Hydraulic Systems, Mechanical Winches, PTO Driven, Electronic Controls, Air Brakes Application: Timber Transportation, Roadside Logging, Hatchery Loading, Wood Chipping Support, Lumber Stacking End User: Logging Contractors, Timber Harvesters, Sawmills, Forest Managers, Wood Product Manufacturers |
| Companies Covered | Pitts Trailers, Palmse Mehaanikakoda Ou, JPM Trailers, Scandicon OÜ, Stepa Farmkran Gesellschaft, Chieftain Trailers, B.W.S. Manufacturing, BELL Equipment, Kesla Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forestry Trailers Market Strategic Shifts & Innovations
Digital load management and connected fleet monitoring are compressing operational planning cycles for timber contractors, while material innovations and regulatory stringency reshape equipment specifications.
Telematics-enabled weight distribution sensors are overtaking conventional mechanical load indicators in premium trailer configurations. Large-scale logging contractors in Sweden and Finland are specifying factory-integrated cellular connectivity for real-time payload optimization. This capability is overtaking traditional manual scaling methods at roadside landings, compressing weighing cycle times and reducing disputes with mill procurement systems.
The EU F-Gas Regulation's phase-down schedule for fluorinated greenhouse gases is tightening allowable leakage rates from transport refrigeration units. Trailer manufacturers serving temperature-sensitive pulpwood segments must now certify thermal insulation performance under standardized test protocols. Baltic producers are responding by specifying vacuum-insulated panel cores that maintain payload ratings while meeting MEE-equivalent efficiency benchmarks for cross-border haulage.
Contractor purchasing committees are consolidating equipment specifications across multi-site operations. Large Nordic forest management cooperatives are displacing individualized trailer configurations with standardized fleet packages negotiated through framework agreements. This concentration is most visible in Finland's Metsähallitus contractor network, where centralized procurement now dictates crane reach, axle spacing, and bunk geometry across participating hauliers.
Forestry Trailers Market Segmentation
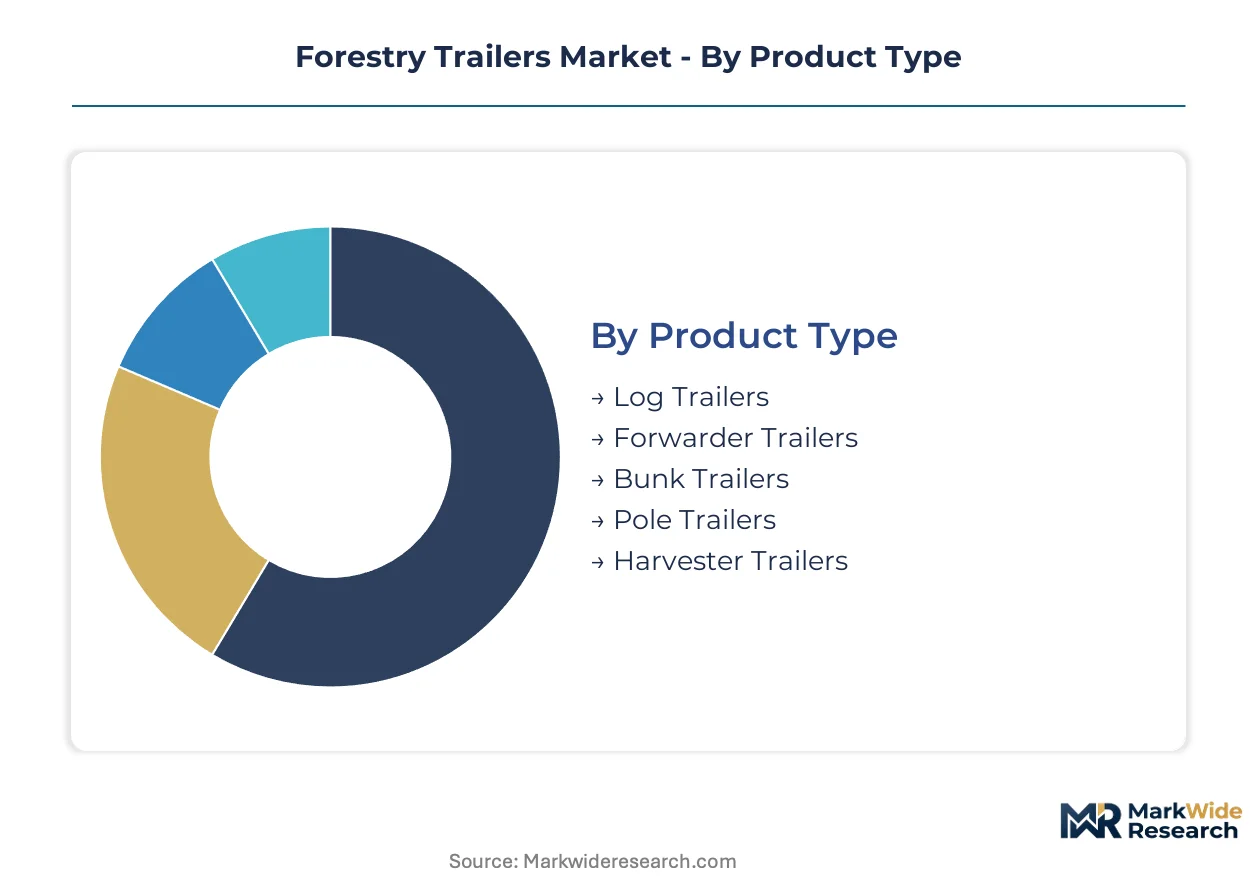
Forestry trailer procurement patterns diverge sharply between standardized fleet packages for large contractors and bespoke configurations for specialized extraction conditions. Equipment specification decisions cascade across axle geometry, crane integration, and load monitoring architecture, creating distinct commercial tiers within each product category.
Product Type:
Customization intensity varies from universal chassis platforms to terrain-specific bogie designs engineered for narrow-gauge forest tracks.
- Log Trailers:Fabricated from high-strength steel with gross vehicle weight ratings exceeding 30 tonnes, these haul felled timber from extraction sites to roadside landings or mill facilities. Demand concentrates across softwood and hardwood operations in Estonia, Finland, and Sweden where centralized timber procurement systems dominate contractor fleet specifications.
- Forwarder Trailers:Purpose-built for cut-to-length harvesting systems, these feature refined hydraulic architectures compatible with forwarder-mounted cranes and grapple loaders. Expansion is steepest in Central European forests as mechanized systems displace manual felling, forcing chassis geometry redesigns for roadside loading efficiency.
- Bunk Trailers:Specialized designs optimized for Baltic forest conditions with reinforced stake pockets and adjustable bunks.
- Pole Trailers:Extended single-bunk configurations for utility pole and veneer log transport.
- Harvester Trailers:Integrated platforms combining felling head transport with log accumulation functions.
Most installed capacity flows through Log Trailers. Expansion is steepest in Forwarder Trailers.
Technology:
Cost-to-performance ratios separate proven field architectures from emerging control systems commanding premium positioning.
- Hydraulic Systems:High-pressure crane circuits and load-sensing valve architectures sustain the largest installed base due to proven field durability and lower service complexity. Demand persists among Polish and Romanian contractors absorbing price-sensitive demand from secondary markets for refurbished equipment.
- Electronic Controls:Telematics-enabled weight distribution sensors and cellular connectivity for real-time payload optimization command premium positioning. Large-scale logging contractors in Sweden and Finland specify factory-integrated systems to compress weighing cycle times and reduce disputes with mill procurement systems.
- Mechanical Winches:Cable-based loading systems for low-mechanization extraction zones.
- PTO Driven:Power-take-off configurations leveraging tractor hydraulics for cost-sensitive operations.
- Air Brakes:Pneumatic braking architectures for high-speed road transport segments.
Hydraulic Systems retain the dominant installed base. Electronic Controls are climbing the fastest as cellular-enabled fleet monitoring becomes standard in Nordic procurement specifications.
Application:
Volume concentration tracks mechanization intensity across the timber value chain from stump to mill gate.
- Timber Transportation:Long-haul road transport from forest landings to sawmills and pulp facilities represents the core revenue application with universal applicability across softwood and hardwood species.
- Roadside Logging:Short-cycle loading and sorting operations at extraction sites demand integrated crane-trailer configurations for single-operator efficiency.
- Hatchery Loading:Specialized seedling and nursery stock transport for reforestation contractors.
- Wood Chipping Support:Biomass feedstock delivery to combined heat and power plants and pellet mills.
- Lumber Stacking:Finished dimension lumber transport from sawmill yards to distribution centers.
Timber Transportation commands the largest equipment population. Roadside Logging is gaining share fastest as cut-to-length harvesting compresses operational planning cycles.
End User:
Procurement scale and specification authority separate integrated forest owners from fragmented contractor bases.
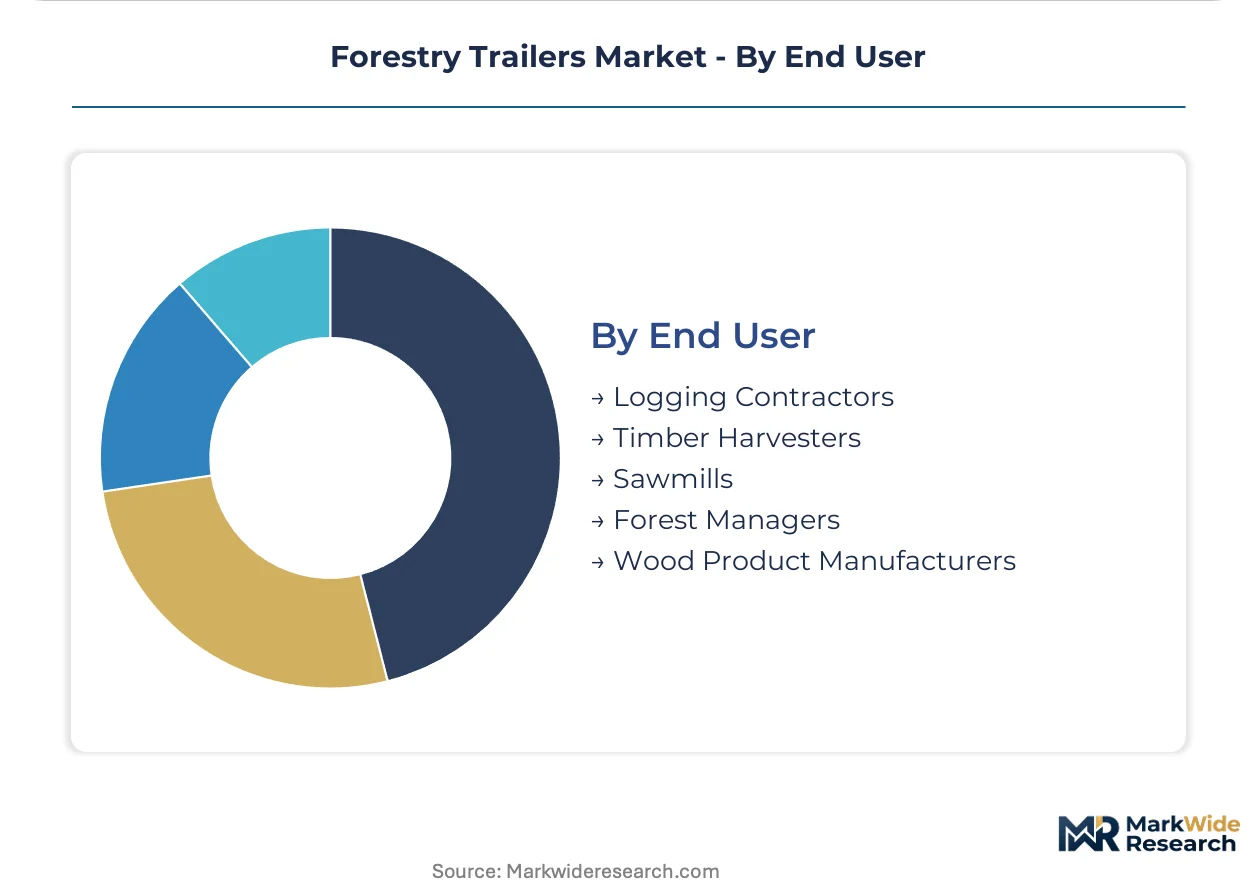
- Logging Contractors:Private forestry contractors in Nordic countries are expanding mechanized fleet investments, with Finland's Metsähallitus contractor network dictating standardized crane reach, axle spacing, and bunk geometry through centralized procurement.
- Timber Harvesters:Integrated harvesting and hauling operations specifying matched forwarder-trailer systems for cut-to-length compatibility.
- Sawmills:Captive fleet operators with dedicated specifications for mill yard logistics and just-in-time raw material delivery.
- Forest Managers:State forest enterprises in Estonia consolidating contractor specifications across multi-site operations.
- Wood Product Manufacturers:Panelboard and engineered wood producers with specialized chip and residual transport requirements.
Logging Contractors represent the largest addressable equipment base. Timber Harvesters show the steepest specification upgrade trajectory as integrated operations displace fragmented hauling arrangements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled hydraulic technicians and specialized fabricators concentrate in southern Sweden and western Finland, anchoring the industry's engineering talent base. This workforce distribution shapes manufacturing capacity and aftermarket service networks across Northern Europe.
Sweden
Sweden's Transportstyrelsen enforces strict axle-load limits that directly influence bogie designs and trailer configurations. The EU F-Gas Regulation drives demand for lighter chassis materials that reduce auxiliary power requirements. Manufacturing clusters around Jönköping and Växjö specialize in high-strength steel fabrication for premium forwarder trailer systems.
Finland
Finland's Traficom mandates brake system standards and operator visibility requirements that reshape platform investments. Metsähallitus contractor networks standardize crane reach and bunk geometry through centralized procurement frameworks. Tampere and Lahti host integrated crane-trailer system specialists serving mechanized cut-to-length operations.
Estonia
Estonia's state forest management consolidation standardizes trailer specifications across contractor fleets. National roadworthiness frameworks align with EU machinery directives for cross-border transport permissions. Tartu-based fabricators supply modular bogie configurations optimized for Baltic forest extraction conditions.
United States
High-volume logging contractors across the southeastern United States drive demand for durable log trailer platforms. EPA emissions standards influence auxiliary power system specifications for transport refrigeration segments. Manufacturing scale concentrates in Alabama and Georgia, serving mechanized softwood harvesting operations.
Germany
German forestry contractors adopt cut-to-length harvesting systems that require refined hydraulic architectures. KBA enforces roadworthiness certification that shapes trailer brake and suspension specifications. Baden-Württemberg fabricators specialize in electronic control integration for premium fleet monitoring applications.
Forestry Trailers Market Key Industry Players
The competitive structure tilts toward specialized regional fabricators with deep hydraulic engineering heritage. Market concentration remains moderate, with no single operator commanding dominant share across all product categories. Three archetypes define competitive positioning: integrated crane-trailer system specialists, scale-driven chassis manufacturers, and terrain-specific custom fabricators. Capacity expansion and technology licensing represent the dominant competitive moves, as players seek to bridge hydraulic and electronic control domains without absorbing full R&D burdens.
Among North American scale manufacturers, Pitts Trailers anchors the high-volume segment serving southeastern logging contractors. Nordic specialists Palmse Mehaanikakoda Ou and Kesla Oyj occupy positions within the integrated systems tier, representing the convergence of crane engineering with trailer platform design. These three exemplify how geographic proximity to end-use markets shapes competitive specialization.
| Leading Market Players |
|---|
| Pitts Trailers |
| Palmse Mehaanikakoda Ou |
| JPM Trailers |
| Scandicon OÜ |
| Stepa Farmkran Gesellschaft |
| Chieftain Trailers |
| B.W.S. Manufacturing |
| BELL Equipment |
| Kesla Oyj |
| Others |
Cost & Logistics Intelligence
High-strength steel metallurgy adoption simultaneously compresses material costs and concentrates fabrication capability among Nordic specialists with advanced welding certifications. This dual effect reshapes procurement economics for contractors balancing EU Stage V weight compliance against payload maximization.
Pricing Analysis
Bundled crane-trailer systems command substantial premiums over unbundled chassis-only configurations across Nordic procurement frameworks. Price differentiation hinges on CE marking tier and after-sales service bundling, with integrated telematics packages separating premium tenders from standard fleet replacements. Cost compression in economy-tier hydraulic systems is intensifying because Polish and Romanian secondary markets absorb price-sensitive demand. Small-scale Baltic contractors exhibit highest price sensitivity; large-scale Finnish Metsähallitus network participants show lowest sensitivity due to framework-negotiated volume terms.
Supply Chain Analysis
Direct-to-contractor channels handle large-fleet hyperscale demand, while regional distributors serve fragmented Polish and Romanian operators. Axle and suspension component fabrication concentrates in southern Sweden and western Finland, with high-strength steel plate sourcing drawing from German and Finnish mills. Supply chain vulnerability rests on single-source dependency for specialized hydraulic valve architectures. Distribution runs through manufacturer-direct relationships for integrated systems and independent equipment dealers for standard log trailer configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The forestry trailers market functions as a stable compounder anchored by irreversible mechanization trends across Central European harvesting operations. Regulatory ratchets on emissions and weight limits sustain replacement demand regardless of timber price cycles.
For Market Incumbents: Lock in hydraulic technician training partnerships with regional vocational institutes to constrain aftermarket service fragmentation. Deepen captive supply of high-strength steel fabrication capacity in Jönköping and Tampere clusters to defend margin position against emerging Polish fabricators. Prioritize certification pre-compliance with pending EU machinery directive brake system revisions. For New Entrants and Emerging Players: Romanian hardwood contractors operating low-mechanization Carpathian basin sites represent the most penetrable buyer archetype for cut-to-length compatible forwarder trailers. Estonian state forest management consolidation creates white space for modular bogie configurations standardized across emerging contractor fleets. Pursue specification inclusion through centralized digital procurement platforms piloted by Finnish timber marketing cooperatives. For Investors and Strategic Acquirers: Valuations sit cheapest among regional custom fabricators with deep hydraulic engineering heritage but limited electronic control integration capabilities. Long-term viability favors specialists bridging mechanical reliability with telematics-enabled fleet monitoring architectures. Watch for inflection when EU machinery regulation revisions trigger mandatory platform redesign investments that strain undercapitalized Tier 2 fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Strength Steel Fabrication | Captive Jönköping mill capacity secures EU Stage V weight compliance without supply disruption. |
| Telematics Platform Integration | Cellular-enabled payload optimization compresses weighing cycle times for Metsähallitus contractors. |
| Joint Venture with Hydraulic Component Suppliers | Tampere-based valve engineering partnerships reduce lead time exposure from Finnish axle clusters. |
| Geographic Expansion into Romanian Contractor Networks | Carpathian basin hardwood mechanization gaps create first-mover positioning for forwarder trailer specialists. |
| Long-term Framework Agreement with State Forest Enterprises | Estonian centralized procurement consolidation locks in multi-year volume commitments for modular bogie configurations. |
Research Approach
Direct dialogue with forestry equipment procurement managers, hydraulic systems engineers, state forest enterprise contracting officers, and regional aftermarket service technicians grounded qualitative assessment. Secondary validation drew from EU machinery directive filings, Traficom and Transportstyrelsen regulatory databases, Estonian state forest management procurement records, and Nordic customs trade data. Bottom-up contractor fleet surveys and top-down equipment production estimates were triangulated to establish baseline volumes.
Segment-level outputs across the analysis window reflect modeled interactions between product type, technology architecture, and end-user procurement scale. CAGRs were derived from regression analysis against mechanization intensity indices and regulatory compliance cost trajectories. Forecast inputs incorporated EU F-Gas Regulation phase-down schedules and projected cut-to-length harvesting adoption curves in Central European hardwood operations.
Underlying measurement precision varies by segment; electronic control and integrated crane-trailer configurations carry tighter precision than refurbished hydraulic aftermarket estimates. Forecasts reflect assumptions on regulatory implementation timing and contractor capital expenditure cycles. Periodic stress-testing of base assumptions against EU machinery directive revision drafts and timber price volatility indices is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Latin America Two-Wheeler Components Market
Vehicle Components
South Africa Automotive Carbon Fiber Composites Market
Vehicle Components
Global Truck and Trailer Landing Gear Market
Vehicle Components
Wheel Seals Market
Vehicle Components
Vehicle Cargo Box Market
Vehicle Components
Tow Tractor Market
Vehicle Components
Cross Roller Bearings Market
Vehicle Components
Global Automotive Carbon Monocoque Chassis Market
Vehicle Components
Bicycle Components Aftermarket Market
Vehicle Components
Engine Components Market
Vehicle Components
Automotive Battery Terminals Market
Vehicle Components
Trailer Stabilizer Market
Vehicle Components
Bicycle Front Hub Market
Vehicle Components
Snowplows Market
Vehicle Components
Russia Automotive Composites Market
Vehicle Components
Bicycle Lights Market