
 Vehicle Retarder Market | 2026-2036
Vehicle Retarder Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Retarder Market Analysis
Shortages of mechatronics engineers with hybrid braking expertise is redrawing competitive boundaries in the vehicle retarder supply base. Voith Group leverages its deep hydraulic retarder heritage to sustain dominance in European bus and coach applications. ZF Friedrichshafen anchors its position through integrated driveline architectures that bundle electric retarders with automated transmissions. Cummins competes by extending its engine braking portfolio into exhaust retarder systems for North American heavy truck fleets.
A vehicle retarder is an auxiliary braking device that dissipates kinetic energy through hydraulic fluid shear, electromagnetic resistance, pneumatic pressure, or exhaust backpressure to reduce service brake wear on heavy commercial vehicles. Hydraulic retarders typically generate continuous braking torque up to several thousand newton-meters through stator-rotor interaction within a sealed oil circuit, enabling controlled descent on prolonged grades without thermal fade. Electric retarder technology is capturing the fastest growth trajectory as battery-electric and hybrid commercial platforms require regenerative-compatible auxiliary braking architectures. Exhaust retarders retain mature volume positions in cost-sensitive mining and construction equipment segments where simplicity outweighs efficiency gains. OEM supply agreements concentrate margin pools around integrated driveline packages rather than standalone aftermarket units.
NHTSA's Federal Motor Vehicle Safety Standards govern retarder performance labeling and braking system integration requirements for US commercial vehicles, while ECE R13 type approval administered by Germany's KBA enforces harmonized braking distribution and heat dissipation protocols across European type certifications. China's MIIT implements GB standards that mandate retarder compatibility testing for domestic heavy truck homologation, tightening market access for non-compliant imports. Stakeholders must monitor how emerging brake-by-wire architectures and autonomous emergency braking mandates reshape retarder control interfaces and certification pathways across major commercial vehicle regulatory regimes.
Market Dynamics
The transition from hydraulic to electric retarder architectures is compressing supplier margins while redrawing certification requirements across commercial vehicle platforms. This technology pivot forces incumbent suppliers to rebuild core competencies around electromagnetic braking integration.
Growth Catalysts
- ECE R13 Braking Mandates:European type approval requirements for heavy commercial vehicles mandate retarder compatibility testing, compelling OEMs to pre-integrate auxiliary braking systems during platform development.
- Long-Haul Logistics Expansion:Fleet operators across Germany's autobahn corridors and Alpine transit routes are standardizing retarder installations to reduce brake fade incidents on sustained descents.
- Battery-Electric Platform Convergence:Regenerative braking architectures on electric heavy trucks require electric retarder integration to manage thermal loads during mixed-mode braking cycles.
Market Restraints
- Copper and Rare-Earth Price Volatility:Electric retarder manufacturing depends on copper windings and neodymium magnets, exposing suppliers to commodity swings that compress unit economics.
- Supplier Concentration in Hydraulic Components:Precision machining capacity for retarder housings and stator assemblies clusters in southern Germany and northern Italy, creating geographic supply vulnerability.
- Exhaust Retarder Substitution Ceiling:Mining equipment operators in cost-sensitive markets retain exhaust backpressure systems despite efficiency penalties, capping electric retarder penetration in off-highway segments.
Strategic Opportunities
- India's PLI-Backed Commercial Vehicle Electrification:Production-linked incentive schemes for electric buses create retrofit demand for electric retarder systems compatible with domestic brake-by-wire platforms.
- Autonomous Truck Braking Redundancy:Self-driving freight platforms require failsafe auxiliary braking architectures, opening specification windows for dual-retarder configurations.
- Remanufacturing Channel Development:Independent service networks in Poland and the Czech Republic are building hydraulic retarder rebuild capabilities, capturing aftermarket value pools outside OEM control.
Industry Challenges
- Mechatronics Talent Scarcity:Hybrid braking system design requires engineers fluent in both electromagnetic simulation and hydraulic control algorithms, a skill intersection with limited labor market depth.
- Dual Certification Timelines:Retarder suppliers seeking US market entry must sequence NHTSA FMVSS compliance testing after ECE R13 approval, extending product launch cycles by 14-18 months.
- Legacy Fleet Integration Complexity:Retrofitting electric retarders onto pre-2018 chassis requires custom driveline adapters and control module reprogramming, fragmenting installation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Retarder Market |
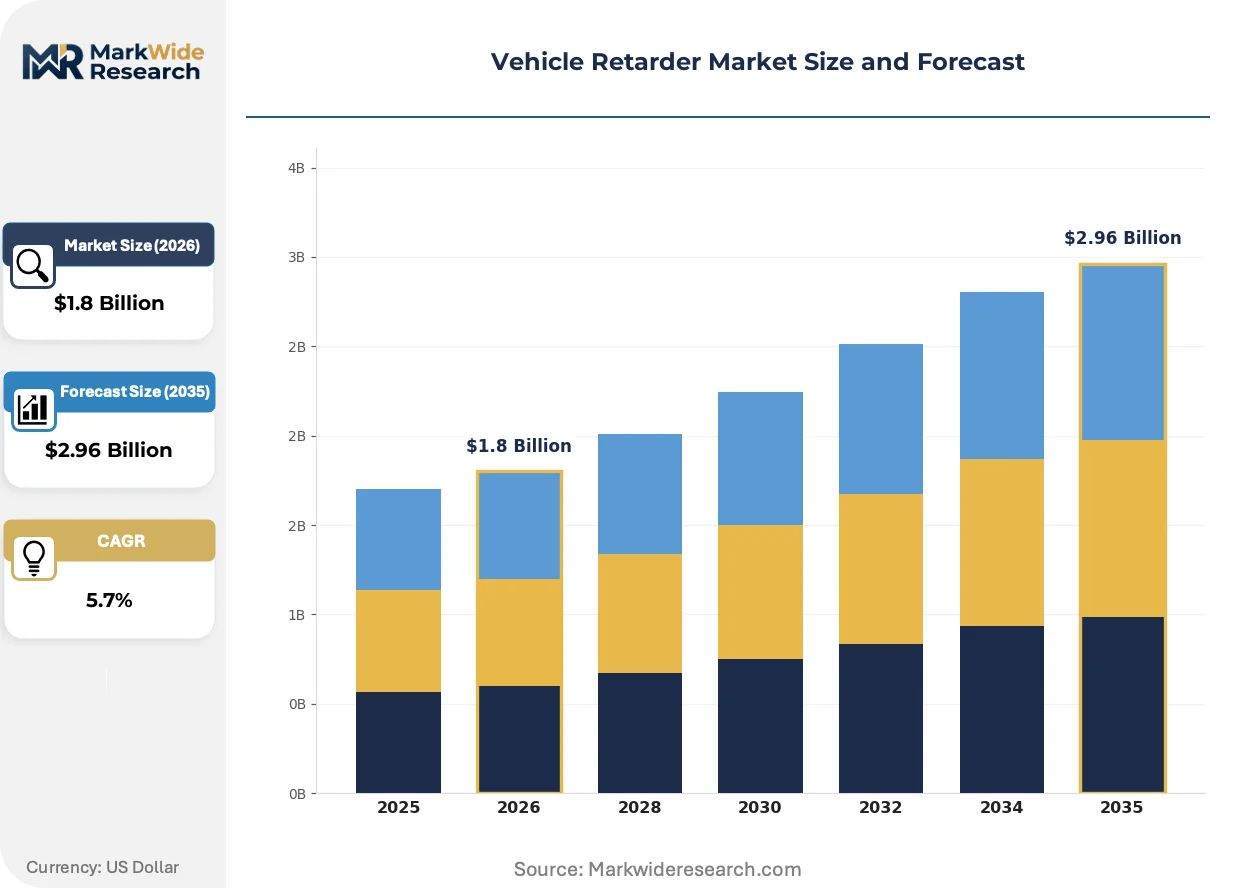
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Hydraulic, Electric, Pneumatic, Exhaust Application: Heavy Trucks, Buses, Construction Vehicles, Mining Equipment Type: Telma, Jacob, Retarder Damping, Viscous End User: OEMs, Aftermarket, Fleet Operators, Logistics Companies |
| Companies Covered | Telma, Klam, Voith Group, Shaanxi Fast, Brakes India, ZF Friedrichshafen, Frenelsa, TBK, Cummins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Retarder Market Emerging Trajectories
Electromagnetic braking architectures are overtaking hydraulic systems as the dominant auxiliary braking technology. This shift is compressing supplier R&D timelines while elevating software integration capabilities as the primary competitive differentiator.
Permanent-magnet eddy current retarders are supplanting hydraulic stator-rotor assemblies in European bus and coach applications. Municipal transit authorities in Germany and the Netherlands are specifying magnet-based systems for their maintenance-free operation and instant torque response. This transition is supplanting traditional fluid-cooled architectures and forcing hydraulic specialists to acquire electromagnetic design expertise or exit the segment.
Europe's F-Gas Regulation is tightening refrigerant containment requirements for retarder cooling circuits that share thermal management with vehicle HVAC systems. Manufacturers must now certify leak-tightness across combined cooling loops, adding validation cost and complexity. Heavy-duty truck platforms with integrated thermal architectures face the steepest compliance burden, driving modular cooling separation in new designs.
Fleet procurement departments are consolidating brake system sourcing under driveline package contracts rather than standalone retarder purchases. Large logistics operators in France and Spain now specify integrated transmission-retarder bundles from single suppliers, compressing margins for component-only vendors. This concentration is most visible in long-haul tractor segments where total cost of ownership modeling dominates supplier selection.
Vehicle Retarder Market Segmentation
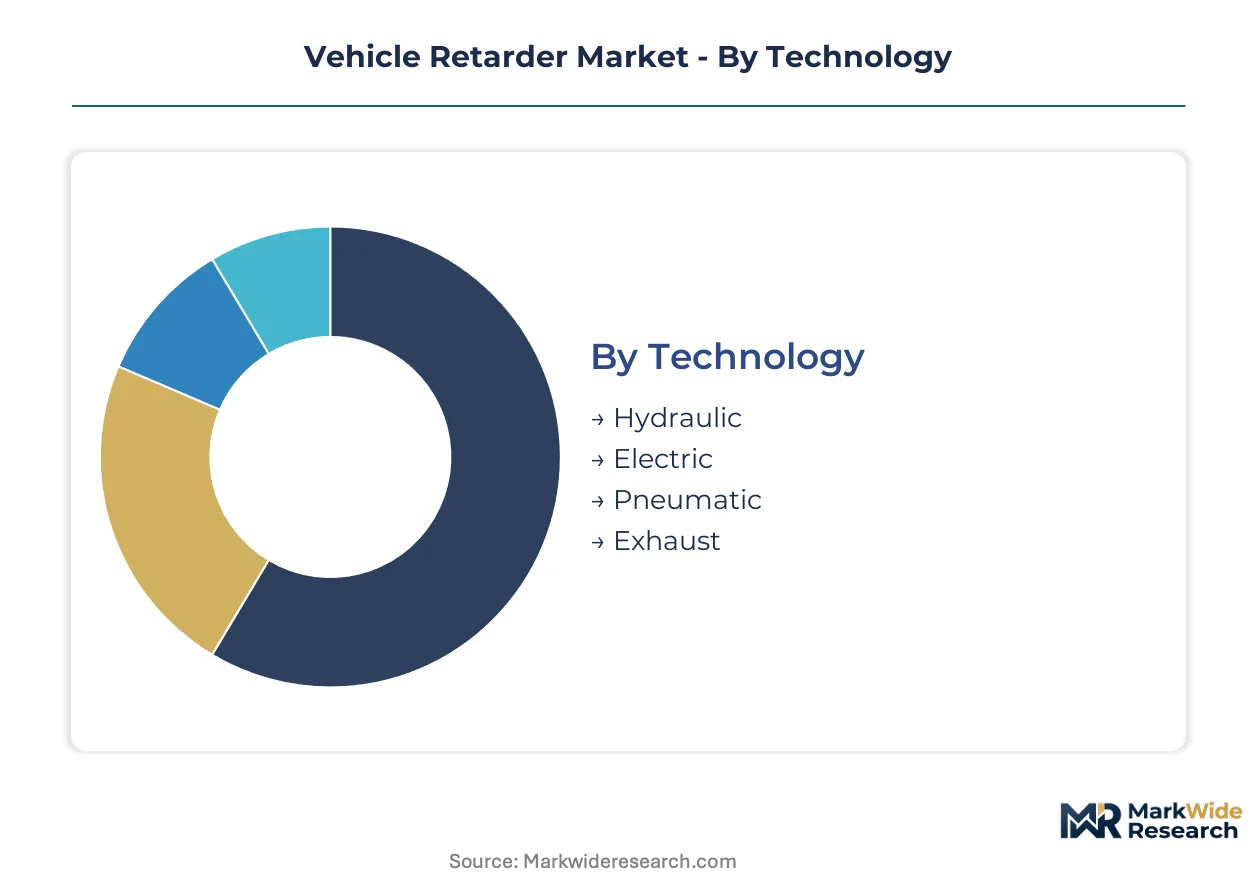
Retarder procurement patterns diverge sharply across technology platforms and vehicle duty cycles. Fleet operators weigh total cost of ownership against regulatory compliance when selecting auxiliary braking architectures for specific route profiles and payload requirements.
Technology:
Electric retarders face intensifying substitution pressure from regenerative braking systems on battery-electric platforms, while hydraulic architectures confront margin compression from permanent-magnet alternatives.
- Hydraulic:Stator-rotor assemblies within sealed oil circuits generate continuous braking torque through fluid shear. German long-haul fleets specify these systems for Alpine descent routes where thermal management dominates procurement criteria.
- Electric:Eddy current and electromagnetic resistance architectures integrate with battery-electric drivelines. Municipal transit authorities in the Netherlands favor these for maintenance-free operation and instant torque response.
- Pneumatic:Compressed-air braking assistance serves cost-sensitive commercial segments. Southeast Asian truck operators deploy these systems where infrastructure simplicity outweighs efficiency optimization.
- Exhaust:Backpressure valves create engine braking through restricted exhaust flow. Mining contractors in Australia retain these for off-highway equipment where repair accessibility trumps fuel economy.
Hydraulic systems retain volume leadership; electric architectures hold the steepest expansion curve.
Application:
Vehicle duty cycles determine retarder specification intensity, with continuous-grade operation demanding fundamentally different architectures than intermittent urban braking.
- Heavy Trucks:Tractor-trailers traversing Germany's autobahn corridors require retarders rated for sustained thermal loads. OEMs pre-integrate these systems to satisfy ECE R13 type approval mandates.
- Buses:Stop-start urban transit cycles favor electric retarders with rapid torque modulation. Coach operators on intercity routes specify hydraulic alternatives for prolonged descent control.
- Construction Vehicles:Articulated dump trucks and graders operate in low-speed high-torque conditions. Exhaust retarders persist here due to contamination tolerance and field-service simplicity.
- Mining Equipment:Ultra-class haul trucks in open-pit operations demand failsafe auxiliary braking. Pneumatic retarders dominate this segment for their independence from electrical systems.
Heavy trucks command the largest installed base; buses are climbing the fastest as electrification accelerates.
Type:
Mechanical configuration determines integration complexity with existing driveline architectures, shaping procurement decisions across vehicle modification scenarios.
- Telma:Eddy current retarders mount directly to driveline components without mechanical linkage. French bus manufacturers specify these for retrofit compatibility with automated transmission packages.
- Jacob:Engine compression release brakes modify valve timing to generate pumping resistance. North American heavy truck fleets standardize these for their zero driveline intrusion and minimal weight penalty.
- Retarder Damping:Integrated transmission-mounted units provide seamless torque blending. These configurations suit European coach operators demanding smooth deceleration for passenger comfort.
- Viscous:Shear-based fluid coupling delivers progressive braking torque. Japanese construction equipment OEMs employ these for their compact packaging in space-constrained chassis.
Jacob systems retain volume leadership; Telma configurations gain share fastest through electrification tailwinds.
End User:
Procurement authority concentration determines specification influence, with integrated fleet operators wielding greater design leverage than fragmented aftermarket channels.
- OEMs:Vehicle manufacturers specify retarders during platform development to optimize driveline packaging. German commercial vehicle producers increasingly bundle electric retarders with automated transmissions.
- Aftermarket:Independent service networks install retrofit systems on legacy chassis. Polish rebuild specialists are developing hydraulic retarder remanufacturing capabilities outside OEM control.
- Fleet Operators:Large logistics companies negotiate driveline package contracts directly. Spanish long-haul fleets now consolidate brake system sourcing under transmission-supplier agreements.
- Logistics Companies:E-commerce delivery fleets prioritize total cost of ownership in procurement. These operators specify electric retarders for urban distribution routes with regenerative braking compatibility.
OEMs retain volume leadership; fleet operators are expanding fastest as procurement centralization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's KBA enforces ECE R13 type approval standards that shape retarder certification across European commercial vehicle platforms. Fleet procurement decisions in specific national markets respond to distinct regulatory pressures and route topography.
Germany
Long-haul logistics operators along Alpine transit corridors specify retarders for sustained descent control. KBA-administered ECE R13 mandates pre-integration during platform development. Stuttgart-based commercial vehicle OEMs bundle electric retarders with automated transmissions for heavy-duty tractor platforms.
United States
North American heavy truck fleets prioritize engine braking systems for zero driveline intrusion and minimal weight penalties. NHTSA's Federal Motor Vehicle Safety Standards govern retarder performance labeling and braking system integration. Indiana and Michigan host manufacturing clusters where suppliers sequence FMVSS compliance testing after European approvals.
China
Domestic heavy truck homologation requires retarder compatibility testing under MIIT-implemented GB standards. Battery-electric commercial platform expansion creates demand for regenerative-compatible auxiliary braking architectures. Shaanxi province anchors production capacity for transmission-integrated retarder systems serving domestic OEMs.
India
Production-linked incentive schemes for electric buses generate retrofit demand for electric retarder systems. Central government PLI schemes accelerate commercial vehicle electrification timelines. Tamil Nadu and Maharashtra industrial corridors concentrate brake system component manufacturing for domestic assembly.
Japan
Construction equipment OEMs specify compact viscous retarders for space-constrained chassis in mining and grading applications. METI oversees industrial standards coordination across commercial vehicle component sectors. Aichi prefecture maintains precision machining capacity for shear-based fluid coupling assemblies.
Vehicle Retarder Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the vehicle retarder supply base. Tier-one suppliers bundle retarders within driveline packages, while component specialists compete on retrofit compatibility and aftermarket rebuild services. Three archetypes dominate: integrated transmission manufacturers, hydraulic heritage specialists, and electric braking entrants. Competitive moves concentrate on strategic partnerships for brake-by-wire integration and geographic expansion into PLI-backed manufacturing jurisdictions.
Within the integrated tier, Voith Group and ZF Friedrichshafen exemplify divergent strategic positions. Voith leverages hydraulic retarder heritage in European bus and coach applications. ZF anchors its position through driveline architectures that bundle electric retarders with automated transmissions. Cummins occupies a distinct position extending engine braking portfolios into exhaust retarder systems for North American heavy truck fleets.
| Leading Market Players |
|---|
| Telma |
| Klam |
| Voith Group |
| Shaanxi Fast |
| Brakes India |
| ZF Friedrichshafen |
| Frenelsa |
| TBK |
| Cummins |
| Others |
Supply Flow & Price Mechanics
Fourteen-week lead times for precision-machined stator housings concentrate pricing power among southern German suppliers, compressing margins for electric retarder entrants competing against established hydraulic specialists with captive machining capacity.
Pricing Analysis
Price spreads between German-engineered hydraulic retarders and Chinese-manufactured electric alternatives span roughly two-to-one in unit terms. Three-tier pricing structure across premium, standard, and economy levels separates ECE R13-certified systems from GB-standard units and unlabeled aftermarket alternatives. Cost compression in the electric tier is intensifying because copper and neodymium commodity exposure erodes unit economics faster than design efficiency gains offset. Fleet operators in Southeast Asia exhibit the highest price sensitivity, while Alpine logistics contractors in Germany prioritize thermal performance over acquisition cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate hydraulic retarder assembly, whereas electric retarder manufacturers maintain strategic stockpiles of copper windings and rare-earth magnets to hedge commodity volatility. Precision machining capacity clusters in Germany, Italy, and Japan, with Shaanxi province emerging for transmission-integrated assembly. Manufacturing draws from copper rod, neodymium magnet, and aluminum casting feedstocks. Single-source vulnerability concentrates in precision grinding equipment for stator-rotor finishing. Distribution runs through OEM driveline bundling contracts rather than standalone component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechatronics engineers fluent in both electromagnetic simulation and hydraulic control algorithms remain scarce across the supply base, constraining product development velocity and widening the capability gap between integrated tier-one suppliers and component specialists.
For Market Incumbents: Shield installed base relationships by embedding electric retarder offerings within automated transmission packages before pure-play electromagnetic entrants achieve brake-by-wire certification. Acquire precision machining capacity in northern Italy to secure stator housing supply against geographic concentration risk.
For New Entrants and Emerging Players: Lead with aftermarket retrofit solutions for pre-2020 heavy truck chassis in Poland and the Czech Republic, where independent service networks lack OEM-aligned electric retarder options. Target municipal bus electrification in India under PLI-backed procurement windows.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because brake-by-wire integration requirements will eliminate standalone component vendors unable to fund dual-certification timelines. Watch NHTSA rulemaking on autonomous truck braking redundancy as the signal for specification inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Brake-by-Wire Integration Partnership | Secures specification slots on autonomous truck platforms requiring redundant auxiliary braking architectures. |
| Rare-Earth Magnet Supply Agreement | Locks in neodymium pricing for electric retarder production against commodity volatility exposure. |
| ECE R13 Dual-Certification Investment | Accelerates US market entry sequencing after European approval, compressing launch cycles. |
| Hydraulic Remanufacturing Channel Buildout | Captures aftermarket value pools in Poland and Czech Republic outside OEM control. |
| PLI-Aligned India Manufacturing Footprint | Positions for electric bus retrofit demand under central government incentive schemes. |
Methodological Framework
Operator-level perspectives from fleet maintenance directors, OEM platform engineers, Tier 1 supplier procurement managers, and aftermarket service network heads anchored the qualitative base. Secondary validation drew from NHTSA FMVSS filings, KBA type approval databases, MIIT GB standard registrations, and commercial vehicle production data. Bottom-up unit demand modeling triangulated against top-down OEM driveline bundling contract analysis.
Sensitivity analysis tested volume and value outputs across technology substitution scenarios, regulatory compliance timeline variations, and commodity price band shifts. Segmentation dimensions spanned propulsion architecture, vehicle duty cycle, thermal management configuration, and regional certification cluster. CAGRs derived from installed base turnover rates and electrification penetration curves, with electric retarder share trajectories calibrated against battery-electric heavy truck adoption patterns.
Underlying assumptions cover ECE R13 mandate enforcement continuity, copper price band stability, and brake-by-wire platform rollout sequencing, with deviation risk concentrated in autonomous truck regulatory acceleration and rare-earth supply disruption. Revision becomes warranted when electric heavy truck penetration crosses threshold levels that eliminate hydraulic system viability in long-haul segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Global Automotive Constant Vehicle Joint Boots Market
Vehicle Components
Motorcycle Monoshock Suspension Market
Vehicle Components
US Automotive Sensors Market
Vehicle Components
Transmission Components Market
Vehicle Components
Trailer Axle Market
Vehicle Components
Navigation Light Market
Vehicle Components
Automotive Powertrain Sensors Market
Vehicle Components
Throttle Cable Market
Vehicle Components
Global Automotive Battery Sensor Market
Vehicle Components
Bicycle Brake Cable Market
Vehicle Components
Garbage Collection Vehicle Market
Vehicle Components
Global Tyre Inflators Market
Vehicle Components
Car Modification Market
Vehicle Components
Sideloaders Market
Vehicle Components
Steering Knuckle Market
Vehicle Components
2 Wheeler Fuel Injection System Market