
 Drive Mode-Linked Powertrain Actuator Systems Market | 2026-2036
Drive Mode-Linked Powertrain Actuator Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Drive Mode-Linked Powertrain Actuator Systems Market Insights
Market Context
The capital-intensity divergence between integrated powertrain suppliers and component specialists is collapsing as mechatronic integration demands heavier upfront tooling investment. Robert Bosch GmbH leverages its semiconductor and sensor portfolio to bundle actuator control modules with proprietary software stacks. ZF Friedrichshafen AG anchors its position through integrated driveline architectures that combine actuation with transmission and axle systems. BorgWarner Inc. competes by specializing in electric actuator designs for hybrid and battery-electric platforms.
Technical Definition and Segments
Drive Mode-Linked Powertrain Actuator Systems are electromechanical or electro-hydraulic devices that adjust engine, transmission, and driveline parameters in response to selectable driving modes, typically operating with response times under 100 milliseconds and force outputs ranging from 50 to 500 Newtons depending on subsystem. These systems enable real-time calibration of throttle mapping, shift scheduling, suspension stiffness, and torque vectoring to match operator intent with vehicle dynamics. Electric actuators dominate passenger car applications where packaging efficiency and noise reduction carry premium value, while electro-hydraulic variants retain structural share in commercial vehicles and off-highway equipment requiring higher force density. Sensor-based control and mechatronic integration represent the fastest-expanding technology segments as OEMs consolidate distributed controllers into domain-centralized architectures.
Regulatory Frame and Outlook
NHTSA crashworthiness standards and EPA greenhouse gas regulations in the United States, alongside EMA emissions frameworks and EU Green Deal decarbonization mandates in Europe, compel actuator suppliers to certify components for functional safety and lifecycle emissions tracking. Japan's METI energy efficiency directives and China's MIIT new-energy vehicle technical standards add parallel compliance layers for suppliers serving those production hubs. Stakeholders must monitor how domain controller consolidation and over-the-air calibration capabilities reshape procurement specifications for actuator hardware.
Market Dynamics
Domain controller consolidation across powertrain architectures is compressing actuator procurement from distributed electromechanical suppliers toward centralized mechatronic integrators, reshaping supplier relationships and tooling amortization cycles.
Growth Catalysts
- EPA greenhouse gas regulations:Passenger car OEMs in the United States face tightening fleet-average emissions mandates that require precise real-time powertrain calibration, expanding demand for sub-100-millisecond response actuators.
- Hybrid platform proliferation:Multi-mode drivetrain architectures require intelligent actuation to coordinate engine restart, electric torque fill, and transmission pre-selection across operating modes.
- EU F-Gas Regulation:The phase-down of fluorinated greenhouse gases in mobile air conditioning and thermal management systems accelerates electric actuator replacement of pneumatic and hydraulic alternatives.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings embedded in high-torque electric actuator motors compress margin predictability for component specialists lacking backward integration into magnet supply.
- Semiconductor foundry concentration:Taiwan and South Korea dominate automotive-grade microcontroller and power electronics fabrication, creating single-source vulnerability for actuator control module suppliers.
- Functional safety certification burden:ISO 26262 ASIL-D requirements for safety-critical throttle and shift actuators extend development timelines and lock out smaller suppliers lacking dedicated validation infrastructure.
Strategic Opportunities
- India automotive manufacturing expansion:PLI scheme incentives for advanced automotive technology components create localized production opportunity for actuators serving Maruti Suzuki, Tata Motors, and Hyundai Motor India export programs.
- Over-the-air calibration capability:Actuator hardware with embedded firmware update architecture enables recurring revenue service models and reduces warranty exposure through remote parameter optimization.
- Sensor-actuator fusion:Integration of torque and position sensing directly into actuator housings eliminates discrete sensor modules, reducing wiring complexity and assembly cost for OEMs consolidating domain controllers.
Industry Challenges
- Mechatronics engineering talent scarcity:The convergence of mechanical design, embedded software, and motor control expertise in single roles outpaces university program output and forces competitive compensation escalation.
- Legacy powertrain software integration:Proprietary communication protocols in existing transmission control units resist standardized actuator interfaces, forcing custom firmware development per OEM program.
- Tooling amortization compression:Shorter vehicle platform lifecycles and powertrain architecture pivots toward electrification strand specialized actuator production equipment before full depreciation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drive Mode-Linked Powertrain Actuator Systems Market |
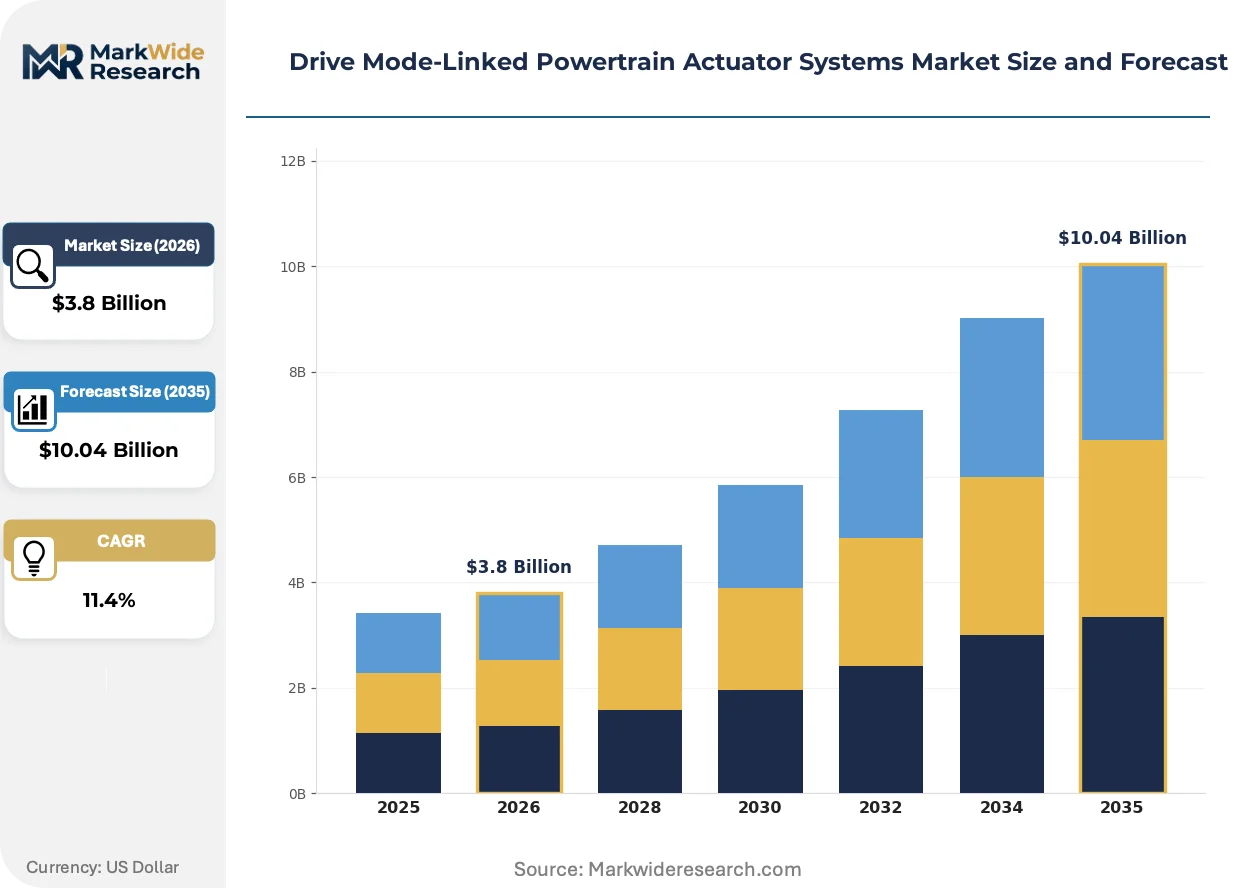
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Actuators, Hydraulic Actuators, Pneumatic Actuators, Electro-Hydraulic Actuators, Servo Actuators Technology: Sensor-Based Control, Adaptive Control, Mechatronic Integration, Microcontroller Driven, Feedback Loop Systems Application: Passenger Cars, Commercial Vehicles, Agricultural Machinery, Construction Equipment, Mining Vehicles End User: OEM Manufacturers, Tier-1 Suppliers, Aftermarket Service Providers, Vehicle Assemblers |
| Companies Covered | Aisin Corporation, ZF Friedrichshafen AG, Robert Bosch GmbH, Schaeffler AG, BorgWarner Inc., Hitachi Astemo, Marelli, Hyundai Mobis, JATCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drive Mode-Linked Powertrain Actuator Systems Market Trends and Innovations
Actuator technology trajectories center on packaging density gains, regulatory compliance automation, and procurement model restructuring as OEMs consolidate supplier bases around system-level integrators.
Brushless DC motor technology with integrated position sensing is miniaturizing shift-by-wire and clutch actuation modules to fit within transmission bell housings previously reserved for purely mechanical linkages. Tier-1 suppliers serving premium passenger car programs have adopted these compact designs since 2022. The reduction in actuator envelope volume is miniaturizing adjacent hydraulic manifolds and enabling transverse-engine packaging previously impossible with electromechanical actuation.
EU F-Gas Regulation mandates on fluorinated greenhouse gas containment and service recovery are forcing redesign of thermal management actuators to eliminate pneumatic refrigerant control valves. Industrial consequence includes accelerated validation of hermetic electric expansion valve actuators for heat pump systems. Battery-electric vehicle platforms with integrated thermal management are most affected, with German and Swedish OEMs specifying all-electric actuator architectures for 2025 model year programs.
Fleet procurement departments at commercial vehicle operators now specify actuator mean-time-between-failure data and total cost of ownership models rather than unit price alone. This behavior shift compresses supplier selection cycles and elevates reliability documentation requirements. North American heavy-duty truck manufacturing clusters exhibit this pattern most visibly, with PACCAR and Daimler Truck North America centralizing actuator qualification under powertrain reliability engineering rather than component purchasing functions.
Drive Mode-Linked Powertrain Actuator Systems Market Segmentation
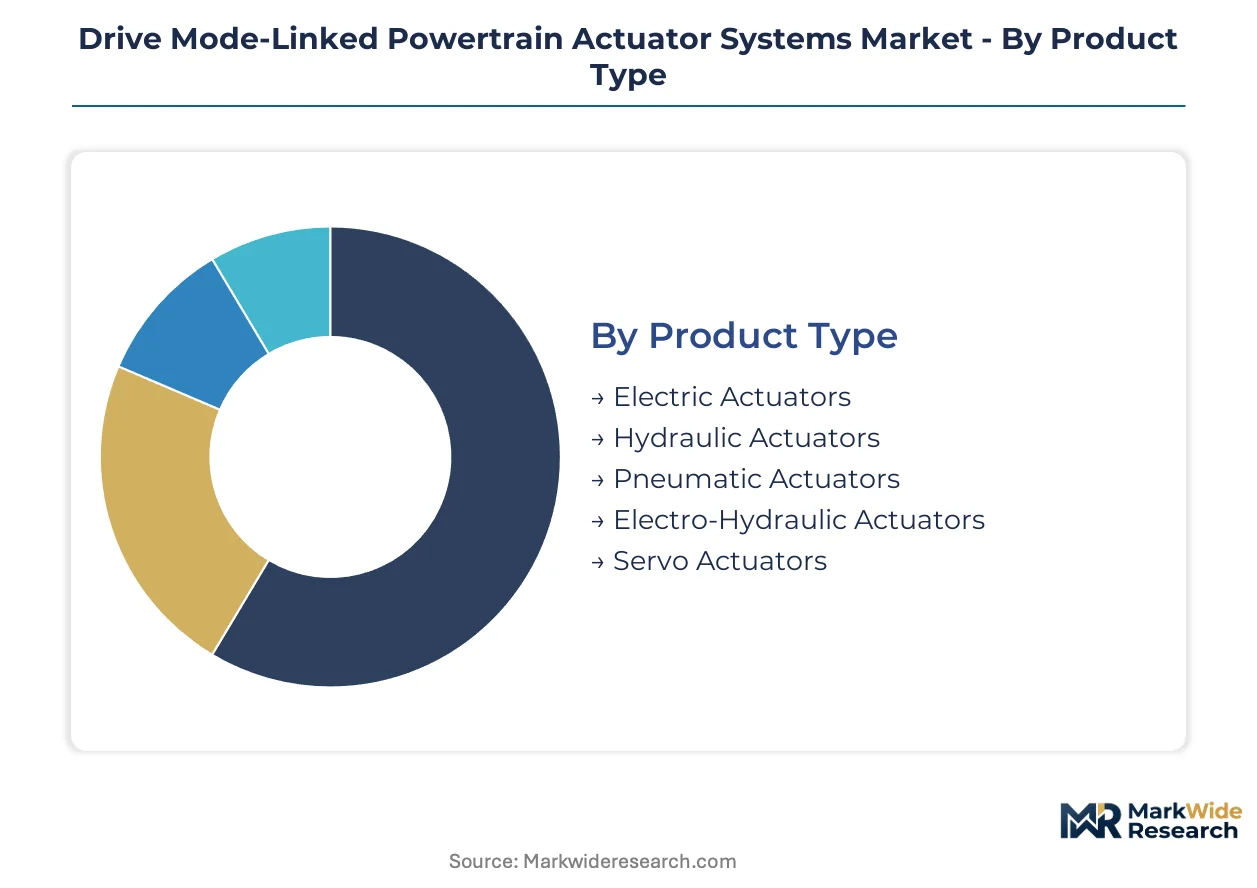
Segmentation reveals how actuator procurement patterns diverge across electrification maturity levels and regulatory jurisdictions. Suppliers must align product architectures with distinct certification requirements and integration complexity tiers.
Product Type:
Electric actuators dominate domestic supply chains serving battery-electric platforms, while hydraulic and pneumatic variants concentrate in export-oriented heavy-equipment manufacturing.
- Electric Actuators:Brushless DC motor designs with integrated position sensing deliver sub-100-millisecond response times for shift-by-wire applications. Demand concentrates in German and Japanese passenger car programs where packaging efficiency and NVH reduction carry premium value, with EPA greenhouse gas regulations accelerating replacement of mechanical linkages.
- Hydraulic Actuators:High-force-density piston systems operating at 200+ bar pressures serve commercial vehicle transmission and driveline applications. Export-led demand from North American heavy-duty truck manufacturing clusters favors these designs for torque capacity, though EU F-Gas Regulation is compressing their share in thermal management subsystems.
- Pneumatic Actuators:Compressed-air systems retain niche presence in legacy commercial vehicle brake and suspension actuation where electrification retrofit costs exceed replacement economics.
- Electro-Hydraulic Actuators:Hybrid architectures combining electric motor precision with hydraulic force multiplication address mining and construction equipment requiring position accuracy under variable load conditions.
- Servo Actuators:Closed-loop motor systems with real-time feedback enable torque vectoring and active differential applications in performance-oriented passenger car platforms.
Electric actuators command the established base. The steepest expansion runs through electro-hydraulic variants serving off-highway electrification transitions.
Technology:
Technology selection tracks OEM domain controller consolidation strategies, with mechatronic integration and sensor fusion commanding cost premiums over discrete microcontroller implementations.
- Sensor-Based Control:Torque and position sensing embedded directly into actuator housings eliminates discrete sensor modules and reduces wiring complexity. Tier-1 suppliers serving premium passenger car programs in Japan and Germany have adopted these designs since 2022, with ISO 26262 ASIL-D certification requirements filtering out smaller component specialists.
- Mechatronic Integration:Consolidation of mechanical actuation, motor control, and embedded software into single housings aligns with OEM domain-centralized architectures. ZF Friedrichshafen AG and Robert Bosch GmbH anchor this segment through bundled actuator control modules with proprietary software stacks.
- Adaptive Control:Machine learning-enabled parameter adjustment responds to driving mode selection and road condition inputs in real-time.
- Microcontroller Driven:Discrete control architectures persist in cost-sensitive commercial vehicle applications where functional safety requirements permit ASIL-B implementations.
- Feedback Loop Systems:Continuous position verification enables precise throttle mapping and shift scheduling calibration across operating modes.
Mechatronic integration captures margin concentration. Sensor-based control is climbing the fastest as OEMs consolidate distributed controllers.
Application:
Application mix reflects diverging electrification timelines, with passenger car platforms leading actuator content per vehicle while commercial vehicle and off-highway segments lag by 3-5 years.
- Passenger Cars:Multi-mode drivetrain architectures require intelligent actuation to coordinate engine restart, electric torque fill, and transmission pre-selection. Chinese and German OEMs specify all-electric actuator architectures for integrated thermal management systems, with MIIT new-energy vehicle technical standards mandating lifecycle emissions tracking.
- Commercial Vehicles:Fleet procurement departments at PACCAR and Daimler Truck North America now specify mean-time-between-failure data and total cost of ownership models rather than unit price alone.
- Agricultural Machinery:Electro-hydraulic implements require position-controlled actuation for precision planting and harvesting operations.
- Construction Equipment:High-force actuators enable automated boom and bucket control in excavators and wheel loaders.
- Mining Vehicles:Extreme-duty actuators with sealed housings operate in abrasive environments with extended service intervals.
Passenger cars anchor volume scale. Commercial vehicles are gaining share fastest as fleet telematics enable outcome-based procurement.
End User:
End user structure is reshaping as domain controller consolidation compresses procurement from distributed electromechanical suppliers toward centralized mechatronic integrators.
- OEM Manufacturers:Volkswagen Group, Toyota Motor Corporation, and Hyundai Motor Group specify actuator architectures at platform level, bundling hardware with proprietary calibration software. Direct OEM relationships require ASIL-D certification and over-the-air update capability.
- Tier-1 Suppliers:Integrated powertrain suppliers including BorgWarner Inc. source actuators for incorporation into transmission and axle system modules, consolidating supplier bases around system-level integrators.
- Aftermarket Service Providers:Independent repair networks demand actuator interchangeability and diagnostic protocol compatibility.
- Vehicle Assemblers:Contract manufacturers serving emerging market OEMs prioritize unit cost over integration depth.
OEM manufacturers command specification authority. Tier-1 suppliers are expanding fastest as mechatronic integration demands heavier upfront tooling investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese manufacturing clusters where mechatronic integration commands premium positioning, while Chinese suppliers compete on volume scale with compressed margins. This asymmetry shapes procurement patterns across regional automotive hubs.
Germany
Stuttgart and Munich automotive clusters drive demand for brushless DC actuator modules serving premium passenger car platforms. EU F-Gas Regulation mandates accelerate electric actuator replacement of pneumatic thermal management components. ZF Friedrichshafen AG anchors the Baden-Württemberg supplier ecosystem through integrated driveline architectures.
China
Shanghai and Guangzhou manufacturing corridors scale production for domestic new-energy vehicle programs. MIIT technical standards mandate lifecycle emissions tracking for powertrain components. BYD and SAIC Motor procurement specifications favor localized actuator supply chains with embedded firmware update capability.
United States
Michigan and Tennessee automotive manufacturing clusters demand sub-100-millisecond response actuators for multi-mode hybrid drivetrains. EPA greenhouse gas regulations tighten fleet-average emissions compliance requirements. Detroit-based powertrain engineering centers specify actuator architectures with over-the-air calibration for 2025 model year programs.
Japan
Nagoya and Tokyo metropolitan manufacturing belts concentrate precision actuator production for export-oriented vehicle programs. METI energy efficiency directives mandate component-level emissions disclosure. Toyota Motor Corporation and Honda Motor anchor domestic procurement through proprietary control module specifications.
India
Tamil Nadu and Maharashtra automotive corridors expand capacity under PLI scheme incentives for advanced component manufacturing. Maruti Suzuki and Tata Motors localize actuator sourcing for domestic and export vehicle programs. Chennai-based suppliers develop cost-optimized designs for ASIL-B commercial vehicle applications.
Drive Mode-Linked Powertrain Actuator Systems Market Competitive Landscape
Concentration sits with integrated powertrain suppliers and diversified automotive component conglomerates that bundle actuator hardware with proprietary software stacks. The vendor base compresses around three strategic archetypes: semiconductor-enabled system integrators leveraging sensor portfolios, transmission-focused driveline specialists, and electric platform component specialists. Dominant competitive moves include mechatronic integration investments and domain controller consolidation partnerships with OEM platform engineering teams.
Among diversified German automotive suppliers, ZF Friedrichshafen AG and Robert Bosch GmbH exemplify the integrated system archetype through bundled control modules. BorgWarner Inc. occupies a specialist position focused on electric actuator designs for hybrid and battery-electric platforms. These three anchors represent distinct competitive vectors within a market restructuring around centralized procurement specifications.
| Leading Market Players |
|---|
| Aisin Corporation |
| ZF Friedrichshafen AG |
| Robert Bosch GmbH |
| Schaeffler AG |
| BorgWarner Inc. |
| Hitachi Astemo |
| Marelli |
| Hyundai Mobis |
| JATCO |
| Others |
Pricing and Supply Chain Analysis
Forty-five-day semiconductor lead times for automotive-grade microcontrollers compress actuator control module availability and amplify pricing power for suppliers with captive chip inventories. This inventory tightness intersects with EPA greenhouse gas compliance deadlines to reward German and Japanese integrated suppliers while squeezing component specialists dependent on spot-market sourcing.
Pricing Analysis
Configured-to-order pricing for ASIL-D certified actuators commands a 40-60% premium over standard ASIL-B implementations for commercial vehicle applications. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade, volume scale, and after-sales service bundling. Cost compression in economy-tier electric actuators is intensifying because Chinese suppliers are scaling brushless DC motor production for domestic new-energy vehicle programs. Fleet procurement departments at North American heavy-duty truck operators exhibit the highest price sensitivity, while German premium passenger car OEMs prioritize response-time performance over unit cost.
Supply Chain Analysis
Taiwan Strait transit vulnerability concentrates risk for automotive-grade microcontroller supply that feeds actuator control module production. Manufacturing draws from Germany, China, and Japan for precision motor assemblies, neodymium magnet processing, and hermetic housing fabrication. Single-source vulnerability sits with Taiwan and South Korea for power electronics fabrication. Distribution runs through Tier-1 integrated powertrain suppliers who bundle actuator hardware with proprietary calibration software stacks for OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domain controller consolidation represents a high-growth disruption as EPA tailpipe standards and EU F-Gas Regulation force real-time powertrain calibration capabilities. This regulatory-technological inflection compresses procurement toward mechatronic integrators with embedded firmware architectures.
For Market Incumbents: Fortify market position through backward integration into semiconductor inventories and sensor fabrication capacity. Lock in multi-year supply agreements with Taiwanese foundries before capacity allocation tightens further. Prioritize ASIL-D certification investment to filter out smaller competitors lacking validation infrastructure. For New Entrants and Emerging Players: Lead with India PLI scheme incentives for localized actuator production serving Maruti Suzuki and Tata Motors export programs. Target cost-optimized ASIL-B commercial vehicle applications where incumbent tooling amortization cycles create procurement gaps. Deploy sensor-actuator fusion as the primary go-to-market angle to eliminate discrete module complexity for emerging market OEMs. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because domain-centralized architectures will compress the supplier base from distributed electromechanical specialists toward integrated mechatronic platforms. Acquisition targets should display embedded software capabilities and existing OEM domain controller partnerships. Monitor over-the-air calibration adoption rates at Detroit-based powertrain engineering centers as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Mechatronic Integration Investment | Consolidates mechanical actuation, motor control, and embedded software into single housings aligned with OEM domain-centralized architectures. |
| Semiconductor Supply Agreement | Secures automotive-grade microcontroller allocation from Taiwan and South Korea foundries amid single-source vulnerability. |
| ASIL-D Certification Pathway | Locks out smaller competitors lacking dedicated functional safety validation infrastructure for throttle and shift actuators. |
| Over-the-Air Firmware Architecture | Enables recurring revenue service models and reduces warranty exposure through remote parameter optimization at OEM platforms. |
| India Manufacturing Footprint | Captures PLI scheme incentives for advanced automotive technology components serving domestic and export vehicle programs. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 supplier procurement directors, aftermarket service managers, and semiconductor distribution specialists and refined through secondary validation. Bottom-up demand modeling triangulated with top-down market sizing drew from vehicle production databases, IHS Markit registration data, SEC filings from listed automotive suppliers, and EPA certification records. Primary fieldwork concentrated on powertrain engineering centers in Michigan, Stuttgart, and Nagoya.
Variance decomposition across vehicle class, propulsion architecture, content per vehicle, and regional production cluster drove segmentation-level growth trajectories throughout the forecast period. CAGRs derived from installed base turnover rates, platform lifecycle timing, and regulatory compliance deadline clustering. Model inputs incorporated EPA greenhouse gas regulation phase-in schedules, EU F-Gas Regulation phase-down curves, and MIIT new-energy vehicle technical standard adoption patterns.
The analysis sits within stated boundaries; outcomes outside hybrid platform proliferation timelines or semiconductor supply normalization would require recalibration. Forecasts reflect documented assumptions about domain controller consolidation velocity and rare earth magnet price stability. Practitioners should keep alternative scenarios live as EPA regulatory stringency and Taiwan Strait logistics conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Brake Booster Market
Powertrain
Powertrain Domain Control Unit Platforms Market
Powertrain
Brazil Automotive Engine Oils Market
Powertrain
Global Automotive Tappet Market
Powertrain
Car Drive System Market
Powertrain
Diesel Particulate Filter (DPF) Market
Powertrain
Global Automotive Clutch Pedals Market
Powertrain
United States Electro Hydraulic Power Steering Market
Powertrain
Turbine Housing for Automobile Market
Powertrain
Automotive Slipper Clutch Market
Powertrain
Asia-Pacific Automotive Engine Oils Market
Powertrain
North America Electrically Powered Hydraulic Steering Market
Powertrain
Emission Control Catalyst for Small Engines Market
Powertrain
Automotive Fuel Pressure Regulator Market
Powertrain
Iridium Spark Plug Market
Powertrain
Tachometer Market