
 Wheelhouse Liner Market | 2026-2036
Wheelhouse Liner Market Size, Share, and Industry Trends Forecast 2026-2036
Wheelhouse Liner Market Analytics
ISO 9001 quality management certification is redrawing competitive boundaries in wheelhouse liner supply. Ken-Tool leverages its tooling heritage to sustain specialized rubber liner production for heavy-duty applications. Husky Liners dominates aftermarket channel control through direct retail distribution and proprietary fitment databases. OER competes on brand strength in classic vehicle restoration segments, anchoring a niche with dedicated enthusiast buyers.
A wheelhouse liner is a protective panel installed within the wheel arch cavity of a vehicle, typically molded from thermoplastic olefin, rubber compounds, or aluminum alloys to shield structural elements from road debris, moisture, and salt-induced corrosion while reducing tire cavity resonance. The component serves primarily to extend chassis service life and improve cabin acoustics in both passenger and commercial vehicles. Rubber liners lead the product type landscape on account of their elasticity and cost efficiency in high-volume OEM contracts, while composite liners represent the fastest-expanding category as manufacturers substitute glass-reinforced polymers for metal to achieve weight reduction targets in electric platforms. Aftermarket providers capture significant margin pools through branded fitment systems, though OEMs anchor absolute volume demand through platform-level supply agreements with vehicle assemblers.
The US NHTSA maintains crashworthiness standards that influence wheelhouse liner material thickness and attachment integrity, while the EPA regulates volatile organic compound emissions from adhesive and coating processes used in liner manufacturing. ISO 14001 environmental management frameworks increasingly gate supplier qualification for multinational OEM procurement programs. Stakeholders must monitor evolving battery-electric vehicle platform architectures, as skateboard chassis designs alter wheel arch geometry and load distribution requirements.
Market Dynamics
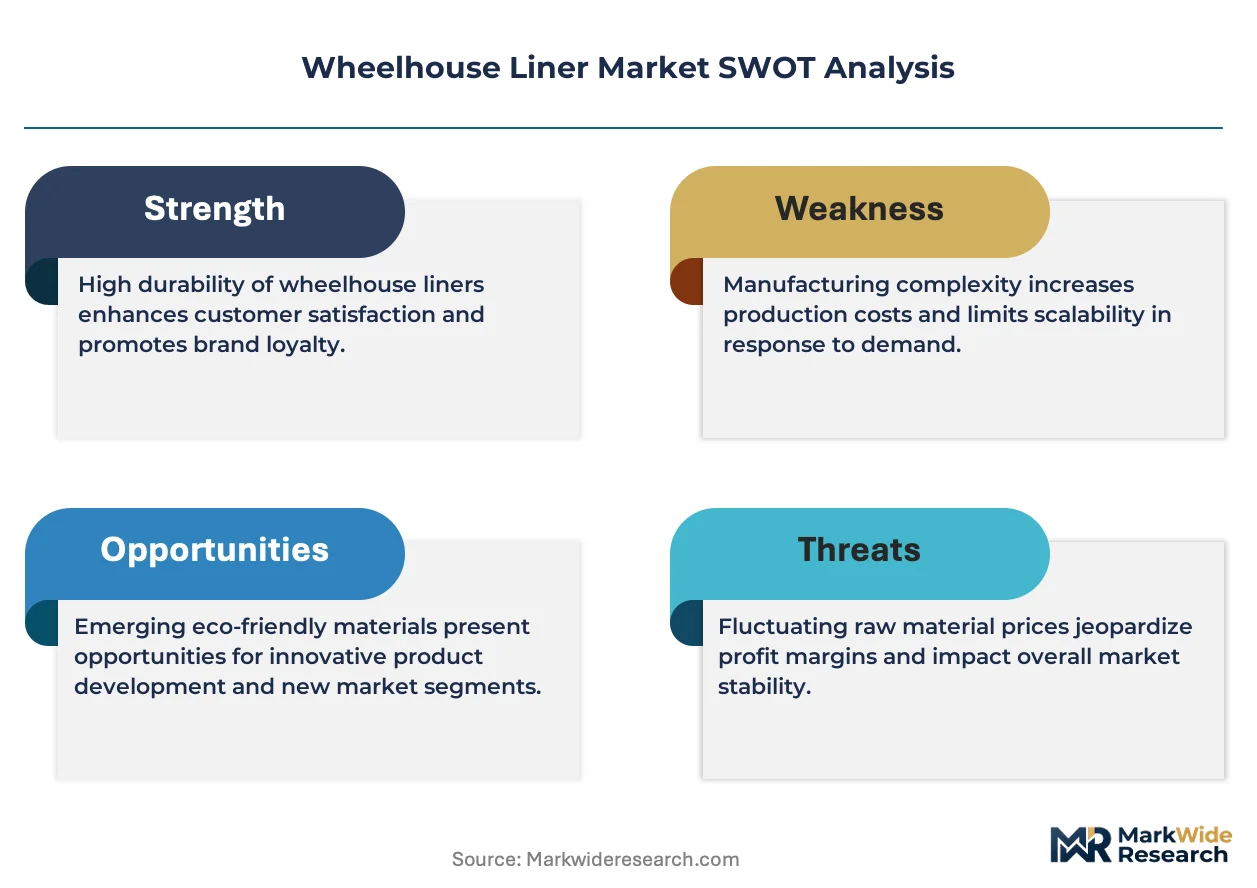
Electric vehicle platform architectures are compressing wheel arch geometries and redistributing structural loads, forcing liner suppliers to redesign attachment systems and material thickness profiles for battery-intensive chassis configurations.
Growth Catalysts
- EPA Emissions Standards:Tightening volatile organic compound limits on adhesive and coating processes are accelerating investment in low-VOC thermoplastic bonding technologies for OEM supply chains.
- EV Acoustic Engineering:Tire cavity resonance dampening requirements in battery-electric platforms are expanding specification scopes for multi-layer composite liners with integrated sound-absorbing substrates.
- Detroit Manufacturing Corridor:Concentrated vehicle assembly capacity in Michigan and Ohio is anchoring regional demand for corrosion-resistant rubber liners in high-volume truck and SUV programs.
Market Restraints
- Petrochemical Feedstock Volatility:Thermoplastic olefin and synthetic rubber input costs fluctuate with crude oil derivatives, compressing margin predictability for molded component suppliers.
- Midwest Supply Concentration:Tier-1 liner manufacturing clusters heavily around Great Lakes logistics hubs, creating geographic vulnerability to winter freight disruptions and single-source dependencies.
- Aluminum Substitution Ceiling:Weight-driven substitution toward aluminum wheelhouse shields faces cost barriers in mass-market vehicle segments, limiting penetration below premium price tiers.
Strategic Opportunities
- Texas EV Battery Belt:Emerging Gigafactory corridors around Austin and Dallas-Fort Worth present white-space demand for localized liner production serving new assembly plants.
- IRA Domestic Content Credits:Inflation Reduction Act battery component sourcing incentives are pulling liner suppliers toward US-based polymer compounding and molding operations.
- Direct-to-Installer Platforms:Digital fitment databases paired with mobile technician networks are bypassing traditional distributor markups in collision repair and fleet maintenance channels.
Industry Challenges
- ISO 14001 Certification Timelines:Environmental management system audits required for multinational OEM qualification are extending supplier onboarding cycles by 8-14 months.
- Skateboard Chassis Integration:Flat-floor battery pack architectures alter wheel arch load paths and attachment point spacing, demanding costly tooling revisions for legacy liner designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheelhouse Liner Market |
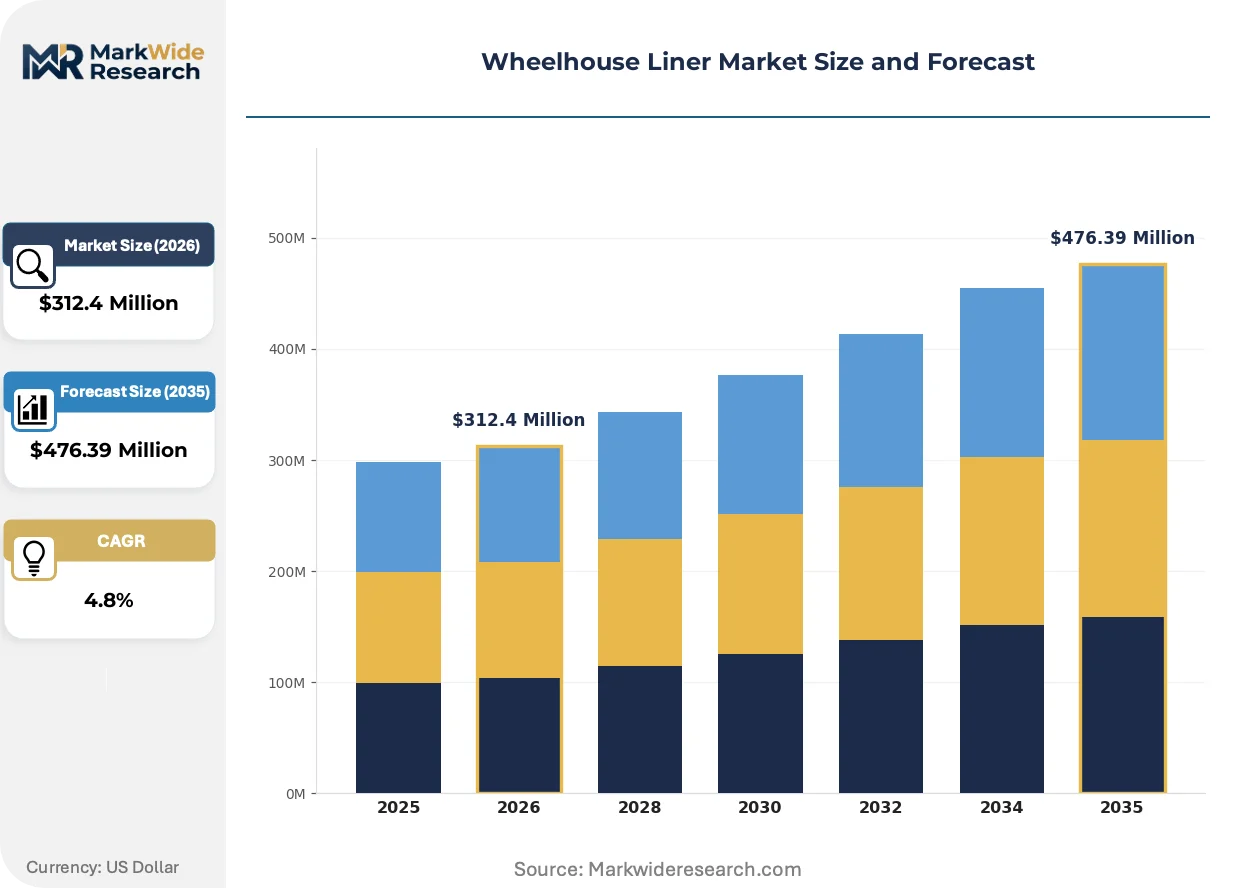
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Liners, Plastic Liners, Composite Liners, Metal Liners End User: OEMs, Aftermarket Providers, Dealerships, Vehicle Assemblers Installation Type: Onshore, Mobile, Fixed, Removable Application: Heavy-Duty Vehicles, Passenger Vehicles, Off-Road Vehicles, Agricultural Machinery |
| Companies Covered | Ken-Tool, Sherman, K-Metal, Duraliner, AMD, OER, Omix-Ada, Husky Liners, DeWALT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheelhouse Liner Market Evolving Landscape
Material science advances and regulatory compliance pressures are converging to transform wheelhouse liner specifications, with lightweighting mandates and acoustic performance targets driving specification divergence across vehicle platforms.
Glass-reinforced polymer composites are supplanting stamped aluminum in premium electric vehicle wheel arches. Luxury EV manufacturers specify these materials for 15-25% mass reduction in unsprung-adjacent components. The substitution is compressing metal-forming equipment utilization rates while expanding thermoplastic press capacity investments.
NHTSA crashworthiness standards are tightening attachment integrity requirements for underbody protective panels. The updated FMVSS testing protocols now mandate retention force thresholds for wheelhouse liners during frontal offset collisions. Heavy-duty truck and commercial van segments are responding with redesigned mechanical fastening systems replacing adhesive-only bonding.
Fleet maintenance departments are consolidating supplier relationships around single-source fitment programs with lifecycle cost guarantees. Large commercial vehicle operators are displacing fragmented parts sourcing with multi-year liner replacement contracts bundled under total cost of ownership frameworks. This concentration is most visible in long-haul trucking corridors linking Chicago, Dallas, and Atlanta distribution hubs.
Wheelhouse Liner Market Segmentation
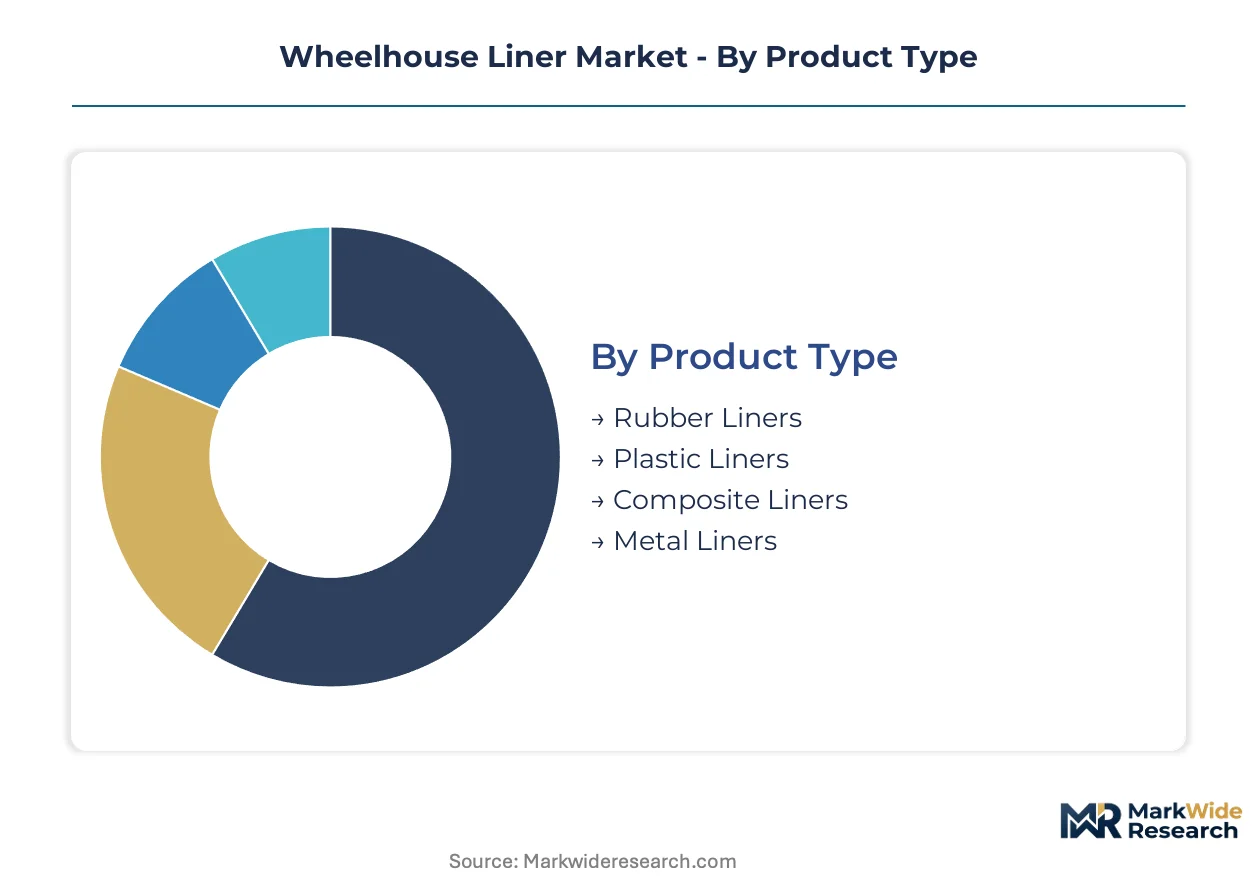
Wheelhouse liner procurement patterns diverge sharply across product chemistry, installation modality, and vehicle platform requirements. Each segment commands distinct margin profiles and channel strategies that suppliers must align against OEM platform specifications and aftermarket service cycles.
Product Type:
Rubber formulations dominate high-volume OEM contracts through the Detroit manufacturing corridor, while composite chemistries penetrate premium EV architectures where mass reduction commands specification priority.
- Rubber Liners:Molded from EPDM and synthetic rubber compounds, these liners deliver elasticity and cost efficiency for high-mileage fleet applications. Demand concentrates in Michigan and Ohio truck assembly plants where corrosion resistance and acoustic dampening anchor specification requirements.
- Composite Liners:Glass-reinforced polymer matrices achieve 15-25% mass reduction versus metal equivalents in battery-electric platforms. Luxury EV manufacturers specify these for unsprung-adjacent weight savings, though thermoplastic press capacity investments lag demand acceleration.
- Plastic Liners:Thermoplastic olefin variants serve mid-market passenger vehicles with balanced cost-performance profiles.
- Metal Liners:Stamped aluminum shields retain position in heavy-duty commercial segments where impact resistance outweighs weight penalties.
By volume, rubber formulations lead. By growth pace, composite materials are climbing the fastest.
End User:
Volume concentration tilts toward platform-level supply agreements, while margin capture favors branded aftermarket channels with proprietary fitment systems.
- OEMs:Direct procurement from vehicle assemblers locks in multi-year platform supply with stringent ISO 14001 environmental qualification requirements.
- Aftermarket Providers:Digital fitment databases and mobile technician networks are displacing traditional distributor markups in collision repair channels.
- Dealerships:Service department parts counters capture replacement demand from warranty expiration cohorts.
- Vehicle Assemblers:Final assembly integration demands just-in-sequence delivery coordination with chassis line pacing.
OEM procurement anchors absolute volume. Aftermarket channels deliver superior margin per unit through branded positioning.
Installation Type:
Attachment system design varies with service context, from permanent factory integration to field-replaceable modules for fleet maintenance operations.
- Fixed:Factory-installed mechanical fastening systems satisfy NHTSA FMVSS retention force thresholds for frontal offset collision integrity.
- Removable:Clip-based attachment enables rapid field replacement in commercial fleet maintenance programs.
- Onshore:Domestic molding operations align with IRA domestic content credit requirements for battery component supply chains.
- Mobile:Technician-deployed liner replacement serves long-haul trucking corridors linking Chicago, Dallas, and Atlanta distribution hubs.
Fixed installations dominate factory output. Removable configurations are gaining share fastest in fleet lifecycle management contracts.
Application:
Load severity and environmental exposure dictate material thickness profiles, with off-road and agricultural segments demanding reinforced geometries absent from passenger car specifications.
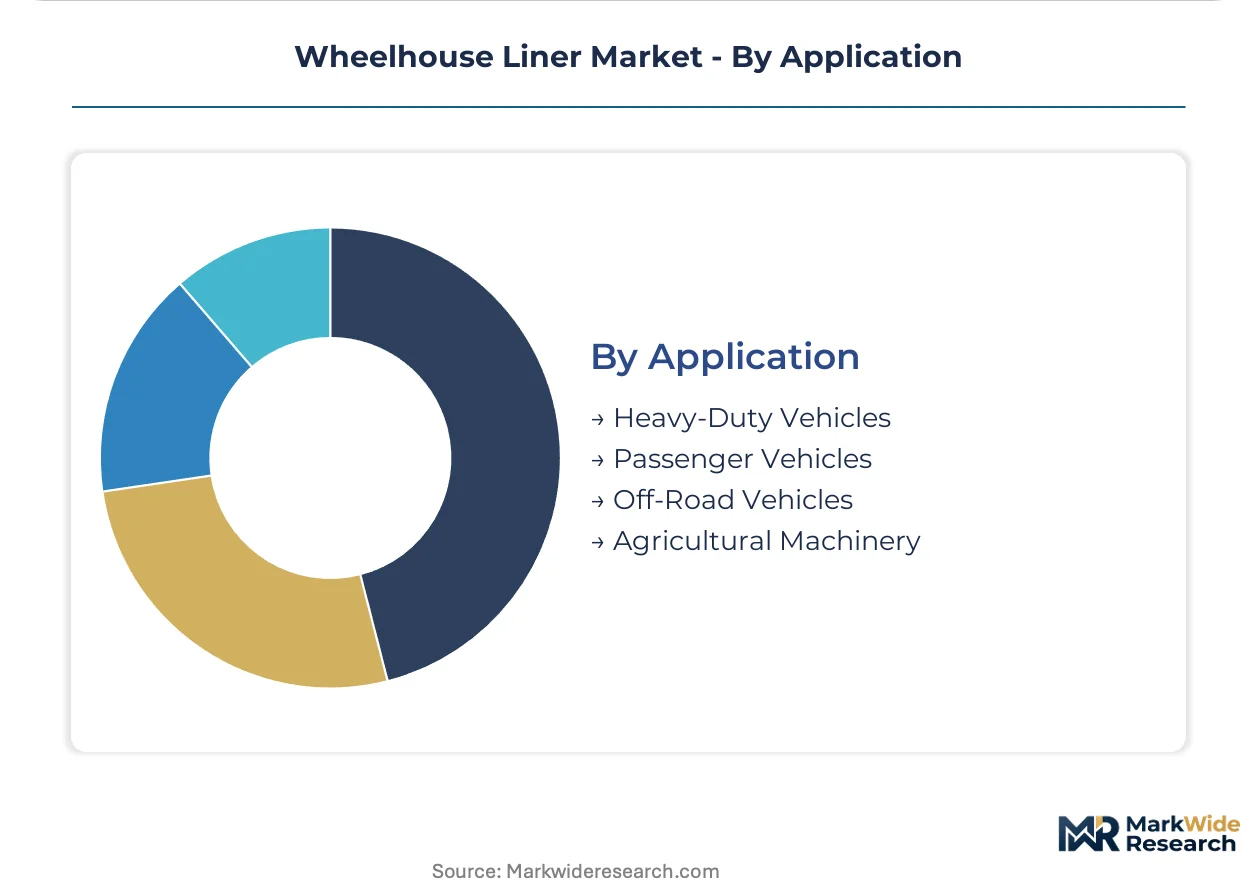
- Heavy-Duty Vehicles:Commercial truck wheel arches require thicker rubber formulations to withstand gravel impact and salt spray exposure on interstate corridors.
- Passenger Vehicles:Cabin acoustic engineering specifications in battery-electric platforms are expanding demand for multi-layer composite liners with integrated sound-absorbing substrates.
- Off-Road Vehicles:Recreational and utility terrain vehicles specify impact-resistant geometries for unimproved surface operation.
- Agricultural Machinery:Combine and tractor applications demand chemical-resistant compounds for fertilizer and pesticide exposure environments.
Heavy-duty commercial applications lead by unit volume. Passenger EV platforms are expanding most quickly by specification complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive assemblers and fleet operators concentrate procurement decisions in manufacturing corridors where Tier-1 supplier density meets regulatory enforcement capacity. Regional demand patterns track vehicle assembly footprints, EPA enforcement zones, and logistics infrastructure for polymer feedstock distribution.
United States
Detroit-area vehicle assemblers anchor consumption of corrosion-resistant rubber liners for truck and SUV platforms. NHTSA FMVSS retention force thresholds govern attachment system design for frontal offset collision integrity. Michigan and Ohio manufacturing clusters concentrate molding capacity along Great Lakes freight corridors serving just-in-sequence chassis line delivery.
Germany
Luxury EV manufacturers specify glass-reinforced polymer composites for unsprung-adjacent mass reduction in battery-electric architectures. EU REACH chemical safety protocols regulate adhesive bonding processes and thermoplastic compound formulations. Stuttgart and Munich industrial zones concentrate Tier-1 liner engineering capacity alongside premium vehicle assembly plants.
China
Domestic EV platform producers compress wheel arch geometries for skateboard chassis configurations, demanding redesigned liner attachment systems. MIIT vehicle safety standards influence underbody component material thickness specifications. Yangtze River Delta manufacturing hubs cluster thermoplastic press capacity to serve battery-electric vehicle export programs.
Japan
Passenger EV acoustic engineering requirements expand specification scopes for multi-layer composite liners with integrated sound-absorbing substrates. METI industrial standards govern volatile organic compound emissions from molding operations. Nagoya and Osaka production corridors sustain specialized rubber compounding for hybrid and electric platform supply chains.
Mexico
Cross-border automotive supply chains position liner molding operations to serve US vehicle assembly with IRA domestic content credit alignment. Mexican environmental enforcement tracks NOM industrial emissions standards for polymer processing facilities. Nuevo León and Bajío Region industrial parks concentrate foreign-owned Tier-1 component manufacturing for North American platform integration.
Wheelhouse Liner Market Competitive Landscape
Player mix skews toward diversified automotive component conglomerates with captive polymer compounding operations and specialized aftermarket fitment specialists with proprietary distribution infrastructure. Market structure exhibits tiered concentration: OEM-facing molders with platform-level supply agreements dominate absolute volume, while branded aftermarket providers capture superior margin per unit through direct retail channel control. Strategic archetypes include ISO-certified Tier-1 system suppliers, heritage tooling companies with heavy-duty specialization, and digital-native fitment database operators. Competitive moves center on backward integration into polymer compounding and geographic expansion toward emerging EV battery belt corridors.
Among heritage automotive tooling specialists, Ken-Tool occupies a position exemplifying rubber liner production for heavy-duty fleet applications. Husky Liners represents the aftermarket channel archetype, anchoring branded fitment system distribution through proprietary database control. OER sits within the restoration segment specialist tier, serving dedicated enthusiast buyer cohorts in classic vehicle markets.
| Leading Market Players |
|---|
| Ken-Tool |
| Sherman |
| K-Metal |
| Duraliner |
| AMD |
| OER |
| Omix-Ada |
| Husky Liners |
| DeWALT |
| Others |
Value Network & Pricing Analysis
ISO 14001 environmental management certification gates supplier qualification for multinational OEM procurement programs while simultaneously enabling price differentiation between certified and uncertified production tiers. The dual function of this standard compresses margin pools for non-compliant molders while expanding premium capture for Tier-1 system suppliers with verified environmental frameworks.
Pricing Analysis
Cost-plus contracts with petrochemical feedstock indexation dominate high-volume OEM agreements along the Detroit manufacturing corridor. Price differentiation separates ISO 14001-certified Tier-1 suppliers from uncertified competitors, with brand premium and volume scale as secondary tiering factors. Pricing pressure stems from thermoplastic olefin input cost volatility tied to crude oil derivatives. Fleet operators exhibit highest price sensitivity through total cost of ownership frameworks, while luxury EV manufacturers prioritize mass reduction specifications over unit cost.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes elevates inbound logistics costs for glass-reinforced polymer resin shipments serving domestic thermoplastic press capacity. Supply concentrates in the United States, Germany, and China, with raw material dependencies on EPDM rubber compounds, synthetic thermoplastic olefins, and aluminum sheet feedstock. Single-source vulnerability runs through Great Lakes logistics hubs concentrated around Detroit-area molding operations. Distribution runs through just-in-sequence delivery coordination with vehicle assembler chassis lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as fleet maintenance departments consolidate supplier relationships around single-source fitment programs with lifecycle cost guarantees, displacing fragmented parts sourcing.
For Market Incumbents: Consolidate backward integration into polymer compounding operations to defend margin position against petrochemical feedstock volatility. Expand thermoplastic press capacity investments toward Texas EV battery belt corridors to capture emerging Gigafactory demand. ISO 14001 certification maintenance anchors platform-level supply agreement retention against emerging competitors. For New Entrants and Emerging Players: Lead with digital fitment database development paired with mobile technician networks to bypass traditional distributor markups in collision repair channels. Target the Texas EV battery belt white-space around Austin and Dallas-Fort Worth assembly plants. Direct-to-installer platforms offer the most penetrable go-to-market angle against entrenched aftermarket distributors. For Investors and Strategic Acquirers: IRA domestic content credit implementation reshapes the acquisition landscape toward US-based polymer compounding and molding operations. Long-term viability centers on suppliers with verified environmental management frameworks and proximity to emerging battery-electric vehicle assembly corridors. The signal to watch is skateboard chassis platform adoption rates altering wheel arch geometry specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive EPDM and thermoplastic olefin supply reduces exposure to petrochemical price volatility. |
| Texas Manufacturing Footprint Expansion | Proximity to Austin and Dallas-Fort Worth Gigafactory corridors aligns with IRA domestic content requirements. |
| ISO 14001 Certification Investment | Environmental management system verification gates multinational OEM procurement program qualification. |
| Digital Fitment Database Development | Proprietary vehicle configuration data enables direct-to-installer platform bypass of distributor markups. |
| Mobile Technician Network Partnership | Field-deployed replacement services capture fleet maintenance contracts in long-haul trucking corridors. |
Research Methodology
A standing panel of OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distribution channel heads, and fleet maintenance operations managers provided ongoing calibration against market developments. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, SEC filings from automotive component suppliers, and EPA emissions compliance records. Bottom-up volume modeling triangulated against top-down market sizing across rubber, composite, plastic, and metal liner chemistries.
Consistency checks validated volume and value outputs against external benchmarks including vehicle assembly forecasts and polymer consumption trends. The analytical framework segmented by product type, end user, installation configuration, and application severity across the projection horizon. CAGRs derived from regression analysis of historical platform adoption rates and content-per-vehicle trajectories. Key inputs included battery-electric vehicle architecture penetration assumptions and NHTSA FMVSS retention force threshold compliance timelines.
Underlying assumptions cover EPA emissions standard enforcement continuity, petrochemical feedstock price band stability, and skateboard chassis platform adoption curves, with deviation risk concentrated in IRA domestic content credit rulemaking changes. Forecasts reflect these documented conditions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
China Automotive Carbon Fiber Composites Market
Vehicle Components
Automotive Position Sensor Market
Vehicle Components
Global Automotive EGR Valves Market
Vehicle Components
Bicycle Lights Market
Vehicle Components
Idler Arm Market
Vehicle Components
Industrial Gearbox Market
Vehicle Components
South Africa Automotive Carbon Fiber Composites Market
Vehicle Components
Railway Brake Pads Market
Vehicle Components
Crash Lock Box Market
Vehicle Components
Electric Vehicles Component Market
Vehicle Components
Towing Equipment Market
Vehicle Components
Wheel Studs Market
Vehicle Components
Railway Air Filter Market
Vehicle Components
Car Sunshade Market
Vehicle Components
Anchorage Connector Market
Vehicle Components
Truck Suspension System Market