
 North America Naval Vessels Market | 2026-2036
North America Naval Vessels Market Size, Share, and Industry Trends Forecast 2026-2036
North America Naval Vessels Market Analytics
Buyer concentration among US and Canadian naval procurement offices is recalibrating contract award patterns across the builder base. General Dynamics Corporation leverages its Electric Boat division to dominate nuclear submarine construction. Huntington Ingalls Industries anchors large-deck amphibious and surface combatant production at its Virginia and Mississippi facilities. Austal USA specializes in aluminum-hulled littoral platforms, competing for independently derived hull programs.
North America naval vessels are steel and aluminum hulls engineered to naval classification society scantling rules, with displacement ranging from patrol craft below 1,000 tonnes to nuclear aircraft carriers exceeding 100,000 tonnes, built through modular block construction and outfitted with integrated electric propulsion or nuclear reactors for sustained blue-water operations. Destroyers and submarines command the largest share of current contract value, with amphibious assault ships representing a mature segment facing production-gap risk between hull generations. Frigates are gaining share as the US Navy accelerates the Constellation-class program and Canada advances its Canadian Surface Combatant replacement.
The US Navy's Naval Sea Systems Command, Canada's Department of National Defence procurement branch, and the American Bureau of Shipping classification standards collectively govern hull design approval, construction oversight, and fleet certification requirements across the region. Environmental compliance with EPA vessel discharge standards and evolving Coast Guard safety mandates are adding engineering scope to newbuild specifications. Stakeholders must monitor how congressional appropriations for Columbia-class ballistic missile submarines reshape yard capacity allocation for surface combatant programs.
Market Dynamics
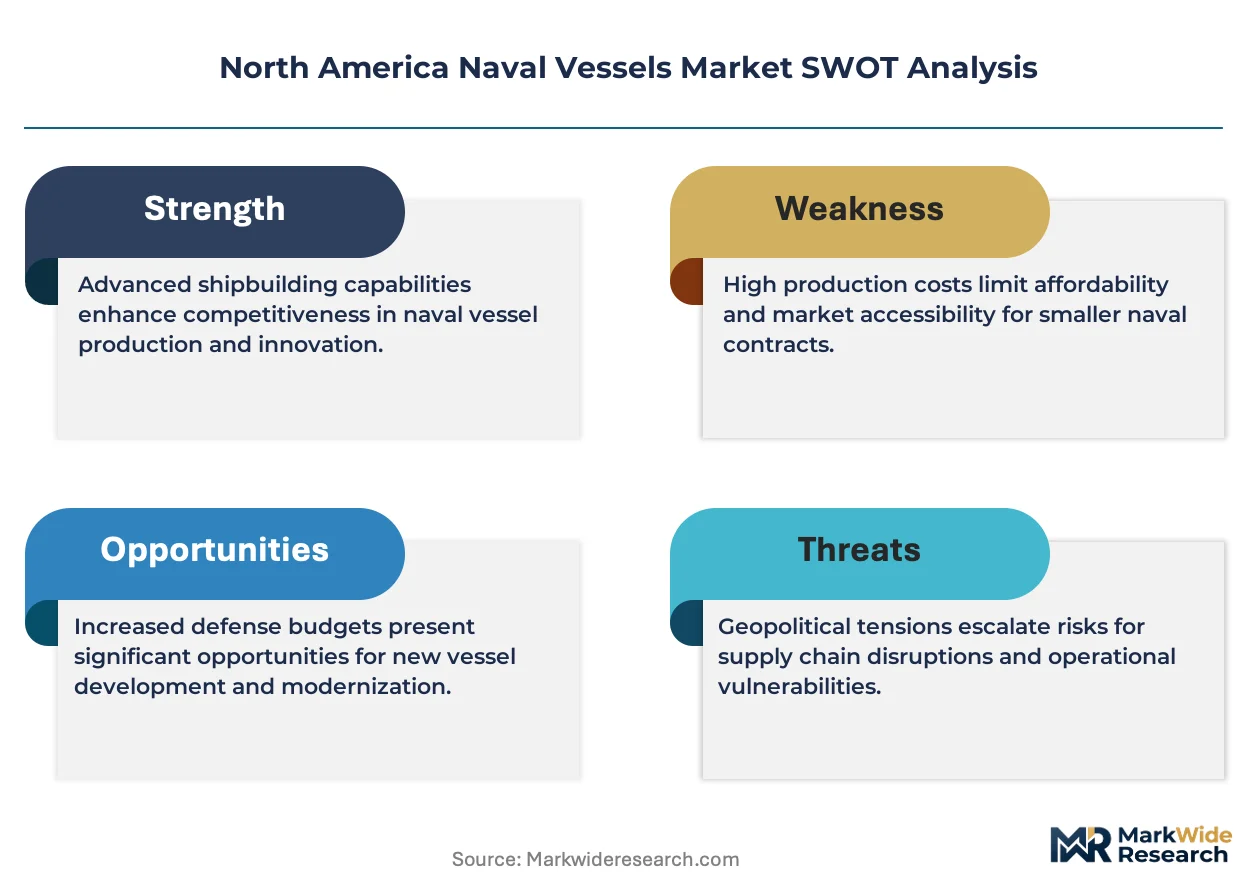
The US Navy's surface fleet recapitalization is compressing yard capacity allocation between nuclear submarine programs and large surface combatant construction, creating a zero-sum competition for skilled labor and drydock space along the Gulf and Atlantic coasts.
Growth Catalysts
- The Jones Act:Domestic sourcing mandates under this statute and the National Defense Authorization Act require US-built hulls for all naval procurement, insulating American shipyards from foreign competition and guaranteeing contract flow.
- Constellation-class frigate acceleration:The US Navy's expanded buy rate for this program is pulling forward steel-cutting schedules at Wisconsin and Alabama facilities, activating dormant construction lines.
- Unmanned surface vessel demand:Autonomous hull programs are creating parallel procurement streams that operate outside traditional manned-shipyard bottlenecks, opening new builder categories.
Market Restraints
- Specialized steel supply concentration:HY-80 and HY-100 high-yield submarine-grade plate production concentrates at a single US mill, creating single-source vulnerability for pressure hull fabrication.
- Nuclear welder certification scarcity:The finite pool of NAVSEA-qualified welders limits simultaneous construction starts for Columbia-class ballistic missile submarines and Virginia-class attack boats.
- Environmental compliance layering:EPA vessel discharge standards and evolving Coast Guard safety mandates are extending engineering review cycles and adding non-recurring design costs to newbuild specifications.
Strategic Opportunities
- Canadian Surface Combatant replacement:Canada's Department of National Defence procurement branch is advancing a 15-ship program with Irving Shipbuilding, creating a secondary demand anchor outside US fiscal cycles.
- Integrated electric propulsion convergence:The merging of advanced permanent magnet motors with solid-state power distribution is enabling smaller engineering crews and reduced machinery space claims in next-generation destroyers.
- Modular block construction standardization:Cross-yard adoption of common structural interfaces and outfitting sequences is allowing hull sections to be built at secondary facilities and transported to final assembly points.
Industry Challenges
- Naval architect pipeline depletion:US maritime engineering programs at MIT, University of Michigan, and Virginia Tech are producing fewer graduates than retirement rates at Electric Boat and Huntington Ingalls, constraining design office capacity.
- American Bureau of Shipping certification backlog:Plan approval queues for novel unmanned hull configurations are extending lead times for first-of-class vessels, delaying revenue recognition for prototype programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Naval Vessels Market |
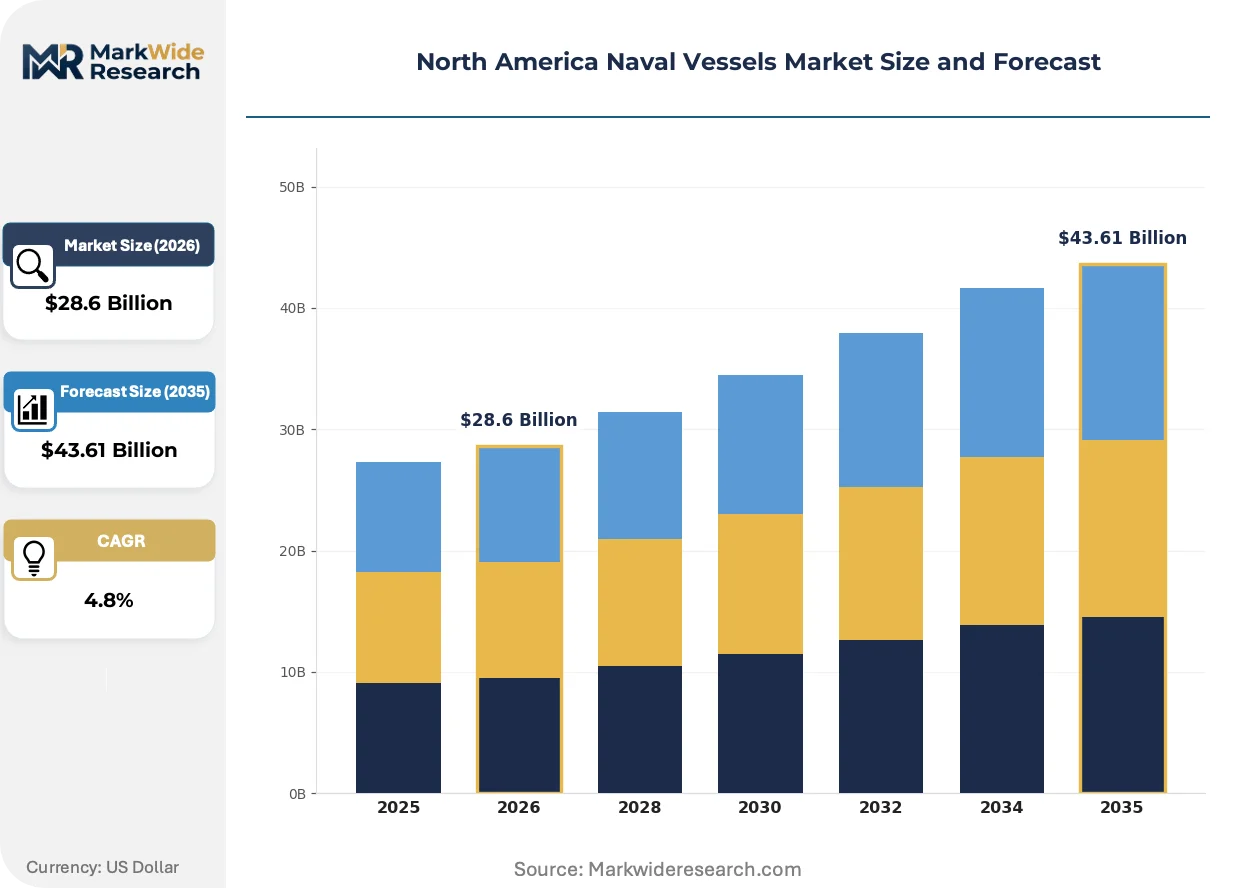
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Frigates, Destroyers, Submarines, Amphibious Assault Ships End User: Naval Forces, Coast Guards, Defense Contractors, Government Agencies Technology: Stealth Systems, Navigation Systems, Combat Management Systems, Communication Systems Size: Large, Medium, Small, Patrol Craft |
| Companies Covered | General Dynamics Corporation, Huntington Ingalls Industries, Lockheed Martin Corporation, Austal USA, Northrop Grumman Corporation, BAE Systems plc, Fincantieri S.p.A., Irving Shipbuilding Inc., Raytheon Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Naval Vessels Market Evolving Landscape
Digital engineering tools and autonomous systems architecture are rewriting hull design workflows and crewing models across North American naval construction, compressing traditional development cycles while expanding operational envelopes.
Integrated electric propulsion is consolidating auxiliary, service, and main propulsion power into unified zonal distribution architectures. The US Navy's DDG(X) next-generation destroyer program is mandating this configuration for all follow-on hulls. This technology consolidation is collapsing the traditional separation between mechanical and electrical engineering disciplines in shipyard hiring.
The National Defense Authorization Act's progressive domestic content thresholds are tightening supply chain localization requirements for major subsystems. Canadian procurement under the Industrial and Technological Benefits policy is mirroring this pressure, mandating in-country value capture for the Surface Combatant program. Frigate and auxiliary hull categories face the steepest compliance adjustments as foreign-sourced combat systems require waivers or replacement.
Fleet readiness contracting is displacing traditional unit procurement as the dominant financial interface between navies and builders. The US Navy's performance-based logistics arrangements with Electric Boat for submarine maintenance are extending into new construction, with fixed-availability payments replacing milestone-based billing. This shift is most visible in Virginia and Washington state, where sustainment workloads now rival production revenue at primary facilities.
North America Naval Vessels Market Segmentation
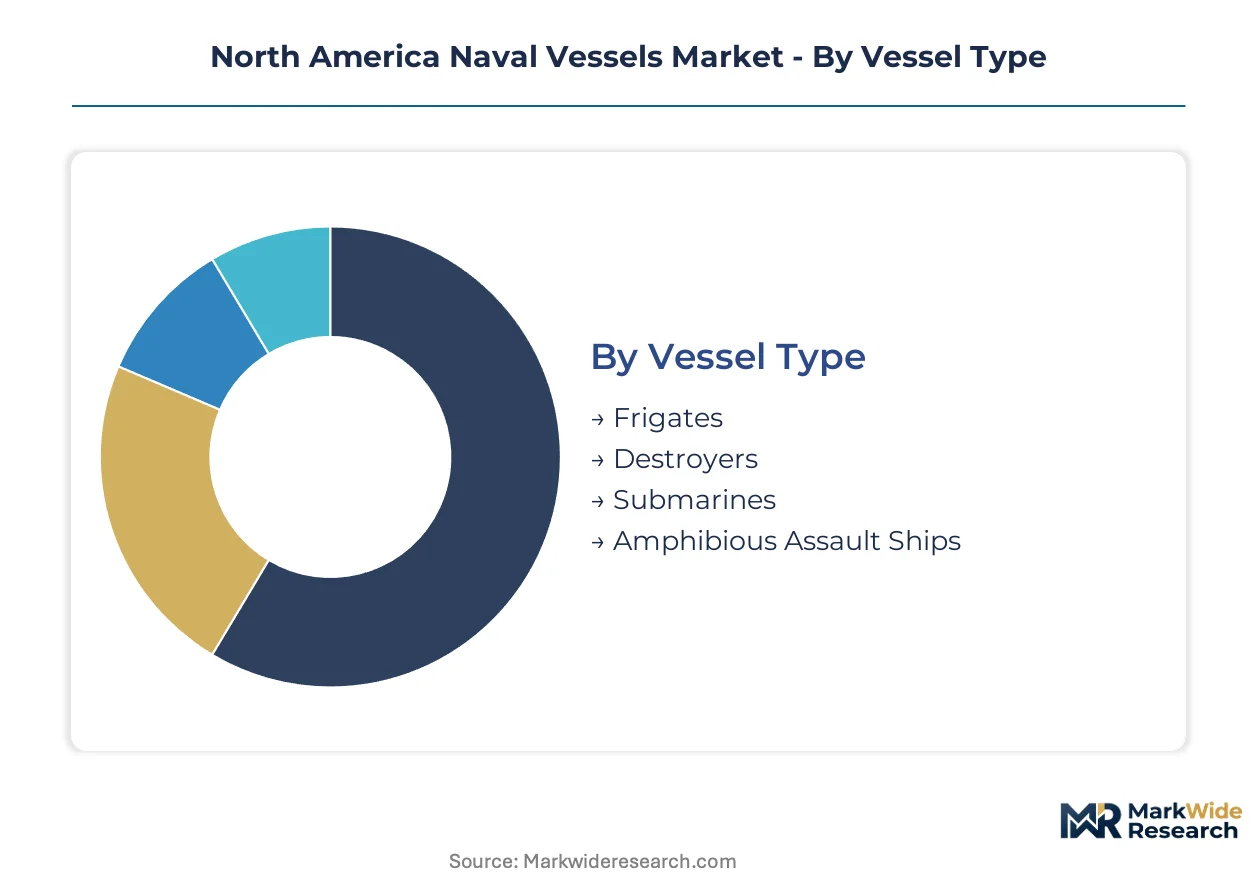
Segmentation of North American naval vessels reveals how procurement concentration, mission requirements, and technology integration shape contract allocation across builder facilities. Understanding these dimensions clarifies where yard capacity, specialized labor pools, and supply chain investments cluster.
Vessel Type:
Supply concentration across US shipyards directly maps to vessel complexity and hull classification, with nuclear-certified facilities commanding distinct procurement queues.
- Submarines:Columbia-class ballistic missile and Virginia-class attack boats require HY-80/100 steel plate and NAVSEA-certified nuclear welders available only at Electric Boat and Newport News. Demand concentrates along the Atlantic seaboard where pressure hull fabrication and reactor compartment integration occur under single-source material constraints.
- Destroyers:Arleigh Burke and forthcoming DDG(X) hulls anchor large surface combatant production at Huntington Ingalls Mississippi facilities and Bath Iron Works, with integrated electric propulsion systems driving engineering crew consolidation and machinery space reduction in next-generation designs.
- Frigates:Constellation-class steel hulls activate construction lines at Wisconsin and Alabama yards outside traditional nuclear-submarine corridors.
- Amphibious Assault Ships:Large-deck LHA/LHD production at Virginia facilities represents mature platform demand facing intergenerational production gaps.
Submarines absorb the bulk of installed capacity; frigates are expanding most quickly.
End User:
Procurement authority distribution determines contract vehicle structures and funding cycle exposure across the builder base.
- Naval Forces:US Navy Naval Sea Systems Command and Canada's Department of National Defence procurement branch govern multi-year shipbuilding plans with congressional or parliamentary appropriation dependencies.
- Defense Contractors:Prime integrators like General Dynamics and Huntington Ingalls serve as construction agents, managing subcontractor tiers for combat systems and platform integration under fixed-price or cost-plus arrangements.
- Coast Guards:National Security Cutter and offshore patrol vessel programs operate under Department of Homeland Security budget lines with distinct mission profiles from blue-water naval requirements.
- Government Agencies:Maritime Administration and research vessel operators procure auxiliary hulls through separate appropriation streams with civilian classification standards.
Naval Forces command the dominant share of contracted tonnage; Coast Guards are gaining procurement velocity through homeland security budget growth.
Technology:
Subsystem integration complexity is reshaping supplier tiers and design office staffing across classification disciplines.
- Combat Management Systems:Aegis baseline configurations and successor architectures consolidate sensor fusion, weapons direction, and networked warfare capabilities into integrated combat information centers requiring specialized software engineering pools.
- Stealth Systems:Radar cross-section reduction through hull shaping, composite superstructures, and signature management treatments adds non-recurring engineering costs and extends plan approval cycles with the American Bureau of Shipping.
- Navigation Systems:GPS-denied positioning and inertial reference platforms support contested-environment operations.
- Communication Systems:Satellite-linked and line-of-sight data links enable distributed maritime operations.
Combat Management Systems represent the most capacity-constrained integration domain; Stealth Systems are climbing the fastest in engineering hour allocation.
Size:
Hull displacement categories determine construction methodology, block transport logistics, and final assembly site selection.
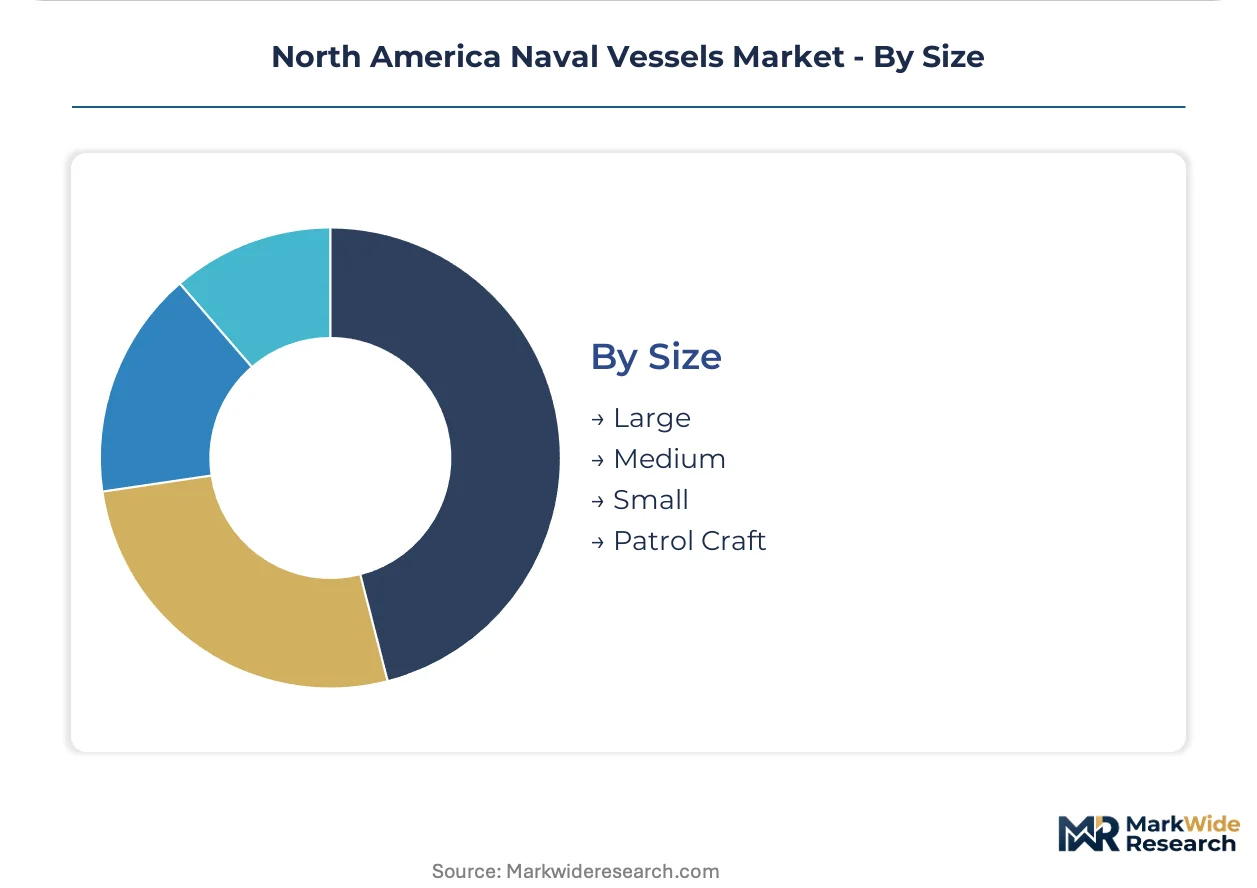
- Large:Aircraft carriers and amphibious assault ships exceeding 40,000 tonnes require drydock availability at Newport News or Huntington Ingalls Virginia facilities, with modular block construction demanding heavy-lift capacity and riverine transport coordination.
- Medium:Destroyers and frigates in the 3,000-10,000 tonne range suit multiple yard configurations, enabling competitive sourcing and production line activation at Bath, Pascagoula, or Marinette facilities.
- Small:Littoral Combat Ships and mine countermeasures vessels below 3,000 tonnes.
- Patrol Craft:Coastal and riverine platforms under 1,000 tonnes.
Large hulls monopolize heavy infrastructure investment; Medium vessels are gaining share fastest through frigate program acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Naval procurement concentrates along the Atlantic and Gulf coasts where submarine-grade steel fabrication and nuclear-certified welding capacity cluster. Congressional appropriations for Columbia-class ballistic missile submarines are compressing yard schedules across multiple states.
United States
Electric Boat in Connecticut and Huntington Ingalls in Virginia anchor nuclear submarine and aircraft carrier construction under NAVSEA oversight. The National Defense Authorization Act mandates domestic hull sourcing through the Jones Act. Gulf Coast facilities in Mississippi and Alabama handle large surface combatants and amphibious assault ships.
Canada
Irving Shipbuilding in Nova Scotia leads the Canadian Surface Combatant program with fifteen hulls planned for delivery to the Royal Canadian Navy. The Industrial and Technological Benefits policy requires in-country value capture for major subsystems. Halifax shipyards are expanding steel-cutting capacity to accommodate accelerated frigate schedules.
Mexico
SEMAR operates naval shipyards at Salina Cruz and Guaymas for patrol craft and coastal defense vessels. The Secretariat of the Navy maintains independent procurement authority for littoral platforms under national security budgets. Pacific coast facilities focus on counter-narcotics interdiction hulls below one thousand tonnes displacement.
North America Naval Vessels Market Competitive Landscape
United States producers anchor one tier; Canadian specialists hold secondary positions in complementary hull categories. The builder base concentrates around nuclear-certified facilities and large-deck construction sites with limited cross-entry. Three archetypes dominate: integrated prime contractors managing multi-hull programs, aluminum-hulled littoral specialists, and foreign-owned subsidiaries operating under domestic content waivers. Capacity expansion and modular block construction partnerships represent the primary competitive vectors as yards compete for skilled labor pools.
Within the integrated prime tier, General Dynamics Corporation and Huntington Ingalls Industries exemplify the capital-intensive model that dominates nuclear and large surface combatant construction. Austal USA occupies a distinct position as the aluminum-hulled specialist competing for independently derived hull programs outside traditional steel yards. These three entities collectively represent the spectrum from nuclear submarine fabrication to littoral platform production across the regional market.
| Leading Market Players |
|---|
| General Dynamics Corporation |
| Huntington Ingalls Industries |
| Lockheed Martin Corporation |
| Austal USA |
| Northrop Grumman Corporation |
| BAE Systems plc |
| Fincantieri S.p.A. |
| Irving Shipbuilding Inc. |
| Raytheon Technologies Corporation |
| Others |
Value Network & Pricing Analysis
Sovereign-backed defense contractors and family-owned shipyard specialists anchor construction capacity across the Atlantic and Gulf coasts, translating congressional appropriation cycles into rigid contract pricing and long-term supply commitments that insulate prime builders from spot-market volatility while compressing margins at subcontractor tiers.
Pricing Analysis
High-volume, low-margin production of standardized hull blocks competes against premium-margin, low-volume nuclear submarine contracts for finite yard capacity. Price differentiation centers on NAVSEA certification grade and steel specification tier, with HY-80/100 submarine-grade plate commanding substantial premiums over conventional naval steel. Cost compression in frigate construction intensifies as Constellation-class acceleration pulls forward fixed-price commitments. Coast Guard procurement offices exhibit highest price sensitivity; Naval Sea Systems Command programs demonstrate lowest sensitivity due to mission-critical specifications.
Supply Chain Analysis
Welder certification scarcity across Connecticut, Virginia, and Mississippi constrains simultaneous construction starts for Columbia-class and Virginia-class hulls, forcing sequential capacity allocation that extends lead times. Geographic supply concentration centers on United States, Canada, and limited Mexican littoral facilities. Raw material dependencies include HY-80/100 steel plate, marine-grade aluminum, and reactor-grade forgings. Single-source vulnerability at the lone domestic HY-80/100 mill creates structural supply risk. Distribution runs through NAVSEA-managed prime contractor networks with tiered subcontractor qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from nuclear welder certification scarcity and single-source steel supply is forcing marginal builders toward joint venture arrangements or exit, concentrating contract awards among NAVSEA-qualified primes with captive fabrication capacity.
For Market Incumbents: Deploy modular block construction partnerships to expand effective capacity without greenfield facility investment. Huntington Ingalls and General Dynamics Electric Boat should deepen captive supply relationships with the sole HY-80/100 mill to preempt competitor access. Secure NAVSEA-certified welder pipelines through apprenticeship partnerships with Virginia Tech and MIT maritime engineering programs to offset demographic retirement waves. For New Entrants and Emerging Players: Digital-channel unmanned surface vessel procurement streams offer the most penetrable entry vector outside traditional manned-shipyard bottlenecks. Target Coast Guard offshore patrol vessel and Maritime Administration auxiliary hull programs where certification requirements remain less stringent than nuclear-submarine standards. Pursue aluminum-hulled littoral platform specialization to compete for independently derived hull awards outside steel-yard queues. For Investors and Strategic Acquirers: Distressed-cycle entries favor second-tier modular construction facilities in Wisconsin and Alabama with Constellation-class frigate program exposure but limited nuclear certification overhead. Long-term viability rests on congressional appropriation continuity for surface fleet recapitalization. Watch Columbia-class ballistic missile submarine budget acceleration as the inflection signal—material production-gap risk between hull generations would trigger capacity reallocation away from surface combatants and compress valuations at exposed facilities.| Strategic Initiative | Industry Significance |
|---|---|
| NAVSEA Welder Certification Pipeline Investment | Electric Boat and Newport News apprenticeship programs secure reactor-grade fabrication capacity against demographic retirement. |
| HY-80/100 Steel Supply Agreement | Long-term offtake contracts with the sole domestic mill eliminate single-source vulnerability for pressure hull programs. |
| Modular Block Construction Partnership | Cross-yard standardization enables secondary facility utilization without greenfield capital deployment. |
| Unmanned Surface Vessel Prototype Development | Autonomous hull programs operate outside traditional shipyard bottlenecks, opening new builder categories. |
| Canadian Surface Combatant Joint Venture | Irving Shipbuilding's 15-hull program creates secondary demand anchor outside US fiscal cycles. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with NAVSEA program executives, shipyard operations directors, classification society surveyors, and congressional defense appropriations staff. Secondary sources included Naval Sea Systems Command budget justifications, Congressional Research Service shipbuilding reports, American Bureau of Shipping plan approval databases, and Department of Defense contract announcement records. Bottom-up hull-by-hull production schedules triangulated against top-down congressional appropriation projections.
Granularity-level modeling addressed vessel type, displacement category, propulsion architecture, and end-user procurement authority across the analysis window. Segment-level CAGRs derived from production-rate assumptions tied to multi-year shipbuilding plans and Congressional Budget Office cost estimates. Industry-specific forecast inputs incorporated Columbia-class acceleration schedules and Constellation-class steel-cutting timelines.
The model holds under sustained congressional defense appropriation continuity; deviation in nuclear welder certification throughput or HY-80/100 mill operational status would shift capacity allocation assumptions. Forecasts reflect documented production schedules and identified supply constraints. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Jack-Up Vessels Market
Marine
Asia-Pacific Leisure Boat Marine Coating Market
Marine
Marine Elevators Market
Marine
Hydrofoil Market
Marine
Singapore Container Transshipment Market
Marine
Rigid Inflatable Boats (RIB) Market
Marine
Marine Suspension Seat Bases Market
Marine
Marine Pipes Market
Marine
Marine Fasteners Market
Marine
Marine Fender Market
Marine
Hydraulic Marine Cranes Market
Marine
Asia-Pacific Electric Boat Market
Marine
LNG Bunkering Vessel Market
Marine
Autonomous Underwater Vehicle (AUV) Market
Marine
Marine Base Steering Gear Market
Marine
Hydrogen Ships Market