
 Ambulance Vehicles Market | 2026-2036
Ambulance Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Ambulance Vehicles Market Insights
Advanced Life Support specification tiers is unwinding legacy procurement patterns across municipal and private ambulance fleets. REV Group leverages its vertical manufacturing footprint to control chassis-to-body build quality for North American emergency services. Daimler AG anchors premium ICU-capable van platforms with integrated electrical architectures that sustain prolonged life-support operations. Ford Motor Company competes on fleet standardization, offering chassis commonality that reduces parts complexity for high-volume EMS operators.
An ambulance vehicle is a medically configured transport unit built on a reinforced chassis with patient compartment climate control, oxygen delivery systems, and electrical capacity for onboard monitoring equipment, designed to move patients while sustaining clinical interventions during transit. Advanced Life Support configurations command premium positioning due to integrated ventilator and defibrillator power requirements, while Patient Transport segments serve stable interfacility transfers with lighter specifications. Diesel propulsion still dominates installed fleet bases, though Hybrid variants are capturing replacement cycle interest where municipalities face emissions mandates.
FDA device-clearance requirements for onboard medical equipment shape ambulance builder design partnerships, while EPA emissions standards filter available chassis platforms for domestic assembly. NHTSA crashworthiness protocols define structural reinforcement thresholds that differentiate certified builders from aftermarket converters. Stakeholders must weigh electrification timelines against rural range constraints and charging infrastructure gaps before committing fleet transition capital.
Market Dynamics
The ambulance vehicle market is experiencing a structural compression between electrification mandates and rural operational constraints, with municipal procurement offices now weighing total cost of ownership against charging infrastructure availability before fleet replacement decisions.
Growth Catalysts
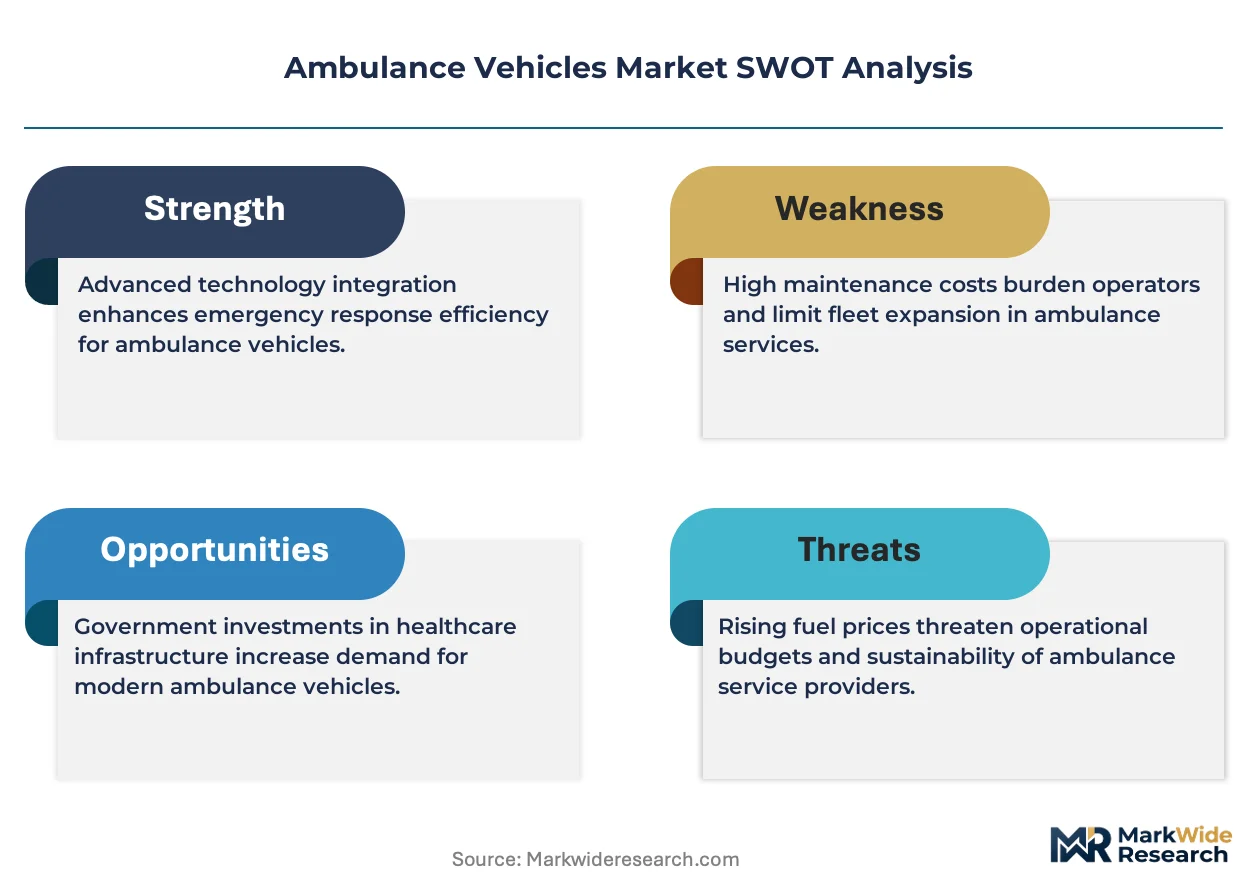
- IRA Clean Vehicle Tax Credits:US municipalities access federal incentives for electric fleet conversions, accelerating budget approvals for zero-emission ambulance acquisitions.
- Advanced Life Support tier migration:Hospital networks demand ICU-capable transport units, expanding specification requirements beyond basic emergency response configurations.
- Hybrid powertrain maturation:Extended range capabilities address range anxiety in suburban and exurban service territories where full electrification remains impractical.
Market Restraints
- Lithium battery supply concentration:Cathode material processing clusters in limited jurisdictions create input cost volatility and geopolitical exposure for domestic chassis assemblers.
- NHTSA structural certification timelines:Crashworthiness validation protocols extend new platform introduction cycles, delaying product refresh schedules.
- Specialized technician scarcity:Dual-competency workforce requirements combining automotive electrical systems with FDA-cleared medical device maintenance constrain service network expansion.
Strategic Opportunities
- Interfacility transfer segment expansion:Aging demographics in Japan and Germany expand non-emergency patient transport contracts with lighter-specification vehicle requirements.
- Vehicle-to-grid integration:Bidirectional charging capabilities position ambulance fleets as mobile emergency power reserves during grid instability events.
- Modular body architecture:Standardized patient compartment designs enable rapid reconfiguration between Advanced Life Support and Patient Transport specifications within single chassis investments.
Industry Challenges
- Cross-certification complexity:Simultaneous EPA emissions compliance, NHTSA crash safety validation, and FDA medical device clearance create multi-agency coordination bottlenecks extending product development timelines.
- Legacy fleet interoperability:Existing maintenance facilities require electrical infrastructure upgrades to service high-voltage hybrid and electric platforms, demanding capital allocation beyond vehicle acquisition budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ambulance Vehicles Market |
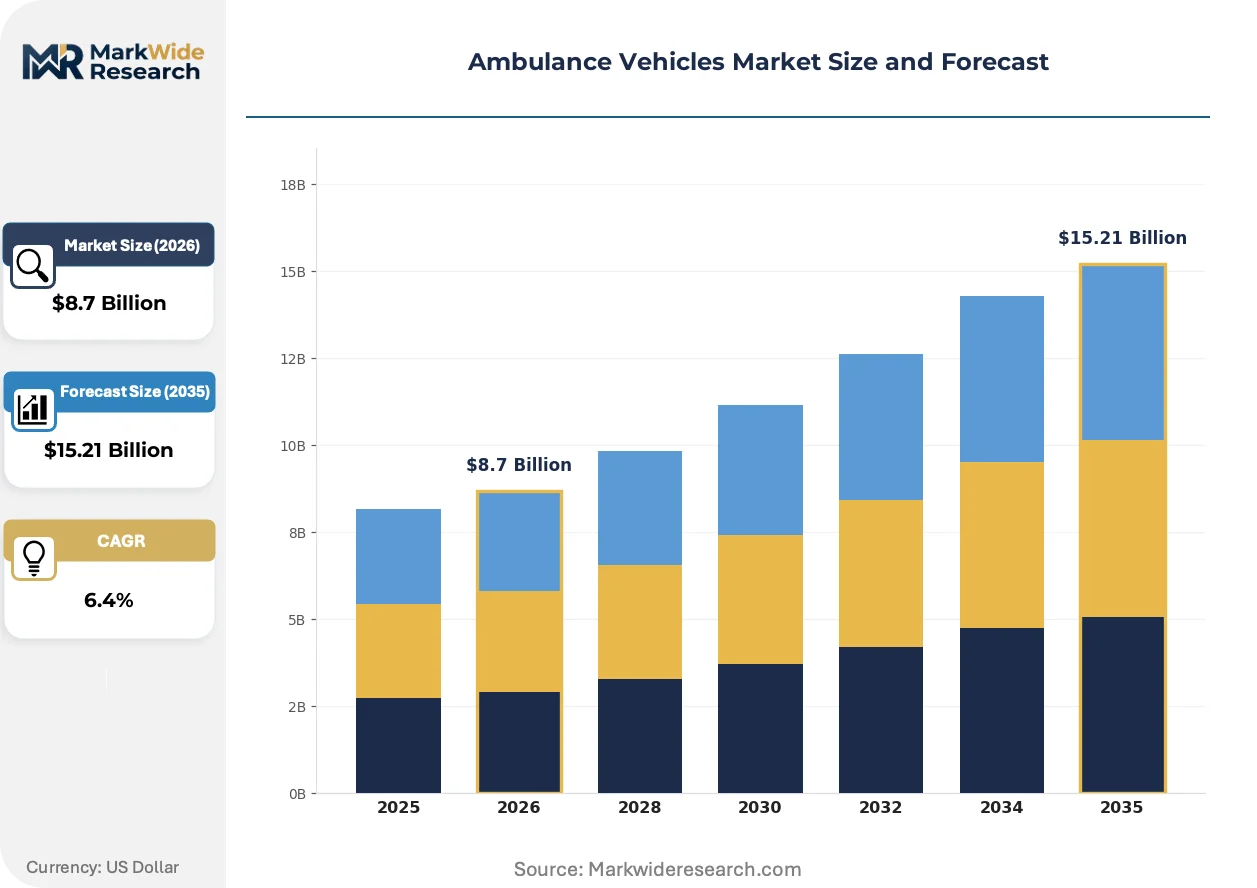
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Basic Life Support, Advanced Life Support, Patient Transport, Mobile Intensive Care, Rapid Response Propulsion: Diesel, Electric, Hybrid, Gasoline, Hydrogen Fuel Cell End User: Emergency Medical Services, Fire Departments, Private Operators, Military Medical Units, Disaster Response Teams Application: Emergency Response, Patient Transfer, Disaster Management, Event Medical Coverage, Non-Emergency Transportation |
| Companies Covered | REV Group, Inc., Daimler AG (Mercedes-Benz), Ford Motor Company, Toyota Motor Corporation, Tata Motors Limited, Babcock International Group PLC, Air Methods Corporation, Falck A/S, Braun Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ambulance Vehicles Market Trends and Innovations
Propulsion architecture decisions now precede chassis selection in municipal procurement workflows, reversing traditional specification sequences where body configuration drove platform choices.
Modular battery-electric drivetrain packages are decomposing the integrated powertrain procurement model that long tied ambulance builders to specific chassis manufacturers. Municipal fleet managers in California and New York pilot swappable battery configurations that extend operational range without permanent platform commitment. This flexibility is compressing long-term supplier relationships and enabling multi-source chassis strategies previously impractical under conventional diesel supply arrangements.
EPA Phase 3 greenhouse gas standards for heavy-duty vehicles tighten emissions thresholds for Class 3-5 chassis platforms commonly deployed in Type II ambulance configurations. The regulation forces chassis suppliers to accelerate hybrid powertrain availability or risk exclusion from municipal bid pools. Private EMS operators in Texas and Florida now specify hybrid-ready electrical architectures even where full electrification remains years distant, preserving future compliance optionality.
Fleet standardization preferences among multi-jurisdiction health systems are consolidating purchasing authority previously dispersed across individual municipalities. Regional hospital networks in the United Kingdom and Australia now negotiate enterprise-level vehicle contracts that override local procurement autonomy. This concentration shifts negotiating leverage toward volume buyers and compressing margins for builders dependent on fragmented municipal sales channels.
Ambulance Vehicles Market Segmentation
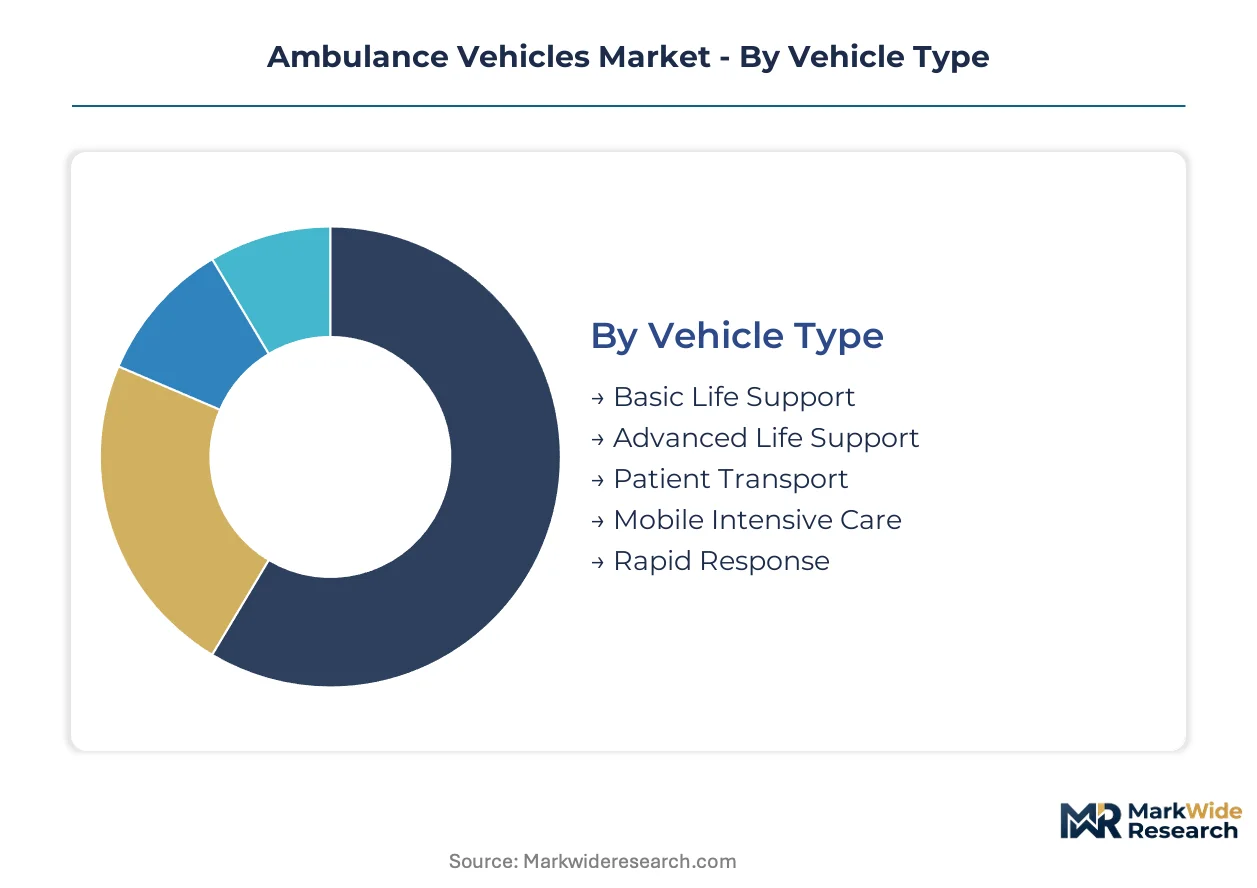
Segmentation in ambulance vehicles reflects divergent regulatory thresholds across patient acuity levels and propulsion architectures. Procurement patterns fragment along emergency capability tiers, with certification requirements from FDA, EPA, and NHTSA filtering available configurations for each use case.
Vehicle Type:
FDA device-clearance requirements and NHTSA crashworthiness protocols create distinct certification burdens across emergency capability tiers, with Advanced Life Support configurations demanding integrated electrical architectures that Basic Life Support units avoid.
- Advanced Life Support:ICU-capable configurations integrate ventilator power systems, defibrillator mounts, and sustained climate control for critical patient interventions during transit. Hospital networks in the United States concentrate procurement authority here, with federal emergency preparedness funding accelerating fleet upgrades to this specification tier.
- Basic Life Support:Standard emergency response units carry oxygen delivery and basic monitoring without sustained power-intensive interventions. Municipal EMS operators in suburban and exurban territories favor this tier where call volumes do not justify ALS capital commitments and technician training costs.
- Patient Transport:Interfacility transfer vehicles with lighter specifications serve stable patients between hospitals and long-term care facilities.
- Mobile Intensive Care:Neonatal and specialized critical care platforms with isolated climate zones and dedicated equipment racks.
- Rapid Response:Compact units prioritizing speed over patient compartment capacity for first-responder deployment.
Established volume favors Basic Life Support; emerging adoption favors Advanced Life Support.
Propulsion:
Cost tier stratification separates mature diesel infrastructure from electrification capital requirements, with hybrid architectures capturing intermediate positions where charging gaps persist.
- Diesel:Dominates installed fleet bases with proven range, rapid refueling, and established maintenance networks across rural service territories. EPA Phase 3 greenhouse gas standards now pressure this segment, with California and New York municipalities already excluding pure diesel platforms from bid pools.
- Hybrid:Combines electric drive with range-extending combustion, addressing emissions mandates while preserving operational flexibility. Suburban EMS operators in Texas and Florida specify hybrid-ready electrical architectures to preserve future compliance optionality without full electrification commitment.
- Electric:Zero-emission platforms constrained by charging infrastructure availability and battery supply concentration risks.
- Gasoline:Limited to light-duty Type II configurations where capital constraints override efficiency considerations.
- Hydrogen Fuel Cell:Emerging alternative for heavy-duty applications requiring rapid refueling without battery weight penalties.
Diesel retains dominant share; hybrid platforms are expanding most quickly where electrification timelines remain uncertain.
End User:
Customer type determines specification authority concentration, with fragmented municipal procurement giving way to consolidated health system contracting.
- Emergency Medical Services:Dedicated ambulance services operating under municipal contracts or regional health authority agreements, representing the core volume base with standardized fleet replacement cycles.
- Private Operators:For-profit transport companies competing on interfacility transfer contracts and event medical coverage, with lighter specification requirements and faster asset turnover.
- Fire Departments:Cross-trained emergency response integrating fire suppression and medical transport capabilities.
- Military Medical Units:Theater evacuation and field hospital platforms with ruggedized specifications and NATO interoperability requirements.
- Disaster Response Teams:Federal and state emergency management assets deployed for mass casualty events and natural disaster mobilization.
Public EMS commands procurement volume; private operators are gaining share fastest in non-emergency segments.
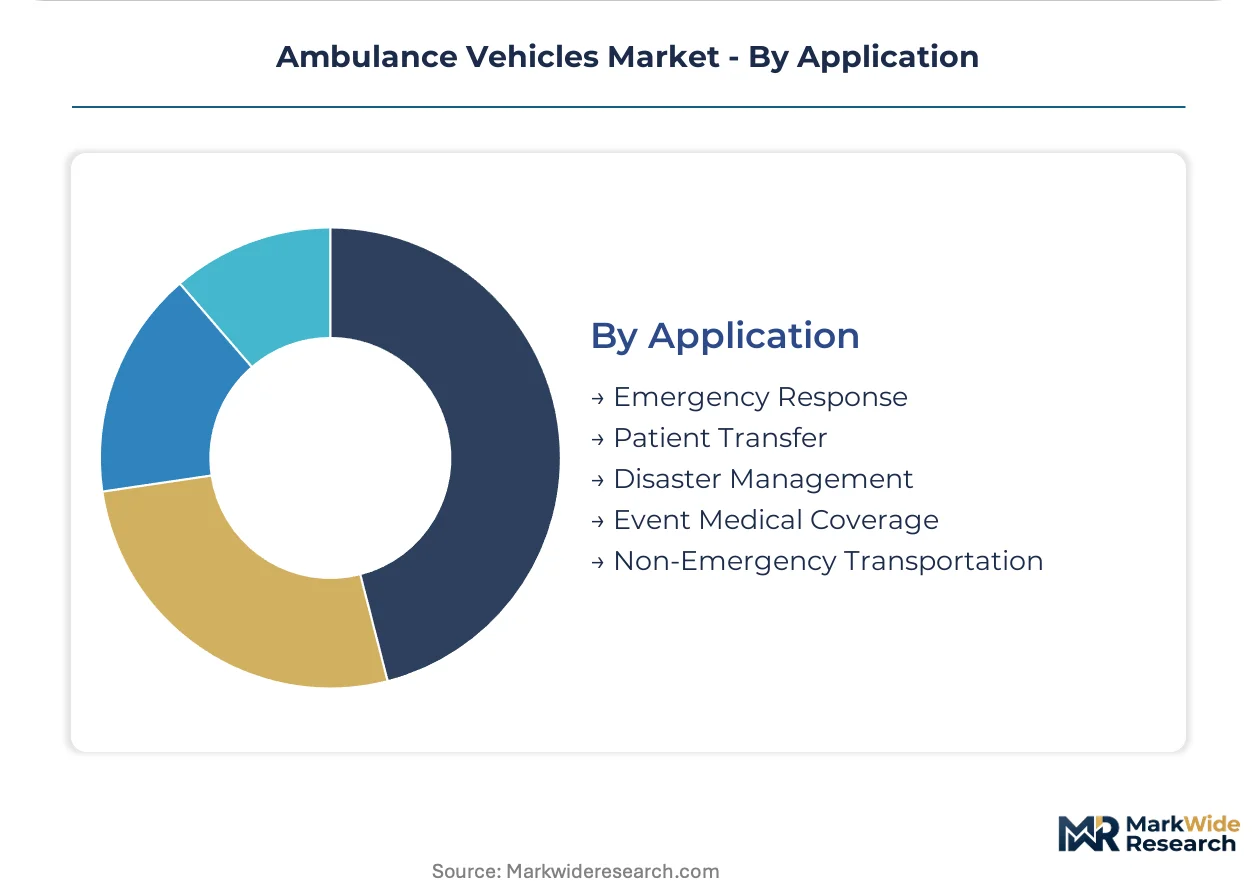
Application:
Margin structure varies sharply between emergency response urgency premiums and scheduled transfer efficiency requirements.
- Emergency Response:Time-critical deployment with full ALS capabilities, commanding highest per-mile reimbursement rates and justifying premium vehicle specifications.
- Patient Transfer:Scheduled interfacility movements with stable patients, where lighter BLS configurations and optimized routing drive unit economics.
- Disaster Management:Surge capacity deployment requiring modular body architectures for rapid reconfiguration between patient transport and mobile treatment.
- Event Medical Coverage:Temporary standby services for sporting events and mass gatherings with rapid-response specifications.
- Non-Emergency Transportation:Dialysis, chemotherapy, and routine medical appointments with wheelchair accessibility requirements.
Emergency Response generates premium pricing; Patient Transfer offers volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chassis manufacturing concentrates in Germany, the United States, and Japan, with body builders clustering near Detroit, Stuttgart, and Nagoya to minimize logistics costs for final assembly. Municipal procurement patterns diverge sharply between emission-mandated coastal markets and range-dependent interior territories.
United States
Federal emergency preparedness funding and aging fleet replacement cycles drive municipal contract awards across California, Texas, and New York. The IRA Clean Vehicle Tax Credits accelerate budget approvals for zero-emission acquisitions in coastal municipalities. Detroit-based chassis suppliers coordinate with regional body builders in Michigan and Ohio to fulfill multi-state health system contracts.
Germany
ICU-capable transport specifications from hospital networks in Bavaria and North Rhine-Westphalia expand Advanced Life Support procurement volumes. The EU Green Deal emissions targets pressure municipal operators in Berlin and Hamburg toward hybrid platform adoption. Stuttgart anchors premium van platform manufacturing with integrated electrical architectures for prolonged life-support operations.
Japan
Aging demographics in Tokyo, Osaka, and Fukuoka expand non-emergency patient transport contracts with lighter-specification vehicle requirements. METI efficiency standards shape propulsion choices for municipal fleets in the Kanto region. Nagoya-based automotive suppliers coordinate chassis-to-body integration for domestic emergency services and export markets.
United Kingdom
NHS consolidation of purchasing authority across regional hospital networks in London, Manchester, and Birmingham compresses margins for builders dependent on fragmented municipal sales channels. The UK's net-zero fleet targets accelerate hybrid specification in urban ambulance services. West Midlands manufacturing clusters serve both domestic replacement cycles and export demand from Commonwealth health systems.
India
Private EMS operators in Maharashtra, Karnataka, and Tamil Nadu compete on interfacility transfer contracts with capital-constrained Basic Life Support configurations. BIS certification requirements for onboard medical equipment filter available chassis platforms for domestic assembly. Tata Motors anchors volume production in Pune and Jamshedpur for both government tenders and private fleet operators.
Ambulance Vehicles Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated chassis-body builders competing against specialized converters on certification speed and specification flexibility. The vendor base stratifies across three tiers: premium ICU-capable platform specialists, mid-market fleet standardization providers, and regional cost-optimized assemblers. Dominant competitive moves include backward integration into chassis supply and modular body architecture development to enable rapid reconfiguration between specification tiers.
Among North American integrated manufacturers, REV Group exemplifies the vertically controlled production archetype, while Ford Motor Company anchors fleet standardization strategies for high-volume EMS operators. Daimler AG occupies the premium-tier position for ICU-capable van platforms with sustained power architectures. These three players represent divergent strategic bets on electrification timing, specification complexity, and customer concentration.
| Leading Market Players |
|---|
| REV Group, Inc. |
| Daimler AG (Mercedes-Benz) |
| Ford Motor Company |
| Toyota Motor Corporation |
| Tata Motors Limited |
| Babcock International Group PLC |
| Air Methods Corporation |
| Falck A/S |
| Braun Industries |
| Others |
Pricing and Supply Chain Analysis
NHTSA crashworthiness certification gates both supplier qualification and price differentiation simultaneously, with only certified builders commanding ALS premiums while aftermarket converters compete at thinner margins in the BLS tier. This regulatory filter compresses pricing power at the low end while sustaining premium capture for ICU-capable platforms with integrated electrical architectures.
Pricing Analysis
FDA device-clearance requirements dictate the pricing tier structure across the ambulance vehicle market, separating premium ALS configurations with sustained power systems from standard BLS units with basic monitoring capabilities. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with hospital networks showing lowest price sensitivity for ICU-capable transport while municipal EMS operators in capital-constrained jurisdictions drive cost compression in the BLS segment. Pricing pressure stems from hybrid powertrain maturation as suburban operators demand future-proofed electrical architectures without full electrification premiums.
Supply Chain Analysis
Lithium cathode processing concentration in China and South Korea creates a chokepoint that underwrites input cost volatility for domestic chassis assemblers pursuing electrification roadmaps. Chassis manufacturing draws from Germany, the United States, and Japan, with body builders clustering near Detroit, Stuttgart, and Nagoya to minimize logistics costs for final assembly. Single-source vulnerability in battery supply chains threatens production schedules for hybrid and electric platform rollouts. Distribution runs through regional health system procurement offices consolidating previously fragmented municipal purchasing authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from FDA-cleared medical device maintenance contracts and fleet management software subscriptions is expanding faster than hardware sales, repositioning ambulance builders as recurring-revenue platforms rather than transactional equipment vendors.
For Market Incumbents: Fortify chassis supply security through backward integration into electrical architecture production or captive battery supply agreements, as lithium processing concentration threatens production continuity for hybrid platform rollouts. Deepen certification moats by accelerating NHTSA validation pipelines for modular body designs that enable rapid reconfiguration between ALS and Patient Transport specifications within single chassis investments. For New Entrants and Emerging Players: Anchor in India's private EMS operator segment, where capital-constrained Basic Life Support configurations face limited competition from integrated global manufacturers and BIS certification requirements filter out unqualified converters. Target interfacility transfer contracts in Japan's aging demographic corridors with lighter-specification vehicles optimized for non-emergency patient transport economics and METI efficiency compliance. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electric and hybrid ambulance sub-segments as charging infrastructure requirements and battery supply security demands reshape fleet procurement economics. Acquisition candidates with established NHTSA certification pipelines and existing service network density offer superior long-term viability against pure manufacturing plays. Monitor EPA Phase 3 implementation timelines as the critical signal for electrification commitment inflection across municipal bid pools.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Body Architecture Development | Enables rapid reconfiguration between ALS and BLS specifications within single chassis investments. |
| Battery Supply Agreement | Secures cathode material access against geopolitical exposure and input cost volatility. |
| Vehicle-to-Grid Integration Partnership | Positions ambulance fleets as mobile emergency power reserves during grid instability events. |
| FDA Submission for Onboard Device Clearance | Accelerates design partnerships with medical equipment manufacturers for ALS configurations. |
| Health System Enterprise Contract | Captures volume concentration as regional hospital networks override local procurement autonomy. |
Research Methodology
Operator-level perspectives from municipal EMS fleet managers, hospital procurement committees, private ambulance service owners, and NHTSA certification engineers anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from EPA emissions filings, FDA device-clearance databases, and hospital GPO contract records. Bottom-up unit economics modeling triangulated against top-down health system expenditure tracking across the analysis window.
Sensitivity analysis framed the forecast framework, testing electrification adoption curves against charging infrastructure buildout assumptions and battery supply concentration risks. Segmentation dimensions modeled include vehicle type tier, propulsion architecture, end-user concentration, and application urgency premium across the projection horizon. CAGRs derived from replacement cycle timing, federal funding authorization patterns, and emissions mandate compliance deadlines without year-specific anchoring.
Material uncertainties — lithium supply disruptions, NHTSA certification timeline extensions, and municipal budget authorization delays — sit outside the modeled envelope. Forecasts reflect assumptions about hybrid powertrain cost parity achievement and health system procurement consolidation trajectories. Practitioners should keep alternative scenarios live as EPA Phase 3 implementation schedules and IRA credit renewal negotiations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Bicycle Frames Market
Vehicle Components
Automotive Exhaust Gas Sensor Market
Vehicle Components
Fuel Sensor Market
Vehicle Components
Global Fuel Tank and Delivery System Market
Vehicle Components
Russia Automotive Composites Market
Vehicle Components
Exhaust Manifolds and Downpipes Market
Vehicle Components
Bicycle Bottom Bracket Market
Vehicle Components
High Security Registration Plates Market
Vehicle Components
Rail Wheel and Axle Market
Vehicle Components
Mining Vehicle AC Kits Market
Vehicle Components
Piston Market
Vehicle Components
High Precision Heavy Load Bearings Market
Vehicle Components
Global Automotive Battery Sensor Market
Vehicle Components
Trailer Brake Controllers Market
Vehicle Components
Railway Vehicle Coupler Market
Vehicle Components
Driveline Systems for Electric Vehicle Market