
 Exhaust Manifolds and Downpipes Market | 2026-2036
Exhaust Manifolds and Downpipes Market Size, Share, and Industry Trends Forecast 2026-2036
Exhaust Manifolds and Downpipes Market Insights
Stainless steel specification upgrades across OEM supply tiers is unwinding legacy cast iron procurement patterns. Tenneco leverages integrated exhaust system engineering to anchor North American passenger vehicle programs. FORVIA sustains dual-material expertise across cast and tubular architectures. Eberspächer Group specializes in thermal management integration that differentiates its manifold-downpipe module offerings.
Exhaust manifolds and downpipes are pressure-boundary components that collect combustion gases from engine cylinder heads and channel them through catalytic aftertreatment systems, typically fabricated from ferritic stainless steel grades or SiMo cast iron to withstand cyclic temperatures exceeding 900°C and thermal fatigue loads. Their primary purpose is to optimize exhaust gas scavenging efficiency while maintaining structural integrity under corrosive high-thermal-gradient operating conditions. Stainless steel manifolds command premium positioning in passenger vehicle OEM supply channels where weight reduction and thermal responsiveness justify material cost deltas against cast iron alternatives. Performance Vehicles and Commercial Trucks represent contrasting demand poles, with the former driving ceramic coated downpipe uptake for thermal retention and the latter sustaining mild steel volume through cost-sensitive fleet replacement cycles.
EPA tailpipe standards and Euro 7 proposals from the European Commission are tightening permissible NOx and particulate thresholds, forcing manifold-downpipe designs toward integrated close-coupled catalyst positioning and reduced thermal mass configurations. China's MIIT fuel consumption mandates and NMPA vehicle certification protocols are accelerating domestic supplier qualification requirements for stainless steel exhaust architectures. Stakeholders must monitor regulatory divergence between EPA, Euro 7, and GB standards as compliance-driven material specifications reshape sourcing geography and manufacturing investment priorities.
Market Dynamics
EPA and Euro 7 emissions benchmarks are compressing allowable exhaust backpressure thresholds, forcing passenger vehicle OEMs to abandon legacy cast iron manifold procurement in favor of stainless steel assemblies that deliver superior thermal responsiveness and weight reduction.
Growth Catalysts
- EPA tailpipe standards:Tightening NOx and particulate thresholds in the United States mandate integrated close-coupled catalyst positioning, driving demand for reduced thermal mass manifold configurations.
- Passenger vehicle OEMs:Procurement teams across Germany, China, and the United States are expanding stainless steel manifold assembly orders to meet fuel efficiency and emissions compliance simultaneously.
- Ceramic coating technology:Performance vehicle manufacturers are adopting thermal retention coatings on downpipes to optimize exhaust gas scavenging efficiency at sustained high operating temperatures.
Market Restraints
- Nickel and chromium price volatility:Ferritic stainless steel feedstock costs fluctuate with commodity markets, compressing margin structures for tier-1 suppliers locked into long-term OEM pricing agreements.
- Regional supply concentration:Domestic tier-1 suppliers in Germany, China, and the United States anchor regional supply chains, creating geographic vulnerability to localized production disruptions or trade friction.
- Mild steel substitution in commercial fleets:Cost-sensitive commercial truck replacement cycles sustain demand for lower-grade materials that undercut stainless steel penetration in heavy-duty segments.
Strategic Opportunities
- China MIIT fuel consumption mandates:Domestic supplier qualification requirements for stainless steel exhaust architectures are accelerating, opening procurement channels for certified manufacturers.
- Thermal management integration:Convergence of manifold-downpipe modules with active thermal control systems creates premium positioning for suppliers with systems engineering capabilities.
- Aftermarket ceramic coating services:Performance vehicle owners in the United States are pursuing retrofit thermal retention upgrades outside OEM channels, expanding addressable service revenue.
Industry Challenges
- Welding automation skill gaps:Ferritic stainless steel manifold fabrication requires specialized orbital welding expertise that outpaces current vocational training pipeline output in manufacturing regions.
- Euro 7 certification timelines:Proposed European Commission particulate standards remain in regulatory consultation, delaying R&D lock decisions and freezing capital allocation for new platform development.
- Legacy cast iron integration:OEMs maintaining dual-material supply chains face complexity costs from incompatible thermal expansion coefficients between cast iron and stainless steel interface points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Exhaust Manifolds and Downpipes Market |
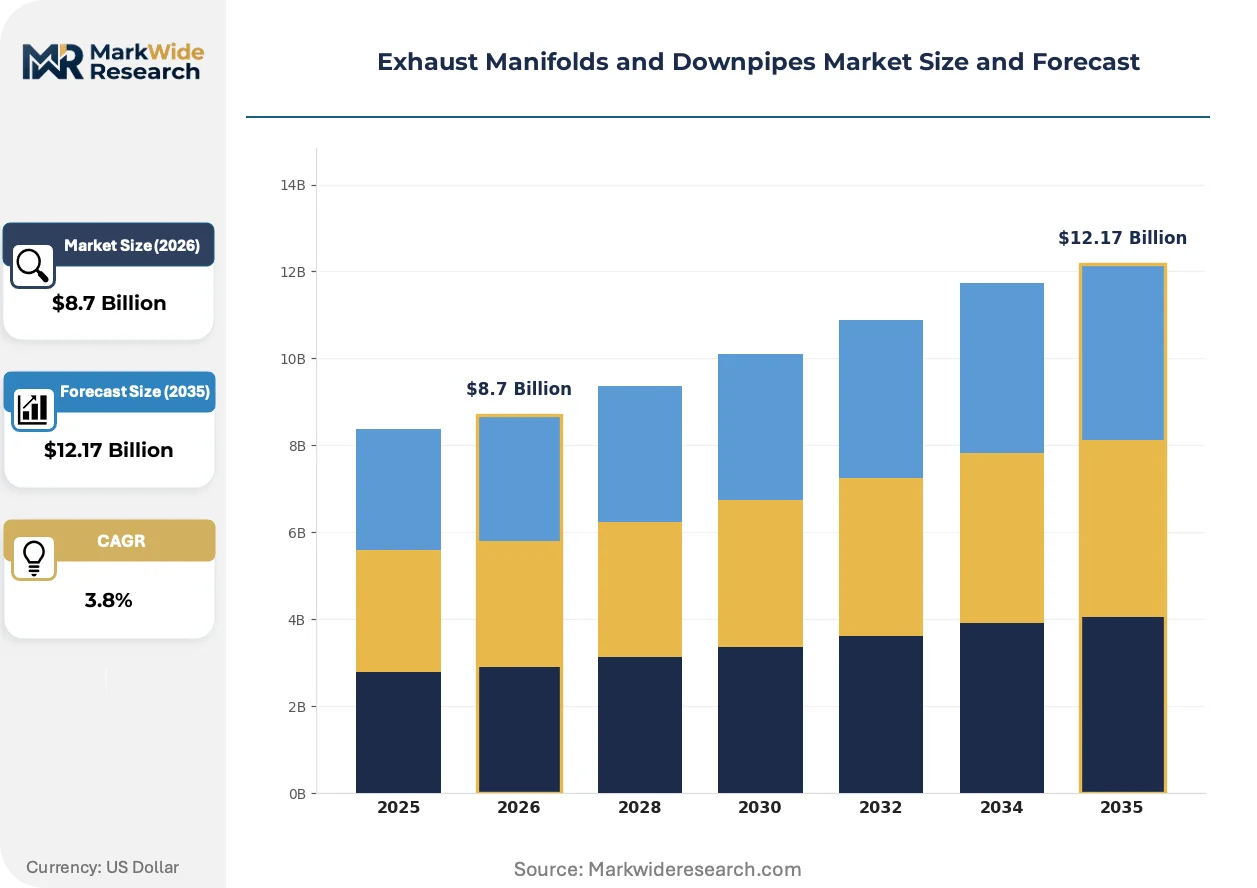
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cast Iron Manifolds, Stainless Steel Manifolds, Ceramic Coated Downpipes, Mild Steel Downpipes, Composite Manifolds Application: Passenger Vehicles, Commercial Trucks, Motorcycles, Performance Vehicles, Off-Road Vehicles Manufacturing Stage: OEM Supply, Aftermarket Parts, Remanufactured Components, Custom Fabrication Distribution Channel: Automotive Dealerships, Auto Parts Retailers, E-commerce Platforms, Specialty Garages |
| Companies Covered | Tenneco, FORVIA, Eberspächer Group, Bosal, Benteler International, Friedrich Boysen, Sejong Industrial, SANGO, Dinex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Exhaust Manifolds and Downpipes Market Trends and Innovations
Material substitution and regulatory compression are actively reshaping exhaust system engineering priorities, with thermal performance optimization displacing cost-centric procurement as the dominant design criterion across passenger vehicle programs.
Thin-wall ferritic stainless steel grades are displacing conventional cast iron architectures in manifold fabrication. Passenger vehicle OEMs in Germany and the United States are accelerating adoption for weight reduction and faster light-off times. This material transition is displacing legacy foundry supply relationships and compressing procurement timelines toward just-in-sequence delivery models.
Euro 7 proposals from the European Commission mandate stricter particulate number limits and expanded real-driving emissions testing. These requirements force manifold-downpipe designs toward integrated sensor ports and reduced thermal mass configurations. Passenger vehicle platforms targeting 2027 compliance deadlines are most affected, with engineering teams prioritizing close-coupled catalyst positioning over underfloor alternatives.
Buyer concentration among mega-platform OEMs is consolidating supplier qualification lists to reduce validation overhead. Tier-1 exhaust system integrators are displacing standalone manifold specialists from new vehicle program awards. This consolidation is most visible in China, where MIIT certification protocols favor suppliers with full-system integration capabilities over component-only manufacturers.
Exhaust Manifolds and Downpipes Market Segmentation
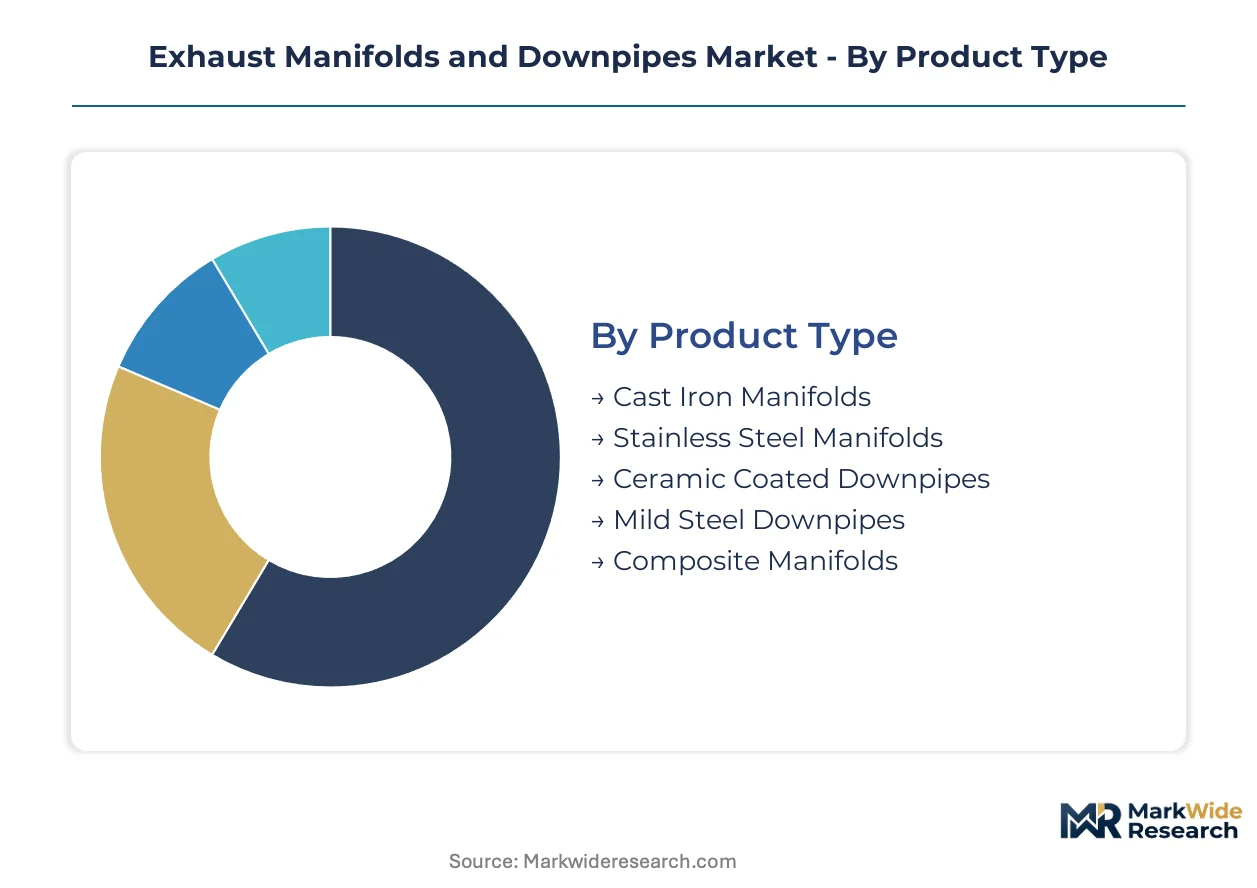
Segmentation in exhaust manifolds and downpipes reveals divergent material strategies across vehicle platforms and procurement channels. Each dimension—product type, application, manufacturing stage, and distribution—carries distinct margin profiles and regulatory exposure that reshape supplier positioning.
Product Type:
Geographic demand patterns split sharply: stainless steel variants concentrate in Germany, China, and the United States where OEMs face tightening EPA and Euro 7 backpressure mandates, while cast iron and mild steel sustain volume in cost-sensitive domestic fleet markets.
- Cast Iron Manifolds:SiMo alloy grades withstand cyclic thermal loads exceeding 900°C in heavy-duty commercial applications. Demand clusters in North American and Chinese commercial truck replacement cycles where fleet operators prioritize unit cost over weight reduction.
- Stainless Steel Manifolds:Thin-wall ferritic grades deliver faster catalyst light-off and 30-40% weight reduction versus cast iron. Procurement concentrates in German and U.S. passenger vehicle OEM supply chains where Euro 7 and EPA timelines compress thermal mass requirements.
- Ceramic Coated Downpipes:Thermal barrier coatings optimize exhaust gas velocity for performance applications. U.S. specialty builders and German tuning segments drive specification.
- Mild Steel Downpipes:Lower-grade material sustains aftermarket volume in price-sensitive commercial fleet maintenance. Regional production in China and India serves domestic replacement demand.
- Composite Manifolds:Emerging polymer-ceramic hybrid architectures target niche weight-critical platforms. Limited qualification among tier-1 suppliers constrains near-term penetration.
Stainless steel manifolds hold the largest share; momentum sits with ceramic coated downpipes.
Application:
Volume distribution tracks divergent compliance timelines: passenger vehicle platforms absorb engineering change costs for Euro 7 readiness, while commercial segments defer material upgrades across extended replacement cycles.
- Passenger Vehicles:OEMs in Germany, China, and the United States anchor stainless steel manifold procurement. EPA tailpipe standards and MIIT fuel consumption mandates force close-coupled catalyst integration.
- Commercial Trucks:Fleet operators in North America and China sustain mild steel and cast iron volume. Cost-per-mile calculations override thermal efficiency gains in replacement part selection.
- Motorcycles:Compact packaging constraints favor tubular stainless architectures. Japanese and Indian OEMs drive specification for emissions-compliant small-displacement engines.
- Performance Vehicles:Thermal retention engineering commands premium positioning. U.S. and German aftermarket channels absorb ceramic-coated downpipe uptake.
- Off-Road Vehicles:Durability requirements under corrosive operating conditions sustain SiMo cast iron. Agricultural and construction equipment OEMs in the United States and Brazil anchor demand.
Passenger vehicles dominate volume; performance vehicles are climbing the fastest.
Manufacturing Stage:
Margin concentration shifts upstream as OEM supply chains consolidate around full-system integrators, while aftermarket and custom channels fragment across regional fabrication networks.
- OEM Supply:Tier-1 exhaust system integrators in Germany, China, and the United States capture platform-level awards. Qualification protocols favor suppliers with thermal management integration capabilities.
- Aftermarket Parts:Independent distributors and auto parts retailers serve replacement demand. Price competition from Chinese manufacturers compresses margin structures in North American and European channels.
- Remanufactured Components:Circular economy mandates in the European Union and selective U.S. state programs stimulate core recovery. Limited standardization constrains scale.
- Custom Fabrication:Specialty garages and performance shops in the United States and Germany produce batch-quantity tubular assemblies. Labor-intensive welding processes limit throughput.
OEM supply holds the largest share; custom fabrication is expanding most quickly.
Distribution Channel:
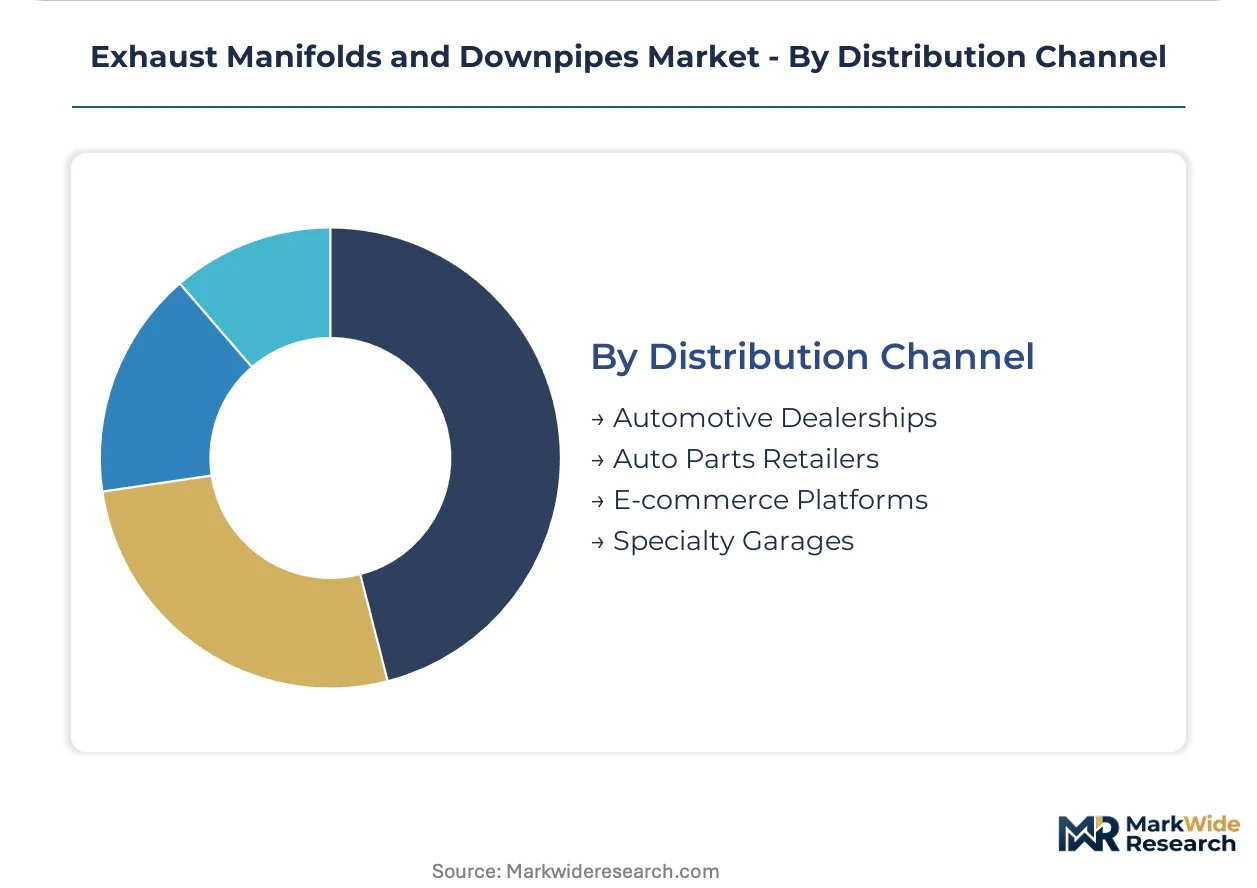
Channel economics reflect customer acquisition cost divergence: dealerships capture warranty-driven replacement, while e-commerce platforms erode traditional auto parts retailer margins in non-urgent maintenance.
- Automotive Dealerships:Authorized service networks handle warranty-related manifold replacements. OEM captive parts pricing sustains premium positioning.
- Auto Parts Retailers:National chains in the United States and Europe stock fast-moving SKUs for commercial fleet maintenance. Inventory carrying costs pressure working capital.
- E-commerce Platforms:Cross-border sales from Chinese suppliers penetrate price-sensitive DIY segments. Shipping logistics for bulky exhaust components constrain conversion rates.
- Specialty Garages:Performance-focused installers in Germany and the United States specify ceramic-coated downpipes. Technical consultation requirements sustain service revenue attachment.
Automotive dealerships hold the largest share; e-commerce platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stainless steel manifold fabrication clusters in Germany, China, and the United States, where EPA and Euro 7 compliance timelines compress procurement cycles. Tier-1 suppliers anchor regional supply chains around regulatory pressure points.
United States
EPA tailpipe standards tighten allowable exhaust backpressure thresholds for passenger vehicle OEMs. The agency's NOx and particulate mandates force close-coupled catalyst integration. Detroit-area automotive clusters concentrate stainless steel procurement decisions for domestic platform engineering.
Germany
Passenger vehicle manufacturers accelerate stainless steel manifold orders ahead of Euro 7 implementation. The European Commission's proposed particulate number limits expand real-driving emissions testing requirements. Stuttgart and Munich engineering centers drive thermal management specification for premium platform development.
China
MIIT fuel consumption mandates accelerate domestic supplier qualification for stainless steel exhaust architectures. NMPA vehicle certification protocols tighten allowable emissions thresholds. Shanghai and Yangtze River Delta manufacturing bases concentrate tier-1 integration capacity for export and domestic OEM programs.
Japan
Motorcycle OEMs specify tubular stainless architectures for compact packaging constraints. METI emissions standards for small-displacement engines drive thermal efficiency engineering. Nagoya and Osaka industrial corridors anchor precision fabrication capacity for two-wheeler export markets.
South Korea
Domestic automotive groups expand stainless steel manifold procurement for hybrid platform thermal management. Ministry of Environment emissions benchmarks align with Euro 7 trajectory. Ulsan and Gyeonggi Province production complexes integrate close-coupled catalyst modules for global vehicle exports.
Exhaust Manifolds and Downpipes Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the exhaust system value chain. Tier-1 integrators with full-system engineering capabilities capture OEM platform awards, while component specialists compete on material processing efficiency. The market structures around three strategic archetypes: integrated exhaust system engineers, dual-material specialists, and regional fabrication houses. Competitive moves concentrate on thermal management integration partnerships and backward integration into stainless steel feedstock processing.
Among European-anchored system integrators, Tenneco and FORVIA exemplify divergent strategic positioning. Tenneco occupies a position emphasizing integrated exhaust system engineering for North American passenger vehicle programs. FORVIA represents dual-material expertise spanning cast and tubular architectures across European OEM supply channels. Eberspächer Group anchors the thermal management integration specialist archetype, differentiating module offerings through close-coupled catalyst positioning expertise.
| Leading Market Players |
|---|
| Tenneco |
| FORVIA |
| Eberspächer Group |
| Bosal |
| Benteler International |
| Friedrich Boysen |
| Sejong Industrial |
| SANGO |
| Dinex |
| Others |
Pricing and Supply Chain Analysis
Stainless steel substitution for legacy cast iron manifolds simultaneously redistributes supply geography toward Germany, China, and the United States while compressing pricing power at tier-1 suppliers locked into long-term OEM contracts. Nickel and chromium feedstock volatility feeds back into sourcing decisions, accelerating backward integration into ferritic steel processing among exhaust system integrators.
Pricing Analysis
Euro 7 and EPA tailpipe standards dictate the pricing tier structure across passenger vehicle OEM supply channels. Three-tier pricing structure across premium, standard, and economy levels separates ceramic-coated performance downpipes from thin-wall stainless manifolds and legacy cast iron assemblies. Cost compression in standard-tier ferritic grades is intensifying because nickel price volatility erodes fixed-price contract margins. Commercial fleet operators exhibit highest price sensitivity, while performance vehicle OEMs absorb premium thermal retention coatings without volume elasticity.
Supply Chain Analysis
Germany, China, and the United States anchor stainless steel manifold fabrication capacity for EPA and Euro 7 compliance programs. Supply chains draw from ferritic steel mills in South Korea and Japan, nickel feedstock from Indonesian processing facilities, and chromium from South African mining operations. Single-source vulnerability concentrates in nickel sulfate refining for high-temperature alloy grades. Distribution runs through tier-1 exhaust system integrators delivering just-in-sequence to OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as composite manifold architectures and integrated thermal management modules threaten component-level suppliers with disintermediation.
For Market Incumbents: Consolidate welding automation capabilities and captive ferritic steel processing to defend margin position against nickel volatility. Secure Euro 7 pre-certification status with Stuttgart and Munich engineering centers before competitor lock-in. Prioritize thermal management integration partnerships that embed manifold-downpipe modules within active exhaust control systems. For New Entrants and Emerging Players: MIIT certification fast-track programs in China's Yangtze River Delta open procurement channels for qualified stainless steel exhaust architectures. Target aftermarket ceramic coating services for U.S. performance vehicle owners outside OEM warranty channels. Pursue white-label fabrication partnerships with specialty garages in Germany seeking batch-quantity tubular assemblies. For Investors and Strategic Acquirers: The market sits at a regulatory compression phase that favors tier-1 integrators with full-system engineering capabilities over standalone component manufacturers. Long-term viability across the next decade hinges on thermal management convergence and close-coupled catalyst positioning expertise. Watch for Euro 7 certification timeline acceleration as the inflection signal triggering consolidation among dual-material specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferritic Steel Processing | Captive nickel and chromium feedstock control insulates tier-1 suppliers from commodity volatility affecting EPA compliance programs. |
| Thermal Management Integration Partnership | Close-coupled catalyst positioning expertise differentiates module offerings for Euro 7 passenger vehicle platforms. |
| MIIT Certification Fast-Track Investment | Accelerated domestic supplier qualification opens procurement channels with Shanghai-based OEM engineering centers. |
| Ceramic Coating Service Expansion | Aftermarket thermal retention upgrades capture performance vehicle owners in U.S. specialty garage channels. |
| Welding Automation Scale-Up | Orbital welding capacity expansion addresses skill gap constraints limiting thin-wall stainless manifold throughput. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, tier-1 exhaust system procurement leads, aftermarket distribution managers, and thermal management R&D directors. Secondary validation drew from EPA regulatory filings, MIIT fuel consumption compliance databases, Euro 7 consultation documents, IHS Markit vehicle production data, and SEC disclosures from listed automotive suppliers. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions including manifold material grade, vehicle propulsion architecture, content per vehicle by platform class, OEM tier positioning, and regional regulatory cluster alignment. CAGRs were derived from regression analysis of historical procurement volumes against compliance timeline acceleration. Industry-specific forecast inputs incorporated Euro 7 implementation probability weighting and nickel price scenario modeling.
Decision-makers should treat outputs as directional under base assumptions of sustained EPA and Euro 7 regulatory trajectories; material deviation in particulate standard stringency or nickel supply disruption would warrant model refresh. Forecasts reflect documented assumptions about stainless steel adoption curves and thermal mass reduction engineering priorities. Recalibration cycles align with material shifts in European Commission regulatory consultations and MIIT certification protocol amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Fuel Sensor Market
Vehicle Components
Autonomous Trains Components Market
Vehicle Components
Portable Wheel Jack Market
Vehicle Components
Steering Column Cowls Market
Vehicle Components
Automotive Sensors Market
Vehicle Components
Traffic Control Device Tape Market
Vehicle Components
Global Navigation Lighting Market
Vehicle Components
Latin America Automotive Connectors Market
Vehicle Components
Steel and Rubber Tracks Market
Vehicle Components
Idler Arm Market
Vehicle Components
Europe Automotive Lightweight Car Market
Vehicle Components
4x4 Vehicle Parts and Accessories Market
Vehicle Components
Vehicle Cargo Box Market
Vehicle Components
HCV Suspension System Market
Vehicle Components
Engine Air Filter Market
Vehicle Components
Car Seat and Accessories Market