
 North America Vacuum Truck Market | 2026-2036
North America Vacuum Truck Market Size, Share, and Industry Trends Forecast 2026-2036
North America Vacuum Truck Market Analytics
Telematics integration with real-time tank monitoring is reconfiguring how vacuum truck fleets manage routing and payload optimization across North American operations. Federal Signal Corporation leverages embedded sensor architectures to sustain competitive positioning in municipal segments. Guzzler Manufacturing anchors its market presence through specialized dry suction configurations for industrial remediation. Vac-Con differentiates via advanced hydroexcavation packages that dominate utility contractor channels.
A vacuum truck combines a high-capacity debris tank with a powerful vacuum pump system, typically generating suction of 15 to 28 inches of mercury to extract liquid, slurry, or dry material from underground infrastructure, industrial sites, or environmental containment zones. Combination units that merge liquid and dry suction capabilities command the broadest application scope across sewer maintenance and oilfield cleanup operations. Oil and Gas application demand concentrates in the Permian Basin and Alberta oil sands, where produced water handling requirements drive above-3000-gallon capacity orders. Municipal end users represent the most stable procurement pool, with environmental services contractors representing the fastest-growing buyer category as outsourced infrastructure maintenance expands.
EPA wastewater discharge standards and OSHA excavation safety protocols directly shape vacuum truck specification requirements and fleet replacement cycles across the United States. Transport Canada CMVSS regulations and provincial environmental compliance frameworks in Alberta and Texas govern tank integrity standards and operator certification protocols. Stakeholders must monitor evolving PFAS remediation mandates and methane reduction commitments that will redirect vacuum truck deployment patterns toward environmental containment and landfill gas extraction sites.
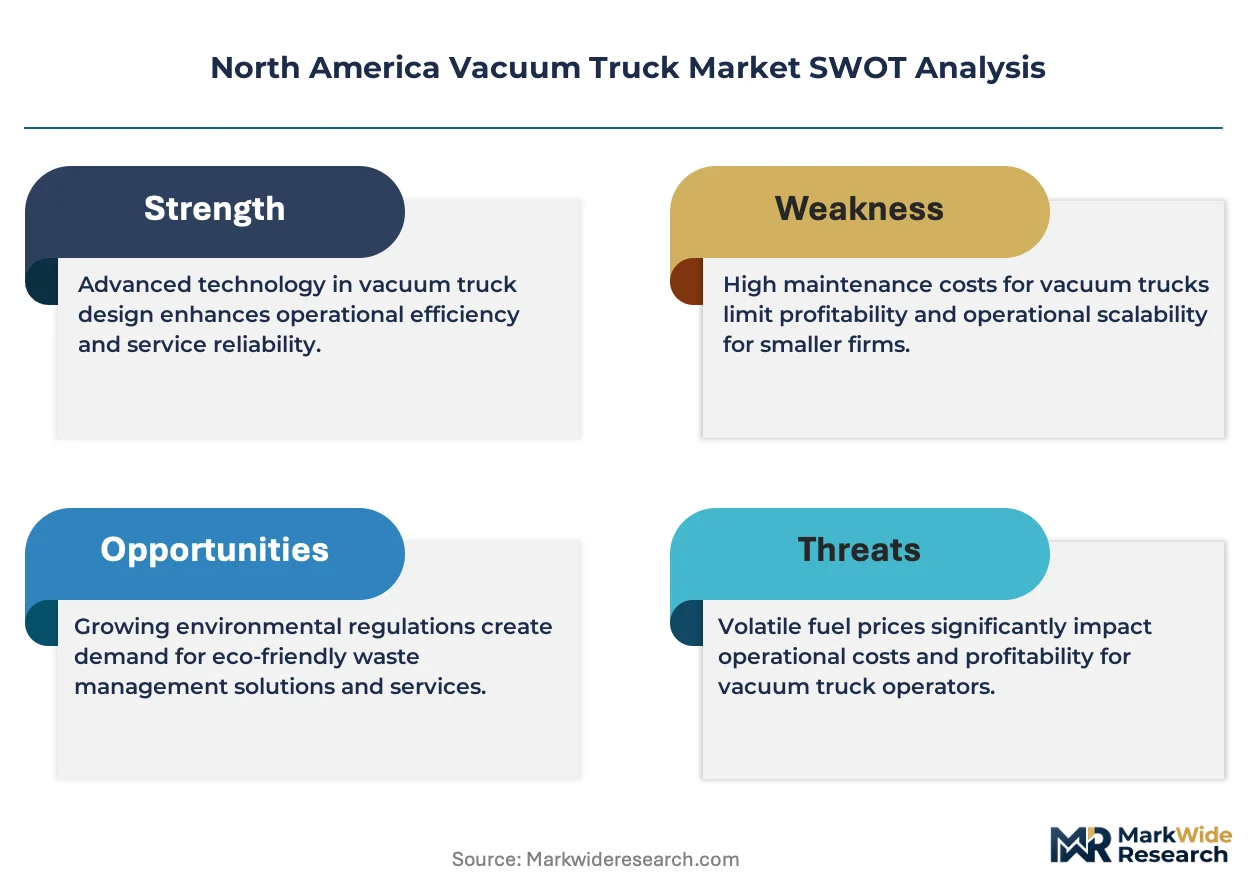
Market Dynamics
Telematics-enabled payload optimization is restructuring fleet procurement economics across municipal and contractor segments, compressing replacement cycles for units lacking real-time tank monitoring and route intelligence capabilities.
Growth Catalysts
- EPA Wastewater Infrastructure Rules:Stricter discharge standards in Texas and Alberta are forcing municipal sewer departments to expand vacuum truck fleets for proactive line maintenance and emergency response capacity.
- OSHA Excavation Safety Standards:Hydroexcavation methods are displacing mechanical digging near buried utilities, pulling combination-type vacuum trucks into utility contractor equipment rosters.
- Produced Water Handling:Permian Basin and Alberta oil sands operators require above-3000-gallon capacity units for escalating flowback and produced water management volumes.
Market Restraints
- Specialized Chassis Supply Concentration:Heavy-duty truck chassis availability constrains vacuum truck build rates, with municipal-spec cab configurations facing 8-14 month lead times from domestic manufacturers.
- High-Grade Aluminum Alloy Volatility:Tank fabrication costs fluctuate with aerospace and automotive demand for 5083 and 5454 aluminum plate, compressing fabricator margins on fixed municipal contracts.
- Operator Certification Burden:Transport Canada CMVSS and provincial environmental frameworks in Alberta impose multi-stage operator credentialing that extends deployment timelines for new fleet entrants.
Strategic Opportunities
- PFAS Remediation Mandates:Emerging federal and state-level per- and polyfluoroalkyl substance cleanup obligations are redirecting vacuum truck deployment toward environmental containment sites and landfill gas extraction facilities.
- Methane Reduction Commitments:Oil and gas operator net-zero targets are creating demand for vapor-recovery-equipped vacuum trucks at wellhead and processing facility locations.
- Telematics-Conveyance Convergence:Integration of real-time tank monitoring with automated dispatch platforms is opening subscription-based fleet management revenue streams for equipment providers.
Industry Challenges
- Certified Hydroexcavation Operator Shortage:Utility contractors face 90-120 day recruitment cycles for operators meeting OSHA excavation safety and confined space entry requirements simultaneously.
- Legacy Fleet Telematics Retrofit Complexity:Municipalities with 2015-2019 vintage units encounter CAN bus incompatibility when attempting to integrate modern sensor architectures without full powertrain replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Vacuum Truck Market |
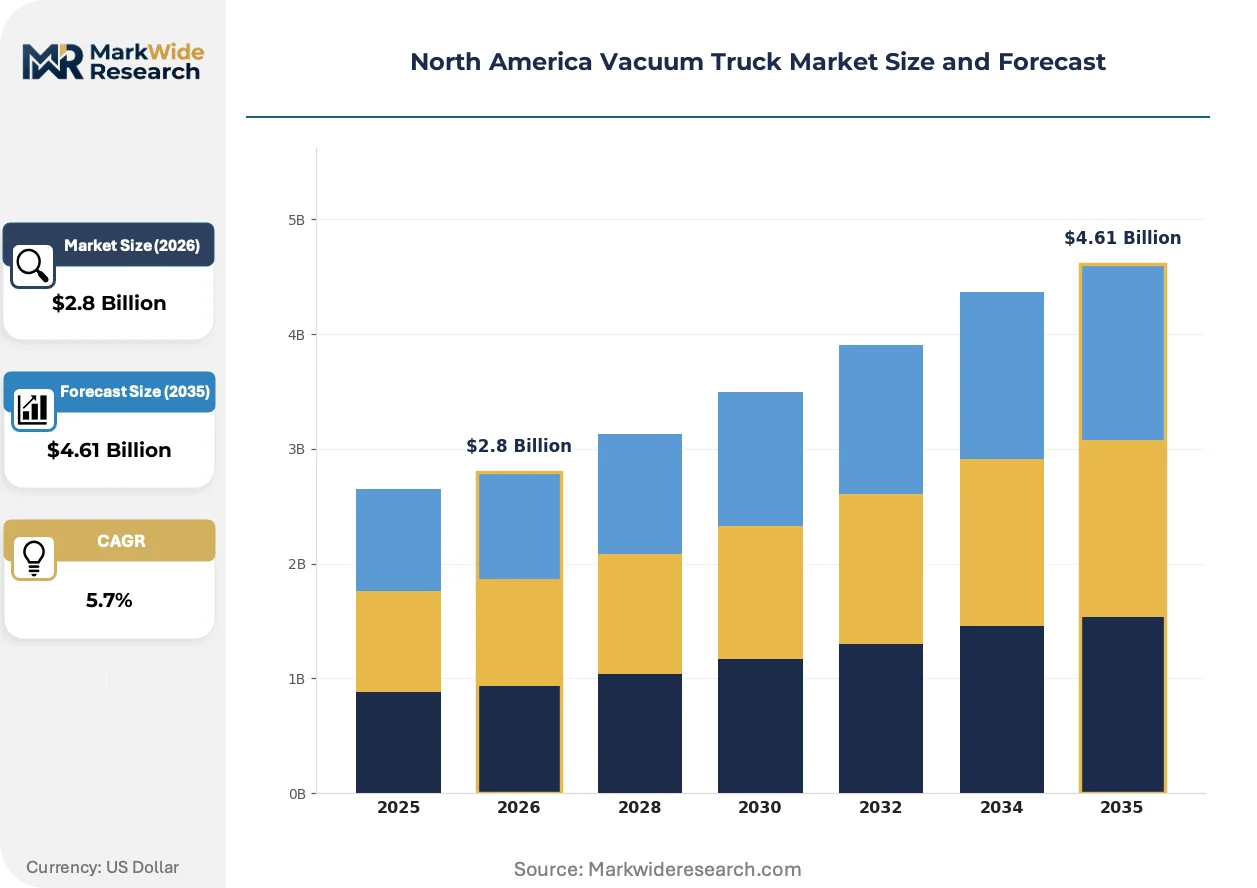
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Liquid Suction, Liquid Disposal, Dry Suction, Combination Application: Industrial Cleaning, Sewer Maintenance, Oil & Gas, Construction End User: Municipalities, Contractors, Oil & Gas Companies, Environmental Services Capacity: 500-1000 Gallons, 1000-2000 Gallons, 2000-3000 Gallons, Above 3000 Gallons |
| Companies Covered | Guzzler Manufacturing, Super Products LLC, Federal Signal Corporation, Alamo Group Inc., GapVax, Vac-Con, Keith Huber Corporation, Kaiser AG, Vactor Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Vacuum Truck Market Evolving Landscape
Active sensor fusion and automated payload management are reconfiguring vacuum truck operational economics, shifting competitive advantage from tank capacity specifications toward data-driven utilization rates and lifecycle cost transparency.
Dual-compartment tank designs with isolated liquid and dry material chambers are collapsing the equipment count required for combined sewer cleaning and industrial remediation contracts. Environmental services contractors in Texas and Alberta are specifying these configurations to reduce mobilization costs between municipal and oilfield assignments. The structural result is compressing fleet diversity requirements and favoring multi-capability single-unit procurement over specialized dedicated assets.
EPA enforcement of updated wastewater discharge standards under the Clean Water Act is mandating documented material handling chain-of-custody for municipal sewer maintenance operations. Vacuum truck fleets must now integrate GPS-tagged collection records with laboratory sampling protocols to demonstrate compliance. Municipal procurement specifications in Houston, Calgary, and Denver are embedding these data-capture requirements as mandatory bid qualifications, disqualifying equipment lacking embedded telematics architectures.
Service contract structures are unbundling equipment ownership from operational responsibility across municipal and industrial buyer segments. Environmental services contractors are assuming full fleet management accountability including maintenance, operator provision, and regulatory documentation, while municipal clients retain usage scheduling authority. This arrangement concentrates capital deployment risk with specialized operators and accelerates equipment refresh cycles in Texas and Alberta municipal markets where outsourcing penetration exceeds 40 percent of sewer maintenance activity.
North America Vacuum Truck Market Segmentation
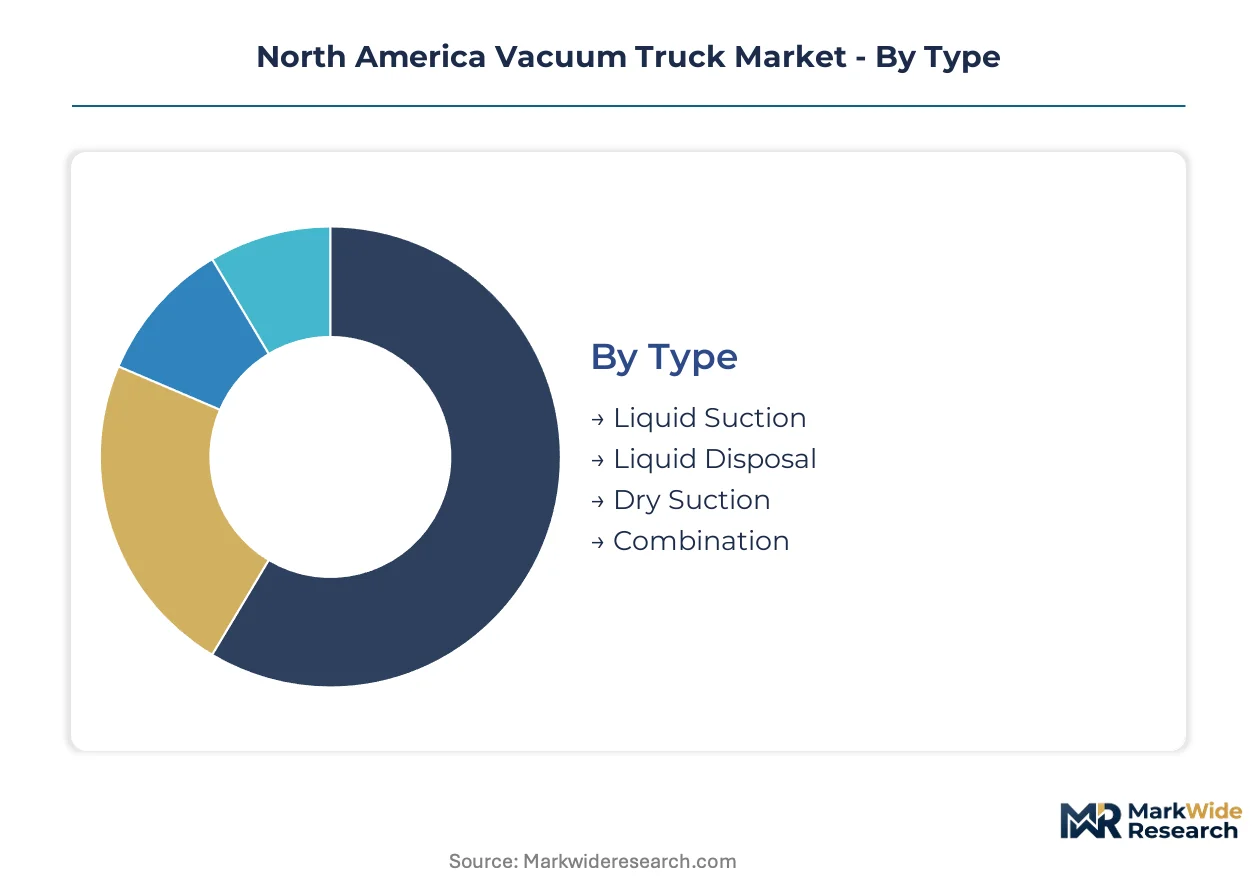
Vacuum truck segmentation reveals distinct procurement rhythms across equipment types and user categories. Fleet replacement cycles vary dramatically between municipal sewer departments and oilfield contractors, creating tiered demand patterns that manufacturers must navigate.
Type:
Combination units turn over fastest as multi-capability demands intensify, while single-purpose liquid disposal trucks cycle slowest in stable municipal fleets.
- Liquid Suction:Dedicated wet-only systems with centrifugal or rotary vane pumps optimized for municipal sewer line cleaning and stormwater basin maintenance. Houston and Calgary sewer departments specify these for routine preventive maintenance contracts where dry material handling is unnecessary.
- Combination:Dual-chamber designs integrating liquid and dry suction capabilities with isolated debris compartments and switching manifold systems. Environmental services contractors across Texas and Alberta favor these for contract flexibility spanning sewer maintenance mornings and industrial remediation afternoons.
- Liquid Disposal:Tanker-configured units for classified liquid transport from collection point to treatment facility.
- Dry Suction:Positive displacement blower systems for powder, ash, and granular material extraction.
Combination units dominate installed base growth in contractor fleets. Liquid disposal trucks anchor municipal procurement stability where specifications change minimally across replacement cycles.
Application:
Cost tier analysis shows oil and gas commanding premium pricing while construction operates at compressed margins.
- Oil & Gas:High-specification builds for produced water, flowback fluids, and drilling mud handling in Permian Basin and Alberta oil sands operations. Above-3000-gallon capacity requirements and corrosion-resistant tank alloys distinguish this segment.
- Sewer Maintenance:Municipal-spec units with EPA-compliant documentation systems and telematics integration for chain-of-custody tracking. Houston, Denver, and Calgary procurement departments embed these requirements as mandatory bid qualifications.
- Industrial Cleaning:Configurations for manufacturing facility tank cleaning and process equipment maintenance.
- Construction:Hydroexcavation-focused builds for utility exposure work near buried infrastructure.
Sewer maintenance holds the deepest installed base. Oil and gas applications concentrate expansion investment as production water volumes escalate.
End User:
Customer type segmentation distinguishes capital ownership patterns from operational outsourcing arrangements.
- Environmental Services:Multi-sector contractors assuming full fleet management responsibility including maintenance, operators, and regulatory documentation. These entities refresh equipment fastest as they consolidate municipal outsourcing contracts exceeding 40 percent of sewer maintenance activity in Texas and Alberta.
- Municipalities:Direct procurement departments with 8-14 year replacement cycles and rigid specification adherence to EPA and Transport Canada frameworks.
- Contractors:Specialized construction and utility firms with project-based utilization patterns.
- Oil & Gas Companies:Operator-owned fleets or leased equipment arrangements for field operations.
Municipalities anchor the largest cumulative fleet value. Environmental services contractors are climbing fastest as outsourcing penetration accelerates.
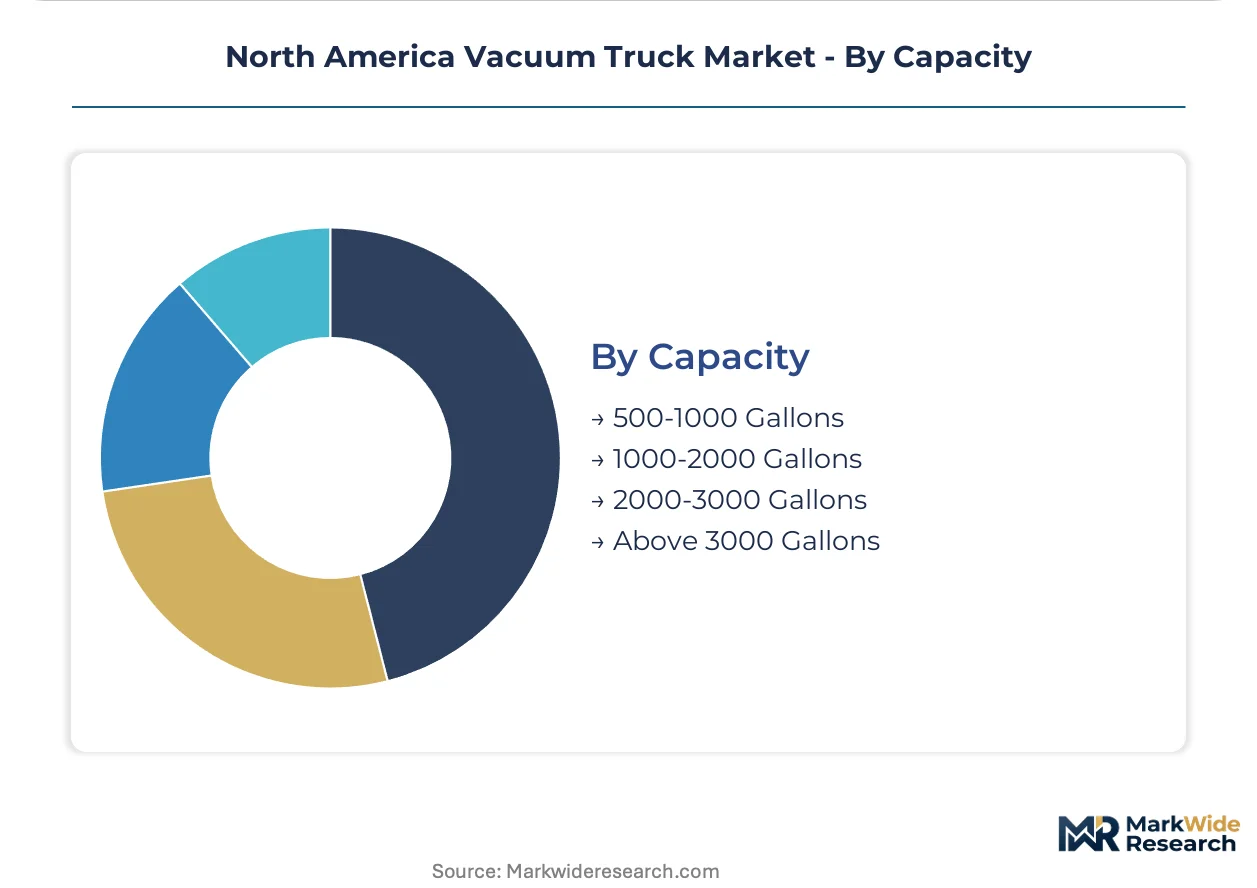
Capacity:
Volume segmentation tracks directly with haul distance economics and site accessibility constraints.
- Above 3000 Gallons:Heavy-haul configurations for oilfield produced water management where remote wellhead locations demand maximum payload per trip. Permian Basin operators specify these to minimize round-trip frequency to disposal facilities.
- 2000-3000 Gallons:Municipal workhorse range balancing maneuverability in urban sewer networks with sufficient volume for productive shift scheduling.
- 1000-2000 Gallons:Compact urban units for dense downtown infrastructure and restricted access industrial sites.
- 500-1000 Gallons:Mini configurations for residential septic service and confined space operations.
2000-3000 gallon units dominate municipal installed base. Above-3000-gallon configurations concentrate expansion activity in oilfield logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian vacuum truck fabricators export heavily into Permian Basin oilfield logistics and Great Lakes municipal procurement corridors. Cross-border equipment flows concentrate in hydroexcavation and produced water handling configurations.
United States
Texas and Louisiana municipal sewer departments drive combination-unit procurement to meet EPA Clean Water Act documentation mandates. OSHA excavation safety protocols force utility contractors toward hydroexcavation-capable builds. Houston anchors the Gulf Coast cluster where environmental services contractors consolidate outsourced maintenance contracts.
Canada
Alberta oil sands operators demand above-3000-gallon capacity units for flowback fluid management at remote wellhead locations. Transport Canada CMVSS tank integrity standards and provincial environmental frameworks govern operator certification timelines. Calgary-based fabricators supply both domestic municipal fleets and cross-border oilfield contractors.
Mexico
Pemex infrastructure maintenance and northern border industrial zones generate liquid suction unit demand for refinery turnaround and maquiladora wastewater handling. Mexican federal environmental regulations under SEMARNAT tighten discharge monitoring requirements. Monterrey and Tijuana industrial corridors concentrate contractor fleet deployment.
North America Vacuum Truck Market Competitive Landscape
Channel-controlling players compete with product-specialist players across municipal, oilfield, and industrial remediation verticals. The vendor base organizes into three tiers: diversified industrial conglomerates with vacuum truck divisions, dedicated environmental equipment fabricators, and regional chassis-body integrators serving single-state procurement pools. Strategic archetypes include telematics-integrated fleet solution providers, dry suction specialization shops, and hydroexcavation package assemblers. Competitive moves center on embedded sensor architecture partnerships and municipal outsourcing contract consolidation.
Among North American fabricators, Federal Signal Corporation, Guzzler Manufacturing, and Vac-Con occupy distinct positioning within the equipment supply chain. Federal Signal represents the diversified industrial archetype with municipal-focused embedded system capabilities. Guzzler Manufacturing anchors dry suction specialization for industrial remediation applications. Vac-Con exemplifies hydroexcavation package integration targeting utility contractor channels. These three entities collectively illustrate the segmentation between technology-forward fleet solutions and application-specific mechanical configurations.
| Leading Market Players |
|---|
| Guzzler Manufacturing |
| Super Products LLC |
| Federal Signal Corporation |
| Alamo Group Inc. |
| GapVax |
| Vac-Con |
| Keith Huber Corporation |
| Kaiser AG |
| Vactor Manufacturing |
| Others |
Value Network & Pricing Analysis
Heavy-duty truck chassis fabrication in the United States concentrates procurement leverage among three domestic manufacturers, anchoring margin capture downstream with municipal fleet operators who face extended build queues. This upstream bottleneck transmits directly into contractor segments where environmental services firms absorb premium pricing to secure delivery slots.
Pricing Analysis
Next-generation telematics-integrated vacuum trucks command substantial premiums over 2015-2019 vintage units lacking embedded sensor architectures. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling. Price compression runs through economy-tier liquid suction configurations as municipal procurement standardizes around EPA-mandated documentation systems. Environmental services contractors exhibit lowest price sensitivity due to outsourcing contract consolidation, while independent construction operators face acute margin pressure.
Supply Chain Analysis
Tariff exposure between the United States and Canada dominates supply chain risk for cross-border chassis-component flows. Tank fabrication draws from aluminum plate suppliers in the United States, Canada, and Mexico, with 5083 and 5454 alloy specifications resting on aerospace and automotive demand cycles. Single-source vulnerability concentrates in specialized pump assemblies from German and Italian component houses. Distribution runs through municipal procurement departments, environmental services contractors, and oilfield equipment lessors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. EPA wastewater discharge documentation mandates and OSHA excavation safety protocols create switching costs that lock municipal buyers into certified supplier relationships.
For Market Incumbents: Build certification moats by embedding Transport Canada CMVSS compliance and EPA chain-of-custody documentation as non-negotiable bid qualifications. Deepen backward integration into aluminum tank fabrication to capture margin from volatile alloy pricing. Channel control through municipal outsourcing contract consolidation represents the critical defensive lever against emerging telematics-native entrants. For New Entrants and Emerging Players: Build out vapor-recovery-equipped configurations targeting methane reduction commitments at Permian Basin wellhead locations. PFAS remediation mandates in Texas and Alberta landfill gas extraction sites offer the most penetrable white-space target. Go-to-market execution should anchor on subscription-based fleet management revenue streams rather than equipment-only transactions. For Investors and Strategic Acquirers: Secondary-cycle assets sit with environmental services contractors consolidating municipal outsourcing contracts exceeding forty percent of sewer maintenance activity. Five-to-ten year viability hinges on telematics architecture ownership and recurring service revenue attachment rates. Monitor OSHA enforcement intensity around hydroexcavation certification as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Architecture Integration | Embedded sensor partnerships with Federal Signal and Vac-Con reconfigure municipal procurement qualification criteria. |
| PFAS Remediation Fleet Positioning | Vapor-recovery configurations capture emerging landfill gas extraction mandates across Texas and Alberta. |
| Municipal Outsourcing Consolidation | Environmental services contractors assume full fleet management accountability, accelerating equipment refresh cycles. |
| Aluminum Tank Fabrication Backward Integration | In-house production of 5083 alloy components insulates margin from aerospace demand volatility. |
| Cross-Border Canadian Fabricator Expansion | Calgary-based suppliers leverage Transport Canada certification for Permian Basin oilfield logistics penetration. |
Research Methodology
A spread of perspectives from municipal fleet managers, environmental services contractors, oilfield logistics operators, and chassis procurement directors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through EPA enforcement records, Transport Canada CMVSS filings, and municipal procurement databases. Customs data on aluminum plate imports and heavy-duty truck chassis production statistics anchored bottom-up and top-down triangulation across the analysis window.
Demand-supply balance modeling segmented the market by equipment type, application vertical, end-user category, and tank capacity tier. CAGRs were derived from replacement cycle analysis and fleet expansion patterns rather than macroeconomic extrapolation. Hydroexcavation adoption curves, produced water volume trajectories in the Permian Basin and Alberta oil sands, and telematics penetration rates served as industry-specific forecast inputs throughout the projection horizon.
Stress conditions across aluminum alloy pricing volatility, chassis lead time extension, and OSHA certification timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and outsourcing penetration ceilings. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Medium and Heavy Duty Commercial Vehicles (MHCV) Market
Heavy-Duty Trucks
Airport Catering Truck Market
Heavy-Duty Trucks
US Tanker Truck Market
Heavy-Duty Trucks
US Vacuum Truck Market
Heavy-Duty Trucks
Big Rig Trucks Market
Heavy-Duty Trucks
China Full-Truck-Load (FTL) Market
Heavy-Duty Trucks
Middle East Refrigerated Truck Market
Heavy-Duty Trucks
Heavy Duty Truck Wash Market
Heavy-Duty Trucks
Truck Headache Rack Market
Heavy-Duty Trucks
Global Boom Truck Market
Heavy-Duty Trucks
Utility Trucks Market
Heavy-Duty Trucks
United States Tank Trucking Market
Heavy-Duty Trucks
Platooning Trucks Market
Heavy-Duty Trucks
Asia Pacific Garbage Truck Bodies Market
Heavy-Duty Trucks
United States Refrigerated Trucking Market
Heavy-Duty Trucks
Heavy-Truck Composite Component Market