
 Aluminum Alloy Wheel Market | 2026-2036
Aluminum Alloy Wheel Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Alloy Wheel Market Analysis
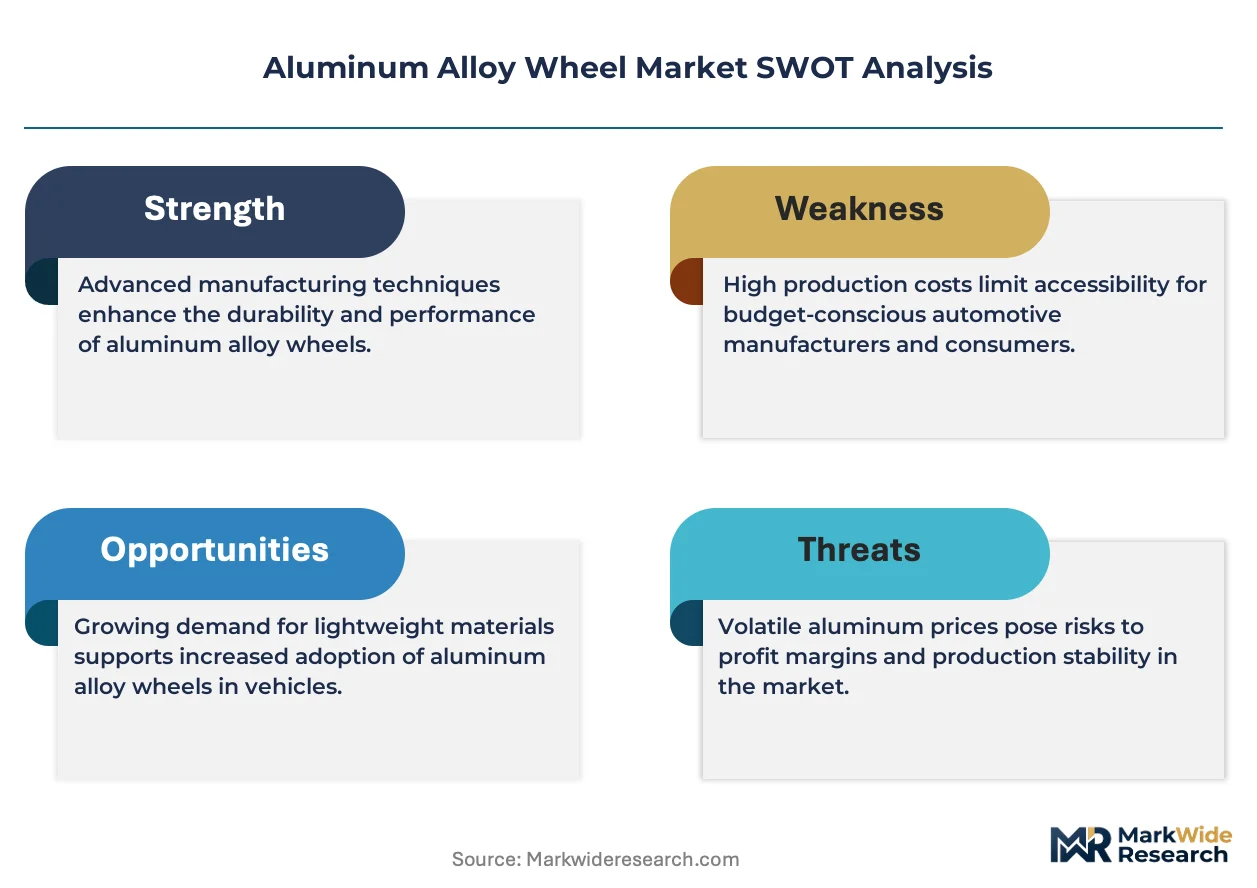
Electric vehicle OEM procurement is broadening the end-use vertical mix for aluminum alloy wheels beyond conventional internal combustion engine platforms. CITIC Dicastal Co. Ltd leverages its casting scale to anchor supply contracts with domestic Chinese EV producers. Enkei Corporation specializes in forged wheel technology for performance segments. RONAL AG controls aftermarket distribution channels across European retail networks.
Aluminum alloy wheels are structural automotive components formed from aluminum-silicon-magnesium alloys through casting or forging processes, designed to reduce unsprung mass while maintaining fatigue resistance under cyclic loading. Their primary purpose spans OEM fitment for fuel efficiency gains and aftermarket replacement for aesthetic and performance customization. Cast wheels occupy the highest volume tier due to cost efficiency in mass-market passenger car fitment, while forged wheels command premium positioning in performance and racing applications where strength-to-weight ratios determine competitive outcomes. The aftermarket channel exhibits structural fragmentation across online platforms and independent distributors, complicating price transparency.
EPA fuel economy standards in the United States and the EU Green Deal framework shape product design requirements by penalizing vehicle weight and carbon intensity across the lifecycle. China's MIIT enforces GB standards for automotive aluminum component quality that govern market access for domestic and imported wheel suppliers. Stakeholders must monitor evolving alloy composition mandates and recycling content thresholds as regulators tighten embodied carbon accounting.
Market Dynamics
Electric vehicle platform architectures are forcing aluminum alloy wheel suppliers to reengineer load-bearing specifications as unsprung mass reduction becomes a critical range-extending lever for battery-electric powertrains.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Penalties on vehicle weight compel OEMs to specify lighter wheel materials, pulling aluminum alloys into standard fitment tiers previously occupied by steel.
- China's NEV subsidy extensions:Domestic EV manufacturers scale aluminum-intensive unibody platforms, expanding procurement volumes for cast and forged wheel suppliers with localized production footprints.
- Forging process automation:Robotics integration in flow-forming and rotary forging compresses cycle times, enabling cost-competitive penetration into mid-market passenger segments.
Market Restraints
- Primary aluminum price volatility:LME aluminum fluctuations and smelter energy cost spikes in China and Russia transmit directly to wheel manufacturer margin compression.
- Supply concentration in Shandong and Henan provinces:Overreliance on Chinese casting capacity creates geopolitical and logistics risk for non-domestic OEMs without qualified secondary sourcing.
- Steel wheel residual cost advantage:Commercial vehicle and economy passenger segments retain steel specifications where total cost of ownership calculations override weight savings.
Strategic Opportunities
- India's PLI scheme for auto components:Localization incentives attract wheel suppliers to establish forging and casting operations serving domestic OEMs and export markets.
- Closed-loop aluminum recycling:Post-consumer scrap recovery and in-house remelt integration reduce embodied carbon intensity, aligning with EU Green Deal lifecycle accounting requirements.
- Direct-to-consumer online fitment:Digital platforms with VIN-matched sizing algorithms bypass traditional distributor tiers, capturing aftermarket margin pools.
Industry Challenges
- Fatigue testing certification timelines:SAE J2530 and TUV validation protocols extend product approval cycles, delaying revenue recognition for new wheel designs.
- Alloy composition IP disputes:Proprietary silicon-magnesium ratios and heat treatment sequences generate litigation risk between incumbent suppliers and new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Alloy Wheel Market |
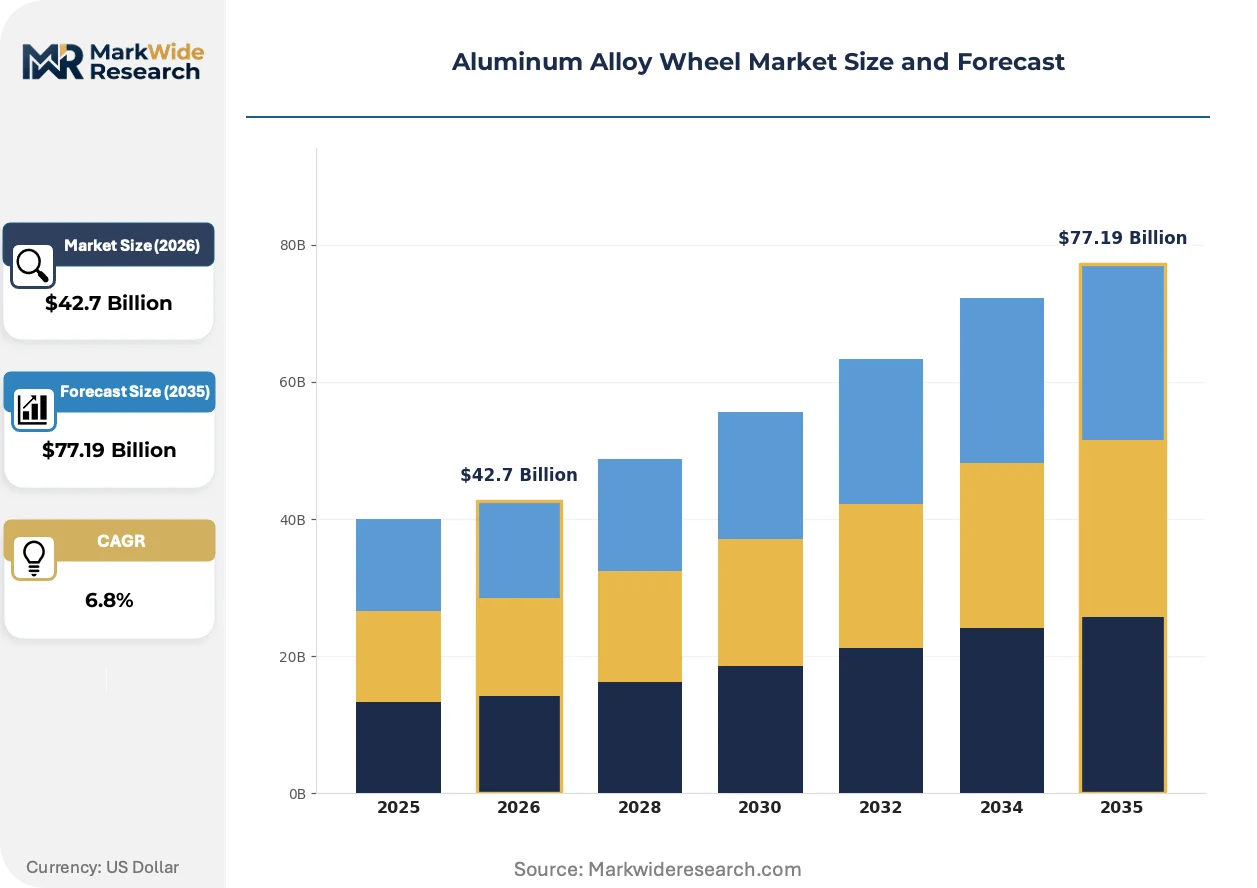
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $77.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forged Wheels, Cast Wheels, Multi-Piece Wheels, Replica Wheels End User: Passenger Cars, Commercial Vehicles, Racing Vehicles, Aftermarket Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Distributors Application: Performance, Aesthetic, Off-Roading, Standard |
| Companies Covered | BORBET GmbH, Lizhong Wheel Group, CITIC Dicastal Co. Ltd, Topy Industries Ltd, Enkei Corporation, Maxion Wheels, Wanfeng Auto Wheel Co. Ltd, Alcoa Wheels, RONAL AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Alloy Wheel Market Emerging Trajectories
Process innovation and regulatory carbon accounting are converging to redefine competitive advantage in aluminum alloy wheel manufacturing, with material traceability and production automation emerging as decisive capability differentiators.
Flow-forming hybrid manufacturing is expanding into mass-market EV wheel specifications. This process combines cast preforms with rotary forging to achieve forged-like strength-to-weight ratios at casting-equivalent costs. Chinese EV OEMs have adopted flow-formed wheels for mid-range sedan platforms, compressing the historical premium positioning of forged products and forcing traditional cast suppliers to upgrade equipment or cede segment share.
The EU F-Gas Regulation and accompanying CBAM framework are reshaping supplier qualification criteria by imposing embodied carbon disclosure requirements on imported aluminum components. Wheel manufacturers must now document smelter energy sources and alloying content through certified chain-of-custody systems. European OEM procurement teams are prioritizing suppliers with verified low-carbon primary aluminum or closed-loop scrap integration, disadvantaging producers without EU-localized remelt capacity.
Fleet operators and leasing companies are consolidating aftermarket wheel procurement through centralized tender platforms, displacing fragmented independent distributor networks. These aggregated buying pools specify standardized fitment ranges and warranty terms, compressing price variability and favoring suppliers with scale economies in logistics and inventory management. Germany and the Netherlands exhibit the most advanced consolidation, with fleet management companies directly contracting wheel suppliers for multi-year replacement cycles.
Aluminum Alloy Wheel Market Segmentation
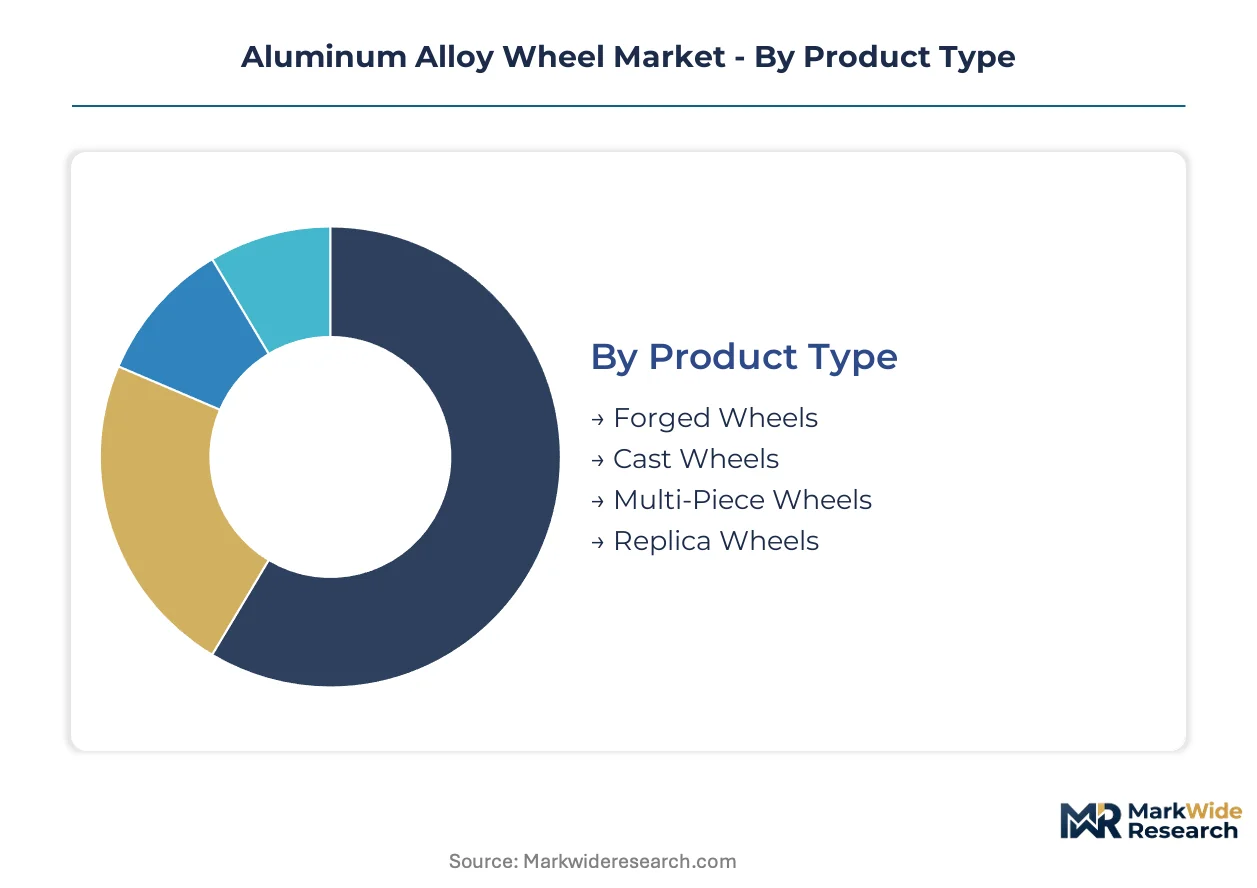
Aluminum alloy wheel procurement patterns diverge sharply between OEM fitment cycles governed by platform redesign timelines and aftermarket replacement driven by wear, damage, or aesthetic refresh decisions. Segmentation reveals how manufacturing process economics and end-use performance requirements create distinct competitive arenas with divergent margin structures.
Product Type:
Upgrade cycles from cast to forged specifications accelerate as EV platforms prioritize unsprung mass reduction for range optimization.
- Forged Wheels:Monoblock aluminum blanks undergo high-pressure compression under rotary forging or flow-forming to achieve grain-aligned microstructures with superior fatigue resistance. Demand concentrates in German performance OEMs and Chinese EV sedan platforms where 15-20% weight reduction justifies 3-4x cost premiums over cast alternatives.
- Cast Wheels:Gravity or low-pressure casting of A356 aluminum-silicon-magnesium alloy dominates volume production for mass-market passenger fitment. Chinese domestic brands and US full-line manufacturers specify cast specifications for standard wheel programs where per-unit cost targets override incremental weight savings.
- Multi-Piece Wheels:Modular construction combining forged centers with spun rims enables custom offset and width configurations for aftermarket customization.
- Replica Wheels:Reverse-engineered designs replicate OEM styling at reduced price points for insurance replacement and budget-conscious aftermarket segments.
Volume placements concentrate in Cast Wheels; the faster expansion belongs to Forged Wheels.
End User:
Customer type determines specification stringency, with OEM procurement teams enforcing SAE J2530 fatigue protocols that aftermarket channels often bypass.
- Passenger Cars:Light-duty platforms generate the largest procurement volumes across both ICE and battery-electric architectures. Chinese NEV manufacturers and German premium OEMs drive aluminum content increases as 18-22 inch diameters become standard fitment.
- Commercial Vehicles:Fleet operators retain steel specifications for heavy-duty applications where load ratings and total cost of ownership calculations override weight reduction incentives.
- Racing Vehicles:Motorsport sanctioning bodies mandate forged construction with documented metallurgical certification for competitive eligibility.
- Aftermarket:Fragmented demand spans insurance replacement, cosmetic upgrade, and performance modification use cases with highly variable quality standards.
Procurement scale favors Passenger Cars; Racing Vehicles command the steepest price premiums per unit.
Distribution Channel:
Channel structure determines working capital intensity and margin capture, with direct OEM contracts offering volume certainty against aftermarket volatility.
- Direct Sales:Long-term supply agreements with vehicle manufacturers specify annual volume commitments, alloy composition requirements, and just-in-sequence delivery obligations. Chinese wheel producers leverage direct contracts with domestic EV platforms to anchor capacity utilization.
- Retail Stores:Independent tire and wheel shops provide immediate fitment services with mounting, balancing, and alignment capabilities that pure e-commerce cannot replicate.
- Online Platforms:Digital marketplaces with VIN-matched sizing algorithms displace traditional distributor tiers by collapsing search costs and expanding SKU visibility.
- Distributors:Regional wholesalers maintain inventory buffers and credit terms for smaller retail accounts lacking direct manufacturer relationships.
Revenue stability concentrates in Direct Sales; Online Platforms are climbing the fastest as fleet procurement digitizes.
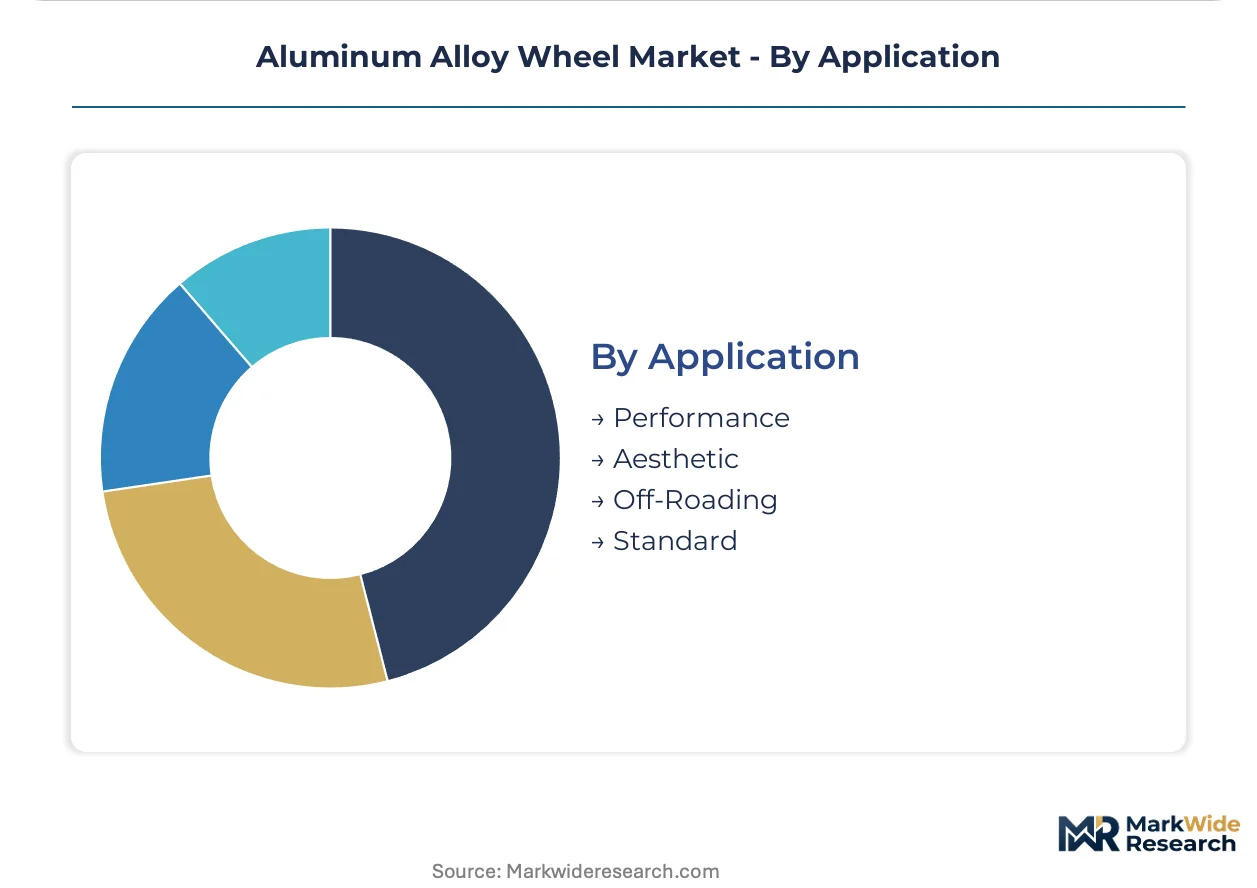
Application:
Use case segmentation separates commodity replacement from performance-driven specification upgrades with divergent technical requirements.
- Performance:Track-oriented specifications prioritize thermal management under sustained braking loads and lateral stiffness for steering precision. Japanese and German tuning markets sustain premium pricing for forged flow-formed constructions.
- Aesthetic:Cosmetic upgrades emphasize finish durability, spoke design variety, and diameter upsizing without structural modification. Chinese consumer preferences favor polished or painted finishes with complex multi-spoke geometries.
- Off-Roading:Beadlock-compatible forged designs accommodate low-pressure operation for traction in unparsed terrain.
- Standard:Baseline fitment specifications meet regulatory minimums for strength and durability without performance optimization.
Unit economics favor Aesthetic applications; Performance specifications deliver the highest contribution margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shandong and Henan provinces concentrate casting capacity for aluminum alloy wheels, drawing procurement commitments from domestic EV manufacturers seeking localized supply chains.
China
Domestic NEV manufacturers BYD and NIO scale aluminum-intensive unibody platforms, expanding procurement volumes for cast and forged wheel specifications. MIIT enforces GB standards for automotive aluminum component quality that govern market access for all wheel suppliers. Production clusters in Shandong and Henan provinces anchor global casting capacity, with CITIC Dicastal leveraging localized operations to secure direct OEM contracts.
Germany
Premium OEMs BMW and Mercedes-Benz specify forged wheels for performance variants where 15-20% weight reduction justifies cost premiums. The EU F-Gas Regulation and CBAM framework impose embodied carbon disclosure requirements on imported aluminum components. Industrial concentration in Baden-Württemberg and Bavaria hosts forging specialists serving motorsport and luxury passenger segments with documented metallurgical certification.
United States
EPA Corporate Average Fuel Economy standards penalize vehicle weight, compelling Detroit Three automakers to specify aluminum alloys in standard fitment tiers. NHTSA safety protocols govern wheel fatigue testing and validation timelines for OEM approval. Manufacturing presence in Michigan and Ohio supports just-in-sequence delivery to assembly plants, though primary aluminum price volatility compresses margins for domestic producers.
Japan
Performance-oriented tuning markets sustain premium pricing for forged flow-formed constructions in track-oriented applications. METI industrial policy supports lightweighting initiatives across automotive component supply chains. Technical concentration in Aichi and Osaka prefectures maintains expertise in rotary forging and heat treatment sequences for racing and high-performance road specifications.
India
PLI scheme incentives for auto components attract wheel suppliers establishing forging and casting operations serving domestic OEMs and export markets. BIS quality standards align with international fatigue protocols for OEM qualification. Emerging production corridors in Tamil Nadu and Gujarat target capacity buildout for Maruti Suzuki and Hyundai-Kia procurement programs.
Aluminum Alloy Wheel Market Vendor Landscape
Top-tier vendors anchor direct OEM supply contracts, while mid-scale fabricators compete through process specialization and geographic proximity to emerging demand centers. The vendor base separates into casting-scale operators, forging-technology specialists, and aftermarket distribution controllers. Strategic archetypes include integrated aluminum smelter-wheel producers, flow-forming equipment innovators, and closed-loop recycling operators. Competitive moves concentrate on capacity expansion in India and Southeast Asia, plus backward integration into primary aluminum sourcing.
Within the casting-scale tier, CITIC Dicastal Co. Ltd and Wanfeng Auto Wheel Co. Ltd exemplify Chinese producers leveraging localized capacity to anchor domestic EV procurement. Enkei Corporation occupies a position among forging-technology specialists serving performance segments with documented metallurgical expertise. RONAL AG represents aftermarket distribution controllers with European retail network penetration.
| Leading Market Players |
|---|
| BORBET GmbH |
| Lizhong Wheel Group |
| CITIC Dicastal Co. Ltd |
| Topy Industries Ltd |
| Enkei Corporation |
| Maxion Wheels |
| Wanfeng Auto Wheel Co. Ltd |
| Alcoa Wheels |
| RONAL AG |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation compliance gates both qualified supply and premium-tier pricing access, as wheel manufacturers must document smelter energy sources and alloying content through certified chain-of-custody systems to serve European OEM procurement teams.
Pricing Analysis
Short lead-time premiums command 15-25% markups over standard contract pricing as OEM just-in-sequence delivery obligations compress planning horizons. Three-tier pricing structure across premium, standard, and economy levels separates forged flow-formed specifications from gravity-cast mass-market fitment from steel-retention commercial vehicle segments. Cost compression in standard cast tiers is intensifying because Chinese domestic brands consolidate procurement volumes around localized suppliers. Fleet operators and leasing companies exhibit highest price sensitivity through centralized tender platforms, while German performance OEMs show least sensitivity where weight reduction justifies cost premiums.
Supply Chain Analysis
Primary aluminum supply rests on Chinese smelter capacity in Shandong and Henan provinces, Russian hydro-powered production, and Gulf Cooperation Council petrochemical-integrated operations. A356 alloy ingot, magnesium master alloy, and silicon metal feed forging and casting operations with divergent purity specifications. Single-source vulnerability concentrates in Chinese casting capacity where geopolitical friction threatens qualified supplier status for non-domestic OEMs. Distribution runs through direct OEM contracts with annual volume commitments, regional distributor inventory buffers, and emerging VIN-matched digital platforms collapsing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU CBAM embodied carbon disclosure requirements erect a barrier-to-entry moat for compliant players, forcing non-integrated wheel manufacturers to invest in remelt capacity or cede European OEM procurement to verified low-carbon suppliers.
For Market Incumbents: Anticipate margin compression from flow-forming equipment innovators penetrating mid-market EV segments by upgrading rotary forging automation or securing captive scrap supply through closed-loop recycling integration. Defensive consolidation should prioritize backward integration into primary aluminum sourcing and certification investment for EU Green Deal lifecycle accounting compliance. For New Entrants and Emerging Players: Flow-forming hybrid manufacturing offers a technology-first wedge into Chinese NEV mid-range sedan procurement where cost-forged strength-to-weight ratios displace traditional cast suppliers. White-space targets include India's PLI scheme localization incentives and fleet operator direct-to-consumer online fitment platforms bypassing fragmented distributor networks. For Investors and Strategic Acquirers: OEM procurement team consolidation around verified low-carbon primary aluminum suppliers is the leading indicator that backward-integrated remelt operators will command acquisition premiums over pure-play fabricators. Long-term viability favors vertically integrated specialists with EU-localized production and documented metallurgical certification. Watch for MIIT enforcement actions on GB standards compliance as inflection signal for Chinese market access restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-loop Aluminum Recycling Integration | Post-consumer scrap recovery reduces embodied carbon intensity for EU CBAM compliance. |
| Flow-forming Equipment Automation | Rotary forging robotics compress cycle times for mid-market EV penetration. |
| India PLI Scheme Manufacturing Footprint | Localization incentives attract forging operations serving Maruti Suzuki procurement. |
| Direct-to-consumer Online Fitment Platform | VIN-matched sizing algorithms bypass distributor tiers capturing aftermarket margin. |
| EU-localized Remelt Capacity Buildout | Verified low-carbon primary aluminum secures BMW and Mercedes-Benz supply contracts. |
Methodological Framework
Independent corroboration across OEM platform engineering directors, Tier 1 supplier procurement leads, aftermarket distributor operations heads, and aluminum smelter technical sales managers underwrites the qualitative findings. Secondary validation draws from EPA fuel economy compliance filings, EU ETS carbon disclosure databases, MIIT GB standards documentation, and vehicle production registration data. Bottom-up segment sizing triangulates against top-down macroeconomic anchors across propulsion architecture and regional production cluster dimensions.
Historical reference periods spanning platform redesign cycles and aftermarket replacement frequency patterns anchor the projection horizon. Segmentation modeling incorporates manufacturing process type, end-use vertical, distribution channel structure, and application performance tier. CAGRs derive from regression analysis of procurement volume trends against regulatory compliance cost trajectories. Forecast inputs include NEV penetration assumptions and alloy composition mandate evolution under tightening lifecycle accounting protocols.
Forecast precision tightens around the base case; tail outcomes carry wider variance under LME aluminum price volatility spikes and geopolitical trade restriction scenarios. Forecasts reflect documented assumptions on subsidy persistence and OEM platform standardization timelines. A small set of named triggers—CBAM enforcement stringency, MIIT GB standards revision, and flow-forming equipment cost curves—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Automotive Exhaust Gas Sensor Market
Vehicle Components
Sideloaders Market
Vehicle Components
Steer-by-Wire Road Wheel Actuator Modules Market
Vehicle Components
Trailer Axle Market
Vehicle Components
Traffic Control Device Tape Market
Vehicle Components
HCV Axles Market
Vehicle Components
Bicycle Bottom Bracket Market
Vehicle Components
Air Suspension Market
Vehicle Components
Global Wheel Tractor Scraper Market
Vehicle Components
Global Automotive Steering Torque Sensor Market
Vehicle Components
Cylindrical Roller Bearings Market
Vehicle Components
Asia-Pacific Industrial Brakes Market
Vehicle Components
Automotive Position Sensor Market
Vehicle Components
Vehicle-To-X Products Market
Vehicle Components
Towing Equipment Market
Vehicle Components
Automotive Pyrofuse Market