
 Saudi Arabia Road Freight Transport Market | 2026-2036
Saudi Arabia Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Road Freight Transport Market Analytics
Composite-based lightweight trailer construction is expanding across Saudi fleet procurement, cutting fuel expenditure per tonne-kilometer. Almajdouie Group leverages its integrated heavy-haulage network to dominate cross-border routes into the GCC. Zahid Group anchors its position through captive maintenance and parts distribution infrastructure. DHL Group competes on temperature-controlled pharmaceutical logistics, a segment where regulatory compliance creates defensible margins.
Saudi Arabia road freight transport encompasses the movement of goods by motorized vehicles over the Kingdom's paved road network, utilizing heavy trucks with gross vehicle weights exceeding 16 tonnes for long-haul routes and light trucks below 3.5 tonnes for last-mile distribution. The sector functions as the dominant mode for domestic cargo movement, connecting industrial cities, port terminals, and consumption centers across approximately 72,000 kilometers of highways. Heavy trucks command the largest share of tonnage moved, though cargo vans exhibit the fastest structural growth as same-day delivery expectations reshape urban logistics. Full truckload services retain margin leadership on bulk commodity corridors, while less than truckload operations fragment competitively around Riyadh and Jeddah.
SFDA pharmaceutical transport guidelines, SASO vehicle emission standards, and the Ministry of Transport's smart fleet monitoring mandates collectively reshape equipment specifications and operational compliance burdens. The General Authority of Civil Aviation's cargo zone liberalization intersects with road freight through bonded trucking corridors, tightening integration between air and land modes. Stakeholders must weigh electrification pilot commitments against diesel infrastructure lock-in as the Kingdom's renewable energy buildout accelerates.
Market Dynamics
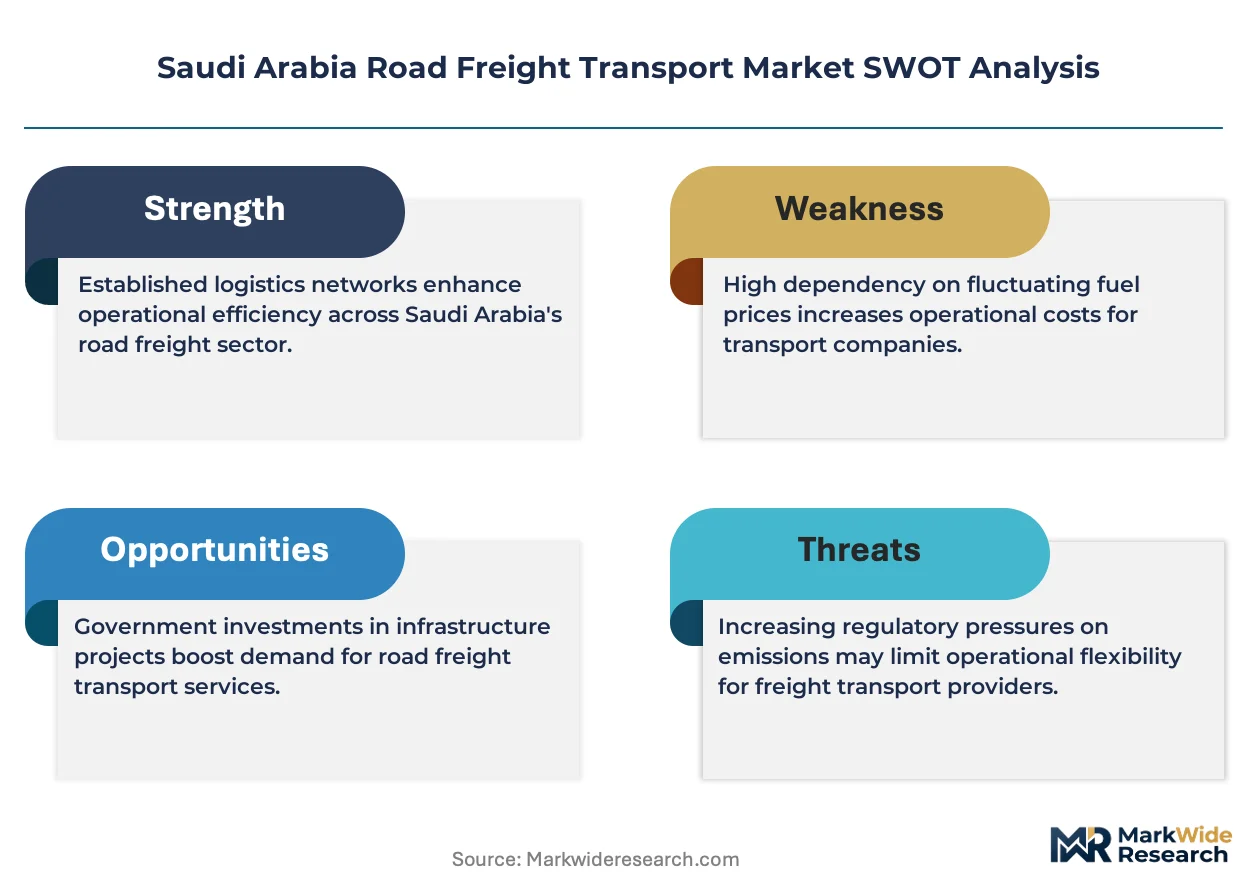
Vision 2030 privatization mandates are fragmenting fleet ownership across Saudi Arabia, converting state-controlled trucking assets into concession-based operator networks and forcing incumbents to compete against newly licensed logistics entrants on bonded corridor routes.
Growth Catalysts
- E-commerce fulfillment infrastructure:Same-day delivery expectations from Riyadh and Jeddah consumers are compressing warehouse-to-door cycle times and expanding light commercial vehicle deployment.
- SFDA pharmaceutical cold chain mandates:Temperature-controlled transport certification requirements are creating specialized service tiers with premium rate structures.
- GCC cross-border integration:Unified customs protocols are reducing dwell times at Saudi-UAE and Saudi-Bahrain border crossings, accelerating round-trip utilization on heavy-haulage corridors.
Market Restraints
- Diesel price volatility:Fuel constitutes 35-45% of operating costs for long-haul operators, with subsidy reduction timelines creating margin uncertainty.
- Driver supply concentration:Dependence on expatriate labor from South Asian source markets exposes fleets to visa policy fluctuations and wage inflation.
- Electrification infrastructure gap:Charging network density remains insufficient for battery-electric heavy trucks outside Riyadh-Jeddah corridor pilot zones.
Strategic Opportunities
- Neom logistics zone development:The Red Sea coastal megaproject requires dedicated construction material haulage and eventual permanent distribution infrastructure.
- Hydrogen fuel cell corridors:NEOM's green hydrogen production creates potential for zero-emission trucking pilot routes with captive fuel supply.
- Air-land bonded trucking:King Abdulaziz International Airport cargo zone liberalization enables integrated multimodal service offerings for pharmaceutical and electronics shippers.
Industry Challenges
- Fleet telematics integration:Ministry of Transport smart monitoring mandates require retrofitting legacy vehicles with GPS and electronic logging devices on compressed timelines.
- Specialized cold chain technician scarcity:Refrigeration system maintenance and pharmaceutical handling certification programs have not scaled to match fleet expansion rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Road Freight Transport Market |
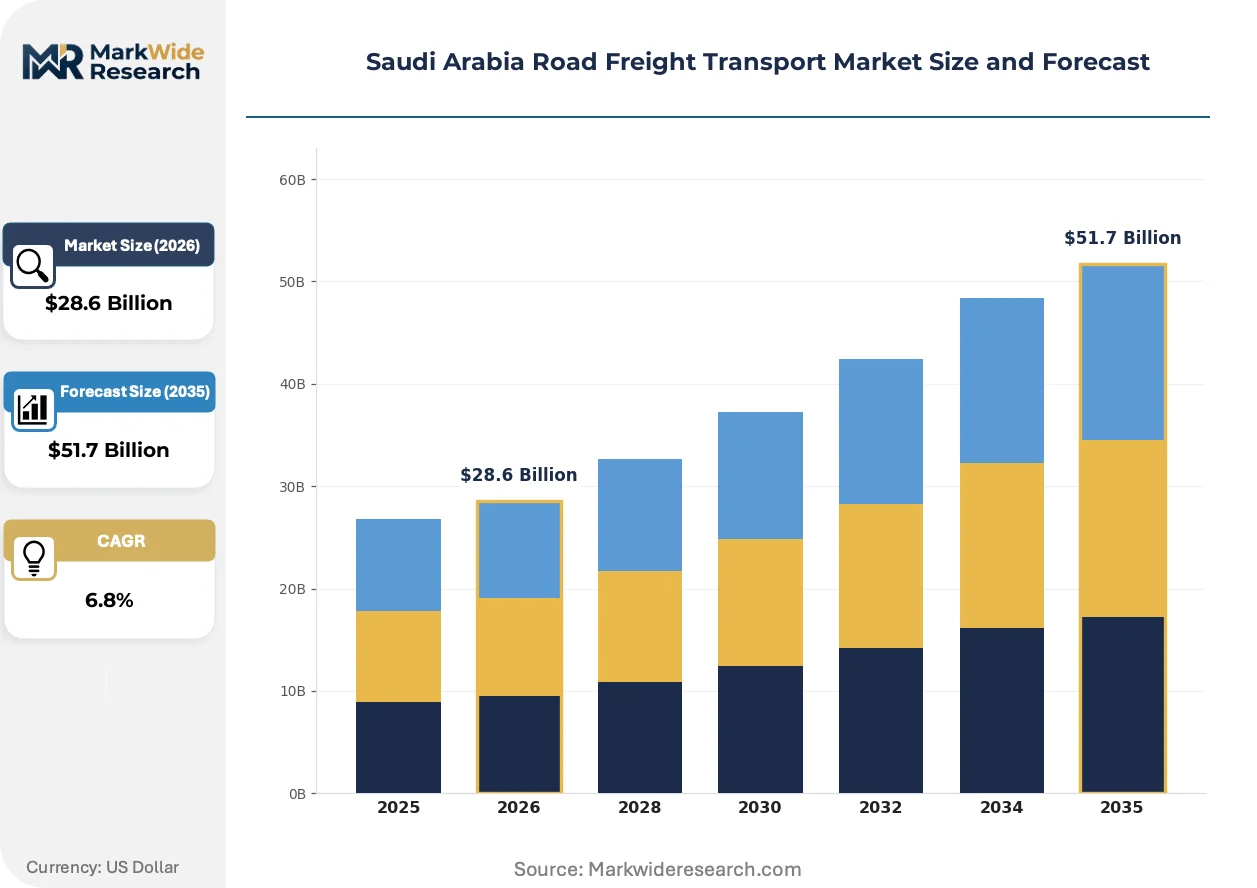
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Heavy Trucks, Light Trucks, Cargo Vans, Trailers Service Type: Full Truckload, Less Than Truckload, Intermodal, Dedicated End User: Retail, Manufacturing, Agriculture, Construction Operational Model: Third-Party Logistics, Freight Forwarding, Own Fleet, E-commerce Delivery |
| Companies Covered | Kadi Group Holding, Rashed Abdul Rahman Al Rashed & Sons Group, Almajdouie Group, SMSA Express Transportation Company Ltd., Aramex, Al Rajhi Group, Munawla Cargo Co. Ltd., Zahid Group, DHL Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Road Freight Transport Market Evolving Landscape
Digital freight matching platforms are compressing broker margins and reallocating pricing power toward shippers with predictable volume profiles, while composite materials and alternative propulsion systems reshape equipment procurement criteria.
Telematics-integrated trailer tracking is unifying cargo visibility with predictive maintenance scheduling. Large fleet operators are deploying these systems across dry van and refrigerated assets to optimize utilization rates. This convergence is compressing the information advantage traditionally held by established freight brokers.
SASO vehicle emission standards are tightening particulate matter and nitrogen oxide limits for new heavy truck registrations. Equipment importers must certify compliance through designated testing facilities before customs clearance. European and East Asian OEMs are accelerating Euro VI-equivalent engine introductions to maintain market access.
Shippers are consolidating vendor relationships around integrated service providers capable of handling temperature-sensitive pharmaceuticals, hazardous materials, and general freight under unified contracts. This concentration is displacing fragmented spot-market arrangements on high-volume Riyadh-Jeddah lanes. Pharmaceutical distributors and supermarket chains are driving this consolidation most aggressively.
Saudi Arabia Road Freight Transport Market Segmentation
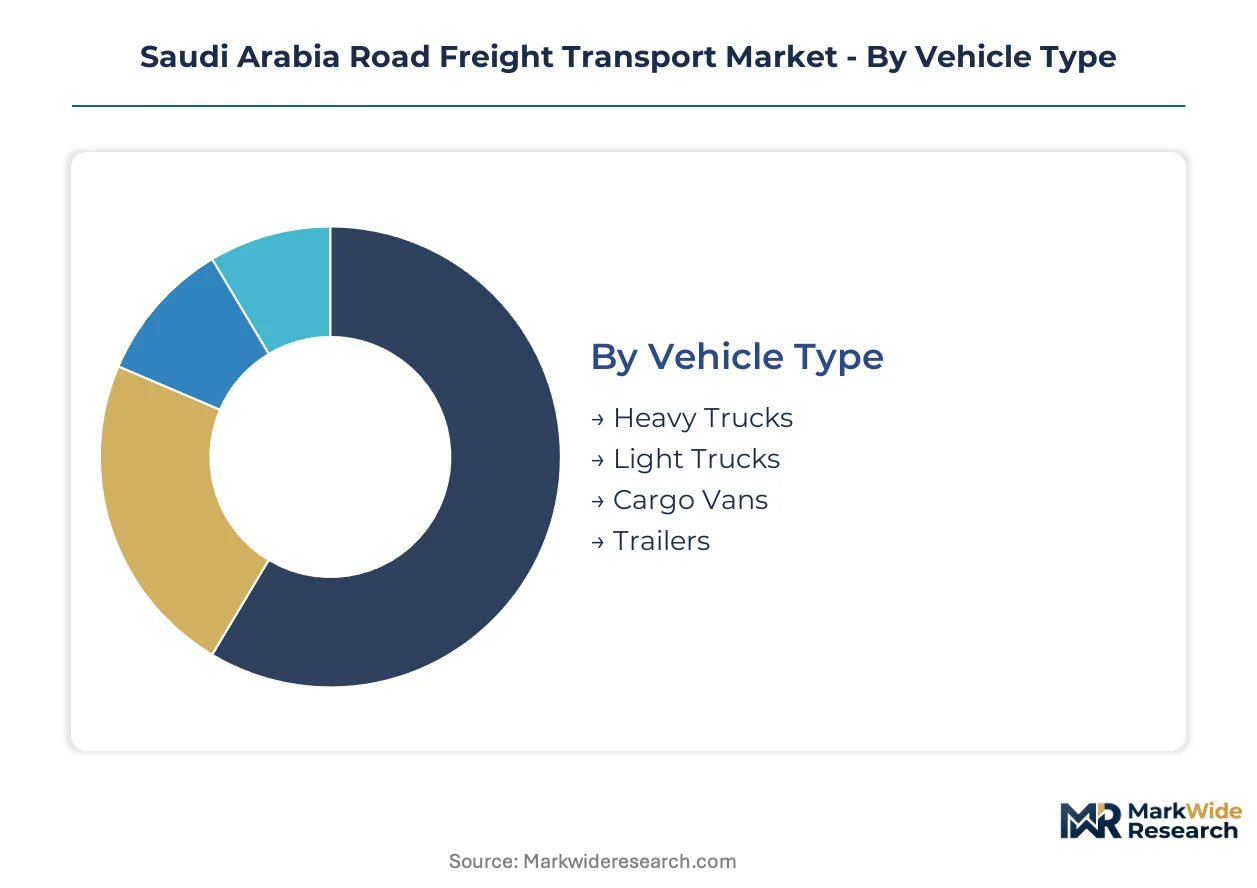
Segmentation in Saudi Arabia road freight transport reveals how fleet composition, service specialization, and operational control determine margin capture across the Kingdom's logistics corridors. Distinct equipment and service tiers serve Riyadh's industrial belt, Jeddah's port hinterland, and emerging Neom construction zones with divergent economics.
Vehicle Type:
Volume leadership belongs to heavy trucks on long-haul bulk corridors, while premium economics concentrate in specialized temperature-controlled and lightweight composite trailers.
- Heavy Trucks:Gross vehicle weights exceeding 16 tonnes dominate tonnage moved across the Kingdom's 72,000-kilometer highway network. Fleet procurement concentrates around Riyadh-Dammam and Riyadh-Jeddah corridors where cement, petrochemicals, and construction materials generate predictable backhaul demand.
- Light Trucks:Vehicles between 3.5 and 16 tonnes GVW bridge warehouse-to-depot distribution with higher per-kilometer rates than heavy-haul counterparts. Urban logistics operators deploy these assets for regional distribution from bonded zones at King Abdulaziz International Airport and King Khalid International Airport.
- Cargo Vans:Last-mile delivery vehicles below 3.5 tonnes GVW are expanding most quickly as same-day fulfillment expectations reshape Riyadh and Jeddah consumer logistics. E-commerce platforms and quick-commerce grocery services drive utilization.
- Trailers:Skeletal, flatbed, and refrigerated trailer assets determine payload flexibility and fuel efficiency per tonne-kilometer. Composite-material construction is penetrating fleet replacement cycles to reduce diesel consumption.
Mature deployment sits with Heavy Trucks. Newer deployment is concentrated in Cargo Vans.
Service Type:
Cost tier separation runs from contracted dedicated capacity at premium rates to fragmented spot-market less-than-truckload competition with thinner margins.
- Full Truckload:Point-to-point dedicated capacity for single-shipper volumes commands rate premiums on bulk commodity corridors. Cement producers, petrochemical distributors, and supermarket chains lock in annual contracts with guaranteed utilization.
- Less Than Truckload:Consolidated multi-shipper cargo moves through hub-and-spoke terminals with higher handling intensity and lower per-tonne yields. Competitive fragmentation concentrates around Riyadh's Suly district and Jeddah's Obhur logistics cluster.
- Intermodal:Rail-truck and air-truck bonded movements integrate with King Abdulaziz International Airport cargo zones and Saudi Railway Company freight terminals. Regulatory alignment between the General Authority of Civil Aviation and Ministry of Transport enables sealed container transfers.
- Dedicated:Captive fleet arrangements for single-shipper exclusive use guarantee capacity availability with premium pricing. Pharmaceutical distributors and automotive assemblers favor this structure for SFDA-compliant cold chain security.
Margin compression is deepest in Less Than Truckload. Rate stability is strongest in Dedicated.
End User:
Customer type determines equipment specification, with temperature-controlled and hazardous-material certifications creating service tier differentiation.
- Retail:Supermarket chains and e-commerce platforms drive cargo van and light truck deployment for high-frequency replenishment. Same-day delivery SLAs compress warehouse-to-door cycle times in Riyadh and Jeddah metropolitan zones.
- Manufacturing:Industrial city freight—SADARA, Jubail, Yanbu—generates heavy truck demand for raw material inbound and finished goods outbound. Just-in-time assembly plant requirements favor dedicated contract structures.
- Agriculture:Date harvest logistics and chilled meat exports require seasonal surge capacity with refrigerated trailer availability. SFDA compliance mandates govern transport from Qassim and Al-Ahsa production zones.
- Construction:Neom, Red Sea Project, and Qiddiya megaprojects absorb heavy-haulage capacity for construction materials and oversized equipment. Project logistics operators coordinate with Ministry of Transport permits for abnormal loads.
Equipment standardization is highest in Retail. Specialized certification requirements are most stringent in Agriculture.
Operational Model:
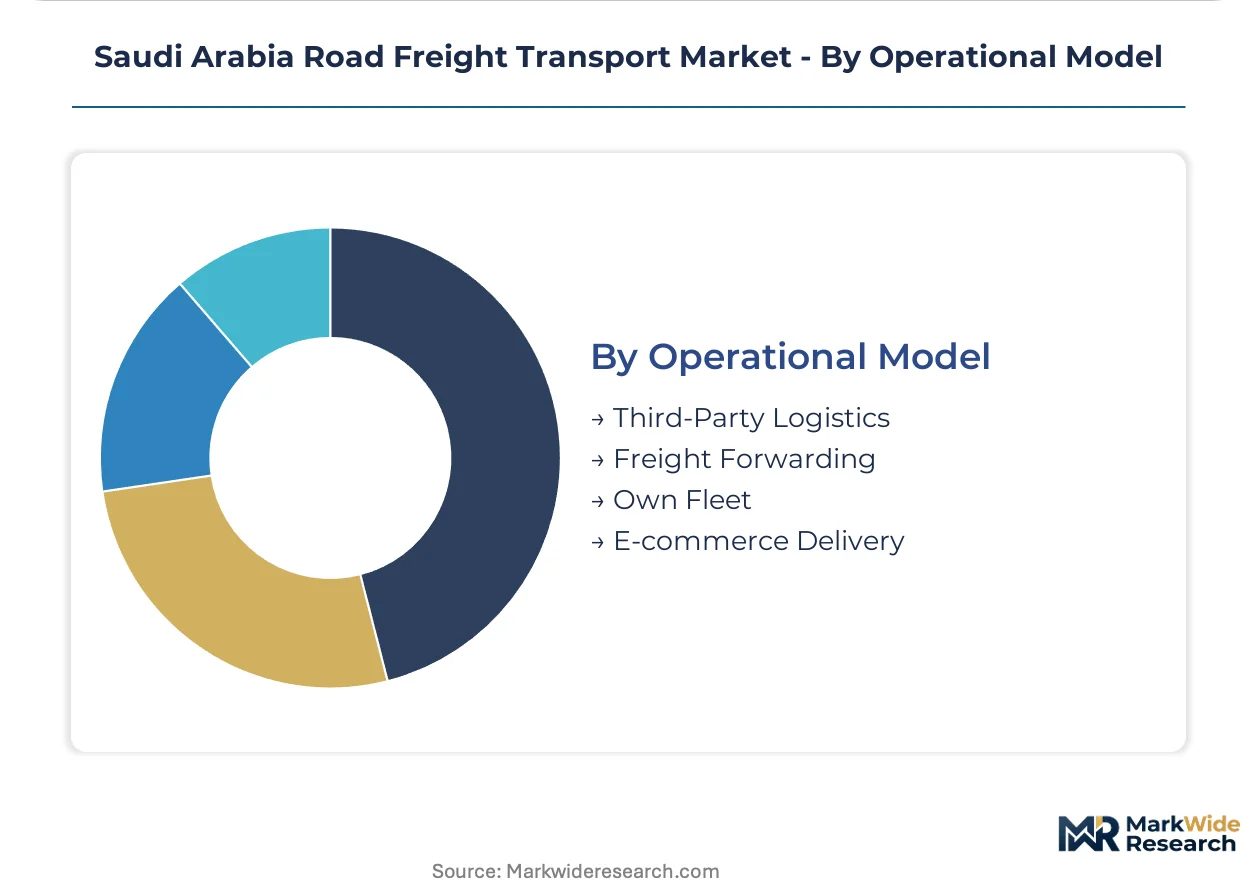
Control over assets versus outsourced brokerage determines margin capture and capital intensity profiles across the Kingdom's logistics value chain.
- Third-Party Logistics:Asset-light operators broker capacity across fragmented carrier networks with technology platforms compressing traditional margin structures. Almajdouie Group and Zahid Group anchor this tier with integrated service portfolios.
- Freight Forwarding:International shipment coordination combines air, sea, and land modes through bonded trucking corridors. King Abdulaziz International Airport cargo zone liberalization intensifies competition for pharmaceutical and electronics forwarding.
- Own Fleet:Captive trucking operations by cement producers, petrochemical majors, and retail chains internalize transport costs with direct driver employment. Visa policy fluctuations for South Asian labor expose these operations to wage inflation risk.
- E-commerce Delivery:Platform-controlled last-mile networks deploy cargo vans and light trucks with algorithmic route optimization. Noon and Amazon.sa drive consolidation of previously fragmented courier capacity.
Capital intensity peaks in Own Fleet. Technology leverage is deepest in E-commerce Delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh and Jeddah concentrate the majority of freight demand, with industrial corridors and port-linked distribution zones driving equipment deployment patterns across the Kingdom's four major economic regions.
Riyadh
The capital's industrial belt generates heavy truck demand for cement, petrochemicals, and construction materials moving along the Riyadh-Dammam corridor. Ministry of Transport smart fleet monitoring mandates require GPS and electronic logging device installation across all commercial vehicles operating within the metropolitan zone. Suly district logistics clusters concentrate less-than-truckload consolidation terminals serving supermarket chains and e-commerce fulfillment centers.
Eastern Province
Jubail and Yanbu industrial cities anchor heavy-haulage routes for SADARA petrochemical complexes and raw material inbound flows. SFDA pharmaceutical transport guidelines govern cold chain certification for temperature-sensitive cargo moving from Dammam port to regional distribution centers. Ras Al-Khair minerals processing zone absorbs specialized flatbed capacity for oversized equipment and construction materials.
Western Region
Jeddah's King Abdulaziz International Airport cargo zone liberalization intensifies bonded trucking competition for pharmaceutical and electronics shippers. General Authority of Civil Aviation logistics hub mandates require sealed container transfers between air and land modes at Obhur logistics cluster. Red Sea port hinterland distribution connects to Makkah consumption centers through dedicated corridor permits.
NEOM Northwest
The Red Sea coastal megaproject requires dedicated construction material haulage and abnormal load permits from Ministry of Transport for oversized equipment. NEOM's green hydrogen production creates potential for zero-emission trucking pilot routes with captive fuel supply infrastructure. Project logistics operators coordinate seasonal surge capacity for Red Sea Project and Qiddiya parallel developments.
Saudi Arabia Road Freight Transport Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated logistics groups commanding premium positions on cross-border GCC routes while asset-light brokers fragment around urban last-mile delivery. The vendor base organizes into three strategic archetypes: diversified conglomerates with captive maintenance infrastructure, international express carriers with temperature-controlled certification, and platform-controlled e-commerce delivery networks. Competitive moves concentrate on fleet telematics integration and pharmaceutical cold chain compliance upgrades.
Within the diversified conglomerate tier, Almajdouie Group and Zahid Group anchor positions through integrated heavy-haulage networks and captive parts distribution infrastructure. DHL Group represents the international carrier archetype with regulatory-compliant pharmaceutical logistics capabilities. These three entities exemplify how operational control over assets and specialized certification create defensible margin structures against fragmented spot-market competition.
| Leading Market Players |
|---|
| Kadi Group Holding |
| Rashed Abdul Rahman Al Rashed & Sons Group |
| Almajdouie Group |
| SMSA Express Transportation Company Ltd. |
| Aramex |
| Al Rajhi Group |
| Munawla Cargo Co. Ltd. |
| Zahid Group |
| DHL Group |
| Others |
Value Network & Pricing Analysis
Family-owned logistics conglomerates anchored in Riyadh and Jeddah exercise pricing discipline through captive maintenance networks and bonded corridor concessions, while diesel subsidy reduction timelines force supply chain reconfigurations toward fuel-efficient composite trailers and alternative propulsion pilots.
Pricing Analysis
Heavy-haulage bulk corridors generate volume leadership but compress margins, while temperature-controlled pharmaceutical logistics and dedicated contract structures capture premium yields. Three-tier pricing structure across premium certification, standard fleet, and spot-market economy levels reflects SFDA compliance burdens and telematics integration costs. Cost compression in less-than-truckload urban segments is intensifying because digital freight platforms consolidate shipper bargaining power. Supermarket chains and cement producers exhibit lowest price sensitivity through annual volume commitments, whereas fragmented spot-market brokers face acute margin pressure.
Supply Chain Analysis
Domestic-content mandates under Vision 2030 privatization reforms are reshaping fleet procurement toward Saudi-assembled chassis and locally sourced trailer components, reducing import dependency on European and East Asian OEMs. Equipment supply draws from Germany, Japan, and South Korea for Euro VI-equivalent engines and telematics systems. Steel, aluminum, and composite fiber reinforcements constitute critical raw material inputs. Single-source vulnerability concentrates in advanced refrigeration compressor technology for pharmaceutical cold chain units. Distribution runs through bonded logistics clusters at King Abdulaziz International Airport and King Khalid International Airport, with final-mile deployment controlled by e-commerce platform networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where fleet operators are pursuing captive fuel supply infrastructure and in-house driver training academies to insulate margins from diesel volatility and expatriate labor visa fluctuations.
For Market Incumbents: Deepen telematics-integrated fleet monitoring capabilities to satisfy Ministry of Transport mandates ahead of compliance deadlines, while securing exclusive concession rights on bonded trucking corridors connecting King Abdulaziz International Airport cargo zones to Jeddah port hinterland. SFDA pharmaceutical certification requirements create defensible moats against asset-light digital entrants.
For New Entrants and Emerging Players: Begin with specialized cold chain capacity serving Qassim date harvest logistics and Al-Ahsa chilled meat export corridors, where seasonal surge demand outstrips incumbent refrigerated trailer availability. Neom construction material haulage presents white-space opportunity for abnormal load permit expertise. Partner with European refrigeration OEMs for rapid SFDA compliance certification.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap fleet operators with established GCC cross-border permits and underutilized heavy-haulage assets in the Eastern Province. Long-term viability hinges on hydrogen fuel corridor positioning as NEOM green hydrogen production scales. Watch for Ministry of Transport electrification pilot tender announcements as inflection signal for alternative propulsion infrastructure deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Fleet Integration | Ministry of Transport mandates GPS and electronic logging device retrofitting across Riyadh metropolitan commercial vehicle operations. |
| SFDA Cold Chain Certification | Pharmaceutical transport guidelines create specialized service tiers with premium rate structures for temperature-controlled compliance. |
| NEOM Hydrogen Corridor Development | Green hydrogen production enables zero-emission trucking pilot routes with captive fuel supply infrastructure. |
| Air-Land Bonded Trucking Expansion | General Authority of Civil Aviation cargo zone liberalization tightens multimodal integration for pharmaceutical and electronics shippers. |
| Composite Trailer Procurement | Lightweight construction reduces diesel consumption per tonne-kilometer as fuel subsidy reduction timelines advance. |
Research Methodology
Independent corroboration across fleet operations directors, Ministry of Transport regulatory officials, pharmaceutical logistics compliance officers, and bonded zone terminal managers underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation through customs and trade data, Saudi Railway Company freight terminal statistics, General Authority of Civil Aviation cargo throughput disclosures, and SEC filings of listed logistics groups. Bottom-up equipment deployment counts triangulate against top-down freight tonnage estimates across the analysis window.
Rate-of-change decomposition separates volume growth from pricing evolution across vehicle type, service tier, end-use industry, and operational model dimensions. Modeling incorporates diesel price trajectory assumptions, visa policy scenarios for South Asian driver labor, and electrification infrastructure buildout pace. CAGRs derive from segment-level tonnage projections and revenue-per-tonne-kilometer trends. Forecast inputs include e-commerce fulfillment penetration rates, megaproject construction schedules, and SFDA regulatory enforcement intensity.
Underlying measurement precision varies by segment; heavy-haulage bulk corridors and dedicated pharmaceutical contracts carry tighter precision than fragmented spot-market less-than-truckload operations. Forecasts reflect documented assumptions regarding subsidy reduction timelines, cross-border customs protocol harmonization, and renewable energy capacity expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Romania Road Freight Transport Market
Transportation & Logistics
Train Collision Avoidance System Market
Transportation & Logistics
India Road Freight Transport Market
Transportation & Logistics
UAE Cold Chain Logistics Market
Transportation & Logistics
Asia-Pacific Customs Brokerage Market
Transportation & Logistics
Refrigerated Trailer Market
Transportation & Logistics
India less than-Truck-Load (LTL) Market
Transportation & Logistics
Refrigerated Transport Market
Transportation & Logistics
Boxcar Scars Market
Transportation & Logistics
Road Haulage Market
Transportation & Logistics
North America Long-Haul Transport Market
Transportation & Logistics
Thailand Road Freight Transport Market
Transportation & Logistics
Fuel Management Systems (FMS) Market
Transportation & Logistics
Indonesia Road Freight Transport Market
Transportation & Logistics
Mexico Cold Chain Logistics Market
Transportation & Logistics
Parking Meter Market