
 Automotive NVH Materials Market | 2026-2036
Automotive NVH Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive NVH Materials Market Analysis
Direct supply contracts between resin producers and vehicle assemblers is tilting procurement away from traditional tiered distribution. Covestro AG leverages its polyurethane foam chemistry leadership to anchor long-term supply agreements with European OEMs. BASF SE competes through integrated polyamide and rubber compound operations that sustain margin capture across vibration damping applications.
Automotive NVH materials encompass engineered substrates—polyurethane foams, ethylene-propylene-diene rubber, glass fiber-reinforced composites, and mass loaded vinyl sheeting—formulated to attenuate airborne sound, structure-borne vibration, and powertrain noise across passenger and commercial vehicle architectures. These materials typically operate across temperature ranges from minus forty to one hundred fifty degrees Celsius while maintaining acoustic absorption coefficients above point eight at critical engine frequencies. Foam formulations dominate current volume consumption due to their dual-function thermal-acoustic performance, though composite laminates represent the fastest-growing category as OEMs pursue gram-per-decibel weight reduction targets. Mass loaded vinyl occupies a stable niche in luxury vehicle segments where maximum transmission loss justifies material cost premiums.
The US NHTSA and EPA coordinate noise emission limits with fuel economy regulations that effectively mandate lighter NVH solutions, while Europe's ECE R51 and REACH chemical restrictions compel reformulation away from certain plasticizers and flame retardants. China's MIIT enforces GB standards for passenger car noise that drive domestic material certification requirements. Stakeholders must monitor evolving chemical compliance thresholds alongside electrification-driven shifts in noise source profiles from internal combustion to electric motor whine and inverter switching frequencies.
Market Dynamics
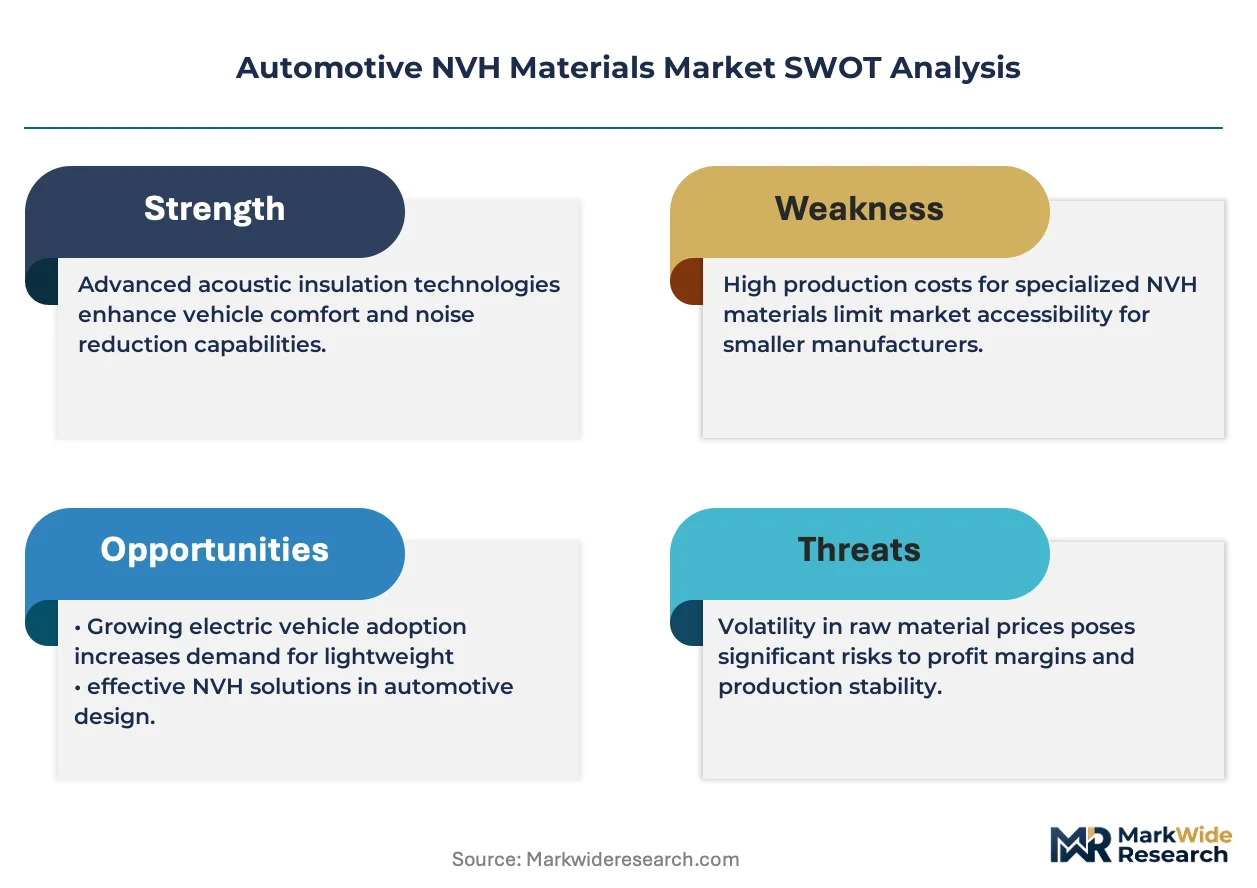
Electric vehicle platform architectures are eliminating traditional engine masking noise, forcing acoustic engineers to confront wind, tire, and inverter whine frequencies that previously hid beneath powertrain roar. This shift compresses material performance windows while demanding lighter substrates.
Growth Catalysts
- REACH chemical reformulation mandates:Europe's phased restrictions on legacy plasticizers and halogenated flame retardants are accelerating bio-based polyurethane development. Suppliers capturing certification early anchor OEM qualification pipelines.
- MIIT GB noise standards:China's passenger car noise limits are tightening test-cycle requirements, compelling domestic assemblers to source certified acoustic materials rather than commodity substitutes.
- Lightweight composite laminates:Gram-per-decibel weight targets in premium battery-electric architectures are displacing denser mass-loaded vinyl with glass fiber-polypropylene sandwiches in floor and dash applications.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane foam precursors track propylene and benzene indices, compressing converter margins when crude swings exceed fifteen percent quarterly.
- German supply corridor concentration:Premium OEM acoustic engineering centers cluster around Stuttgart, Munich, and Wolfsburg, creating geographic dependency risk for tier-two foam molders.
- Acoustic metamaterial substitution:Periodic lattice structures using air gaps rather than dense mass threaten conventional absorption materials in hood liner and wheel arch applications.
Strategic Opportunities
- India PLI scheme for automotive:Component-level incentives for advanced materials are attracting acoustic substrate investments to Tamil Nadu and Gujarat manufacturing corridors.
- Thermal-acoustic convergence:Battery pack fire barriers that simultaneously dampen cooling pump noise represent uncontracted white space in electric vehicle skateboard platforms.
- Direct OEM contracting:Resin producers bypassing tiered distribution to lock in volume commitments with vehicle assemblers are capturing margin previously allocated to intermediaries.
Industry Challenges
- Multi-physics simulation talent scarcity:Coupled acoustic-thermal-structural modeling for electric vehicle NVH requires engineers fluent in COMSOL and Actran platforms, a skill set concentrated among German and Japanese specialists.
- Dual certification timelines:Materials must simultaneously satisfy ECE R51 noise emission and REACH chemical compliance, with sequential testing extending qualification cycles to thirty-six months.
- Inverter frequency mapping:Switching harmonics from silicon carbide power electronics span 8-12 kHz, a range where conventional foam absorption coefficients drop below design thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive NVH Materials Market |
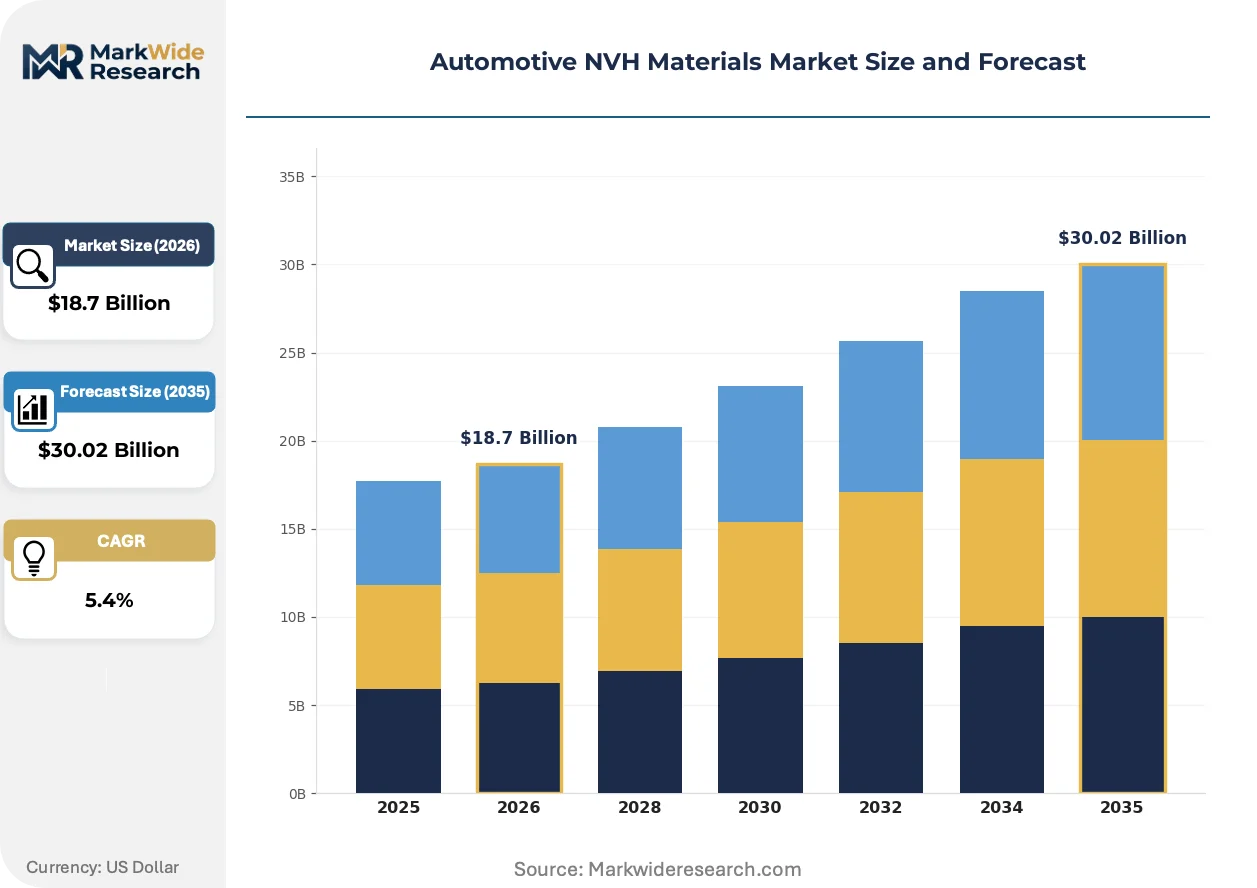
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Foam, Rubber, Composite, Mass Loaded Vinyl Application: Sound Absorption, Sound Insulation, Vibration Damping, Noise Barriers End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Installation Method: Adhesive Bonding, Mechanical Fastening, Spray Application, Preformed |
| Companies Covered | Covestro AG, ExxonMobil, BASF SE, DuPont, Lanxess AG, Dow Inc., Sumitomo Riko Company Limited, ElringKlinger AG, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive NVH Materials Market Emerging Trajectories
Material science is converging with electric vehicle thermal management, as substrates must now simultaneously attenuate sound, resist 150°C battery pack temperatures, and shed weight. This triple constraint is compressing incumbent formulations.
Recycled carbon fiber nonwoven mats is hybridizing acoustic and structural functions in load-bearing interior panels. BMW and Polestar specifications now require 30-50 percent recycled content in A-pillar and parcel shelf substrates. The technology is hybridizing what were separate damping and reinforcement layers, reducing part count and assembly labor.
ECHA's 2025 restriction roadmap on organophosphate esters is forcing reformulation of flexible polyurethane foams used in seat and headliner applications. Compounders are pivoting to phosphorus-nitrogen synergists and bio-polyols at commercial scale. European converters face the steepest retooling costs, while Asian suppliers with cleaner-sheet formulations capture qualification slots.
Fleet operators and lease aggregators now specify acoustic performance in total-cost-of-ownership tenders rather than accepting OEM standard builds. This procurement compression is elevating aftermarket upgrade demand for mass-loaded vinyl and constrained-layer damping sheets. The pattern is most visible in German executive fleet contracts, where driver retention metrics weight cabin quietude heavily.
Automotive NVH Materials Market Segmentation
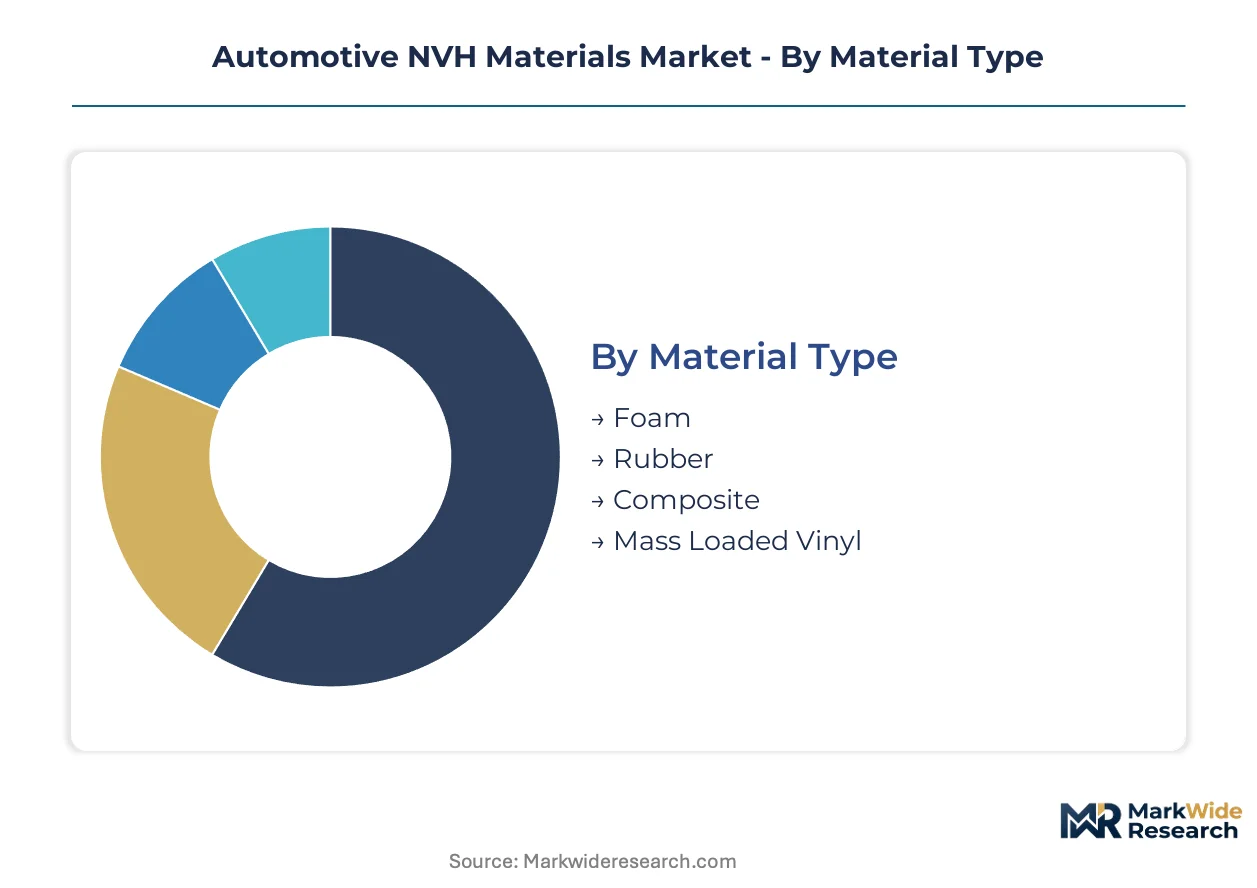
Material specifications diverge sharply between internal combustion and electric vehicle platforms, with acoustic engineers selecting substrates based on frequency targeting rather than universal application. Segmentation discipline separates commodity foam converters from composite laminate specialists capturing gram-per-decibel contracts.
Material Type:
Mature polyurethane chemistry dominates installed capacity while emerging bio-polyol formulations capture regulatory-driven qualification slots.
- Foam:Open-cell polyurethane structures deliver dual-function thermal-acoustic performance across temperature ranges from minus forty to one hundred fifty degrees Celsius. German premium OEMs concentrate demand here for seat and headliner applications, with REACH plasticizer restrictions forcing rapid reformulation toward phosphorus-nitrogen synergists.
- Composite:Glass fiber-reinforced polypropylene sandwiches displace denser alternatives in floor and dash architectures. Battery-electric platforms in Stuttgart and Munich engineering centers specify these laminates for weight-critical acoustic solutions where gram-per-decibel targets override material cost premiums.
- Rubber:Ethylene-propylene-diene compounds sustain vibration damping in suspension bushings and body mounts through compression set resistance.
- Mass Loaded Vinyl:Dense sheeting occupies stable demand in luxury vehicle segments where maximum transmission loss justifies cost.
Foam handles the majority of throughput; composite is the fastest mover on share.
Application:
Cost tier separation emerges between specification-grade solutions and commodity substitutes.
- Sound Absorption:Porous substrates convert acoustic energy to heat through viscous dissipation in fibrous or cellular structures. China's MIIT GB noise standards tighten test-cycle requirements, compelling domestic assemblers to source certified absorption materials rather than unqualified alternatives.
- Vibration Damping:Constrained-layer and extensional damping treatments attenuate structure-borne energy at body panel resonances. German OEM acoustic engineering centers cluster around Stuttgart and Wolfsburg, creating geographic concentration for high-performance damping specifications.
- Sound Insulation:Mass-spring-mass barriers block airborne transmission through impedance mismatch.
- Noise Barriers:Engine bay and wheel arch treatments target specific frequency ranges from powertrain and tire sources.
Sound absorption commands the largest specification volume; vibration damping is expanding most quickly as electric platforms eliminate engine masking noise.
End User:
Customer type determines contract structure, with direct OEM engagement displacing traditional tiered distribution channels.
- OEMs:Vehicle manufacturers specify acoustic performance at platform architecture stage, locking resin producers into long-term supply agreements. Covestro AG anchors European contracts through polyurethane foam chemistry leadership.
- Vehicle Assemblers:Contract manufacturers and joint venture operations source certified materials against MIIT GB or ECE R51 compliance requirements.
- Tier-1 Suppliers:System integrators manage subsystem acoustic performance against OEM specifications.
- Aftermarket Providers:Fleet operators and lease aggregators now specify acoustic upgrades in total-cost-of-ownership tenders, elevating demand for mass-loaded vinyl retrofits in German executive fleet contracts.
OEMs direct the largest specification authority; aftermarket providers are gaining share fastest as procurement compression elevates upgrade demand.
Installation Method:
Volume concentration favors high-throughput application technologies suitable for automated assembly lines.
- Adhesive Bonding:Pressure-sensitive and reactive adhesive systems enable lightweight attachment without mechanical penetrations. BASF SE competes through integrated polyamide and rubber compound operations that sustain margin capture across bonded vibration damping applications.
- Preformed:Compression-molded and thermoformed substrates arrive at assembly plants as finished geometry, reducing line-side labor. India's PLI scheme for automotive components attracts acoustic substrate investments to Tamil Nadu and Gujarat manufacturing corridors.
- Mechanical Fastening:Clip and fastener systems retain substrates in high-vibration environments.
- Spray Application:Liquid-applied damping compounds conform to complex geometries in body shop operations.
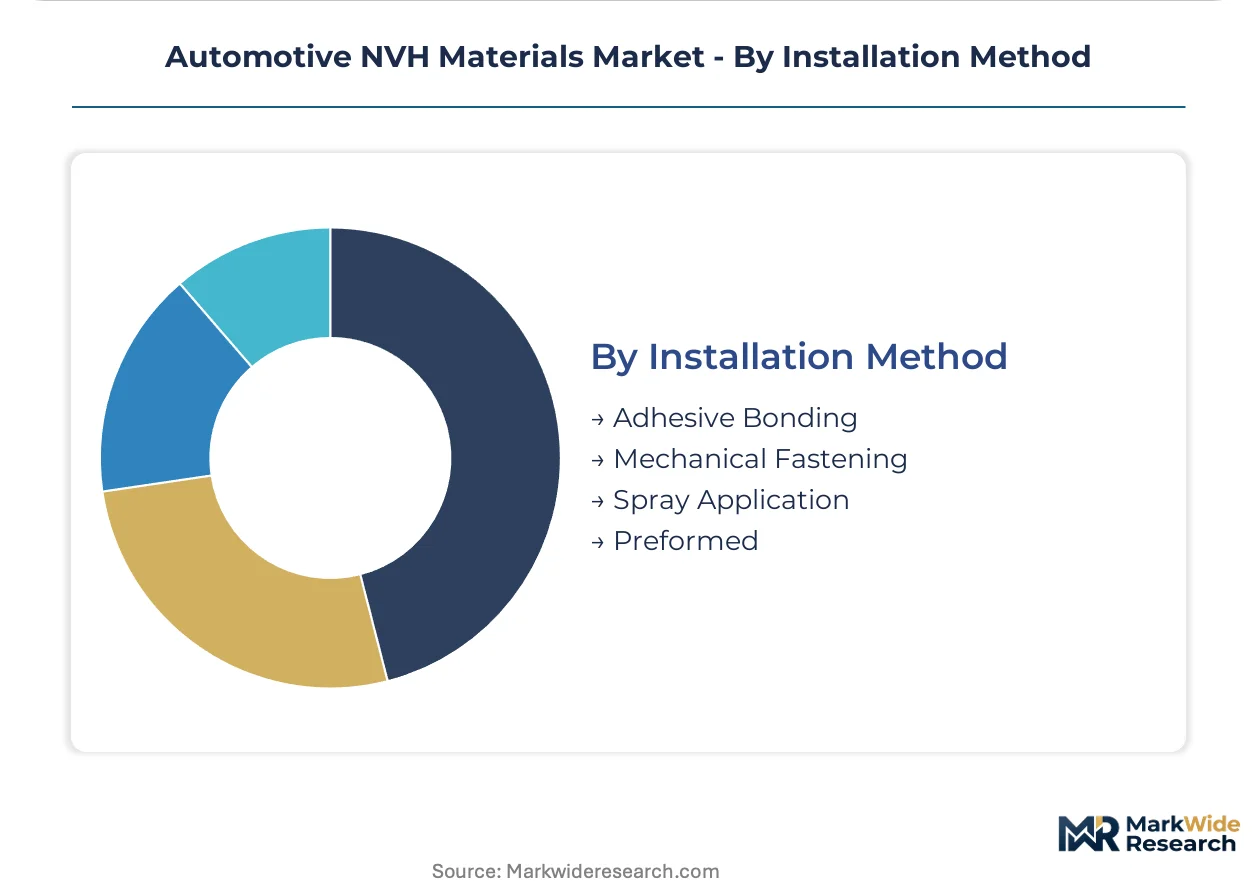
Adhesive bonding handles the dominant installation volume; preformed substrates are climbing the fastest as OEMs compress assembly cycle times.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's premium automotive corridor while Chinese domestic suppliers compete on volume at compressed margins. This asymmetry shapes procurement patterns across major manufacturing geographies.
United States
NHTSA coordinates noise emission limits with EPA fuel economy regulations that mandate lighter NVH solutions. The Inflation Reduction Act's domestic content incentives accelerate reshoring of acoustic material production. Detroit's engineering centers specify gram-per-decibel composite laminates for electric truck platforms.
Germany
REACH chemical restrictions compel reformulation away from legacy plasticizers and halogenated flame retardants. ECE R51 noise emission standards tighten material performance requirements. Stuttgart, Munich, and Wolfsburg anchor premium OEM acoustic engineering clusters where direct resin producer contracts displace tiered distribution.
China
MIIT enforces GB standards for passenger car noise that drive domestic material certification requirements. Dual carbon goals accelerate bio-polyol development in polyurethane foam chemistry. Yangtze River Delta manufacturing corridors attract acoustic substrate investments from global compounders seeking qualification slots.
India
The PLI scheme for automotive components offers tiered incentives for advanced materials manufacturing. BIS certification requirements for noise compliance elevate specification-grade sourcing over commodity substitutes. Tamil Nadu and Gujarat corridors host new foam molding and composite laminate capacity serving domestic EV platforms.
Japan
METI supports next-generation acoustic metamaterial research through public-private partnerships targeting inverter frequency challenges. JIS standards govern material qualification timelines for domestic assemblers. Kanto and Kansai engineering centers concentrate multi-physics simulation talent for coupled acoustic-thermal modeling.
Automotive NVH Materials Market Vendor Landscape
Integrated chemical conglomerates and specialized rubber compounders split the market along capability lines. The structure tilts toward consolidation at the resin production tier while fragmentation persists among foam molders and substrate converters. Two archetypes dominate: polyurethane chemistry leaders with direct OEM contracting power, and diversified materials groups capturing margin across vibration damping applications. Competitive moves center on backward integration into bio-polyol feedstocks and geographic expansion into India's PLI corridors.
Within the integrated chemistry tier, Covestro AG and BASF SE exemplify contrasting paths to margin capture. Covestro anchors European supply relationships through polyurethane foam leadership, while BASF sustains position across polyamide and rubber compound operations. DuPont occupies a specialist position in high-performance polymer formulations. These three represent the strategic archetypes reshaping procurement: direct-contract resin producers, diversified materials integrators, and performance polymer specialists.
| Leading Market Players |
|---|
| Covestro AG |
| ExxonMobil |
| BASF SE |
| DuPont |
| Lanxess AG |
| Dow Inc. |
| Sumitomo Riko Company Limited |
| ElringKlinger AG |
| 3M Company |
| Others |
Supply Flow & Price Mechanics
Undercapacity in German polyurethane foam conversion is tightening supply discipline and elevating pricing leverage for resin producers with direct OEM contracts. This utilization squeeze concentrates margin capture upstream while tier-two molders absorb feedstock volatility without corresponding price recovery mechanisms.
Pricing Analysis
Configured-to-order pricing for platform-specific acoustic laminates commands substantial premiums over standard foam formulations. Contract-based long-term offtake dominates, with price differentiation driven by REACH certification tier and volume scale commitments. Cost compression in commodity foam tiers is intensifying because propylene and benzene index volatility outpaces converter hedging capacity. Fleet operators and lease aggregators exhibit highest price sensitivity, while premium OEM engineering centers prioritize gram-per-decibel performance over unit economics.
Supply Chain Analysis
Upstream propylene oxide and polyether polyol production anchors in Germany, China, and the United States. The supply chain draws from benzene, propylene, and bio-based feedstock streams, with polyurethane precursors exhibiting single-source vulnerability for specialized isocyanate grades. Distribution runs through direct resin producer-to-OEM contracts that displace traditional tier-one system integrators in European premium corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across electric vehicle platform architectures creates specialist niches as acoustic engineers abandon universal solutions for frequency-targeted substrates. This demand-side shift rewards compounders with certification depth and composite laminate capabilities.
For Market Incumbents: Pre-empt acoustic metamaterial substitution by anchoring bio-polyol formulations in REACH-compliant qualification pipelines. Backward integration into captive polyol feedstocks defends margin position against petrochemical index volatility. Capacity addition in India's Tamil Nadu and Gujarat corridors captures PLI scheme incentives before domestic compounders consolidate position.
For New Entrants and Emerging Players: Thermal-acoustic convergence in battery pack fire barriers represents the most penetrable entry point, with uncontracted white space across electric vehicle skateboard platforms. India's BIS certification requirements for noise compliance elevate specification-grade sourcing over commodity substitutes, creating qualification arbitrage for clean-sheet compounders. A go-to-market angle anchored in COMSOL and Actran simulation partnerships bypasses multi-physics talent scarcity concentrated among German and Japanese specialists.
For Investors and Strategic Acquirers: Capital is best deployed toward diversified materials integrators with polyamide-rubber compound operations spanning vibration damping applications. Long-term viability over a five-to-ten year window favors suppliers with dual ECE R51 and REACH certification capabilities. The signal to watch is inverter frequency mapping failures above 8 kHz, where conventional foam absorption coefficients drop below design thresholds and force material replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Polyol Feedstocks | Covestro AG and BASF SE anchor margin capture against REACH plasticizer restrictions. |
| Long-term Supply Agreement with Premium OEMs | Direct contracting with Stuttgart and Munich engineering centers displaces tiered distribution. |
| Capacity Expansion in India's PLI Corridors | Tamil Nadu and Gujarat manufacturing investments capture component-level incentives for advanced materials. |
| Joint Venture for Thermal-Acoustic Substrates | Battery pack fire barriers that dampen cooling pump noise address uncontracted electric vehicle platform needs. |
| Green Manufacturing Transition | Recycled carbon fiber nonwoven mats meet BMW and Polestar specifications for 30-50 percent recycled content. |
Methodological Framework
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement leads, resin producer technical directors, and aftermarket distributors converged on the working assumptions. Primary interviews combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and vehicle production databases. Bottom-up segmentation modeling and top-down macroeconomic reconciliation triangulated volume and value estimates.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation dimensions spanning material chemistry, propulsion architecture, application frequency targeting, and regional production cluster. CAGRs derived from coupled volume trajectory and price evolution modeling incorporated gram-per-decibel weight reduction targets and REACH reformulation timelines as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in crude oil indices, automotive production cycles, or electric vehicle adoption curves would shift the trajectory. Forecasts reflect documented assumptions about certification timelines and feedstock cost pass-through mechanisms. Cross-checking against IHS Markit vehicle registration data and OEM platform disclosure filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Chassis Sensors Market
Vehicle Components
Seating and Positioning Belts Market
Vehicle Components
4-Wheeled Containers Market
Vehicle Components
Automotive Pyrofuse Market
Vehicle Components
Engine Mounting Brackets Market
Vehicle Components
Exhaust Gas Recirculation (EGR) Valve Market
Vehicle Components
United States Automotive Connectors Market
Vehicle Components
Air Brake Reservoirs Market
Vehicle Components
Portable Wheel Jack Market
Vehicle Components
Saudi Arabia Car Rental and Leasing Market
Vehicle Components
Bicycle Accessories Market
Vehicle Components
Vehicle Air Deflector Market
Vehicle Components
Global Wheel Tractor Scraper Market
Vehicle Components
China Forklift Battery Market
Vehicle Components
Trailer Canopy Market
Vehicle Components
Mining Vehicle AC Kits Market