

High Efficiency Rolling Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
High Efficiency Rolling Bearings Market Insights
Market Context
Ceramic hybrid bearing technology is reconfiguring how OEMs design high-speed rotating assemblies for electrified drivetrains. SKF leverages integrated sensor packages to differentiate its offerings in wind turbine main shaft applications. Schaeffler anchors European supply through captive ceramic ball production in Bavaria. Timken competes on tapered roller specialization for rail axlebox retrofits across North American Class I networks.
Technical Definition and Segment Structure
High efficiency rolling bearings are precision-engineered antifriction components designed to operate below standard torque thresholds through optimized internal geometry, surface finishes below 0.1 micrometer Ra, and advanced lubrication retention architectures; their primary purpose is to reduce parasitic energy loss in rotating equipment while extending maintenance intervals in inaccessible installations. Deep groove ball bearings dominate volume in small electric motor applications where standardization drives cost compression, while ceramic hybrid technology captures disproportionate margin in aerospace equipment spindles where thermal stability commands premium positioning. Cylindrical roller configurations sustain structural demand from machine tool builders seeking radial load capacity without angular contact complexity.
Regulatory Environment and Outlook
REACH chemical restrictions and the EU F-Gas Regulation are tightening lubricant formulation standards and pressuring manufacturers to validate alternative greases across operating temperature bands. The FAA and EASA airworthiness directives on bearing condition monitoring are mandating sensor integration for new aerospace equipment certifications. Stakeholders must weigh capital allocation between polymer cage R&D for rail electrification programs and brass cage retention for existing heavy machinery manufacturing installed bases.
Market Dynamics
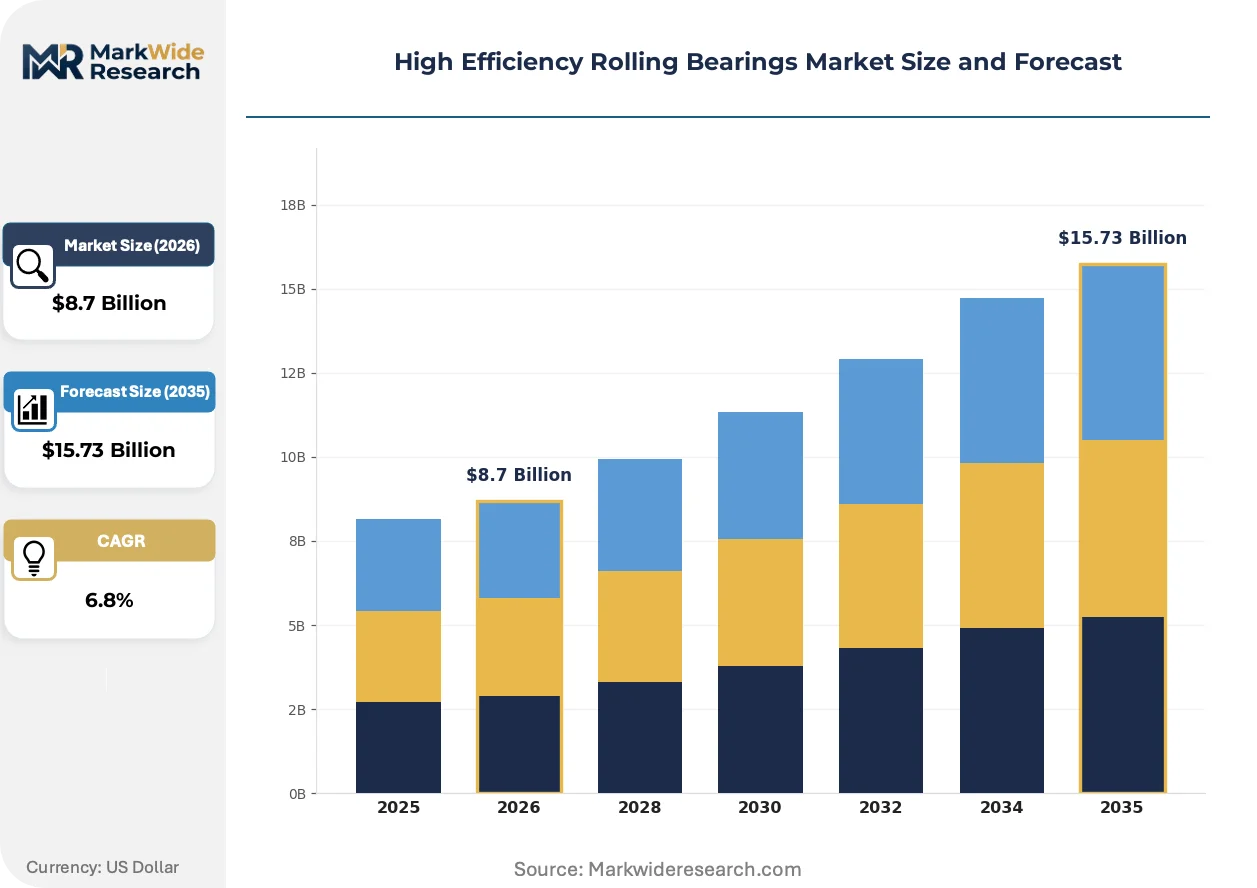
Ceramic hybrid bearing adoption is compressing maintenance cycles across wind turbine drivetrains while REACH chemical restrictions force lubricant reformulation, creating simultaneous pull and push forces on manufacturing capacity allocation.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases is accelerating material substitution toward low-friction steel grades and ceramic hybrids in precision rotating equipment across German and French manufacturing clusters.
- Wind turbine OEM procurement:Offshore wind developers are specifying ceramic hybrid main shaft bearings to extend service intervals beyond 100,000 operating hours in inaccessible nacelle installations.
- Rail electrification programs:European infrastructure operators are retrofitting axlebox assemblies with high-efficiency tapered roller configurations to reduce energy consumption in freight corridors.
Market Restraints
- Silicon nitride supply concentration:Ceramic ball production capacity concentrates in Bavaria and selected Japanese prefectures, exposing buyers to single-source risk during demand surges.
- Specialized grinding wheel scarcity:Surface finish requirements below 0.1 micrometer Ra depend on diamond abrasive supply chains vulnerable to export licensing delays.
- REACH compliance timeline:The European Chemicals Agency's substance authorization process extends lubricant validation cycles by 18-24 months, freezing product launches.
Strategic Opportunities
- Indian precision manufacturing:The country's PLI scheme for advanced automotive components is attracting bearing suppliers to establish local ceramic machining capabilities for electric vehicle drivetrains.
- Sensor-integrated condition monitoring:FAA and EASA airworthiness directives on predictive maintenance are mandating embedded vibration and temperature sensing in aerospace spindle bearings.
- Remanufacturing channel development:North American Class I railroads are unbundling bearing refurbishment from OEM service contracts, creating independent aftermarket volume.
Industry Challenges
- Ceramic metallization expertise gap:Silicon nitride-to-steel raceway interface engineering requires specialized plasma spray technicians in short supply across Midwestern US industrial corridors.
- Multi-standard certification burden:Simultaneous ISO 492 dimensional validation and AAR M-1003 quality system audits extend product qualification timelines for rail suppliers.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Efficiency Rolling Bearings Market Trends and Innovations
Integrated sensor architectures and additive manufacturing of bearing cages are redefining how rotating equipment suppliers capture value beyond component sales, shifting competitive focus toward data-enabled service models.
Embedded vibration and temperature sensing is digitizing condition monitoring across wind turbine main shaft installations. SKF and Schaeffler are shipping sensor-integrated deep groove ball bearings as standard for offshore wind OEMs. The technology is digitizing aftermarket revenue streams by enabling predictive maintenance contracts that displace scheduled replacement intervals.
The EU F-Gas Regulation's phasedown schedule is forcing lubricant manufacturers to validate PFAS-free grease formulations across -40°C to 150°C operating bands. REACH chemical restrictions compound this pressure by restricting traditional extreme-pressure additives. Aerospace equipment spindles face the tightest compliance windows, with EASA certification timelines extending 12-18 months for reformulated lubricant systems.
Wind turbine operators are unbundling bearing procurement from drivetrain OEM supply agreements, establishing direct commercial relationships with Schaeffler and Timken for main shaft and gearbox components. This disintermediation concentrates in North American offshore developments where project finance structures favor equipment supplier diversity. The pattern compresses OEM margin capture while expanding bearing manufacturers' direct service obligations.
High Efficiency Rolling Bearings Market Segmentation
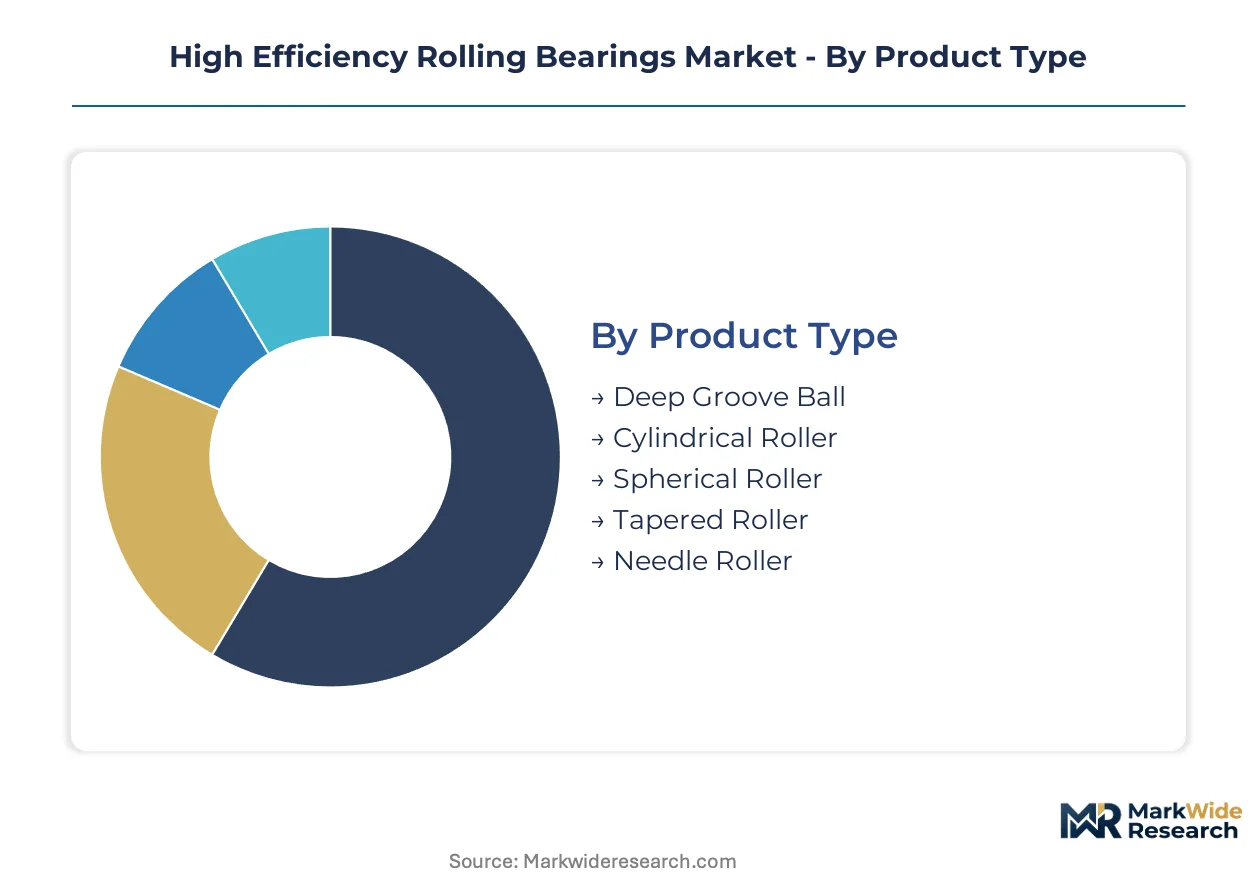
Segmentation in high efficiency rolling bearings reveals divergent replacement cycles across product architectures, with standardized ball bearings turning over in months while ceramic hybrid installations persist for decades in inaccessible wind turbine nacelles. Understanding these temporal patterns guides capacity planning and margin capture strategies for manufacturers serving electrification and precision manufacturing end-uses.
Product Type:
Cycle times vary dramatically across bearing geometries, with deep groove ball configurations experiencing rapid inventory turnover in electric motor supply chains while tapered roller variants endure extended qualification periods for rail axlebox retrofits.
- Deep Groove Ball:These bearings incorporate continuous raceway grooves accommodating combined radial and axial loads with minimal friction coefficients. Demand concentrates in German precision manufacturing clusters where small electric motor OEMs specify standardized dimensions for cost compression in industrial automation equipment.
- Cylindrical Roller:Separable inner and outer ring designs enable simplified mounting in machine tool spindles requiring high radial load capacity without angular contact complexity. Japanese machine tool builders in Aichi Prefecture anchor specification-setting for these configurations in semiconductor manufacturing equipment.
- Spherical Roller:Self-aligning double-row designs accommodate shaft deflection in heavy machinery applications with misalignment tolerance.
- Tapered Roller:Conical geometry distributes combined loads across line contact for rail freight axleboxes and automotive differentials.
- Needle Roller:Compact radial designs maximize load capacity within constrained envelope dimensions for aerospace actuation systems and textile machinery.
Deep groove ball bearings anchor the volume base while ceramic hybrid configurations gain share at the steepest rate in wind turbine main shaft applications.
Technology:
Cost tier differentiation separates commodity steel cages from premium ceramic hybrids, with polymer architectures capturing mid-tier positioning in rail electrification programs balancing weight reduction against brass cage durability.
- Steel Cage:Stamped or machined steel retainers deliver cost-optimized performance in standard industrial motors and pumps where operating temperatures remain below 120°C.
- Polymer Cage:Glass fiber-reinforced polyamide designs reduce centrifugal mass and enable grease-free operation in high-speed electric vehicle drivetrains.
- Brass Cage:Machined bronze retainers withstand elevated temperatures and aggressive lubricants in steel mill equipment and heavy machinery gearboxes.
- Ceramic Hybrid:Silicon nitride rolling elements on steel raceways achieve thermal stability and electrical insulation for aerospace spindles and offshore wind turbines.
- Magnetic Bearings:Active electromagnetic levitation eliminates mechanical contact entirely in turboexpander applications and high-speed compressors.
Steel cage technology dominates unit economics across high-volume industrial applications while ceramic hybrid configurations expand most quickly in precision rotating equipment.
Application:
Customer type segmentation separates project-financed infrastructure operators from OEM-integrated equipment builders, with aftermarket procurement patterns diverging sharply between scheduled replacement and condition-based maintenance regimes.
- Wind Turbines:Main shaft and gearbox bearings face 20-25 year service life requirements in offshore installations where crane access costs exceed component replacement expenses.
- Machine Tools:High-speed spindles demand ABEC 7-9 precision grades with ceramic hybrids capturing share in five-axis machining centers.
- Aerospace Equipment:Engine and airframe bearings require FAA and EASA certification with embedded sensors now mandated for new equipment.
- Rail Systems:Axlebox retrofits across European freight corridors prioritize energy efficiency gains from reduced rolling resistance.
- Textile Machinery:High-speed spinning frames utilize compact needle roller designs for rapid acceleration cycles.
Machine tool applications anchor manufacturing volume while wind turbine installations climb the fastest as offshore development accelerates.
End User Industry:
Supply concentration patterns align with geographic clustering of downstream manufacturing, with German automotive and French aerospace supply chains driving specification standardization across European bearing procurement.
- Power Generation:Utilities and independent power producers specify bearings for gas turbines, hydroelectric generators, and expanding renewable portfolios.
- Heavy Machinery Manufacturing:Construction and mining equipment builders prioritize sealed spherical roller designs for contaminated operating environments.
- Aviation:Commercial and defense airframers source through qualified supplier lists with AS9100 certification requirements.
- Transportation Systems:Rail operators and automotive OEMs balance initial cost against total lifecycle energy consumption metrics.
- Textile Production:Emerging Asian manufacturing hubs drive demand for high-speed bearings in spinning and weaving automation.
Heavy machinery manufacturing anchors current procurement volume while power generation applications expand most rapidly through renewable energy buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German bearing exports supply precision components to North American wind turbine OEMs while Japanese ceramic ball producers serve aerospace manufacturers across France and the United Kingdom.
Germany
Wind turbine drivetrain OEMs and rail axlebox retrofit programs absorb the majority of domestic high-efficiency bearing output. The EU F-Gas Regulation accelerates ceramic hybrid adoption in Bavarian manufacturing clusters. Schweinfurt anchors European precision bearing production, with local suppliers validating low-friction steel grades for export markets.
United States
North American Class I railroads drive demand for tapered roller configurations in freight corridor electrification. The FAA mandates sensor-integrated condition monitoring for new aerospace certifications. Midwestern industrial corridors face ceramic metallization expertise gaps that constrain local silicon nitride-to-steel interface engineering capacity.
Japan
Machine tool builders in Aichi Prefecture specify cylindrical roller bearings for semiconductor manufacturing equipment. METI industrial standards enforce precision grade validation for high-speed spindle applications. Ceramic ball production concentrates in selected prefectures, exposing buyers to single-source supply risk during demand surges.
India
The PLI scheme for advanced automotive components attracts bearing suppliers establishing local ceramic machining capabilities for electric vehicle drivetrains. BIS standards harmonization with ISO 492 dimensional protocols streamlines import substitution. Tamil Nadu and Gujarat host emerging precision manufacturing clusters serving domestic EV OEM procurement.
France
Aerospace equipment spindles command premium ceramic hybrid positioning for thermal stability in five-axis machining centers. EASA airworthiness directives extend lubricant reformulation certification timelines by 12-18 months. The Auvergne-Rhône-Alpes region concentrates precision rotating equipment supply chains serving Safran and Airbus qualified supplier networks.
High Efficiency Rolling Bearings Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around three strategic archetypes: integrated sensor-technology providers, captive ceramic material producers, and tapered roller specialization houses. Consolidation pressure concentrates in wind turbine main shaft applications where direct procurement disintermediates OEM supply chains. Dominant competitive moves include backward integration into silicon nitride ball production and geographic expansion through Indian PLI scheme participation.
Among European-based integrated technology providers, SKF and Schaeffler exemplify the sensor-embedded condition monitoring archetype, while Timken represents North American tapered roller specialization. These three occupy positions across distinct competitive vectors: SKF anchors offshore wind direct procurement relationships, Schaeffler maintains captive Bavarian ceramic production, and Timken serves Class I rail network refurbishment channels. Japanese precision houses NSK, NTN, and JTEKT sit within the machine tool and automotive supply tier, with MinebeaMitsumi representing miniature bearing scale economics. Chinese volume producers including C & U Group compete on cost-optimized deep groove ball configurations for industrial motor applications.
| Leading Market Players |
|---|
| SKF |
| Schaeffler |
| NSK |
| NTN |
| JTEKT |
| Timken |
| MinebeaMitsumi |
| RBC Bearings |
| C & U Group |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Bavarian ceramic ball production is tightening supplier pricing power while forcing buyers into multi-year offtake commitments. This utilization squeeze propagates through wind turbine OEM procurement channels, compressing margins on standard steel configurations while elevating ceramic hybrid premiums.
Pricing Analysis
The technology-generation pricing gap separates legacy steel-cage bearings from ceramic hybrid configurations and emerging magnetic levitation systems. Three-tier pricing structure across premium ceramic hybrids, mid-tier polymer cages, and economy steel retainers reflects certification grade differentiation and volume scale. Pricing pressure stems from REACH compliance costs extending lubricant validation cycles, forcing cost absorption in standard industrial tiers. Electric motor OEMs exhibit highest price sensitivity due to commoditized deep groove ball specifications, while aerospace spindle buyers prioritize thermal stability over unit economics.
Supply Chain Analysis
Tariff exposure between Germany and selected Asian ceramic producers dominates supply chain risk calculations for European wind turbine developers. Silicon nitride ball production concentrates in Bavaria, selected Japanese prefectures, and emerging Tamil Nadu machining clusters, drawing from diamond abrasive supply chains vulnerable to export licensing delays. Raw material dependencies span silicon nitride powder, low-friction steel grades, and specialized grinding wheels. Single-source vulnerability concentrates in ceramic metallization expertise for silicon nitride-to-steel raceway interfaces. Distribution runs through direct procurement relationships with wind turbine operators and OEM-integrated supply chains for rail and aerospace applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance contracts are expanding faster than hardware sales as wind turbine operators unbundle bearing procurement from drivetrain OEM agreements. This service-attach layer captures recurring revenue through sensor-integrated condition monitoring platforms.
For Market Incumbents: Pre-empt direct procurement disintermediation by embedding sensor-integrated condition monitoring as standard in offshore wind main shaft offerings. Consolidate position through captive ceramic ball capacity expansion in Bavaria to offset silicon nitride supply concentration risk. Reinforce rail axlebox retrofit channels against emerging Indian PLI scheme participants by accelerating ISO 492 and AAR M-1003 dual certification timelines.
For New Entrants and Emerging Players: Build out ceramic machining capabilities in Tamil Nadu and Gujarat to capture Indian electric vehicle drivetrain procurement under PLI scheme incentives. Target aerospace equipment spindle refurbishment as the most penetrable segment given extended EASA lubricant reformulation certification timelines creating incumbent capacity constraints. Establish go-to-market partnerships with European rail infrastructure operators seeking supplier diversity in freight corridor electrification programs.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across ceramic hybrid production lines as silicon nitride ball manufacturing scales to meet wind turbine demand. Long-term viability favors vertically integrated specialists with captive ceramic material production and sensor-embedded condition monitoring platforms. The acquisition target archetype combines Bavarian ceramic ball production assets with FAA-certified aerospace bearing portfolios. Watch for silicon nitride supply contract renegotiation frequency as an inflection indicator for pricing power shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Nitride Production | Captive ceramic ball supply secures wind turbine OEM direct procurement relationships against Japanese competitor concentration. |
| Sensor-Integrated Condition Monitoring Platform Launch | FAA and EASA airworthiness directives mandate embedded vibration sensing for new aerospace equipment certifications. |
| Indian PLI Scheme Manufacturing Footprint | Tamil Nadu and Gujarat precision clusters serve domestic electric vehicle drivetrain procurement with import substitution advantages. |
| Remanufacturing Channel Development | North American Class I railroads unbundle bearing refurbishment from OEM service contracts, creating independent aftermarket volume. |
| PFAS-Free Lubricant Validation Program | EU F-Gas Regulation and REACH chemical restrictions force reformulation across -40°C to 150°C operating bands. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with wind turbine procurement directors, rail maintenance engineers, aerospace spindle designers, and bearing manufacturing plant managers; and secondary validation through customs trade data, SEC filings of listed suppliers, METI industrial standard disclosures, and EASA airworthiness directive databases. Bottom-up and top-down triangulation cross-checked capacity utilization signals in Bavarian ceramic production against project finance structures in North American offshore wind development.
Forecast inputs span product type segmentation across deep groove ball, cylindrical roller, and ceramic hybrid configurations; technology tiers from steel cage through magnetic bearings; and application dimensions including wind turbine main shaft, machine tool spindle, and rail axlebox retrofits. CAGRs were derived from installed base replacement cycle analysis and electrification program procurement timelines. Industry-specific inputs incorporate EU F-Gas Regulation phasedown schedules and REACH substance authorization timelines across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese volume producers or Indian PLI scheme entrants would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.