
 Freight Railcar Parts Market | 2026-2036
Freight Railcar Parts Market Size, Share, and Industry Trends Forecast 2026-2036
Freight Railcar Parts Market Analysis
Digital predictive maintenance technology is fragmenting traditional aftermarket supply chains by enabling condition-based component replacement rather than scheduled overhauls. Wabtec Corporation leverages sensor-integrated braking systems to capture recurring service revenue. Trinity Industries Inc. anchors its position through backward integration into tank car and hopper manufacturing. Knorr-Bremse AG specializes in electronically controlled pneumatic brakes that compete on energy efficiency metrics.
Freight railcar parts encompass the replaceable mechanical, pneumatic, and structural subsystems—typically fabricated from AAR-certified steel alloys, polymer composites, or cast iron with Brinell hardness ratings exceeding 300 HB—that restore or enhance rolling stock performance. These components sustain the operational integrity of freight cars moving bulk commodities across Class I railroad networks. Wheels and axles constitute the largest installed base by unit volume, though composite brake shoes and polymer wear liners represent the fastest-expanding material categories as operators pursue weight reduction and extended replacement intervals. The maintenance and repair application segment commands disproportionate margin pools due to recurring demand from aging North American fleets.
The Federal Railroad Administration enforces Part 215 and Part 232 standards governing component integrity and brake system performance, while the Association of American Railroads mandates M-1003 quality certification for parts suppliers seeking network access. Transport Canada and the Transportation Safety Board coordinate cross-border harmonization of defect detection protocols, tightening compliance costs for aftermarket entrants. Stakeholders must monitor how pending rulemakings on bearing temperature monitoring and automated track inspection reshape component qualification requirements.
Market Dynamics
Condition-based maintenance protocols are restructuring procurement rhythms across North American freight rail operations. Sensor-integrated braking systems from Wabtec and electronically controlled pneumatic architectures from Knorr-Bremse are compressing traditional overhaul cycles into predictive replacement events.
Growth Catalysts
- Federal Railroad Administration Part 232 mandates:Brake system performance standards are forcing material upgrades to polymer composites and AAR-certified steel alloys across Class I networks.
- Bulk commodity shippers in Illinois, Indiana, and Ohio:Fleet renewal programs in the Midwest rail manufacturing corridor are generating concentrated demand for wheels, axles, and wear components.
- Transport Canada safety harmonization:Cross-border defect detection protocols with the U.S. are accelerating bearing temperature monitoring adoption and component qualification requirements.
Market Restraints
- AAR M-1003 certification barriers:Quality certification requirements for network access create compliance cost burdens that deter aftermarket entrants from scaling operations.
- Steel alloy input volatility:AAR-certified steel with Brinell hardness ratings exceeding 300 HB faces price instability tied to scrap metal and energy costs.
- Legacy cast iron brake shoe substitution:Composite brake shoes with extended replacement intervals are compressing unit volumes for traditional foundry suppliers.
Strategic Opportunities
- Automated track inspection rulemakings:Pending Federal Railroad Administration standards on bearing temperature monitoring will reshape component qualification and create first-mover advantages for sensor-integrated suppliers.
- Polymer wear liner penetration:Weight reduction mandates in bulk commodity transport are opening replacement markets for composite materials in hopper and tank car applications.
- Service revenue unbundling:Digital predictive maintenance platforms enable recurring revenue capture through condition-based component replacement rather than scheduled overhauls.
Industry Challenges
- Cross-border compliance synchronization:Transport Canada and U.S. Federal Railroad Administration rulemaking timelines create certification lag for dual-market suppliers.
- Sensor-legacy system integration:Electronically controlled pneumatic brakes require retrofit protocols for aging pneumatic architectures in existing fleet units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freight Railcar Parts Market |
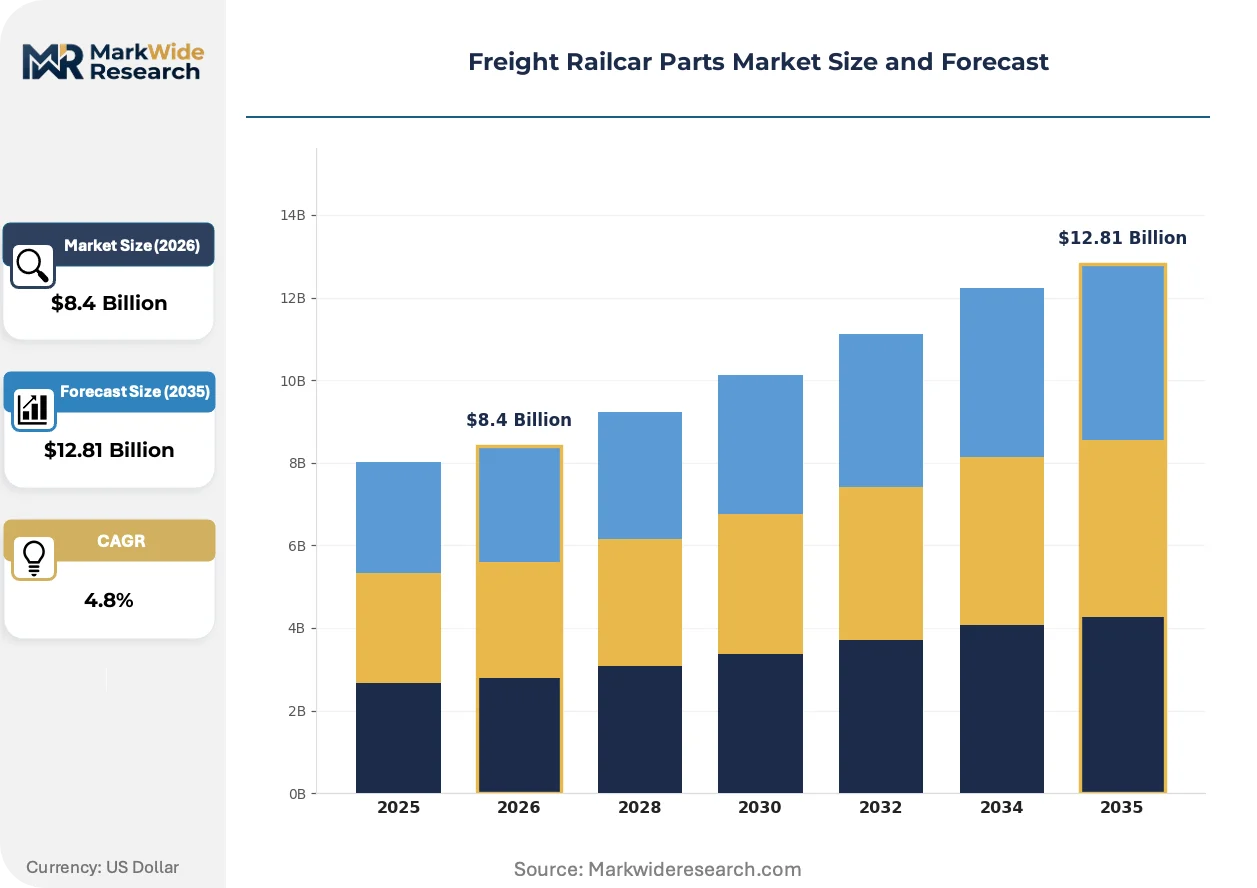
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.81 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Part Type: Wheels, Brakes, Couplers, Axles Material: Steel, Aluminum, Polymer, Composite Application: Freight Transport, Maintenance, Repair, Replacement End User: Rail Operators, Maintenance Facilities, Leasing Companies, OEMs |
| Companies Covered | Progress Rail Services Corporation, Trinity Industries Inc., Wabtec Corporation, Amsted Industries Incorporated, Westinghouse Air Brake Technologies Corporation, Knorr-Bremse AG, National Steel Car Limited, FreightCar America Inc., The Greenbrier Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freight Railcar Parts Market Emerging Trajectories
Digital infrastructure is penetrating mechanical subsystems faster than supplier business models can adapt. The shift from scheduled maintenance to condition-based replacement is compressing traditional distribution channels and fragmenting aftermarket supply chains.
Sensor-integrated brake monitoring systems are digitizing maintenance workflows across Class I railroad networks. Union Pacific and BNSF Railway are deploying axle-mounted temperature and vibration sensors at scale. This architecture is digitizing procurement from calendar-based overhauls toward event-triggered component replacement, compressing inventory cycles for traditional distributors.
The Federal Railroad Administration Part 215 component integrity standards are tightening material traceability requirements. Suppliers must now document alloy composition and hardness testing across wheel and axle production batches. Fabricators serving the Midwest rail corridor are responding by retrofitting foundries with automated inspection and digital record-keeping systems.
Class I railroads are consolidating supplier relationships around integrated service contracts rather than discrete parts procurement. Maintenance and repair operations in the U.S. Midwest are shifting toward long-term agreements covering component supply, installation, and predictive monitoring. This pattern is most visible among bulk commodity shippers operating aging hopper fleets across Illinois and Ohio.
Freight Railcar Parts Market Segmentation
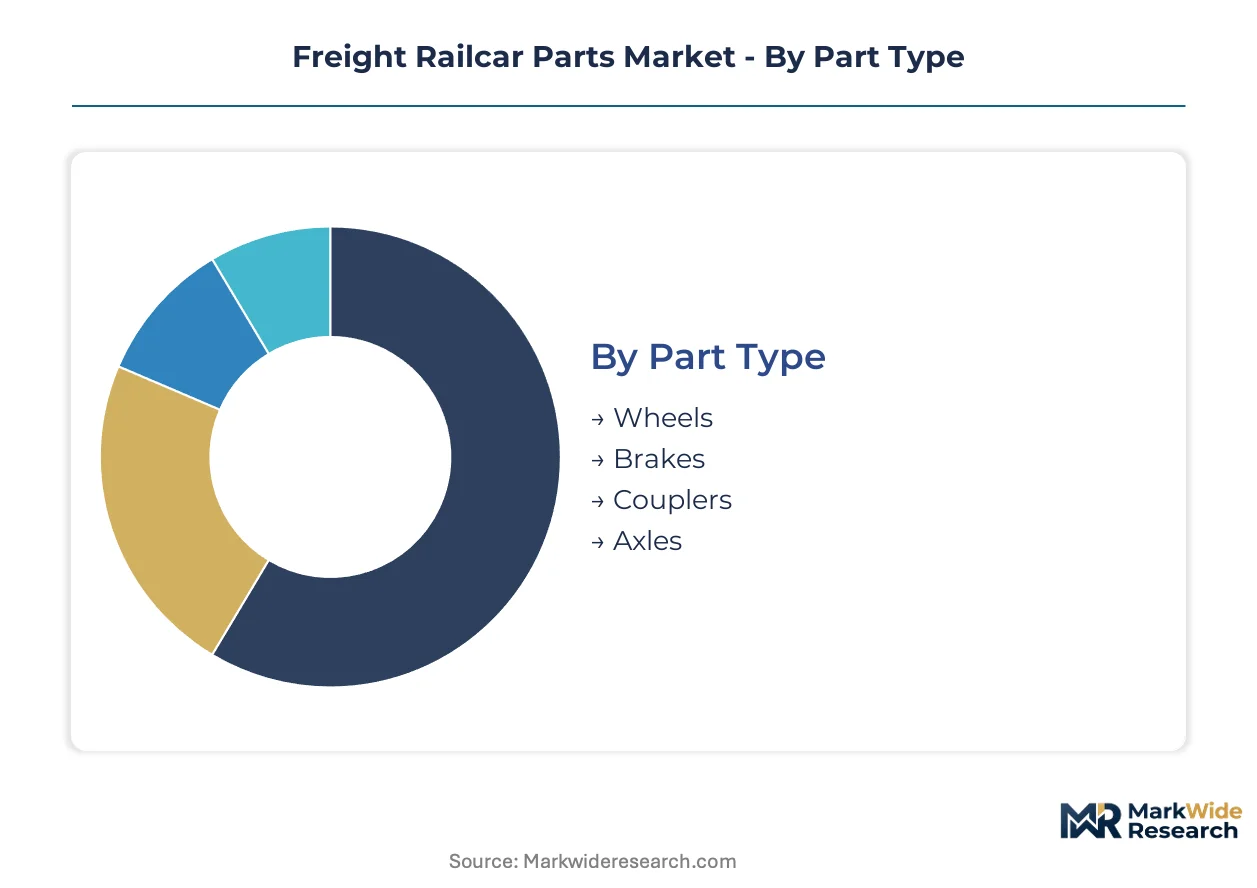
Freight railcar parts procurement patterns diverge sharply across operational contexts. Component specifications, material certifications, and replacement rhythms vary by whether parts serve new build programs, scheduled maintenance, or emergency repair scenarios.
Part Type:
Cost tier determines supplier margins and procurement consolidation intensity across mechanical subsystems.
- Wheels:Forged AAR-certified steel alloys with Brinell hardness ratings exceeding 300 HB withstand 100-ton axle loads across bulk commodity corridors. Demand concentrates in Illinois, Indiana, and Ohio as fleet renewal programs accelerate replacement cycles for aging hopper and tank car units.
- Brakes:Electronically controlled pneumatic architectures and sensor-integrated friction components are displacing legacy cast iron shoe systems. Federal Railroad Administration Part 232 mandates are forcing material upgrades to polymer composites across Class I networks, compressing traditional foundry volumes.
- Couplers:Grade E steel castings with controlled chemistry specifications absorb impact loads in unit train operations.
- Axles:Vacuum-degassed steel forgings subject to ultrasonic testing protocols maintain structural integrity under cyclic fatigue.
Wheels command the established base. The steepest expansion runs through brakes.
Material:
Application severity dictates alloy selection and certification requirements across rolling stock subsystems.
- Steel:AAR-certified alloys with documented heat treatment and hardness testing dominate wheels, axles, and structural castings. Transport Canada and Federal Railroad Administration harmonization on defect detection protocols is tightening traceability requirements for Midwest rail corridor fabricators.
- Aluminum:Extruded and forged grades reduce unsprung mass in specialized intermodal well car components. Weight reduction mandates in bulk commodity transport are opening replacement markets for lightweight alloys in hopper applications.
- Polymer:High-performance thermoset composites extend replacement intervals in brake shoes and wear liners.
- Composite:Fiber-reinforced polymer matrices penetrate non-structural applications where corrosion resistance outweighs modulus requirements.
Steel retains volume leadership. Aluminum and polymer composites are gaining share fastest.
Application:
Customer type segments procurement behavior between capital-intensive new builds and recurring aftermarket demand.
- Freight Transport:Original equipment specifications for new railcar builds require full AAR M-1003 certification and lot-controlled material documentation. OEMs and leasing companies in the U.S. Midwest corridor concentrate demand for wheels, axles, and couplers in concentrated procurement windows.
- Maintenance:Scheduled overhaul programs at Class I railroad shops generate predictable demand for wear components. Union Pacific and BNSF Railway are consolidating supplier relationships around integrated service contracts covering component supply, installation, and predictive monitoring.
- Repair:Event-triggered replacement responds to defect detection alerts and field failures.
- Replacement:Condition-based protocols triggered by sensor-integrated brake monitoring systems compress traditional inventory cycles.
Maintenance commands the established base. The steepest expansion runs through replacement.
End User:
Volume concentration and technical capability separate integrated operators from fragmented service providers.
- Rail Operators:Class I railroads including Union Pacific and BNSF Railway deploy predictive maintenance platforms at scale. These operators are digitizing procurement from calendar-based overhauls toward event-triggered component replacement, fragmenting traditional aftermarket supply chains.
- Maintenance Facilities:Independent and railroad-affiliated shops perform scheduled overhauls and defect remediation across aging North American fleets.
- Leasing Companies:Fleet owners managing railcar assets on behalf of bulk commodity shippers coordinate multi-year renewal programs.
- OEMs:Railcar builders in the Illinois-Indiana-Ohio manufacturing corridor source certified components for new production.
Rail operators command the established base. The steepest expansion runs through maintenance facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States exports precision-machined wheelsets and AAR-certified brake components to Canadian and Mexican Class I railroads through cross-border procurement agreements. Bulk commodity corridors spanning the Midwest manufacturing belt concentrate demand generation and parts fabrication capacity.
United States
Class I railroads including Union Pacific and BNSF Railway operate sensor-integrated predictive maintenance platforms across 140,000 route-miles. Federal Railroad Administration Part 232 brake mandates and Part 215 component integrity standards enforce polymer composite adoption and material traceability. The Illinois-Indiana-Ohio corridor anchors domestic fabrication, with foundries in Chicago, Fort Wayne, and Cleveland supplying certified wheels and axles.
Canada
Transport Canada harmonizes defect detection protocols with U.S. standards, accelerating bearing temperature monitoring adoption across Canadian National and Canadian Pacific Kansas City networks. The Transportation Safety Board coordinates cross-border safety rulemakings that tighten component qualification timelines. Ontario's Hamilton-Toronto manufacturing cluster supplies forged axles and coupler castings to integrated North American fleets.
Mexico
Ferromex and Kansas City Southern de México expand unit train operations for automotive and agricultural exports, generating aftermarket demand for wear components. Secretariat of Communications and Transportation rail safety directives align with U.S. braking standards under USMCA trade provisions. Monterrey's steel fabrication district produces Grade E coupler castings and structural components for binational supply chains.
Germany
Knorr-Bremse AG anchors European electronically controlled pneumatic brake technology, exporting control systems to North American retrofit programs. KBA rail vehicle regulations and EU safety standards for freight interoperability shape component design specifications. Saxony's rail technology cluster around Dresden and Leipzig supplies precision-machined pneumatic valves and sensor modules.
China
MIIT rail equipment certification standards and GB/T railway component specifications govern export-qualified production for international tendering. State-owned rolling stock manufacturers source certified steel forgings from domestic suppliers for overseas project deliveries. Shandong Province's heavy industry corridor around Jinan fabricates wheelsets and brake rigging for Belt and Road rail infrastructure contracts.
Freight Railcar Parts Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. Consolidation around integrated service contracts is compressing traditional parts distribution, while AAR M-1003 certification barriers protect incumbent fabricators from aftermarket entrants. Three archetypes dominate: vertically integrated railcar builders capturing captive component demand; brake-system specialists monetizing sensor-integrated recurring revenue; and independent foundries supplying certified steel forgings to maintenance networks. Competitive moves center on backward integration into material supply and predictive maintenance platform deployment.
Among North American integrated manufacturers, Trinity Industries Inc. and The Greenbrier Companies exemplify railcar-builder archetypes with captive parts demand from owned leasing fleets. Wabtec Corporation occupies a position on the technology-vector, representing sensor-integrated system suppliers. Knorr-Bremse AG anchors the European specialist tier. These three names illustrate how geographic origin and corporate structure map to strategic positioning without requiring granular operational claims.
| Leading Market Players |
|---|
| Progress Rail Services Corporation |
| Trinity Industries Inc. |
| Wabtec Corporation |
| Amsted Industries Incorporated |
| Westinghouse Air Brake Technologies Corporation |
| Knorr-Bremse AG |
| National Steel Car Limited |
| FreightCar America Inc. |
| The Greenbrier Companies |
| Others |
Supply Flow & Price Mechanics
The Illinois-Indiana-Ohio manufacturing corridor concentrates AAR-certified steel forging capacity, giving Midwest fabricators pricing leverage over maintenance networks dependent on certified wheel and axle supply. Foundries in Chicago, Fort Wayne, and Cleveland capture premium margins through M-1003 quality certification barriers that lock out unqualified competitors from Class I procurement pools.
Pricing Analysis
Sensor-integrated brake systems command substantial premiums over legacy cast iron architectures, while electronically controlled pneumatic components occupy a mid-tier position above conventional friction materials. Three-tier pricing structure across premium, standard, and economy levels reflects AAR certification grade, volume commitment scale, and after-sales service bundling. Cost compression in standard-grade castings is intensifying because composite brake shoes with extended replacement intervals erode foundry volumes. Bulk commodity shippers operating aging hopper fleets exhibit highest price sensitivity, whereas Class I railroads deploying predictive maintenance platforms prioritize performance metrics over unit cost.
Supply Chain Analysis
Export control regimes on precision sensor technology limit flows of bearing temperature monitoring systems from Germany and China into North American retrofit programs. AAR-certified steel supply concentrates in the United States, Canada, and Mexico, with vacuum-degassed forgings drawing from scrap metal and energy-intensive production inputs. Single-source vulnerability runs through specialized polymer composite formulations for brake shoes. Distribution runs through integrated service contracts rather than discrete parts procurement, compressing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified AAR M-1003 certification capacity remains scarce relative to demand from aging North American fleets, creating structural leverage for holders of accredited production assets. The gap between certified fabricators and maintenance network requirements widens as Transport Canada and Federal Railroad Administration harmonization tightens qualification timelines.
For Market Incumbents: Insulate margin positions by deepening backward integration into AAR-certified steel alloy supply and deploying predictive maintenance platforms that capture recurring service revenue. Lock in long-term agreements with Union Pacific and BNSF Railway before sensor-legacy system integration costs erode switching barriers. Prioritize certification investment in bearing temperature monitoring components ahead of pending Federal Railroad Administration rulemakings. For New Entrants and Emerging Players: Independent maintenance facilities in the U.S. Midwest represent the most penetrable entry point for aftermarket brake shoe and wear liner supply, as Class I consolidation leaves fragmented service providers underserved. Target polymer composite penetration in hopper and tank car applications where weight reduction mandates open replacement markets. Pursue white-label manufacturing partnerships with Ontario's Hamilton-Toronto forging cluster to bypass AAR M-1003 certification barriers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because Federal Railroad Administration and Transport Canada harmonization creates durable certification moats around incumbent fabricators. Acquisition targets should display integrated sensor-legacy capabilities or captive steel alloy supply. Monitor pending automated track inspection rulemakings as the inflection signal for first-mover advantages in component qualification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Alloy Supply | Captive AAR-certified forging capacity insulates margins from scrap metal volatility. |
| Sensor-Integrated Brake System Deployment | Wabtec and Knorr-Bremse architectures compress overhaul cycles into recurring revenue streams. |
| AAR M-1003 Certification Investment | Quality accreditation locks out unqualified competitors from Class I network access. |
| Integrated Service Contract Consolidation | Long-term agreements with bulk commodity shippers displace discrete parts distribution. |
| Polymer Composite Wear Liner Expansion | Weight reduction mandates in Illinois-Ohio hopper fleets open replacement material markets. |
Methodological Framework
A spread of perspectives from Class I railroad procurement officers, AAR-certified foundry operations managers, maintenance facility directors, and polymer composite R&D leads converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through Association of American Railroads M-1003 certification databases, Federal Railroad Administration Part 215 and Part 232 regulatory filings, Transport Canada safety directives, and SEC disclosures from listed railcar builders. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the North American freight rail network.
Demand-supply balance dynamics shaped the analytical framework, with freight car fleet age distributions, commodity transport volume patterns, and regulatory compliance timelines driving replacement cycle assumptions across the projection horizon. Segmentation dimensions modeled include part type, material certification grade, application context, and end-user technical capability. CAGRs were synthesized from installed base depreciation curves and technology substitution rates. Industry-specific forecast inputs incorporated bearing temperature monitoring adoption trajectories and polymer composite penetration in wear component applications.
Practitioners should monitor Federal Railroad Administration rulemaking timelines, Transport Canada defect detection protocol harmonization, and steel alloy input cost volatility for early signals of forecast deviation. Material shifts in automated track inspection mandates or AAR certification requirement changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Vehicle Exhaust Hose Market
Vehicle Components
Mechanical Control Cables Market
Vehicle Components
Railway Brake Pads Market
Vehicle Components
Off-Highway Diesel Engine Market
Vehicle Components
Steering Gear Market
Vehicle Components
HCV Axles Market
Vehicle Components
Automotive Air Flow Sensors Market
Vehicle Components
Automotive Wheel Speed Sensor Market
Vehicle Components
Automotive Powertrain Sensors Market
Vehicle Components
GCC Automotive Connectors Market
Vehicle Components
Tricycle Vending Cart Market
Vehicle Components
Bicycle Lights Market
Vehicle Components
Europe Automotive Lightweight Car Market
Vehicle Components
Hydrostatic Transmission Market
Vehicle Components
Idler Arm Market
Vehicle Components
Truck Suspension System Market