
 Fuel Pumps Market | 2026-2036
Fuel Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Pumps Market Analysis
Electrification of fuel delivery architectures is rewriting component requirements across vehicle platforms. Robert Bosch GmbH leverages its integrated powertrain portfolio to anchor supply relationships with European and Asian OEMs. Denso Corporation sustains manufacturing scale through captive semiconductor sourcing for pump motor controllers. Continental AG competes on mechatronic module integration, combining sensors and actuators within single fuel pump assemblies.
A fuel pump is a mechanical or electromechanical device that pressurizes and transfers liquid fuel from storage tanks to engine combustion chambers, typically operating at pressures between 3 bar and 6 bar for port-injected gasoline systems and exceeding 15 bar for gasoline direct injection. Its primary commercial purpose is to ensure precise fuel metering that optimizes combustion efficiency while minimizing evaporative emissions. Positive displacement pumps occupy the largest share of automotive applications due to their consistent flow rates across varying engine loads. Electric pump technology is expanding fastest as 48-volt mild-hybrid architectures proliferate, displacing mechanical cam-driven units. Submersible pump configurations dominate aftermarket replacement cycles because tank-integrated designs reduce cavitation and noise.
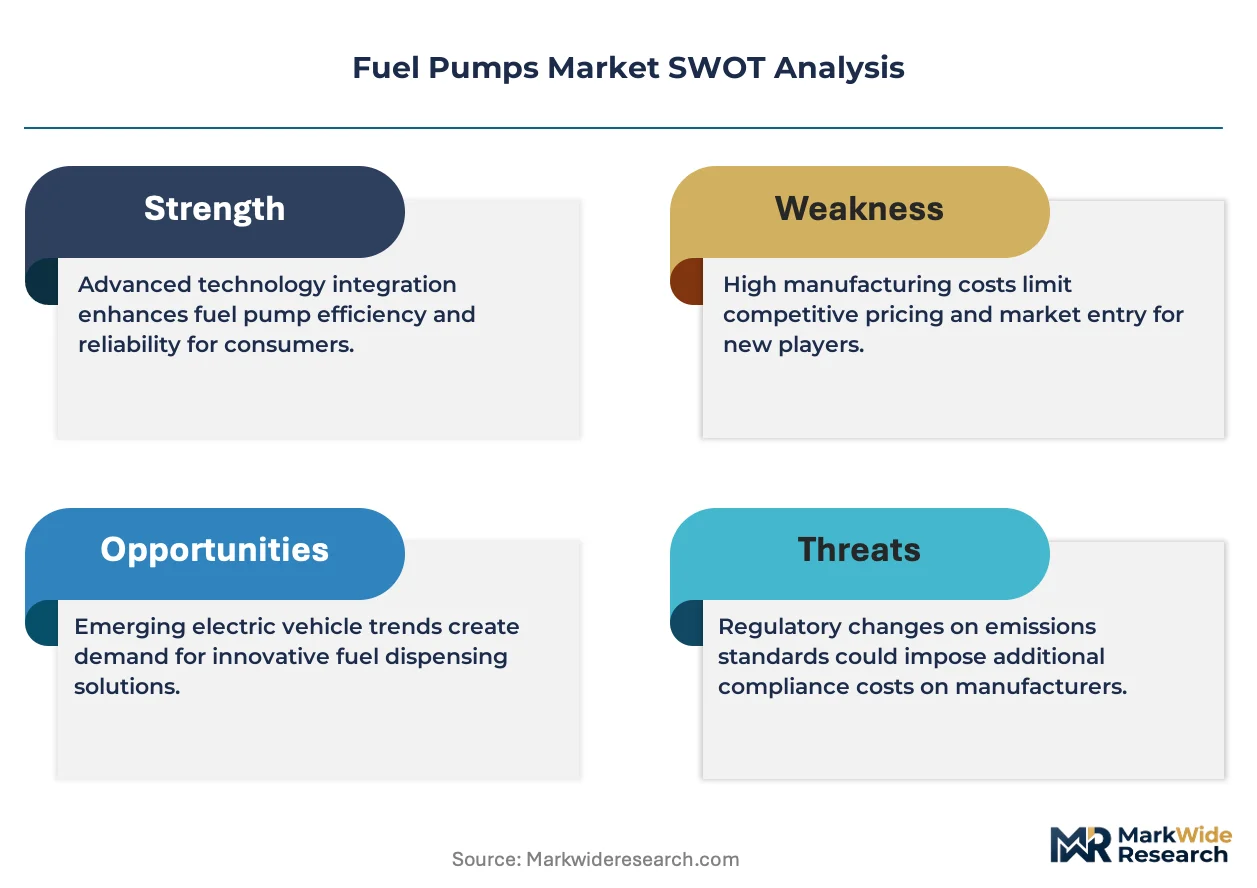
EPA tailpipe standards, Euro 6d emissions frameworks, and China's GB 18352.6-2016 regulations collectively mandate tighter evaporative emission controls and onboard diagnostic monitoring of fuel system integrity. These requirements force pump manufacturers to invest in sealed bearing technologies, leak detection sensors, and materials compatible with ethanol-blended and biodiesel fuels. Stakeholders must monitor how upcoming particulate number limits for gasoline engines reshape high-pressure pump specifications and retrofit obligations across installed vehicle fleets.
Market Dynamics
Electrification of fuel delivery architectures is collapsing the installed base of mechanical cam-driven pumps as 48-volt mild-hybrid platforms expand across passenger vehicle lineups. This technology shift forces suppliers to reconfigure production assets and recalibrate component specifications for higher-pressure electric architectures.
Growth Catalysts
- EPA Tier 3 tailpipe standards:Tighter evaporative emission controls mandate sealed bearing technologies and leak detection integration in fuel pump assemblies for US-bound vehicles.
- Gasoline direct injection proliferation:High-pressure pump requirements exceeding 15 bar are expanding procurement volumes for precision-machined positive displacement units across powertrain portfolios.
- China and India passenger vehicle production:Expanding manufacturing footprints in these markets concentrate demand for tank-integrated submersible pump configurations.
Market Restraints
- Semiconductor supply concentration:Captive sourcing of motor controller chips by integrated tier-one suppliers limits second-tier pump manufacturers' access to critical electronic components.
- Ethanol compatibility material costs:Fluoropolymer seals and stainless steel internals required for E85 compatibility inflate bill-of-materials costs versus conventional gasoline-rated components.
- Mechanical pump aftermarket collapse:Shrinking replacement cycles for cam-driven units as electric architectures dominate new vehicle production erode traditional service-channel revenue pools.
Strategic Opportunities
- India fuel retail infrastructure modernization:Upgraded dispensing systems and underground storage tank retrofits create pull for commercial-grade submersible turbine pumps at retail stations.
- 48-volt mild-hybrid platform expansion:Convergence of electric pump technology with integrated thermal management modules enables mechatronic assembly bundling opportunities.
- Germany Euro 6d-ISC-FCM implementation:In-service conformity monitoring mandates create aftermarket diagnostic equipment and sensor retrofit demand across installed fleets.
Industry Challenges
- High-pressure machining capability scarcity:Precision grinding and honing expertise for 15+ bar pump housings concentrates among specialized tier-two suppliers, constraining capacity scaling.
- Multi-fuel certification timeline compression:Simultaneous validation against gasoline, ethanol blends, and biodiesel specifications extends development cycles and testing expenditure.
- Legacy vehicle software integration:Electric pump controller communication protocols must backward-compatible with older engine control unit architectures, complicating firmware architecture decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Pumps Market |
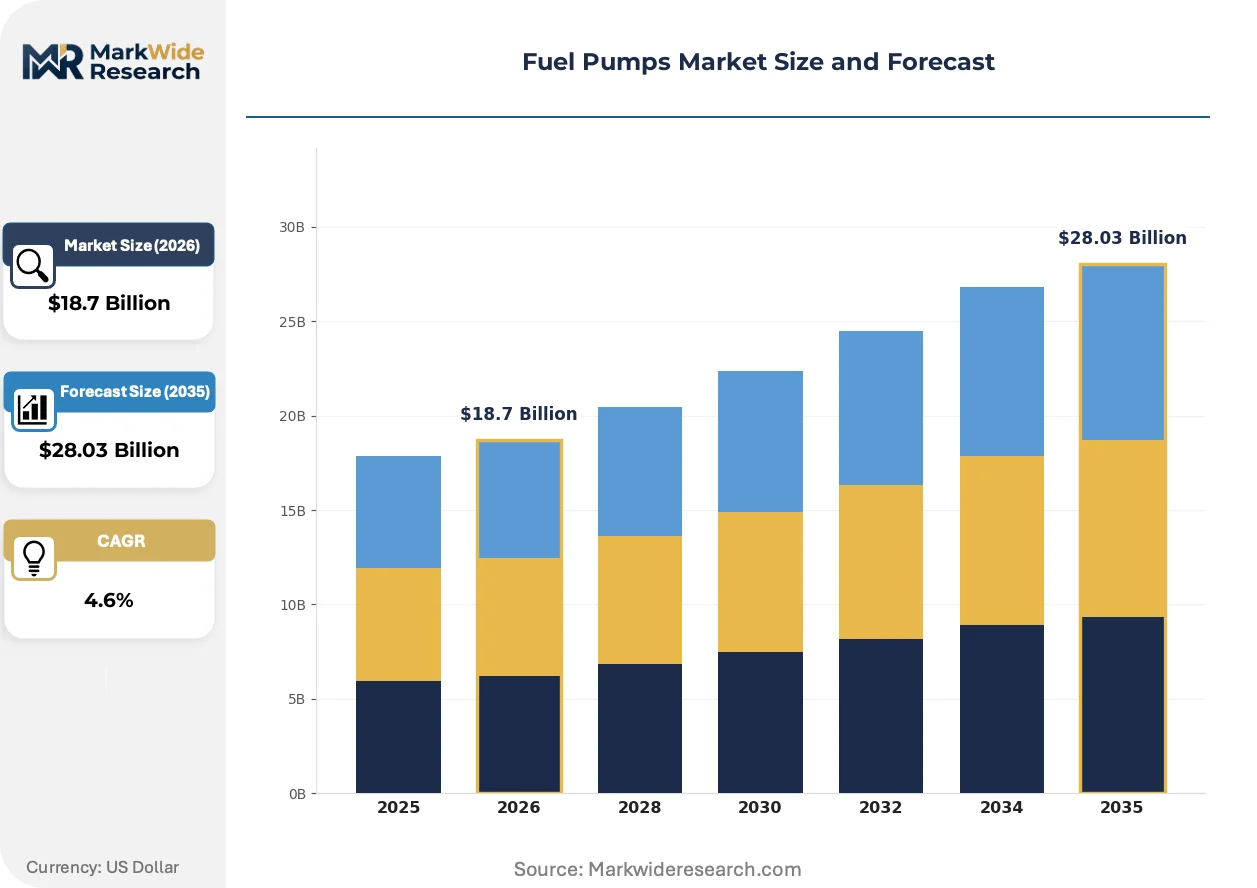
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Positive Displacement Pumps, Centrifugal Pumps, Submersible Pumps, Diaphragm Pumps End User: Gas Stations, Industrial, Automotive, Marine Technology: Electric Pumps, Hydraulic Pumps, Mechanical Pumps, Digital Pumps Application: Petrol, Diesel, Biofuel, Industrial Fuels |
| Companies Covered | Robert Bosch GmbH, Denso Corporation, Continental AG, Aisin Corporation, Delphi Technologies, TI Fluid Systems plc, General Motors Company, Walbro LLC, Pricol Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Pumps Market Emerging Trajectories
Active redesign of fuel system architectures is compressing component count and merging functions previously handled by discrete parts. Suppliers are responding with integrated mechatronic modules that combine sensing, actuation, and control within single assemblies.
Brushless DC motor technology is collapsing the distinction between pump and controller hardware in next-generation fuel delivery systems. Tier-one suppliers are adopting these motors across premium and mid-range vehicle platforms to meet noise-vibration-harshness targets. The structural consequence is elimination of separate motor-controller procurement relationships as single-source integrated units become standard.
China's GB 18352.6-2016 emissions framework and its subsequent amendments are tightening onboard diagnostic requirements for fuel system integrity monitoring. Pump manufacturers must now embed pressure sensors and leak detection algorithms within pump assemblies rather than relying on external engine control unit calculations. Passenger vehicle platforms bound for the Chinese market are prioritizing these smart pump configurations in their sourcing specifications.
Fleet operators and independent repair channels are compressing replacement part sourcing cycles through direct e-commerce procurement. Traditional wholesale distribution through jobber networks is losing share to platform-based purchasing in North American and European aftermarket segments. This pattern is most pronounced in commercial vehicle applications where fleet maintenance departments centralize purchasing decisions and prioritize availability over brand loyalty.
Fuel Pumps Market Segmentation
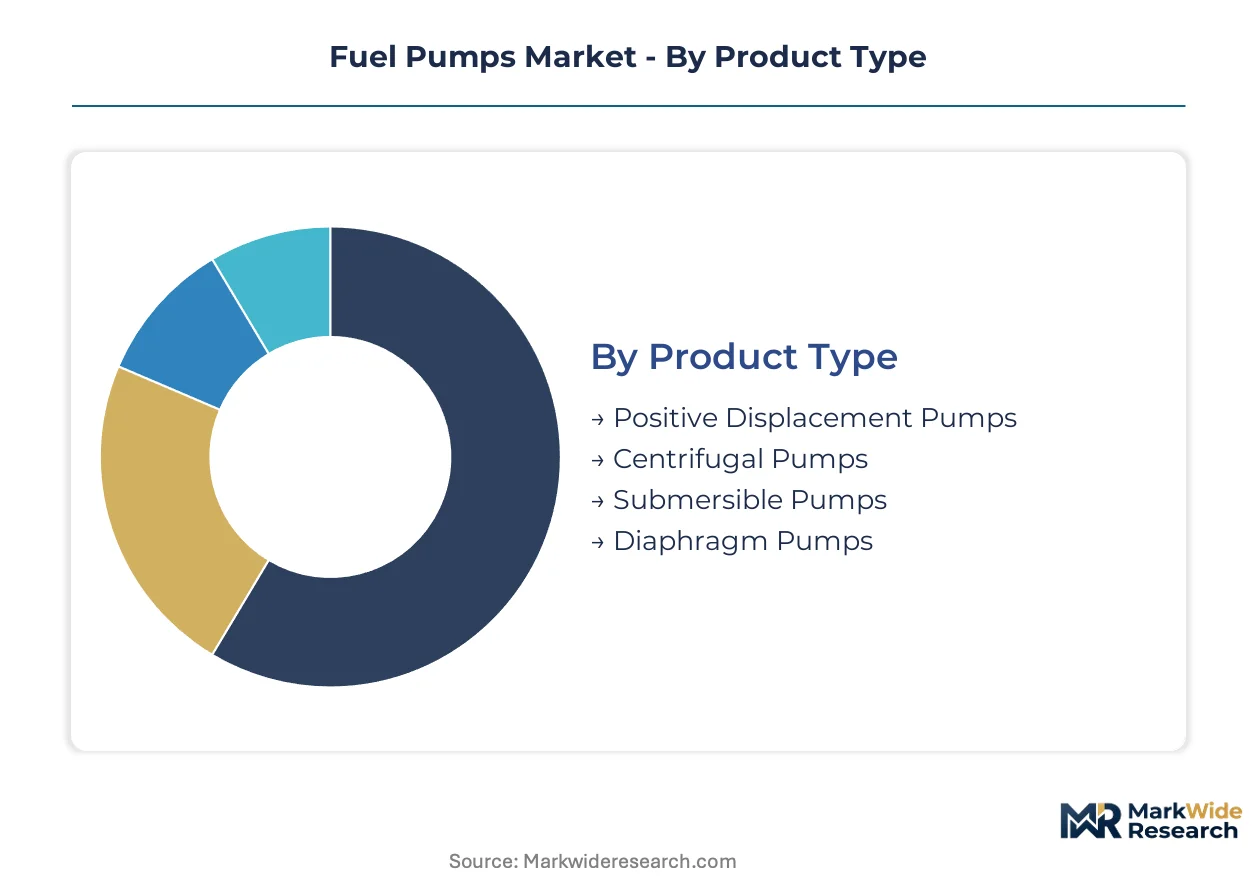
Fuel pump procurement patterns diverge sharply across product architectures, end-use environments, and technology generations. Segment boundaries determine warranty exposure, replacement cycle frequency, and supplier qualification requirements for component manufacturers.
Product Type:
After-sales service intensity varies dramatically across pump architectures, with tank-integrated designs demanding specialized diagnostic equipment and external units enabling faster field replacement.
- Positive Displacement Pumps:These units trap fixed fuel volumes between rotating elements or reciprocating pistons, delivering consistent flow rates regardless of downstream pressure fluctuations. Automotive OEMs in Germany and China specify these for gasoline direct injection systems where precision metering at 15+ bar pressures is mandatory for EPA Tier 3 and Euro 6d compliance.
- Submersible Pumps:Motor and pump assemblies mount directly inside storage tanks, eliminating suction lift limitations and reducing cavitation risk. Fuel retail operators across India prioritize these configurations for underground tank retrofits under infrastructure modernization programs, though sealed bearing replacement requires complete tank access.
- Centrifugal Pumps:Rotating impellers accelerate fuel radially for high-flow, low-pressure transfer applications. Marine bunkering operations and bulk fuel terminals specify these for volume loading where precision metering is secondary to throughput speed.
- Diaphragm Pumps:Flexible membranes isolate pumping chambers from drive mechanisms, enabling leak-free handling of corrosive biofuel blends. Agricultural equipment and small-engine applications favor these for ethanol compatibility without seal degradation.
By volume, Positive Displacement Pumps leads. By growth pace, Submersible Pumps is ahead.
End User:
Customer procurement sophistication spans from centralized fleet purchasing departments to fragmented independent repair channels, reshaping distribution economics and margin capture.
- Automotive:Passenger vehicle and commercial truck manufacturers specify pump modules through multi-year platform contracts. China's expanding production footprints and India's rising vehicle output concentrate procurement volumes for electric pump configurations compatible with 48-volt mild-hybrid architectures.
- Gas Stations:Retail fuel dispensing infrastructure requires ATEX-certified submersible turbine pumps with integrated leak detection. India's fuel retail modernization creates replacement demand as older underground storage systems reach end-of-service life.
- Industrial:Manufacturing facilities, power generation plants, and mining operations deploy heavy-duty pumps for bulk fuel transfer and process heating. Reliability-centered maintenance contracts dominate procurement, favoring suppliers with regional service networks.
- Marine:Commercial shipping and recreational boating applications demand corrosion-resistant materials for saltwater environments. IMO 2020 sulfur regulations shifted bunker fuel specifications, requiring pump material upgrades for low-sulfur distillate compatibility.
Automotive commands the largest revenue pool. Gas Stations exhibits the steepest expansion trajectory as retail infrastructure upgrades accelerate.
Technology:
Technology transitions are collapsing legacy supply relationships as integrated mechatronic modules displace discrete component procurement.
- Electric Pumps:Brushless DC motors with integrated controllers deliver precise speed modulation for variable engine demand. These dominate new vehicle platforms as mechanical cam-driven units phase out, though semiconductor supply constraints limit second-tier manufacturer participation.
- Mechanical Pumps:Engine-driven cam or belt arrangements persist in legacy vehicle fleets and cost-sensitive small-engine applications. Aftermarket replacement volumes are contracting as electric architectures capture production share.
- Hydraulic Pumps:Fluid-power actuation serves specialized industrial and marine applications requiring explosion-proof operation or extreme pressure ratios. Niche specification limits addressable market scale.
- Digital Pumps:Smart configurations embed pressure sensors, flow meters, and diagnostic algorithms for onboard fuel system integrity monitoring. China's GB 18352.6-2016 emissions framework mandates these capabilities for vehicles bound for that market.
Electric Pumps holds dominant share. Digital Pumps is climbing the fastest as regulatory diagnostic requirements tighten.
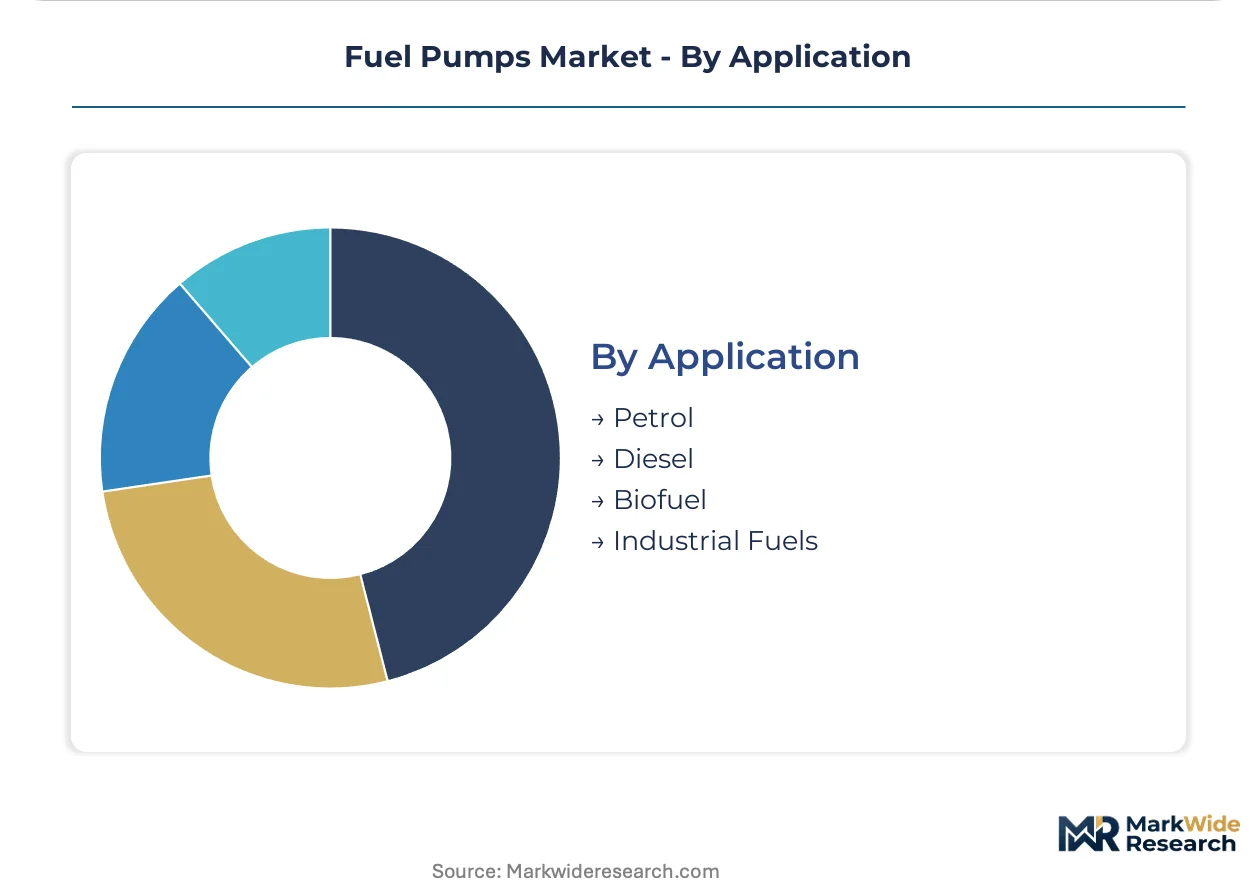
Application:
Fuel chemistry diversity is fragmenting certification requirements, with multi-fuel validation extending development timelines and testing expenditure.
- Petrol:Gasoline transfer and injection applications span port-injected systems at 3-6 bar through direct injection architectures exceeding 15 bar. Material specifications concentrate on aromatic hydrocarbon resistance and evaporative emission containment.
- Diesel:High-pressure common rail injection demands precision-machined components for pressures reaching 2,500 bar in commercial vehicle applications. Lubricity additive compatibility influences seal material selection.
- Biofuel:Ethanol blends through E85 and biodiesel specifications require fluoropolymer seals, stainless steel internals, and modified elastomer compounds. Agricultural and fleet applications in Brazil and the US Midwest drive specification adoption.
- Industrial Fuels:Kerosene, heating oil, and process fuel handling prioritizes flow capacity and temperature tolerance over precision metering. Bulk transfer terminals and commercial heating systems constitute primary demand.
Petrol retains largest volume position. Biofuel is gaining share fastest as renewable fuel mandates expand across transport sectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pump manufacturers supply high-pressure injection systems to passenger vehicle assembly plants across China and India, creating a trade corridor that concentrates precision machining expertise in Central Europe while production volumes scale in Asia.
China
Passenger vehicle output expansion and fuel retail infrastructure upgrades drive procurement of tank-integrated submersible pumps. GB 18352.6-2016 emissions standards mandate onboard diagnostic monitoring of fuel system integrity. The Yangtze River Delta manufacturing cluster around Shanghai anchors domestic production capacity for electric pump modules serving 48-volt mild-hybrid platforms.
Germany
Gasoline direct injection proliferation and Euro 6d-ISC-FCM in-service conformity requirements sustain demand for 15+ bar precision pumps. The KBA enforces stringent evaporative emission controls and leak detection certification. Bavaria's automotive supplier corridor, stretching from Munich to Ingolstadt, hosts concentrated machining capacity for high-pressure pump housings.
India
Passenger vehicle production growth and fuel station modernization programs concentrate demand for submersible turbine pumps at retail outlets. CEA guidelines and Petroleum and Natural Gas Regulatory Board standards govern underground storage system upgrades. The Chennai-Bengaluru industrial corridor scales manufacturing of cost-optimized electric pump configurations for domestic OEMs.
United States
EPA Tier 3 tailpipe standards and evaporative emission regulations tighten specifications for sealed bearing technologies in fuel pump assemblies. The Midwest manufacturing belt, spanning Michigan and Ohio, maintains assembly operations for high-volume pump modules bound for light truck and SUV platforms.
Japan
Brushless DC motor adoption for noise-vibration-harshness compliance and hybrid powertrain integration sustains electric pump demand. METI standards and JIS certification frameworks govern component reliability testing. The Nagoya-Toyota industrial zone concentrates mechatronic module development combining pump, sensor, and controller functions.
Fuel Pumps Market Vendor Landscape
On the supply side, the industry is tiered between integrated powertrain specialists controlling semiconductor sourcing and specialized machining houses concentrated in high-pressure component niches. Consolidation pressures concentrate among tier-one suppliers with captive electronics capabilities, while tier-two manufacturers face capacity constraints for precision grinding operations. Three archetypes dominate: diversified automotive conglomerates with full powertrain portfolios, precision machining specialists with honed expertise in high-pressure housings, and regional fabricators serving aftermarket replacement cycles. Competitive dynamics center on backward integration into motor controller semiconductors and geographic expansion through platform supply contracts with emerging market OEMs.
Among diversified conglomerates with integrated powertrain operations, Robert Bosch GmbH, Denso Corporation, and Continental AG exemplify the tier-one archetype that anchors supply relationships through bundled mechatronic offerings. These entities occupy positions where scale and captive component sourcing create structural advantages in procurement negotiations with global vehicle manufacturers.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Denso Corporation |
| Continental AG |
| Aisin Corporation |
| Delphi Technologies |
| TI Fluid Systems plc |
| General Motors Company |
| Walbro LLC |
| Pricol Limited |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's Yangtze River Delta electric pump module production compresses supplier margins while concentrating pricing power among German precision-machining houses serving 15+ bar gasoline direct injection specifications. This utilization asymmetry forces tier-two manufacturers to absorb semiconductor cost volatility or exit high-pressure segments entirely.
Pricing Analysis
The technology-generation pricing gap separates legacy mechanical cam-driven pumps from 48-volt mild-hybrid electric architectures and emerging digital smart-pump configurations with embedded diagnostics. Pricing stratifies across premium, standard, and economy tiers based on pressure rating certification and captive semiconductor integration. Cost compression in standard-tier electric pumps is intensifying because brushless DC motor controller shortages limit second-tier participation. Fleet procurement departments exhibit highest price sensitivity through centralized e-commerce platforms, while German OEM platform contracts demonstrate lowest sensitivity due to multi-year qualification requirements.
Supply Chain Analysis
Export-control restrictions on advanced semiconductor manufacturing equipment constrain motor controller chip flows to non-captive pump manufacturers, segmenting supply relationships. Manufacturing concentrates in China, Germany, and Japan, with precision grinding capacity for high-pressure housings anchored in Bavaria and Nagoya. Supply chains draw from fluoropolymer seal producers, rare-earth magnet suppliers, and precision steel forging operations. Single-source vulnerability concentrates in specialized honing equipment for 15+ bar pump housings. Distribution runs through tier-one mechatronic module suppliers directly to OEM platform teams, bypassing traditional wholesale channels for new vehicle production.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision grinding and honing expertise for high-pressure pump housings concentrates among a shrinking pool of specialized tier-two suppliers, creating structural bottlenecks that reshape competitive positioning across the value chain.
For Market Incumbents: Insulate high-pressure machining relationships through long-term capacity reservations with Bavarian and Nagoya-based precision houses before semiconductor-captive competitors consolidate remaining supply. Secure backward integration into brushless DC motor controller design to neutralize chip allocation disadvantages against Denso and Bosch captive sourcing. Monitor Euro 6d-ISC-FCM diagnostic retrofit obligations as a service revenue anchor. For New Entrants and Emerging Players: India's fuel retail infrastructure modernization offers the most penetrable white-space, with CEA-mandated underground storage tank retrofits creating demand for commercial-grade submersible turbine pumps outside established automotive supply relationships. Target aftermarket diagnostic equipment for legacy fleet compliance monitoring as a low-capital entry path. Pursue direct e-commerce procurement relationships with fleet maintenance departments to bypass entrenched jobber networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision-machining specialists with multi-year platform contracts and captive honing capabilities, offering superior cash flow predictability over component-assembly operations. Long-term viability hinges on exposure to 48-volt mild-hybrid platform proliferation rather than mechanical pump aftermarket decline. Watch for GB 18352.6-2016 diagnostic mandate acceleration as an inflection signal for smart-pump configuration demand.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Machining Capacity Expansion | Secures 15+ bar pump housing supply for gasoline direct injection platforms bound for EPA Tier 3 compliance. |
| Brushless DC Motor Controller Integration | Eliminates semiconductor allocation risk through in-house design capability matching Denso captive sourcing. |
| India Fuel Retail Infrastructure Partnership | Captures CEA-mandated underground storage tank retrofit demand outside automotive OEM supply chains. |
| Digital Smart-Pump Certification | Meets China's GB 18352.6-2016 onboard diagnostic requirements for fuel system integrity monitoring. |
| Aftermarket Diagnostic Equipment Development | Monetizes Euro 6d-ISC-FCM in-service conformity mandates across Germany's installed fleet base. |
Methodological Framework
A spread of perspectives from OEM platform engineers, tier-one supplier procurement leads, aftermarket distributor operations heads, and fuel retail infrastructure operators converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, SEC 10-K filings from listed suppliers, and EPA certification records. Bottom-up triangulation across segment-level procurement volumes and top-down reconciliation against national vehicle output statistics anchored value estimates.
Demand-supply balance modeling tracked electric pump adoption curves against 48-volt mild-hybrid platform proliferation, mechanical pump replacement cycle collapse, and precision machining capacity constraints across the analysis window. Segmentation dimensions included pump architecture, pressure rating tier, end-use environment, technology generation, and regional regulatory cluster. CAGRs derived from slope-consistent growth pattern matching to historical platform adoption curves, with cross-checks against OEM powertrain roadmap disclosures and emissions regulation phase-in schedules.
Practitioners should monitor semiconductor supply allocation shifts, Euro 6d-ISC-FCM enforcement timing, and China GB standard amendment trajectories for early signals requiring forecast reassessment. Forecasts reflect documented assumptions about mild-hybrid platform penetration rates and machining capacity expansion timelines. Material shifts in EPA Tier 3 implementation stringency or brushless DC motor technology cost curves would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
South Korea Automotive Engine Oils Market
Powertrain
Transmission Repair Market
Powertrain
Vehicle Power Tailgate System Market
Powertrain
Automatic Transmission Torque Converter Market
Powertrain
Asia-Pacific Automotive Engine Oils Market
Powertrain
Automotive Crankshaft Sensor Market
Powertrain
Timing Belt Kits Market
Powertrain
Crankshaft Position Sensor Market
Powertrain
Global Automotive Clutch Market
Powertrain
Gas Engine Market
Powertrain
Asia Pacific Gasoline Injection Technologies Market
Powertrain
Exhaust Flexible Couplings Market
Powertrain
Global Industrial Brakes and Clutches Market
Powertrain
Automotive Hydraulic Lash Adjuster Market
Powertrain
Electric Two-Wheeler Powertrain and Range Validation Test Systems Market
Powertrain
Global Automotive Engine Cover Market