
 Global Fruit and Vegetable Powder Market | 2026-2036
Global Fruit and Vegetable Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fruit and Vegetable Powder Market Intelligence
The fruit and vegetable powder category is pivoting between premium freeze-dried botanical extracts and commodity-grade spray-dried fillers. Döhler GmbH leverages its European botanical supply network to sustain dominance in beverage flavoring applications. Kanegrade anchors its position through specialized fruit powder formulations for confectionery and dairy clients. Aarkay Food Products Ltd competes on manufacturing scale across drum-dried vegetable powders for industrial food processing buyers.
Fruit and vegetable powders are dehydrated plant-derived materials produced through controlled thermal or sublimation processes, typically retaining standardized polyphenol, fiber, or pigment concentrations for reconstitution in finished goods. Spray drying remains the dominant processing technology due to throughput economics, though freeze drying commands premium positioning in nutritional supplements where volatile compound preservation determines efficacy. Beverage flavoring applications lead volume consumption, while cosmetic ingredients represent the fastest-expanding margin pool as topical antioxidant claims intensify formulation demand. Food and beverage manufacturers occupy the largest end-user channel, with pharmaceutical companies deepening procurement of standardized herbal powders for tablet and capsule excipient applications.
FDA GRAS self-determination requirements and EFSA novel food catalog listings shape ingredient approval pathways for cross-border powder trade. BIS quality certification mandates in India and USDA organic handling standards govern raw material eligibility for export-oriented processing facilities. Stakeholders must monitor evolving EU deforestation regulation traceability obligations for tropical fruit sourcing and their cascading impact on supply chain documentation costs.
Market Dynamics
Clean-label ingredient mandates from nutritional supplement manufacturers are compressing lead times between raw material procurement and finished goods formulation, forcing powder processors to consolidate spray-drying capacity near organic sourcing clusters.
Growth Catalysts
- EU Green Deal agricultural sustainability standards:Certified organic raw material streams are redirecting sourcing patterns toward traceable supply chains that command premium pricing in beverage flavoring applications.
- India's PLI scheme incentives:Food processing infrastructure investments are accelerating domestic spray-drying capacity buildouts that reduce import dependency for tropical fruit powders.
- Freeze-drying technology maturation:Volatile compound preservation capabilities are expanding addressable market share in nutritional supplements where polyphenol efficacy determines procurement decisions.
Market Restraints
- Tropical fruit input cost volatility:Climate-induced yield fluctuations in mango, pineapple, and papaya growing regions compress margin predictability for commodity-grade powder processors.
- EU deforestation regulation traceability obligations:Supply chain documentation requirements for tropical fruit sourcing are inflating compliance overhead for export-oriented processing facilities.
- Spray-drying thermal degradation:High-temperature processing limits volatile antioxidant retention, constraining application in premium cosmetic ingredient formulations.
Strategic Opportunities
- Cosmetic ingredient channel expansion:Topical antioxidant claims are intensifying formulation demand from skincare manufacturers seeking standardized pigment concentrates.
- Pharmaceutical excipient standardization:Tablet and capsule manufacturers are deepening procurement of herbal powders with certified polyphenol concentrations for consistent dissolution profiles.
- USDA organic handling standards harmonization:Export-oriented Indian processing facilities are capturing EU market access through dual-certification programs that reduce customs friction.
Industry Challenges
- Spray-drying engineering talent scarcity:Process optimization for heat-sensitive compounds requires specialized thermal engineering expertise concentrated in European equipment manufacturers.
- Dual certification timeline compression:Simultaneous BIS quality certification and USDA organic handling approvals extend facility commissioning cycles for greenfield Indian processing plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fruit and Vegetable Powder Market |
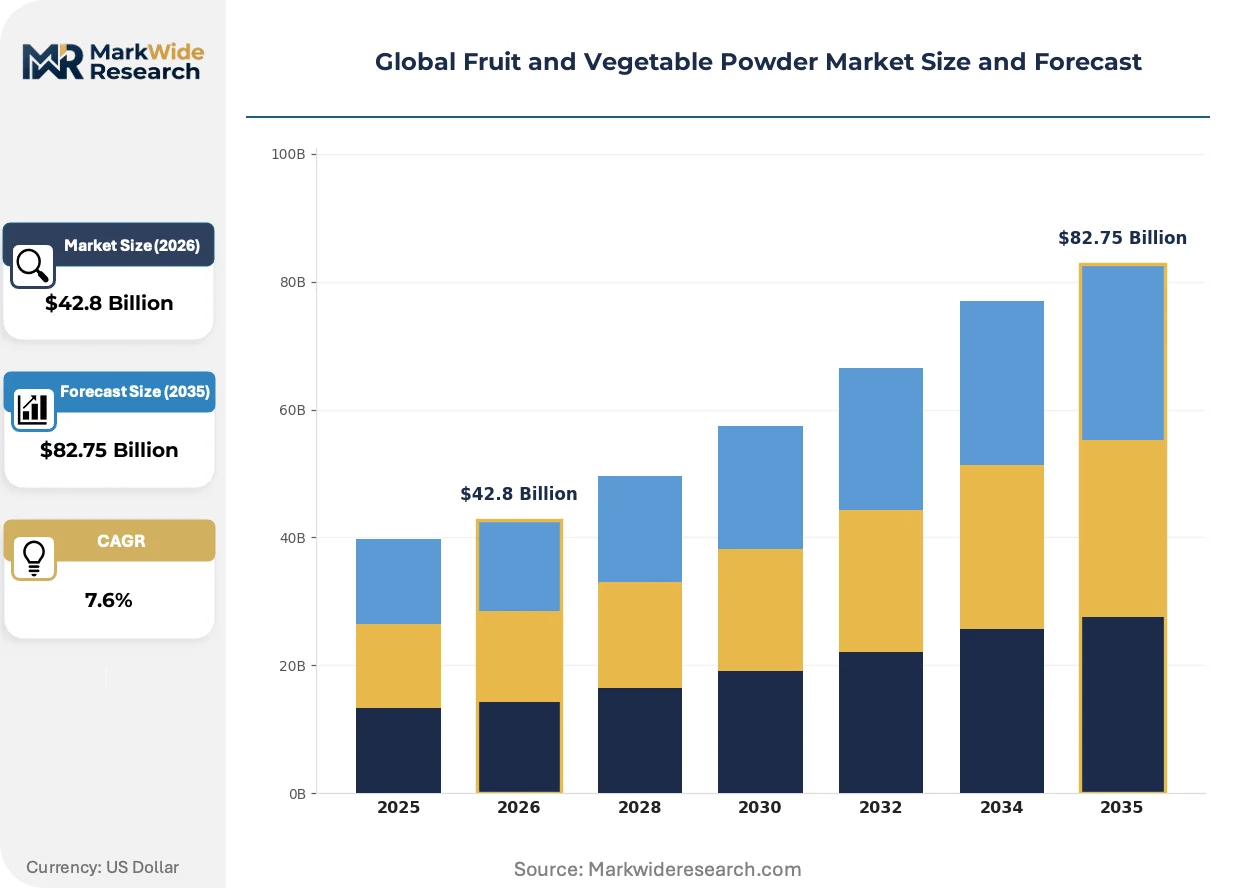
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $82.75 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Powder, Vegetable Powder, Mixed Powder, Herbal Powder Application: Beverage Flavoring, Food Processing, Nutritional Supplements, Cosmetic Ingredients, Animal Feed Processing Technology: Spray Drying, Freeze Drying, Drum Drying, Vacuum Drying, Extrusion End User: Food & Beverage Manufacturers, Pharmaceutical Companies, Cosmetic Companies, Animal Nutrition Providers |
| Companies Covered | International Flavors & Fragrances Inc, Kanegrade, Aarkay Food Products Ltd, NutraDry, Döhler GmbH, Batory Foods, Iprona SpA, Paradise Fruits, FutureCeuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fruit and Vegetable Powder Market Strategic Shifts & Innovations
Processing technology convergence and regulatory traceability mandates are fragmenting the competitive landscape between premium freeze-dried botanical specialists and volume-oriented spray-dried commodity producers.
Encapsulation technology using modified starch and maltodextrin carriers is modularizing formulation flexibility for beverage manufacturers. Mid-tier flavoring houses are adopting microencapsulation systems at accelerated rates to mask off-notes in vegetable-forward formulations. This modularizing capability is compressing minimum order quantities and enabling just-in-time powder procurement models that reduce working capital requirements.
EFSA novel food catalog listing requirements are reshaping cross-border powder trade documentation. Ingredient approval pathways now mandate comprehensive toxicological dossiers for non-traditional fruit sources, elevating regulatory affairs headcount at mid-cap processors. Nutritional supplement segments targeting EU distribution are most affected, with many reformulating around catalog-listed botanicals to accelerate time-to-market.
Direct procurement relationships between food manufacturers and certified organic farms are displacing traditional trader intermediaries in tropical fruit supply chains. Large-scale beverage conglomerates are establishing captive sourcing agreements that guarantee volume commitments in exchange for exclusivity on harvest lots. This disintermediation is most visible in Indian mango powder supply chains, where domestic processors are building backward integration into Maharashtra and Uttar Pradesh growing regions.
Global Fruit and Vegetable Powder Market Segmentation
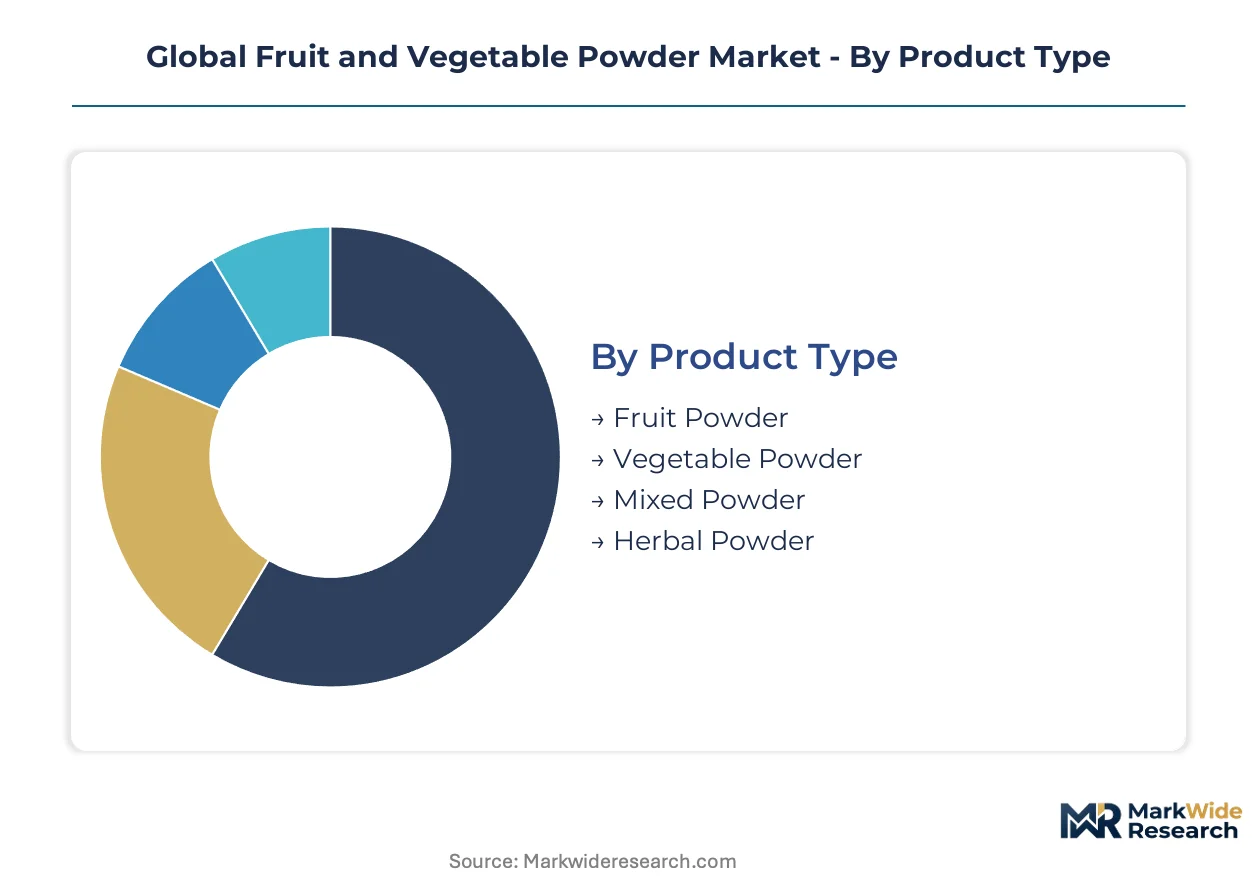
Powder processors navigate divergent margin structures across product categories, with freeze-dried botanical extracts commanding premium positioning against commodity spray-dried fillers. Application-driven procurement patterns fragment the competitive landscape between beverage flavoring volume buyers and cosmetic ingredient specialists seeking standardized pigment concentrates.
Product Type:
Reformulation cycles in nutritional supplements and clean-label mandates are accelerating upgrade trajectories from commodity powders toward certified organic and functional-grade alternatives.
- Fruit Powder:Dehydrated tropical and temperate fruit materials standardized for polyphenol, natural sugar, and pigment retention. Beverage manufacturers in India and EU markets concentrate procurement on mango and pineapple powders where PLI scheme capacity buildouts are compressing import dependency.
- Vegetable Powder:Thermal-processed carrot, beet, and spinach derivatives with standardized fiber and beta-carotene specifications. Nutritional supplement manufacturers in Germany deepen procurement for clean-label tablet excipients as EFSA novel food catalog compliance costs reshape sourcing decisions.
- Mixed Powder:Blended fruit-vegetable formulations targeting convenience-oriented beverage applications.
- Herbal Powder:Botanical extracts with certified marker compound concentrations for pharmaceutical and wellness applications.
Volume placements concentrate in Fruit Powder; the faster expansion belongs to Herbal Powder.
Application:
Cost tier stratification separates commodity-grade industrial buyers from premium formulation channels where efficacy claims justify processing technology premiums.
- Beverage Flavoring:The dominant consumption channel by tonnage, spanning natural flavor enhancement and color stabilization in ready-to-drink formulations. Döhler GmbH sustains supply relationships with European bottlers through captive botanical networks that guarantee harvest lot traceability under EU Green Deal standards.
- Cosmetic Ingredients:Standardized antioxidant and pigment concentrates for topical formulation claims. Skincare manufacturers in France and South Korea intensify procurement of freeze-dried berry powders where volatile compound preservation determines claim substantiation.
- Food Processing:Industrial-scale incorporation into baked goods, confectionery, and dairy systems.
- Nutritional Supplements:Capsule and tablet excipients with certified dissolution profiles.
- Animal Feed:Palatability enhancers and natural pigment sources for aquaculture and poultry sectors.
Food Processing absorbs the highest absolute volumes; Cosmetic Ingredients are climbing the fastest as topical antioxidant claims proliferate.
Processing Technology:
Technology selection locks processors into distinct margin pools, with capital intensity and thermal engineering expertise determining competitive defensibility.
- Spray Drying:Dominant throughput economics using heated air streams to atomize liquid feedstocks into granular powders. Indian processing facilities accelerate capacity buildouts under PLI scheme incentives, though thermal degradation limits application in premium cosmetic formulations.
- Freeze Drying:Sublimation-based dehydration preserving volatile aromatic and bioactive compounds. European equipment manufacturers concentrate specialized engineering talent that constrains technology transfer to emerging processing clusters.
- Drum Drying:Continuous thermal processing for high-volume vegetable powder production.
- Vacuum Drying:Reduced-pressure thermal processing for heat-sensitive botanical materials.
- Extrusion:High-shear thermal processing for modified texture and solubility profiles.
Spray Drying maintains the largest installed base; Freeze Drying is gaining share fastest in nutritional supplement and cosmetic channels.
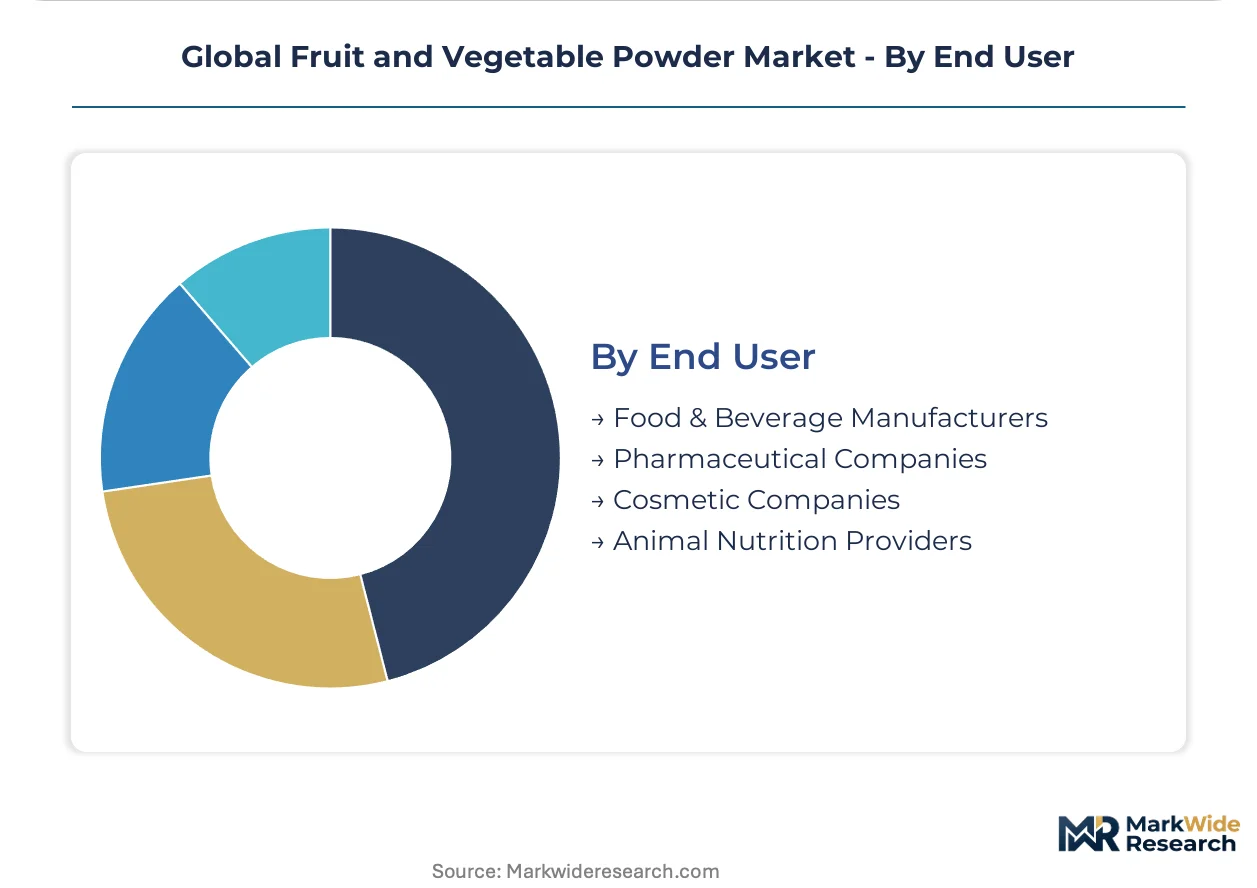
End User:
Customer type determines procurement sophistication, with pharmaceutical and cosmetic buyers imposing stricter certification and documentation requirements than industrial food processors.
- Food & Beverage Manufacturers:The largest channel by procurement value, spanning multinational conglomerates and regional flavoring houses. Direct sourcing agreements with certified organic farms in Maharashtra and Uttar Pradesh are displacing traditional trader intermediaries in Indian mango powder supply chains.
- Pharmaceutical Companies:Tablet and capsule manufacturers demanding standardized polyphenol concentrations and certified dissolution profiles. EMA and FDA GRAS compliance pathways elevate regulatory affairs overhead for powder suppliers targeting cross-border distribution.
- Cosmetic Companies:Skincare and personal care formulators seeking topical antioxidant claim substantiation.
- Animal Nutrition Providers:Feed compounders incorporating natural pigments and palatability enhancers.
Procurement volumes concentrate with Food & Beverage Manufacturers; Pharmaceutical Companies are expanding most quickly as herbal excipient standardization deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Nashik-Ahmednagar corridor anchors the most aggressive capacity expansion trajectory, with PLI scheme subsidies drawing spray-drying investment away from traditional European processing clusters.
United States
California's Central Valley and Florida's citrus belt supply raw material streams for nutritional supplement manufacturers demanding certified organic handling documentation. FDA GRAS self-determination pathways shape ingredient approval timelines for cross-border powder trade, while USDA organic certification mandates govern export eligibility. Chicago-area distribution hubs consolidate procurement for midwestern food processing plants reformulating around clean-label vegetable powders.
Germany
Beverage flavoring houses in Hamburg and Cologne deepen procurement of freeze-dried botanical extracts as EFSA novel food catalog compliance costs reshape sourcing decisions. EU Green Deal agricultural sustainability standards redirect supply chains toward traceable organic raw material streams. Bavarian processing facilities concentrate specialized thermal engineering talent for heat-sensitive compound preservation.
India
Maharashtra and Uttar Pradesh growing regions attract backward integration investments from domestic spray-drying operators seeking captive mango powder supply. FSSAI quality mandates and BIS certification requirements govern facility commissioning timelines for export-oriented plants. Gujarat's food processing corridors accelerate capacity buildouts under PLI scheme incentives that reduce import dependency for tropical fruit derivatives.
France
Skincare manufacturers in Paris and Lyon intensify procurement of freeze-dried berry powders where volatile compound preservation determines topical antioxidant claim substantiation. EMA pharmaceutical excipient standards elevate documentation requirements for herbal powder suppliers targeting tablet and capsule applications. Provence-Alpes-Côte d'Azur clusters specialize in cosmetic-grade botanical extraction.
China
Yangtze River Delta processing zones supply volume-grade vegetable powders for industrial food manufacturing across Asia-Pacific distribution networks. SAMR food safety regulations and GB standards govern cross-border shipment documentation for dehydrated plant materials. Shandong Peninsula facilities concentrate drum-drying capacity for high-throughput carrot and beet powder production.
Global Fruit and Vegetable Powder Market Key Industry Players
Premium-margin players sit above commodity-margin players across processing technology tiers, with freeze-drying specialists commanding pricing multiples over spray-dried volume operators. The vendor base stratifies between European botanical network holders, Asian scale-driven fabricators, and mid-tier regional flavoring houses. Three archetypes dominate: captive sourcing integrators, equipment-locked technology specialists, and formulation-flexible modular suppliers. Competitive moves concentrate on backward integration into certified organic farms and microencapsulation capability licensing.
Among European network-based operators, Döhler GmbH and Kanegrade exemplify divergent specialization vectors—Döhler anchoring beverage flavoring supply relationships through captive botanical sourcing, Kanegrade occupying confectionery and dairy formulation niches. Aarkay Food Products Ltd represents the scale-driven Asian archetype, with drum-dried vegetable powder capacity positioned for industrial food processing procurement. These three illustrate how geographic processing clusters and technology selection lock competitors into distinct margin pools and customer relationship intensities.
| Leading Market Players |
|---|
| International Flavors & Fragrances Inc |
| Kanegrade |
| Aarkay Food Products Ltd |
| NutraDry |
| Döhler GmbH |
| Batory Foods |
| Iprona SpA |
| Paradise Fruits |
| FutureCeuticals |
| Others |
Cost & Logistics Intelligence
Beverage conglomerates and nutritional supplement manufacturers command pricing leverage through volume commitments and certification requirements that stratify procurement tiers. Their consolidation of direct sourcing agreements with certified organic farms in Maharashtra and Uttar Pradesh compresses margin pools for trader intermediaries while elevating premiums for traceable supply documentation under EU Green Deal standards.
Pricing Analysis
Value-based pricing anchors on polyphenol retention efficacy and organic certification tier. Three-tier pricing structure across premium freeze-dried extracts, standard spray-dried powders, and economy drum-dried fillers separates cosmetic ingredient specialists from industrial food processors. Cost compression in commodity-grade vegetable powders intensifies as Indian PLI scheme capacity buildouts expand domestic spray-drying output. Nutritional supplement manufacturers exhibit lowest price sensitivity due to efficacy-dependent procurement, while animal feed compounders remain most price-sensitive.
Supply Chain Analysis
Return flows of non-conforming powder lots for reprocessing or downgrading into animal feed applications create reverse-logistics complexity at Indian processing facilities. Primary supply concentrates in India, Germany, and the United States, with raw material streams drawing from tropical mango and pineapple growing regions, temperate berry cultivation zones, and vegetable belt harvests. Single-source vulnerability in Maharashtra mango supply chains elevates risk exposure from climate-induced yield fluctuations. Distribution runs through captive sourcing agreements for large beverage manufacturers and regional distribution hubs serving mid-tier flavoring houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
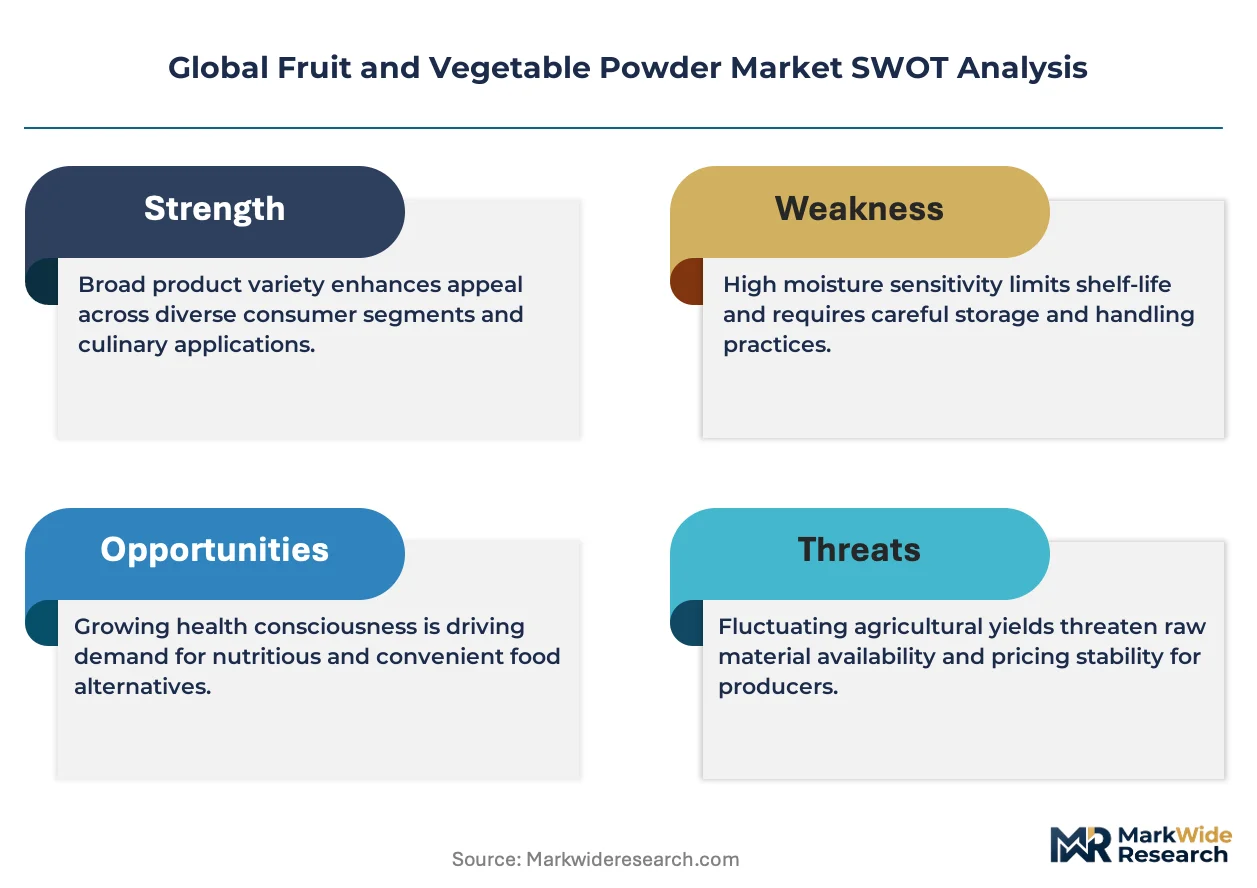
EU deforestation regulation traceability obligations erect a cost-of-compliance barrier that favors incumbent processors with established documentation infrastructure and certified organic farm networks. This regulatory moat disadvantages new entrants lacking backward integration capabilities.
For Market Incumbents: Lock in supply security through captive sourcing agreements with certified organic farms in Maharashtra and Uttar Pradesh growing regions. Invest in dual BIS-USDA certification capacity at Gujarat processing corridors to capture EU market access. Defend against emerging Indian scale players by deepening freeze-drying engineering partnerships with Bavarian equipment specialists. For New Entrants and Emerging Players: Launch via microencapsulation technology licensing to mid-tier beverage flavoring houses seeking formulation flexibility. Target cosmetic ingredient channels in France and South Korea where topical antioxidant claim substantiation commands premium positioning. Pursue white-space opportunities in pharmaceutical excipient standardization for tablet and capsule applications. For Investors and Strategic Acquirers: Distressed-cycle entries favor freeze-drying technology specialists with EU EFSA novel food catalog compliance capabilities in German and French processing clusters. Long-term viability hinges on backward integration depth and regulatory documentation infrastructure. Monitor EU deforestation regulation enforcement intensity and PLI scheme subsidy renewal signals as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Organic Farms | Maharashtra and Uttar Pradesh captive sourcing secures traceable supply chains under EU Green Deal standards. |
| Dual Certification Capacity Investment | Simultaneous BIS quality and USDA organic handling approvals reduce customs friction for Indian export facilities. |
| Microencapsulation Technology Licensing | Modified starch and maltodextrin carrier systems enable just-in-time procurement models for beverage manufacturers. |
| Freeze-Drying Engineering Partnerships | Bavarian thermal engineering expertise constrains technology transfer to emerging processing clusters. |
| Cosmetic Ingredient Channel Expansion | Paris and Lyon skincare manufacturers intensify procurement of volatile-compound-preserving berry powders. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with spray-drying plant managers, procurement leads at beverage and nutritional supplement manufacturers, distribution channel partners, and regulatory affairs directors at powder processing facilities combined with secondary validation from FSSAI quality mandates, EFSA novel food catalog listings, and USDA organic handling standards. Bottom-up capacity assessments across Indian PLI scheme facilities and top-down demand modeling from end-use consumption patterns underwent rigorous triangulation.
Data-stream reconciliation across production capacity databases, import-export trade flows, and end-use procurement surveys informed the analytical framework. Segmentation dimensions modeled include processing technology tier, application channel, certification grade, and regional production hub clustering. CAGRs derived from fitted growth curves applied to base-year market sizing across the projection horizon. Industry-specific forecast inputs incorporated PLI scheme subsidy trajectories and EU deforestation regulation compliance cost assumptions.
Climate-induced tropical fruit yield volatility, regulatory documentation requirement changes, and freeze-drying equipment supply constraints are the dominant revision risks. Forecasts reflect documented assumptions regarding subsidy continuity and certification timeline standardization. Practitioners should monitor EU enforcement intensity, Indian monsoon patterns, and European thermal engineering talent availability for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Flavanols Market
Specialty Ingredients
Fermentation Products Market
Specialty Ingredients
Global Pet Food Flavors Market
Specialty Ingredients
Green Sic Market
Specialty Ingredients
Aromatherapy Carrier Oil Market
Specialty Ingredients
Specialty Food Ingredients Market
Specialty Ingredients
Middle East and Africa Customized Premixes Market
Specialty Ingredients
Marine Spicules Market
Specialty Ingredients
Specialty Beverage Stabilizers Market
Specialty Ingredients
Global Ayurvedic Herbs Market
Specialty Ingredients
Abies Alba (Fir) Leaf Oil Market
Specialty Ingredients
Floral Water Market
Specialty Ingredients
Specialty Meat Ingredients Market
Specialty Ingredients
Europe Specialty Food Ingredients Market
Specialty Ingredients
Food Decorations and Inclusions Market
Specialty Ingredients
North America Grape Seed Extract Market