
 Europe Specialty Food Ingredients Market | 2026-2036
Europe Specialty Food Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Specialty Food Ingredients Market Foresight
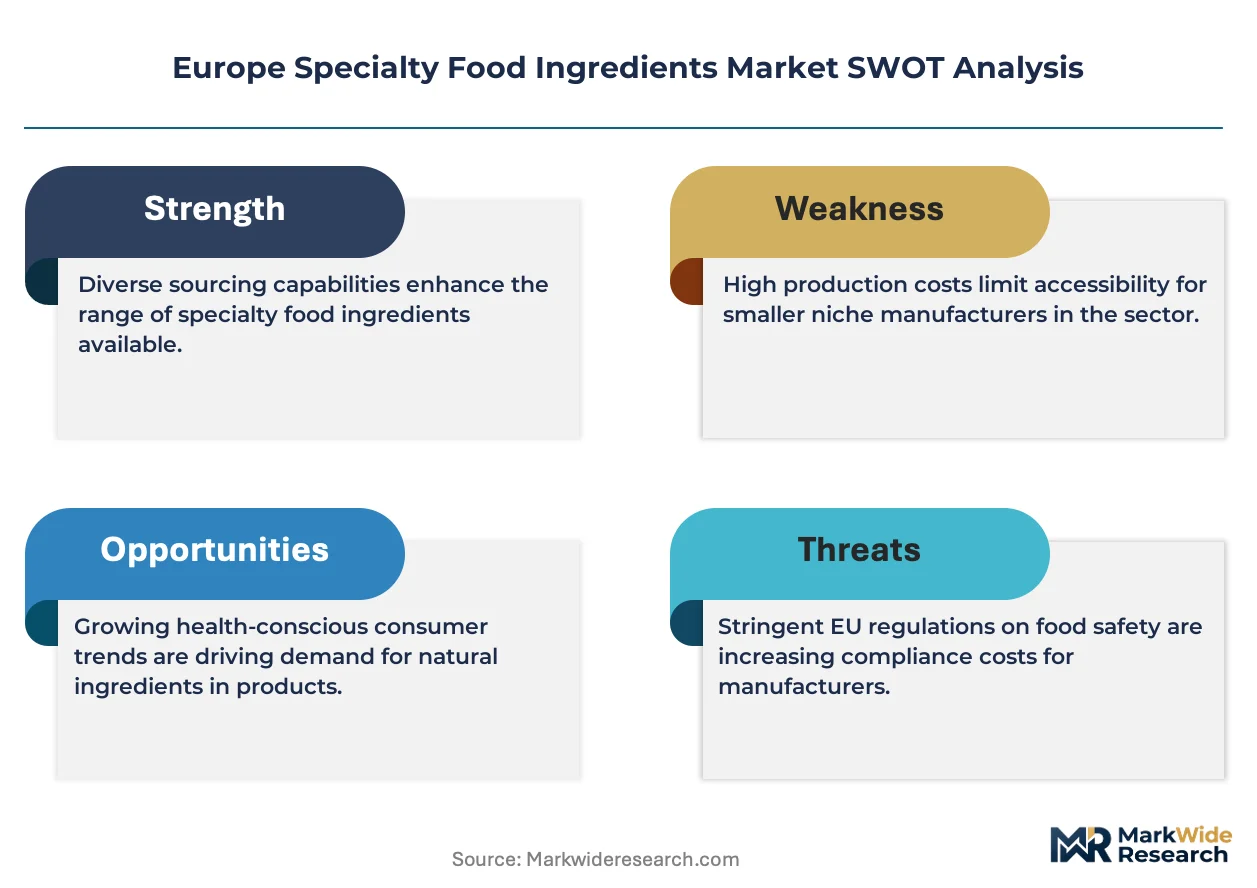
REACH is shifting the cost-of-entry calculus for specialty food ingredient suppliers entering or expanding within Europe, forcing reformulation investments and third-party certification costs that favor well-capitalized incumbents. Kerry Group leverages its integrated taste and nutrition platforms to sustain premium positioning across dairy and savory applications. Givaudan SA anchors its competitive edge in natural flavor extraction and biotechnology-driven ingredient development. DSM-Firmenich differentiates through its merger-scale R&D footprint and enzymatic solutions portfolio.
Specialty food ingredients comprise functionally active substances—emulsifiers, modified starches, high-intensity sweeteners, and natural flavorings—engineered to deliver specific textural, sensory, or preservative outcomes at dosage levels typically below five percent of finished product weight. These ingredients serve industrial food manufacturers seeking to standardize batch consistency, extend shelf stability, or achieve clean-label positioning without sacrificing performance. Sweeteners and flavorings command the deepest margin pools due to patent-protected extraction processes and concentrated buyer reliance on sensory differentiation. Emulsifiers face accelerating competition from plant-derived lecithin alternatives as bakery and dairy processors reformulate around allergen and GMO-free claims. Starch modification technologies are concentrating investment around cold-water swelling and clean-label viscosity solutions for sauces and ready-meal applications.
EMA, EFSA, and the EU Green Deal collectively shape product standards, safety assessments, and carbon disclosure obligations that determine market access across all member states. EFSA's evolving guidance on novel food classifications and ECHA's substance restriction timelines create compliance windows that advantage suppliers with established regulatory affairs capabilities. Stakeholders must monitor how the EU AI Act and digital product passport requirements will reshape traceability investments and supplier qualification protocols.
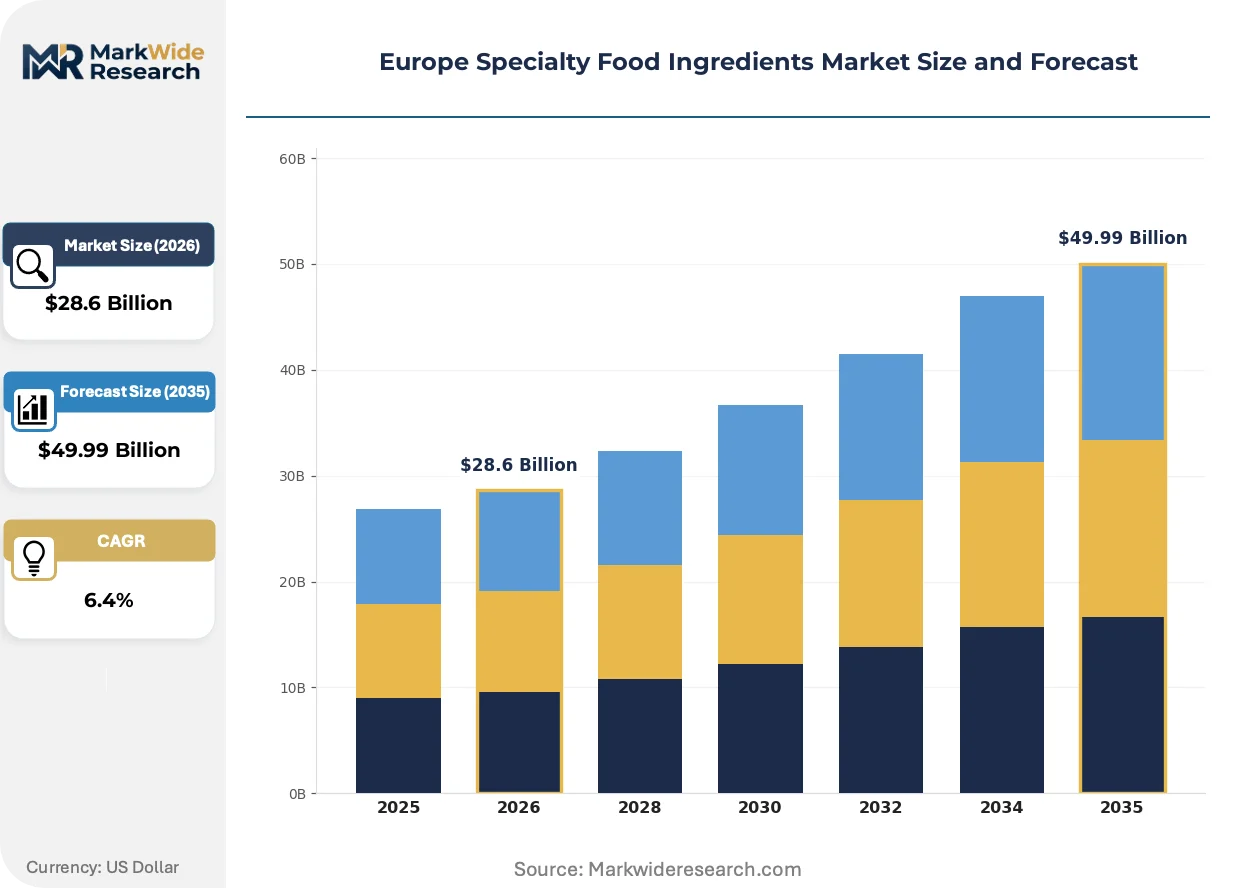
Market Dynamics
REACH compliance and the EU Green Deal are forcing specialty food ingredient suppliers to reconfigure purification processes and carbon-accounting systems, elevating capital requirements and favoring incumbents with established regulatory infrastructure.
Growth Catalysts
- Clean-label bakery demand:German, French, and Italian processors are reformulating around natural emulsifiers and fermentation-derived flavorings, pulling investment toward plant-based texturizers.
- EU Green Deal carbon mandates:Disclosure obligations under the Corporate Sustainability Reporting Directive are accelerating supplier qualification protocols that reward low-carbon ingredient sourcing.
- Netherlands-Belgium processing clusters:Large-scale dairy and confectionery operations in these regions concentrate procurement volume for high-performance modified starches and enzymatic solutions.
Market Restraints
- Raw material concentration:Plant-derived lecithin supply chains depend heavily on South American and Eastern European oilseed processors, exposing formulators to harvest volatility.
- REACH registration costs:ECHA substance evaluation timelines and data requirements create multi-year compliance windows that block mid-tier entrants from novel ingredient categories.
- Technical substitution limits:Natural emulsifiers face performance gaps in high-fat bakery applications where synthetic alternatives maintain superior shelf-stability.
Strategic Opportunities
- Poland and Romania food manufacturing:Underpenetrated markets in Central and Eastern Europe offer first-mover positioning as regional dairy and ready-meal capacity expands.
- Digital product passport integration:EU AI Act traceability requirements will create service revenue streams for suppliers offering blockchain-verified ingredient provenance systems.
- Fermentation-platform convergence:Precision fermentation combined with enzymatic modification enables novel protein and flavor molecule production at scale.
Industry Challenges
- Regulatory affairs talent scarcity:EFSA novel food dossier preparation and ECHA substance defense require specialized toxicologists and regulatory scientists in short supply across the continent.
- Cold-chain starch modification capex:Clean-label viscosity solutions demand continuous processing equipment investments that strain mid-cap balance sheets.
- Legacy ERP integration friction:Carbon-accounting software deployment conflicts with established batch tracking systems in multi-site European manufacturing networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Specialty Food Ingredients Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsifiers, Starch, Sweeteners, Flavorings Application: Bakery, Dairy, Confectionery, Sauces End User: Food Manufacturers, Retailers, Restaurants, Food Service Form: Powder, Liquid, Granule, Paste |
| Companies Covered | Archer Daniels Midland Company, Kerry Group, Givaudan SA, Cargill, Incorporated, International Flavors & Fragrances Inc., DSM-Firmenich, Tate & Lyle PLC, Ingredion Inc., Roquette Freres, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Specialty Food Ingredients Market Shifts & Advancements
Biotechnology platforms and regulatory digitization are compressing development cycles while reshaping how ingredient suppliers demonstrate compliance and differentiate performance claims.
Precision fermentation is absorbing capital and technical talent as the dominant pathway for natural flavor molecule and alternative protein production. Dairy and savory application developers in the Netherlands and Denmark are scaling pilot volumes to commercial quantities within eighteen-month windows. This platform is absorbing market share from solvent extraction methods by delivering batch-to-batch consistency that satisfies EFSA novel food safety dossier requirements.
CSRD disclosure mandates are forcing ingredient suppliers to deploy lifecycle assessment software and third-party carbon verification by 2025. The regulation compresses supplier qualification timelines as food manufacturers demand Scope 3 data for procurement decisions. Modified starch and emulsifier categories face the steepest compliance burden given their agricultural upstream exposure and energy-intensive processing steps.
Direct supplier relationships are displacing traditional distributor networks for high-volume bakery and dairy processors seeking technical co-development partnerships. Category managers in German and Belgian manufacturing clusters now require on-site application laboratories and rapid prototype turnaround as standard commercial terms. This pattern concentrates purchasing power among vertically integrated ingredient platforms with regional technical service infrastructure.
Europe Specialty Food Ingredients Market Segmentation
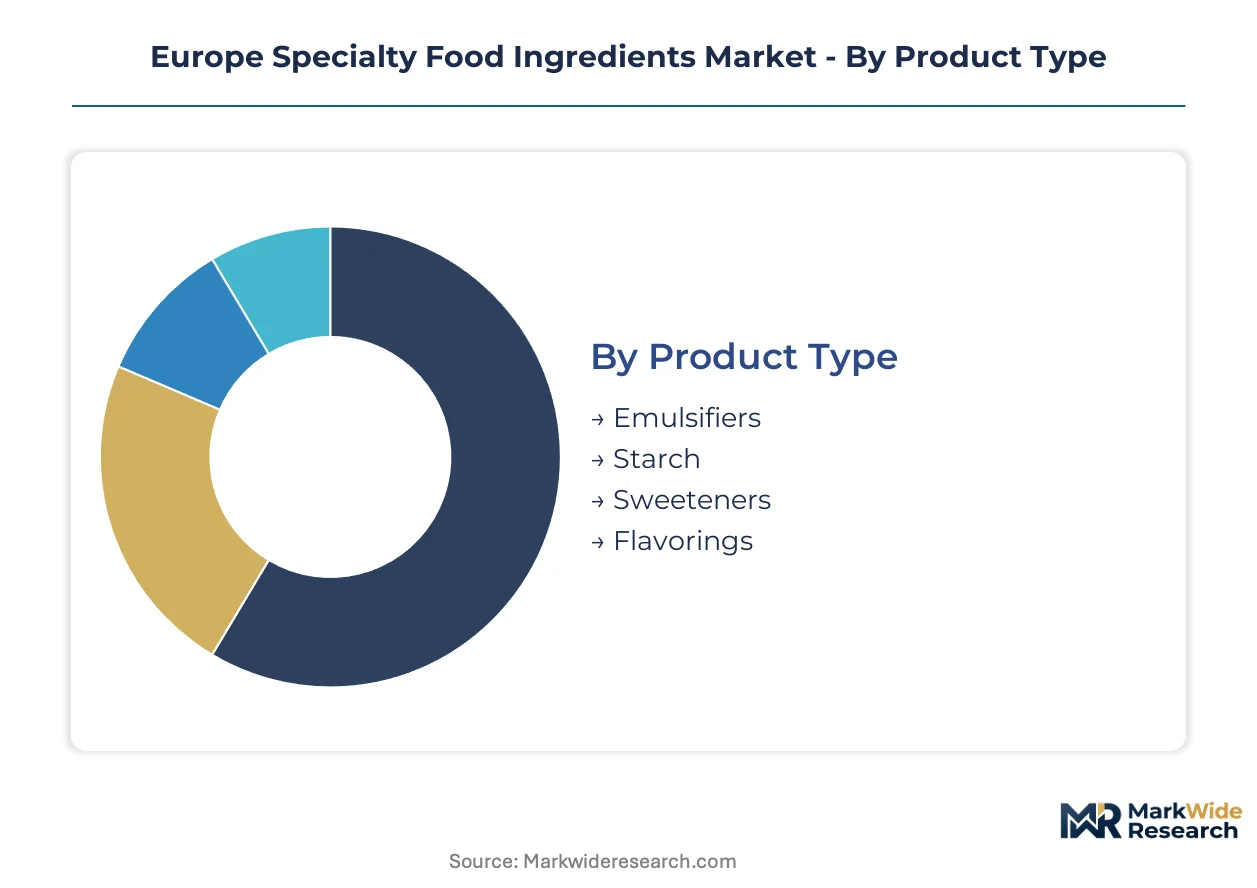
Specialty food ingredient purchasing decisions diverge sharply across product categories and end-use applications. Capital requirements, regulatory exposure, and technical service intensity vary dramatically by segment, reshaping supplier competitive positioning.
Product Type:
Emulsifiers and modified starches demand the heaviest purification infrastructure and continuous processing equipment, while flavor extraction and sweetener synthesis concentrate R&D spend on biotechnology platforms.
- Emulsifiers:These surface-active agents stabilize oil-water interfaces in high-fat bakery and dairy matrices. German and Belgian processors are reformulating around plant-derived lecithin alternatives as REACH restrictions tighten on synthetic variants, though performance gaps persist in extended shelf-life applications.
- Starch:Modified starches deliver viscosity, freeze-thaw stability, and mouthfeel control through physical, chemical, or enzymatic alteration. Netherlands-based dairy and ready-meal manufacturers drive demand for cold-water swelling variants that eliminate heat-processing steps.
- Sweeteners:High-intensity and bulk sweeteners replace or reduce caloric sugars in reduced-calorie confectionery and beverages.
- Flavorings:Natural and nature-identical flavor molecules provide sensory differentiation in clean-label positioning strategies.
Most installed capacity flows through Starch. Expansion is steepest in Flavorings.
Application:
Dairy and bakery applications concentrate procurement volume in the Netherlands-Belgium corridor, while confectionery and sauce manufacturers prioritize sweetness modulation and viscosity control respectively.
- Bakery:Bread, pastry, and cake applications rely on emulsifiers for dough conditioning and crumb softening. French and Italian artisanal producers are accelerating clean-label reformulation, pulling demand toward enzyme-based dough strengtheners and fermented flavor precursors.
- Dairy:Yogurt, cheese, and ice cream processing requires stabilizer systems for texture and freeze-thaw resistance. Large-scale Dutch dairy cooperatives specify modified starches with precise amylose-amylopectin ratios for premium mouthfeel.
- Confectionery:Chocolate, gum, and candy production depends on emulsifiers for fat bloom control and sweeteners for bulk replacement.
- Sauces:Dressings, condiments, and ready-meal gravies utilize cold-swelling starches for instant viscosity without heat activation.
Bakery commands the largest procurement budgets. Dairy is gaining share fastest as functional yogurt and plant-based alternatives proliferate.
End User:
Food manufacturers dominate technical co-development relationships, while food service and retail channels prioritize cost efficiency and supply security over formulation partnership.
- Food Manufacturers:Industrial processors of packaged goods maintain direct supplier relationships for batch consistency and regulatory documentation. German and Belgian manufacturing clusters require on-site application laboratories and rapid prototype turnaround as standard commercial terms.
- Food Service:Commercial kitchens and catering operations purchase pre-formulated ingredient systems for operational simplicity.
- Retailers:Private-label product development teams source ingredients through consolidated procurement functions with limited technical service expectations.
- Restaurants:Fine dining and chain operators utilize specialty ingredients for menu differentiation, though volumes remain fragmented.
Food Manufacturers absorb the majority of specialty ingredient volume. Food Service is climbing the fastest as centralized commissary kitchens expand across Poland and Romania.
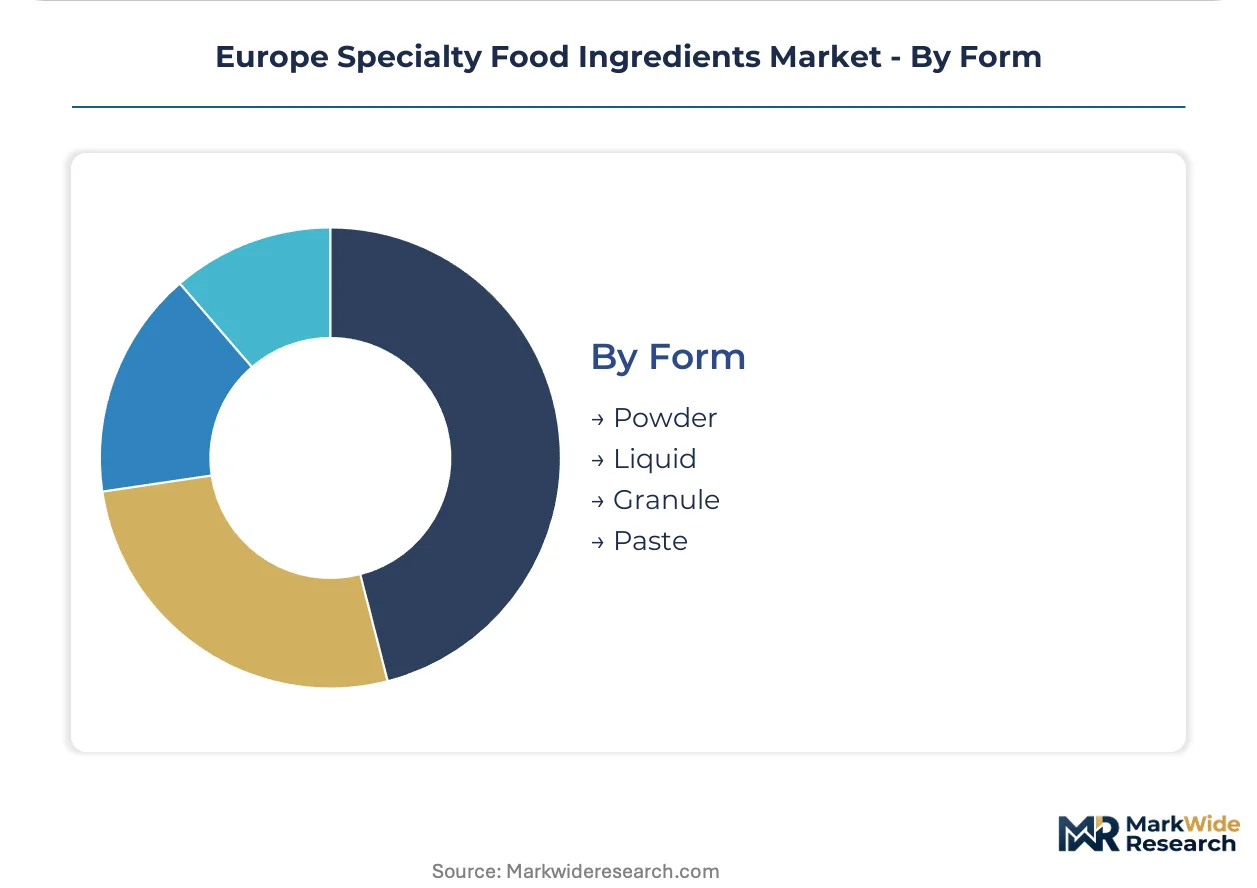
Form:
Powder and liquid formats dominate high-volume applications, while granule and paste forms address specific handling and solubility requirements in smaller-batch processing.
- Powder:Spray-dried and agglomerated powders offer storage stability, precise dosing, and ease of dispersion in dry-mix applications. Bakery premix manufacturers across Germany and France specify powder emulsifiers for consistent distribution in flour blends.
- Liquid:Pumpable concentrates simplify metering in continuous processing lines and enable faster hydration in high-moisture systems. Dutch dairy processors prefer liquid modified starches for direct injection into HTST pasteurization circuits.
- Granule:Free-flowing granules reduce dusting and improve flowability in pneumatic conveying systems.
- Paste:Semi-solid preparations concentrate active ingredients for minimal dosage in high-value flavor applications.
Powder retains the broadest installed base. Liquid is expanding most quickly as continuous processing lines proliferate in Central European dairy operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized regulatory toxicologists and EFSA dossier specialists cluster in the Netherlands, Belgium, and Germany, anchoring the continent's compliance infrastructure for specialty ingredient suppliers.
Germany
Clean-label bakery reformulation drives procurement of natural emulsifiers and enzyme-based dough strengtheners. REACH substance evaluation timelines from ECHA compress registration windows for novel ingredients. The Baden-Württemberg and Bavaria manufacturing corridors concentrate dairy and confectionery processing capacity requiring modified starches.
Netherlands
Large-scale dairy cooperatives specify high-performance modified starches with precise amylose-amylopectin ratios for premium mouthfeel control. CSRD disclosure mandates accelerate supplier qualification protocols demanding Scope 3 carbon data. The Randstad cluster hosts application laboratories serving technical co-development partnerships with food manufacturers.
Belgium
Chocolate and confectionery processors drive demand for emulsifiers managing fat bloom control in high-cocoa applications. EU Green Deal carbon-accounting requirements elevate procurement criteria for low-carbon ingredient sourcing. The Flanders processing belt integrates with Dutch dairy networks for cross-border starch and enzyme supply.
France
Artisanal bakery producers accelerate fermentation-derived flavoring adoption for clean-label positioning. EFSA novel food classification guidance shapes dossier preparation requirements for biotechnology-derived ingredients. The Île-de-France and Auvergne-Rhône-Alpes regions concentrate savory and dairy application development.
Poland
Expanding ready-meal and dairy manufacturing capacity creates first-mover positioning for emulsifier and starch suppliers. National adoption of EU CSRD timelines lags Western counterparts by twelve to eighteen months, creating transitional procurement windows. The Łódź and Warsaw manufacturing zones attract Central European food service commissary investment.
Europe Specialty Food Ingredients Market Competitive Landscape
The competitive structure tilts toward integrated taste-and-nutrition platforms with established regulatory affairs infrastructure. Consolidation among mid-cap specialists continues as REACH registration costs and CSRD compliance investments strain standalone balance sheets. Three archetypes dominate: diversified ingredient conglomerates with merger-scale R&D footprints, biotechnology-focused flavor and protein developers, and regional application laboratories with technical service depth. Competitive moves concentrate on portfolio diversification into precision fermentation platforms and backward integration into agricultural upstream.
Within the integrated platform tier, Kerry Group and DSM-Firmenich exemplify scale-driven positioning anchored by combined taste, nutrition, and enzymatic solution portfolios. Givaudan SA occupies a specialist position representing biotechnology-forward extraction and natural flavor molecule development. Archer Daniels Midland Company and Cargill, Incorporated sit within the agricultural-origin conglomerate archetype, leveraging oilseed and grain processing integration for lecithin and starch derivative supply.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Kerry Group |
| Givaudan SA |
| Cargill, Incorporated |
| International Flavors & Fragrances Inc. |
| DSM-Firmenich |
| Tate & Lyle PLC |
| Ingredion Inc. |
| Roquette Freres |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between REACH-registered premium ingredients and unregistered commodity alternatives manifests in parallel supply chain configurations across the continent. Premium-tier suppliers command pricing power through ECHA dossier completion and CSRD carbon verification, while commodity traders compete on spot-market lecithin and unmodified starch flows from Eastern European oilseed processors.
Pricing Analysis
Bundled technical service contracts separate premium pricing from unbundled commodity transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with REACH-compliant natural emulsifiers carrying substantial premiums over synthetic alternatives. Cost compression in economy-tier modified starches is intensifying because South American soy harvest volatility feeds raw material uncertainty. Food service distributors exhibit highest price sensitivity, while Dutch dairy cooperatives prioritize batch consistency over unit cost.
Supply Chain Analysis
REACH registration and EFSA novel food qualification requirements gate supplier participation and concentrate procurement relationships among validated incumbents. Raw material sourcing draws from South American soy processors, Eastern European sunflower seed crushers, and Southeast Asian palm kernel operations. Single-source vulnerability runs through fermentation-derived flavor precursors dependent on Danish and Dutch precision fermentation capacity. Distribution runs through integrated ingredient platforms with regional technical laboratories rather than traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Clean-label bakery reformulation across Germany, France, and Italy pulls procurement toward premium natural emulsifiers and fermentation-derived flavorings with verified carbon footprints.
For Market Incumbents: Cement regulatory affairs infrastructure as the primary defensive moat. ECHA substance evaluation timelines and EFSA novel food dossier requirements create multi-year barriers that block mid-tier entrants from biotechnology-derived categories. Backward integration into South American and Eastern European oilseed processing secures lecithin supply against harvest volatility. Prioritize on-site application laboratories in the Netherlands-Belgium corridor where technical co-development partnerships are becoming standard commercial terms. For New Entrants and Emerging Players: Capture first-mover positioning in Poland and Romania where expanding ready-meal and dairy manufacturing capacity outpaces established supplier technical service coverage. National adoption of EU CSRD timelines in these markets lags Western counterparts, creating transitional procurement windows for carbon-verified ingredient suppliers. Target centralized food service commissary kitchens with pre-formulated stabilizer systems that eliminate on-site technical support requirements. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH registration costs and CSRD compliance investments strain standalone mid-cap balance sheets. Long-term viability favors integrated taste-and-nutrition platforms with merger-scale R&D footprints and established EFSA dossier capabilities. Acquisition target archetype: regional application laboratories with technical service depth in underpenetrated Central European markets. Watch EFSA guidance evolution on precision fermentation-derived novel foods as the inflection indicator for platform valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Platform Scale-Up | Enables commercial volumes of natural flavor molecules that satisfy EFSA novel food safety requirements. |
| Backward Integration into Oilseed Processing | Captures South American and Eastern European lecithin supply chains against harvest volatility exposure. |
| CSRD Carbon Verification Deployment | Accelerates supplier qualification protocols under Corporate Sustainability Reporting Directive mandates. |
| Regional Application Laboratory Expansion | Meets German and Belgian manufacturing cluster demands for on-site technical co-development partnerships. |
| Digital Product Passport Integration | Creates service revenue streams from blockchain-verified ingredient provenance systems under EU AI Act traceability requirements. |
Research Methodology
Direct dialogue with EFSA regulatory affairs consultants, Dutch dairy cooperative procurement directors, German bakery R&D managers, and precision fermentation platform engineers grounded qualitative assessment. Secondary validation drew from ECHA substance registration databases, EU CSRD implementation guidance, Cefic chemical industry reports, and customs trade flow records for lecithin and modified starch categories. Bottom-up volume modeling across product segments triangulated against top-down market sizing from manufacturing capacity and consumption intensity indicators.
Bottom-up segment analysis modeled emulsifier, modified starch, sweetener, and flavoring categories across bakery, dairy, confectionery, and sauce applications. Deployment patterns by food manufacturer, food service, retail, and restaurant end users shaped adoption curve assumptions across the projection horizon. CAGRs derived from historical volume trajectories adjusted for REACH compliance cost pass-through and CSRD-driven supplier consolidation. Key inputs included ECHA registration timeline projections and precision fermentation platform commercialization schedules from Netherlands and Denmark pilot facilities.
EFSA novel food classification shifts, ECHA substance restriction accelerations, and EU Green Deal carbon border adjustment implementations are the dominant revision risks. Forecasts assume stable regulatory implementation timelines and continued clean-label demand trajectory across core Western European markets. Deviation in EFSA guidance on biotechnology-derived ingredient safety assessments would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Specialty Syrup Market
Specialty Ingredients
Global Sea Buckthorn Oil Market
Specialty Ingredients
Global Pet Food Flavors Market
Specialty Ingredients
Specialty Carbohydrates Market
Specialty Ingredients
Food Decorations and Inclusions Market
Specialty Ingredients
North America Grape Seed Extract Market
Specialty Ingredients
Normal and Specialty Fats Market
Specialty Ingredients
Grape Seed Extract in Pet Food Application Market
Specialty Ingredients
Mangosteen Market
Specialty Ingredients
Specialty Mint Oils Market
Specialty Ingredients
Vanilla Extract Alternatives Market
Specialty Ingredients
North America Specialty Food Ingredient Market
Specialty Ingredients
Global Fruit and Vegetable Powder Market
Specialty Ingredients
Agarwood Essential Oil Market
Specialty Ingredients
Vetiver Oil Market
Specialty Ingredients
Mangosteen Extract Market