
 Floral Water Market | 2026-2036
Floral Water Market Size, Share, and Industry Trends Forecast 2026-2036
Floral Water Market Analytics
Certified organic distillation expertise is reorganizing competitive dynamics in floral water production. Alteya Organics leverages its Bulgarian rose valley operations to sustain year-round hydrosol supply chains. Mountain Rose Herbs anchors North American distribution through direct-to-practitioner channels. Florihana competes on small-batch copper still methods that appeal to aromatherapy professionals.
Floral water denotes the aqueous condensate recovered during steam or hydro-distillation of aromatic plant material, typically containing trace essential oil constituents at concentrations below one percent and serving as a functional ingredient in topical and sensory applications. Organic floral water commands premium positioning due to EC 834/2007 compliance costs and limited certified biomass availability, while hydrosols represent the fastest-expanding category as formulators replace synthetic fragrances in rinse-off products. Essential oil blends occupy a mature niche where margin pools depend on backward integration into distillation assets rather than blending alone.
EMA guidelines on herbal medicinal products, REACH Annex XVII restrictions on residual solvents, and ISO 9001 quality management standards collectively shape product specifications and market access for European floral water suppliers. FDA cosmetic labeling requirements in the United States impose additional substantiation burdens on aromatherapy claims. Stakeholders must monitor evolving definitions of "natural" and "naturally derived" across jurisdictions to anticipate reformulation mandates and procurement specification shifts.
Market Dynamics
Clean-label cosmetics procurement is consolidating hydrosol demand around certified organic distillation capacity, with REACH Annex XVII solvent thresholds and EC 834/2007 compliance costs filtering supplier pools across European formulation hubs.
Growth Catalysts
- REACH solvent thresholds:Tightening residual limits for botanical extracts in Europe are disqualifying conventional solvent-based alternatives, redirecting procurement toward steam-distilled hydrosols.
- Rinse-off cosmetics:Formulators replacing synthetic fragrance systems in shampoos and body washes are specifying hydrosols as functional water-phase ingredients.
- Bulgaria's Rose Valley:Concentrated damask rose distillation infrastructure anchors regional supply security for premium organic floral water.
Market Restraints
- Certified biomass scarcity:EC 834/2007 organic certification limits available rose and lavender feedstock, inflating raw material costs for compliant producers.
- Single-region concentration:Bulgaria and France together control the majority of EU organic hydrosol distillation capacity, creating geographic supply risk.
- Synthetic fragrance substitution:Low-cost artificial aroma chemicals remain economically viable for mass-market rinse-off applications.
Strategic Opportunities
- North American practitioner channels:Direct distribution to aromatherapy professionals and holistic health practitioners remains underdeveloped outside established coastal markets.
- Copper still small-batch positioning:Traditional distillation methods command premium pricing from professional aromatherapists seeking traceable provenance.
- EU Green Deal bioeconomy incentives:Circular economy funding streams support investment in zero-waste distillation systems utilizing agricultural byproducts.
Industry Challenges
- Organic certification timelines:EC 834/2007 conversion periods and audit backlogs delay new entrant market access by 24-36 months.
- Distillation asset intensity:Copper still fabrication and biomass storage infrastructure require capital deployment that fragments producer scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floral Water Market |
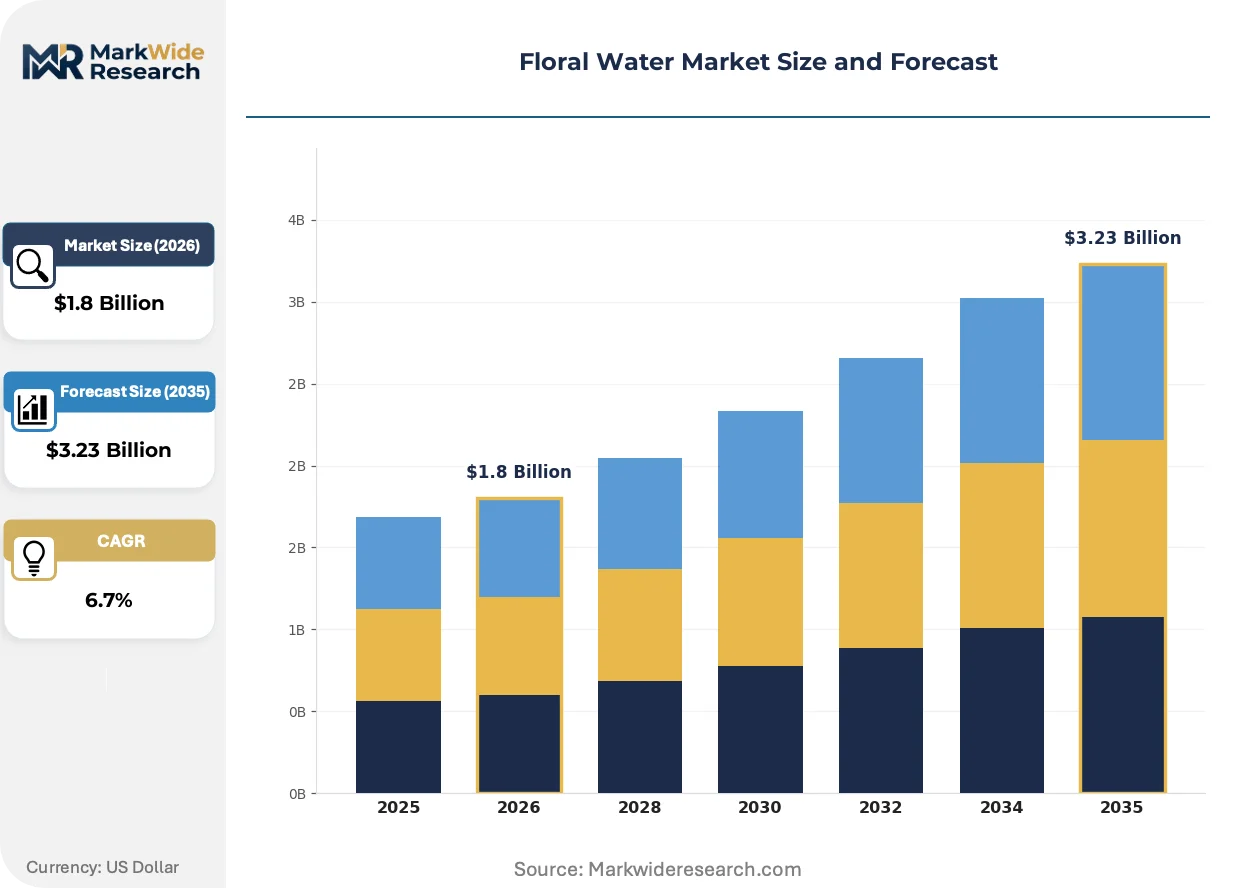
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Floral Water, Synthetic Floral Water, Hydrosols, Essential Oil Blends Application: Cosmetics, Skincare, Aromatherapy, Food & Beverage Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales End User: Consumers, Manufacturers, Retailers, Health Professionals |
| Companies Covered | Mountain Rose Herbs, Plant Therapy Essential Oils, Alteya Organics, Florihana, Apivita, Melvita, Aura Cacia, Neal's Yard Remedies, Heritage Store, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floral Water Market Evolving Landscape
Steam distillation technology is segmenting into parallel quality tiers as professional and mass-market buyers diverge in specification requirements. This technical schism is reshaping capital allocation across equipment categories.
Copper still hydrosol production is bifurcating market tiers. Small-batch artisanal distillers serve aromatherapy professionals demanding traceable provenance and therapeutic-grade specifications. Industrial stainless-steel column systems supply cosmetic manufacturers prioritizing volume consistency and cost efficiency. This equipment divergence is compressing mid-scale producer margins as buyers sort into distinct quality-price brackets.
REACH Annex XVII residual solvent restrictions are tightening extractive processing standards. The regulation mandates sub-ppm thresholds for hexane and other petrochemical solvents in botanical preparations. Cosmetic formulators in France and Germany are responding by rewriting procurement specifications to exclude solvent-extracted fragrance materials.
Ingredient sourcing is consolidating around direct farm partnerships. Cosmetic brands are bypassing traditional wholesale distributors to contract specific harvest lots from Bulgarian and Moroccan distillers. This channel compression is most visible in premium skincare lines targeting EU and US consumers with batch-traceable claims.
Floral Water Market Segmentation
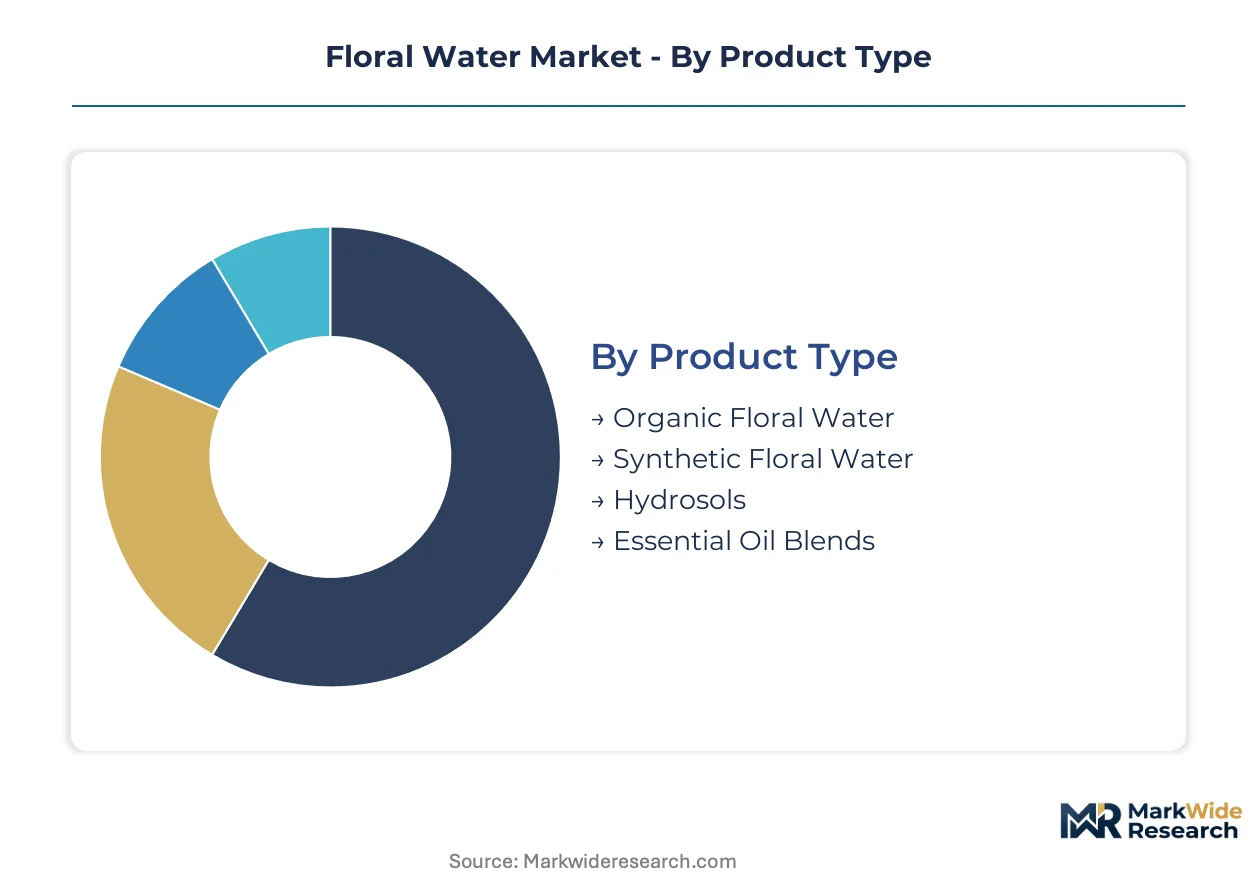
Segmentation in floral water markets tracks how certification standards, distillation methods, and channel structures partition value capture across producer tiers. Buyers sort into distinct specification brackets that reshape procurement patterns and margin distribution.
Product Type:
Domestic consumption concentrates on certified organic grades in France and Bulgaria, while export-led demand pulls hydrosols toward North American cosmetic formulators and Asian skincare manufacturers.
- Organic Floral Water:Steam-distilled condensate from EC 834/2007 certified biomass, containing trace volatile compounds below 0.1 percent concentration. French and Bulgarian distillers anchor supply for EU clean-label cosmetic lines facing REACH Annex XVII compliance mandates. Certified biomass scarcity inflates raw material costs and extends procurement timelines.
- Hydrosols:Aqueous co-products of essential oil distillation, standardized for functional water-phase applications in rinse-off formulations. North American procurement is accelerating as cosmetic brands replace synthetic fragrance systems; Bulgarian Rose Valley infrastructure dominates premium supply security.
- Synthetic Floral Water:Laboratory-compounded aroma solutions mimicking natural hydrosol profiles. Mass-market personal care brands in emerging economies specify these for cost-sensitive body care lines.
- Essential Oil Blends:Concentrated aromatic preparations requiring dilution for topical use. Aromatherapy practitioners and spa operators drive specification, with margin pools dependent on backward integration into distillation assets.
Organic floral water commands the established base. The steepest expansion runs through hydrosols.
Application:
Volume concentration tracks formulation complexity, with multi-ingredient cosmetic systems absorbing larger hydrosol volumes than single-note aromatherapy applications.
- Cosmetics:Functional water-phase ingredient in emulsions, toners, and setting sprays. Rinse-off shampoo and body wash formulations in France and Germany are specifying hydrosols to meet clean-label procurement mandates under REACH solvent restrictions.
- Skincare:Standalone topical mist and toner applications requiring batch-traceable provenance. Premium lines target EU and US consumers with direct farm partnerships from Bulgarian and Moroccan distillers.
- Aromatherapy:Sensory and therapeutic applications demanding copper still methods and small-batch traceability. Professional practitioners in coastal US markets and German wellness clinics drive specification.
- Food & Beverage:Flavoring and aromatic finishing for craft beverages and confectionery. Regulatory divergence between FDA GRAS status and EFSA novel food assessments fragments formulation approval pathways.
Cosmetics absorbs the dominant volume share. Skincare is climbing the fastest as direct-to-consumer premium lines proliferate.
Distribution Channel:
Channel selection correlates with buyer sophistication, as professional formulators bypass retail intermediaries while consumers depend on curated access points.
- Direct Sales:Bulk procurement contracts between cosmetic manufacturers and distiller cooperatives in Bulgaria's Rose Valley. Batch-traceable claims and harvest lot documentation command premium positioning.
- Specialty Stores:Curated retail environments targeting aromatherapy professionals and holistic health practitioners. German and French urban markets sustain highest per-square-meter throughput for certified organic grades.
- Online Retail:Direct-to-consumer platforms enabling small-batch artisanal distillers to reach geographically dispersed practitioner networks. North American coastal markets show strongest conversion for copper still provenance claims.
- Supermarkets:Mass-market personal care aisles in France, Germany, and US suburban corridors. Synthetic and lower-grade hydrosols compete on shelf price against artificial fragrance alternatives.
Direct sales captures the volume anchor. Online retail is expanding most quickly as practitioner networks digitize procurement.
End User:
User type determines specification stringency, with commercial manufacturers imposing stricter documentation requirements than individual consumers.
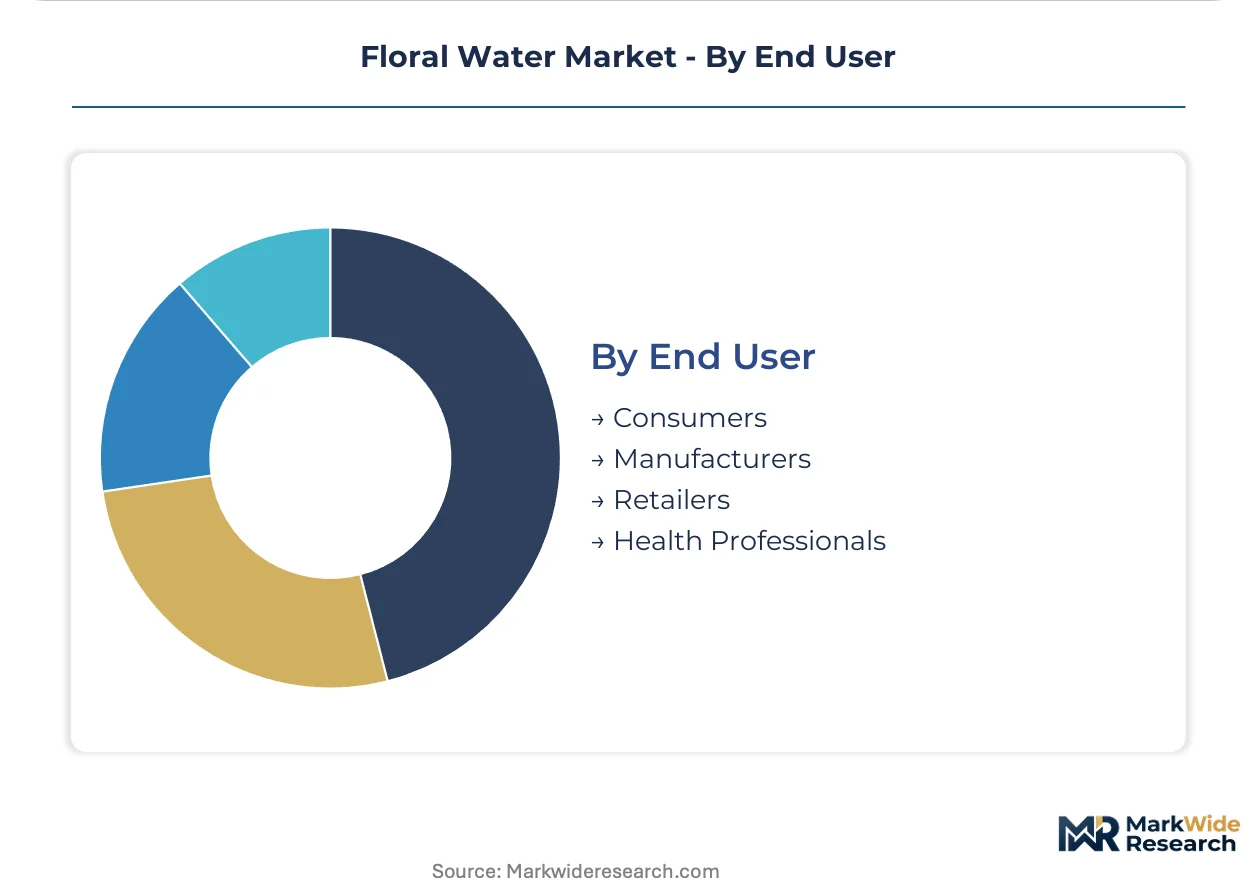
- Manufacturers:Cosmetic and personal care formulators requiring certificate of analysis, organic certification, and REACH compliance documentation. French and German procurement teams are rewriting specifications to exclude solvent-extracted materials.
- Health Professionals:Aromatherapists, naturopaths, and spa operators seeking therapeutic-grade specifications and traceable provenance. Small-batch copper still methods command loyalty in this segment.
- Consumers:Individual purchasers of retail skincare and home fragrance products. Clean-label awareness drives premium willingness in urban EU and US markets.
- Retailers:Curators of specialty and department store beauty assortments. Margin pressure from synthetic alternatives constrains organic floral water shelf space in mass-market environments.
Manufacturers dominate procurement volume. Health professionals are gaining share fastest as practitioner channel infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France consumes floral water predominantly through high-end cosmetic formulation, while Bulgaria specializes in raw material export and the United States channels demand through practitioner-direct networks. This tripartite consumption split shapes divergent regulatory exposure and supply chain investments across the three markets.
France
Cosmetic formulators in Paris and Grasse specify certified organic hydrosols for clean-label skincare lines targeting EU consumers. REACH Annex XVII solvent restrictions are disqualifying conventional fragrance materials from procurement lists. The Grasse perfume cluster is retooling distillation partnerships toward steam-extracted alternatives.
Bulgaria
Damask rose hydrosol output from the Rose Valley anchors regional supply security for premium organic grades. EC 834/2007 compliance costs and certified biomass scarcity limit new entrant expansion. Kazanlak-based distillers are extending direct farm partnerships to cosmetic brands bypassing wholesale intermediaries.
United States
Aromatherapy practitioners and holistic health professionals drive specification for copper still hydrosols with traceable provenance. FDA cosmetic labeling requirements impose substantiation burdens on therapeutic claims. Coastal markets in California and Oregon sustain highest per-capita consumption of artisanal floral water grades.
Germany
Wellness clinics and spa operators in Bavaria and Baden-Württemberg procure therapeutic-grade hydrosols for sensory applications. EMA guidelines on herbal medicinal products shape quality documentation requirements for professional channels. The Black Forest region hosts small-batch distillers serving domestic aromatherapy networks.
Floral Water Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding backward integration into certified biomass and distillation assets. The middle layer fragments across geographic niches and certification grades. Three archetypes dominate: valley-integrated rose specialists, copper-still artisanal producers, and practitioner-channel distributors. Competitive moves concentrate on direct farm partnerships and online retail infrastructure expansion.
Among valley-integrated producers, Alteya Organics represents the archetype of certified organic distillation with captive biomass access. Florihana exemplifies copper still small-batch positioning for professional aromatherapy markets. Mountain Rose Herbs anchors the practitioner-channel distributor archetype through North American direct-to-professional networks.
| Leading Market Players |
|---|
| Mountain Rose Herbs |
| Plant Therapy Essential Oils |
| Alteya Organics |
| Florihana |
| Apivita |
| Melvita |
| Aura Cacia |
| Neal's Yard Remedies |
| Heritage Store |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Bulgarian distillers and French cosmetic houses lock in certified organic hydrosol supply while anchoring price visibility across volatile harvest cycles. These bilateral agreements tether procurement security to EC 834/2007 compliance costs, insulating premium-tier buyers from spot-market biomass scarcity.
Pricing Analysis
Long-term offtake agreements dominate premium organic grades, with price differentiation resting on EC 834/2007 certification tier and copper still batch traceability. Three-tier pricing structure across premium, standard, and economy levels stratifies by distillation method and harvest lot documentation. Cost compression in mass-market synthetic alternatives is intensifying because artificial fragrance compounds undercut steam-distilled hydrosols on unit economics. Mass-market personal care manufacturers exhibit highest price sensitivity, while aromatherapy professionals demonstrate lowest sensitivity to provenance premiums.
Supply Chain Analysis
Rose Valley distillation infrastructure in Bulgaria represents a geographic chokepoint that concentrates premium damask rose hydrosol output. Supply draws from certified organic rose biomass, copper still fabrication capacity, and REACH-compliant solvent-free extraction systems. Single-region concentration in Bulgaria and France creates structural vulnerability to climate-induced harvest volatility. Distribution runs through direct farm partnerships, specialty retail channels, and online practitioner networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Floral water procurement is shifting toward platform-mediated direct contracting between distillers and cosmetic formulators, with interoperability between batch-traceability systems and EU Green Deal bioeconomy reporting standards reshaping ecosystem economics.
For Market Incumbents: Compound backward integration into certified biomass assets to defend margin pools against emerging copper still artisanal entrants. Secure captive supply of EC 834/2007-certified rose and lavender feedstock in Bulgaria's Rose Valley. Deepen channel control through proprietary online retail infrastructure targeting North American aromatherapy practitioners. For New Entrants and Emerging Players: Differentiate on small-batch copper still provenance to penetrate underdeveloped health professional channels in German wellness clinics and US coastal markets. Target direct-to-practitioner distribution as the most penetrable route, bypassing consolidated wholesale intermediaries. Pursue EU Green Deal circular economy funding to finance zero-waste distillation systems utilizing agricultural byproducts. For Investors and Strategic Acquirers: Valley-integrated organic distillers with captive Rose Valley biomass access represent the highest-conviction acquisition archetype for long-horizon positioning. Monitor REACH Annex XVII enforcement intensity as the critical inflection signal for solvent-extracted material displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Organic Distillation Capacity Expansion | EC 834/2007 compliance secures access to EU clean-label cosmetic procurement pipelines. |
| Direct Farm Partnership Contracts | Bypassing wholesale intermediaries captures margin from batch-traceable premium skincare lines. |
| Copper Still Small-Batch Positioning | Therapeutic-grade specifications command loyalty from professional aromatherapy practitioners. |
| Online Retail Infrastructure Buildout | Digital channels enable geographic reach to dispersed North American practitioner networks. |
| EU Green Deal Bioeconomy Certification | Circular economy credentials unlock public funding for zero-waste distillation investments. |
Research Methodology
Desk research of customs trade databases, EC 834/2007 certification registries, and REACH enforcement precedents preceded structured interviews with distiller cooperative managers, cosmetic procurement leads, aromatherapy practitioners, and specialty retail buyers. Primary fieldwork across Bulgaria's Rose Valley and France's Grasse cluster was cross-validated against ECHA regulatory filings and EU organic production statistics. Bottom-up biomass availability modeling was triangulated with top-down cosmetic formulation demand estimates.
Variance decomposition across product type, application, distribution channel, and end user dimensions anchored the analytical framework throughout the forecast period. CAGRs were derived from segment-level demand elasticity modeling and supply-constrained biomass growth curves. Hydrosol substitution rates for synthetic fragrances and certified organic conversion timelines served as industry-specific forecast inputs.
Material uncertainties — regulatory redefinition of "naturally derived" claims, climate volatility in Bulgarian harvest yields, and REACH solvent threshold revisions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding biomass certification pipeline velocity and practitioner channel digitalization rates. Practitioners should keep alternative scenarios live as EU Green Deal bioeconomy incentive structures and FDA cosmetic labeling enforcement postures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Tea-Based Skin Care Products Market
Specialty Ingredients
Europe Specialty Food Ingredients Market
Specialty Ingredients
Specialty Food Ingredients Market
Specialty Ingredients
Green Sic Market
Specialty Ingredients
Pericarp Waste Market
Specialty Ingredients
Normal and Specialty Fats Market
Specialty Ingredients
Sun-Care Natural Oils Market
Specialty Ingredients
Benzoe Siam Market
Specialty Ingredients
Personal Care Specialty Ingredients Market
Specialty Ingredients
Specialty Syrup Market
Specialty Ingredients
Specialty Ingredients Market
Specialty Ingredients
Specialty Shortenings Market
Specialty Ingredients
Evening Primrose Oil Market
Specialty Ingredients
Aromatherapy Carrier Oil Market
Specialty Ingredients
Fermentation Products Market
Specialty Ingredients
Gentian Market