
 Specialty Beverage Stabilizers Market | 2026-2036
Specialty Beverage Stabilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Beverage Stabilizers Market Outlook
Asset-light toll manufacturing and third-party blending agreements is rewriting competitive entry dynamics for mid-tier stabilizer suppliers. Cargill leverages its integrated agricultural supply chain to control raw gum and starch input costs across multiple continents. Ingredion anchors its position through deep R&D partnerships with North American and European beverage formulators seeking texture-system customization.
Specialty beverage stabilizers comprise hydrocolloid, emulsifier, protein, and starch-based compounds engineered to maintain suspension, viscosity, and phase integrity in complex liquid matrices, typically functioning within pH ranges of 2.5 to 7.0 and thermal processing windows up to 121°C. Their primary commercial purpose is to extend shelf life while delivering consistent mouthfeel in beverages containing pulp, protein, fat, or functional actives. Emulsifiers and gums currently dominate value capture due to irreplaceable performance in dairy-alternative and functional beverage applications, while protein-based stabilizers represent the fastest-expanding margin pool as plant-protein beverage formulations proliferate. Powder formulations retain the largest volume share for industrial-scale procurement, though liquid delivery systems are gaining traction in automated batching environments.
FDA food additive regulations, EFSA novel food assessments, and FSSAI ingredient approval pathways collectively determine which stabilizer chemistries achieve commercial scale in their respective jurisdictions, with clean-label positioning now a de facto market access requirement rather than premium differentiation. The EU Green Deal and associated Farm-to-Fork targets are tightening scrutiny of synthetic emulsifier petitions while accelerating natural hydrocolloid qualification timelines. Stakeholders must monitor evolving jurisdiction-specific permissible daily intake revisions and invest in preemptive regulatory dossier preparation for emerging protein and fermentation-derived stabilizer platforms.
Market Dynamics
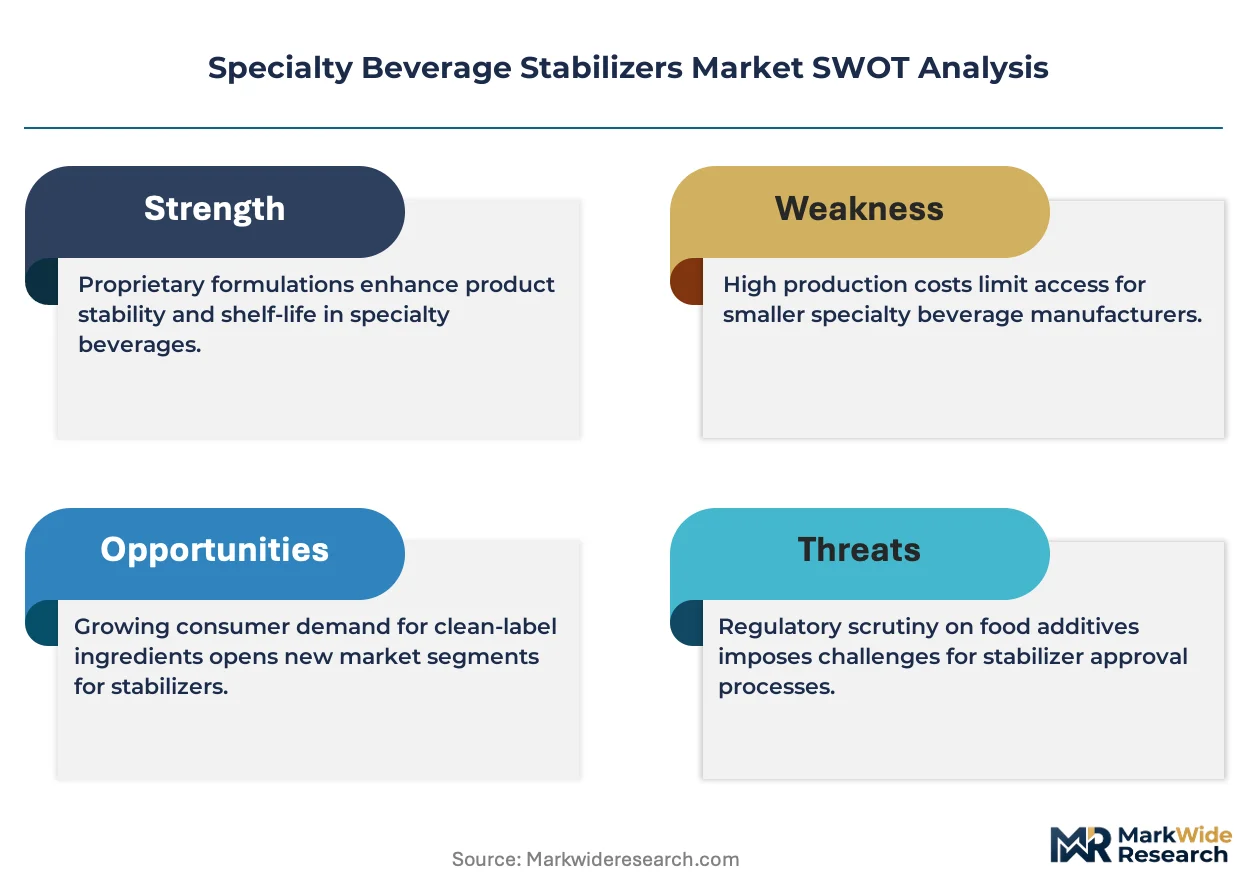
Clean-label regulatory mandates from the FDA and EFSA are forcing beverage manufacturers to abandon synthetic emulsifiers in favor of natural hydrocolloid and protein-based stabilizer systems, compressing reformulation timelines and redrawing supplier qualification criteria.
Growth Catalysts
- FDA Clean-Label Pressure:Petition backlogs for synthetic additives under 21 CFR are accelerating natural gum adoption in U.S. functional beverage lines.
- Plant-Protein Beverage Proliferation:Oat, pea, and fava protein formulations require specialized stabilizer architectures to prevent phase separation during thermal processing.
- Germany:Premium private-label beverage innovation cycles in this market are the shortest globally, driving rapid stabilizer qualification and volume procurement.
Market Restraints
- Locust Bean Supply Concentration:Over 70% of global carob gum raw material originates from Morocco and Portugal, creating price volatility exposure.
- EFSA Novel Food Timelines:Fermentation-derived stabilizer platforms face 18-24 month safety assessment windows that delay commercial scale-up.
- Technical Limitation:Current natural emulsifier alternatives fail to match mono- and diglyceride performance in high-fat dairy alternatives above 5% lipid content.
Strategic Opportunities
- Japan:Aging demographics and convenience-store beverage culture create underpenetrated demand for shelf-stable functional drinks with extended stability windows.
- EU Green Deal Incentives:Farm-to-Fork targets subsidize agricultural waste-to-hydrocolloid processing, lowering input costs for pectin and cellulose derivatives.
- Automated Batching Systems:Liquid stabilizer delivery formats are displacing powder handling in North American and European contract manufacturing facilities.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Beverage companies struggle to hire specialists capable of integrating clean-label stabilizers into complex pH and thermal processing matrices.
- Multi-Jurisdiction Dossier Costs:Simultaneous FDA GRAS, EFSA novel food, and FSSAI ingredient approval pathways require capital outlays that strain mid-tier stabilizer suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Beverage Stabilizers Market |
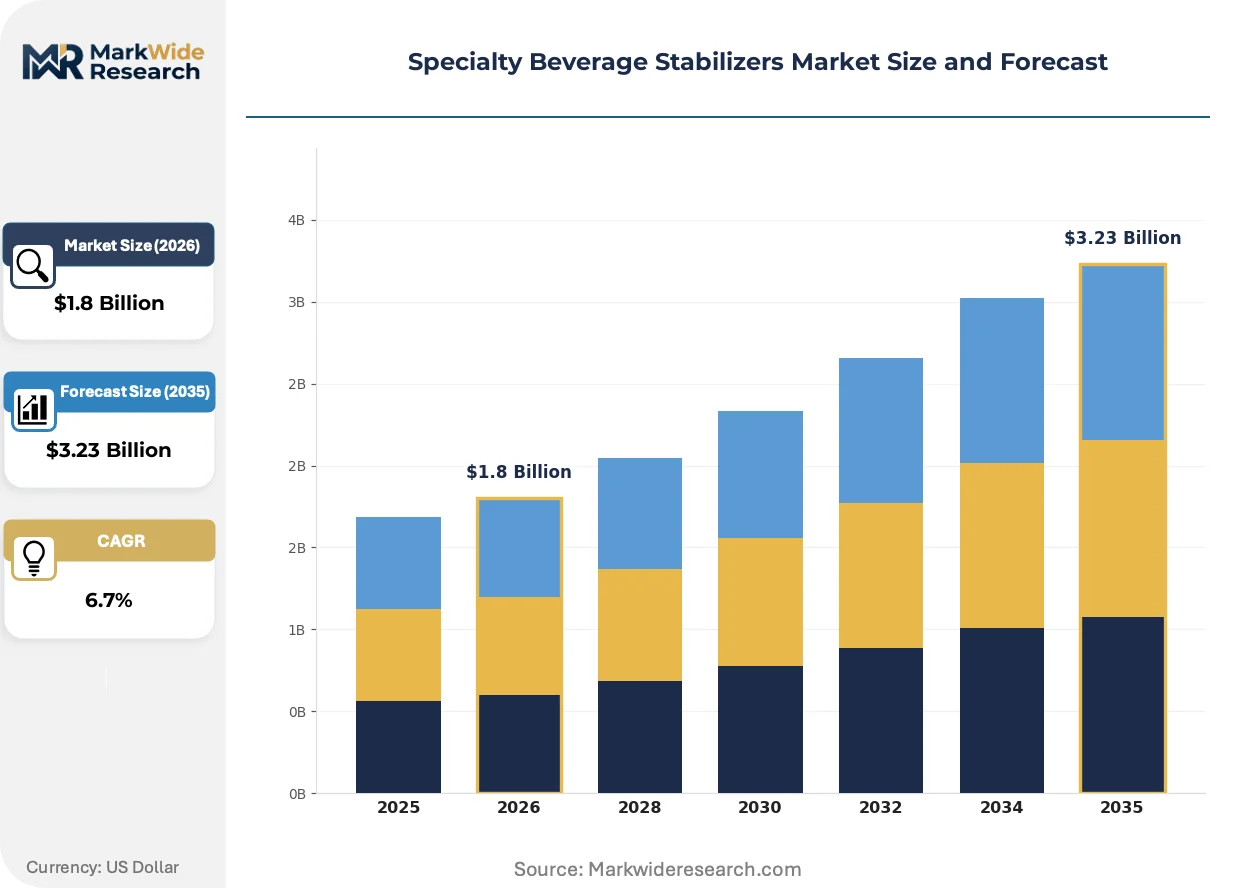
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Stabilizer Type: Emulsifiers, Gums, Starch, Proteins End Use: Soft Drinks, Alcoholic Beverages, Dairy Drinks, Functional Beverages Formulation Type: Liquid, Powder, Granular, Paste Distribution Channel: Online, Wholesale, Supermarkets, Specialty Stores |
| Companies Covered | W. R. Grace, Cargill, BASF, Ingredion, Tate & Lyle, Koninklijke DSM, PQ Corporation, CP Kelco, Ashland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Beverage Stabilizers Market Strategic Shifts
Enzymatic modification of starches and fermentation-derived hydrocolloids are displacing conventional extraction methods, while regulatory jurisdictions compete to establish the dominant safety assessment framework for next-generation stabilizer platforms.
Fermentation-based stabilizer production using precision-cultured microbial strains is rendering obsolete traditional agricultural extraction dependencies. North American and European beverage formulators are accelerating adoption timelines from 36 to 18 months for qualified fermentation-derived ingredients. This technology is compressing supply chain risk exposure while enabling consistent batch-to-batch functional performance previously unattainable with weather-dependent crop harvests.
EFSA's tightened scrutiny of synthetic emulsifier petitions under the EU Green Deal is accelerating natural hydrocolloid qualification timelines while blocking new chemical additive entries. Industrial consequence includes forced reformulation of existing European beverage portfolios containing polysorbates and sorbitan esters. Dairy-alternative and functional beverage segments are responding by pre-qualifying multiple natural gum suppliers to ensure continuity of supply.
Beverage manufacturers are consolidating stabilizer procurement under single-source technical partnerships rather than transactional multi-vendor purchasing. Contract manufacturing channels are being disrupted as brand owners demand direct stabilizer supplier involvement in formulation development. This pattern is most visible in Germany and the United States where premium beverage innovation cycles compress supplier selection windows.
Specialty Beverage Stabilizers Market Segmentation
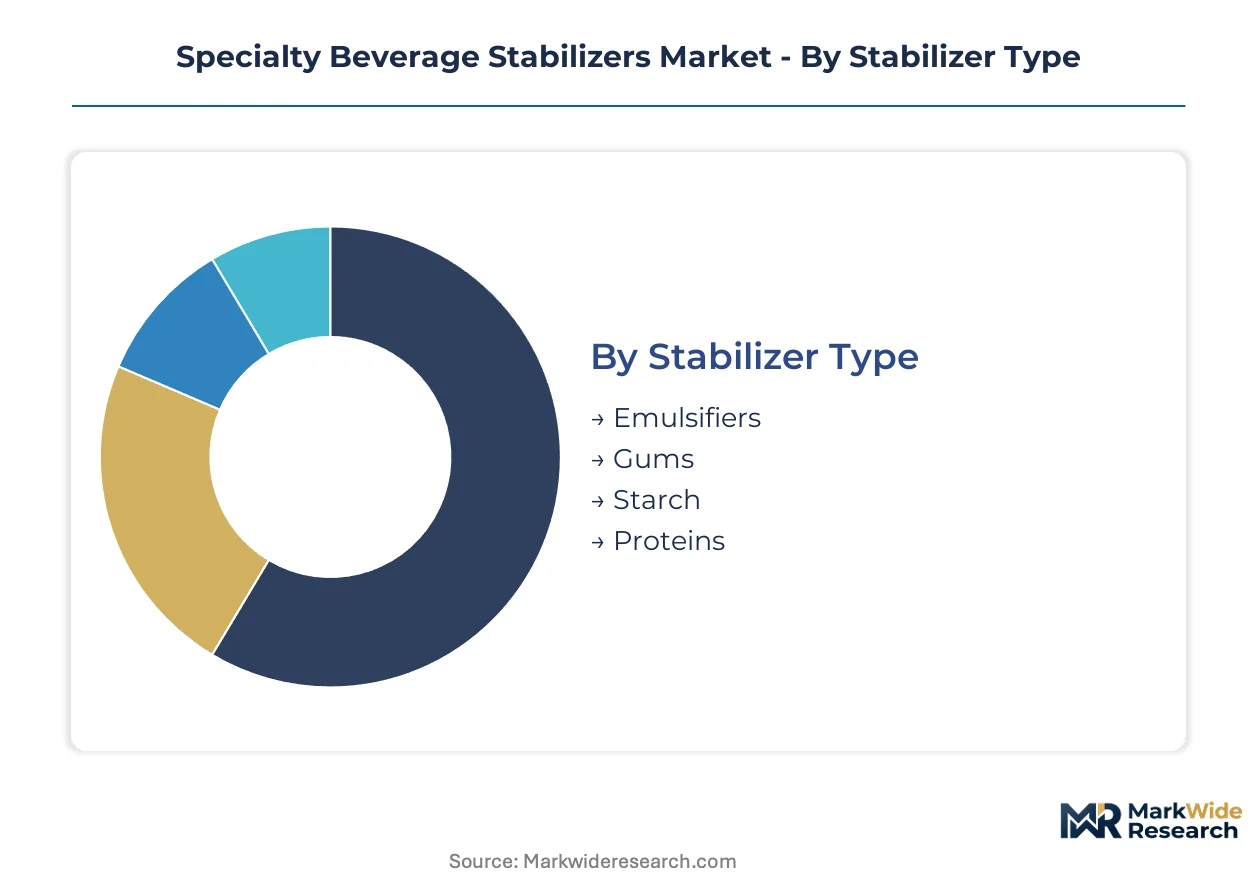
Specialty beverage stabilizers serve distinct functional requirements across pH ranges, thermal processing windows, and shelf-life targets. Segmentation reveals where formulation complexity drives premium pricing versus where commodity procurement dominates.
Stabilizer Type:
Use-case spectrum spans fat emulsification, suspension maintenance, viscosity building, and protein stabilization in complex liquid matrices.
- Emulsifiers:Lipophilic and hydrophilic molecular structures create stable oil-water interfaces in dairy-alternative beverages. Demand concentrates in oat and almond milk formulations where lipid content exceeds 2%, with EFSA's tightened scrutiny of synthetic variants accelerating natural lecithin and gum arabic substitution timelines.
- Gums:Polysaccharide networks from locust bean, guar, and xanthan provide thixotropic flow and particle suspension. Germany's premium private-label beverage manufacturers qualify multiple gum suppliers simultaneously to ensure continuity amid Moroccan and Portuguese supply concentration.
- Starch:Modified and native starches deliver cost-effective viscosity in neutral-pH juice applications. Enzymatic modification processes are displacing conventional extraction in North American facilities seeking cleaner label positioning.
- Proteins:Plant-derived and fermentation-based systems prevent phase separation in high-protein functional beverages. Technical limitations persist in matching mono- and diglyceride performance above 5% lipid content.
Established volume favors emulsifiers; emerging adoption favors proteins.
End Use:
Application maturity ranges from century-old carbonated formulations to fermentation-derived functional actives requiring novel stabilization architectures.
- Functional Beverages:Vitamin-fortified, probiotic, and protein-enriched matrices demand multi-component stabilizer systems capable of surviving UHT processing and extended ambient distribution. Japan's aging demographics and convenience-store culture create concentrated demand for shelf-stable functional drinks with 12-18 month stability windows.
- Dairy Drinks:Traditional milk, flavored milk, and fermented beverages rely on carrageenan and pectin for protein stabilization and mouthfeel consistency. Reformulation pressure from clean-label mandates in the United States is forcing substitution toward locust bean and gellan gum alternatives.
- Soft Drinks:Carbonated and still beverages with pulp or clouding agents require suspension stabilizers that tolerate low pH and high CO2 pressure. Procurement emphasizes cost optimization over technical differentiation.
- Alcoholic Beverages:Beer, wine, and spirits applications use stabilizers for chill haze prevention and flavor emulsion stability. Regulatory complexity from TTB and national alcohol authorities constrains ingredient innovation cycles.
Procurement scale favors soft drinks; margin expansion favors functional beverages.
Formulation Type:
Delivery format selection reflects batch size, automation level, and handling infrastructure investment across manufacturing facilities.
- Powder:Spray-dried and agglomerated formats dominate industrial-scale procurement for dry-blend operations. Volume concentration in North American and European contract manufacturing facilities with established powder handling systems.
- Liquid:Pre-hydrated and cold-water-dispersible solutions enable automated batching and reduced processing time. Adoption is climbing fastest in European facilities upgrading to continuous processing lines.
- Granular:Intermediate particle size reduces dust generation versus fine powders while maintaining rapid dissolution. Preferred in mid-scale beverage operations without pneumatic conveying infrastructure.
- Paste:High-concentration suspensions for specific hydrocolloid applications requiring controlled hydration kinetics. Limited to specialized dairy-alternative and dessert beverage formulations.
Installed base favors powder; capital investment favors liquid.
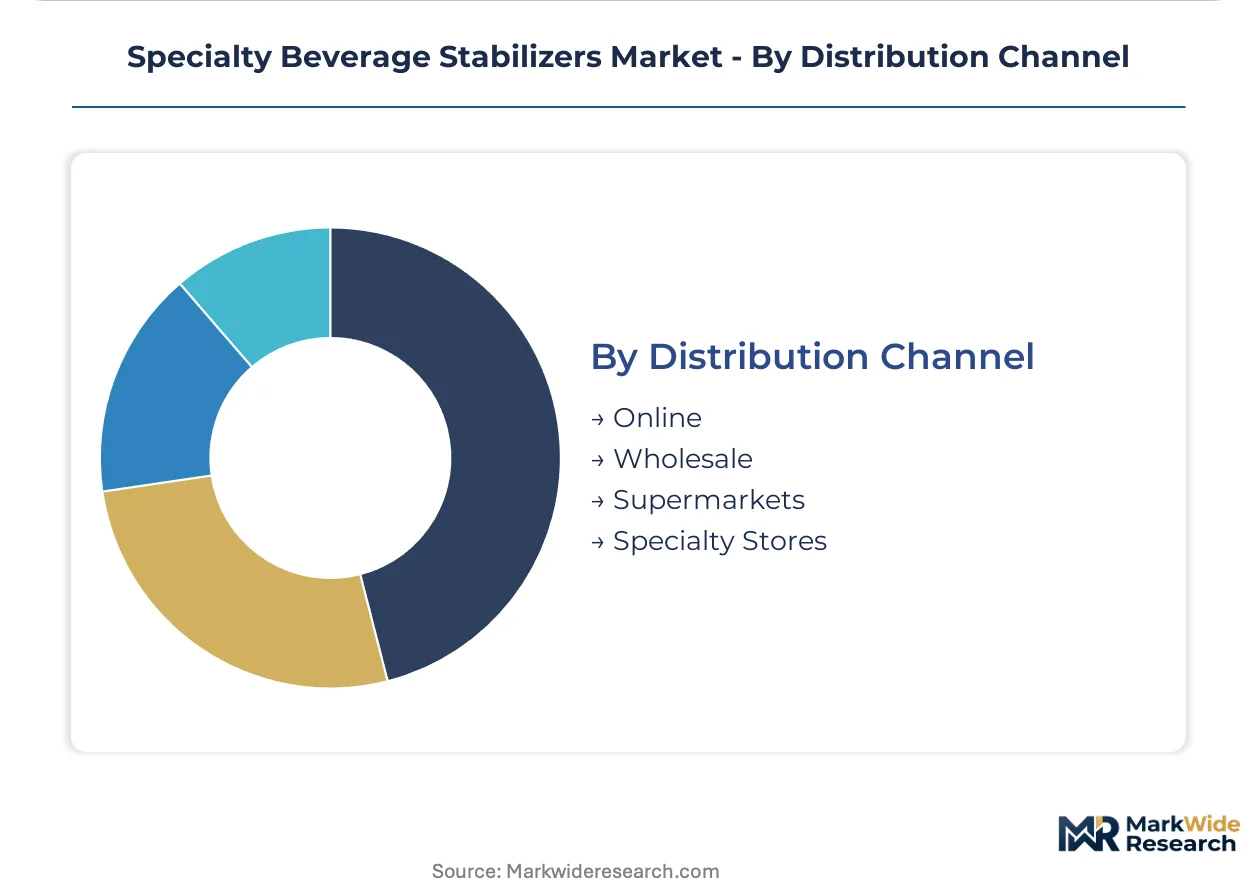
Distribution Channel:
Channel structure separates ingredient procurement for multinational beverage corporations from artisanal and regional formulator access.
- Wholesale:Direct and distributor-mediated bulk sales to beverage manufacturers and contract packers. Cargill and Ingredion anchor this channel through technical service integration and formulation partnership programs.
- Online:E-procurement platforms and direct manufacturer portals serving small-to-mid-tier formulators. Accelerating penetration among craft beverage startups and regional functional drink brands in the United States.
- Supermarkets:Limited retail-packaged stabilizer sales for home beverage preparation and small commercial kitchens. Marginal revenue contribution concentrated in urban centers with strong specialty food retail presence.
- Specialty Stores:Ingredient supply shops and foodservice distributors catering to artisanal beverage producers. Germany's shortest innovation cycles drive rapid stabilizer turnover in this channel.
Volume concentration favors wholesale; growth velocity favors online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in specialty beverage stabilizers reveal concentrated raw material sourcing against dispersed formulation demand. Morocco and Portugal supply over 70% of locust bean gum feedstock, while finished stabilizer consumption clusters in premium beverage manufacturing hubs across three continents.
United States
Functional beverage startups in Austin and Los Angeles drive rapid stabilizer qualification cycles for plant-protein formulations. FDA petition backlogs under 21 CFR accelerate natural gum substitution timelines. Chicago anchors North American contract manufacturing capacity for automated batching systems.
Germany
Premium private-label beverage innovation cycles here compress supplier selection windows to under six months. EFSA novel food assessments under EU Green Deal frameworks block synthetic emulsifier entries. Hamburg and Munich host Europe's densest concentration of beverage formulator technical partnerships.
Japan
Aging demographics and convenience-store culture generate concentrated demand for shelf-stable functional drinks. METI standards for food additive safety shape regional qualification protocols. Tokyo-Osaka corridor dominates Asia-Pacific beverage R&D facility placement.
China
Domestic oat and pea protein beverage brands scale production requiring specialized stabilizer architectures. SAMR ingredient registration pathways determine which hydrocolloid systems achieve commercial scale. Yangtze River Delta beverage clusters source increasingly from regional starch modification facilities.
Brazil
Tropical fruit pulp beverage exports to North America and Europe drive suspension stabilizer procurement. ANVISA regulatory harmonization with Mercosur standards accelerates multi-jurisdiction dossier preparation. São Paulo state concentrates South American beverage contract manufacturing infrastructure.
Specialty Beverage Stabilizers Market Competitive Environment
On the supply side, the industry is consolidating around integrated agricultural processors and specialized hydrocolloid extractors with captive raw material positions. Three archetypes dominate: diversified agribusiness conglomerates controlling upstream gum and starch supply, precision fermentation startups displacing crop-dependent extraction, and regional toll manufacturers offering formulation-as-a-service. Competitive maneuvering concentrates on backward integration into Moroccan and Portuguese locust bean supply chains, alongside accelerated EFSA and FDA regulatory dossier filing for novel protein-based platforms.
Within the integrated agribusiness tier, Cargill and Ingredion exemplify supply chain control strategies spanning multiple continents. CP Kelco occupies a position as a hydrocolloid specialist with extraction technology anchored to specific agricultural geographies. These three entities represent divergent approaches to raw material security—direct agricultural sourcing, deep R&D partnerships, and specialized extraction expertise—each responding to clean-label regulatory compression from FDA and EFSA.
| Leading Market Players |
|---|
| W. R. Grace |
| Cargill |
| BASF |
| Ingredion |
| Tate & Lyle |
| Koninklijke DSM |
| PQ Corporation |
| CP Kelco |
| Ashland |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta's starch modification clusters feed downstream pricing power to North American beverage formulators seeking enzymatically modified alternatives to synthetic emulsifiers. Cost compression in natural hydrocolloid tiers intensifies as Moroccan locust bean harvest volatility transmits through to German and U.S. procurement offices.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-scale and certification-grade differentiation driving tier separation. Pricing stratifies across fermentation-derived premium tiers, standard agricultural-extraction grades, and economy native starch positions. Price erosion runs through economy tiers as Chinese regional suppliers expand enzymatic modification capacity. Craft beverage startups exhibit highest price sensitivity; multinational functional beverage corporations demonstrate lowest sensitivity due to formulation lock-in costs.
Supply Chain Analysis
Extended payment terms from integrated agribusiness conglomerates to Moroccan and Portuguese locust bean cooperatives stabilize upstream supply-chain finance facilities. Raw material dependencies center on Moroccan carob gum, Indian guar seed, and Brazilian pectin feedstock. Single-source vulnerability concentrates in locust bean gum where over 70% of global feedstock originates from two countries. Distribution runs through wholesale technical partnerships anchored by direct supplier-formulator collaboration rather than distributor mediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation chemistry expertise capable of integrating clean-label stabilizers into complex pH and thermal matrices remains scarce across all three major beverage manufacturing hubs, constraining reformulation velocity and supplier qualification throughput.
For Market Incumbents: Entrench supply security through backward integration into Moroccan and Portuguese locust bean supply chains while accelerating EFSA and FDA regulatory dossier filing for novel protein-based platforms. Precision fermentation startups threaten agricultural-extraction incumbents with 18-month qualification compression. Capacity addition in Yangtze River Delta starch modification facilities defends margin position against Chinese regional competitors. For New Entrants and Emerging Players: Establish a beachhead in Japan's shelf-stable functional beverage segment where aging demographics and convenience-store culture create underpenetrated demand for extended stability windows. Liquid stabilizer delivery formats for automated batching systems represent the most penetrable application tier. Partner directly with Austin and Los Angeles functional beverage startups for rapid qualification cycles rather than pursuing multinational procurement channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision fermentation platforms displacing crop-dependent extraction with 18-month qualification timelines versus 36-month agricultural alternatives. Long-term viability hinges on regulatory dossier depth across FDA GRAS, EFSA novel food, and FSSAI pathways simultaneously. The signal to watch is EFSA petition approval velocity for fermentation-derived hydrocolloids as inflection indicator for platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Locust Bean Supply | Cargill's Moroccan agricultural partnerships secure raw gum cost control against Portuguese harvest volatility. |
| Precision Fermentation Platform Investment | Microbial strain cultivation renders weather-dependent crop extraction obsolete with consistent batch performance. |
| Regulatory Dossier Acceleration | Simultaneous FDA GRAS and EFSA novel food filing compresses 18-24 month safety assessment windows. |
| Liquid Delivery Format Expansion | Pre-hydrated solutions enable automated batching adoption in European continuous processing line upgrades. |
| Technical Partnership Consolidation | Single-source supplier relationships replace transactional procurement in Germany's six-month innovation cycles. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across beverage formulation laboratories, contract manufacturing facilities, and hydrocolloid extraction operations. Primary interviews engaged beverage R&D directors, procurement leads at functional beverage brands, plant managers at starch modification facilities, and regulatory affairs specialists navigating FDA and EFSA petition pathways. Secondary validation drew from FDA 21 CFR filings, EFSA novel food assessment registers, FSSAI ingredient approval databases, and customs trade data tracking Moroccan locust bean gum exports. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Calibration anchored segment-level projections to enzymatic modification capacity expansion in Chinese facilities, fermentation-derived platform commercialization timelines, and clean-label regulatory petition backlogs. Modeled dimensions spanned stabilizer type, end-use application, formulation format, and regional manufacturing cluster. CAGRs derived from volume trajectory analysis weighted by qualification cycle compression and substitution elasticity between natural and synthetic systems. Forecast inputs incorporated EFSA Green Deal implementation pace and Japanese convenience-store beverage turnover rates.
Stress conditions across Moroccan harvest yield variance, EFSA assessment timeline extension, and precision fermentation scale-up success rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions concerning regulatory pathway efficiency and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Fermentation Products Market
Specialty Ingredients
Benzoe Siam Market
Specialty Ingredients
Mangosteen Market
Specialty Ingredients
Normal and Specialty Fats Market
Specialty Ingredients
Customized Nutrient Premixes Market
Specialty Ingredients
Floral Water Market
Specialty Ingredients
Abies Alba (Fir) Leaf Oil Market
Specialty Ingredients
Specialty Food Ingredients Market
Specialty Ingredients
Pomegranate Seed Oil Nutricosmetic Ingredients Market
Specialty Ingredients
Global Fruit and Vegetable Powder Market
Specialty Ingredients
Green Sic Market
Specialty Ingredients
Agarwood Essential Oil Market
Specialty Ingredients
Grape Seed Extract in Pet Food Application Market
Specialty Ingredients
North America Specialty Food Ingredient Market
Specialty Ingredients
Marine Spicules Market
Specialty Ingredients
Tamanu Oil Market