
 Specialty Meat Ingredients Market | 2026-2036
Specialty Meat Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Meat Ingredients Market Analytics
Premium clean-label specification tiers is redrawing competitive boundaries in specialty meat ingredients. Kerry Group plc leverages its taste and nutrition portfolio to anchor positions in European processed meat applications. Cargill sustains broad supply chain control across animal proteins and plant-based alternatives for meat processors. DuPont specializes in enzyme and antimicrobial solutions that extend shelf stability for convenience meat formats.
Specialty meat ingredients comprise functional additives, flavor systems, and preservation compounds formulated to enhance sensory attributes, processing yields, and shelf stability in meat products. These ingredients typically incorporate defined protein concentrations, controlled moisture activity levels, and standardized particle sizes to ensure uniform dispersion during comminution or injection processes. Powder formulations dominate industrial procurement for their storage efficiency and dosing precision in high-volume meat processing operations. Liquid marinades represent the fastest-growing form segment as ready-to-cook and pre-seasoned meat products expand retail penetration. Processed meat applications command the largest share of demand within the application dimension, though convenience foods segments attract margin-focused ingredient suppliers.
EU Green Deal frameworks and REACH chemical registration protocols constrain synthetic additive approvals while accelerating natural extract development across European ingredient portfolios. FDA food additive regulations and USDA FSIS labeling standards govern product claims and safety substantiation for suppliers accessing North American meat processing channels. Stakeholders must monitor evolving regulatory thresholds for nitrite replacement technologies and natural preservation systems.
Market Dynamics
EU Green Deal sustainability mandates and REACH chemical safety protocols are forcing ingredient suppliers to reformulate entire portfolios around natural extracts and bio-based alternatives, eliminating synthetic preservatives that have anchored processed meat formulations for decades.
Growth Catalysts
- Clean-label reformulation mandates:Processed meat manufacturers across Germany, France, and Italy are accelerating procurement of natural curing agents and plant-derived antimicrobials to meet EFSA clean-label substantiation requirements.
- Convenience meat format expansion:Ready-to-cook marinated cuts and pre-seasoned retail packs are driving liquid marinade ingredient volumes as urban consumers reduce home preparation time.
- Enzyme-based yield enhancement:Transglutaminase and protease systems are penetrating sausage and emulsified meat operations seeking improved texture binding and water retention without phosphate additives.
Market Restraints
- Raw material cost volatility:Collagen and animal protein hydrolysate prices fluctuate with European livestock herd cycles and feed grain import dependencies.
- Supply concentration in natural extracts:Rosemary extract and green tea catechin suppliers cluster in Mediterranean agricultural zones, creating single-source vulnerability for antioxidant formulations.
- Technical performance gaps:Natural nitrite replacements from celery powder and fermented vegetable sources deliver inconsistent residual nitrite levels compared to synthetic sodium nitrite.
Strategic Opportunities
- Eastern European processor expansion:Polish and Romanian meat processors are modernizing facilities and importing Western European ingredient specifications to access EU export channels.
- Cell-cultured meat ingredient pre-positioning:Growth media proteins and scaffolding material suppliers can establish technical partnerships with cultivated meat developers before regulatory frameworks solidify.
- CSRD supply chain disclosure requirements:EU Corporate Sustainability Reporting Directive mandates are creating premium tiers for ingredients with verified lifecycle carbon footprints and deforestation-free sourcing.
Industry Challenges
- Clean-label formulation expertise scarcity:Meat scientists capable of balancing natural preservation efficacy with sensory stability command salary premiums that mid-tier processors struggle to absorb.
- Dual certification complexity:Suppliers seeking simultaneous organic certification under EU 2018/848 and halal compliance face conflicting processing aid restrictions and audit timelines.
- Legacy equipment retrofit costs:Powder-to-liquid ingredient system conversions require capital outlays for dosing pumps and CIP-compatible tank infrastructure that smaller abattoirs defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Meat Ingredients Market |
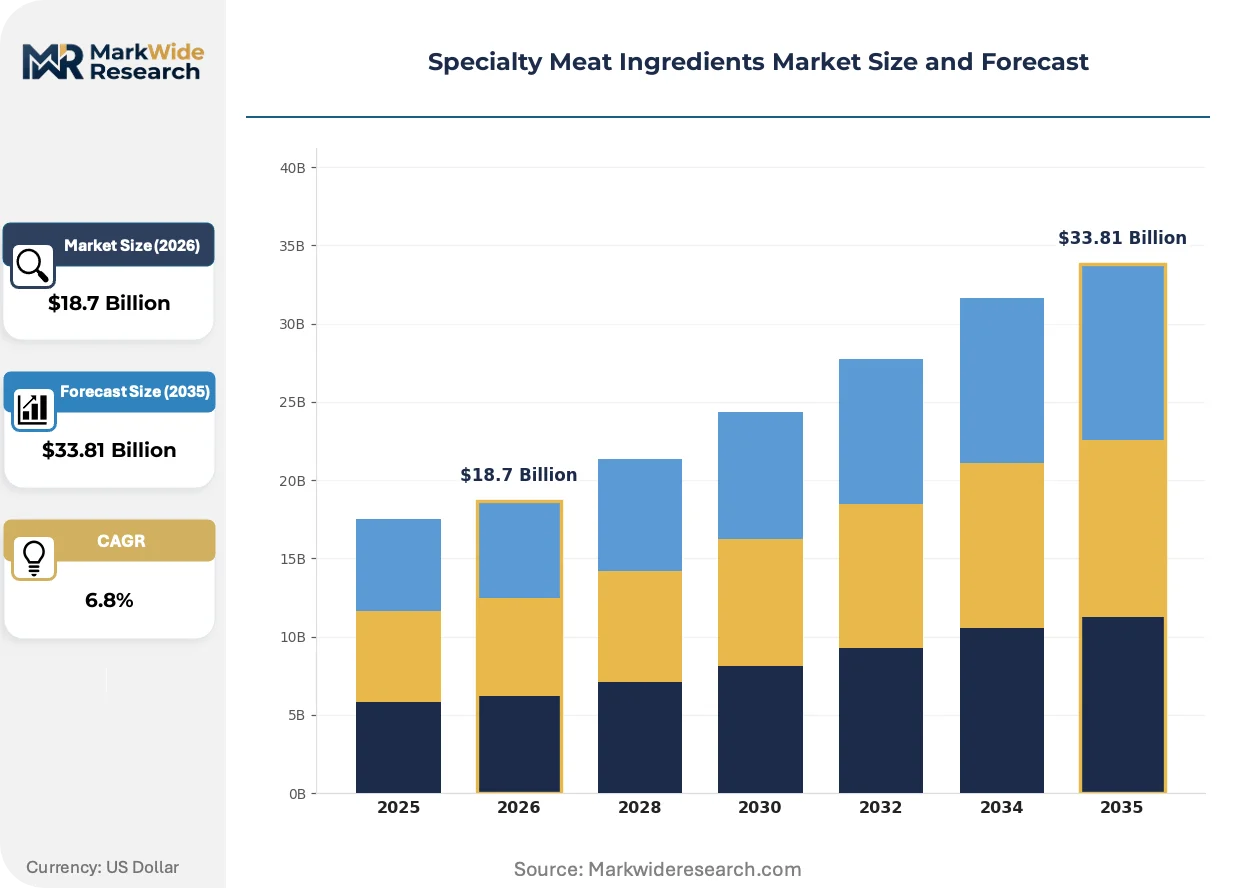
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seasonings, Marinades, Brines, Flavor Enhancers Form: Powder, Liquid, Paste, Granules Application: Processed Meat, Convenience Foods, Ready-to-Cook, Packaged Foods End User: Food Manufacturers, Restaurants, Catering Services, Retailers |
| Companies Covered | Archer Daniels Midland Company, Cargill, Kerry Group plc, Ingredion Incorporated, Tate & Lyle PLC, DuPont, Sensient Technologies Corporation, Givaudan, International Flavors & Fragrances Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Meat Ingredients Market Evolving Landscape
Active ingredient delivery systems and bio-preservation technologies are displacing conventional chemical additives across European meat processing. Formulation science now prioritizes multi-functional ingredients that simultaneously address shelf stability, sensory performance, and clean-label compliance.
Microencapsulation technology for volatile flavor compounds and oxygen-sensitive natural antioxidants is miniaturizing protection barriers to sub-100-micron scales. Premium sausage and cured meat producers in Northern Italy and Bavaria are adopting these systems to prevent flavor degradation during thermal processing. The technology is miniaturizing ingredient particle architectures while extending functional performance windows, compressing the cost gap between natural and synthetic preservation systems.
REACH authorization restrictions on synthetic biocides and EU Green Deal Farm-to-Fork chemical reduction targets are accelerating substitution timelines for traditional curing salts. Ingredient suppliers must submit extended safety dossiers for remaining synthetic additives while scaling fermentation-derived alternatives. Small-to-midsize cured meat operations in Spain and Portugal face the steepest compliance burdens as they lack internal regulatory affairs capacity.
Direct procurement relationships between meat processors and specialty ingredient developers are displacing traditional distributor intermediaries in high-volume accounts. Large German sausage manufacturers now contract directly with enzyme suppliers for customized transglutaminase blends, bypassing regional chemical distributors. This pattern concentrates most visibly in the Ruhr industrial corridor where processor consolidation has created sufficient volume to justify dedicated technical service arrangements.
Specialty Meat Ingredients Market Segmentation
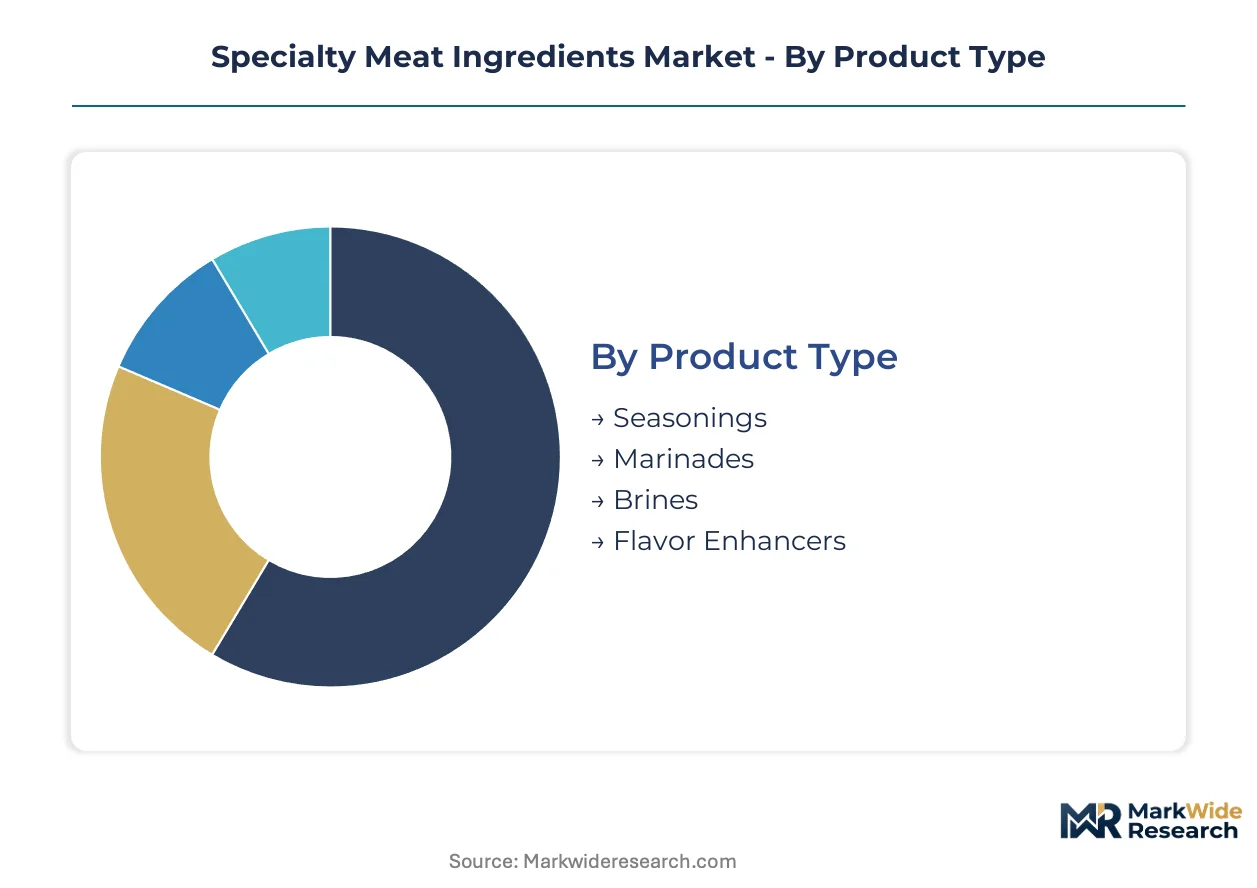
Specialty meat ingredients fragment across functional roles, physical states, and customer workflows. Each dimension carries distinct margin profiles and technical service requirements that reshape supplier resource allocation.
Product Type:
Domestic procurement concentrates in seasoning and brine categories for traditional sausage operations across Germany and Italy. Export-led demand flows toward flavor enhancers serving international processed meat brands with standardized taste profiles.
- Seasonings:Spice and herb blends with defined particle size distributions ensure uniform dispersion in comminuted meat matrices. Bavarian and Northern Italian cured meat houses drive specification intensity here, prioritizing clean-label substantiation under EFSA guidelines.
- Marinades:Acidulated liquid systems incorporating enzymes and flavor precursors penetrate muscle tissue for ready-to-cook applications. Urban retail format expansion across French and Benelux markets accelerates volume procurement of pre-formulated marinade concentrates.
- Brines:Phosphate and salt solutions with controlled ionic strength optimize water-binding in injected whole-muscle cuts.
- Flavor Enhancers:Yeast extracts and hydrolyzed vegetable proteins deliver umami impact without MSG declaration.
Seasonings command the established base. The steepest expansion runs through marinades.
Form:
Cost tier differentiation separates industrial-scale powder procurement from premium liquid dosing systems. High-volume processors optimize for storage density and automated handling, while convenience food specialists absorb liquid form premiums for formulation flexibility.
- Powder:Spray-dried and agglomerated formulations with controlled moisture activity below 0.3 aW enable extended ambient storage. German sausage manufacturers in the Ruhr corridor anchor demand through pneumatic conveying systems integrated into continuous production lines.
- Liquid:Aqueous and oil-based suspensions with viscosity-modified rheology suit injection and tumbling operations. Ready-to-cook marinated retail packs across French hypermarkets are expanding procurement fastest.
- Paste:High-solids concentrated systems minimize water freight for regional meat processors.
- Granules:Intermediate particle architectures balance dissolution speed with dust control in manual handling environments.
Powder retains volume leadership. Liquids are climbing the fastest as convenience formats proliferate.
Application:
Customer type stratification separates commodity-driven processed meat procurement from margin-focused convenience food development. Application selection dictates regulatory burden intensity, with cured meat categories facing concentrated EFSA additive scrutiny.
- Processed Meat:Emulsified and whole-muscle products incorporating curing salts, binders, and preservatives under EU 1169/2011 labeling mandates. German sausage traditions sustain the deepest ingredient specification catalogs here.
- Convenience Foods:Pre-cooked and shelf-stable meat formats requiring extended microbiological stability without refrigeration. Mediterranean export-oriented processors are expanding procurement of natural preservation systems fastest.
- Ready-to-Cook:Marinated fresh cuts with reduced home preparation requirements for urban consumers.
- Packaged Foods:Retail-portioned products with defined shelf-life claims and traceability documentation.
Processed meat anchors revenue concentration. Convenience foods are gaining share fastest through clean-label reformulation premiums.
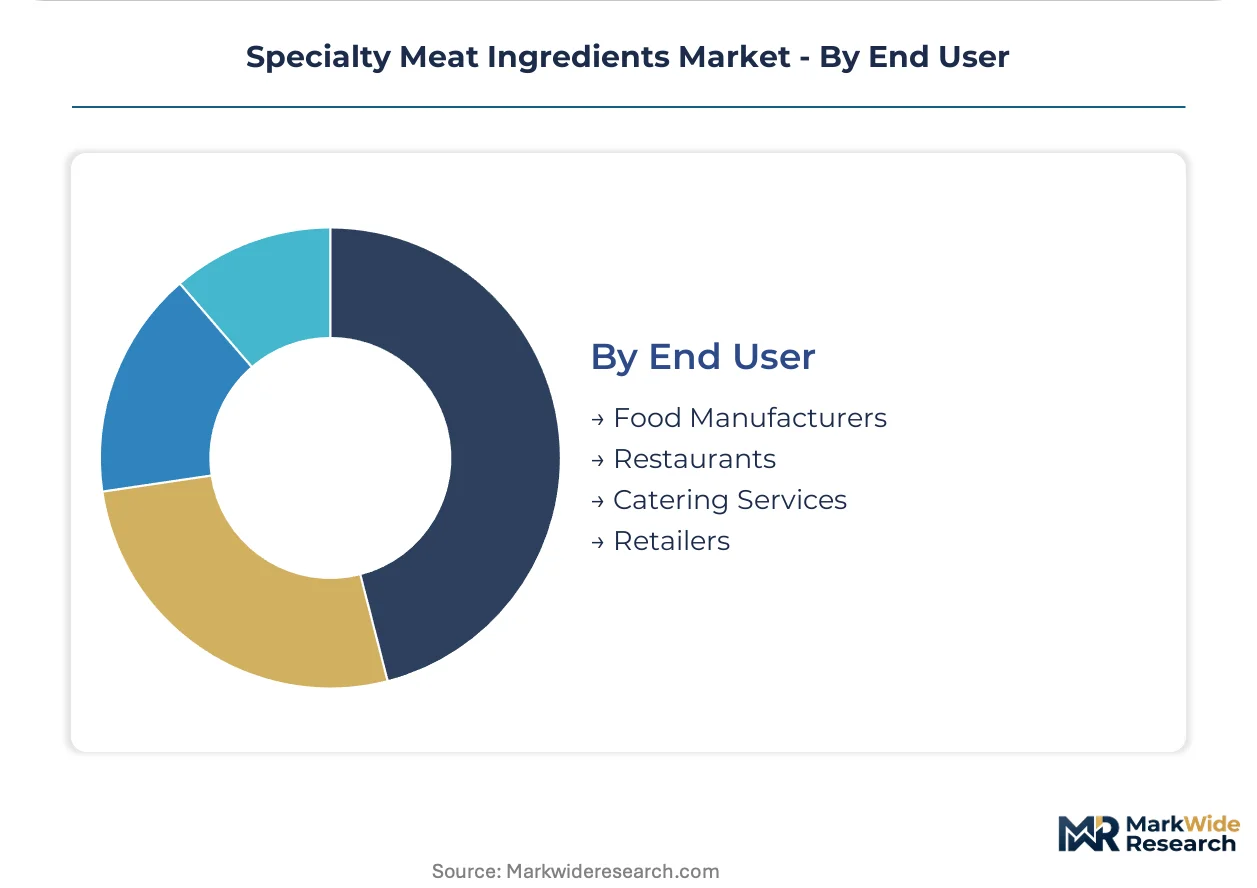
End User:
Supply concentration clusters around food manufacturers with technical service dependencies, while service sector users prioritize cost minimization and delivery reliability over formulation partnership.
- Food Manufacturers:Integrated meat processing operations with in-house R&D capability and direct supplier technical collaboration. Large German and Polish processors are consolidating procurement through direct enzyme and natural extract contracts.
- Restaurants:Foodservice operators sourcing pre-formulated marinade and seasoning systems for menu consistency.
- Catering Services:Institutional volume buyers with price-sensitive procurement and limited formulation customization.
- Retailers:Private-label developers specifying ingredient systems for contract manufacturer execution.
Food manufacturers command the established base. Retailers are expanding procurement fastest through private-label convenience meat development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ingredient supply concentrates most heavily in Germany, where sausage and cured meat traditions sustain specialized procurement networks. REACH chemical registration protocols and EU Green Deal mandates are reshaping sourcing requirements across European manufacturing corridors.
Germany
Sausage manufacturers in the Ruhr industrial corridor drive bulk enzyme and natural extract procurement for emulsified meat operations. EFSA clean-label substantiation requirements are accelerating reformulation away from synthetic curing salts toward fermented vegetable alternatives. Bavarian cured meat houses in Munich and Nuremberg are adopting microencapsulated flavor systems to prevent thermal degradation during processing.
France
Urban retail format expansion across Paris and Lyon hypermarkets is lifting liquid marinade volumes for ready-to-cook meat packs. EU 1169/2011 labeling mandates are constraining additive declarations and pushing processors toward multi-functional natural ingredients. Charcuterie specialists in the Rhône-Alpes region are contracting directly with rosemary extract suppliers for antioxidant formulations.
Italy
Northern Italian cured meat producers in Parma and Modena are specifying premium clean-label tiers for protected designation of origin products. REACH authorization restrictions on synthetic biocides are forcing substitution timelines for traditional curing salts in artisanal operations. Emilia-Romagna processing clusters are integrating transglutaminase systems to improve texture binding without phosphate additives.
Poland
Meat processors in Warsaw and Kraków are modernizing facilities to import Western European ingredient specifications for EU export access. CSRD supply chain disclosure mandates are creating procurement premiums for verified lifecycle carbon footprints. Polish sausage manufacturers are scaling natural preservation systems to meet German retail buyer requirements.
Spain
Mediterranean export-oriented processors in Barcelona and Valencia are expanding natural preservation procurement fastest among convenience food segments. EU Green Deal Farm-to-Fork chemical reduction targets are compressing compliance timelines for small-to-midsize cured meat operations. Andalusian ham producers are testing fermented vegetable nitrite replacements to maintain residual stability in long-cure products.
Specialty Meat Ingredients Market Competitive Landscape
Concentration sits with diversified nutrition and taste solution providers that span multiple protein categories beyond meat. The supplier base organizes into three functional tiers: broad-line ingredient conglomerates with supply chain control across animal and plant proteins; specialized enzyme and antimicrobial developers focused on shelf stability extension; and flavor systems houses delivering sensory performance for processed meat matrices. Competitive positioning hardens through direct technical service contracts with large processors and portfolio diversification into cell-cultured meat ingredient pre-positioning.
Among broad-line nutrition suppliers, Kerry Group plc and Cargill occupy positions that span taste, texture, and preservation functions for European processed meat applications. DuPont exemplifies the specialized tier through its concentration on enzyme-based yield enhancement and antimicrobial solutions. These three anchors represent distinct strategic postures: Kerry Group plc leverages integrated taste and nutrition portfolios; Cargill sustains upstream control across protein sourcing; DuPont targets technical performance gaps in natural preservation efficacy.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill |
| Kerry Group plc |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| DuPont |
| Sensient Technologies Corporation |
| Givaudan |
| International Flavors & Fragrances Inc. |
| Others |
Value Network & Pricing Analysis
Fermented vegetable nitrite replacements displacing synthetic sodium nitrite are redrawing procurement geography toward Mediterranean agricultural zones while compressing cost premiums between natural and conventional preservation systems. This substitution dynamic simultaneously elevates rosemary extract and celery powder sourcing from Spain and Italy and intensifies price competition among processors lacking backward integration into extract production.
Pricing Analysis
EU Green Deal chemical reduction mandates and REACH authorization protocols dictate the pricing tier structure across specialty meat ingredient procurement. Three-tier pricing structure across premium clean-label, standard reformulation, and economy synthetic tiers separates EFSA-substantiated natural extracts from transitional blends and legacy chemical additives. Cost compression in the standard tier is intensifying as mid-size Polish and Romanian processors import Western European specifications without scale economies. Food manufacturers with direct technical service contracts exhibit the lowest price sensitivity, while catering services and institutional buyers drive procurement toward economy tiers.
Supply Chain Analysis
Spain and Italy anchor Mediterranean antioxidant extract production, while Germany concentrates enzyme and functional protein manufacturing for emulsified meat operations. Raw material flows draw from rosemary and green tea agricultural zones in Andalusia and Sicily, collagen hydrolysate processing in Bavaria, and fermentation-derived cultures in the Netherlands. Single-source vulnerability clusters in Mediterranean botanical supply, creating exposure to climate-driven harvest volatility and EU Farm-to-Fork pesticide residue thresholds. Distribution runs through direct procurement relationships with large German sausage manufacturers, displacing traditional chemical distributor intermediaries in high-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label reformulation mandates are fragmenting procurement across processor tiers, creating specialist niches for natural extract developers and enzyme suppliers capable of bridging technical performance gaps with synthetic legacy systems.
For Market Incumbents: Shield formulation expertise advantages by embedding meat scientists into direct technical service contracts with large Ruhr corridor processors, insulating against emerging biotechnology entrants offering precision fermentation alternatives. Deepen backward integration into rosemary extract and transglutaminase production to capture margin compression from REACH-driven synthetic additive phase-outs. For New Entrants and Emerging Players: Differentiate on CSRD-compliant lifecycle carbon footprint verification, targeting Polish and Romanian processors modernizing for German retail buyer access with limited internal sustainability documentation capacity. White-space concentration sits in cultivated meat growth media proteins and scaffolding materials before regulatory frameworks solidify, with technical partnership pre-positioning as the preferred go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed natural extract specialists in Spain and Portugal lacking the regulatory affairs capacity to navigate EFSA clean-label substantiation independently. Long-term viability over a five-to-ten year window hinges on portfolio diversification beyond meat into cell-cultured protein ingredient systems. The signal to watch is EU authorization timelines for fermented vegetable nitrite replacements achieving residual stability parity with synthetic alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Technical Service Contracting | Bypasses distributor intermediaries for large German sausage manufacturers seeking customized enzyme blends. |
| Backward Integration into Extract Production | Captures rosemary and green tea catechin margins in Mediterranean agricultural zones. |
| CSRD Supply Chain Disclosure Certification | Creates premium procurement tiers for verified lifecycle carbon footprints under EU Corporate Sustainability Reporting Directive. |
| Cell-Cultured Meat Ingredient Pre-Positioning | Establishes technical partnerships with cultivated meat developers before regulatory frameworks solidify. |
| Microencapsulation Technology Adoption | Prevents flavor degradation in Bavarian and Northern Italian cured meat thermal processing operations. |
Research Methodology
A spread of perspectives from meat processing R&D directors, procurement leads at German sausage manufacturers, EFSA regulatory affairs specialists, and Mediterranean botanical extract suppliers converged on the working assumptions. Primary interviews with these stakeholders were cross-referenced against customs and trade data, EU 1169/2011 labeling compliance filings, and industry association reports from Cefic and FoodDrinkEurope. Bottom-up volume modeling across ingredient categories was triangulated with top-down market sizing from processor capacity and production line data.
Segmentation dimensions modeled include functional role, physical state, application category, and end-user workflow type across the projection horizon. CAGRs were derived from processor procurement volume trajectories and reformulation timelines driven by regulatory substitution mandates. Forecast inputs incorporated REACH authorization sunset dates for synthetic biocides and EU Green Deal Farm-to-Fork chemical reduction targets.
Material uncertainties — livestock herd cycle volatility, climate-driven botanical extract harvest variability, and EFSA clean-label substantiation timeline delays — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and processor capital availability for legacy equipment retrofit. Recalibration cycles align with material shifts in EU authorization protocols and Green Deal implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Evening Primrose Oil Market
Specialty Ingredients
Specialty Shortenings Market
Specialty Ingredients
Food Decorations and Inclusions Market
Specialty Ingredients
Tamanu Oil Market
Specialty Ingredients
Global Pet Food Flavors Market
Specialty Ingredients
North America Specialty Food Ingredient Market
Specialty Ingredients
Madecassoside Market
Specialty Ingredients
Middle East and Africa Customized Premixes Market
Specialty Ingredients
Benzoe Siam Market
Specialty Ingredients
Sun-Care Natural Oils Market
Specialty Ingredients
Flavanols Market
Specialty Ingredients
Specialty Carbohydrates Market
Specialty Ingredients
Mangosteen Extract Market
Specialty Ingredients
Specialty Food Ingredients Market
Specialty Ingredients
Grape Seed Extract in Pet Food Application Market
Specialty Ingredients
Marine Spicules Market