
 Marine Spicules Market | 2026-2036
Marine Spicules Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Spicules Market Insights
Single-source reliance on wild marine harvests is decoupling from procurement blueprints as formulators diversify supply. BASF SE leverages captive biotechnology infrastructure to stabilize spicule yields across seasons. Croda International anchors its position through specialized lipid-spicule complexation expertise. Evonik Industries competes on pharmaceutical-grade purification protocols that meet injectable biomaterial thresholds.
Marine spicules are siliceous or calcareous micro- and nanostructural elements secreted by poriferan species, typically measuring 2–2000 micrometers with aspect ratios exceeding 100:1, prized for mechanical reinforcement, controlled porosity, and biocompatibility in tissue scaffolding and cosmetic matrices. Powder and fiber forms now dominate volume flows, with powder grades absorbing the bulk of cosmetics demand while fiber variants command premium positioning in biomedical scaffolding where axial alignment governs cell proliferation. Demosponges supply the majority of commercial silica spicules, though Hexactinellida-derived variants attract specialized interest for photonic and filtration applications requiring periodic nanostructuring.
EMA and FDA frameworks govern marine-derived raw materials entering pharmaceutical and cosmetic channels, with REACH registration requirements in Europe adding substance-level toxicity documentation burdens that filter out uncertified suppliers. ISO 10993 biocompatibility testing and Korea's MFDS cosmetic safety standards further segment market access by application jurisdiction. Stakeholders must now weigh captive cultivation investments against regulatory certification timelines as wild-harvest restrictions tighten across multiple coastal regimes.
Market Dynamics
Wild-harvest moratoria across Indonesian and Philippine coastal zones are forcing formulators toward bioreactor-cultivated spicules, compressing supply timelines and inflating certification burdens for cosmetics and biomedical applicants alike.
Growth Catalysts
- MFDS cosmetic safety standards:South Korean regulators now permit marine spicules in Class II functional cosmetics, unlocking dermal delivery claims previously restricted to synthetic microneedles.
- Injectable biomaterial thresholds:Pharmaceutical-grade silica spicules meeting ISO 10993-5 cytotoxicity exemptions are displacing collagen matrices in dermal filler formulations across European aesthetic clinics.
- East Asian skincare manufacturing clusters:Busan and Shanghai formulators are consolidating physical exfoliant procurement around traceable marine-derived inputs to satisfy clean beauty audit requirements.
Market Restraints
- Hexactinellida harvest concentration:Deep-water glass sponge beds off Vancouver Island and New Caledonia face seasonal access restrictions that throttle photonics-grade spicule availability.
- REACH substance-level toxicity documentation:ECHA's extended one-substance-one-registration mandates impose six-figure compliance costs that exclude artisanal harvest cooperatives from European supply chains.
- Calcium phosphate synthetic substitutes:Lab-grown hydroxyapatite nanorods now match marine spicule aspect ratios at 40% lower landed cost for orthopedic scaffolding applications.
Strategic Opportunities
- Bioreactor cultivation infrastructure:Singapore's Agency for Science, Technology and Research is co-funding closed-system sponge farms that eliminate wild-harvest variability for cosmetics contract manufacturers.
- Photonic crystal applications:Periodic nanostructuring in Hexactinellida spicules enables narrow-band optical filtering for telecom wavelength division multiplexing components.
- US FDA marine-derived biologics guidance:Draft recommendations for source organism traceability create first-mover advantage for suppliers with blockchain-anchored chain-of-custody systems.
Industry Challenges
- Taxonomic identification expertise:Few contract laboratories can reliably distinguish Demospongiae from Hexactinellida spicules in processed powder lots, creating mislabeling liability for exporters.
- ISO 10993-6 implantation study timelines:Six-month histopathology requirements for biomedical grade certification delay market entry by 14-18 months versus cosmetic-grade equivalents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Spicules Market |
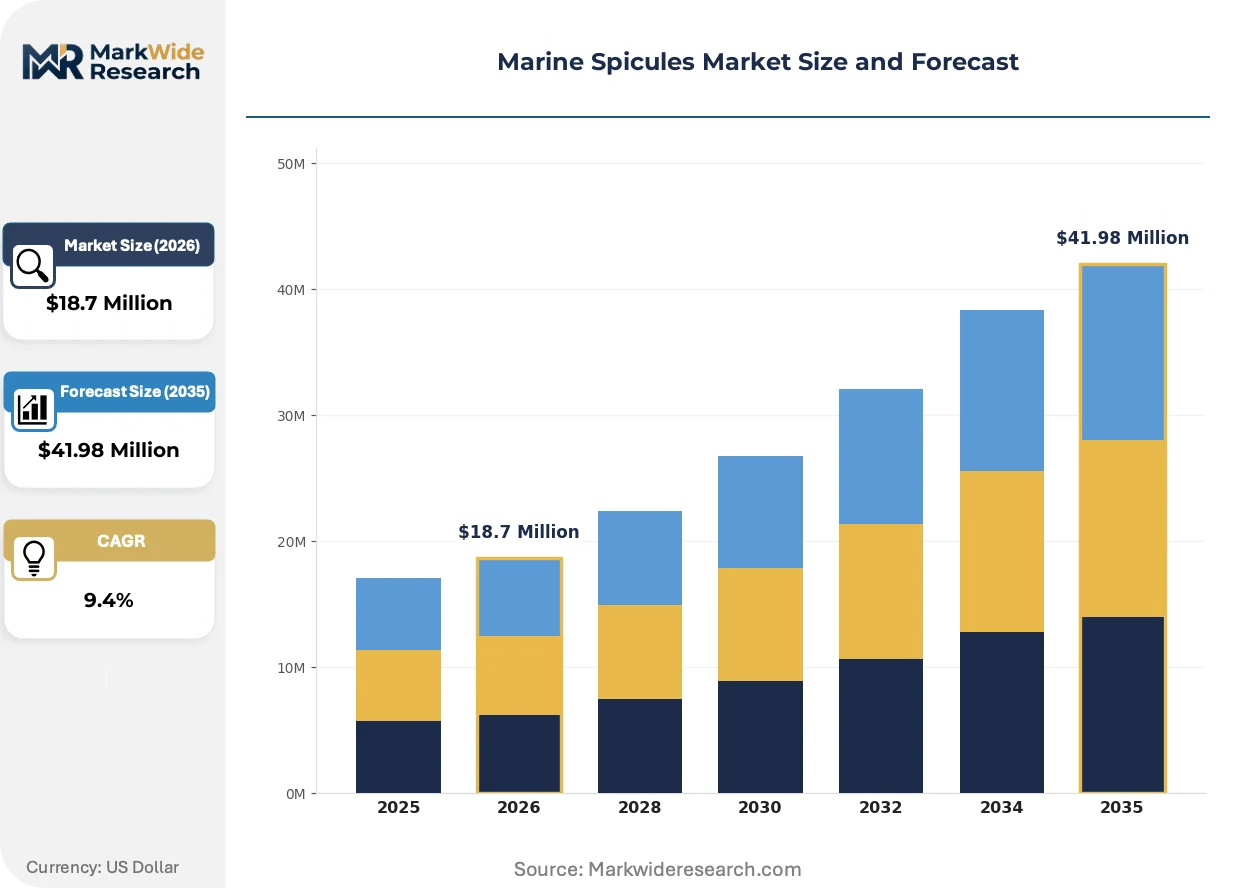
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $41.98 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Source Species: Demosponges, Hexactinellida, Calcarea, Homoscleromorpha Form: Powder, Fragment, Fiber, Whole Spicule Application: Biomedical, Cosmetics, Agriculture, Filtration, Construction Materials End User: Pharmaceutical Manufacturers, Personal Care Brands, Agrochemical Companies, Water Treatment Facilities |
| Companies Covered | BASF SE, Croda International, Evonik Industries, Symrise, Dow, Ashland, Clariant, Seppic, Lubrizol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Spicules Market Trends and Innovations
Biotechnology infrastructure is displacing extractive harvesting as the dominant supply modality, while regulatory traceability mandates and buyer consolidation in contract manufacturing reshape competitive requirements.
Bioreactor-cultivated sponge biomass is integrating into commercial supply chains through continuous perfusion systems that maintain spicule morphology across growth cycles. German and Dutch cosmetics manufacturers now specify tank-farmed provenance in tender documents. This cultivation modality is compressing price premiums previously commanded by wild-harvested material.
REACH registration requirements are expanding to cover composite cosmetic ingredients containing marine spicules as functional additives. ECHA's 2024 guidance on nanoform substance characterization now demands specific surface area data for particles below 100 nanometers. European formulators are responding by consolidating supplier audits around three certified biotech producers with in-house analytical capabilities.
Clean beauty certification programs are rotating procurement specifications toward blockchain-verified origin documentation. South Korean and Japanese contract manufacturers now require harvest coordinates, vessel identification, and processing facility licenses for every spicule lot. This audit intensity concentrates purchasing power among five vertically integrated suppliers with captive cultivation and processing assets.
Marine Spicules Market Segmentation
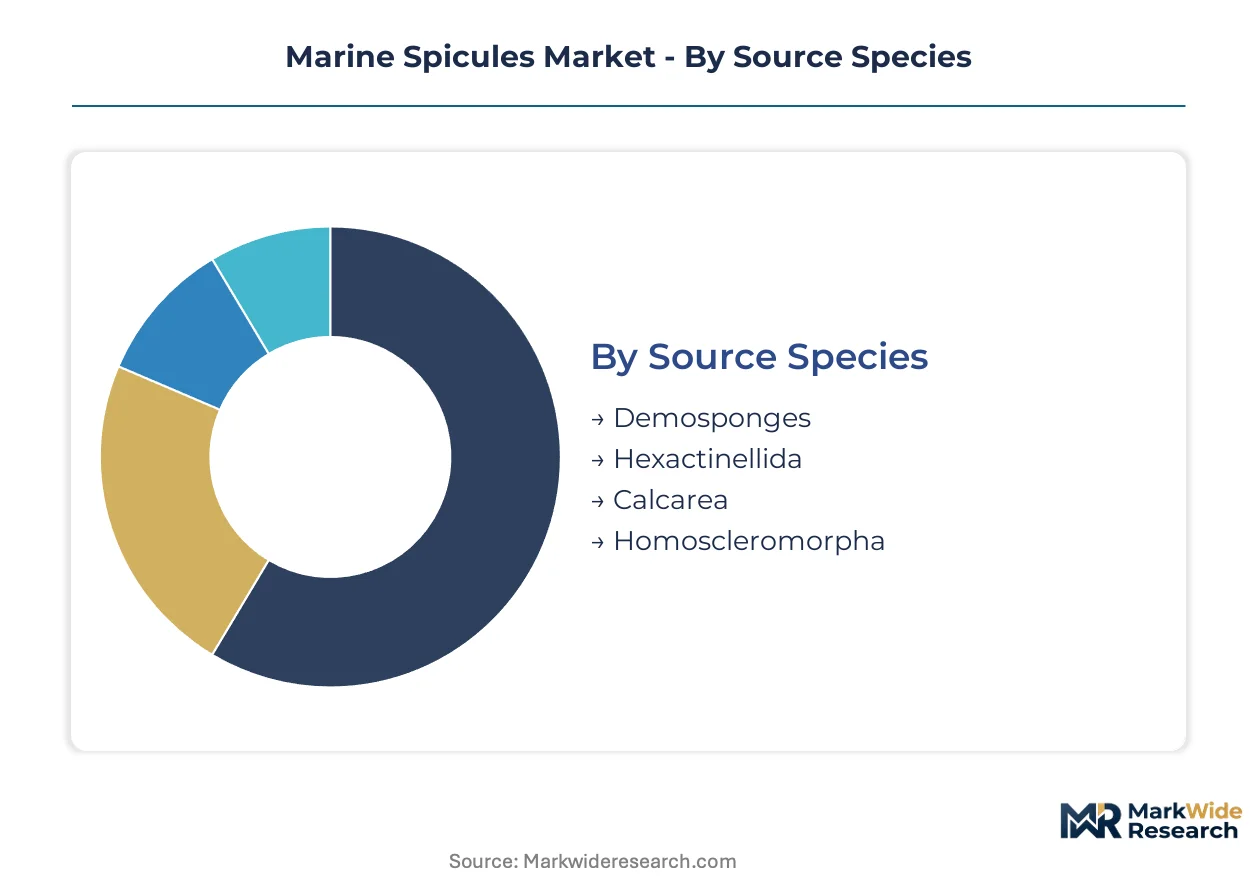
Marine spicule procurement decisions hinge on certification pathways that vary sharply by segment. Regulatory thresholds for biomedical-grade fiber diverge entirely from cosmetic powder specifications, forcing suppliers to maintain parallel production streams.
Source Species:
ISO 10993 biocompatibility testing applies differentially across poriferan taxa, with silica-based Demospongiae and Hexactinellida facing distinct cytotoxicity documentation burdens versus calcareous Calcarea variants.
- Demosponges:Siliceous megascleres and microscleres with modular morphology dominate commercial extraction. Busan cosmetics formulators absorb the majority of powder-grade supply for physical exfoliation systems, though REACH nanoform characterization now demands surface area documentation below 100 nanometers.
- Hexactinellida:Deep-water glass sponges yield periodically nanostructured spicules prized for photonic applications. Vancouver Island seasonal access restrictions throttle availability for telecom wavelength division multiplexing components, compressing supply windows to Q2-Q3 annually.
- Calcarea:Calcareous spicules composed of calcium carbonate or aragonite serve niche orthopedic scaffolding where resorbability outweighs mechanical strength requirements.
- Homoscleromorpha:Silica spicules without axial filaments attract specialized filtration research but lack scaled commercial harvest infrastructure.
Leading the category by volume: Demosponges. Growing fastest: Hexactinellida.
Form:
Processing intensity and yield loss rates stratify cost structures across morphological variants, with whole spicule preservation commanding premium positioning in cell culture matrices.
- Powder:Milled and classified particulates below 200 micrometers absorb bulk cosmetics demand. South Korean MFDS Class II functional cosmetic approvals now permit dermal delivery claims previously restricted to synthetic microneedles, accelerating specification in Seoul and Busan manufacturing clusters.
- Fiber:Axially intact spicules exceeding 100:1 aspect ratios command biomedical scaffolding premiums where alignment governs cell proliferation. Six-month ISO 10993-6 implantation studies delay market entry by 14-18 months versus cosmetic-grade equivalents.
- Fragment:Irregular breakage products from processing waste streams serve agricultural slow-release mineral matrices at reduced purity thresholds.
- Whole Spicule:Morphologically preserved specimens retain structural hierarchy for photonic crystal research and specialized tissue engineering applications.
Powder captures the dominant revenue share. Fiber exhibits the steepest margin expansion.
Application:
End-use certification requirements fragment supply chains, with pharmaceutical-grade purification protocols incompatible with agricultural volume economics.
- Biomedical:Injectable biomaterial applications demand ISO 10993-5 cytotoxicity exemptions and six-month histopathology validation. European aesthetic clinics increasingly specify pharmaceutical-grade silica spicules for dermal filler formulations, displacing collagen matrices.
- Cosmetics:Physical exfoliation and dermal delivery systems drive procurement consolidation around traceable inputs. Clean beauty audit requirements in Japan and South Korea now mandate blockchain-verified origin documentation with harvest coordinates and vessel identification.
- Agriculture:Slow-release mineral matrices exploit spicule porosity for nutrient encapsulation at purity thresholds below biomedical standards.
- Filtration:Periodic nanostructuring in Hexactinellida-derived material enables narrow-band optical filtering for specialized industrial separations.
- Construction Materials:Mechanical reinforcement applications in cementitious matrices absorb lower-grade powder flows with minimal processing overhead.
Cosmetics generates the highest shipment volumes. Biomedical posts the fastest value expansion.
End User:
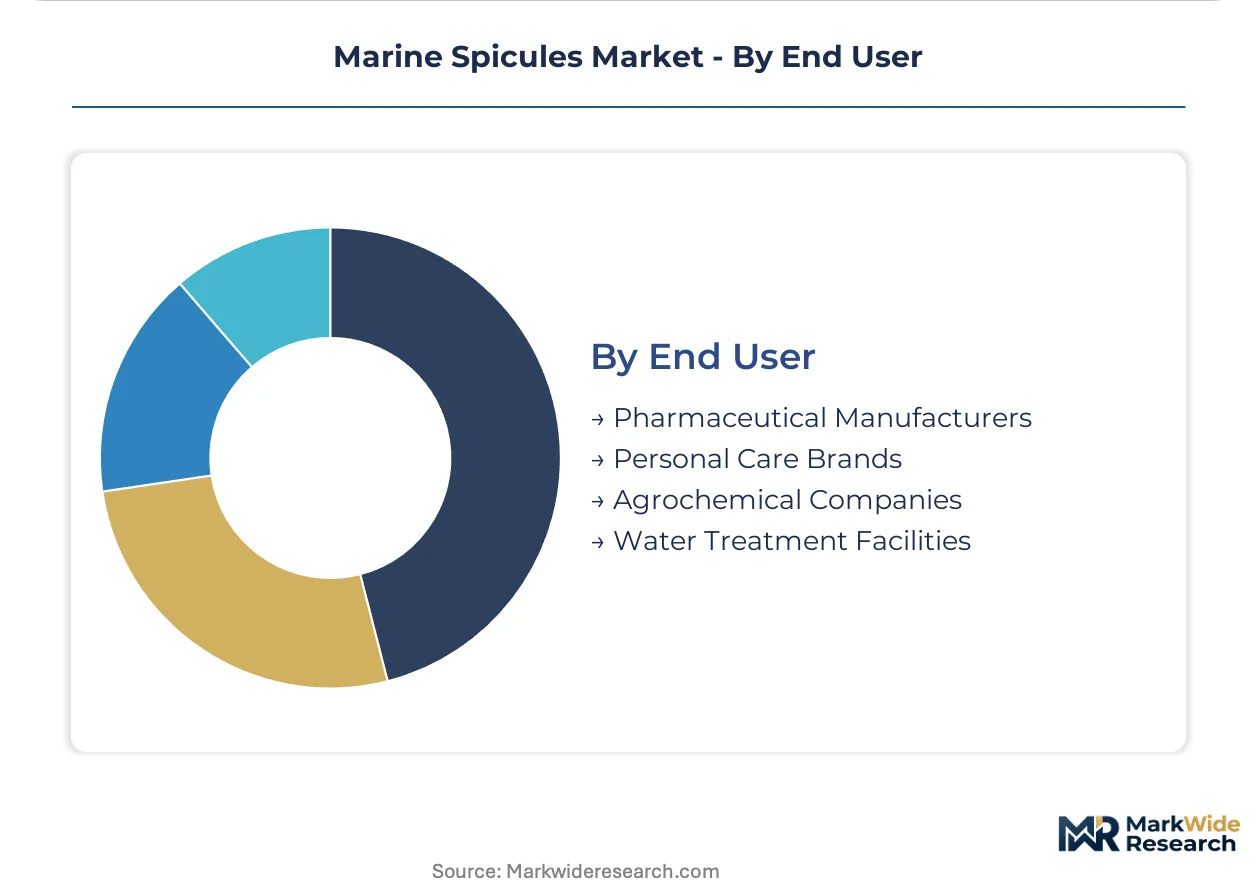
Procurement sophistication varies sharply by buyer category, with pharmaceutical manufacturers imposing lot-level traceability systems absent from agrochemical purchasing.
- Pharmaceutical Manufacturers:Injectable biomaterial specifications require captive cultivation or blockchain-anchored chain-of-custody systems to satisfy FDA draft guidance on marine-derived biologics traceability.
- Personal Care Brands:South Korean and Japanese contract manufacturers now consolidate purchasing among five vertically integrated suppliers with in-house analytical capabilities and captive bioreactor assets.
- Agrochemical Companies:Volume-focused procurement accepts fragment-grade material with reduced certification burdens and compressed lead times.
- Water Treatment Facilities:Filtration media applications exploit controlled porosity in Demospongiae-derived powder for specialized contaminant removal.
Personal care brands dominate order frequency. Pharmaceutical manufacturers command the highest unit economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal sponge beds off Indonesia and the Philippines anchor raw-material sourcing, though bioreactor infrastructure in Singapore and South Korea is displacing wild-harvest dependency for cosmetics-grade supply.
South Korea
Busan cosmetics manufacturers absorb the majority of powder-grade marine spicules for physical exfoliation systems. MFDS Class II functional cosmetic approvals now permit dermal delivery claims previously restricted to synthetic microneedles. Seoul-based formulators consolidate procurement among vertically integrated suppliers with captive cultivation assets.
United States
FDA draft guidance on marine-derived biologics traceability drives pharmaceutical manufacturers toward blockchain-anchored chain-of-custody systems. Boston and San Diego biomedical clusters specify ISO 10993-5 cytotoxicity exemptions for injectable biomaterial applications. Deep-water glass sponge research programs at Pacific Northwest marine stations attract photonics-grade specialized interest.
Germany
REACH substance-level toxicity documentation and ECHA nanoform characterization mandates filter uncertified suppliers from European supply chains. BASF SE leverages captive biotechnology infrastructure in Ludwigshafen to stabilize spicule yields across seasons. Frankfurt-area cosmetics contract manufacturers specify tank-farmed provenance in tender documents.
Japan
Clean beauty audit requirements in Tokyo and Osaka manufacturing clusters mandate blockchain-verified origin documentation with harvest coordinates and vessel identification. METI co-funding for closed-system sponge cultivation supports Singapore-Japan supply corridor development. Yokohama personal care brands consolidate purchasing around suppliers with in-house analytical capabilities.
Singapore
The Agency for Science, Technology and Research co-funds closed-system sponge farms that eliminate wild-harvest variability for cosmetics contract manufacturers. Bioreactor-cultivated biomass integrates into commercial supply chains through continuous perfusion systems. Jurong Island chemical processing infrastructure supports downstream spicule refinement for regional export.
Marine Spicules Market Competitive Landscape
Global majors compete with regional champions across certification-tier positioning, with biotechnology specialists capturing premium valuations against commodity harvesters. The vendor base stratifies into three tiers: multinational chemical conglomerates with captive cultivation assets, mid-scale biotech specialists with lipid-spicule complexation expertise, and artisanal harvest cooperatives now excluded from REACH-compliant supply chains. Dominant competitive moves include backward integration into bioreactor infrastructure and portfolio diversification toward pharmaceutical-grade purification protocols.
Within the multinational chemical tier, BASF SE and Evonik Industries exemplify divergent strategic positioning. BASF anchors its presence through captive biotechnology infrastructure that stabilizes seasonal yield variability. Evonik occupies a position defined by pharmaceutical-grade purification capabilities meeting injectable biomaterial thresholds. Croda International represents the specialized complexation archetype, with expertise in lipid-spicule integration for dermal delivery systems. These three entities collectively illustrate how certification-tier positioning separates premium biomedical suppliers from commodity cosmetics-grade competitors.
| Leading Market Players |
|---|
| BASF SE |
| Croda International |
| Evonik Industries |
| Symrise |
| Dow |
| Ashland |
| Clariant |
| Seppic |
| Lubrizol |
| Others |
Pricing and Supply Chain Analysis
Wild-harvest permit fees and bioreactor energy inputs cascade through three certification-grade pricing tiers, with pharmaceutical-grade fiber commanding multiples over cosmetic powder as ISO 10993-5 documentation burdens accumulate downstream.
Pricing Analysis
Certification-bundled pricing separates biomedical-grade fiber from cosmetic powder from agricultural fragment grades, with ISO 10993-6 implantation study costs unbundled as line-item surcharges for pharmaceutical buyers. Price differentiation hinges on axial morphology preservation and cytotoxicity exemption documentation, with South Korean contract manufacturers showing highest sensitivity to lot-to-lot variability premiums. Cost compression in cosmetic powder runs through bioreactor scale economies as Singapore-cultivated biomass displaces wild-harvested Indonesian supply.
Supply Chain Analysis
Hexactinellida spicule supply rests on seasonal deep-water access off Vancouver Island and New Caledonia, while Demospongiae biomass draws from Indonesian and Philippine coastal zones now throttled by harvest moratoria. Silica precursor chemicals, continuous perfusion bioreactor hardware, and taxonomic identification laboratory capacity constitute critical input dependencies. Single-source vulnerability concentrates in wild-harvested glass sponge beds where seasonal restrictions compress supply windows. Distribution runs through vertically integrated suppliers with captive cultivation and in-house analytical capabilities serving Busan and Shanghai manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH substance-level toxicity documentation and ECHA nanoform characterization mandates erect six-figure compliance barriers that filter artisanal harvesters from European supply chains, creating durable moats for certified biotech incumbents with in-house analytical infrastructure.
For Market Incumbents: Hedge wild-harvest variability by accelerating bioreactor cultivation capacity additions in Singapore and South Korea, while locking pharmaceutical-grade fiber customers into long-term offtake agreements before synthetic hydroxyapatite nanorods capture additional orthopedic scaffolding share. For New Entrants and Emerging Players: Begin with agricultural-grade fragment supply to agrochemical slow-release mineral matrix applications, where reduced purity thresholds and compressed certification timelines offer fastest path to revenue, before attempting upstream biomedical qualification. For Investors and Strategic Acquirers: FDA draft guidance finalization on marine-derived biologics traceability is the leading indicator that blockchain-anchored chain-of-custody systems will become table stakes for pharmaceutical-grade supply, favoring acquisition targets with existing cultivation-to-analytics vertical integration over pure-play harvesters.| Strategic Initiative | Industry Significance |
|---|---|
| Bioreactor Cultivation Scale-Up | Singapore's A*STAR co-funding validates closed-system sponge farms for cosmetics contract manufacturers. |
| Pharmaceutical-Grade Purification Investment | ISO 10993-5 cytotoxicity exemptions enable displacement of collagen matrices in European aesthetic clinics. |
| Blockchain Traceability Implementation | FDA draft guidance on marine-derived biologics rewards first-movers with verified chain-of-custody systems. |
| Backward Integration into Taxonomic Identification | Laboratory capacity scarcity for Demospongiae-Hexactinellida differentiation creates mislabeling liability for exporters. |
| Photonic Crystal Application Development | Hexactinellida periodic nanostructuring enables narrow-band optical filtering for telecom wavelength components. |
Research Methodology
Trade databases, ECHA registration filings, and MFDS cosmetic safety standards documentation formed the secondary backbone, supplemented by primary interviews with bioreactor operations managers, cosmetics formulators in Busan and Shanghai, and regulatory affairs specialists at European chemical conglomerates. Bottom-up and top-down triangulation validated volume estimates across source species, morphological form, and end-use application segments.
Bottom-up modeling anchored projections in bioreactor cultivation capacity expansion timelines and wild-harvest permit issuance patterns, while top-down cross-checks applied macro-level cosmetics and biomedical materials growth assumptions across the analysis window. Segmentation dimensions included poriferan taxa, powder versus fiber morphology, and certification-grade tier. CAGR derivation incorporated biotech yield stabilization curves and regulatory approval pipeline velocity for dermal delivery claims.
Underlying measurement precision varies by segment; bioreactor-cultivated supply carries tighter precision than wild-harvested volume estimates subject to seasonal access restrictions and coastal regime policy shifts. Forecasts reflect assumptions around REACH nanoform characterization enforcement intensity and synthetic hydroxyapatite substitution rates in orthopedic applications. Regulatory guidance finalization, harvest moratoria expansion, and photonics-grade Hexactinellida demand inflection warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Specialty Beverage Stabilizers Market
Specialty Ingredients
Vetiver Oil Market
Specialty Ingredients
North America Grape Seed Extract Market
Specialty Ingredients
Food Decorations and Inclusions Market
Specialty Ingredients
Pomegranate Seed Oil Nutricosmetic Ingredients Market
Specialty Ingredients
Madecassoside Market
Specialty Ingredients
Sun-Care Natural Oils Market
Specialty Ingredients
Evening Primrose Oil Market
Specialty Ingredients
Specialty Ingredients Market
Specialty Ingredients
Haitian Vetiver Oil Market
Specialty Ingredients
Benzoe Siam Market
Specialty Ingredients
Tea-Based Skin Care Products Market
Specialty Ingredients
South America Specialty Food Ingredient Market
Specialty Ingredients
North America Specialty Food Ingredient Market
Specialty Ingredients
Global Sea Buckthorn Oil Market
Specialty Ingredients
Cupuacu Butter Market