
 Beta Carotene Market | 2026-2036
Beta Carotene Market Size, Share, and Industry Trends Forecast 2026-2036
Beta Carotene Market Intelligence
ISO 22000 certification is reorganizing supplier eligibility across the beta carotene value chain, pushing smaller extractors toward third-party audit investments. DSM-Firmenich leverages backward integration into fermentation-derived carotenoids to sustain European pharmaceutical-grade supply. Cyanotech Corporation anchors its position through Hawaiian microalgae cultivation, while Zhejiang Medicine Co., Ltd. competes on synthetic and natural intermediate scale out of East China.
Beta carotene, a lipid-soluble C40 carotenoid with two retinyl groups, typically delivers provitamin A activity at conversion rates near 12:1 by weight and is manufactured through either fungal fermentation of Blakeslea trispora or extraction from Dunaliella salina algae. The natural product type segment commands premium positioning in dietary supplements and clean-label food applications where EFSA health claims and FDA notification requirements elevate compliance costs. Synthetic beta carotene dominates animal feed and mass-market food coloring, while emulsified forms capture share in beverage fortification where dispersion stability determines specification adherence.
FDA color additive regulations under 21 CFR 73.95 and EFSA Panel on Food Additives evaluations govern permitted uses and purity thresholds, directly influencing formulation decisions by food manufacturers and cosmetic companies. REACH registration requirements for synthetic precursors and China's GB 2760 food additive standards further fragment compliance obligations across supply chains. Stakeholders must monitor evolving natural-source certification schemes and regional maximum-level adjustments to preserve formulation flexibility and market access.
Market Dynamics
Fermentation-derived natural beta carotene is compressing synthetic market share as EFSA clean-label enforcement tightens procurement specifications across European dietary supplement channels.
Growth Catalysts
- EFSA Health Claims Regulation:Approved Article 13.1 and 14.1 claims for provitamin A activity drive premium positioning in fortified foods and supplements across EU member states.
- Blakeslea trispora Fermentation:Industrial-scale fungal cultivation delivers natural-source carotenoids at cost parity with synthetic processes, accelerating substitution in colorant applications.
- China Fermentation Cluster:Zhejiang Province's concentrated intermediate production supplies global formulators with bulk natural beta carotene for downstream encapsulation.
Market Restraints
- Algal Biomass Volatility:Dunaliella salina cultivation in open ponds faces climate-induced yield fluctuations that constrain natural-source supply reliability.
- REACH Registration Burden:Synthetic precursor compliance costs under EU chemical regulations disproportionately burden mid-scale European manufacturers.
- Lutein and Astaxanthin Substitution:Competing carotenoids with overlapping antioxidant positioning capture share in eye health and skin care formulations.
Strategic Opportunities
- Brazil Nutraceutical Expansion:ANVISA's streamlined novel ingredient pathways reduce entry barriers for fermented natural beta carotene in Latin America's fastest-growing supplement market.
- Beverage Emulsification Demand:Stable dispersion formats for clear drinks and functional waters open new formulation categories beyond traditional tablets and softgels.
- EU Green Deal Bioeconomy Incentives:Fermentation-based production qualifies for sustainable manufacturing subsidies that improve natural-source cost competitiveness.
Industry Challenges
- ISO 22000 Audit Backlog:Third-party certification queues delay supplier qualification timelines for smaller extraction operations seeking clean-label supply contracts.
- Algae-to-Fermentation Process Transfer:Manufacturers retooling from open-pond Dunaliella systems to controlled fermentation face steep technical learning curves and yield optimization periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beta Carotene Market |
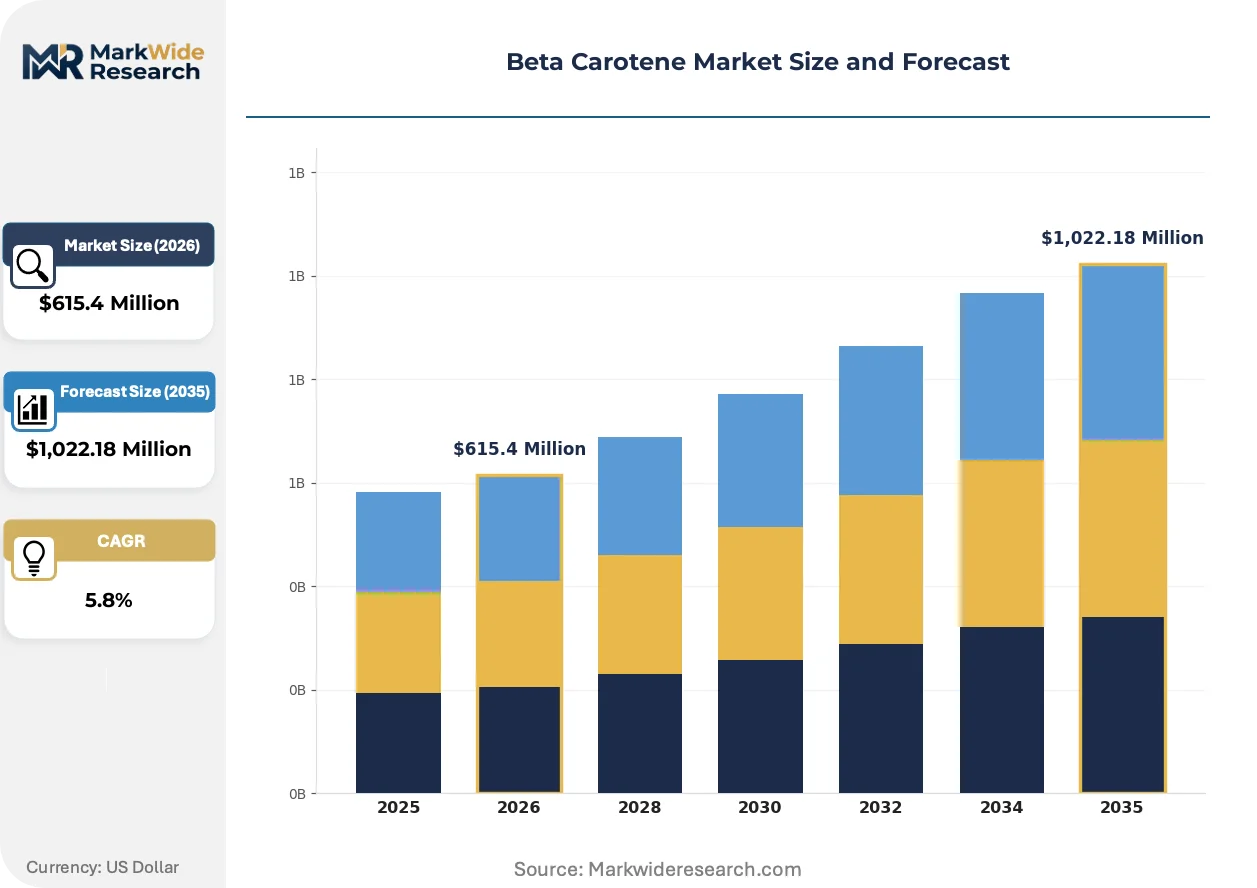
| Market Size in 2026 | $615.4 Million |
| Market Size in 2035 | $1,022.18 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Emulsified, Powdered Application: Food & Beverage, Dietary Supplements, Cosmetics, Animal Feed End User: Food Manufacturers, Cosmetic Companies, Pharmaceuticals, Pet Food Producers Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Divi's Nutraceuticals, Cyanotech Corporation, dsm-firmenich, Lycored, Givaudan, BASF SE, Allied Biotech Corporation, Chr. Hansen, Zhejiang Medicine Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beta Carotene Market Strategic Shifts & Innovations
Bioprocess engineering advances are collapsing the cost gap between natural and synthetic beta carotene production, while regulatory differentiation accelerates format-specific demand fragmentation across end-use verticals.
Precision fermentation of Blakeslea trispora is supplanting algal extraction as the dominant natural-source pathway, delivering batch-to-batch consistency that Dunaliella open-pond cultivation cannot match. Dietary supplement contract manufacturers in Germany and the Netherlands are converting fermentation capacity at pace. This technology compression is eroding the traditional natural-source premium and forcing algal suppliers toward astaxanthin specialization.
EFSA's 2023 updated guidance on food additive specifications tightened purity thresholds for synthetic beta carotene used in infant nutrition and medical foods. The industrial consequence is elevated analytical testing burdens and reformulation costs for legacy synthetic-dependent suppliers. Pharmaceutical-grade applications in France and Italy are responding by accelerating natural-source validation programs to preempt future specification tightening.
Direct-procurement relationships between finished goods brands and fermentation facilities are shortening traditional multi-tier distribution channels. Supplement and functional food manufacturers in California and New York are establishing captive supply agreements that bypass conventional ingredient distributors. This channel compression is most visible in North American clean-label segments where lot traceability and certification documentation carry premium value.
Beta Carotene Market Segmentation
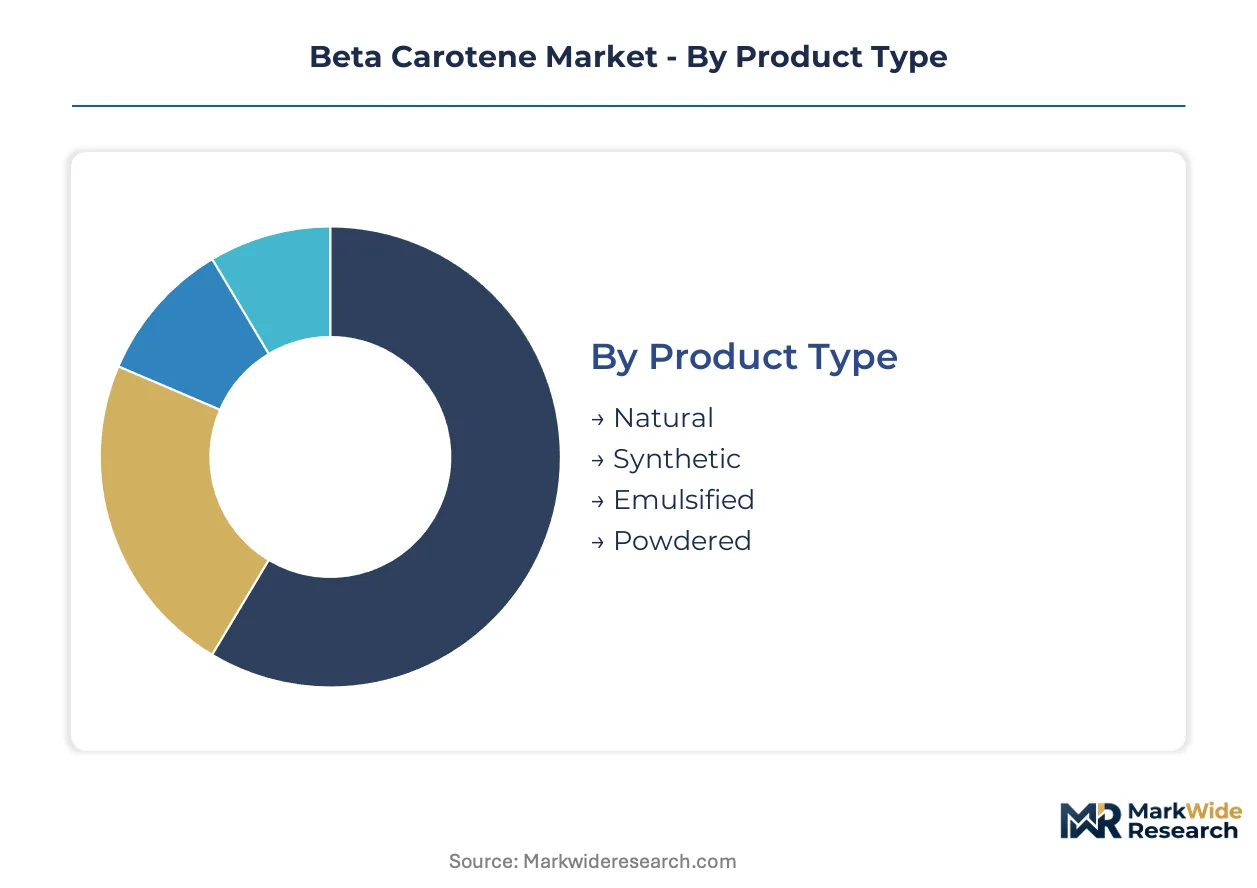
Segmentation in the beta carotene market reveals how substitution pressures from competing carotenoids reshape procurement patterns across product formats. Manufacturers must align specification tiers with end-use compliance requirements to defend margin positions.
Product Type:
Substitution pressure from lutein and astaxanthin concentrates in synthetic and powdered formats where functional differentiation is weakest, while natural-source segments leverage EFSA clean-label enforcement to sustain premium positioning.
- Natural:Derived from Blakeslea trispora fermentation or Dunaliella salina extraction, this format carries ISO 22000 certification requirements that filter supplier eligibility. Dietary supplement manufacturers in Germany and the Netherlands are converting fermentation capacity to capture EFSA Article 13.1 health claim advantages.
- Synthetic:Petrochemical-derived beta carotene dominates animal feed and mass-market food coloring where cost sensitivity overrides clean-label preferences. REACH registration burdens under ECHA guidelines disproportionately constrain mid-scale European synthetic producers.
- Emulsified:Water-dispersible forms target beverage fortification with dispersion stability specifications.
- Powdered:Dry formats serve tablet and capsule manufacturing with compressibility and flow characteristics.
Synthetic anchors the volume base while natural gains share at the steepest rate.
Application:
Cost tier stratification separates pharmaceutical-grade specifications from commodity feed applications, with compliance burden intensity determining margin architecture across verticals.
- Food & Beverage:FDA 21 CFR 73.95 color additive regulations and EFSA purity thresholds govern formulation decisions. Infant nutrition and medical food segments face elevated analytical testing requirements that compress synthetic supplier margins.
- Dietary Supplements:Provitamin A conversion claims at 12:1 weight ratios drive premium positioning in encapsulated and softgel formats. California and New York contract manufacturers are establishing direct-procurement relationships with fermentation facilities to bypass traditional distribution tiers.
- Cosmetics:Antioxidant positioning competes with astaxanthin and lutein in skin care formulations.
- Animal Feed:Cost-driven synthetic dominance persists in poultry and aquaculture pigmentation.
Dietary supplements command the highest margin tier while food and beverage delivers the deepest volume scale.
End User:
Customer type fragmentation concentrates procurement power among pharmaceutical-grade buyers who impose certificate-of-analysis requirements that smaller extraction operations struggle to satisfy.
- Food Manufacturers:Mass-market formulators prioritize synthetic beta carotene for stability and cost predictability, though clean-label lines in France and Italy are accelerating natural-source validation programs.
- Cosmetic Companies:Formulation flexibility demands span emulsified aqueous systems to lipid-soluble anhydrous bases.
- Pharmaceuticals:USP-grade specifications for medical foods and prenatal applications impose the most stringent purity thresholds.
- Pet Food Producers:Volume procurement of synthetic forms for companion animal coloration.
Pharmaceuticals impose the most demanding specification burden while pet food producers generate the highest tonnage throughput.
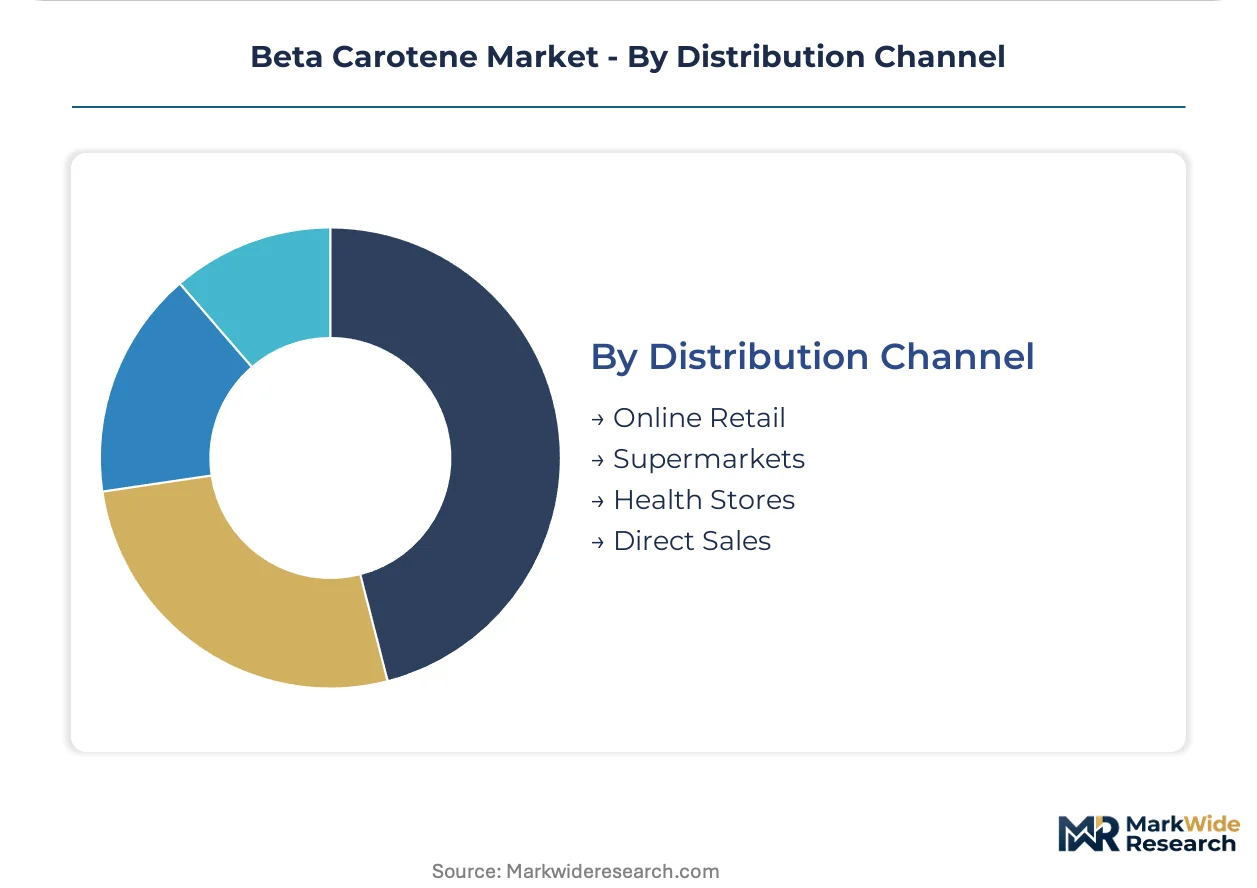
Distribution Channel:
Channel compression is restructuring traditional multi-tier supply chains as finished goods brands seek lot traceability and certification documentation directly from fermentation facilities.
- Online Retail:E-commerce platforms aggregate specialty and clean-label beta carotene products for small-scale supplement manufacturers and research institutions.
- Supermarkets:Mass-market fortified food products reach consumers through conventional grocery retail with limited ingredient transparency.
- Health Stores:Natural products retailers emphasize non-GMO and organic-certified beta carotene supplements.
- Direct Sales:Captive supply agreements between California supplement brands and Zhejiang Province fermentation facilities are shortening distribution layers.
Direct sales channels are expanding most quickly while supermarkets retain the broadest consumer reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites Europe's position as the primary distribution hub for fermentation-derived carotenoids entering pharmaceutical and food-grade channels.
United States
California contract manufacturers and New York-based supplement brands drive clean-label procurement through direct-procurement relationships with Asian fermentation facilities. FDA's 21 CFR 73.95 color additive regulations govern formulation decisions for fortified foods and beverages. DSM-Firmenich maintains backward integration into fermentation-derived carotenoids through European supply lines serving US pharmaceutical-grade demand.
China
Zhejiang Province's concentrated intermediate production supplies global formulators with bulk natural beta carotene for downstream encapsulation and tablet manufacturing. GB 2760 food additive standards establish purity thresholds that align with export market requirements in Europe and North America. Ningbo and Hangzhou fermentation clusters anchor the country's dominance in Blakeslea trispora-derived natural carotenoids.
Germany
Dietary supplement contract manufacturers in Germany convert fermentation capacity to capture EFSA Article 13.1 health claim advantages for provitamin A positioning. REACH registration requirements under ECHA guidelines constrain mid-scale synthetic producers and accelerate natural-source substitution. Hamburg and Frankfurt pharmaceutical corridors impose USP-grade specifications that filter supplier eligibility through certificate-of-analysis requirements.
Netherlands
Rotterdam's chemical logistics infrastructure positions Dutch distributors as gatekeepers for fermentation-derived carotenoids entering European compounding facilities. EFSA clean-label enforcement tightens procurement specifications across dietary supplement channels, elevating ISO 22000 certification as a supplier eligibility filter. DSM-Firmenich leverages Dutch operational bases to sustain pharmaceutical-grade supply continuity across EU member states.
Brazil
ANVISA's streamlined novel ingredient pathways reduce entry barriers for fermented natural beta carotene in Latin America's fastest-growing supplement market. São Paulo and Rio de Janeiro nutraceutical manufacturers expand procurement of natural-source carotenoids amid tightening clean-label requirements. Domestic formulators establish direct relationships with Zhejiang Province fermentation facilities to bypass traditional multi-tier distribution channels.
Beta Carotene Market Key Industry Players
Listed leaders compete with private specialists across certification tiers, with public companies leveraging capital market access to fund backward integration while private operators concentrate on regional clean-label niches. The vendor base organizes around three strategic archetypes: fermentation-scale specialists, algal extraction purists, and synthetic commodity producers. DSM-Firmenich exemplifies the integrated model, Cyanotech Corporation anchors the algal niche, and Zhejiang Medicine Co., Ltd. occupies the intermediate supply tier. Competitive moves concentrate on direct-procurement relationship formation and ISO 22000 certification acquisition to qualify for pharmaceutical-grade supply contracts.
Within the fermentation-scale tier, DSM-Firmenich and Zhejiang Medicine Co., Ltd. exemplify divergent geographic strategies, with the former leveraging European pharmaceutical corridors and the latter dominating intermediate export volumes from East China. Cyanotech Corporation occupies a distinct position as the algal extraction anchor, maintaining Hawaiian microalgae cultivation against the technology compression from precision fermentation. These three named entities represent the structural poles around which mid-scale competitors organize their positioning strategies.
| Leading Market Players |
|---|
| Divi's Nutraceuticals |
| Cyanotech Corporation |
| dsm-firmenich |
| Lycored |
| Givaudan |
| BASF SE |
| Allied Biotech Corporation |
| Chr. Hansen |
| Zhejiang Medicine Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day fermentation batch cycles in Zhejiang Province fermentation clusters concentrate pricing power among integrated producers capable of ISO 22000-certified continuous output, while spot-market buyers face volatility from algal biomass yield fluctuations.
Pricing Analysis
Volume-discount tiering separates pharmaceutical-grade natural beta carotene from commodity synthetic feed-grade material, with EFSA Article 13.1 health claim certification and USP-grade purity testing as the primary price differentiation drivers. Cost compression in synthetic tiers intensifies as REACH registration burdens squeeze mid-scale European manufacturers. Animal feed producers exhibit the highest price sensitivity, while dietary supplement contract manufacturers in Germany and the Netherlands absorb premiums for traceable fermentation-derived supply.
Supply Chain Analysis
China anchors global intermediate production through Zhejiang Province's concentrated fermentation capacity, with the Netherlands and Germany commanding downstream pharmaceutical-grade compounding and distribution. Blakeslea trispora fungal strains, petrochemical precursors, and encapsulation-grade excipients constitute critical input dependencies. Single-source vulnerability concentrates in open-pond Dunaliella salina cultivation exposed to climate-induced yield volatility. Distribution runs through Rotterdam's chemical logistics infrastructure for European pharmaceutical corridors, while direct-procurement relationships between California supplement brands and East Asian fermentation facilities bypass traditional multi-tier channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation technology is disrupting beta carotene production economics, compressing the natural-source premium and forcing algal suppliers toward astaxanthin specialization as EFSA clean-label enforcement accelerates format-specific demand fragmentation.
For Market Incumbents: Shield pharmaceutical-grade positioning through captive backward integration into Blakeslea trispora fermentation capacity, particularly in Zhejiang Province and European corridors. Accelerate ISO 22000 certification acquisition to preempt supplier eligibility filters tightening across EFSA-regulated channels. Defend against astaxanthin and lutein substitution in cosmetics by locking long-term direct-procurement relationships with California and New York supplement brands.
For New Entrants and Emerging Players: Beverage emulsification technical service gaps expose white-space opportunity where incumbent fermentation specialists under-serve dispersion stability requirements for clear functional waters. Target ANVISA-regulated Brazil nutraceutical expansion through streamlined novel ingredient pathways. Penetrate via fermentation-derived natural beta carotene supply agreements with São Paulo contract manufacturers seeking clean-label alternatives to synthetic colorants.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across precision fermentation sub-segments as bioprocess engineering advances collapse batch optimization timelines. Five-to-ten-year viability favors acquisition of mid-scale fermentation facilities with existing Blakeslea trispora strain libraries and validated downstream encapsulation partnerships. Monitor EFSA food additive specification tightening for infant nutrition as the signal indicating accelerated natural-source substitution inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | DSM-Firmenich leverages Dutch operational bases to secure pharmaceutical-grade supply continuity across EU member states. |
| ISO 22000 Certification Acquisition | Third-party audit investments qualify smaller extractors for clean-label supply contracts with German dietary supplement manufacturers. |
| Direct-Procurement Relationship Formation | California brands bypass traditional distribution tiers to capture lot traceability and certification documentation premiums. |
| Algae-to-Fermentation Process Transfer | Manufacturers retooling from Dunaliella open-pond systems face steep technical learning curves during yield optimization periods. |
| Beverage Emulsification Format Development | Stable dispersion systems for clear drinks open formulation categories beyond traditional tablets and softgels. |
Research Approach
The analysis maps natural-source fermentation, synthetic petrochemical-derived, and algal extraction sub-sectors, each validated through fermentation plant managers, dietary supplement procurement leads, pharmaceutical compounding directors, and EFSA regulatory affairs specialists. Primary interview insights triangulate against customs and trade data for carotenoid intermediate flows, SEC 10-K filings for listed nutritional ingredient producers, GB 2760 food additive standards documentation, and EFSA Panel on Food Additives evaluation records. Bottom-up capacity assessments and top-down demand modeling converge through cross-validation against DSM-Firmenich and Zhejiang Medicine operational disclosures.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. The analytical framework segments by product type, application vertical, end-user category, and distribution channel, with fermentation scale and certification tier as industry-specific dimensions. CAGRs derive from weighted average growth assumptions applied to segment-level baseline estimates, incorporating EFSA enforcement intensity indices and ANVISA regulatory pathway velocity as forecast inputs.
Underlying assumptions cover EFSA specification stability, fermentation yield improvement trajectories, and China export license continuity, with deviation risk concentrated in algal biomass climate volatility and REACH registration burden escalation. Recalibration cycles align with material shifts in clean-label procurement specifications and novel ingredient regulatory pathway developments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Vitamins Drink Market
Vitamin Fortified
South America Food Fortifying Agents Market
Vitamin Fortified
North America Vitamin D Market
Vitamin Fortified
Vitamin D3 Oil Market
Vitamin Fortified
Natural Source Vitamin E Market
Vitamin Fortified
Liquid Vitamins Market
Vitamin Fortified
Vitamin AD Drops Market
Vitamin Fortified
Vitamin Fortified and Mineral Enriched Food & Beverage Market
Vitamin Fortified
Gamma-Tocopherol Market
Vitamin Fortified
Vitamin C Market
Vitamin Fortified
Fortified Breakfast Spreads Market
Vitamin Fortified
Food Grade Vitamin B Market
Vitamin Fortified
Europe Vitamin a Market
Vitamin Fortified
Micronutrients Market
Vitamin Fortified
Asia-Pacific Food Fortifying Agent Market
Vitamin Fortified
Feed Vitamins Market