
 Fermentation Products Market | 2026-2036
Fermentation Products Market Size, Share, and Industry Trends Forecast 2026-2036
Fermentation Products Market Foresight
Buyer concentration among pharmaceutical contract manufacturers is pivoting as biologics developers consolidate outsourced fermentation capacity toward fewer qualified suppliers. Lonza Group AG anchors large-scale mammalian cell fermentation services for biopharmaceutical clients across North America and Europe. BASF SE leverages its backward integration into industrial enzyme fermentation to supply downstream partners in detergents and animal nutrition. Cargill, Incorporated competes through geographic dominance in corn-based bioethanol fermentation across the US Midwest.
Fermentation products comprise metabolites, biomass, and recombinant proteins generated through controlled microbial or enzymatic conversion of substrates under optimized temperature, pH, and oxygen conditions, typically achieving titers of 50-150 g/L for commodity organic acids. These outputs serve as building blocks for food preservation, pharmaceutical actives, crop protection agents, and renewable chemicals. Amino acids generated via submerged fermentation command substantial margin pools due to pharmaceutical-grade purity requirements and complex downstream processing, while bioethanol remains volume-dominant but margin-constrained by energy feedstock volatility. Batch fermentation technology occupies the largest installed base, though continuous fermentation systems are gaining traction in citric acid and yeast biomass production for their superior productivity coefficients.
EPA industrial effluent guidelines and FDA current Good Manufacturing Practice standards govern fermentation facility emissions and pharmaceutical product quality, respectively, creating compliance cost barriers that favor capital-rich operators. REACH registration requirements in Europe restrict novel microbial strain introductions, slowing product pipeline expansion for European suppliers. ISO 22000 food safety management certification shapes market access for fermentation-derived food ingredients across export markets. Stakeholders must monitor strain engineering patent thickets and carbon accounting methodologies as these will determine which production platforms secure preferential offtake from sustainability-focused buyers.
Market Dynamics
Pharmaceutical biologics manufacturers are consolidating outsourced fermentation capacity toward fewer qualified suppliers, tightening supplier qualification timelines and compressing batch release cycles for monoclonal antibody production.
Growth Catalysts
- EU Green Deal mandates:Industrial bioprocessing facilities face tightening environmental standards that favor capital-rich operators capable of deploying energy-efficient submerged fermentation infrastructure and carbon capture integration.
- Submerged fermentation scaling:Domestic amino acid producers in China are expanding production infrastructure to serve regional animal feed and food additive markets, concentrating demand in Asia-Pacific manufacturing clusters.
- Continuous fermentation systems:Citric acid and yeast biomass producers are adopting continuous processing for superior productivity coefficients, displacing legacy batch fermentation in high-volume commodity applications.
Market Restraints
- Energy feedstock volatility:Bioethanol fermentation remains margin-constrained by crude oil and natural gas price swings, compressing returns for corn-based producers across the US Midwest.
- REACH registration friction:European suppliers face restricted novel microbial strain introductions, slowing product pipeline expansion and favoring incumbent strain libraries over engineered alternatives.
- Pharmaceutical-grade purity requirements:Amino acid downstream processing demands complex chromatography and crystallization systems, elevating capital intensity above commodity organic acid thresholds.
Strategic Opportunities
- Carbon accounting methodologies:Sustainability-focused buyers are developing preferential offtake criteria that reward fermentation platforms with verified low-carbon intensity, creating differentiation for early adopters.
- Recombinant protein expansion:Enzyme fermentation for detergents and animal nutrition offers margin expansion through backward integration into industrial biotechnology.
- ISO 22000 certification gaps:Export-oriented food ingredient suppliers can secure market access advantages in Asia-Pacific and Middle Eastern import markets through food safety management certification.
Industry Challenges
- Strain engineering patent thickets:CRISPR and metabolic pathway IP landscapes create licensing complexity for novel microbial chassis development, elevating legal review timelines.
- Current Good Manufacturing Practice compliance:FDA pharmaceutical quality standards demand extensive documentation and validation protocols, extending facility commissioning periods.
- Skilled fermentation technologist scarcity:Bioprocess engineering and scale-up expertise shortages constrain facility expansion timelines for mammalian cell culture operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fermentation Products Market |
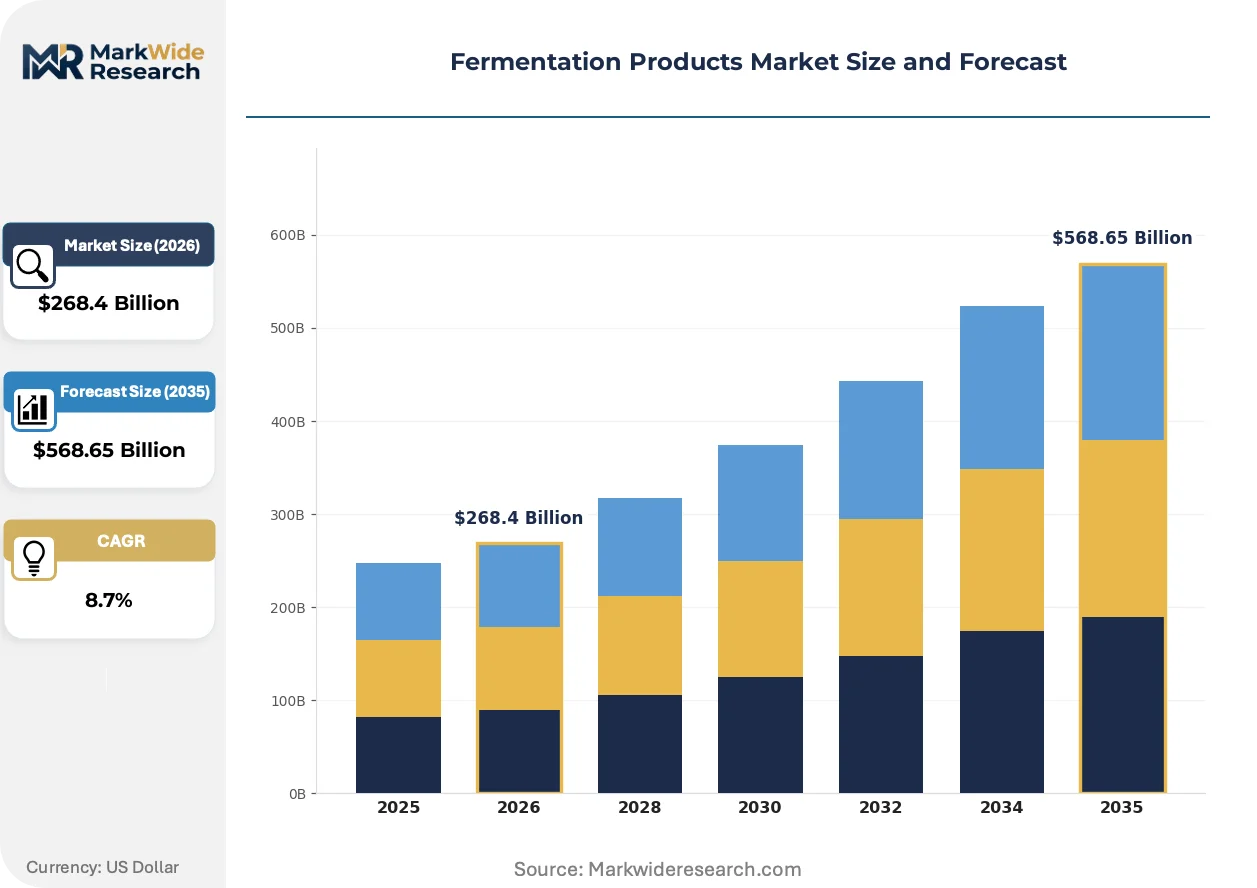
| Market Size in 2026 | $268.4 Billion |
| Market Size in 2035 | $568.65 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioethanol, Lactic Acid, Acetic Acid, Amino Acids Application: Food & Beverage, Pharmaceuticals, Agriculture, Animal Feed End User: Food Manufacturers, Beverage Producers, Nutraceutical Companies, Agricultural Firms Technology: Batch Fermentation, Continuous Fermentation, Solid-State Fermentation, Submerged Fermentation |
| Companies Covered | BASF SE, Cargill, Incorporated, Evonik Industries AG, DuPont de Nemours, Inc., Koninklijke DSM N.V., Lonza Group AG, Novozymes A/S, Archer Daniels Midland Company, Ajinomoto Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fermentation Products Market Shifts & Advancements
Process intensification and digital bioprocessing are compressing development timelines while regulatory carbon accounting is reshaping facility investment criteria across pharmaceutical and industrial fermentation segments.
Continuous perfusion bioreactor technology is electrifying upstream productivity in monoclonal antibody manufacturing. Biopharmaceutical contract manufacturers are adopting these systems to maximize volumetric productivity and reduce facility footprints. The technology is electrifying competitive positioning by enabling smaller-scale facilities to match output of legacy stainless-steel batch plants.
F-Gas Regulation tightening under the EU Green Deal is mandating refrigerant transitions and thermal energy recovery in industrial fermentation facilities. This policy is elevating capital requirements for cooling system retrofits and process heat integration. Citric acid and yeast biomass producers in Germany and the Netherlands are responding with ammonia-based refrigeration and anaerobic digestion coupling.
Buyer concentration among pharmaceutical developers is compressing supplier qualification cycles and unbundling analytical services from manufacturing contracts. Large-molecule developers are directly contracting specialized testing laboratories rather than relying on fermentation partners for release testing. This pattern is most visible in North American biologics clusters where sponsor companies maintain captive quality organizations.
Fermentation Products Market Segmentation
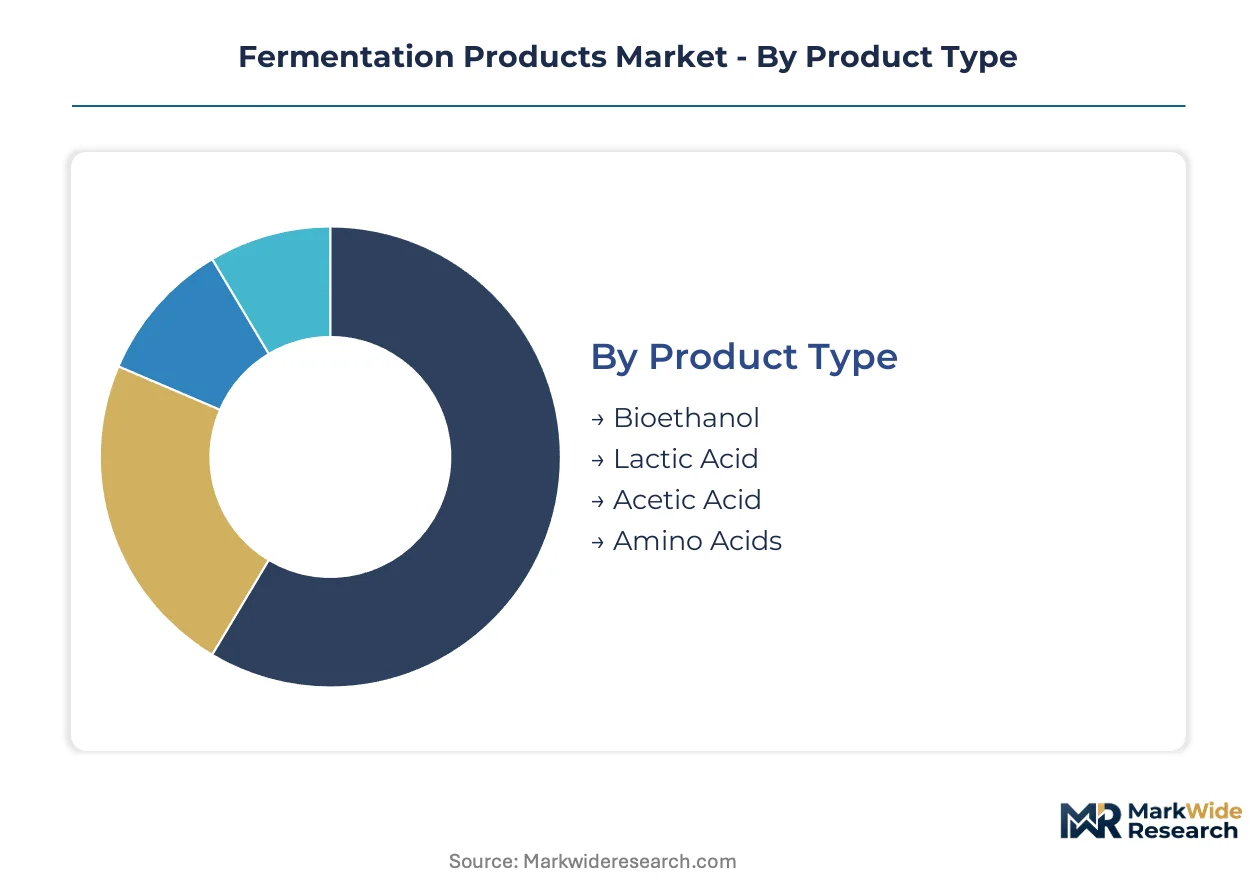
Fermentation product categories diverge sharply in capital intensity and margin structure. Batch systems dominate installed capacity while continuous platforms reshape productivity benchmarks. End-user concentration among pharmaceutical contract manufacturers is compressing supplier qualification timelines across all product tiers.
Product Type:
Supply concentration in organic acids tilts toward corn-belt ethanol corridors and Chinese amino acid clusters, creating divergent margin pools across commodity and specialty grades.
- Bioethanol:Corn-starch conversion via Saccharomyces cerevisiae achieves titers exceeding 15% v/v in optimized dry-grind facilities. Demand concentrates across US Midwest refineries serving Renewable Fuel Standard mandates, though margin compression from natural gas price volatility constrains facility expansion.
- Amino Acids:Pharmaceutical-grade L-lysine and L-threonine require submerged fermentation with complex downstream chromatography and crystallization. Chinese producers in Shandong and Hebei provinces anchor global supply for animal feed applications, while European facilities capture premium pharmaceutical contracts.
- Lactic Acid:Polylactic acid precursor fermentation employs Lactobacillus strains with pH-controlled calcium carbonate neutralization. Food-grade specifications dominate current offtake.
- Acetic Acid:Industrial vinegar production via Acetobacter oxidation serves preservative and chemical intermediate markets.
Today's leader: Amino Acids. Tomorrow's challenger: Bioethanol.
Application:
Cost tier stratification separates pharmaceutical-grade biologics from commodity food additives, with regulatory compliance burden scaling proportionally.
- Pharmaceuticals:Monoclonal antibody production demands mammalian cell fermentation under FDA current Good Manufacturing Practice with extensive batch release documentation. North American biologics clusters in Massachusetts and California concentrate outsourced capacity toward Lonza and Samsung Biologics facilities.
- Food & Beverage:Citric acid and yeast biomass fermentation operates under ISO 22000 certification requirements for export market access. European producers face F-Gas Regulation mandates for refrigerant transitions in cooling-intensive facilities.
- Animal Feed:Lysine and methionine supplementation drives submerged fermentation scale-up in Chinese manufacturing corridors.
- Agriculture:Biopesticide and biostimulant fermentation serves crop protection markets with lower purity thresholds than pharmaceutical applications.
Pharmaceuticals command premium pricing tiers. Food & Beverage delivers volume scale.
End User:
Customer type fragmentation creates distinct procurement patterns, with nutraceutical companies demanding traceability systems that food manufacturers rarely require.
- Food Manufacturers:Preservative and acidulant procurement emphasizes supply security over technical specification, favoring multi-source strategies.
- Nutraceutical Companies:Probiotic and enzyme formulations require strain-specific documentation and stability testing.
- Beverage Producers:Ethanol and organic acid sourcing tracks sugar feedstock availability.
- Agricultural Firms:Amino acid and enzyme feed additives compete on delivered cost per unit protein equivalent.
Nutraceutical buyers pay certification premiums. Agricultural procurement prioritizes landed cost optimization.
Technology:
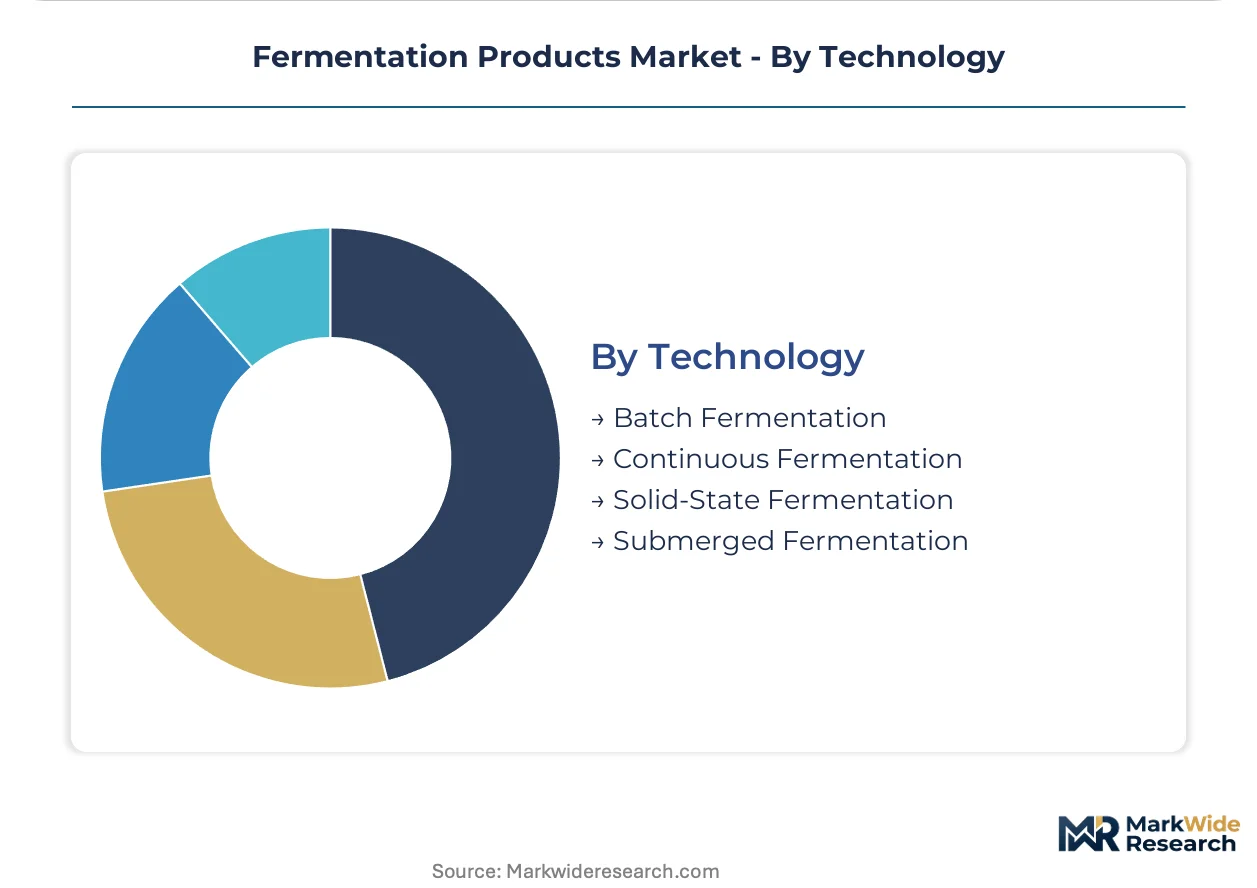
Volume concentration in legacy batch infrastructure constrains continuous system penetration despite superior productivity coefficients.
- Batch Fermentation:Stainless-steel stirred-tank systems with sequential sterilization and inoculation cycles occupy the largest installed base globally. Pharmaceutical biologics manufacturers retain these platforms for regulatory familiarity, though facility footprints exceed continuous alternatives.
- Continuous Fermentation:Chemostat and perfusion configurations achieve higher cell density maintenance with reduced downtime. Citric acid producers in Germany and yeast biomass facilities in the Netherlands are adopting these systems for energy recovery integration under EU Green Deal thermal efficiency mandates.
- Submerged Fermentation:Liquid-phase aerobic culture with controlled dissolved oxygen serves amino acid and antibiotic production.
- Solid-State Fermentation:Moist solid substrate cultivation supports fungal enzyme and traditional food fermentations with lower water consumption.
Batch fermentation retains regulatory anchoring. Continuous systems gain share fastest in commodity organic acids.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates amino acid fermentation capacity while the United States dominates bioethanol refining infrastructure, creating divergent regional specialization patterns across the fermentation products landscape.
China
Submerged fermentation scale-up for L-lysine and L-threonine drives capital deployment in Shandong and Hebei provinces. The Ministry of Ecology and Environment enforces dual carbon goals that constrain energy-intensive facility expansions. Domestic producers in these northern manufacturing corridors are capturing regional animal feed additive demand through backward integration into corn processing.
United States
Corn-starch bioethanol fermentation anchors demand across Iowa, Illinois, and Nebraska refinery networks. EPA Renewable Fuel Standard mandates set blending volume obligations that stabilize offtake for dry-grind facilities. Facility operators in the Midwest are confronting margin compression from natural gas price volatility while maintaining RFS compliance infrastructure.
Germany
Citric acid and yeast biomass producers face F-Gas Regulation mandates for refrigerant transitions in cooling-intensive fermentation plants. EU Green Deal thermal efficiency standards are accelerating continuous system adoption. Producers in the North Rhine-Westphalia chemical corridor are deploying ammonia-based refrigeration and anaerobic digestion coupling to meet compliance deadlines.
India
Enzyme fermentation for detergents and textile processing is expanding around Mumbai and Ahmedabad manufacturing zones. FSSAI food safety certification requirements shape market access for fermentation-derived ingredients. Contract manufacturers in Maharashtra are qualifying pharmaceutical-grade capacity to serve domestic biologics developers.
Switzerland
Mammalian cell fermentation services for monoclonal antibody production concentrate around Basel biopharma clusters. Swissmedic pharmaceutical manufacturing standards enforce stringent batch release documentation protocols. Lonza Group AG anchors large-scale capacity in this region, serving North American and European biologics sponsors.
Fermentation Products Market Competitive Landscape
Chinese producers anchor the commodity amino acid tier; European specialists hold pharmaceutical-grade biologics fermentation. The vendor base splits between capital-intensive mammalian cell culture operators and corn-belt bioethanol refiners. Three archetypes dominate: backward-integrated chemical conglomerates, geographic-focused agricultural processors, and contract biomanufacturing specialists. Competitive moves center on capacity consolidation toward fewer qualified suppliers and carbon capture integration for EU regulatory compliance.
Within the contract biomanufacturing tier, Lonza Group AG exemplifies large-scale mammalian cell fermentation services, while BASF SE represents backward-integrated chemical conglomerates with industrial enzyme capabilities. Among agricultural processors, Cargill, Incorporated anchors geographic dominance in corn-based fermentation infrastructure.
| Leading Market Players |
|---|
| BASF SE |
| Cargill, Incorporated |
| Evonik Industries AG |
| DuPont de Nemours, Inc. |
| Koninklijke DSM N.V. |
| Lonza Group AG |
| Novozymes A/S |
| Archer Daniels Midland Company |
| Ajinomoto Co., Inc. |
| Others |
Supply & Pricing Matrix
Pharmaceutical contract manufacturer consolidation toward fewer qualified suppliers is compressing batch release cycles and forcing fermentation partners to absorb qualification costs, which elevates pricing power for capital-rich operators with validated mammalian cell capacity.
Pricing Analysis
Capacity additions in China are reshaping price floors for commodity amino acids while pharmaceutical-grade biologics maintain contract-based long-term offtake structures. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels separates margin pools, with FDA cGMP-tiered products commanding substantial premiums over ISO 22000 food-grade specifications. Cost compression in corn-based bioethanol runs through natural gas price volatility, which squeezes dry-grind facility returns across the US Midwest. Agricultural feed additive buyers exhibit highest price sensitivity, while biologics sponsors prioritize supply security over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore anchor hub-and-spoke patterns for fermentation-derived ingredients serving European and Asia-Pacific markets. Manufacturing concentrates in China, the United States, and Germany, with Chinese producers dominating amino acid output and US facilities anchoring corn-starch bioethanol. Supply chains draw from corn feedstock, natural gas for thermal energy, and specialized microbial strain libraries. Single-source vulnerability in pharmaceutical-grade monoclonal antibody fermentation elevates risk, as qualified mammalian cell capacity remains concentrated among a handful of contract manufacturers. Distribution runs through bulk liquid tanker networks for organic acids and temperature-controlled logistics for active pharmaceutical ingredients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation products function as a stable compounder anchored by irreversible biologics demand from pharmaceutical developers with limited manufacturing alternatives.
For Market Incumbents: Lock in supplier qualification timelines with biologics sponsors before competitor capacity comes online, and deepen backward integration into strain engineering to capture margin from metabolic pathway IP. Contract manufacturer consolidation poses immediate displacement risk for mid-scale facilities lacking FDA cGMP validation. Carbon capture integration represents the critical lever for EU regulatory compliance and preferential offtake positioning. For New Entrants and Emerging Players: The price-point gap between pharmaceutical-grade monoclonal antibody fermentation and commodity organic acid production offers white-space targeting for mid-tier nutraceutical and enzyme applications. Contract manufacturing for probiotic formulations presents the most penetrable segment, as food-grade ISO 22000 certification requirements remain less stringent than FDA pharmaceutical standards. A go-to-market angle anchored on rapid strain development timelines using CRISPR-edited chassis can differentiate against incumbent strain libraries. For Investors and Strategic Acquirers: Asymmetric upside sits with contract biomanufacturing specialists holding validated mammalian cell capacity in Basel and Boston corridor proximity. The five-to-ten-year viability window favors platforms with demonstrated scale-up from bench to production bioreactor. Acquisition targets should display captive strain engineering capabilities and established FDA master file documentation. The signal to watch is biologics sponsor pipeline advancement into Phase III, which triggers step-change fermentation capacity commitments.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Submerged fermentation scale-up in Shandong province captures regional animal feed additive demand growth. |
| Backward Integration | In-house microbial strain libraries reduce licensing costs from CRISPR patent thickets for metabolic engineering. |
| Green Manufacturing Transition | Ammonia-based refrigeration retrofits satisfy EU F-Gas Regulation mandates for cooling-intensive citric acid plants. |
| Long-term Supply Agreement | Contract biomanufacturing partnerships with Lonza anchor revenue visibility for monoclonal antibody production. |
| Joint Venture | Domestic partnerships in India qualify pharmaceutical-grade capacity under FSSAI certification for regional biologics developers. |
Research Methodology
Multiple input streams — primary interviews with bioprocess engineers and pharmaceutical procurement directors, secondary validation through FDA cGMP inspection records and EMA manufacturing authorization databases, and customs trade data for fermentation product flows — were reconciled through bottom-up facility capacity modeling and top-down demand segmentation triangulation.
Data-stream reconciliation across the projection horizon applied segment-specific growth coefficients to pharmaceutical-grade biologics, food-grade organic acids, and feed-grade amino acids. Modeled dimensions included product purity tier, end-use application, fermentation technology platform, and regional regulatory cluster. CAGRs were derived from facility expansion announcements, sponsor pipeline disclosures, and feedstock cost trajectory assumptions.
Caveats apply where EU Green Deal enforcement intensity, REACH registration friction for novel strains, or biologics sponsor pipeline attrition could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Tea-Based Skin Care Products Market
Specialty Ingredients
Specialty Syrup Market
Specialty Ingredients
Mangosteen Extract Market
Specialty Ingredients
Grape Seed Extract in Pet Food Application Market
Specialty Ingredients
Customized Nutrient Premixes Market
Specialty Ingredients
Cupuacu Butter Market
Specialty Ingredients
Tamanu Oil Market
Specialty Ingredients
Global Sea Buckthorn Oil Market
Specialty Ingredients
Middle East and Africa Specialty Food Ingredients Market
Specialty Ingredients
Gentian Market
Specialty Ingredients
Global Pet Food Flavors Market
Specialty Ingredients
Haitian Vetiver Oil Market
Specialty Ingredients
Mangosteen Market
Specialty Ingredients
Pericarp Waste Market
Specialty Ingredients
Pomegranate Seed Oil Nutricosmetic Ingredients Market
Specialty Ingredients
Specialty Ingredients Market