
 Digestion Resistant Maltodextrin Market | 2026-2036
Digestion Resistant Maltodextrin Market Size, Share, and Industry Trends Forecast 2026-2036
Digestion Resistant Maltodextrin Market Analysis
A shift from single-source corn dextrose supply to multi-source tapioca and wheat starch procurement is restructuring ingredient security across the digestion resistant maltodextrin value chain. Roquette Frères leverages its European pea and wheat starch base to anchor supply continuity for food-grade resistant dextrin. Ingredion Incorporated competes through backward integration into North American corn wet milling. Tate & Lyle PLC differentiates via specialty carbohydrate R&D intensity in its Singapore innovation hub.
Digestion resistant maltodextrin is a low-molecular-weight soluble dietary fiber produced by heat and enzymatic treatment of starch, yielding dextrose equivalents below 20 with over 85% dietary fiber content by weight; it functions as a prebiotic bulking agent, sugar replacer, and moisture retention aid in processed foods and supplements. Powder formulations dominate pharmaceutical and nutraceutical compounding due to superior flowability and shelf stability, while liquid syrups capture expanding beverage fortification demand where rapid dispersion matters. Bakery applications remain mature with thin margin pools, whereas nutraceuticals concentrate value through clinical-grade certification requirements.
The FDA's updated dietary fiber definition under Nutrition Facts labeling rules and EFSA's Article 13 health claim evaluations shape product positioning and substantiation investments across jurisdictions. Japan's Foods for Specified Health Uses system, administered by the Consumer Affairs Agency, creates a premium regulatory pathway for digestion resistant maltodextrin with verified physiological effects. Stakeholders must monitor evolving fiber quantification methodologies and prebiotic claim restrictions as these determine competitive access and pricing power in functional ingredient procurement.
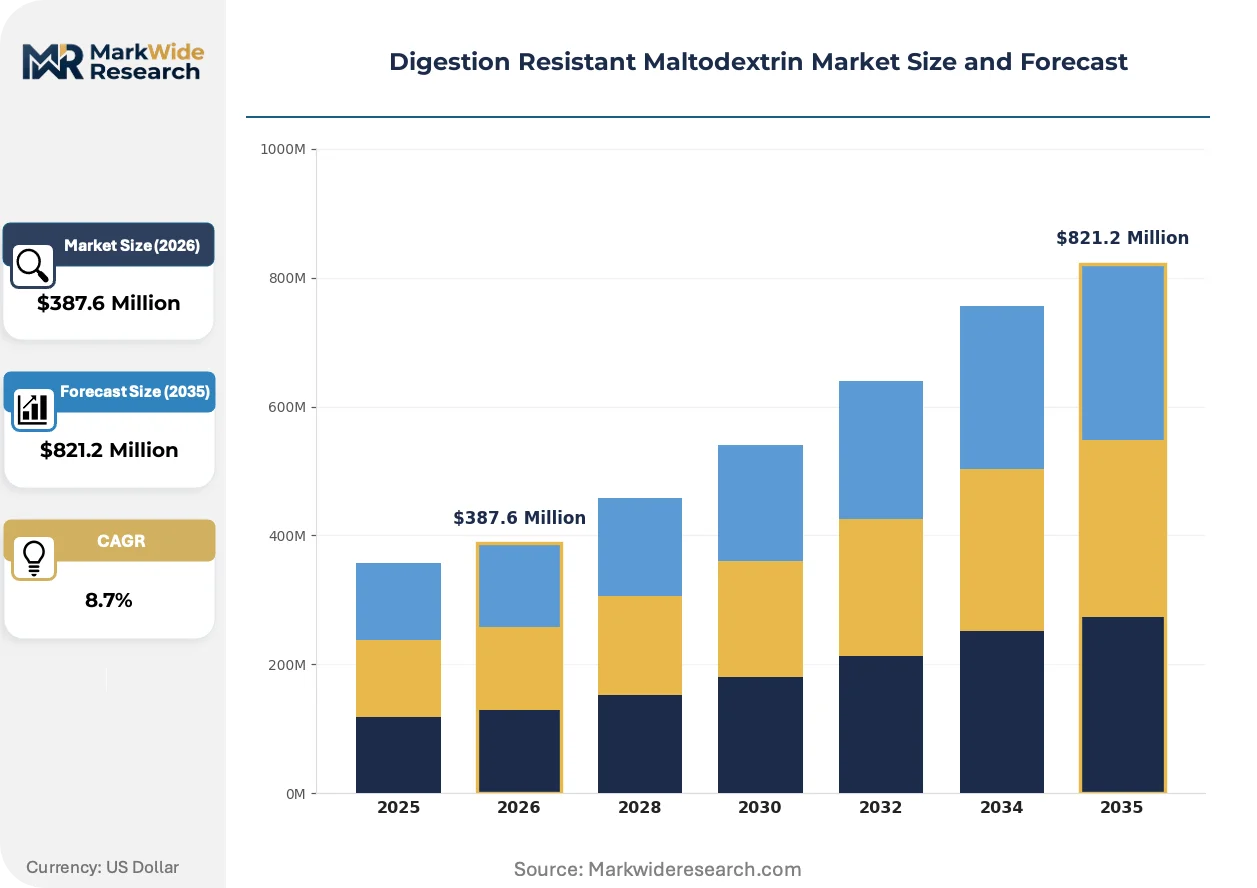
Market Dynamics
Clean-label fiber fortification mandates from FDA and EFSA are compressing formulation cycles while starch feedstock diversification is redrawing procurement geographies across the digestion resistant maltodextrin value chain.
Growth Catalysts
- FDA Dietary Fiber Definition Update:The 2023 fiber quantification guidance under Nutrition Facts labeling rules validates resistant dextrin analytical methods, unlocking label-friendly positioning for beverage and bakery manufacturers seeking prebiotic claims.
- Japan FOSHU Premium Pathway:The Consumer Affairs Agency's verified physiological effects system creates regulatory arbitrage opportunities for clinical-grade resistant maltodextrin commanding price premiums in functional food applications.
- Tapioca Starch Feedstock Pivot:Southeast Asian cassava cultivation expansion is diversifying supply security beyond corn-dependent North American wet milling, enabling non-GMO and allergen-free product line extensions.
Market Restraints
- Corn Wet Milling Concentration:North American corn starch supply dominance creates input cost volatility exposure when agricultural commodity futures spike during planting season disruptions.
- EFSA Article 13 Health Claim Restrictions:The European regulator's stringent substantiation requirements for prebiotic benefits limit marketing language and compress differentiation space for standard-grade products.
- Inulin and Polydextrose Substitution:Established soluble fiber alternatives with deeper clinical dossiers and lower unit economics threaten volume retention in cost-sensitive bakery and dairy applications.
Strategic Opportunities
- India Functional Food Emergence:FSSAI's evolving standards for dietary fiber fortification in processed foods creates first-mover positioning for resistant dextrin suppliers as domestic health-conscious consumption accelerates.
- Clinical Nutrition Contract Manufacturing:Enteral formula and medical food compounders in Germany and Switzerland seek GMP-certified resistant maltodextrin with batch-level fiber content verification.
- Precision Fermentation Convergence:Integration of enzymatic starch modification with cell-cultured ingredient platforms opens novel production pathways reducing thermal processing energy intensity.
Industry Challenges
- Analytical Method Standardization Delays:AOAC and ISO harmonization on resistant dextrin quantification protocols remains incomplete, creating cross-border shipment disputes and customer qualification friction.
- Pharmaceutical-Grade Certification Timelines:USP and EP monograph compliance for excipient-grade resistant maltodextrin requires 18-24 month validation cycles that strain working capital for mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digestion Resistant Maltodextrin Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granule, Liquid, Syrup Application: Food & Beverage, Nutraceuticals, Pharmaceuticals, Bakery End User: Manufacturers, Retailers, Wholesalers, Food Service Distribution Channel: Online, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Roquette Frères, Ingredion Incorporated, Tate & Lyle PLC, Archer Daniels Midland Company, Cargill Incorporated, Matsutani Chemical Industry Co., Ltd., Grain Processing Corporation, Baolingbao Biology Co., Ltd., Tereos Syral S.A.S., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digestion Resistant Maltodextrin Market Emerging Trajectories
Enzymatic specificity advances and regulatory fiber definition refinements are compressing product development timelines while procurement models migrate toward direct compounder relationships.
Precision enzymatic hydrolysis using thermostable alpha-amylase variants is electrifying the production landscape by enabling tighter dextrose equivalent control below 15 DE. Nutraceutical contract manufacturers in Switzerland and Germany are adopting these processes to meet pharmaceutical-grade specifications. The technology is electrifying margin structures by reducing downstream purification steps and enabling single-reactor batch consistency previously requiring multi-stage processing.
EFSA's 2024 guidance on resistant carbohydrate analytical methodologies is tightening fiber content verification requirements for health claim eligibility. Food manufacturers reformulating for the EU market must now submit dual-laboratory validation data resistant dextrin assays. The regulation most affects beverage applications where rapid dissolution requirements previously tolerated broader analytical variance, forcing investments in in-house HPLC capabilities.
Direct procurement relationships between resistant maltodextrin producers and finished goods compounders are displacing traditional ingredient distributor intermediaries in North America and Western Europe. Large beverage and bakery manufacturers now negotiate multi-year offtake agreements specifying minimum dietary fiber content thresholds and origin documentation. This pattern is most visible in Germany where private-label functional food brands consolidate supplier panels to three approved vendors with integrated quality systems.
Digestion Resistant Maltodextrin Market Segmentation
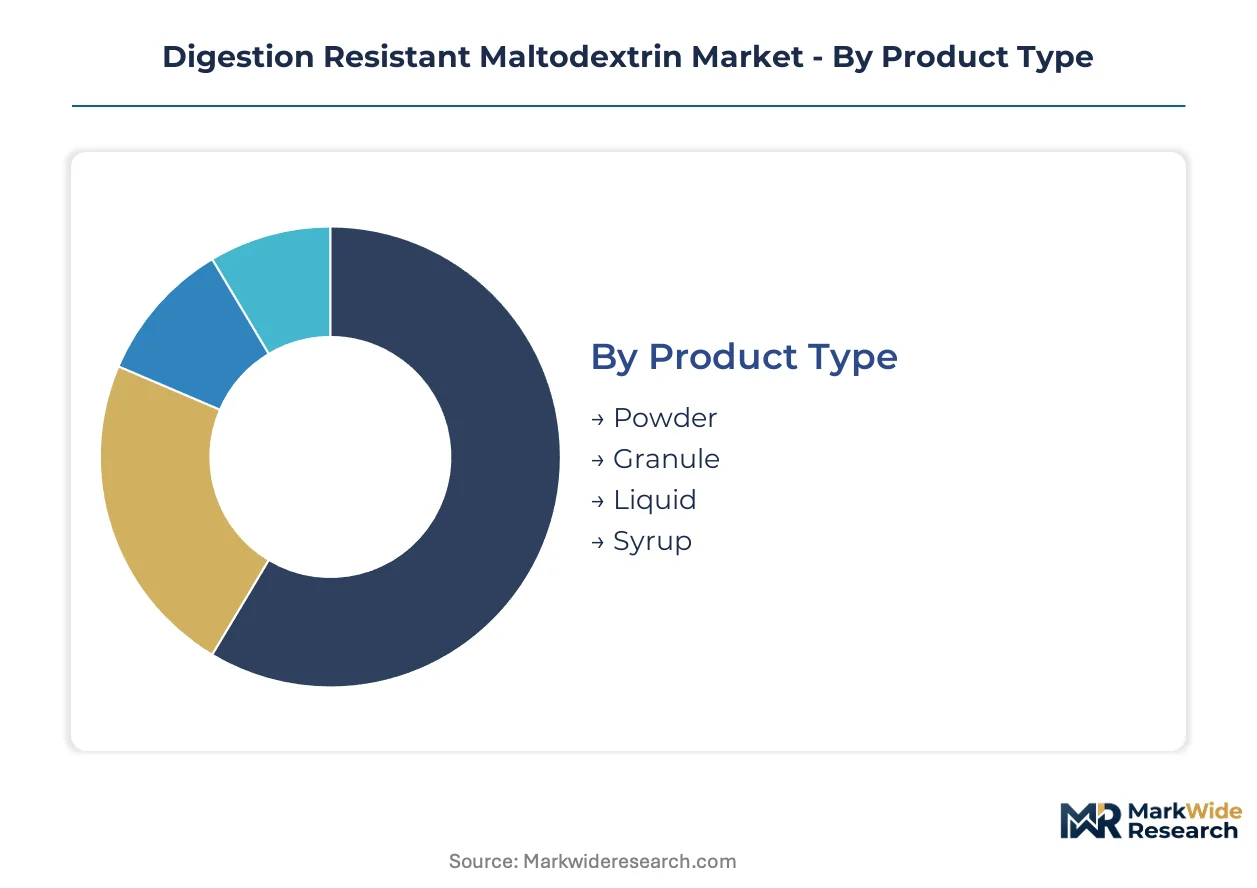
Segmentation in digestion resistant maltodextrin reveals how technical specifications, regulatory pathways, and channel economics fragment procurement behavior across food-grade and clinical-grade demand pools. Understanding these divisions exposes where margin concentrates and where volume commoditizes.
Product Type:
Supply concentration in spray-dried powder capacity at Roquette's Lestrem facility and Ingredion's Argo plant shapes competitive dynamics across physical formats.
- Powder:Spray-dried amorphous particles with dextrose equivalents of 10-18 dominate pharmaceutical tableting and nutraceutical capsule filling due to superior flowability and compressibility. German contract manufacturers in the Rhine-Main cluster specify powder grades with verified fiber content above 85% for enteral nutrition compounding.
- Liquid:Aqueous solutions at 60-75% solids enable rapid dispersion in beverage fortification without hydration delays. Japanese FOSHU-approved functional drinks in Tokyo and Osaka metropolitan areas drive specifications for clarified, low-viscosity syrups with minimal retrogradation.
- Granule:Agglomerated particles bridge powder flow and liquid solubility for bakery premix applications requiring dust-free handling.
- Syrup:High-solids preparations serve industrial-scale beverage manufacturing where metered dosing integrates with existing liquid ingredient systems.
Powder absorbs the bulk of installed capacity; liquid is expanding most quickly.
Application:
Regulatory substantiation requirements and margin structures diverge sharply between health-claim-eligible functional foods and commodity-processed categories.
- Nutraceuticals:Clinical-grade resistant dextrin with batch-level fiber verification and USP monograph compliance commands premium positioning in prebiotic supplements and medical foods. Swiss compounders in Basel and Zurich require GMP certification and dual-laboratory analytical validation for contract manufacturing partnerships.
- Food & Beverage:Clean-label fiber fortification in sports drinks, meal replacements, and dairy alternatives leverages FDA dietary fiber definition compliance for Nutrition Facts panel positioning. US beverage manufacturers prioritize rapid-dissolving grades that withstand pasteurization without viscosity spikes.
- Pharmaceuticals:Excipient-grade material for tablet binders and controlled-release matrices demands tight dextrose equivalent control below 15.
- Bakery:Cost-sensitive bread and pastry applications tolerate broader analytical variance in exchange for moisture retention and shelf-life extension benefits.
Nutraceuticals concentrate value through certification requirements; food and beverage offers the steepest expansion trajectory.
End User:
Procurement scale and technical sophistication separate direct compounder relationships from distributor-mediated transactions.
- Manufacturers:Integrated food and beverage producers with in-house R&D capabilities negotiate multi-year offtake agreements specifying origin documentation and minimum fiber thresholds. Direct relationships displace traditional ingredient distributors in Germany and the United States.
- Food Service:Contract catering and quick-service chains in France and Italy source resistant dextrin through approved supplier panels for menu item fiber claims.
- Retailers:Private-label functional food brands consolidate supplier bases to three approved vendors with integrated quality systems.
- Wholesalers:Regional distributors serve mid-scale processors lacking volume for direct producer negotiations.
Manufacturers absorb the bulk of volume; food service is gaining share fastest.
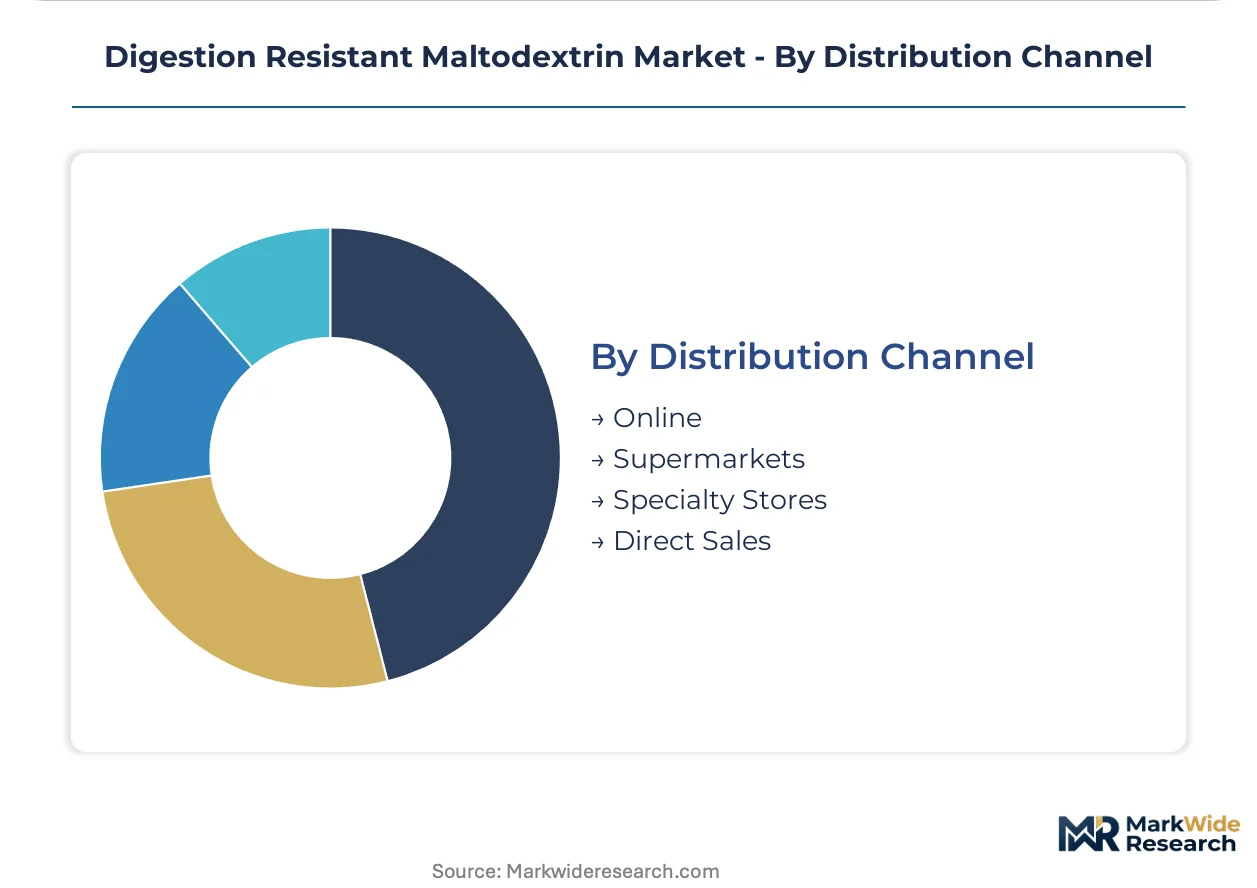
Distribution Channel:
Channel selection reflects order scale, technical support requirements, and geographic proximity to production assets.
- Direct Sales:Multi-year supply agreements between resistant maltodextrin producers and finished goods compounders specify technical service support and joint formulation development. This pattern dominates North American and Western European procurement for beverage and bakery applications.
- Specialty Stores:Ingredient distributors serving small-batch nutraceutical manufacturers in Switzerland and Germany provide smaller minimum order quantities and regulatory documentation packages.
- Online:E-commerce platforms capture spot purchasing from startup functional food brands and research institutions requiring sample quantities.
- Supermarkets:Mass retail channels move consumer-packaged resistant dextrin supplements in limited geographic markets.
Direct sales absorbs the bulk of transaction value; specialty stores are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corn wet milling infrastructure in the United States Midwest and cassava cultivation belts in Southeast Asia anchor geographic supply patterns for resistant maltodextrin feedstocks.
United States
FDA dietary fiber definition updates under Nutrition Facts labeling rules validate resistant dextrin analytical methods for beverage manufacturers. Corn wet milling concentration in Iowa and Illinois creates input cost volatility exposure during planting season disruptions. Chicago-area compounders negotiate multi-year offtake agreements specifying minimum fiber thresholds.
Germany
EFSA Article 13 health claim restrictions compress differentiation space for standard-grade products while clinical nutrition demand concentrates value. Private-label functional food brands consolidate supplier panels to three approved vendors with integrated quality systems. Rhine-Main contract manufacturers require GMP certification for enteral formula compounding.
Japan
The Consumer Affairs Agency's FOSHU system creates regulatory arbitrage opportunities for clinical-grade resistant maltodextrin commanding price premiums. Tokyo and Osaka metropolitan areas drive specifications for clarified, low-viscosity syrups in functional drinks. Verified physiological effects requirements shape substantiation investments.
China
Tapioca starch feedstock pivot from Southeast Asian cassava cultivation enables non-GMO and allergen-free product line extensions. Domestic health-conscious consumption accelerates demand for clean-label fiber fortification. Yangtze River Delta processors adopt precision enzymatic hydrolysis for tighter dextrose equivalent control.
Switzerland
Swissmedic pharmaceutical-grade certification timelines strain working capital for mid-scale processors seeking excipient-grade compliance. Basel and Zurich compounders demand batch-level fiber content verification and dual-laboratory analytical validation. Clinical nutrition contract manufacturing concentrates procurement sophistication.
Digestion Resistant Maltodextrin Market Vendor Landscape
Capacity expansion dominates the current landscape as producers secure feedstock diversification beyond corn-dependent supply chains. The vendor base clusters around three strategic archetypes: integrated starch processors with captive wet milling assets, specialty carbohydrate specialists with enzymatic modification expertise, and regional compounders serving pharmaceutical-grade certification requirements. Backward integration into agricultural sourcing and geographic expansion into Asia-Pacific functional food markets represent the dominant competitive moves reshaping procurement relationships.
Within the integrated processor tier, Roquette Frères and Ingredion Incorporated exemplify divergent feedstock strategies—European pea and wheat starch anchoring versus North American corn wet milling dominance—while Tate & Lyle PLC occupies a position emphasizing specialty carbohydrate R&D intensity. These three entities represent the primary competitive anchors structuring supply continuity negotiations with finished goods manufacturers.
| Leading Market Players |
|---|
| Roquette Frères |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Matsutani Chemical Industry Co., Ltd. |
| Grain Processing Corporation |
| Baolingbao Biology Co., Ltd. |
| Tereos Syral S.A.S. |
| Others |
Supply Flow & Price Mechanics
Clinical-grade certification tiers bifurcate digestion resistant maltodextrin procurement into premium contract manufacturing channels and commodity food-grade spot markets, with pharmaceutical-grade fiber verification commanding threefold supply chain complexity versus standard bakery applications. This divergence concentrates pricing power with GMP-certified producers in Switzerland and Germany while compressing margins for undifferentiated corn-starch-derived volumes in North American bulk trade.
Pricing Analysis
Service bundling separates contract manufacturing partnerships from transactional spot purchasing, with Swiss and German compounders including batch-level fiber verification and dual-laboratory analytical validation within multi-year offtake agreements. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade levels reflects certification intensity and origin documentation requirements. Cost compression in standard food-grade segments is intensifying because tapioca starch feedstock diversification adds handling complexity without commensurate price premiums. Small-scale nutraceutical manufacturers exhibit highest price sensitivity due to minimum order quantity constraints, whereas enteral formula compounders prioritize supply security over unit economics.
Supply Chain Analysis
Return flows and quality failure management are minimal given the food-grade and pharmaceutical-grade nature of resistant maltodextrin, with contamination incidents triggering complete batch destruction rather than refurbishment. Production gravity centers on the United States, France, and Thailand, with corn wet milling in Iowa and Illinois anchoring North American supply while Southeast Asian cassava cultivation feeds tapioca-based diversification. Feedstock dependencies encompass corn starch, wheat starch, and tapioca flour, with enzymatic modification reagents sourced from specialized biochemical suppliers. Single-source vulnerability concentrates in thermostable alpha-amylase enzyme supply, where two producers dominate global availability. Distribution runs through direct producer-compounder relationships in Germany and the United States, displacing traditional ingredient distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where FDA dietary fiber definition updates and EFSA Article 13 health claim substantiation requirements erect regulatory moats favoring incumbent producers with validated analytical capabilities and established clinical dossiers.
For Market Incumbents: Lock in supply continuity through backward integration into Southeast Asian tapioca starch sourcing and captive enzymatic modification capacity, defending against inulin and polydextrose substitution threats in bakery applications by accelerating USP monograph compliance timelines for excipient-grade positioning. For New Entrants and Emerging Players: Precision fermentation-based enzymatic starch modification offers a technology-first entry vector into reduced-energy processing pathways, targeting India's emerging functional food market under FSSAI's evolving fiber fortification standards as the most penetrable geography, with contract manufacturing partnerships providing the lowest-capital go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated starch processors seeking enzymatic modification capabilities and geographic expansion assets, with long-term viability hinging on regulatory arbitrage sustainability across FDA, EFSA, and Japan's FOSHU systems, and the critical inflection signal being harmonization completion between AOAC and ISO resistant dextrin quantification protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tapioca Starch Sourcing | Thailand and Vietnam cassava cultivation expansion reduces corn-dependent supply volatility for non-GMO product lines. |
| GMP Certification Investment | Swissmedic and FDA pharmaceutical-grade compliance opens enteral nutrition contract manufacturing partnerships in Basel and Zurich. |
| Precision Fermentation Technology Adoption | Cell-cultured enzymatic platforms cut thermal processing energy intensity while tightening dextrose equivalent control below 15 DE. |
| Direct Compounder Relationship Development | Multi-year offtake agreements with German private-label functional food brands displace distributor intermediaries and secure volume commitments. |
| Dual-Laboratory Analytical Validation | EFSA's tightened fiber content verification requirements for health claim eligibility necessitate in-house HPLC capability investments. |
Methodological Framework
Independent corroboration across primary interviews with plant managers at starch modification facilities, procurement leads at beverage and bakery manufacturers, regulatory affairs specialists navigating FDA and EFSA fiber definition frameworks, and technical R&D directors at enzymatic processing operations underwrites the qualitative findings, validated against customs and trade data, SEC 10-K filings of integrated processors, AOAC methodology publications, and FOSHU approval databases from Japan's Consumer Affairs Agency, with bottom-up capacity assessments and top-down demand modeling cross-checked for consistency.
Rate-of-change decomposition across the analysis window isolates volume drivers by product type (powder, liquid, granule, syrup), application (nutraceuticals, food and beverage, pharmaceuticals, bakery), and end user (manufacturers, food service, retailers, wholesalers), with CAGRs derived from regression against feedstock cost indices, regulatory approval timelines, and functional food launch pipelines, incorporating enzymatic process yield improvements and pharmaceutical-grade certification penetration as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt FDA fiber definition reinterpretation or EFSA prebiotic claim restriction tightening. Practitioners should monitor AOAC-ISO harmonization progress, Southeast Asian cassava harvest volatility, and precision fermentation technology cost curves for early signals of structural shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
India Food Sweetener Market
Sweeteners
Cassava Syrup Market
Sweeteners
Global Stevia Sugar Blends Market
Sweeteners
Maltitol Market
Sweeteners
Oligofructose Market
Sweeteners
Resistant Maltodextrin Market
Sweeteners
Tagatose Market
Sweeteners
Turbinado Sugar Market
Sweeteners
Sorbitol Market
Sweeteners
Dextrates Market
Sweeteners
Global Cane Molasses Market
Sweeteners
Floral Nectar Market
Sweeteners
Sodium Saccharin Market
Sweeteners
Naturally Derived Sweeteners Market
Sweeteners
Galactose Market
Sweeteners
D-Mannose Market