
 Global Ayurvedic Herbs Market | 2026-2036
Global Ayurvedic Herbs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ayurvedic Herbs Market Foresight
Organic certification under USDA NOP and India Organic standards is bifurcating the competitive landscape into certified export-grade suppliers and domestic commodity traders. Dabur India Ltd. leverages integrated herb cultivation across Rajasthan and Madhya Pradesh to secure raw material consistency. Himalaya Wellness Company anchors its positioning through pharmaceutical-grade extraction facilities that meet WHO-GMP protocols. Patanjali Ayurved Limited competes on volume scale through its sprawling Haridwar manufacturing complex and captive retail network.
Ayurvedic herbs comprise dried or fresh plant materials—roots, leaves, seeds, and flowers—standardized for active marker compounds such as withanolides, curcuminoids, or alkaloids through solvent extraction or supercritical CO2 processing, serving pharmaceutical, nutraceutical, and cosmetic formulation industries. Healthcare applications dominate value capture due to stringent pharmacopeial compliance requirements and practitioner-led prescribing patterns, while dietary supplements represent the fastest-expanding segment as direct-to-consumer brands bypass traditional practitioner channels. Personal care formulations concentrate margin pools in premium dermocosmetic lines that command certification premiums.
FDA Dietary Supplement Current Good Manufacturing Practice regulations, EMA traditional use registration pathways, and India's AYUSH Ministry GMP standards collectively determine market access tiers and product label claims across export destinations. India's BIS and the US Pharmacopeia-National Formulary establish conflicting heavy metal and microbial limits that force dual-testing protocols for cross-border suppliers. Stakeholders must monitor evolving pharmacopeial harmonization negotiations between AYUSH and European pharmacopeias to anticipate compliance cost shifts.
Market Dynamics
Pharmacopeial harmonization pressures between India's AYUSH Ministry and European pharmacopeias are forcing dual-testing protocols that bifurcate supplier tiers into export-grade certified operators and domestic commodity traders.
Growth Catalysts
- EMA Traditional Use Registration Pathways:Germany's pharmaceutical manufacturers now integrate Ayurvedic formulations into complementary medicine portfolios, creating institutional demand channels previously closed to herbal suppliers.
- Supercritical CO2 Extraction Technology:Pharmaceutical-grade extraction facilities meeting WHO-GMP protocols enable standardization of active marker compounds for regulated healthcare applications.
- India's Export Processing Zones:Kerala and Gujarat zones concentrate processing infrastructure and customs clearance efficiencies for cross-border herb shipments.
Market Restraints
- Conflicting Heavy Metal Limits:India's BIS and US Pharmacopeia-National Formulary establish divergent microbial and heavy metal thresholds that force redundant laboratory testing.
- Raw Material Supply Concentration:Integrated herb cultivation clusters in Rajasthan and Madhya Pradesh create geographic dependency risks for large-scale formulators.
- Solvent Extraction Cost Volatility:Petrochemical-derived extraction solvents expose processors to crude oil price swings that compress margin pools in commodity-grade supply tiers.
Strategic Opportunities
- Direct-to-Consumer Channel Bypass:Dietary supplement brands circumvent traditional practitioner networks through e-commerce platforms and subscription models.
- AYUSH Ministry GMP Standardization:India's domestic GMP mandates create certification infrastructure that pre-qualifies suppliers for export markets.
- Cosmeceutical Premium Positioning:Personal care formulations concentrate margin capture in dermocosmetic lines commanding organic certification premiums under USDA NOP standards.
Industry Challenges
- Active Compound Standardization Expertise:Formulation chemists capable of validating withanolide and curcuminoid potency remain scarce across contract manufacturing organizations.
- Pharmacopeial Negotiation Timelines:Ongoing harmonization discussions between AYUSH and European pharmacopeias create regulatory uncertainty that delays product registration investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ayurvedic Herbs Market |
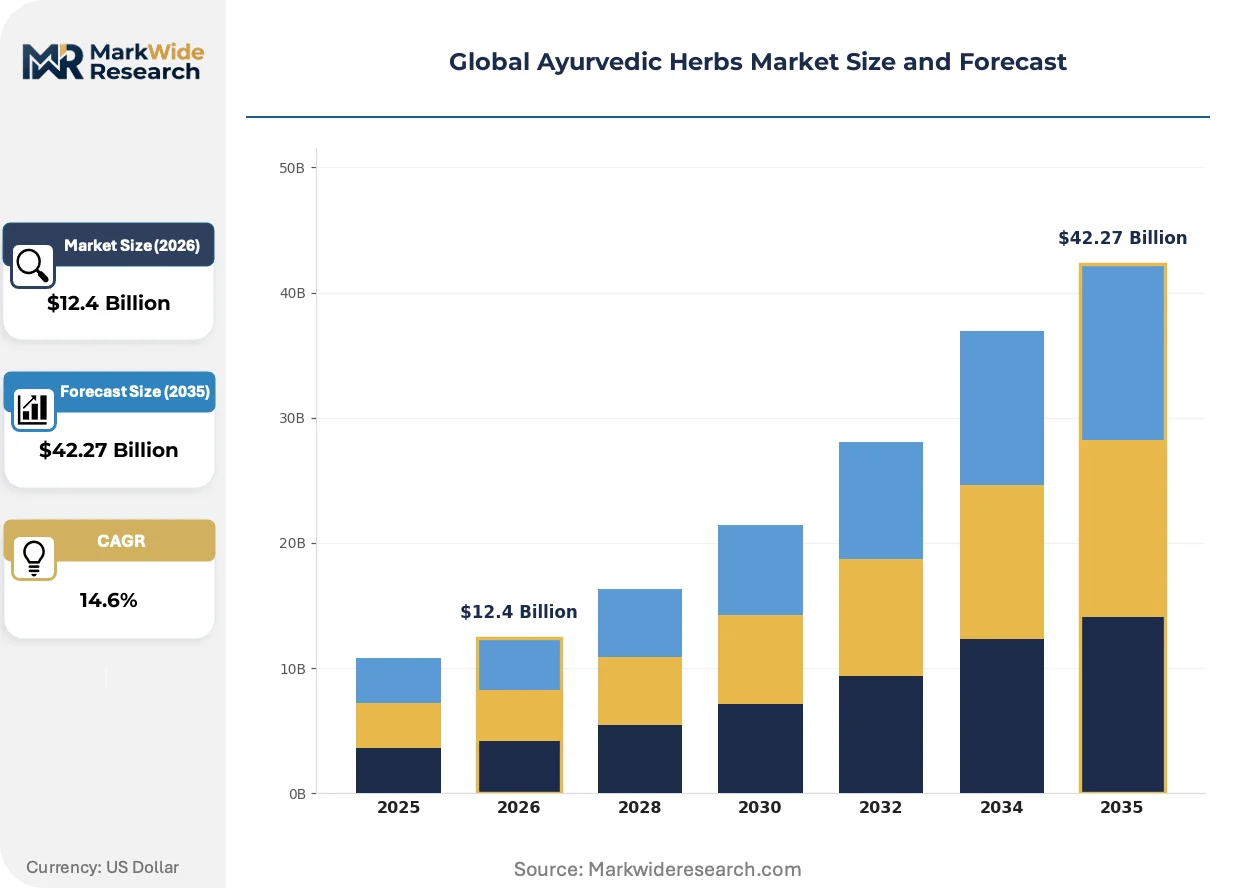
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $42.27 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roots, Leaves, Seeds, Flowers Application: Healthcare, Personal Care, Dietary Supplements, Food & Beverage Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales End User: Individuals, Healthcare Providers, Manufacturers, Researchers |
| Companies Covered | Dabur India Ltd., Patanjali Ayurved Limited, Himalaya Wellness Company, Emami Limited, Baidyanath Ayurved Bhawan Pvt. Ltd., Vicco Laboratories, Kerala Ayurveda Ltd., Kairali Ayurvedic Group, Amrutanjan Health Care Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ayurvedic Herbs Market Shifts & Advancements
Processing technology and certification standards are restructuring competitive advantage away from volume scale toward pharmacopeial compliance and traceability infrastructure.
Supercritical CO2 extraction systems are decomposing the traditional solvent-extraction supply base by enabling pharmaceutical manufacturers to meet WHO-GMP protocols without residual solvent contamination risks. European nutraceutical formulators are adopting these systems at accelerated replacement cycles. The technology is compressing margin structures for commodity-grade solvent processors while concentrating value capture in certified extraction tiers.
REACH registration requirements for botanical substances are compelling EU-based importers to establish full supply chain substance documentation. This regulatory burden is shifting procurement authority toward larger traders with dedicated regulatory affairs capacity. German pharmaceutical distributors now require REACH-compliant dossiers for all Ayurvedic raw material shipments.
Practitioner channel dependence is fragmenting as direct-to-consumer brands build proprietary certification narratives around USDA NOP and India Organic standards. Subscription-based supplement platforms displace traditional Ayurvedic clinic dispensing in urban India and North American diaspora markets. This channel rotation is most pronounced in metropolitan India and California's wellness consumer segments.
Global Ayurvedic Herbs Market Segmentation
Channel dynamics in Ayurvedic herbs bifurcate between practitioner-mediated institutional flows and direct-to-consumer e-commerce platforms. Certification requirements and pharmacopeial compliance create tiered access patterns that reshape which segments reach which buyers.
Product Type:
Roots and leaves dominate pharmaceutical procurement channels due to standardized active compound extraction, while seeds and flowers fragment across cosmetic and food-grade supply tiers.
- Roots:Ashwagandha, turmeric, and licorice roots contain concentrated withanolides and curcuminoids requiring solvent or supercritical CO2 extraction. Demand concentrates in German pharmaceutical manufacturers seeking EMA traditional use registration for standardized extracts.
- Leaves:Tulsi, neem, and brahmi leaves supply dermocosmetic formulators in California and metropolitan India. USDA NOP certification premiums command margin separation from commodity-grade dried leaf traders.
- Seeds:Cumin, fennel, and fenugreek seeds serve FSSAI-regulated food processors and spice exporters from Gujarat processing zones.
- Flowers:Rose, jasmine, and marigold flowers supply fragrance houses and ritual product manufacturers through Kerala export corridors.
By volume, roots lead. By growth pace, leaves are ahead.
Application:
Regulatory stringency separates healthcare applications with pharmacopeial compliance costs from consumer-facing segments where certification narratives substitute for clinical validation.
- Healthcare:WHO-GMP-compliant extracts for practitioner prescribing require validated withanolide and alkaloid standardization. CDSCO and EMA registration pathways concentrate demand among Rajasthan and Madhya Pradesh cultivators with integrated laboratory infrastructure.
- Dietary Supplements:Direct-to-consumer brands bypass traditional Ayurvedic clinic networks through subscription platforms. FDA Dietary Supplement CGMP regulations and California Prop 65 compliance create dual-testing burdens for cross-border suppliers.
- Personal Care:Dermocosmetic lines command organic certification premiums under USDA NOP and India Organic standards. Formulators target premium positioning through REACH-registered botanical dossiers for EU distribution.
- Food & Beverage:FSSAI-mandated heavy metal limits and microbial specifications govern spice and functional ingredient procurement from Gujarat and Kerala processing zones.
Healthcare captures value concentration. Dietary supplements expand most quickly.
Distribution Channel:
Channel selection determines compliance burden intensity, with direct sales and specialty stores absorbing pharmacopeial documentation requirements that supermarkets and pure-play e-commerce platforms circumvent.
- Online Retail:Amazon, iHerb, and direct-brand storefronts displace traditional practitioner dispensing in North American diaspora markets. Subscription models reduce customer acquisition costs for standardized supplement lines.
- Specialty Stores:Ayurvedic clinics and wellness boutiques in Germany and India maintain practitioner-mediated prescribing with integrated diagnostic services. EMA traditional use registration supports institutional credibility.
- Supermarkets:Mass-market spice and personal care placement in Reliance Fresh and DMart chains prioritizes volume scale over certification premiums. FSSAI compliance suffices for domestic Indian retail.
- Direct Sales:Haridwar and Rajasthan-based manufacturers operate captive retail networks with integrated cultivation-to-shelf traceability. Patanjali's sprawling complex exemplifies backward integration into raw material control.
Online retail leads volume expansion. Specialty stores sustain margin concentration.
End User:
User type dictates specification intensity, with manufacturers and healthcare providers demanding validated active compound assays that individual consumers substitute for certification branding.
- Manufacturers:Pharmaceutical and nutraceutical formulators in Germany and India require REACH-compliant dossiers and WHO-GMP extraction protocols. Contract manufacturing organizations face scarcity of formulation chemists capable of withanolide validation.
- Healthcare Providers:Ayurvedic practitioners in Kerala and metropolitan India prescribe standardized extracts with BIS-compliant heavy metal documentation. Institutional prescribing patterns concentrate demand through established clinic networks.
- Individuals:California wellness consumers and urban Indian households purchase through direct-to-consumer platforms prioritizing USDA NOP and India Organic certification narratives over pharmacopeial testing.
- Researchers:Academic institutions and clinical trial sponsors source reference-grade materials with USP-NF or Ph.Eur. compliance for bioavailability and safety studies.
Manufacturers dominate procurement value. Individuals are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The JNPT-London air corridor and Kerala's Cochin Port container terminals underwrite India's export dominance, while Hamburg's pharmaceutical distribution hubs anchor European institutional demand for standardized Ayurvedic extracts.
India
Ministry of AYUSH standardization mandates and CDSCO registration pathways concentrate pharmaceutical-grade extraction in Rajasthan and Madhya Pradesh cultivation belts. FSSAI-regulated heavy metal limits govern spice exports through Gujarat's Mundra Port processing zones. Kerala's Alappuzha cluster specializes in dermocosmetic ingredient shipments to European fragrance houses.
Germany
EMA traditional use registration pathways opened institutional procurement channels for Ayurvedic formulations within complementary medicine portfolios. REACH registration requirements for botanical substances compel full supply chain documentation from Indian exporters. Hamburg's pharmaceutical distributors now require REACH-compliant dossiers for all raw material shipments.
United States
FDA Dietary Supplement CGMP regulations and California Prop 65 compliance create dual-testing burdens for cross-border suppliers. USDA NOP organic certification commands premium positioning in direct-to-consumer channels. Los Angeles and New York metropolitan wellness markets drive subscription-based supplement platform expansion.
United Kingdom
MHRA borderline product classifications determine whether Ayurvedic formulations register as medicines or food supplements. London's wellness retail corridors concentrate practitioner-mediated dispensing alongside direct-brand storefronts. Birmingham's ethnic wholesale networks distribute commodity-grade herbs to South Asian diaspora communities.
Japan
PMDA foreign manufacturer registration requirements limit market access to suppliers with documented GMP compliance. METI-promoted functional food ingredient programs create demand for standardized withanolide extracts. Tokyo's pharmaceutical importers prioritize suppliers with integrated laboratory validation capabilities.
Global Ayurvedic Herbs Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and channel access. The vendor base stratifies into three archetypes: integrated cultivator-processors controlling raw material supply, pharmaceutical-grade extractors meeting WHO-GMP protocols, and volume-scale formulators serving mass retail. Dominant competitive moves include backward integration into captive herb cultivation and technology licensing for supercritical CO2 extraction systems.
Within the integrated cultivation tier, Dabur India Ltd. and Patanjali Ayurved Limited exemplify backward integration strategies spanning Rajasthan and Madhya Pradesh growing regions through Haridwar manufacturing complexes. Himalaya Wellness Company occupies the pharmaceutical-grade extraction position, representing facilities aligned with WHO-GMP protocols for active compound standardization. Kerala Ayurveda Ltd. and Kairali Ayurvedic Group anchor the geographic specialization archetype, with names signaling Kerala-origin supply chain concentration for dermocosmetic and fragrance ingredient exports.
| Leading Market Players |
|---|
| Dabur India Ltd. |
| Patanjali Ayurved Limited |
| Himalaya Wellness Company |
| Emami Limited |
| Baidyanath Ayurved Bhawan Pvt. Ltd. |
| Vicco Laboratories |
| Kerala Ayurveda Ltd. |
| Kairali Ayurvedic Group |
| Amrutanjan Health Care Limited |
| Others |
Supply & Pricing Matrix
Ninety-day inventory cycles for Rajasthan-grown ashwagandha roots concentrate pricing power among integrated cultivator-processors who bypass commodity auction floors. This lead-time compression favors backward-integrated operators in Madhya Pradesh and Haridwar while squeezing margin pools for traders dependent on spot-market procurement.
Pricing Analysis
Volume-discount tiering separates WHO-GMP-certified extractors from domestic commodity traders across three distinct pricing bands. Certification premiums under USDA NOP and India Organic standards command margin separation, while unstandardized dried herb lots trade at commodity benchmarks. Pricing pressure intensifies in solvent-extraction tiers as petrochemical input costs fluctuate. Direct-to-consumer brands exhibit lowest price sensitivity; mass-market spice traders face highest compression.
Supply Chain Analysis
Inventory concentration across Kerala and Gujarat processing zones creates geographic dependency for European fragrance houses and German pharmaceutical distributors. Raw material flows draw from Rajasthan ashwagandha belts, Madhya Pradesh turmeric clusters, and Kerala dermocosmetic cultivars. Single-source vulnerability runs through JNPT-London air corridor capacity constraints. Distribution runs through Hamburg pharmaceutical hubs, Cochin Port container terminals, and direct-brand e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based supplement platforms and certification-as-a-service offerings expand faster than raw herb commodity trading, repositioning recurring revenue as the primary value-capture mechanism.
For Market Incumbents: Consolidate cultivation control through captive herb gardens in Rajasthan and Madhya Pradesh to defend against spot-market volatility. Secure WHO-GMP extraction capacity before EMA traditional use registration deadlines tighten. Channel control through integrated clinic networks remains essential. For New Entrants and Emerging Players: Practitioner education services represent an under-served layer where incumbents lack digital infrastructure. White-space exists in California wellness corridors and metropolitan India for subscription platforms with USDA NOP certification narratives. Go-to-market through Instagram-native wellness influencers bypasses traditional clinic gatekeepers. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate herb trading divisions lacking pharmacopeial compliance infrastructure. Long-term viability hinges on REACH-registered dossier capabilities and supercritical CO2 extraction technology access. Watch EMA-AYUSH harmonization negotiations as regulatory inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Captive herb gardens in Rajasthan and Madhya Pradesh secure raw material consistency against spot-market volatility. |
| Supercritical CO2 Extraction Adoption | Pharmaceutical-grade facilities meeting WHO-GMP protocols enable EMA traditional use registration for standardized extracts. |
| Direct-to-Consumer Platform Launch | Subscription models through Amazon and proprietary storefronts displace traditional Ayurvedic clinic dispensing networks. |
| REACH Registration Compliance | Full supply chain substance documentation satisfies Hamburg pharmaceutical distributor requirements for EU market access. |
| Organic Certification Investment | USDA NOP and India Organic standards command margin premiums in California and metropolitan India wellness segments. |
Research Methodology
A spread of perspectives from Ayurvedic practitioners, CDSCO regulatory affairs leads, extraction facility plant managers, and direct-to-consumer brand operators converged on the working assumptions. Primary fieldwork combined with secondary validation from EMA traditional use registration databases, FSSAI compliance filings, and AYUSH Ministry GMP standards. Bottom-up cultivation volume estimates and top-down pharmaceutical procurement value triangulation anchored the analytical framework.
Segmentation dimensions modeled include product type across roots, leaves, seeds, and flowers; application tier spanning healthcare, dietary supplements, personal care, and food and beverage; and distribution channel structure through online retail, specialty stores, supermarkets, and direct sales. CAGRs were derived from growth rate convergence across these segments. Industry-specific forecast inputs incorporated supercritical CO2 extraction technology adoption curves and REACH registration timeline assumptions.
Forecasts assume regulatory continuity in EMA traditional use pathways and AYUSH GMP mandates; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Specialty Meat Ingredients Market
Specialty Ingredients
Specialty Mint Oils Market
Specialty Ingredients
Grape Seed Extract in Pet Food Application Market
Specialty Ingredients
Gentian Market
Specialty Ingredients
Aromatherapy Carrier Oil Market
Specialty Ingredients
Global Sea Buckthorn Oil Market
Specialty Ingredients
Middle East and Africa Specialty Food Ingredients Market
Specialty Ingredients
Evening Primrose Oil Market
Specialty Ingredients
Aromatherapy Oils Market
Specialty Ingredients
North America Grape Seed Extract Market
Specialty Ingredients
Green Sic Market
Specialty Ingredients
Vetiver Oil Market
Specialty Ingredients
Specialty Shortenings Market
Specialty Ingredients
Dessert Variegates Market
Specialty Ingredients
Customized Nutrient Premixes Market
Specialty Ingredients
Global Pet Food Flavors Market