
 Abies Alba (Fir) Leaf Oil Market | 2026-2036
Abies Alba (Fir) Leaf Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Abies Alba (Fir) Leaf Oil Market Outlook
Synthetic fragrance compounds is decoupling from premium personal care formulations as botanical alternatives gain cost parity at scale. Robertet Group leverages generational expertise in Grasse-based extraction to sustain supply security for luxury fragrance houses. Young Living Essential Oils anchors North American distribution through vertically controlled sourcing networks. Berjé Inc. competes on technical documentation depth, supplying batch-specific chromatographic profiles that satisfy pharmaceutical-grade procurement protocols.
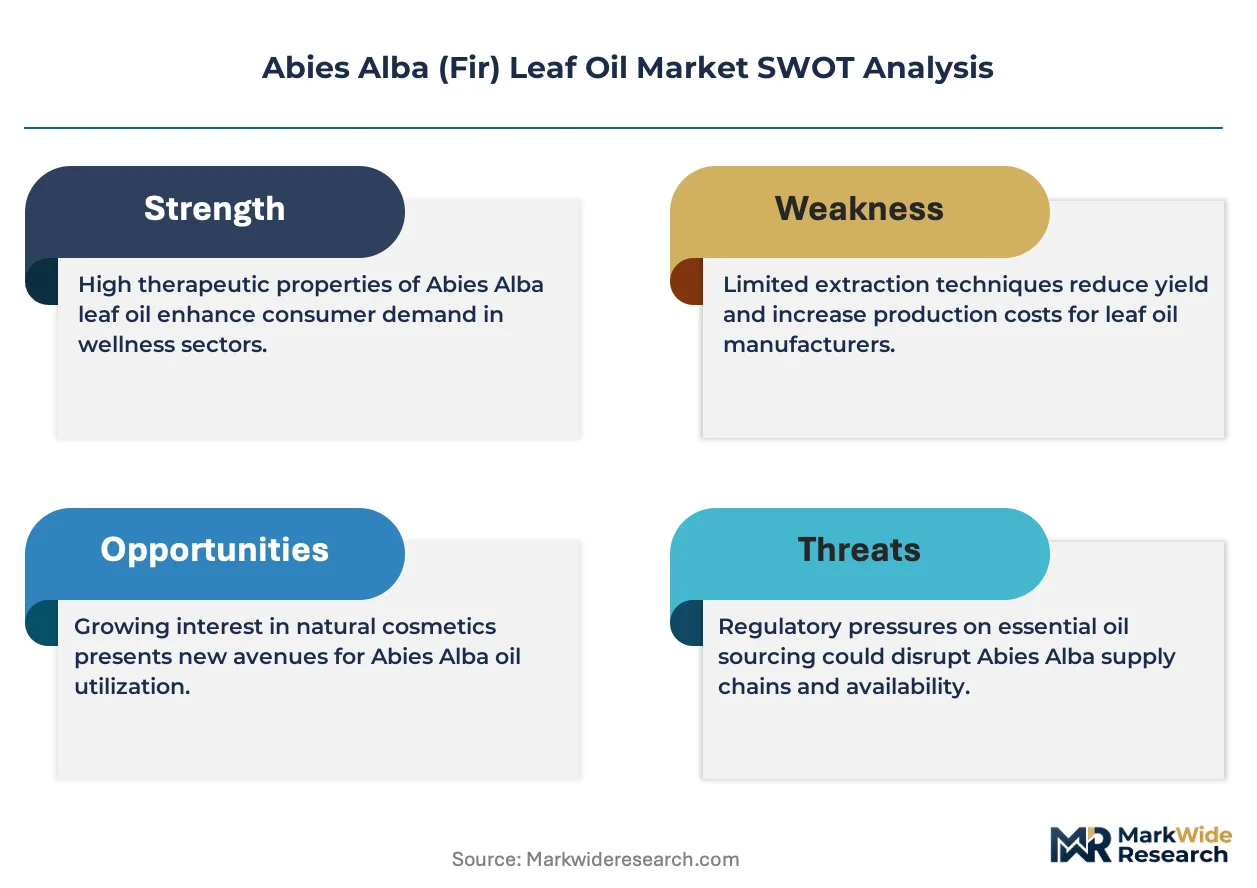
Abies Alba (Fir) Leaf Oil constitutes a volatile essential oil derived from the needle foliage of the European silver fir, typically containing 15-35% bornyl acetate alongside camphene and alpha-pinene fractions, recovered through steam distillation of freshly harvested spring growth for use in perfumery, aromatherapy, and topical therapeutic preparations. Steam distillation retains dominance as the extraction backbone due to capital efficiency and ISO-standardized output consistency, though CO2 extraction is capturing supercritical-grade demand in pharmaceutical applications where residual solvent thresholds approach zero. Essential oil commands the primary value pool given its direct incorporation into high-concentration fragrance formulations, while aromatherapy oil represents the fastest-expanding demand vector as wellness retail channels professionalize quality verification.
EU REACH registration requirements and ECHA substance evaluation protocols are elevating documentation burdens for non-European suppliers, effectively filtering market access toward enterprises with dedicated regulatory affairs capacity. FDA oversight of cosmetic ingredient safety through the Modernization of Cosmetics Regulation Act is extending traceability expectations to imported botanical inputs, compelling upstream suppliers to adopt lot-level digital chain-of-custody systems. Stakeholders must now weigh organic certification premiums against the capital intensity of compliant distillation infrastructure as compliance costs reshape supplier viability thresholds.
Market Dynamics
EU REACH registration requirements are filtering supplier access toward enterprises with dedicated regulatory affairs capacity, compressing the viable vendor base while elevating documentation premiums for compliant botanical inputs.
Growth Catalysts
- EU Green Deal bio-based mandates:France and Germany deploy fir leaf oil in premium skincare lines as synthetic fragrance alternatives face tightening ECHA scrutiny. This policy trajectory accelerates botanical substitution in personal care formulations.
- Alpine sourcing corridor expansion:Certified organic distillation capacity is scaling across Bulgaria, Romania, and southern Poland, securing feedstock volumes for fragrance house procurement.
- Steam distillation standardization:ISO-standardized output consistency enables pharmaceutical-grade batch replication, opening therapeutic applications beyond traditional perfumery.
Market Restraints
- Spring harvest window rigidity:Fresh needle foliage recovery peaks during limited seasonal windows, constraining annual distillation throughput regardless of capital deployment.
- Input cost volatility:Wild-harvested feedstock availability fluctuates with Alpine climate patterns, compressing margin predictability for non-vertically integrated processors.
- Residual solvent thresholds:Pharmaceutical applications demand CO2 extraction where steam distillation cannot achieve near-zero contamination, fragmenting capital allocation across incompatible process technologies.
Strategic Opportunities
- North American wellness retail professionalization:Quality verification infrastructure in aromatherapy channels creates premium positioning for documented supply chains.
- Modernization of Cosmetics Regulation Act traceability:FDA lot-level digital chain-of-custody requirements favor early-adopter suppliers with embedded documentation systems.
- Grasse extraction expertise convergence:Generational knowledge clusters in French fragrance chemistry enable supercritical-grade process hybridization for high-value therapeutic segments.
Industry Challenges
- Regulatory affairs talent scarcity:Dedicated ECHA submission capacity concentrates among established European processors, raising competitive barriers for new market entrants.
- Organic certification timeline compression:Three-year conversion protocols for wild-harvested Alpine stands delay revenue recognition for distillation infrastructure investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Abies Alba (Fir) Leaf Oil Market |
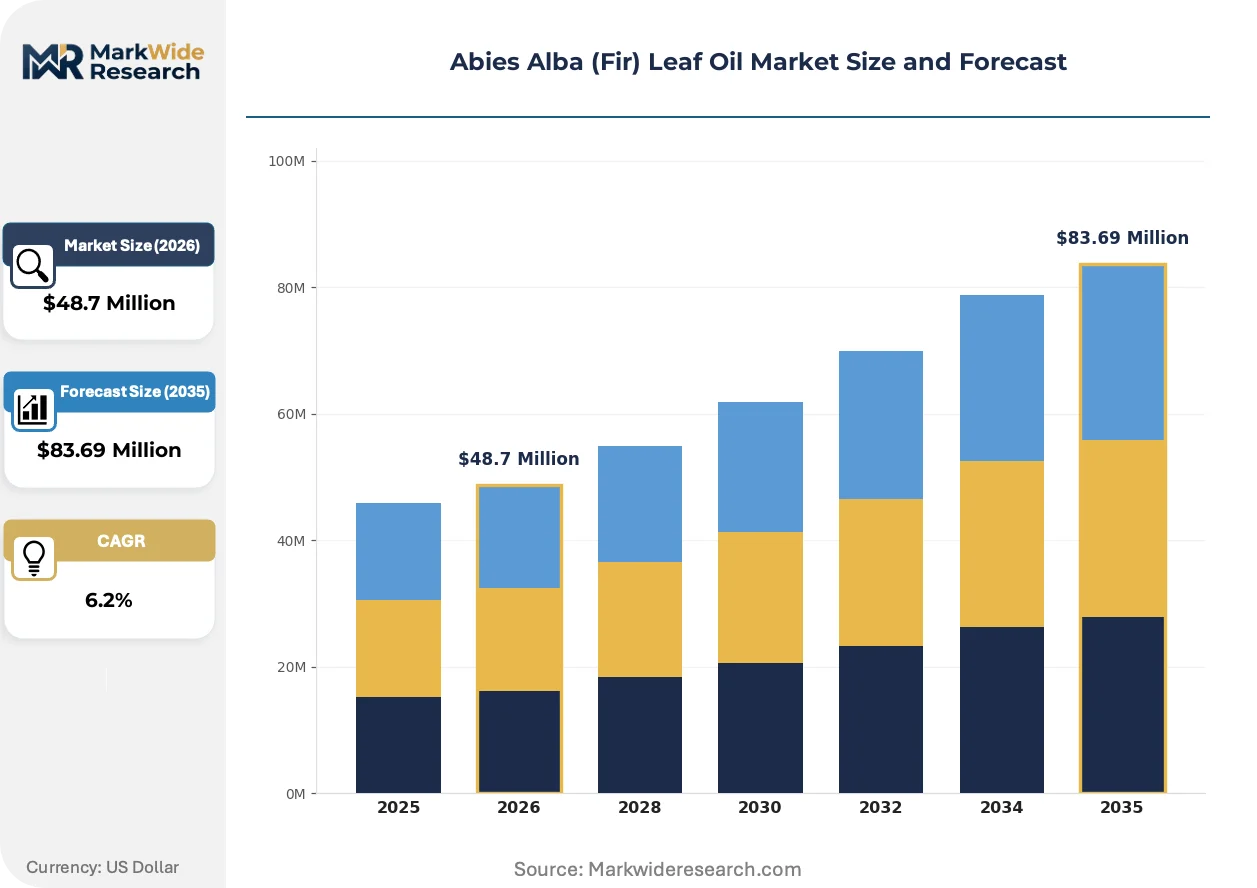
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $83.69 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oil, Carrier Oil, Aromatherapy Oil, Fragrance Oil Extraction Method: Steam Distillation, Cold Press Extraction, Solvent Extraction, CO2 Extraction End User: Cosmetics Industry, Pharmaceutical Industry, Food & Beverage, Household Products Packaging Type: Glass Bottles, Plastic Bottles, Drums, Canisters |
| Companies Covered | Young Living Essential Oils, doTERRA International, Sydney Essential Oils, Reincke und Fichtner GmbH, Eden Botanicals, Florihana Distillerie, Albert Vieille, Berjé Inc., Robertet Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Abies Alba (Fir) Leaf Oil Market Strategic Shifts
Extraction technology diversification and procurement documentation digitization are redrawing competitive boundaries between fragrance, pharmaceutical, and wellness end-uses.
Supercritical CO2 extraction systems are decentralizing pharmaceutical-grade supply away from traditional steam distillation hubs. Aromatherapy oil processors in wellness retail channels adopt CO2 units to meet residual solvent thresholds approaching zero. This capability diffusion fragments the historical concentration of high-purity output among Grasse-based specialists.
REACH substance evaluation protocols are elevating batch-specific chromatographic documentation from competitive advantage to market access prerequisite. ECHA compliance costs now filter supplier viability toward enterprises with in-house analytical chemistry capacity. Fragrance houses respond by consolidating procurement relationships with technically documented upstream partners.
Wellness retail channels now demand lot-level digital chain-of-custody verification as standard procurement protocol. Boutique aromatherapy distributors displace traditional wholesale intermediaries through embedded quality transparency. This channel restructuring concentrates in North American markets where FDA cosmetic ingredient traceability expectations extend to imported botanical inputs.
Abies Alba (Fir) Leaf Oil Market Segmentation
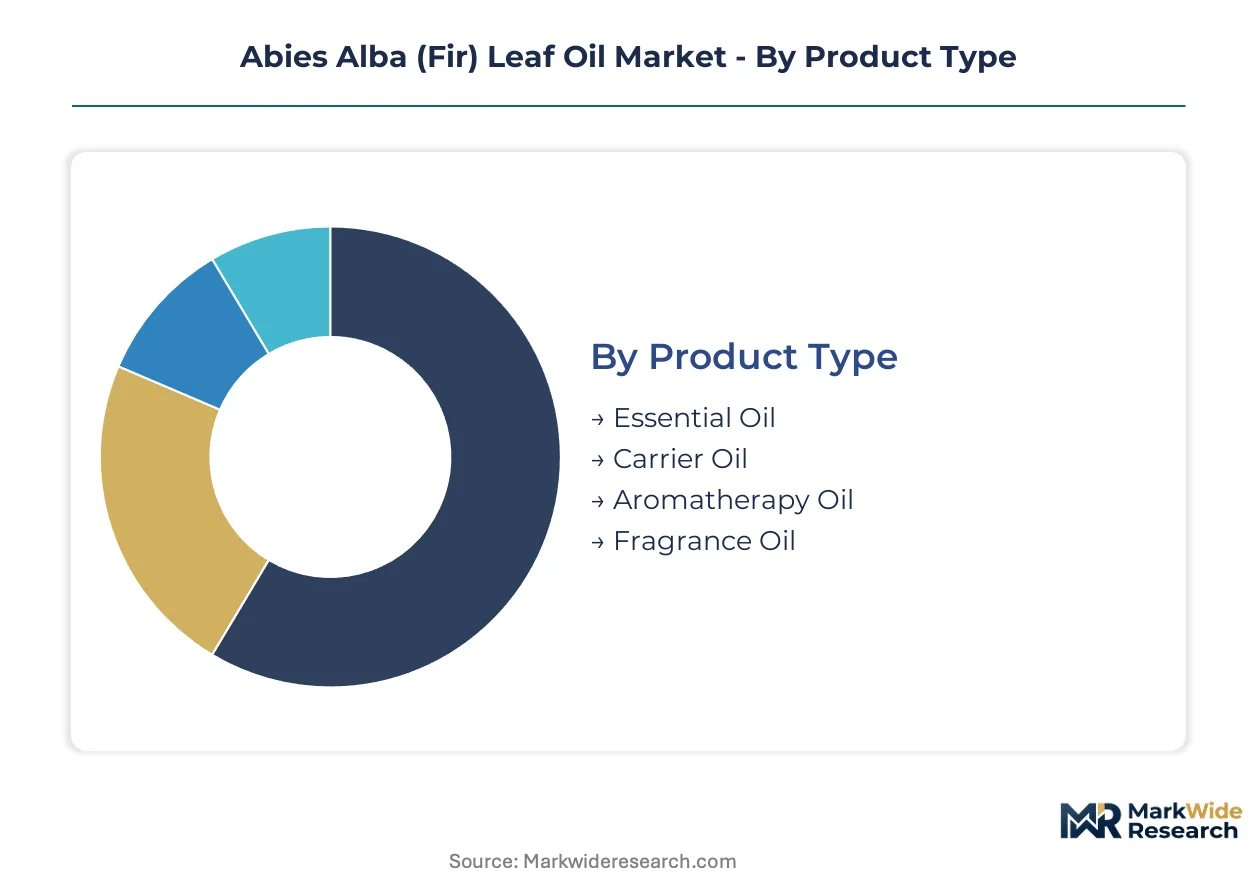
Abies Alba leaf oil segmentation reflects divergent purity specifications and regulatory thresholds across fragrance, therapeutic, and wellness channels. Distinct extraction technologies and packaging protocols create tiered value capture opportunities that reshape supplier positioning.
Product Type:
Upgrade cycles from commodity-grade oils to certified therapeutic and pharmaceutical grades are accelerating as ECHA documentation requirements harden procurement standards.
- Essential Oil:Concentrated volatile oil containing 15-35% bornyl acetate alongside camphene and alpha-pinene fractions, recovered through steam distillation. Demand concentrates in Grasse-based fragrance houses and German pharmaceutical formulators seeking ISO-standardized batch consistency for perfumery and topical therapeutic preparations.
- Aromatherapy Oil:Wellness-grade formulation with documented chromatographic profiles for retail channel professionalization. North American wellness retail networks and French aromatherapy distributors drive the steepest expansion trajectory as quality verification infrastructure matures.
- Carrier Oil:Dilution base for topical application blending, typically incorporating jojoba or sweet almond substrates.
- Fragrance Oil:Synthetic-admixed compound for cost-sensitive personal care and household product applications.
Volume placements concentrate in Essential Oil; the faster expansion belongs to Aromatherapy Oil.
Extraction Method:
Cost tier stratification separates capital-intensive supercritical systems from standardized steam infrastructure, fragmenting supplier viability thresholds.
- Steam Distillation:Dominant extraction backbone leveraging ISO-standardized output consistency and capital efficiency. Bulgarian and Romanian processors anchor volume production for fragrance house procurement, though residual solvent thresholds exclude pharmaceutical-grade applications.
- CO2 Extraction:Supercritical-grade technology achieving near-zero contamination for therapeutic and pharmaceutical segments. Alpine corridor investments in southern Poland and German Black Forest facilities concentrate high-purity capacity as EMA documentation requirements tighten.
- Cold Press Extraction:Mechanical recovery preserving heat-sensitive terpene profiles for premium cosmetic applications.
- Solvent Extraction:Lower-cost alternative for fragrance oil production with higher residual solvent tolerance.
Capital deployment concentrates in Steam Distillation; the steepest margin expansion attaches to CO2 Extraction.
End User:
Application-specific purity mandates from cosmetics and pharmaceutical regulators are decoupling procurement relationships from historical commodity supply channels.
- Cosmetics Industry:Premium skincare and personal care formulations incorporating fir leaf oil as EU Green Deal bio-based mandates displace synthetic fragrance alternatives. French and German formulators lead botanical substitution as REACH substance evaluation protocols elevate documentation burdens.
- Pharmaceutical Industry:Topical therapeutic preparations requiring batch-specific chromatographic profiles and lot-level traceability. FDA Modernization of Cosmetics Regulation Act traceability expectations and EMA quality guidelines compress viable supplier bases toward technically documented upstream partners.
- Food & Beverage:Limited flavoring applications constrained by strict IFRA and FEMA usage thresholds.
- Household Products:Mass-market air care and cleaning formulations prioritizing cost over certified organic provenance.
Procurement volume concentrates in Cosmetics Industry; the fastest share gain belongs to Pharmaceutical Industry.
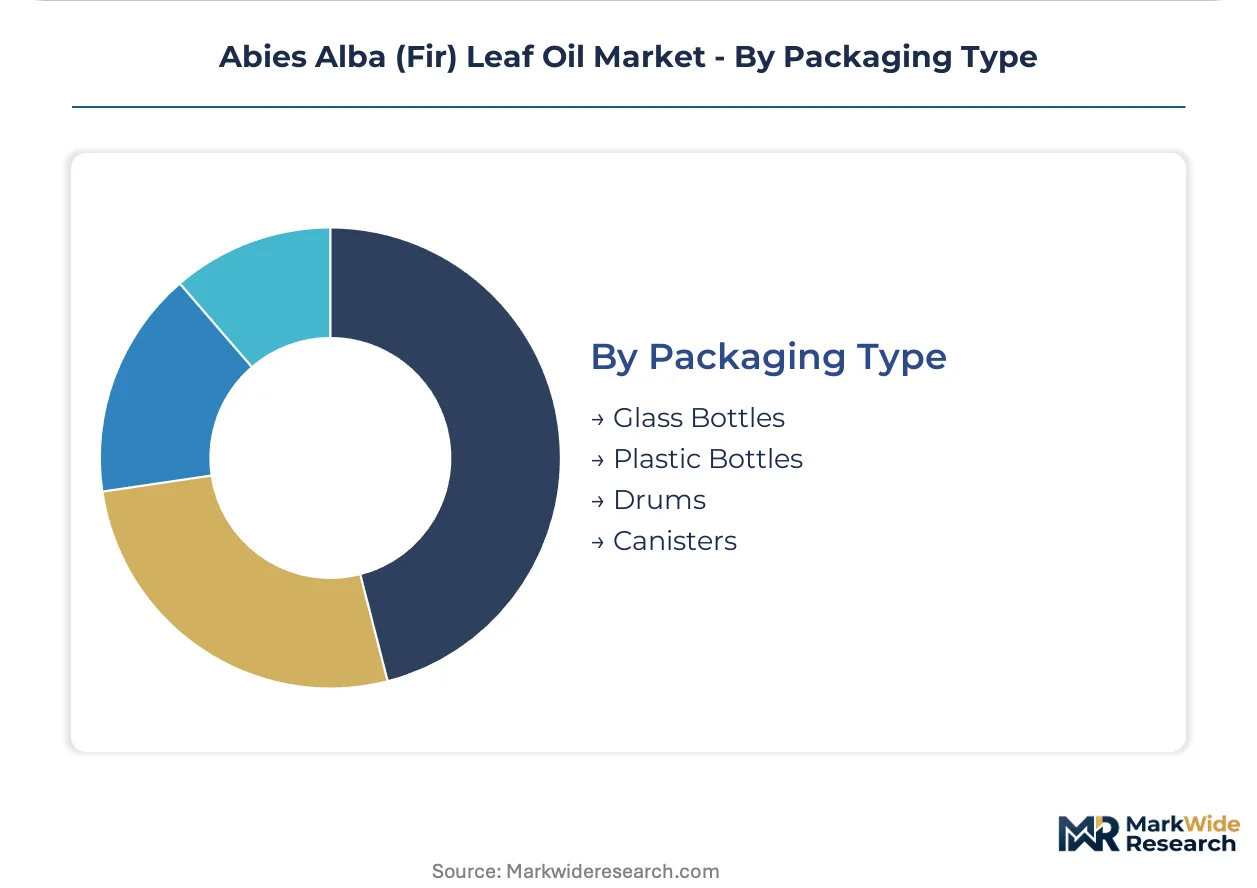
Packaging Type:
Customer type differentiation separates artisan wellness distributors from industrial fragrance houses, dictating unit economics and channel strategy.
- Glass Bottles:Primary containment for aromatherapy retail and premium cosmetic applications requiring UV protection and chemical stability. Boutique North American wellness distributors and French pharmacy channels mandate amber or cobalt glass with tamper-evident closures.
- Drums:Bulk intermediate packaging for fragrance house and pharmaceutical manufacturer procurement. Grasse-based extraction specialists and German compounders standardize on stainless-steel lined drums for volume shipments.
- Plastic Bottles:Cost-optimized containment for household product and economy fragrance oil segments.
- Canisters:Aerosol-compatible packaging for air care and household spray applications.
Shipment value concentrates in Drums; the fastest volume expansion belongs to Glass Bottles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France concentrates premium fragrance house demand through Grasse-based extraction specialists, while Germany anchors pharmaceutical-grade procurement with Black Forest distillation infrastructure. Alpine sourcing corridors in Bulgaria and Romania feed volume production, with southern Poland emerging as a certified organic processing hub.
France
Grasse-based fragrance houses drive premium essential oil consumption for luxury perfumery formulations. EU REACH substance evaluation protocols elevate documentation burdens, filtering supplier access toward technically documented partners. The Provence-Alpes-Côte d'Azur cluster concentrates generational extraction expertise and supercritical-grade process hybridization capacity.
Germany
Pharmaceutical formulators in Baden-Württemberg and Bavaria procure batch-specific chromatographic profiles for topical therapeutic preparations. The Modernization of Cosmetics Regulation Act extends FDA traceability expectations to imported botanical inputs, compelling lot-level digital chain-of-custody adoption. Black Forest facilities anchor high-purity CO2 extraction investments as EMA documentation requirements tighten.
Bulgaria
Certified organic wild-harvesting operations in the Rhodope and Balkan mountain ranges supply fragrance house procurement volumes. EU Green Deal bio-based mandates accelerate botanical substitution in personal care formulations, expanding distillation infrastructure investment. Rose Valley processors leverage seasonal labor pools to manage spring harvest window constraints.
Romania
Alpine corridor expansion in the Carpathian foothills scales certified organic distillation capacity for export-oriented production. Spring harvest rigidity limits annual throughput regardless of capital deployment, compressing margin predictability for non-vertically integrated processors. Transylvanian processing clusters specialize in ISO-standardized steam distillation output for Grasse-based fragrance houses.
Poland
Southern Polish facilities in the Beskid and Tatra foothills concentrate emerging supercritical-grade capacity for pharmaceutical applications. ECHA compliance costs reshape supplier viability thresholds, favoring enterprises with dedicated regulatory affairs capacity. The Małopolska region anchors investments achieving near-zero residual solvent thresholds for therapeutic-grade output.
Abies Alba (Fir) Leaf Oil Market Competitive Environment
Capacity expansion dominates the current landscape as Alpine corridor processors scale certified organic distillation infrastructure. The vendor base stratifies across three tiers: Grasse-based extraction specialists with generational expertise, North American wellness distributors with vertically controlled sourcing networks, and Alpine corridor processors competing on volume scale. Two archetypes define positioning: documentation-heavy European incumbents serving pharmaceutical and fragrance houses, and wellness-channel specialists emphasizing quality transparency. Competitive moves concentrate on geographic expansion into certified organic sourcing corridors and portfolio diversification toward aromatherapy-grade formulations.
Within the European documentation tier, Robertet Group and Berjé Inc. exemplify archetypes differentiated by technical depth and regulatory compliance capacity. Robertet Group anchors generational expertise in Grasse-based extraction, while Berjé Inc. occupies a position emphasizing batch-specific chromatographic profiles. Young Living Essential Oils represents the North American wellness-channel archetype with vertically controlled sourcing networks. These three companies illustrate the competitive divergence between pharmaceutical-grade documentation requirements and wellness retail quality verification infrastructure.
| Leading Market Players |
|---|
| Young Living Essential Oils |
| doTERRA International |
| Sydney Essential Oils |
| Reincke und Fichtner GmbH |
| Eden Botanicals |
| Florihana Distillerie |
| Albert Vieille |
| Berjé Inc. |
| Robertet Group |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap distillers in the Alpine corridor anchor supply discipline through generational land tenure, translating seasonal harvest constraints into premium-tier pricing power while compressing margins for non-vertically integrated processors lacking captive needle sourcing.
Pricing Analysis
Volume placements favor standardized steam-distilled essential oil for fragrance house procurement, while margin capture concentrates in supercritical CO2 grades for pharmaceutical applications. Certification grade and extraction technology drive price differentiation, with EU organic and ECHA REACH documentation commanding substantial premiums over commodity steam-distilled output. Pricing pressure stems from spring harvest window rigidity limiting annual throughput regardless of capital deployment. Contract cosmetics manufacturers exhibit highest price sensitivity, whereas Grasse-based fragrance houses prioritize batch consistency and documentation depth over unit cost.
Supply Chain Analysis
Fresh needle foliage supply rests on wild-harvested stands across Bulgaria, Romania, and southern Poland, with distillation capacity clustering in Rhodope, Carpathian, and Beskid foothill facilities. Bornyl acetate concentration, camphene fractions, and alpha-pinene profiles constitute critical quality-determining inputs. Single-source vulnerability runs through Alpine climate-dependent harvest volumes that fluctuate with temperature and precipitation patterns. Distribution runs through stainless-steel lined drums for fragrance house bulk procurement, while glass bottle channels serve boutique aromatherapy retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steam distillation standardization is yielding to supercritical CO2 extraction in pharmaceutical-grade segments, as near-zero residual solvent thresholds displace legacy thermal recovery methods across therapeutic applications.
For Market Incumbents: Deploy documentation-heavy regulatory affairs capacity as a competitive moat. Consolidate procurement relationships with Bulgarian and Romanian processors facing ECHA compliance cost barriers. Expand captive organic certification coverage across Alpine stands to secure three-year conversion timelines before competitor capital deployment. For New Entrants and Emerging Players: Launch via direct-to-wellness-retail distribution bypassing traditional wholesale intermediaries. Target North American aromatherapy channels where FDA Modernization of Cosmetics Regulation Act traceability requirements favor documented supply chain newcomers. Emphasize lot-level digital chain-of-custody verification as standard procurement protocol. For Investors and Strategic Acquirers: Distressed-cycle entries favor non-vertically integrated Romanian processors facing working capital pressure from spring harvest timing mismatches. Long-term viability hinges on backward integration into certified organic land tenure or supercritical extraction technology deployment. Watch EMA documentation requirement tightening as the inflection signal for pharmaceutical-grade capacity scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Near-zero residual solvent thresholds in EMA guidelines favor pharmaceutical-grade output capture. |
| Backward Integration into Certified Organic Stands | Three-year conversion protocols in Bulgaria and Romania secure feedstock control before competitor entry. |
| Long-term Supply Agreement with Grasse Fragrance Houses | Generational extraction expertise clusters anchor premium pricing through batch-specific chromatographic documentation. |
| Digital Chain-of-Custody System Deployment | FDA lot-level traceability expectations compress viable supplier bases toward early documentation adopters. |
| Joint Venture with Alpine Harvest Cooperatives | Seasonal labor pooling in Rose Valley and Transylvanian clusters mitigates spring harvest window constraints. |
Study Parameters
Multi-period observation of distillation capacity investments, organic certification timelines, and ECHA registration progressions anchored the trend analysis, supplemented by interviews with essential oil extraction specialists, fragrance house procurement directors, pharmaceutical formulator regulatory affairs leads, and Alpine harvest cooperative managers. Secondary validation drew from ECHA substance evaluation databases, EU organic certification registries, Bulgarian and Romanian customs export records, and FDA cosmetic ingredient safety guidance documents. Bottom-up processor capacity modeling triangulated against top-down fragrance and pharmaceutical end-use demand estimates.
Input-output matrices mapped extraction technology deployment against end-use purity requirements across the projection horizon, with segmentation dimensions spanning product grade tier, extraction method, end-use industry, and regional production hub. CAGRs were derived from installed capacity run-rates and penetration assumptions for supercritical-grade therapeutic applications. Forecast inputs incorporated Alpine climate pattern variability effects on wild-harvested feedstock availability and EMA documentation requirement evolution timelines.
Regulatory enforcement intensity shifts, Alpine climate volatility episodes, and supercritical equipment supply bottlenecks are the dominant revision risks to modeled outputs. Forecasts embed assumptions regarding ECHA REACH compliance cost trajectories and FDA traceability system adoption rates. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Mangosteen Market
Specialty Ingredients
South America Specialty Food Ingredient Market
Specialty Ingredients
Green Sic Market
Specialty Ingredients
North America Specialty Food Ingredient Market
Specialty Ingredients
Middle East and Africa Customized Premixes Market
Specialty Ingredients
Mango Butter Market
Specialty Ingredients
Asia-Pacific Specialty Food Ingredient Market
Specialty Ingredients
Agarwood Essential Oil Market
Specialty Ingredients
Food Decorations and Inclusions Market
Specialty Ingredients
Cupuacu Butter Market
Specialty Ingredients
Tea-Based Skin Care Products Market
Specialty Ingredients
Aromatherapy Carrier Oil Market
Specialty Ingredients
Floral Water Market
Specialty Ingredients
Dessert Variegates Market
Specialty Ingredients
Sun-Care Natural Oils Market
Specialty Ingredients
Vetiver Oil Market