
 North America Grape Seed Extract Market | 2026-2036
North America Grape Seed Extract Market Size, Share, and Industry Trends Forecast 2026-2036
North America Grape Seed Extract Market Analytics
DSHEA enforcement is restructuring the cost-of-entry calculus for new grape seed extract suppliers entering the North American nutraceutical channel. Botanic Innovations LLC leverages its cold-press extraction infrastructure to sustain premium positioning in the standardized extract segment. Polyphenolics anchors supply relationships with California wine producers, securing consistent grape pomace feedstock. Indena S.p.A. competes through pharmaceutical-grade certification that meets USP monograph requirements.
Grape seed extract is a polyphenol-rich concentrate derived from Vitis vinifera seeds, typically standardized to 95% proanthocyanidins content and manufactured through aqueous ethanol extraction followed by spray-drying. Its primary commercial purpose centers on delivering antioxidant functionality for dietary supplements, functional foods, and cosmeceutical formulations. The nutraceuticals application segment dominates volume absorption, while the cosmetics application segment commands higher margin pools due to clean-label positioning requirements. Powder format leads production throughput, though capsules generate superior per-unit economics through direct-to-consumer channel premiums.
The FDA, USDA Organic certification, and USP standards collectively govern ingredient purity, label claims, and organic positioning across the North American supply base. These frameworks elevate testing burdens but simultaneously protect incumbent suppliers with established quality management systems. Stakeholders must monitor evolving NDI guidance enforcement patterns and organic supply chain integrity audits to anticipate competitive access shifts.
Market Dynamics
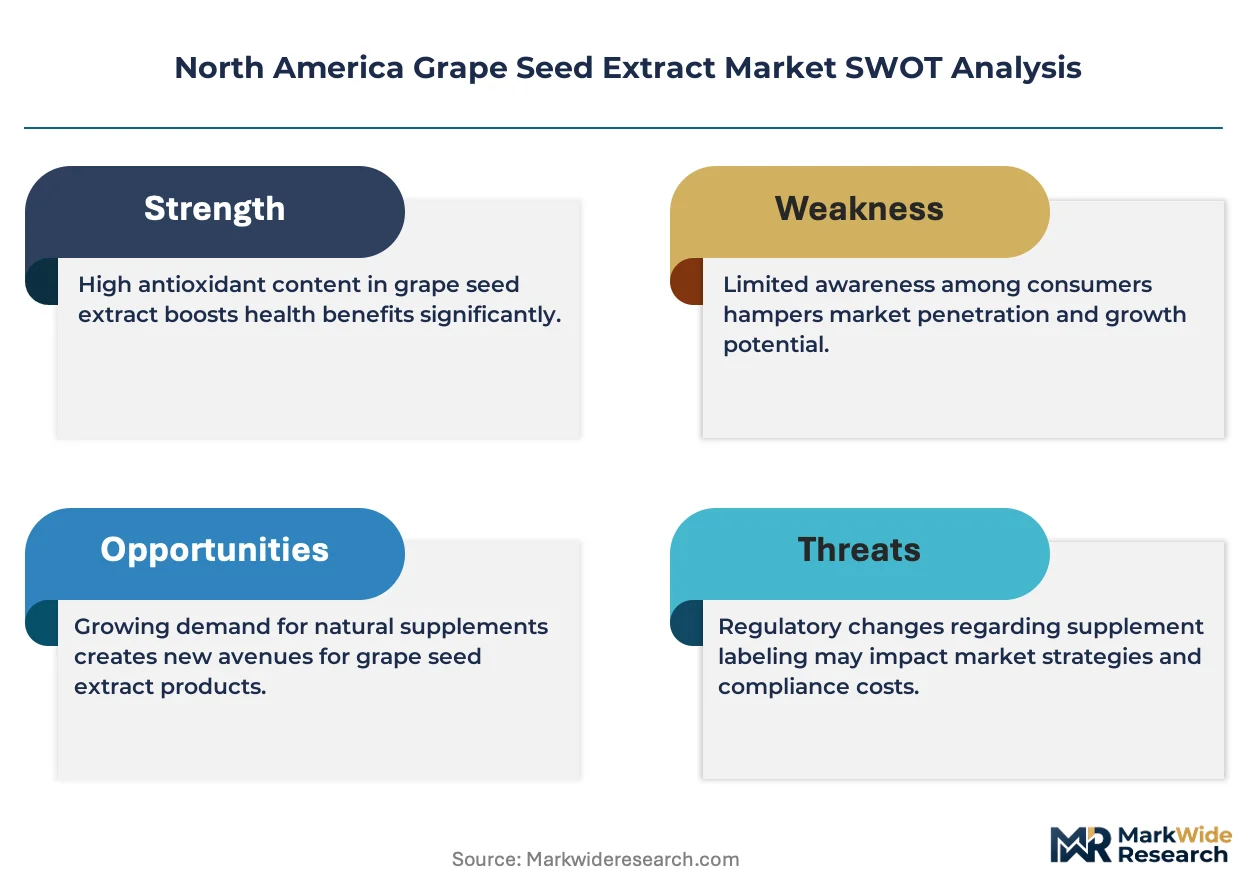
FDA New Dietary Ingredient notification requirements are restructuring supplier qualification protocols across the North American nutraceutical channel, elevating compliance burdens that favor incumbent extract processors with established quality management systems.
Growth Catalysts
- Antioxidant supplement demand:Nutraceutical manufacturers in the United States and Canada are expanding procurement of grape seed extract for cardiovascular and anti-aging formulations, absorbing volume from California's Central Valley processing clusters.
- DSHEA framework maturation:The Dietary Supplement Health and Education Act enforcement patterns are creating predictable compliance pathways that reduce regulatory uncertainty for qualified suppliers.
- Wine region feedstock proximity:California's grape pomace availability supports extract processing concentration, reducing raw material logistics costs for domestic manufacturers.
Market Restraints
- Organic supply chain integrity audits:USDA Organic certification requirements impose traceability burdens that constrain small-scale processors lacking integrated vineyard relationships.
- Input cost volatility:Grape pomace pricing fluctuates with vintage yields and winery contract terms, compressing margins for non-vertically integrated extractors.
- USP monograph compliance:United States Pharmacopeia standardization testing adds fixed analytical costs that disadvantage new market entrants.
Strategic Opportunities
- Cosmeceutical clean-label positioning:Cosmetics application segments command premium margin pools through antioxidant serum and topical formulations targeting skin health claims.
- Direct-to-consumer capsule channels:E-commerce platforms enable extract brands to bypass wholesale nutraceutical distributors, capturing superior per-unit economics.
- Canadian market underpenetration:Health Canada Natural Health Product regulations create a parallel compliance pathway for US-qualified suppliers to expand northward.
Industry Challenges
- NDI notification timelines:FDA New Dietary Ingredient pre-market submissions require 75-day review periods that delay product launches and freeze working capital.
- Analytical chemist scarcity:Proanthocyanidin content verification and adulterant detection demand specialized phytochemical expertise concentrated among legacy suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Grape Seed Extract Market |
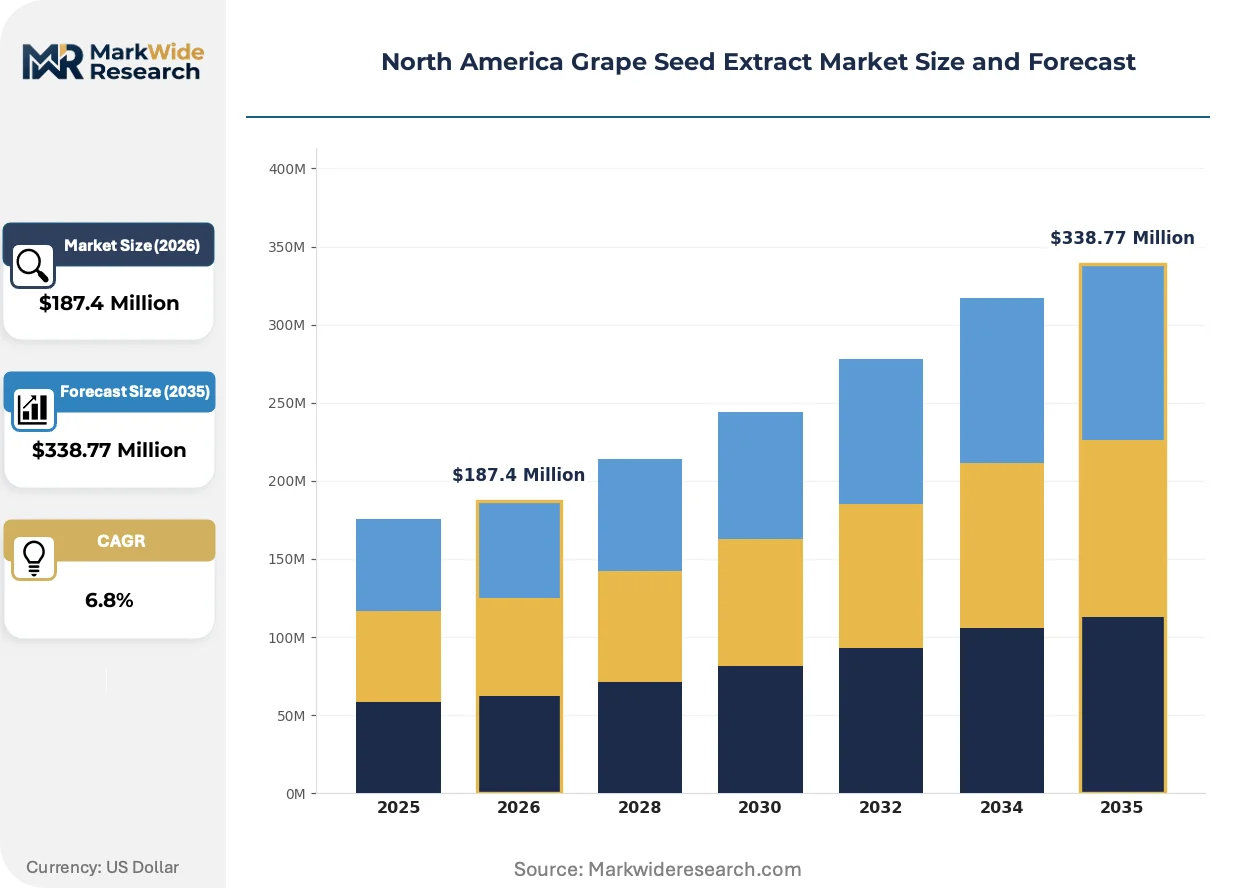
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standardized Extract, Powder, Liquid, Capsules Application: Nutraceuticals, Cosmetics, Pharmaceuticals, Food & Beverages Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies End User: Consumers, Manufacturers, Healthcare Providers, Researchers |
| Companies Covered | Botanic Innovations LLC, Polyphenolics, Naturex, Nexira, Indena S.p.A., NetQem LLC, Piping Rock Health Products, LLC, ConnOils LLC, Natac, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Grape Seed Extract Market Evolving Landscape
Cold-press extraction infrastructure is reshaping competitive positioning in the standardized extract segment, while regulatory digitization and channel fragmentation are simultaneously compressing traditional supply relationships.
Supercritical CO2 extraction technology is overtaking aqueous ethanol methods among premium-positioned suppliers seeking solvent-free certification for clean-label formulations. Nutraceutical contract manufacturers in California and Oregon are retrofitting facilities to accommodate this shift. The technology is overtaking conventional processing in high-margin cosmetic applications where residual solvent thresholds approach detection limits.
FDA's evolving enforcement posture on structure-function claims is tightening substantiation requirements for antioxidant health benefits. Supplement brands must now maintain clinical evidence portfolios that withstand scrutiny under FTC advertising guidelines. California-based formulators are most affected, with several restructuring label copy to qualify claims under the narrower dietary ingredient framework.
Direct procurement from wine cooperatives is replacing spot-market pomace purchasing among volume extract processors. Large nutraceutical buyers are signing multi-year supply agreements with Central Valley wineries, locking in feedstock access. This pattern is most visible in Fresno and Kern counties, where processor-winery integration is deepening.
North America Grape Seed Extract Market Segmentation
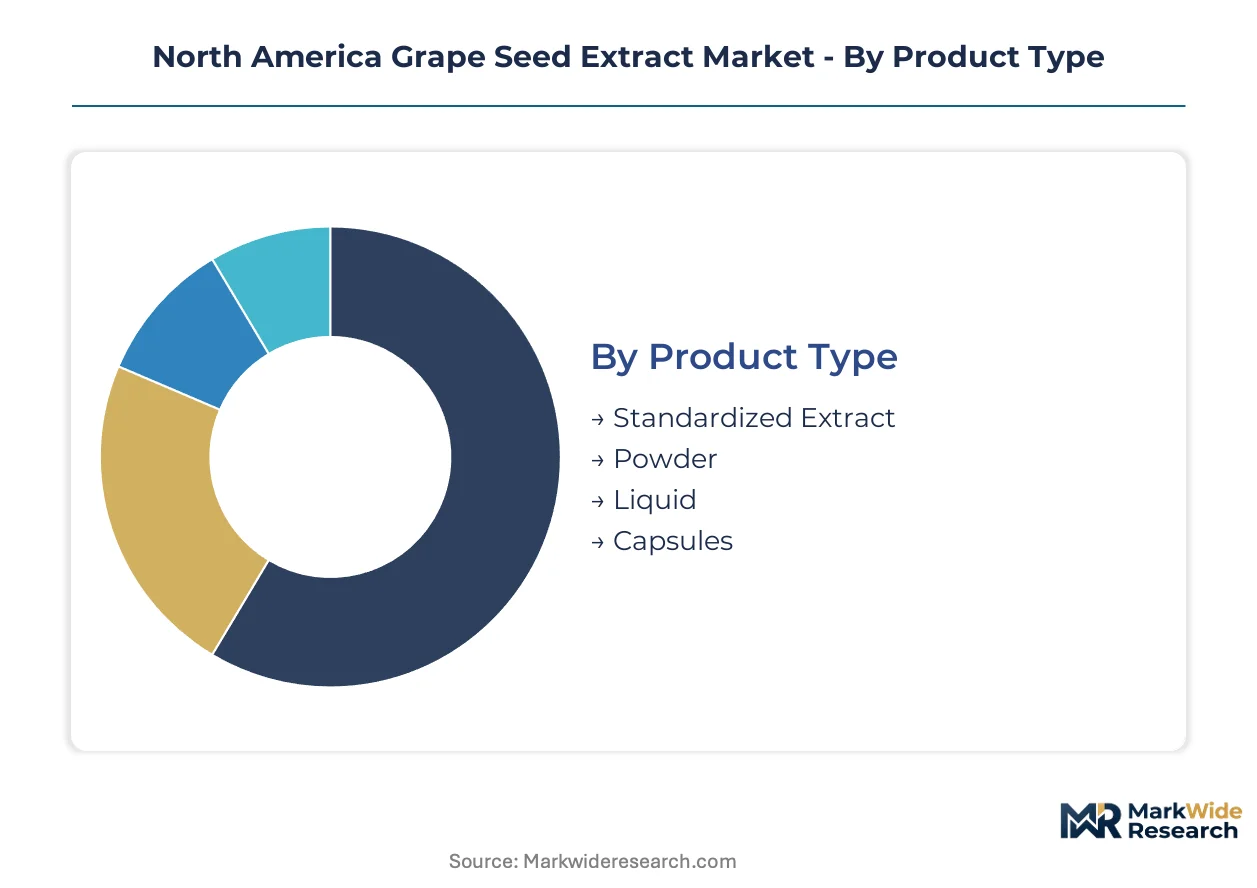
Grape seed extract segmentation reveals how supply chain configuration shapes competitive access across product formats and end-use channels. California's Central Valley processing clusters concentrate technical capabilities that favor certain segment combinations over others.
Product Type:
California's grape pomace availability and extraction infrastructure concentration directly determine which product formats achieve cost-competitive scale.
- Standardized Extract:Aqueous ethanol-derived concentrate standardized to 95% proanthocyanidins content. Demand concentrates among nutraceutical contract manufacturers in California and Oregon seeking USP monograph compliance for cardiovascular supplement formulations. FDA's NDI notification requirements favor incumbent processors with established analytical protocols.
- Powder:Spray-dried format dominating production throughput through efficient bulk handling and extended shelf stability. Central Valley processors leverage proximity to Fresno and Kern county wineries to minimize feedstock logistics costs.
- Liquid:Glycerin-based suspensions targeting functional beverage integration and tincture applications.
- Capsules:Encapsulated powder or liquid delivering direct-to-consumer convenience premiums.
Today's leader: Standardized Extract. Tomorrow's challenger: Capsules.
Application:
Margin architecture varies sharply across end-use sectors, with certification requirements and claim substantiation burdens creating distinct competitive tiers.
- Nutraceuticals:Dietary supplement formulations absorbing the majority of North American volume, with antioxidant cardiovascular and anti-aging positioning driving procurement. DSHEA enforcement patterns and FTC advertising guidelines tighten clinical evidence requirements for structure-function claims.
- Cosmetics:Topical serums and antioxidant skin health formulations commanding premium margin pools through clean-label positioning and solvent-free certification demands. Supercritical CO2 extraction technology is displacing conventional methods in this segment.
- Pharmaceuticals:USP-grade material for investigational drug applications and compounding pharmacies.
- Food & Beverages:Functional ingredient integration requiring GRAS self-determination or FDA notification.
Volume concentrates in Nutraceuticals. Value expansion is climbing the fastest in Cosmetics.
Distribution Channel:
Channel fragmentation is compressing traditional wholesale relationships as extract brands pursue margin recapture through disintermediation.
- Online Retail:Direct-to-consumer platforms enabling brands to bypass nutraceutical distributors and capture superior per-unit economics. E-commerce penetration is expanding most quickly among capsule-format suppliers targeting anti-aging positioning.
- Supermarkets:Mass-market retail placement for mainstream antioxidant supplements.
- Health Stores:Specialty retail channel emphasizing organic certification and premium sourcing narratives.
- Pharmacies:Professional recommendation-driven sales for cardiovascular health applications.
Current infrastructure favors Health Stores. Digital-native challenger: Online Retail.
End User:
Procurement sophistication and technical specification requirements create distinct customer tiers with diverging supplier qualification protocols.
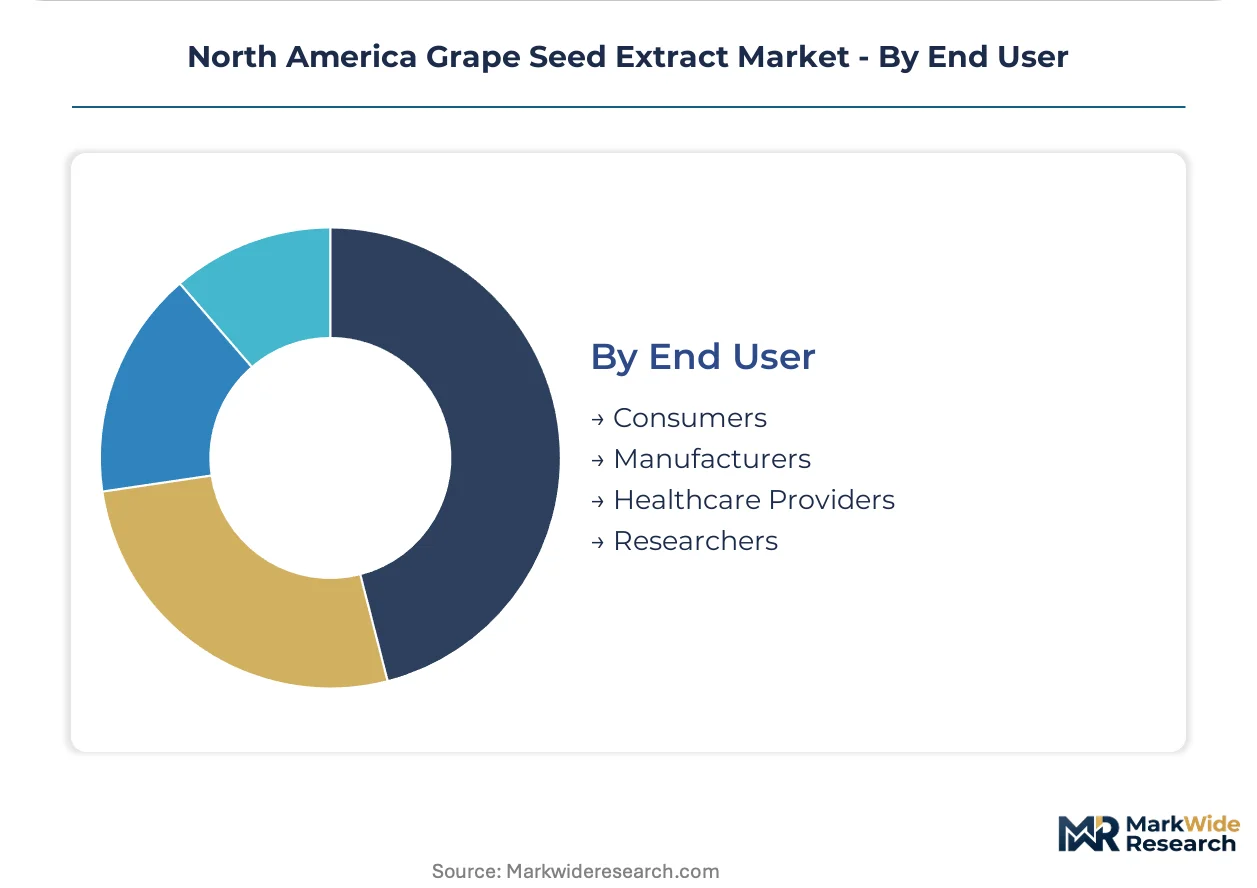
- Consumers:Individual purchasers responding to antioxidant health claims and clean-label positioning, with purchasing decisions influenced by USDA Organic certification visibility and third-party testing seals.
- Manufacturers:Nutraceutical and cosmetic contract manufacturers requiring batch-to-batch proanthocyanidin consistency and Certificate of Analysis documentation.
- Healthcare Providers:Integrative medicine practitioners and clinical nutritionists recommending grape seed extract for patient protocols.
- Researchers:Academic and clinical investigators sourcing pharmaceutical-grade material for bioavailability and efficacy studies.
Volume anchors with Manufacturers. Influence is concentrating with Healthcare Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley concentrates extraction chemists and quality assurance specialists who anchor North American grape seed extract processing capacity.
United States
Nutraceutical contract manufacturers in California and Oregon absorb standardized extract volumes for cardiovascular supplement formulations. FDA's New Dietary Ingredient notification requirements and DSHEA enforcement patterns create compliance pathways that favor established processors with analytical protocols. Fresno and Kern counties host deepening processor-winery integration as large buyers sign multi-year pomace supply agreements with Central Valley wine cooperatives.
Canada
Health Canada Natural Health Product regulations generate parallel compliance demand for US-qualified suppliers expanding northward into underpenetrated antioxidant supplement markets. Canadian nutraceutical distributors face procurement sophistication gaps that create entry opportunities for California-experienced extractors. Ontario and British Columbia concentrate health product manufacturing activity near Toronto and Vancouver metro areas.
Mexico
Emerging functional food and beverage integration demand in Mexico City and Monterrey metro areas creates import-dependent consumption growth. Mexican regulatory alignment with US FDA frameworks simplifies cross-border ingredient qualification for grape seed extract suppliers. Baja California's proximity to California processing clusters supports logistics-efficient supply relationships.
North America Grape Seed Extract Market Competitive Landscape
The competitive structure tilts toward vertically integrated processors with captive vineyard relationships and established quality management systems. Incumbent extractors leverage USP monograph compliance capabilities and organic certification infrastructure to sustain margin positions against new entrants. Three archetypes dominate: wine-integrated pomace processors, pharmaceutical-grade specialists, and direct-to-consumer capsule brands. Capacity expansion through cold-press and supercritical CO2 retrofitting represents the primary competitive move, alongside strategic partnerships locking multi-year feedstock contracts.
Among US-based extraction specialists, Botanic Innovations LLC and Polyphenolics occupy positions reflecting distinct strategic orientations within the California cluster. Botanic Innovations exemplifies technology-differentiated positioning through cold-press infrastructure investment. Polyphenolics represents supply-security-focused archetyping through winery relationship depth. Indena S.p.A. anchors the pharmaceutical-grade certification tier with European-origin quality systems that translate to USP-compliant North American market access.
| Leading Market Players |
|---|
| Botanic Innovations LLC |
| Polyphenolics |
| Naturex |
| Nexira |
| Indena S.p.A. |
| NetQem LLC |
| Piping Rock Health Products, LLC |
| ConnOils LLC |
| Natac |
| Others |
Value Network & Pricing Analysis
Extraction chemist concentration in California's Central Valley amplifies labor-cost differentials between USP-certified processors and commodity-grade competitors, widening spreads between premium pharmaceutical-grade and economy feedstock pricing tiers.
Pricing Analysis
Bundled analytical certification services versus unbundled raw extract sales split the market into divergent pricing architectures. Three-tier pricing structure across premium, standard, and economy levels separates USP monograph-compliant suppliers from USDA Organic-certified mid-tier processors and uncertified commodity extractors. Price differentiation hinges on proanthocyanidin standardization precision and FDA NDI notification completion status. Cost compression in the economy tier is intensifying because winery pomace contract competition is elevating input costs for non-vertically integrated processors. Nutraceutical contract manufacturers exhibit highest price sensitivity, while cosmetic formulators purchasing solvent-free certified material show lowest elasticity.
Supply Chain Analysis
Reverse-logistics flows of spent grape pomace from Central Valley wineries back to extraction facilities anchor circular feedstock recovery economics. Supply concentrates in the United States, with secondary processing nodes in Canada and import-dependent consumption in Mexico. Raw material dependencies center on Vitis vinifera pomace availability, aqueous ethanol or supercritical CO2 solvent supply, and spray-drying energy inputs. Single-source vulnerability runs through California's vintage yield volatility, which compresses processor margins during low-harvest years. Distribution runs through nutraceutical contract manufacturers, direct-to-consumer e-commerce platforms, and health specialty retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America grape seed extract market functions as a stable compounder, with antioxidant supplement demand from aging demographics delivering predictable volume absorption across economic cycles.
For Market Incumbents: Anticipate supercritical CO2 extraction technology displacement by retrofitting cold-press infrastructure ahead of cosmetic clean-label certification demands. Lock multi-year pomace supply agreements with Fresno and Kern county wine cooperatives to defend feedstock access against emerging processor competition. Prioritize USP monograph analytical protocol investment to maintain pharmaceutical-grade certification barriers.
For New Entrants and Emerging Players: Launch via direct-to-consumer capsule e-commerce channels to bypass entrenched nutraceutical distributor relationships and capture premium per-unit economics. Target Canadian health product markets under Health Canada Natural Health Product regulations, where US-qualified suppliers face lower competitive density. Exploit analytical chemist scarcity among legacy suppliers by recruiting phytochemical expertise from adjacent botanical extract industries.
For Investors and Strategic Acquirers: Valuations sit cheapest among wine-integrated pomace processors lacking branded distribution, offering backward integration synergies for downstream nutraceutical formulators. Five-to-ten year viability favors processors with captive vineyard relationships and multi-format extraction capabilities. Monitor FDA NDI guidance enforcement patterns as the inflection signal for competitive access shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Pomace Supply Agreement | Locks feedstock access against vintage yield volatility in California's Central Valley. |
| Supercritical CO2 Retrofit Investment | Enables solvent-free certification for premium cosmetic and clean-label nutraceutical segments. |
| USP Monograph Compliance Pathway | Elevates analytical barriers that protect incumbent positioning against new market entrants. |
| Direct-to-Consumer Capsule Launch | Bypasses wholesale distributor margin capture through e-commerce channel control. |
| Canadian Market Expansion | Leverages Health Canada NHP regulatory familiarity to penetrate underdeveloped antioxidant supplement demand. |
Research Methodology
Multiple input streams — primary interviews with extraction facility managers, nutraceutical procurement directors, and cosmetic formulators; secondary validation through FDA NDI notification databases, USDA Organic certification records, and USP monograph documentation; plus customs trade flow analysis — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned California Central Valley processors, Oregon contract manufacturers, Ontario health product distributors, and Baja California importers. Secondary sources incorporated winery cooperative production data, nutritional supplement retail audit feeds, and phytochemical industry association reports.
Historical volume trajectories were cross-referenced against panel-derived growth assumptions across the projection horizon. Segmentation modeling incorporated product format, application end-use, distribution channel, and customer procurement sophistication dimensions. CAGRs were derived from fitted trend extrapolation moderated by regulatory enforcement pattern assumptions and feedstock availability projections. Industry-specific forecast inputs included vintage yield cyclicality, DSHEA enforcement posture evolution, and supercritical CO2 technology adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA NDI notification timeline delays or sustained drought conditions affecting California grape harvests. Practitioners should monitor Health Canada NHP regulatory harmonization proposals and Central Valley water allocation policy shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Europe Specialty Food Ingredients Market
Specialty Ingredients
Normal and Specialty Fats Market
Specialty Ingredients
Vetiver Oil Market
Specialty Ingredients
Middle East and Africa Customized Premixes Market
Specialty Ingredients
Aromatherapy Carrier Oil Market
Specialty Ingredients
Benzoe Siam Market
Specialty Ingredients
Flavanols Market
Specialty Ingredients
Fermentation Products Market
Specialty Ingredients
Sun-Care Natural Oils Market
Specialty Ingredients
Mangosteen Market
Specialty Ingredients
Customized Nutrient Premixes Market
Specialty Ingredients
Global Ayurvedic Herbs Market
Specialty Ingredients
Mangosteen Extract Market
Specialty Ingredients
Floral Water Market
Specialty Ingredients
Personal Care Specialty Ingredients Market
Specialty Ingredients
Middle East and Africa Specialty Food Ingredients Market