
 Global Pet Food Flavors Market | 2026-2036
Global Pet Food Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pet Food Flavors Market Foresight
Market Context with Strategic Players
Pet specialty retail and direct-to-consumer subscription channels is tilting procurement power toward flavor houses with rapid formulation turnaround capabilities. Kerry leverages its integrated taste and nutrition platform to sustain long-term contracts with multinational pet food manufacturers across North America and Europe. Givaudan differentiates through its dedicated pet care flavor center in Switzerland, where application scientists co-develop species-specific palatability solutions with brand partners. Symrise anchors its position in the premium natural segment through backward integration into botanical extraction and fermentation-derived flavor precursors.
Technical Definition and Structural Segments
Pet food flavors comprise concentrated aromatic compounds, extracts, and reaction flavors engineered to enhance palatability, mask off-notes from functional additives, and trigger species-specific feeding responses in domestic animals. These formulations typically achieve application rates of 0.1% to 2.0% by weight, with spray-dried encapsulation and lipid-coating technologies protecting volatile molecules through extrusion thermal stress exceeding 120°C. Natural flavors and blended flavors command the deepest margin pools as pet food manufacturers reformulate away from synthetic additives to meet clean-label positioning demanded by millennial and Gen Z pet owners. Dog food applications absorb the largest absolute volume of flavor inputs, though cat food segments exhibit higher per-unit flavor intensity and premium pricing due to feline olfactory sensitivity and selective feeding behavior.
Regulatory Frame and Forward-Looking Close
The FDA Center for Veterinary Medicine enforces ingredient safety standards under the Food Safety Modernization Act, while the European Food Safety Authority and FEDIAF nutritional guidelines constrain flavor additive approvals and labeling claims across EU member states. China's Ministry of Agriculture and Rural Affairs and its national feed safety standards are tightening import requirements for foreign flavor premixes, creating compliance barriers for non-domestic suppliers. Stakeholders must monitor diverging regulatory timelines for novel protein and fermentation-derived flavor substrates, as approval asymmetries between the FDA, EFSA, and NMPA will determine which innovation pipelines achieve scalable geographic deployment.
Market Dynamics
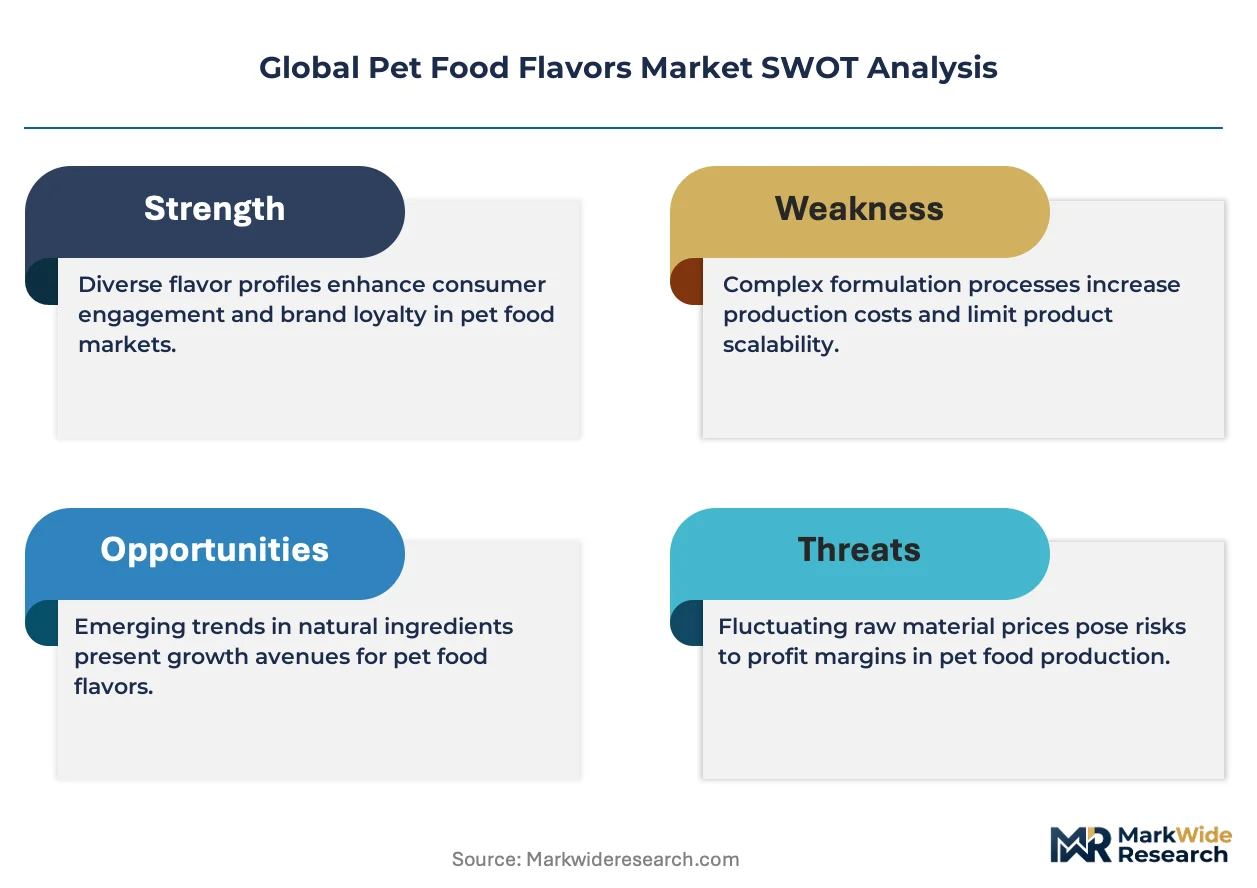
Pet humanization is restructuring flavor procurement around species-specific palatability science and clean-label positioning, forcing reformulation cycles that compress supplier response windows.
Growth Catalysts
- Clean-label mandates:FDA Food Safety Modernization Act traceability requirements and FEDIAF labeling guidelines are accelerating natural flavor adoption across North American and European manufacturing.
- Fresh pet food channels:Direct-to-consumer subscription services in the United States are pulling higher-flavor-intensity formulations with rapid turnaround specifications.
- Feline olfactory sensitivity:Cat food segments command premium flavor inputs due to selective feeding behavior, expanding margin pools for species-specific solutions.
Market Restraints
- Botanical supply volatility:Weather-driven crop failures for vanilla, yeast extracts, and fermentation feedstocks create input cost instability for natural flavor houses.
- Regulatory approval asymmetry:Divergent timelines between FDA, EFSA, and China's NMPA for novel protein substrates fragment innovation deployment across geographies.
- Extrusion thermal degradation:Spray-dried encapsulation costs rise with lipid-coating complexity to protect volatiles above 120°C processing temperatures.
Strategic Opportunities
- Brazilian market underpenetration:ANVISA regulatory harmonization and rising pet ownership in São Paulo and Rio de Janeiro create white space for flavor localization.
- Fermentation-derived precursors:Precision fermentation technology converges with botanical extraction to unlock sustainable, scalable natural flavor molecules.
- Veterinary therapeutic nutrition:Functional pet food formulations masking off-notes from pharmaceuticals open premium application channels.
Industry Challenges
- Species-specific formulation expertise:Shortage of application scientists trained in canine versus feline palatability physiology limits co-development capacity.
- Legacy ERP integration:Pet food manufacturers' aging traceability systems struggle to interface with flavor house batch-lot tracking for FSMA compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pet Food Flavors Market |
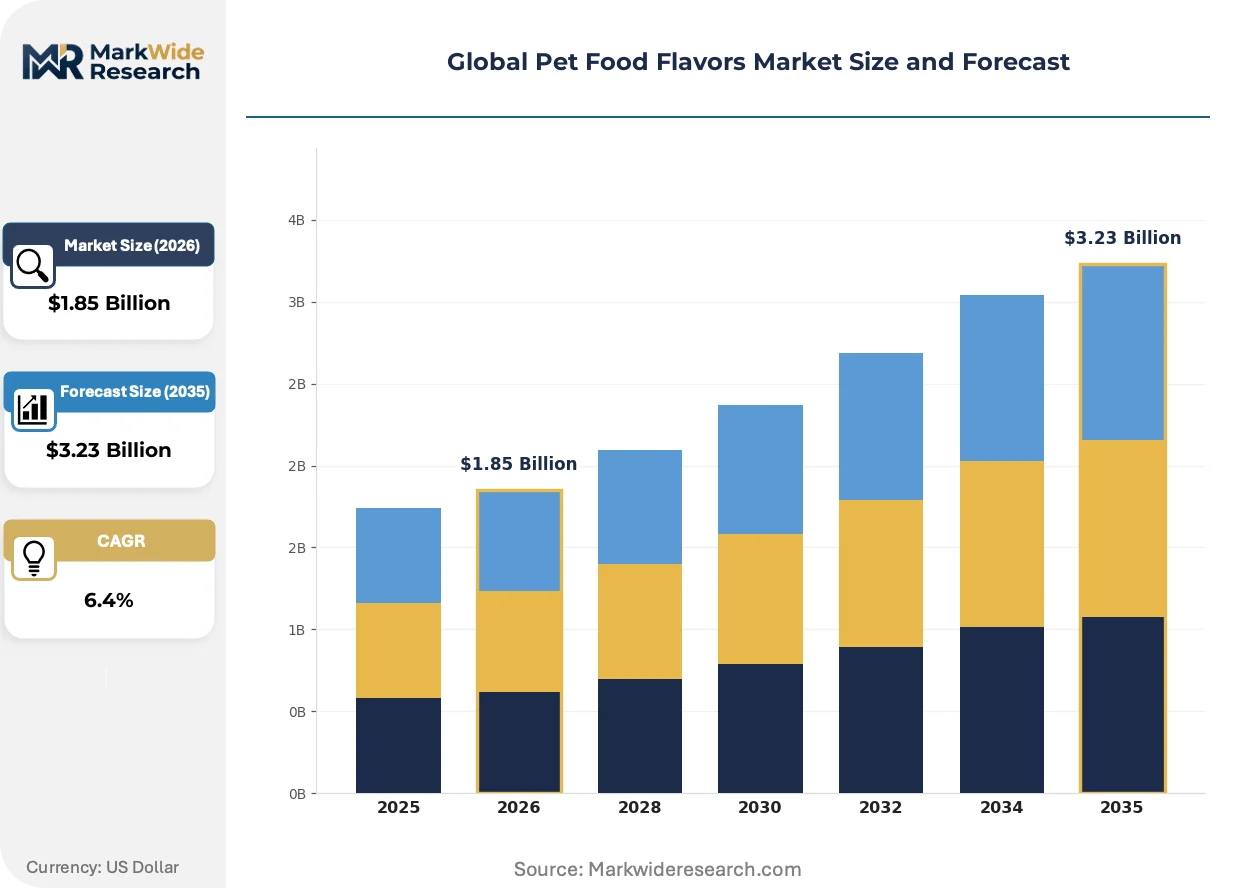
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Artificial Flavors, Organic Flavors, Blended Flavors, Nutritional Enhancers Application: Dog Food, Cat Food, Fish Food, Bird Food, Small Mammal Food End User: Pet Specialty Stores, Online Retailers, Veterinary Clinics, Animal Breeders, Pet Food Manufacturers Packaging Type: Powder, Liquid, Spray, Granular, Pelletized |
| Companies Covered | Kerry, Givaudan, Firmenich SA, Sensient Technologies Corporation, Symrise, T. Hasegawa Co., Ltd., ADM, Huabao International Holdings Limited, Takasago International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pet Food Flavors Market Shifts & Advancements
Flavor delivery technology and regulatory science are converging to reshape how palatability solutions are engineered, tested, and deployed across species-specific applications.
Microencapsulation is migrating from spray-dried powders to lipid-coated and complex coacervation systems that shield volatile molecules through high-shear extrusion. Premium wet dog food manufacturers in U.S. pet specialty retail are adopting these systems fastest. The structural consequence is compressing formulation development cycles from months to weeks.
REACH substance registration requirements and the EU Green Deal's chemical sustainability criteria are tightening scrutiny on synthetic flavor precursors. European flavor houses are accelerating botanical extraction and biotechnology-derived alternatives. Cat food applications face the steepest compliance costs due to higher per-unit flavor intensity demands.
Millennial and Gen Z pet owners are consolidating purchases through subscription platforms that require flavor houses to guarantee batch consistency across variable raw material inputs. Direct-to-consumer fresh pet food brands in the United States are displacing traditional co-manufacturer relationships with direct flavor house partnerships.
Global Pet Food Flavors Market Segmentation
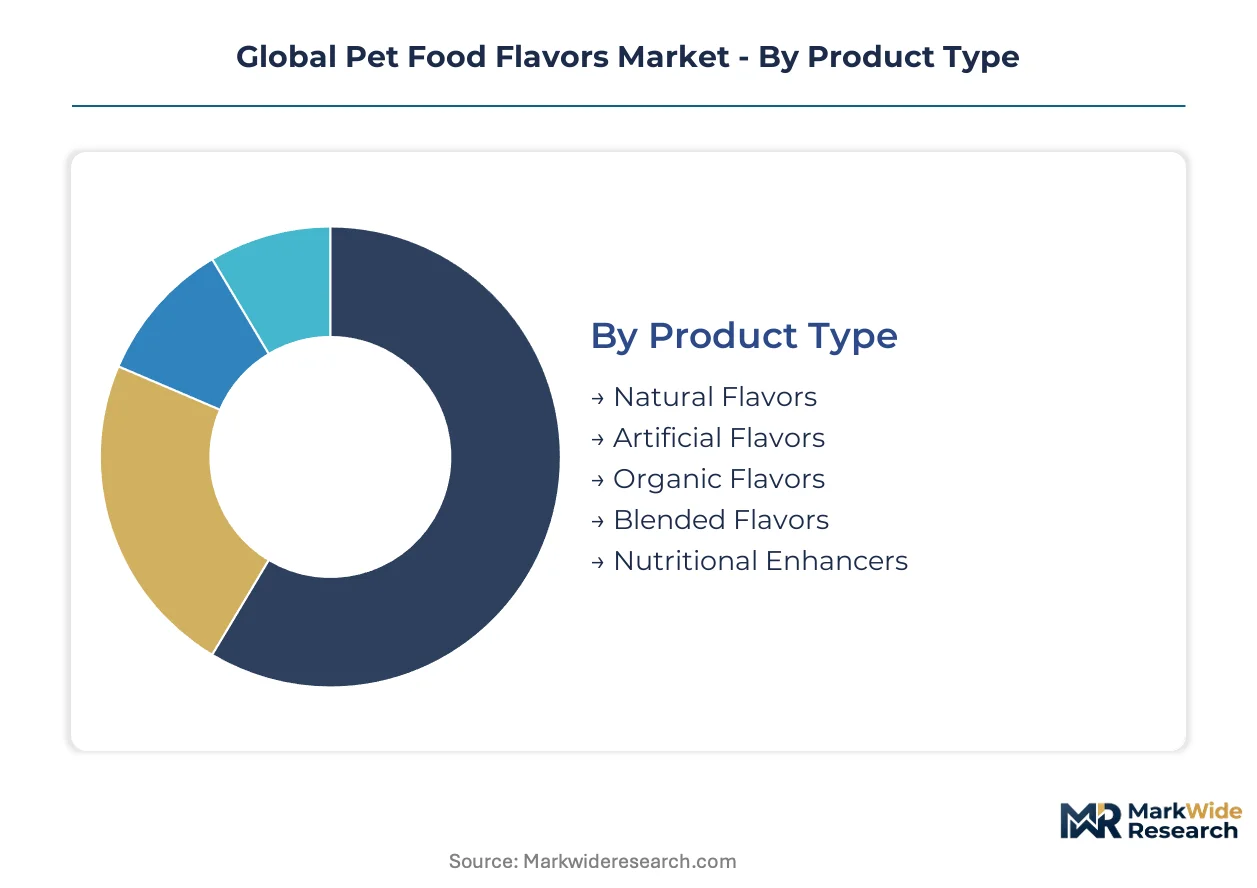
Segmentation in pet food flavors reveals how procurement power, formulation complexity, and channel requirements fragment across distinct product architectures and end-use specifications. Understanding these divides exposes where margin pools concentrate and where supplier capabilities must adapt.
Product Type:
Use-case spectrum spans clean-label positioning at premium tiers through cost-engineered palatability at mass market, with formulation chemistry determining thermal stability and species-specific efficacy.
- Natural Flavors:Botanical extracts and fermentation-derived aromatic compounds deliver clean-label compliance for millennial and Gen Z pet owners. United States fresh pet food subscription channels are pulling rapid-turnaround procurement specifications for these inputs.
- Blended Flavors:Hybrid formulations combine natural precursors with synthetic stability enhancers to balance cost and performance. European manufacturers under FEDIAF guidelines are reformulating toward these intermediate solutions as REACH scrutiny tightens.
- Artificial Flavors:Synthetic aromatic molecules engineered for cost efficiency and batch consistency. Mass-market extruded kibble producers in Brazil and Southeast Asia retain these for margin protection.
- Organic Flavors:Certified organic botanical extracts meeting USDA or EU organic standards. Premium positioning in German and French pet specialty retail commands certification premiums.
- Nutritional Enhancers:Functional flavor systems masking off-notes from pharmaceuticals, probiotics, or novel proteins. Veterinary therapeutic nutrition channels in Japan and South Korea are expanding application scope.
Established volume favors Natural Flavors; emerging adoption favors Nutritional Enhancers.
Application:
Species-specific olfactory physiology and feeding behavior create divergent intensity requirements and formulation complexity tiers.
- Dog Food:Formulations address canine olfactory preferences with moderate flavor intensity and high thermal stability for extrusion processing. United States pet specialty retail channels are specifying lipid-coated microencapsulation systems.
- Cat Food:Feline selective feeding behavior and vomeronasal sensitivity demand premium flavor inputs with higher per-unit intensity. Japanese and South Korean manufacturers command steepest formulation expertise premiums.
- Fish Food:Aquatic species formulations require water-stable delivery systems with controlled leach rates. Tropical ornamental markets in Germany and the Netherlands concentrate demand.
- Bird Food:Psittacine and passerine species exhibit seed-selective behavior requiring masking of pellet off-notes. Brazilian aviculture expansion is pulling regional flavor localization.
- Small Mammal Food:Lagomorph and rodent formulations balance palatability with dental abrasion requirements. Niche positioning in United Kingdom and Australian specialist channels.
Dog Food retains volume dominance; Cat Food captures margin concentration.
End User:
Channel structure determines batch size, turnaround speed, and traceability depth required from flavor suppliers.
- Pet Food Manufacturers:Multinational producers with long-term contracts and integrated quality systems. Kerry and Givaudan sustain dedicated application science partnerships with these accounts.
- Pet Specialty Stores:Premium private-label and exclusive brand formulations with rapid refresh cycles. United States chains are compressing supplier response windows to weeks.
- Online Retailers:Direct-to-consumer platforms requiring batch consistency guarantees across variable raw material inputs. Subscription models in the United States are displacing traditional co-manufacturer relationships.
- Veterinary Clinics:Therapeutic and prescription diet channels with functional masking requirements. Precision fermentation-derived precursors are penetrating this segment fastest.
- Animal Breeders:Volume-focused procurement for working dog and show animal nutrition. Price-sensitive positioning with limited formulation customization.
Pet Food Manufacturers anchor volume; Online Retailers are climbing the fastest.
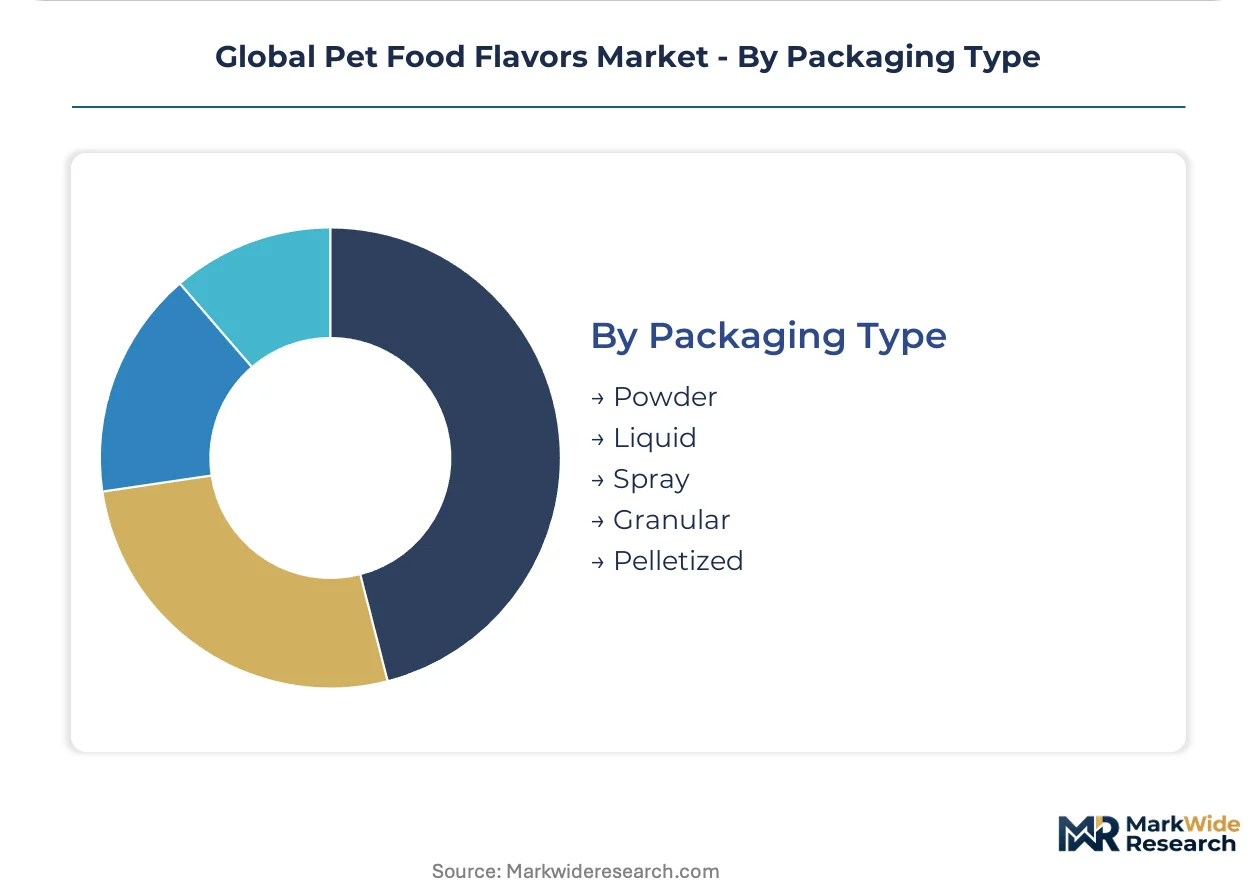
Packaging Type:
Physical form factor determines shelf stability, dosing precision, and integration with downstream manufacturing equipment.
- Powder:Spray-dried encapsulation systems for dry mix applications. Standard for mass-market extrusion operations across Brazil and Mexico.
- Liquid:Oil-soluble and water-dispersible concentrates for wet food and coating applications. Premium wet dog food in United States specialty channels specifications.
- Spray:Aerosolized application systems for post-extrusion surface coating. Emerging adoption for palatability enhancement in European fresh pet food.
- Granular:Free-flowing particles for automated dosing in large-scale manufacturing. Favored by multinational pet food producers for consistency.
- Pelletized:Compressed forms for slow-release or targeted delivery in functional formulations. Veterinary therapeutic applications in Japan and Germany.
Powder and Liquid retain manufacturing dominance; Spray formats gain share in premium channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while cost-sensitive procurement dominates Brazilian manufacturing. German and Japanese markets command formulation expertise premiums. Chinese regulatory tightening is fragmenting supplier access.
United States
Fresh pet food subscription services in metropolitan corridors are pulling rapid-turnaround flavor specifications with batch consistency guarantees. The FDA Food Safety Modernization Act enforces ingredient traceability mandates that compress supplier response windows. Pet specialty retail chains in California and the Northeast are specifying lipid-coated microencapsulation systems for premium wet dog food.
Germany
REACH substance registration and EU Green Deal chemical sustainability criteria are tightening scrutiny on synthetic flavor precursors. EFSA and FEDIAF nutritional guidelines constrain additive approvals and labeling claims across manufacturing. Botanical extraction specialists in Bavaria and North Rhine-Westphalia are accelerating biotechnology-derived alternatives for clean-label positioning.
China
Domestic pet ownership expansion in tier-one cities is driving demand for premium flavor inputs. The Ministry of Agriculture and Rural Affairs and national feed safety standards are tightening import requirements for foreign flavor premixes. Manufacturing clusters in the Yangtze River Delta face compliance barriers that favor domestic supplier consolidation.
Brazil
ANVISA regulatory harmonization and rising pet ownership in São Paulo and Rio de Janeiro are creating white space for flavor localization. Cost-engineered artificial flavors retain dominance in mass-market extruded kibble production. Regional flavor houses are backward integrating into captive botanical supply chains to offset import dependency.
Japan
Feline olfactory sensitivity and selective feeding behavior command premium formulation inputs with steep expertise premiums. METI industrial standards and PMDA veterinary therapeutic guidelines shape functional masking requirements. Precision fermentation-derived precursors are penetrating veterinary nutrition channels in the Kanto and Kansai manufacturing belts.
Global Pet Food Flavors Market Competitive Landscape
Integrated taste-nutrition platforms and dedicated pet care flavor centers split the market between long-term contract anchors and rapid-turnaround specialists. The structure tilts toward consolidated multinational supply relationships with tiered service capabilities. Three archetypes dominate: full-solution flavor houses with backward integration into botanical extraction, application-science specialists co-developing species-specific palatability systems, and regional cost-optimized suppliers serving mass-market extrusion. Competitive moves concentrate on strategic partnerships with direct-to-consumer subscription platforms and capacity expansion into fermentation-derived precursor production.
Within the integrated-platform tier, Kerry and Givaudan occupy positions that exemplify divergent geographic anchoring. Kerry leverages its North American and European manufacturing footprint to sustain long-term contracts with multinational pet food producers. Givaudan anchors its competitive position through Swiss-based application science capabilities. Symrise sits within the premium-natural archetype, representing backward integration strategies into botanical extraction and fermentation-derived flavor precursors.
| Leading Market Players |
|---|
| Kerry |
| Givaudan |
| Firmenich SA |
| Sensient Technologies Corporation |
| Symrise |
| T. Hasegawa Co., Ltd. |
| ADM |
| Huabao International Holdings Limited |
| Takasago International Corporation |
| Others |
Supply & Pricing Matrix
Yangtze River Delta manufacturing clusters anchor global natural flavor extraction capacity, with captive botanical processing in Zhejiang and Jiangsu provinces feeding downstream pricing power to European and North American flavor houses. This geographic concentration creates asymmetric cost structures where fermentation-derived precursor availability dictates margin compression timelines for synthetic alternatives.
Pricing Analysis
The customization-premium spread in pet food flavors spans three-tier pricing structure across premium, standard, and economy levels. Certification grade under FEDIAF guidelines and USDA organic standards commands 15-25 point spreads over conventional inputs. Pricing pressure stems from botanical supply volatility for vanilla and yeast extracts, with mass-market extruded kibble producers in Brazil exhibiting highest price sensitivity while Japanese veterinary therapeutic channels show least elasticity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for flavor premix trade flows. Manufacturing concentrates in China, Switzerland, and the United States, with raw material dependencies on Madagascar vanilla, Indonesian palm derivatives, and Brazilian fermentation feedstocks. Single-source vulnerability in tropical botanical extraction feeds from cyclical weather patterns. Distribution runs through multinational pet food manufacturers with direct-to-consumer subscription platforms gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pet food flavors market rewards scarce formulation expertise in species-specific palatability science, where application scientists trained in feline olfactory physiology command premium contracting rates against a thin talent pipeline.
For Market Incumbents: Insulate long-term contract positions by accelerating backward integration into precision fermentation capacity and securing captive botanical supply chains in Southeast Asia. Kerry and Givaudan should deepen application science partnerships with direct-to-consumer subscription platforms to offset margin erosion from mass-market commoditization. Regulatory compliance investments under evolving FDA FSMA traceability mandates provide defensive moats against regional cost-optimized suppliers. For New Entrants and Emerging Players: Establish a beachhead in Brazilian ANVISA regulatory harmonization corridors by localizing cost-engineered artificial flavor production for mass-market extrusion. The underpenetrated São Paulo and Rio de Janeiro metropolitan corridors offer white-space expansion with lower certification barriers than EU or US markets. Partner with regional pet food co-manufacturers to bypass multinational procurement gatekeeping. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fermentation-derived precursor specialists with veterinary therapeutic nutrition channel penetration. Long-term viability over the 5-10 year horizon hinges on regulatory approval pipeline depth across FDA, EFSA, and NMPA jurisdictions. Target acquisition profiles center on mid-cap flavor houses with captive extraction assets and species-specific formulation IP. The signal to watch is divergence in novel protein substrate approval timelines between major regulatory bodies.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Buildout | Unlocks scalable natural flavor molecules independent of tropical botanical harvest cycles. |
| Species-Specific Palatability Center Investment | Captures premium formulation margins from feline selective feeding behavior requirements. |
| Direct-to-Consumer Platform Partnership | Bypasses traditional co-manufacturer relationships for batch-guaranteed subscription supply. |
| Captive Botanical Supply Chain Integration | Offsets Madagascar vanilla and Indonesian extract price volatility through upstream control. |
| Veterinary Therapeutic Channel Certification | Opens functional masking applications under PMDA and FDA Center for Veterinary Medicine guidelines. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with flavor application scientists, pet food manufacturer procurement directors, and regulatory affairs specialists; and secondary validation through FEDIAF nutritional guidelines, FDA Center for Veterinary Medicine filings, and customs trade data on flavor premix imports. Bottom-up volume modeling triangulated against top-down market sizing from industry association reports and SEC disclosures from listed flavor houses.
Forecast inputs span product type segmentation across natural, blended, and artificial flavor tiers; application intensity differentials between canine and feline formulations; and channel structure evolution from multinational manufacturer contracts to direct-to-consumer subscription platforms. CAGRs derive from regression analysis of historical procurement patterns and projected regulatory timeline impacts across the analysis window. Industry-specific inputs include extrusion thermal stability requirements and species-specific olfactory sensitivity coefficients.
Sensitivities concentrate around regulatory approval asymmetries for novel protein substrates and fermentation-derived flavor precursors between FDA, EFSA, and NMPA jurisdictions. Forecasts reflect assumptions on pet humanization trend persistence and clean-label mandate enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Global Ayurvedic Herbs Market
Specialty Ingredients
Specialty Beverage Stabilizers Market
Specialty Ingredients
Marine Spicules Market
Specialty Ingredients
Europe Specialty Food Ingredients Market
Specialty Ingredients
Grape Seed Extract in Pet Food Application Market
Specialty Ingredients
Mangosteen Extract Market
Specialty Ingredients
Abies Alba (Fir) Leaf Oil Market
Specialty Ingredients
Personal Care Specialty Ingredients Market
Specialty Ingredients
Agarwood Essential Oil Market
Specialty Ingredients
North America Grape Seed Extract Market
Specialty Ingredients
Specialty Ingredients Market
Specialty Ingredients
Middle East and Africa Specialty Food Ingredients Market
Specialty Ingredients
Sun-Care Natural Oils Market
Specialty Ingredients
Mangosteen Market
Specialty Ingredients
Vetiver Oil Market
Specialty Ingredients
Fermentation Products Market