
 Food Decorations and Inclusions Market | 2026-2036
Food Decorations and Inclusions Market Size, Share, and Industry Trends Forecast 2026-2036
Food Decorations and Inclusions Market Intelligence
The distinction between standard and premium, clean-label inclusions is collapsing as consumer expectations for natural ingredients intensify. Barry Callebaut leverages its extensive cocoa sourcing to offer traceable chocolate shavings and decorations. Cargill, Incorporated competes with a portfolio of functional ingredients, including texturizing nut and fruit pieces for large-scale food manufacturers. Dawn Food Products, Inc. specializes in the bakery channel, providing a wide array of sprinkles and icings to professional and retail bakers.
Food decorations and inclusions encompass edible products designed to enhance the aesthetic appeal, texture, and flavor of finished food items. These components are formulated for specific performance criteria, such as heat stability in baking applications or color retention in dairy products. Within product types, chocolate shavings and candied fruits often secure higher price points due to raw material costs. Sprinkles and edible glitter, however, drive volume, especially within the high-turnover confectionery and baking application segments.
Market access is governed by stringent food additive and labeling regulations. The U.S. Food and Drug Administration (FDA) maintains strict controls on color additives, while the European Food Safety Authority (EFSA) evaluates the safety of all food ingredients. In India, the Food Safety and Standards Authority of India (FSSAI) enforces comprehensive labeling requirements for allergens and nutritional content. Producers must therefore navigate a complex web of international standards while innovating with natural, visually appealing products.
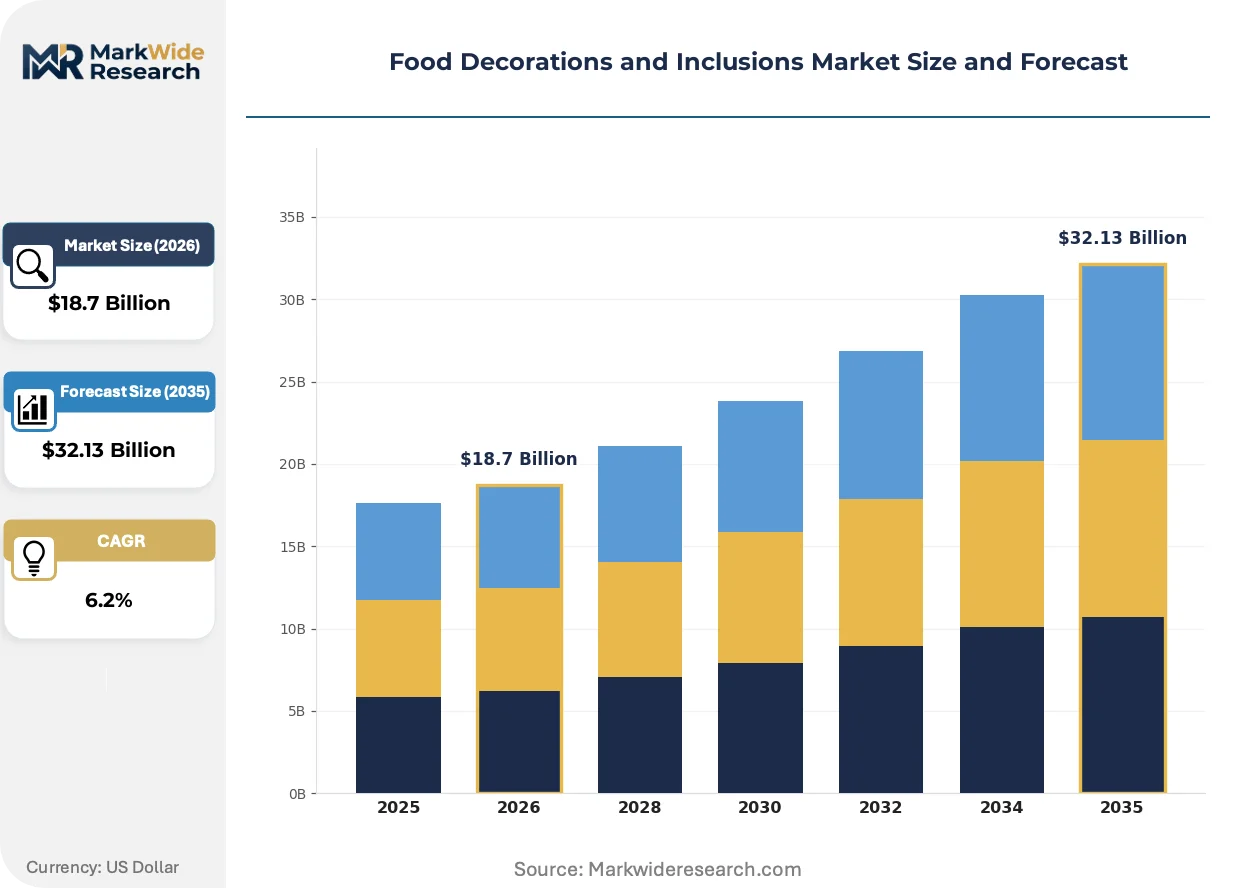
Market Dynamics
The central dynamic shaping the market is the tension between consumer demand for highly visual, unique food presentations and the simultaneous regulatory and consumer-led push for clean-label ingredients, forcing innovation in natural colors and textures.
Growth Catalysts
- Clean-Label Regulation:Stricter food additive reviews by bodies like the European Food Safety Authority (EFSA) compel manufacturers to replace synthetic ingredients, creating demand for natural inclusions and decorations in the bakery and confectionery segments.
- Artisanal Segment Expansion:The expansion of craft bakeries and confectioners, particularly in European markets like Germany and France, fuels requirements for premium, traceable ingredients such as single-origin chocolate shavings and candied regional fruits.
- Material Science Innovation:Advances in encapsulation and processing are yielding more heat-stable and pH-resistant natural colorants and flavorings, enabling their use in demanding applications like baked goods and dairy products without compromising performance.
Market Restraints
- Input Cost Volatility:Price fluctuations for key raw materials, including cocoa, vanilla, and certain fruit purees, directly impact the cost structure of high-value inclusions and can compress margins for producers.
- Supply Chain Opacity:Achieving full traceability for natural ingredients sourced from diverse agricultural regions presents a significant logistical hurdle, complicating clean-label and ethical sourcing claims for manufacturers.
- Technical Performance Gaps:Certain natural colorants exhibit lower vibrancy, light stability, or heat resistance compared to their synthetic counterparts, limiting their application in specific food systems or requiring complex formulation adjustments.
Strategic Opportunities
- Functional Inclusions:There is a significant opportunity to develop inclusions fortified with functional ingredients like probiotics, fiber, or vitamins, targeting the health and wellness segment within snacks and breakfast cereals.
- Emerging Market Penetration:Targeting the expanding middle class in Southeast Asian and Latin American countries with novel and premium bakery and confectionery products offers a substantial avenue for volume growth.
- Plant-Based Formulations:Creating a portfolio of vegan and allergen-free decorations, such as dairy-free chocolate curls or gluten-free cookie pieces, addresses a clear and expanding consumer dietary preference.
Industry Challenges
- Regulatory Fragmentation:Manufacturers face complexity in navigating disparate international standards for color additives and labeling, such as the differences between FDA requirements in the U.S. and EFSA rules in Europe.
- Agricultural Supply Consistency:Ensuring a stable and high-quality supply of agricultural inputs, like fruits and nuts, is becoming more difficult due to climate change-induced weather events affecting crop yields and quality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Decorations and Inclusions Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.13 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sprinkles, Edible Glitter, Candied Fruits, Chocolate Shavings Application: Baking, Confectionery, Dairy Products, Beverages End User: Bakery, Restaurants, Catering Services, Retailers Ingredient Type: Nuts, Fruits, Sugars, Others |
| Companies Covered | Dawn Food Products, Inc., Barry Callebaut, Cargill, Incorporated, Dr. Oetker, Carroll Industries, Delicia, IRCA S.P.A., HLR Praline, ICAM S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Decorations and Inclusions Market Strategic Shifts & Innovations
The industrialization of artisanal aesthetics is reshaping competitive positioning. Mass-market food producers are now adopting technologies and ingredient strategies to replicate the customized, high-quality appearance previously exclusive to small-scale craft businesses, blurring the lines between standard and premium.
Digital Edible Printing
Digital printing on edible surfaces allows for hyper-detailed, customized images and patterns on inclusions like chocolate discs or fondant sheets. High-end confectioners and specialized bakeries are adopting this for short-run, event-specific products. This technology is miniaturizing the scale of personalization, enabling large manufacturers to offer decorations with a bespoke feel that was once the domain of niche artisans.
Regulatory-Driven Reformulation
Regulatory re-evaluation by the European Food Safety Authority (EFSA) concerning agents like titanium dioxide is forcing widespread product reformulation. This scrutiny creates an immediate need for viable, clean-label opacifiers and whiteners, such as rice starch. The confectionery segment is most affected, accelerating R&D to maintain the visual appeal of products like coated sweets and icings.
Plant-Based Ingredient Shift
A significant demand shift toward plant-based and allergen-free food is now extending to the decorations and inclusions category. This trend is disrupting procurement patterns for traditional ingredients like dairy-based sprinkles or chocolate containing milk solids. This consumer behavior is most visible in North American and European retail channels, where brands are actively marketing vegan-certified toppings.
Food Decorations and Inclusions Market Segmentation
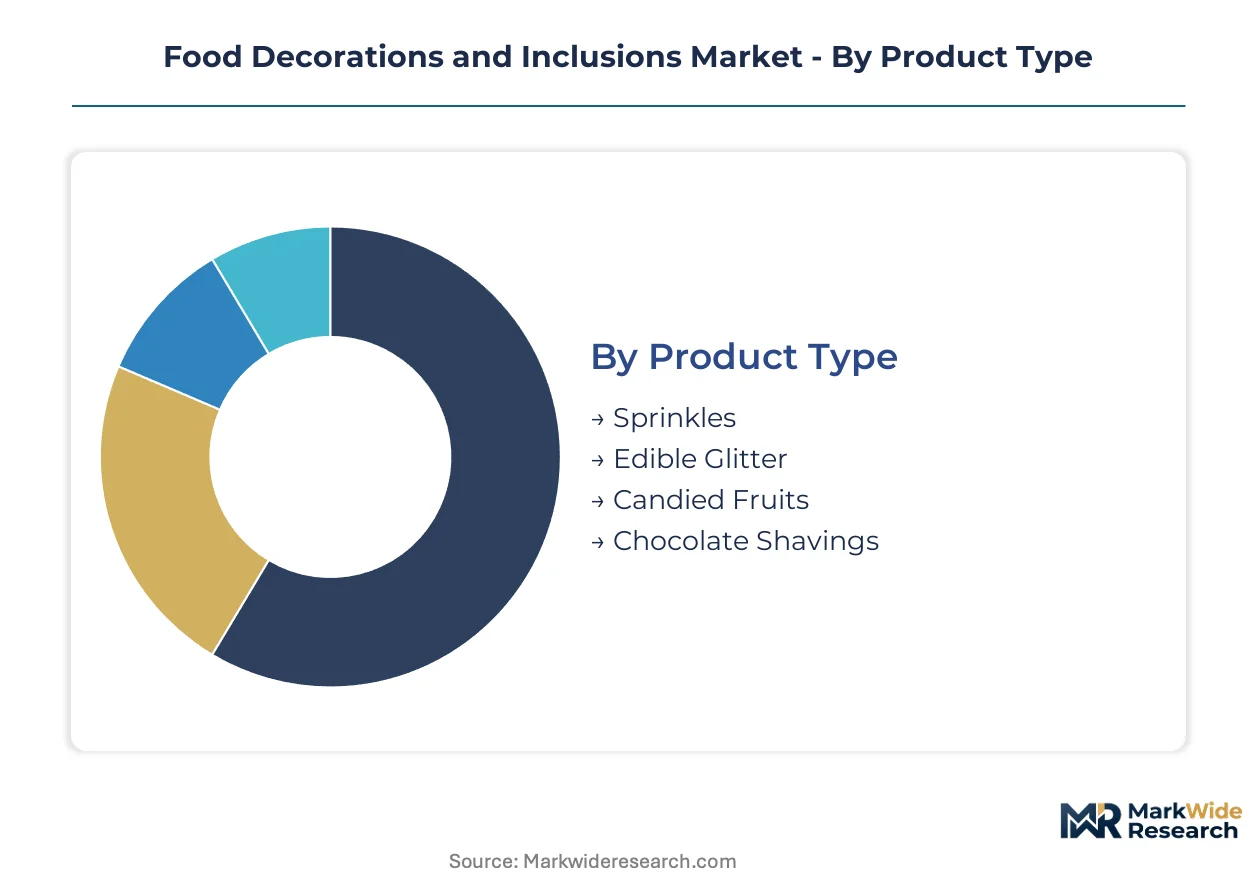
Segmentation provides a granular understanding of the Food Decorations and Inclusions Market, highlighting the diverse product forms, end-use applications, and ingredient compositions that cater to varying consumer and industrial demands. This detailed breakdown reveals distinct value propositions and operational requirements across different market sub-sectors. Analyzing these segments helps manufacturers tailor product development and market entry strategies effectively.
Product Type:
The diverse product types of food decorations and inclusions exhibit varied distribution patterns across different sales channels.
- Chocolate Shavings:Made from cocoa solids, often with high cocoa content for intense flavor and rich color. Demand concentrates in craft confectionery and premium bakery segments, driven by consumer preference for natural, traceable ingredients, particularly in European markets like Germany.
- Sprinkles:Small, colorful sugar confectionery pieces, typically made from sugar, corn syrup, and food coloring. Volume demand is high in the retail bakery channel and for home baking, propelled by their aesthetic appeal and low cost.
- Candied Fruits:Fruit pieces preserved by sugar impregnation, providing chewy texture and natural sweetness. Specialty bakeries and dessert manufacturers utilize these for premium product lines.
- Edible Glitter:Food-grade decorative particles, often made from gum arabic or maltodextrin with approved colorants. Confectionery and event-specific baking applications drive its use for visual impact.
By volume, Sprinkles lead. By growth pace, Chocolate Shavings are ahead, reflecting premiumization trends.
Application:
The application of food decorations and inclusions often dictates the required performance specifications and associated cost structures for manufacturers.
- Baking:Involves ingredients designed to withstand high temperatures and moisture variations during oven processes. Demand is robust in artisanal bakeries for heat-stable fruit inclusions and chocolate pieces, especially in France.
- Confectionery:Focuses on aesthetic appeal and textural contrasts in candies, chocolates, and gums. This segment drives innovation in vibrant natural colorants and unique textural elements, with significant activity in the European market.
- Dairy Products:Incorporates inclusions that maintain texture and color in cold, often acidic, dairy matrices. Yogurts and ice creams are primary end-products for fruit preparations and cookie pieces.
- Beverages:Utilizes smaller, soluble inclusions or decorative elements for visual enhancement and flavor layering. Specialty coffee shops and premium drink manufacturers integrate these for unique offerings.
The Baking and Confectionery segments collectively account for the largest share of market value.
End User:
End-user segments demonstrate distinct purchasing volumes and quality requirements for food decorations and inclusions.
- Bakery:Professional bakeries, ranging from industrial to artisanal, require bulk quantities of inclusions for cakes, pastries, and breads. This segment prioritizes consistent quality and reliable supply chains, especially for clean-label ingredients.
- Retailers:Retail channels, including supermarkets and specialty stores, drive demand for packaged decorations targeting home consumers and smaller professional operations. Consumer trends for convenient, visually appealing baking solutions influence product offerings.
- Restaurants:Foodservice establishments use inclusions for dessert plating and menu innovation, often seeking unique, high-quality decorative elements.
- Catering Services:Caters to events and large-scale food preparation, requiring both aesthetic appeal and logistical efficiency for decorations across diverse menus.
Procurement patterns vary significantly, with large bakeries focusing on bulk ingredients and retailers emphasizing consumer-ready packaging.
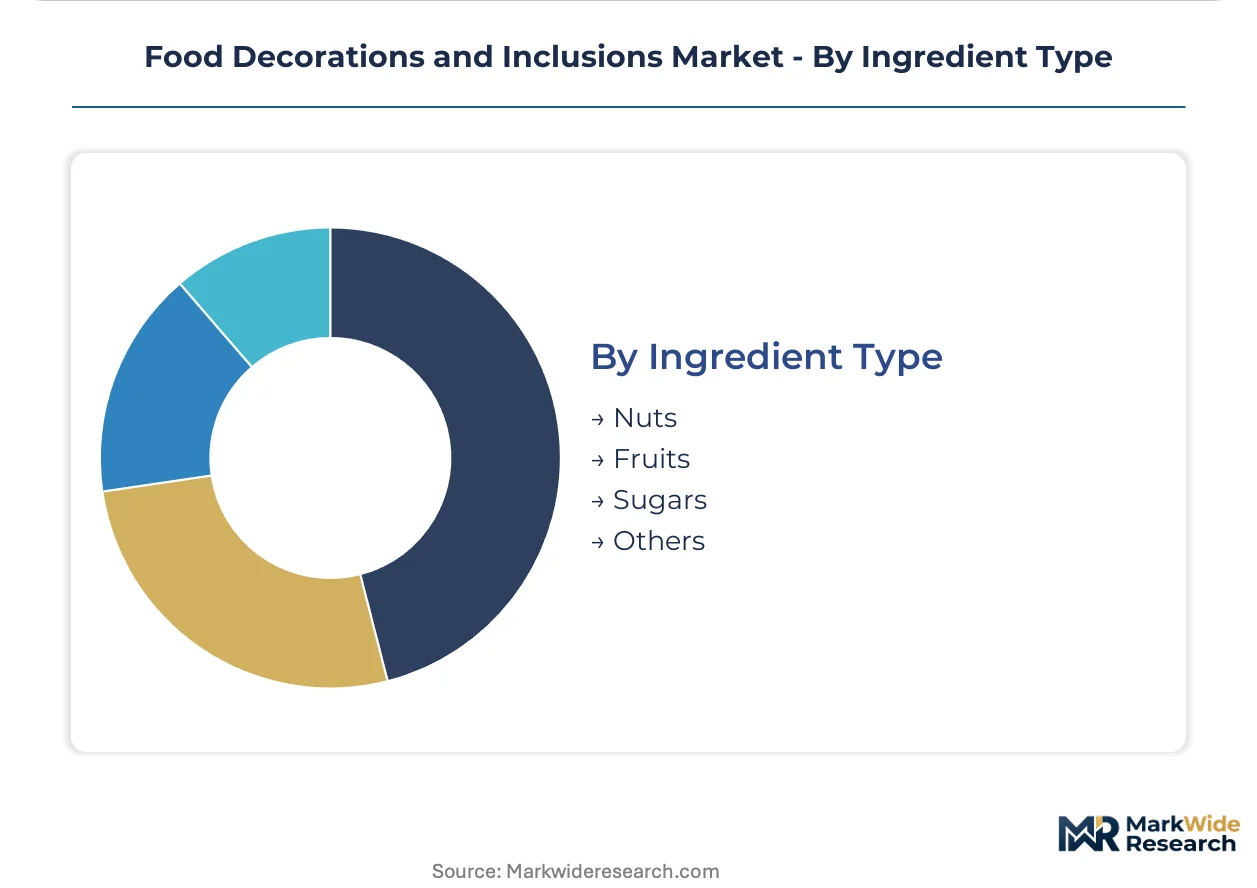
Ingredient Type:
The specific ingredient type significantly influences both the functional properties and the margin profile of the final decoration or inclusion.
- Nuts:Include chopped almonds, pistachios, or hazelnuts, providing texture, flavor, and protein content. Demand for traceable, ethically sourced nuts is expanding in premium confectionery and snack bar applications.
- Fruits:Encompasses candied, dried, or pureed fruit pieces, offering natural sweetness, color, and fiber. Consumer preference for natural ingredients drives demand for fruit inclusions in bakery and dairy products.
- Sugars:Primarily used in sprinkles, icings, and glazes, forming the base for many decorative elements. Innovation focuses on natural colorants and reduced sugar formulations.
- Others:This category includes a diverse range of ingredients like cereals, chocolate derivatives, and edible pearls, providing specialized textures and visual effects.
Volatility in raw material pricing for nuts and fruits introduces complexity into supply chain management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Food Decorations and Inclusions Market exhibits varying supply-side concentrations driven by regional consumer preferences and regulatory environments. European countries, particularly Germany and France, demonstrate strong demand for premium, traceable ingredients due to a flourishing artisanal segment. North America leads in plant-based and functional inclusion innovation, while emerging economies like India and Brazil offer significant volume growth opportunities.
Germany
Demand for clean-label and traceable ingredients drives the premium bakery segment in Germany. The European Food Safety Authority's (EFSA) stricter food additive reviews influence local manufacturers. Craft confectionery producers in Bavaria actively seek unique, high-quality decorations for their specialized products.
France
French artisanal bakeries prioritize heat-stable fruit inclusions and premium chocolate pieces. The European Food Safety Authority's (EFSA) ingredient evaluations shape product development. Lyon's culinary scene fosters innovation in specialized decorative elements for high-end desserts.
United States
United States consumers increasingly seek plant-based and functional inclusions in snacks and breakfast cereals. The U.S. Food and Drug Administration (FDA) maintains strict controls on color additives. Large-scale food manufacturers in the Midwest, like Chicago, integrate diverse inclusions into their product lines.
India
India's expanding middle class fuels demand for novel and premium bakery and confectionery products. The Food Safety and Standards Authority of India (FSSAI) enforces comprehensive labeling requirements. Major food processing hubs in Maharashtra are adapting to these evolving ingredient needs.
Brazil
Brazil presents a substantial avenue for volume growth with its growing consumer base. ANVISA, the national health surveillance agency, regulates food additives and ingredients. Food and beverage companies in São Paulo are exploring innovative decorative elements for local tastes.
Food Decorations and Inclusions Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the Food Decorations and Inclusions Market. The market features a tiered structure, encompassing large, diversified food ingredient suppliers and specialized artisanal ingredient providers. Strategic archetypes include global ingredient powerhouses focusing on scale, regional bakery specialists emphasizing customization, and niche craft ingredient producers targeting premium segments. Portfolio diversification and strategic partnerships are dominant competitive moves among market participants to expand product offerings and geographic reach.
Among global ingredient powerhouses, Barry Callebaut and Cargill, Incorporated exemplify a broad market presence, leveraging extensive sourcing networks to serve diverse food manufacturers. Barry Callebaut, with its deep cocoa expertise, represents a focus on traceable chocolate derivatives for premium applications. Cargill, Incorporated occupies a position as a provider of functional ingredients, including texturizing nuts and fruit pieces for large-scale production. Dawn Food Products, Inc. anchors the specialized bakery channel, providing a wide array of sprinkles and icings to professional and retail bakers, showcasing a concentrated market approach.
| Leading Market Players |
|---|
| Dawn Food Products, Inc. |
| Barry Callebaut |
| Cargill, Incorporated |
| Dr. Oetker |
| Carroll Industries |
| Delicia |
| IRCA S.P.A. |
| HLR Praline |
| ICAM S.p.A. |
| Others |
Cost & Logistics Intelligence
Extended lead times for specialty cocoa and fruit purees directly influence the cost structure for premium inclusions. This supply chain configuration grants pricing power to manufacturers with established sourcing networks.
Pricing Analysis
The European Food Safety Authority's (EFSA) additive regulations dictate the pricing tier structure for many food decorations. Pricing stratifies across premium, standard, and economy tiers, driven by ingredient traceability and certification levels, alongside volume scale for industrial buyers. Pricing softness stems from volatile raw material costs for cocoa and specialty fruits. Home baking consumers exhibit the highest price sensitivity, while high-end confectioners prioritize ingredient quality.
Supply Chain Analysis
Fluctuating inbound logistics costs, particularly for refrigerated fruit shipments across trans-Atlantic routes, impact the supply chain for food inclusions. Supply draws heavily from Côte d'Ivoire for cocoa, Turkey for hazelnuts, and Mediterranean regions for specialty fruits, relying on key raw materials like cocoa beans and fruit purees. Agricultural supply consistency presents a structural risk due to climate change-induced weather events. Distribution runs through specialized food ingredient distributors for industrial clients and retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Food Decorations and Inclusions market is witnessing a buyer-power shift, as large-scale food manufacturers consolidate their ingredient procurement. This dynamic rewards suppliers capable of delivering consistent quality and scale.
For Market Incumbents: Fortify sourcing networks for critical raw materials like cocoa and specialty fruits to mitigate input cost volatility. Invest in advanced R&D for heat-stable natural colorants to counter regulatory-driven reformulation. Enhance traceability certifications for premium ingredients to differentiate against emerging niche craft producers. Expand production capacity in key European markets to serve growing artisanal demand.
For New Entrants and Emerging Players: Differentiate on specialized functional inclusions targeting health and wellness, such as probiotic-fortified sprinkles. Focus on plant-based and allergen-free decorations to penetrate the expanding dietary preference market in North America. The health and wellness segment within breakfast cereals presents a penetrable application. Partner with specialized diet food brands for a targeted go-to-market approach.
For Investors and Strategic Acquirers: Long-term, this sits as a resilient consumer staple play because demand for visually appealing and natural food products remains consistent. Target mid-sized specialists possessing proprietary natural colorant technologies or strong regional brand recognition in Europe. These companies offer established supply chains and innovation capabilities. Accelerated M&A activity among plant-based ingredient providers serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Barry Callebaut can scale production of traceable chocolate decorations for global demand. |
| R&D Investment | Manufacturers can develop heat-stable natural colorants for diverse baking applications. |
| Strategic Partnership | Cargill can secure consistent supply of ethically sourced nuts and fruit pieces. |
| Brand Extension | Dawn Food Products can introduce vegan-certified sprinkles to new consumer segments. |
| Geographic Expansion | Companies can penetrate emerging markets like India with novel bakery ingredients. |
Research Approach
Desk research of regulatory filings, industry association reports, and customs trade data preceded structured interviews with food technologists, procurement managers, and artisanal bakers. This combined approach integrated primary insights with secondary validation. Bottom-up data aggregation and top-down market sizing provided robust triangulation. This methodology ensured comprehensive coverage of market dynamics and competitive landscapes.
Variance decomposition isolated the impact of key market drivers on forecast outcomes across the analysis window. Segmentation dimensions modeled included product type, application, end-user, ingredient type, and regional regulatory cluster. Compound annual growth rates were derived from historical trends and projected growth catalysts. Consumer preference shifts for clean-label products and raw material price volatility served as critical forecast inputs.
Material uncertainties — including geopolitical events and unforeseen regulatory changes — sit outside the modeled envelope. Forecasts reflect assumptions regarding stable market conditions and consistent policy enforcement. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Asia-Pacific Specialty Food Ingredient Market
Specialty Ingredients
Specialty Food Ingredients Market
Specialty Ingredients
Dessert Variegates Market
Specialty Ingredients
Customized Nutrient Premixes Market
Specialty Ingredients
Fermentation Products Market
Specialty Ingredients
Abies Alba (Fir) Leaf Oil Market
Specialty Ingredients
Specialty Mint Oils Market
Specialty Ingredients
Mangosteen Market
Specialty Ingredients
Middle East and Africa Customized Premixes Market
Specialty Ingredients
Pericarp Waste Market
Specialty Ingredients
Aromatherapy Carrier Oil Market
Specialty Ingredients
Specialty Shortenings Market
Specialty Ingredients
Normal and Specialty Fats Market
Specialty Ingredients
Gentian Market
Specialty Ingredients
Personal Care Specialty Ingredients Market
Specialty Ingredients
Vetiver Oil Market