
 Specialty Food Ingredients Market | 2026-2036
Specialty Food Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Food Ingredients Market Analysis
Buyer concentration among dairy processors and large-scale bakery chains is shifting procurement power toward vertically integrated food manufacturers. Kerry Group plc leverages its integrated taste and nutrition platforms to sustain long-term supply agreements with these consolidated buyers. Givaudan differentiates through deep specialization in natural flavor modulators and masking technologies for plant-based applications. Cargill Incorporated anchors its position through backward integration into stevia and fermentation-derived sweetener supply chains.
Specialty food ingredients comprise functionally active compounds—emulsifiers with specific hydrophilic-lipophilic balance values, protein-based stabilizers, and high-intensity sweeteners—engineered to modify texture, extend shelf life, or enhance nutritional profiles in processed foods. Sweeteners and emulsifiers represent the most technically mature categories where margin pools have compressed, while texture improvement functionality is expanding fastest as clean-label reformulations proliferate across sauce manufacturing and confectionery segments. Natural source positioning commands persistent price premiums over synthetic alternatives as bakers and confectioners reformulate to meet retailer clean-label mandates.
FDA GRAS self-affirmation pathways and EPA biofuel coproduct regulations shape ingredient approval timelines and raw material availability for US manufacturers, while EU REACH chemical safety assessments and EFSA novel food authorizations govern market access across European dairy and bakery supply chains. Stakeholders must monitor evolving enzyme engineering capabilities and fermentation scale-up economics to determine whether captive biomanufacturing or strategic outsourcing delivers superior returns on next-generation ingredient portfolios.
Market Dynamics
Precision fermentation scale-up economics and EU Green Deal sustainability mandates are restructuring competitive advantage around captive biomanufacturing capabilities versus outsourced enzyme supply.
Growth Catalysts
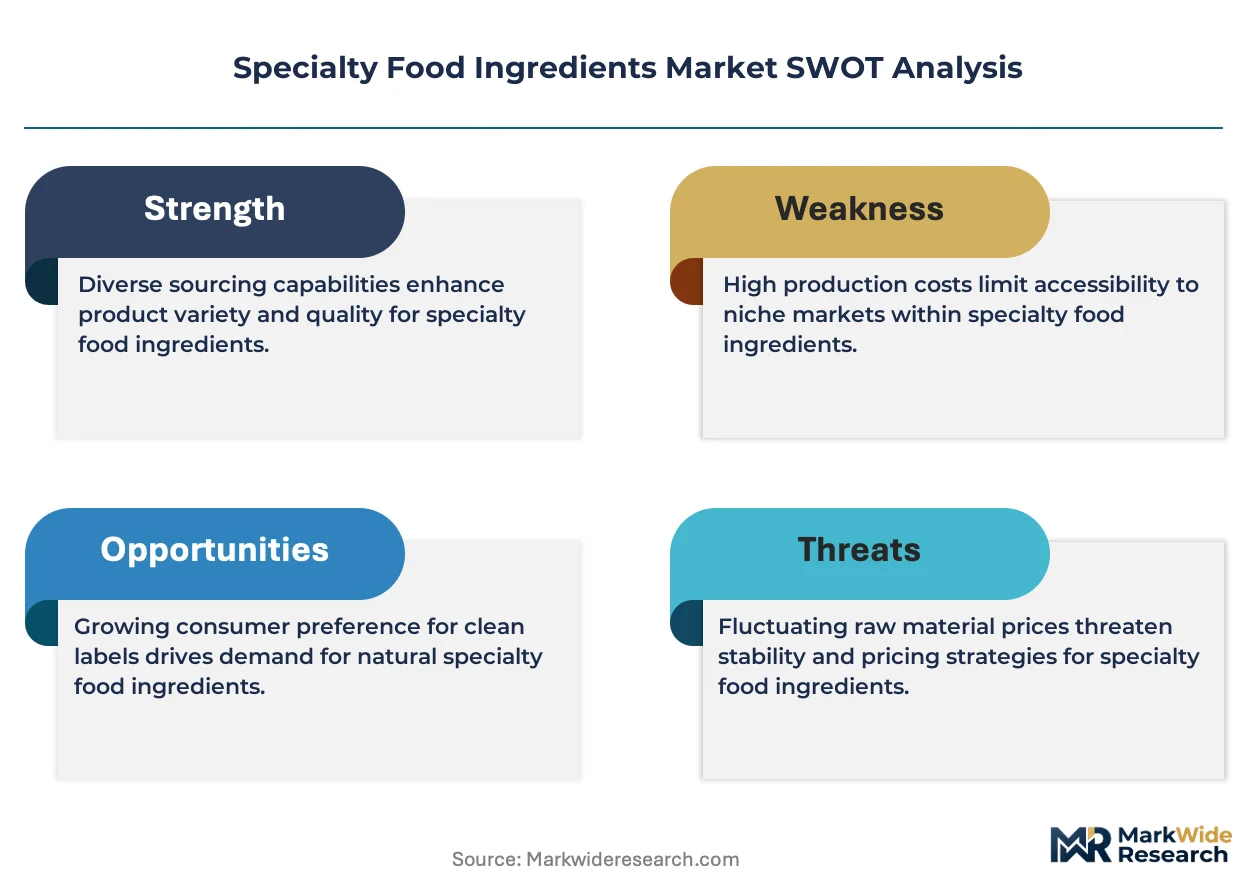
- EU Green Deal mandates:Dairy processors across Germany and France accelerate clean-label reformulations, pulling demand for natural emulsifiers and plant-derived stabilizers into high-volume procurement cycles.
- Precision fermentation hubs:Germany's biotechnology clusters anchor specialty enzyme production, shortening development timelines for novel texture-modifying proteins.
- Novel food authorizations:EFSA streamlined pathways for fermentation-derived ingredients compress regulatory lag, enabling faster commercialization of next-generation sweeteners.
Market Restraints
- Stevia leaf supply volatility:Weather-driven crop failures in China concentrate raw material risk for natural high-intensity sweeteners, squeezing margin pools in technically mature categories.
- REACH compliance burdens:ECHA chemical safety assessments impose documentation costs that disproportionately burden mid-scale emulsifier manufacturers without dedicated regulatory affairs teams.
- Synthetic substitute persistence:Petroleum-derived emulsifiers retain cost advantages in price-sensitive confectionery segments, slowing natural source penetration in emerging markets.
Strategic Opportunities
- Plant-based masking technologies:Flavor modulator demand concentrates in oat milk and pea protein applications where off-note suppression commands persistent price premiums.
- Bakery innovation clusters:Artisan and industrial bakers in Belgium and the Netherlands seek clean-label shelf-life extenders, opening white space for fermentation-derived preservative alternatives.
- CSRD disclosure requirements:Corporate sustainability reporting mandates create procurement preference for ingredients with verified lifecycle assessments and transparent supply chain documentation.
Industry Challenges
- Fermentation scale-up talent scarcity:Bioprocess engineering expertise concentrates in established pharmaceutical hubs, constraining rapid capacity expansion for food-grade enzyme production.
- GRAS self-affirmation complexity:FDA notification pathways for novel proteins require toxicology packages that extend commercialization timelines and elevate legal compliance costs.
- Legacy equipment retrofitting:Dairy and sauce manufacturers face capital intensity in adapting processing lines for heat-sensitive natural stabilizers with narrower temperature tolerance windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Food Ingredients Market |
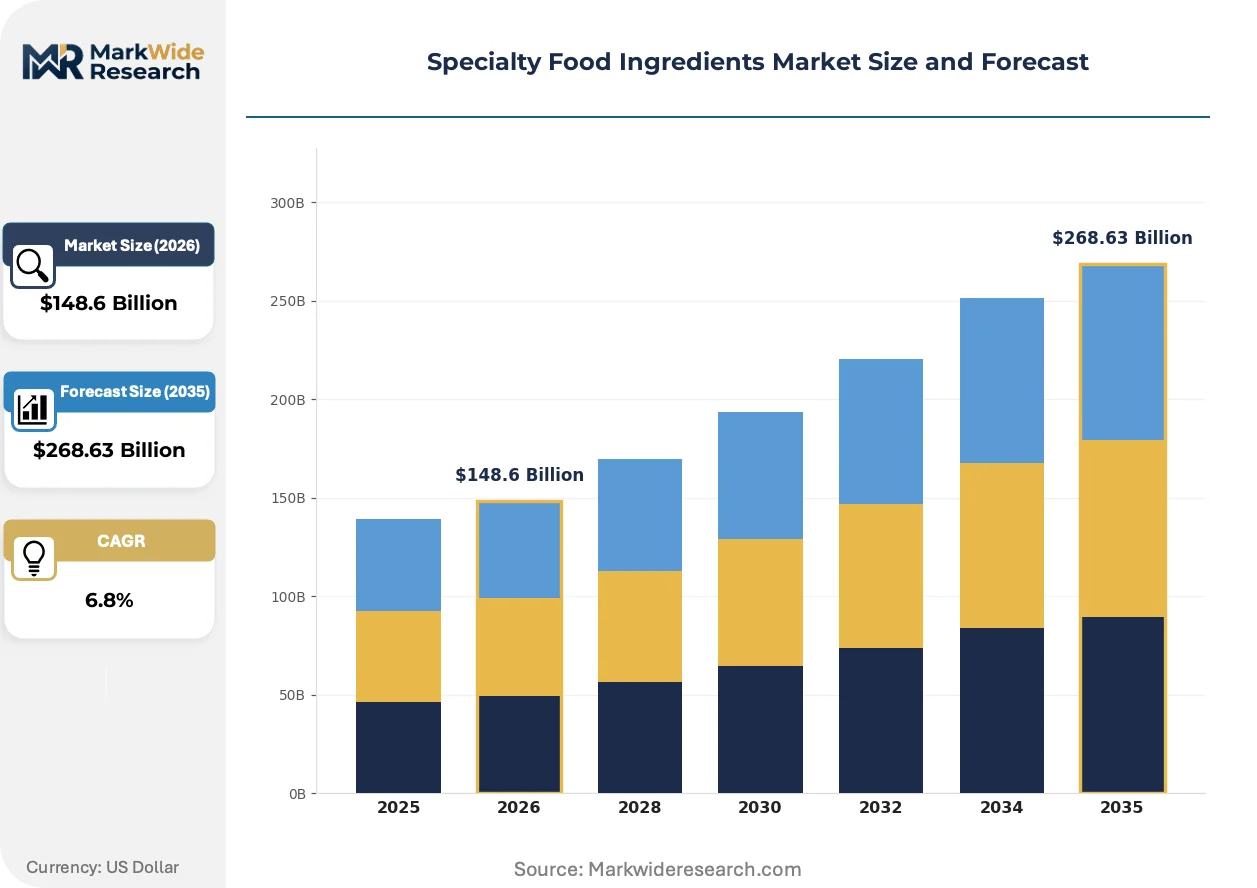
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $268.63 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Emulsifiers, Stabilizers, Thickening Agents, Sweeteners Source: Natural, Synthetic, Organic, Conventional End User: Bakers, Confectioners, Dairies, Sauce Manufacturers Functionality: Texture Improvement, Flavor Enhancement, Shelf Life Extension, Nutritional Value Addition |
| Companies Covered | Kerry Group plc, Givaudan, Cargill Incorporated, DSM, Tate & Lyle PLC, Archer Daniels Midland Company, International Flavors & Fragrances Inc., Sensient Technologies Corporation, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Food Ingredients Market Emerging Trajectories
Biomanufacturing platforms and regulatory disclosure mandates are compressing traditional formulation cycles while rerouting procurement toward traceable, fermentation-derived ingredient portfolios.
Enzyme engineering is converging with computational protein design to accelerate the development of bespoke emulsifiers with precisely tuned hydrophilic-lipophilic balance values. Dairy processors in Denmark and the Netherlands are piloting these tailored solutions at commercial scale. This convergence is displacing commodity lecithin in premium clean-label applications where functional performance must match synthetic benchmarks.
REACH chemical safety assessments and EFSA novel food authorizations are tightening documentation requirements for imported enzyme preparations and plant extracts. Manufacturers now face extended pre-market approval timelines that compress first-mover advantage windows. Bakery and confectionery segments are responding by consolidating supplier bases toward vertically integrated producers with in-house regulatory affairs capabilities.
Buyer concentration among multinational dairy cooperatives and retail-owned bakery chains is compressing switching cycles and elevating price transparency. Long-term supply agreements with volume guarantees are displacing spot-market purchasing in sweetener and stabilizer categories. This pattern is most visible in Germany and France where procurement power has concentrated among three to four vertically integrated food manufacturers.
Specialty Food Ingredients Market Segmentation
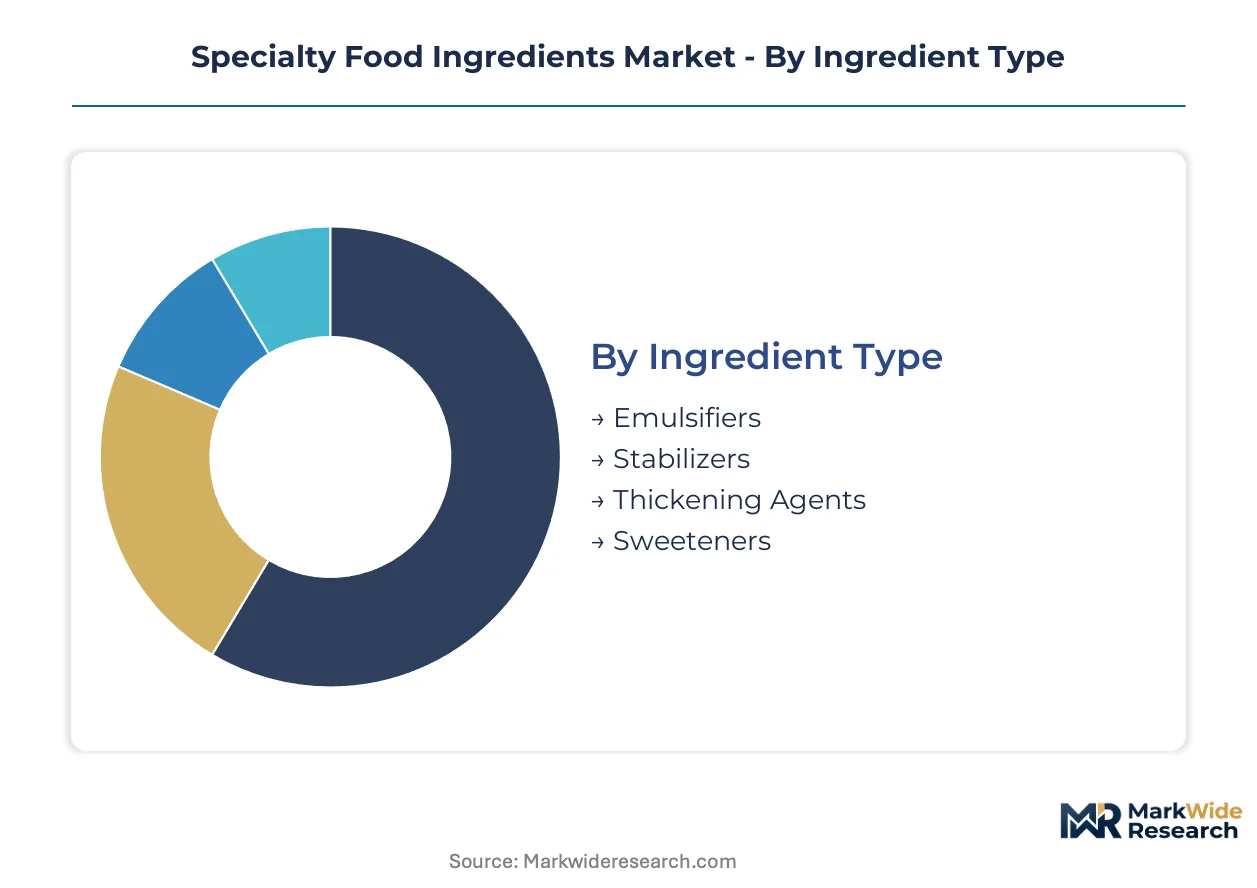
Specialty food ingredients demand fragments across technical specifications, sourcing philosophies, and end-use processing requirements. Procurement patterns diverge sharply between commodity-scale dairy operations and precision-driven artisan bakeries, reshaping supplier portfolio strategies.
Ingredient Type:
Volume concentrates in mature hydrocolloid categories while premium flows toward fermentation-derived alternatives with precise functional tuning.
- Emulsifiers:Surface-active agents with calibrated hydrophilic-lipophilic balance values control fat-water interfaces in clean-label reformulations. German dairy cooperatives and French sauce manufacturers dominate procurement, driven by EU Green Deal mandates phasing out synthetic alternatives.
- Sweeteners:High-intensity compounds—stevia glycosides, monk fruit extracts, and fermentation-derived molecules—deliver sweetness without caloric load. Demand clusters in US beverage and confectionery segments where FDA GRAS self-affirmation pathways enable faster commercialization than EFSA novel food routes.
- Stabilizers:Protein and polysaccharide systems maintain suspension and prevent syneresis in plant-based applications.
- Thickening Agents:Modified starches and hydrocolloids build viscosity in reduced-fat formulations.
Mature deployment sits with emulsifiers. Newer deployment is concentrated in sweeteners.
Source:
Certification tiering separates procurement pools between mass-market conventional supply and premium-track organic and fermentation-derived positioning.
- Natural:Plant-extracted and fermentation-derived compounds command persistent price premiums in clean-label channels. EU REACH documentation burdens and EFSA novel food authorizations constrain import flexibility for non-EU suppliers.
- Synthetic:Petroleum-derived emulsifiers and high-intensity sweeteners retain cost advantages in price-sensitive emerging markets. Confectionery manufacturers in Southeast Asia and Latin America continue procurement despite retailer pressure in premium channels.
- Organic:Certified supply chains with full traceability documentation attract sustainability-linked procurement from retail-owned bakery chains.
- Conventional:Standard agricultural sourcing without certification differentiation serves cost-optimized processed food segments.
Volume leadership belongs to conventional sourcing. Value expansion is climbing fastest in natural.
End User:
Customer scale and technical sophistication determine specification stringency and supplier relationship intensity.
- Dairies:Large-scale processors in Denmark and the Netherlands drive demand for heat-stable natural stabilizers in extended-shelf-life applications. Precision fermentation hubs in Germany shorten development cycles for bespoke protein-based texture systems.
- Bakers:Artisan and industrial segments in Belgium seek clean-label shelf-life extenders without calcium propionate. Fermentation-derived preservative alternatives gain trial in premium bread and pastry lines.
- Confectioners:Chocolate and candy manufacturers balance cost targets with clean-label mandates from retail partners.
- Sauce Manufacturers:Emulsion stability and freeze-thaw tolerance dominate specification requirements in condiment and dressing applications.
Established integration characterizes dairies. Accelerating reformulation activity is concentrating in bakers.
Functionality:
Technical performance requirements map directly to formulation complexity and regulatory scrutiny intensity.
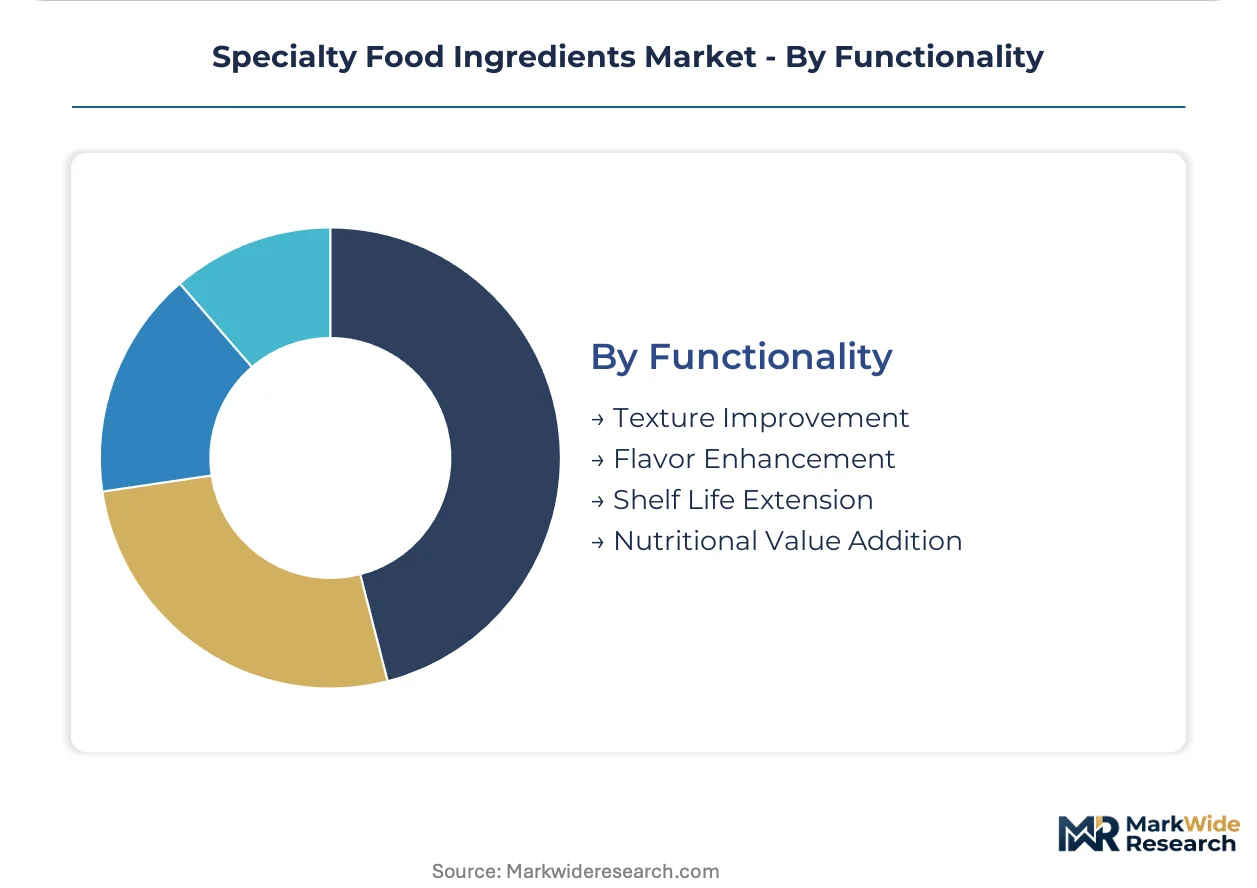
- Texture Improvement:Viscosity building, gelation, and mouthfeel modulation represent the most technically active innovation frontier. Computational protein design converges with enzyme engineering to accelerate bespoke emulsifier development for oat milk and pea protein applications.
- Shelf Life Extension:Natural antioxidant and antimicrobial systems replace synthetic preservatives in clean-label reformulations. Bakery clusters in the Netherlands pilot fermentation-derived alternatives to sorbates and benzoates.
- Flavor Enhancement:Modulators and masking technologies suppress off-notes in plant-based proteins and high-intensity sweetener systems.
- Nutritional Value Addition:Protein fortification, fiber enrichment, and micronutrient delivery serve health-positioned product development.
Deep technical maturity defines shelf life extension. Steepest expansion trajectory is gaining share fastest in texture improvement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates among dairy processors in Germany and France, with bakery innovation clusters in Belgium and the Netherlands driving procurement for clean-label reformulations. Precision fermentation hubs in southern Germany and regulatory alignment around EU Green Deal mandates are redrawing competitive geography.
Germany
Dairy cooperatives in Bavaria and North Rhine-Westphalia drive bulk procurement of natural emulsifiers for extended-shelf-life applications. EFSA novel food authorizations for fermentation-derived ingredients compress regulatory lag, enabling faster commercialization. The precision fermentation corridor between Munich and Heidelberg anchors specialty enzyme production for texture-modifying proteins.
France
Sauce manufacturers in Île-de-France and Lyon cluster demand heat-stable natural stabilizers for clean-label condiment lines. EU REACH chemical safety assessments govern import documentation for enzyme preparations from non-EU suppliers. The Auvergne-Rhône-Alpes region hosts pilot facilities for bespoke protein-based texture systems in plant-based dairy alternatives.
United States
Beverage and confectionery segments concentrate demand for high-intensity sweeteners where FDA GRAS self-affirmation pathways enable faster commercialization than European routes. EPA biofuel coproduct regulations shape raw material availability for fermentation-derived ingredients. California and Illinois anchor formulation R&D for natural flavor modulators in oat milk applications.
Belgium
Artisan and industrial bakers seek clean-label shelf-life extenders without calcium propionate, creating white space for fermentation-derived preservative alternatives. CSRD disclosure requirements elevate procurement preference for ingredients with verified lifecycle assessments. The Flanders region hosts bakery innovation clusters testing natural antioxidant systems in premium bread lines.
Netherlands
Dairy processors in Friesland and Gelderland pilot heat-sensitive natural stabilizers with narrower temperature tolerance windows than synthetic alternatives. ECHA chemical safety assessments impose documentation costs that favor suppliers with dedicated regulatory affairs teams. The Wageningen food valley anchors collaborative R&D between ingredient suppliers and dairy manufacturers on next-generation texture systems.
Specialty Food Ingredients Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue fermentation-derived specialties and computational protein design. The vendor base stratifies between vertically integrated nutrition platforms and focused flavor technology specialists. Two archetypes dominate: integrated taste-and-nutrition conglomerates with captive biomanufacturing, and precision specialists in natural masking and modulation. Competitive moves center on backward integration into fermentation supply chains and strategic partnerships with precision fermentation startups.
Within the integrated platform tier, Kerry Group plc and Cargill Incorporated exemplify scale-driven positioning through combined taste, nutrition, and upstream supply chain control. Givaudan occupies a specialist position in natural flavor modulators and masking technologies. These three entities represent contrasting strategic bets: captive biomanufacturing scale versus deep specialization in sensory performance for plant-based applications.
| Leading Market Players |
|---|
| Kerry Group plc |
| Givaudan |
| Cargill Incorporated |
| DSM |
| Tate & Lyle PLC |
| Archer Daniels Midland Company |
| International Flavors & Fragrances Inc. |
| Sensient Technologies Corporation |
| Ingredion Incorporated |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap producers in Belgium and the Netherlands anchor premium-tier supply for clean-label bakery applications, tightening pricing discipline through controlled volume release and long-term contract structures that resist spot-market volatility.
Pricing Analysis
Volume concentrates in technically mature emulsifier categories where margin pools have compressed, while premium flows toward fermentation-derived alternatives with precise functional tuning. Three-tier pricing structure across premium, standard, and economy levels separates certified organic supply from conventional agricultural sourcing and synthetic petroleum-derived alternatives. Cost compression in standard-tier emulsifiers is intensifying because stevia leaf supply volatility concentrates raw material risk. Confectionery manufacturers in Southeast Asia exhibit highest price sensitivity; dairy cooperatives in Germany and Denmark demonstrate lowest sensitivity due to sustainability-linked procurement mandates.
Supply Chain Analysis
Bioprocess engineering talent scarcity in southern Germany and Denmark constrains rapid capacity expansion for food-grade enzyme production, elevating wage premiums for fermentation specialists and extending project timelines for new manufacturing facilities. Raw material supply draws from Chinese stevia cultivation, German precision fermentation hubs, and Indian botanical extraction clusters. Single-source vulnerability concentrates in fermentation-derived protein supply where pharmaceutical-sector competition for bioreactor capacity elevates allocation risk. Distribution runs through vertically integrated nutrition platforms with captive regulatory affairs capabilities serving consolidated dairy and bakery chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH chemical safety assessments and EFSA novel food authorizations impose documentation burdens that create barrier-to-entry moats favoring incumbent suppliers with dedicated regulatory affairs teams and established approval track records.
For Market Incumbents: Acquire precision fermentation capacity in the Munich-Heidelberg corridor to secure captive supply of texture-modifying proteins. Consolidate supplier relationships with German dairy cooperatives through volume-guaranteed long-term agreements that lock out emerging competitors. Elevation of EFSA novel food documentation requirements threatens mid-scale emulsifier manufacturers lacking in-house regulatory capabilities. Backward integration into stevia and monk fruit extraction supply chains defends margin position against raw material volatility. For New Entrants and Emerging Players: The premium-to-economy price gap in natural shelf-life extenders offers white-space entry for fermentation-derived preservative alternatives targeting Belgian artisan bakers. Target oat milk and pea protein applications where off-note suppression commands persistent price premiums and incumbent flavor modulator portfolios remain underdeveloped. Belgium and the Netherlands present most penetrable geographies given CSRD disclosure requirements elevating procurement preference for verified lifecycle assessments. Go-to-market through bakery innovation clusters in Flanders enables rapid trial-to-adoption conversion without direct confrontation with integrated nutrition platforms. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale emulsifier specialists in France and Germany facing REACH compliance cost escalation without scale economies to absorb regulatory burden. Long-term viability over the projection horizon rests on positioning for fermentation scale-up economics as clean-label mandates displace synthetic alternatives. Target acquisition archetype: precision fermentation startups with validated protein engineering platforms and pending EFSA novel food dossiers. Watch EFSA authorization velocity for fermentation-derived ingredients as inflection indicator for competitive repositioning timing.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Captive biomanufacturing in German hubs shortens development timelines for bespoke texture-modifying proteins. |
| Backward Integration into Botanical Supply | Upstream control over stevia and monk fruit extraction mitigates weather-driven raw material risk concentration. |
| Regulatory Affairs Capability Buildout | In-house EFSA novel food dossier expertise compresses approval timelines and elevates competitive moats. |
| Long-Term Supply Agreement Consolidation | Volume guarantees with German dairy cooperatives displace spot-market purchasing and lock out emerging entrants. |
| Clean-Label Shelf-Life Extender Development | Fermentation-derived preservative alternatives address Belgian baker demand for calcium propionate replacements. |
Methodological Framework
Document review covered EFSA novel food authorization databases, EU REACH registration dossiers, and trade flow records from German and French customs authorities, complemented by interviews with regulatory affairs directors at major emulsifier manufacturers, procurement leads at Dutch dairy cooperatives, and technical R&D heads at Belgian bakery ingredient suppliers. Secondary validation drew from SEC filings of listed nutrition platforms, industry association reports from FoodDrinkEurope, and patent filings in computational protein design. Bottom-up volume estimates from end-use segment consumption patterns were triangulated against top-down production capacity assessments across precision fermentation facilities.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to calibrate growth assumptions across the analysis window. The analytical framework modeled segmentation across ingredient type, source certification tier, end-user processing scale, and functionality requirement. CAGRs were derived from regression analysis of historical consumption patterns adjusted for regulatory mandate implementation schedules and fermentation scale-up economics. Industry-specific forecast inputs included EFSA authorization pipeline velocity and bioreactor capacity allocation trends between pharmaceutical and food-grade applications.
Inputs from EFSA and ECHA regulatory databases were available through the study window; gaps in real-time production capacity utilization data from private fermentation facilities introduce uncertainty bands around near-term supply elasticity assumptions. Forecasts reflect documented assumptions regarding clean-label mandate adoption timelines and precision fermentation cost reduction curves. Material deviation in EFSA novel food authorization velocity or stevia crop yield volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Grape Seed Extract in Pet Food Application Market
Specialty Ingredients
Personal Care Specialty Ingredients Market
Specialty Ingredients
Green Sic Market
Specialty Ingredients
Specialty Carbohydrates Market
Specialty Ingredients
Normal and Specialty Fats Market
Specialty Ingredients
Middle East and Africa Customized Premixes Market
Specialty Ingredients
Middle East and Africa Specialty Food Ingredients Market
Specialty Ingredients
Specialty Beverage Stabilizers Market
Specialty Ingredients
Vanilla Extract Alternatives Market
Specialty Ingredients
Mangosteen Extract Market
Specialty Ingredients
Dessert Variegates Market
Specialty Ingredients
Specialty Ingredients Market
Specialty Ingredients
Agarwood Essential Oil Market
Specialty Ingredients
Benzoe Siam Market
Specialty Ingredients
Gentian Market
Specialty Ingredients
Pomegranate Seed Oil Nutricosmetic Ingredients Market