
 Vegetable Powder Market | 2026-2036
Vegetable Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Vegetable Powder Market Intelligence
Buyer concentration among food and beverage multinationals is decoupling as specialty nutraceutical startups fragment procurement across smaller batch suppliers. GlobalVeg Ingredients leverages backward integration into contract farming networks across multiple climate zones. PureVeg Powders Inc. sustains R&D intensity in low-temperature dehydration patents that preserve heat-sensitive phytonutrients. Olam Food Ingredients anchors its position through bulk container logistics that reduce per-unit shipping costs for industrial buyers.
Vegetable powder consists of dehydrated, milled vegetable tissue typically processed through spray-drying, drum-drying, or freeze-drying to achieve moisture content below 6%, preserving fiber, vitamins, and polyphenols for shelf-stable food fortification and supplement applications. Carrot powder and beetroot powder dominate volume flows into beverage coloring and natural sweetener channels, while spinach powder commands premium positioning in infant nutrition and clinical dietary formulations. Beetroot powder specifically is gaining traction in sports nutrition applications where nitrate content drives functional positioning.
The FDA enforces Good Manufacturing Practice standards for vegetable powders sold as dietary ingredients, while the USDA Organic seal governs certification premiums in North American retail channels. BIS in India mandates heavy metal and microbial testing protocols that determine export eligibility to Middle Eastern and European markets. Stakeholders must monitor evolving pesticide maximum residue limits across destination jurisdictions, as regulatory divergence between FDA tolerances and EU EFSA standards threatens to bifurcate sourcing requirements for multinational suppliers.
Market Dynamics
Clean-label procurement mandates from food and beverage multinationals are forcing vegetable powder suppliers to restructure upstream sourcing, traceability systems, and certification portfolios simultaneously.
Growth Catalysts
- FDA Dietary Supplement Labeling Updates:Tightened purity and origin documentation requirements in the United States are accelerating investment in batch-level traceability infrastructure across supplier networks.
- India PLI Scheme Incentives:Domestic production capacity for export-grade vegetable powders is expanding rapidly as manufacturers leverage BIS certification pathways to access Middle Eastern and European markets.
- Spray-Drying Technology Maturation:Continuous processing systems are reducing moisture variability below 6% thresholds, enabling longer shelf stability for beverage and infant nutrition applications.
Market Restraints
- Input Cost Volatility:Fresh vegetable procurement costs fluctuate with seasonal weather patterns across Mediterranean and North American growing regions, compressing margin predictability.
- Regulatory Divergence:Pesticide maximum residue limits under FDA tolerances and EU EFSA standards are bifurcating, forcing dual-compliance inventory strategies for multinational suppliers.
- Freeze-Drying Capital Intensity:Low-temperature dehydration equipment requires substantial upfront investment, limiting entry for mid-scale processors seeking heat-sensitive phytonutrient preservation capabilities.
Strategic Opportunities
- Sports Nutrition Functional Positioning:Beetroot powder nitrate content is creating new application white space in pre-workout formulations and athletic recovery products.
- Clinical Dietary Formulations:Spinach powder micronutrient density is penetrating hospital and therapeutic nutrition channels previously dominated by synthetic fortification.
- Contract Farming Backward Integration:Direct control over multi-climate zone cultivation is reducing intermediary costs and securing pesticide-free raw material pipelines for organic certification premiums.
Industry Challenges
- Heat-Sensitive Compound Retention:Vitamin C and polyphenol degradation during conventional drum-drying processes requires process engineering expertise that remains scarce in emerging production regions.
- Cross-Jurisdictional Certification Timelines:Simultaneous USDA Organic, EU Organic, and BIS compliance audits extend product launch cycles by 8-14 months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegetable Powder Market |
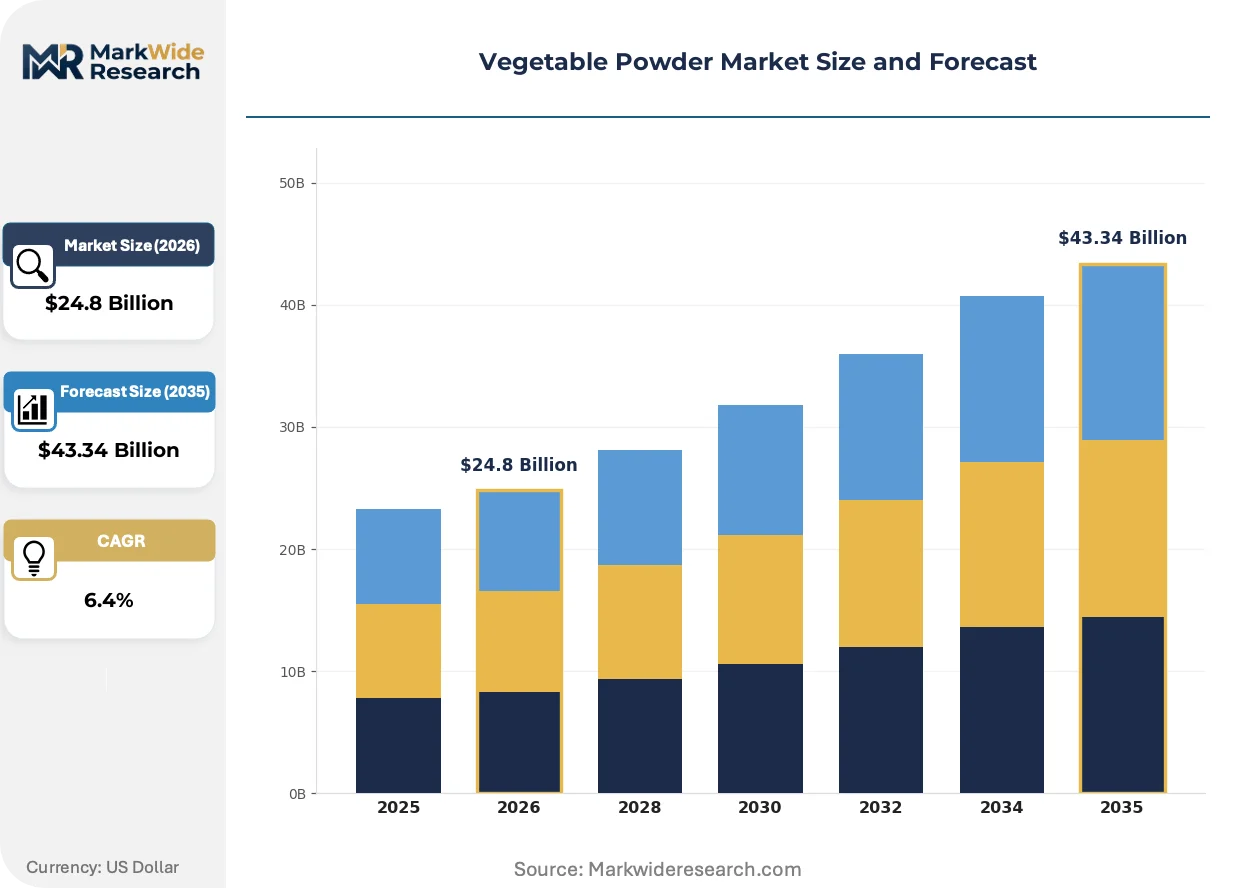
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carrot Powder, Spinach Powder, Beetroot Powder, Broccoli Powder Packaging Type: Bags, Bottles, Pouches, Bulk Containers End User: Food & Beverage, Pharmaceutical, Nutraceutical, Cosmetics Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | OrganicRoots Manufacturing, GlobalVeg Ingredients, GreenHarvest Organics, ShunDi Foods, Olam Food Ingredients, PureVeg Powders Inc., VitaPowder Global, BCFoods Inc., HarvestBulk Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegetable Powder Market Strategic Shifts & Innovations
Dehydration technology convergence with precision agriculture data systems is reshaping how vegetable powder producers optimize yield, quality, and traceability across dispersed farming networks.
Low-temperature vacuum belt drying is unifying the previously separate objectives of moisture reduction and bioactive compound preservation. Nutraceutical formulators in Germany and Japan are adopting these systems at pilot scale. This convergence is compressing the performance gap between artisan freeze-dried products and mass-market spray-dried alternatives.
REACH chemical registration requirements and evolving EU EFSA novel food opinions are tightening ingredient qualification pathways for vegetable powders entering European supplement channels. Manufacturers must now submit comprehensive toxicological dossiers for non-traditional vegetable sources. Beetroot and kale powders face heightened scrutiny, prompting suppliers to pre-validate safety data packages before market entry.
Direct-to-manufacturer sourcing contracts are displacing traditional ingredient distributor intermediaries in North American and European procurement patterns. Large beverage brands now negotiate volume commitments directly with dehydration facilities, bypassing regional wholesalers. This channel compression is most visible in carrot powder procurement for natural coloring applications, where price transparency pressures are restructuring margin allocation across the value chain.
Vegetable Powder Market Segmentation
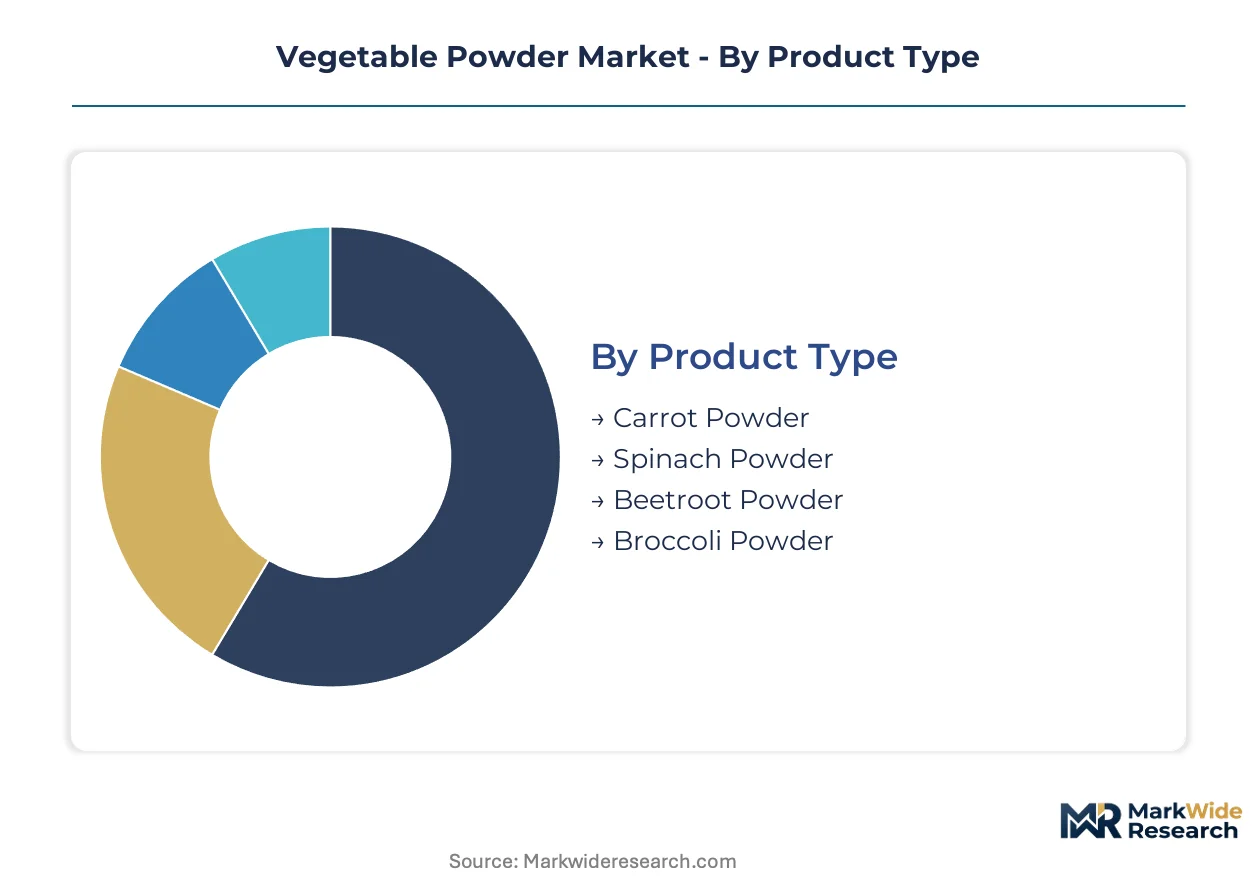
Segmentation in vegetable powders reveals how dehydration technology maturity and certification tiers create distinct procurement pathways. Buyers select product formats and packaging configurations based on end-use shelf stability requirements and traceability mandates.
Product Type:
Upgrade cycles in dehydration equipment are pushing processors toward higher-value powders that retain heat-sensitive compounds through low-temperature methods.
- Carrot Powder:Beta-carotene concentration between 1,000-2,000 IU per gram makes this the standard reference for natural orange coloring in beverage applications. Demand concentrates in North American clean-label beverage manufacturing where FDA color additive regulations favor vegetable-derived alternatives over synthetic dyes.
- Beetroot Powder:Nitrate content of 300-400 mg per 100g enables functional positioning in sports nutrition pre-workout formulations. German and Japanese nutraceutical formulators are expanding procurement volumes for nitric oxide pathway products targeting athletic performance segments.
- Spinach Powder:Iron and folate density supports premium positioning in infant nutrition and clinical dietary channels requiring micronutrient fortification without synthetic additives.
- Broccoli Powder:Sulforaphane preservation challenges limit supply to freeze-dried processing, constraining volume but maintaining price premiums in oncology-focused supplement formulations.
Carrot powder sits at the top of the volume ranking, with beetroot powder climbing the fastest.
Packaging Type:
Cost tier differentiation separates commodity bulk flows from value-added retail-ready formats requiring oxygen barrier properties.
- Bulk Containers:Industrial totes and fiber drums moving 500-1,000 kg lots dominate ingredient manufacturer procurement, with Olam Food Ingredients leveraging container logistics to compress per-unit shipping costs for multinational beverage clients.
- Pouches:Stand-up pouches with resealable closures and high-barrier metallized films command 40-60% price premiums over bags in direct-to-consumer channels, reflecting moisture protection investments for humid climate distribution.
- Bags:Multi-wall paper and polyethylene laminates serve mid-scale food processors seeking 10-25 kg intermediate packaging with moderate shelf stability.
- Bottles:PET and glass containers with desiccant closures target premium supplement retail shelves where visual transparency and dispensing precision justify higher packaging costs.
Bulk containers capture the largest shipment volumes, though pouches are gaining share fastest in e-commerce direct-to-consumer channels.
End User:
Application-specific certification requirements create divergent procurement specifications across customer types.
- Food & Beverage:Clean-label mandates from multinational manufacturers drive batch-level traceability investments, with carrot powder procurement shifting toward direct manufacturer contracts that bypass traditional distributor intermediaries.
- Nutraceutical:Sports nutrition and clinical dietary segments command premium pricing for beetroot and spinach powders with validated bioactive compound retention, requiring low-temperature dehydration patents that preserve heat-sensitive phytonutrients.
- Pharmaceutical:Excipient-grade vegetable powders face USP and EP monograph compliance, with heavy metal and microbial testing protocols extending qualification timelines.
- Cosmetics:Topical antioxidant applications in skincare formulations represent emerging demand for broccoli and spinach powders with polyphenol preservation claims.
Food and beverage sits at the top of the volume ranking, with nutraceutical climbing the fastest as functional positioning expands.
Distribution Channel:
Channel compression is restructuring margin allocation as volume buyers bypass intermediaries.
- Wholesale:Traditional ingredient distributors retain relevance for mid-scale processors lacking direct supplier relationships, though price transparency pressures are compressing margins.
- Online Retail:Amazon and specialized ingredient marketplaces enable small-batch procurement for specialty nutraceutical startups fragmenting demand across smaller suppliers.
- Supermarkets:Mass retail channels move consumer-packaged vegetable powders with USDA Organic seal premiums, requiring brand marketing investments that industrial channels avoid.
- Specialty Stores:Health food and supplement retailers target premium positioning with BIS-certified and EU Organic dual-labeled products for export-quality positioning.
Wholesale retains the largest transaction volume, with online retail expanding most quickly as digital procurement platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium pricing for sports nutrition-grade beetroot powder, while India scales export volumes through BIS-certified dehydration facilities serving Middle Eastern buyers.
United States
Clean-label beverage manufacturers drive carrot powder procurement for natural coloring applications. FDA dietary supplement labeling updates mandate batch-level traceability infrastructure investments. California's Central Valley dehydration clusters process tomato and spinach powders for infant nutrition brands.
Germany
Nutraceutical formulators expand beetroot powder volumes for nitric oxide pathway sports products. REACH chemical registration requirements tighten novel food qualification timelines. Bavarian processing facilities pilot low-temperature vacuum belt drying systems for sulforaphane preservation.
India
Domestic PLI scheme incentives accelerate export-grade production capacity expansion. BIS certification protocols determine Middle Eastern and European market eligibility. Maharashtra and Gujarat dehydration hubs leverage contract farming networks for pesticide-free raw material security.
China
Industrial-scale spray-drying equipment manufacturers serve Asian beverage fortification demand. GB standards govern heavy metal and microbial testing for domestic distribution. Shandong Province processing zones concentrate drum-drying capacity for carrot and beetroot commodity flows.
Japan
Functional food manufacturers import freeze-dried broccoli powder for oncology-focused supplement formulations. METI guidelines influence novel ingredient safety assessment protocols. Chubu region pilot facilities test precision agriculture data integration with dehydration quality control systems.
Vegetable Powder Market Key Industry Players
North American producers anchor one tier; Indian specialists hold contract farming advantages. The supplier base fragments across dehydration technology tiers rather than consolidating around scale leaders. Three archetypes dominate: integrated agribusiness operators with captive cultivation, patent-holding low-temperature dehydration specialists, and regional commodity processors serving price-sensitive beverage channels. Capacity expansion and backward integration into multi-climate farming networks represent the dominant competitive vectors.
Within the integrated agribusiness tier, Olam Food Ingredients and GlobalVeg Ingredients exemplify scale-driven logistics optimization and contract farming control respectively. PureVeg Powders Inc. occupies a position among technology specialists focused on heat-sensitive compound preservation. These three anchors illustrate how geographic origin and structural approach differentiate competitive positioning without requiring identical strategic moves.
| Leading Market Players |
|---|
| OrganicRoots Manufacturing |
| GlobalVeg Ingredients |
| GreenHarvest Organics |
| ShunDi Foods |
| Olam Food Ingredients |
| PureVeg Powders Inc. |
| VitaPowder Global |
| BCFoods Inc. |
| HarvestBulk Co. |
| Others |
Cost & Logistics Intelligence
Clean-label procurement mandates from multinational beverage manufacturers are forcing vegetable powder suppliers to restructure upstream sourcing and certification portfolios, compressing margin allocation and amplifying price sensitivity at the commodity tier.
Pricing Analysis
Capacity additions in India are reshaping price floors for export-grade vegetable powders as BIS-certified facilities expand output for Middle Eastern buyers. Three-tier pricing structure across premium, standard, and economy levels stratifies by dehydration technology and certification tier, with freeze-dried broccoli powder commanding substantial premiums over spray-dried carrot alternatives. Price differentiation hinges on validated bioactive compound retention and dual USDA-EU Organic labeling. Cost compression in standard-grade drum-dried powders is intensifying because of input volatility across Mediterranean growing regions. Mid-scale food processors exhibit highest price sensitivity, while clinical nutrition formulators prioritize heat-sensitive phytonutrient preservation over unit economics.
Supply Chain Analysis
Return flows of non-conforming powder lots for reprocessing or alternative-channel disposition create reverse-logistics complexity for dehydration facilities managing multi-customer contracts. Geographic concentration centers on India, China, and the United States, with Maharashtra and Gujarat hubs leveraging contract farming networks for pesticide-free raw material security. Fresh vegetable inputs draw from seasonal Mediterranean, North American, and Indian growing regions, creating harvest-timing coordination challenges. Single-source vulnerability runs through freeze-drying equipment suppliers concentrated in Germany and Japan. Distribution runs through direct-to-manufacturer contracts displacing traditional wholesale intermediaries, with bulk container logistics serving multinational beverage clients and specialized pouches reaching e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vegetable powder market functions as a stable compounder anchored by irreversible clean-label substitution trends across food, beverage, and nutraceutical formulations.
For Market Incumbents: To counter regulatory divergence between FDA tolerances and EU EFSA pesticide residue standards, established processors should pursue backward integration into multi-climate contract farming networks securing organic certification premiums. Dual-compliance inventory strategies require batch-level traceability infrastructure investments that smaller competitors cannot replicate. Capacity additions in Indian BIS-certified facilities will defend margin position against emerging regional commodity processors. For New Entrants and Emerging Players: Enter via sports nutrition functional positioning for beetroot powder nitrate applications, where validated pre-workout formulations remain underpenetrated relative to synthetic alternatives. Clinical dietary channels for spinach powder micronutrient fortification offer second white-space opportunity with lower certification barriers than pharmaceutical excipient grades. Direct sampling programs to German and Japanese nutraceutical formulators provide viable go-to-market angle bypassing entrenched distributor relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with patent-holding low-temperature dehydration specialists possessing validated heat-sensitive compound preservation capabilities. Five-to-ten-year viability framing favors processors combining captive cultivation control with multi-jurisdictional certification portfolios rather than pure-play commodity operators. Monitor REACH chemical registration timelines and evolving EU EFSA novel food opinions as inflection indicators for European market access costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contract Farming | Captive pesticide-free raw material pipelines secure USDA Organic and EU Organic dual-certification premiums for export eligibility. |
| Low-Temperature Dehydration Patent Expansion | Validated sulforaphane and nitrate preservation capabilities unlock oncology supplement and sports nutrition premium pricing tiers. |
| BIS Certification Pathway Investment | Indian PLI scheme incentives accelerate Middle Eastern and European market access for export-grade vegetable powder production. |
| Direct-to-Manufacturer Channel Development | Bypassing wholesale intermediaries captures margin compression benefits from price transparency pressures in carrot powder procurement. |
| Precision Agriculture Data Integration | Yield optimization and quality control convergence reduces moisture variability below 6% thresholds for infant nutrition applications. |
Research Approach
Coverage spans India, Germany, the United States, China, and Japan, with primary inputs from each market informing demand-side and supply-side dynamics. The research combines structured interviews with dehydration facility operators, procurement leads at multinational beverage manufacturers, regulatory affairs specialists navigating FDA and EFSA compliance, contract farming network coordinators, and nutraceutical formulation scientists. Secondary validation draws from BIS certification registries, USDA Organic operation databases, EU EFSA novel food opinions, FDA dietary supplement labeling guidance documents, and customs trade flow records. Bottom-up capacity and production estimates were triangulated against top-down demand segmentation across food, beverage, nutraceutical, pharmaceutical, and cosmetics end uses.
Rate-of-change decomposition across the analysis window isolates volume drivers from price-mix effects, with segment-specific CAGRs derived from technology adoption curves and certification penetration assumptions. The analytical framework models dehydration technology tier, product type, packaging configuration, end-use industry, and geographic regulatory cluster as core segmentation dimensions. Industry-specific forecast inputs include spray-drying equipment installation rates, PLI scheme disbursement timelines, and evolving pesticide maximum residue limit harmonization progress between FDA and EFSA jurisdictions.
Inputs from BIS, USDA Organic, and EU EFSA registries were available through the study window; gaps in real-time contract farming yield data and proprietary low-temperature dehydration performance metrics introduce uncertainty bands around bioactive compound retention assumptions. Forecasts reflect documented assumptions regarding regulatory harmonization, technology cost curves, and clean-label procurement mandate diffusion rates. Practitioners should monitor REACH chemical registration requirement expansions, EU EFSA novel food opinion issuance patterns, and Indian PLI scheme capacity utilization disclosures for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Bioactive Ingredients Market
Ingredients
Hen Egg White Protein Market
Ingredients
Wheat Starch Derivative Market
Ingredients
Tapioca Pearls Market
Ingredients
Arrowroot Starch Market
Ingredients
Hydrolysed Vegetable Protein (HVP) Market
Ingredients
Heart Health Ingredients Market
Ingredients
Buckwheat Groat Flour Market
Ingredients
Virginiamycin Market
Ingredients
Injection Grade Soybean Oil Market
Ingredients
Pea Flour Market
Ingredients
Tuberose Extract Market
Ingredients
Wheat Malt Market
Ingredients
Bulk Food Ingredients Market
Ingredients
Low-Fat Cocoa Powder Market
Ingredients
Kilned Malt Market