
 Middle East and Africa Customized Premixes Market | 2026-2036
Middle East and Africa Customized Premixes Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Customized Premixes Market Foresight
South Africa's industrial food corridor is tilting toward higher premix throughput as local blenders scale capacity for fortified maize and wheat applications. Cargill Incorporated leverages its Johannesburg technical center to sustain formulation partnerships with regional millers. BASF SE anchors vitamin premix supply through its established distribution network across Sub-Saharan Africa. Koninklijke DSM NV differentiates via micronutrient stability technologies suited to hot-climate logistics.
Customized premixes constitute industrially blended concentrates of vitamins, minerals, amino acids, and functional additives, typically dosed at 0.1% to 2.0% in finished food matrices, manufactured through precision dry-mixing or spray-drying to achieve homogeneous nutrient distribution for fortification consistency. Their primary purpose is enabling food manufacturers to meet nutritional targets without managing dozens of individual raw material streams. Fortified Blends occupy the dominant volume position due to staple food fortification mandates across multiple African jurisdictions, while Nutritional Composites command margin premiums in infant formula and clinical nutrition channels. Functional Mixes are gaining fastest traction among sports nutrition and dietary supplement firms seeking condition-specific positioning.
South Africa's Department of Health fortification regulations, Nigeria's National Agency for Food and Drug Administration and Control product registration requirements, and Saudi Food and Drug Authority import specifications collectively determine permissible nutrient forms, labeling protocols, and market entry pathways for premix suppliers. These frameworks elevate compliance costs for smaller blenders while creating structural advantages for multinationals with dedicated regulatory affairs capacity. Stakeholders must monitor evolving micronutrient mandate expansions and halal certification harmonization across Gulf and East African trade blocs to anticipate formulation and sourcing recalibrations.
Market Dynamics
Fortification mandates across Sub-Saharan Africa and Gulf Cooperation Council states are forcing dairy processors and grain millers to outsource micronutrient blending rather than manage raw material complexity internally.
Growth Catalysts
- South Africa's mandatory maize fortification:The Department of Health regulations tighten micronutrient specifications, compelling industrial millers to source precision-blended premixes for compliance consistency.
- Hot-climate stability technologies:Advanced encapsulation methods protect vitamin potency through extended supply chains, reducing degradation losses during Gulf and East African distribution.
- Nigeria's urban manufacturing corridors:Food production clusters around Lagos and Kano concentrate demand for customized premixes among domestic processors scaling fortified product lines.
Market Restraints
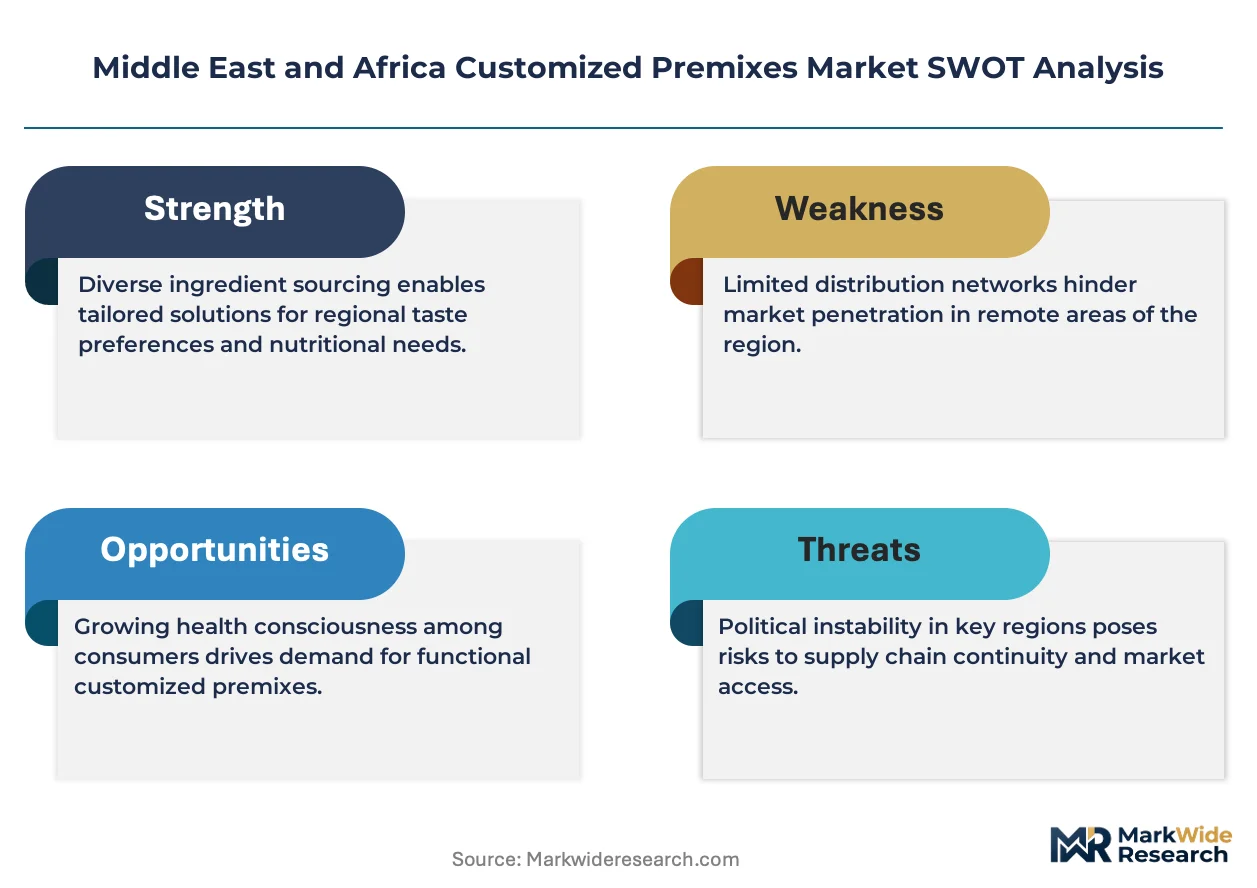
- Vitamin raw material concentration:Global supply of retinol and cholecalciferol precursors concentrates among limited API manufacturers, creating price volatility exposure for regional blenders.
- Halal certification fragmentation:Divergent standards between Gulf national authorities and Indonesian MUI requirements complicate cross-border premix shipments and formulation approvals.
- Import dependency for amino acid premixes:Local production capacity for lysine and methionine concentrates remains underdeveloped across the Middle East and Africa, locking buyers into dollar-denominated sourcing.
Strategic Opportunities
- Kenya's evolving dairy fortification:The Kenya Dairy Board is evaluating mandatory vitamin A and D mandates for fluid milk, creating preemptive formulation partnerships with Nairobi-based processors.
- Clinical nutrition channel expansion:Hospital and long-term care facilities across Saudi Arabia and UAE are adopting disease-specific nutritional composites for malnutrition management protocols.
- Sports nutrition localization:Fitness culture proliferation in South African metropolitan markets drives demand for branched-chain amino acid premixes among domestic supplement manufacturers.
Industry Challenges
- Regulatory affairs talent scarcity:Few local professionals possess dual expertise in food chemistry and Saudi Food and Drug Authority submission protocols, delaying product registrations.
- Precision blending equipment gaps:Achieving coefficient of variation below 5% for micro-dosed nutrients requires capital investment in gravimetric loss-in-weight systems that mid-size blenders struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Customized Premixes Market |
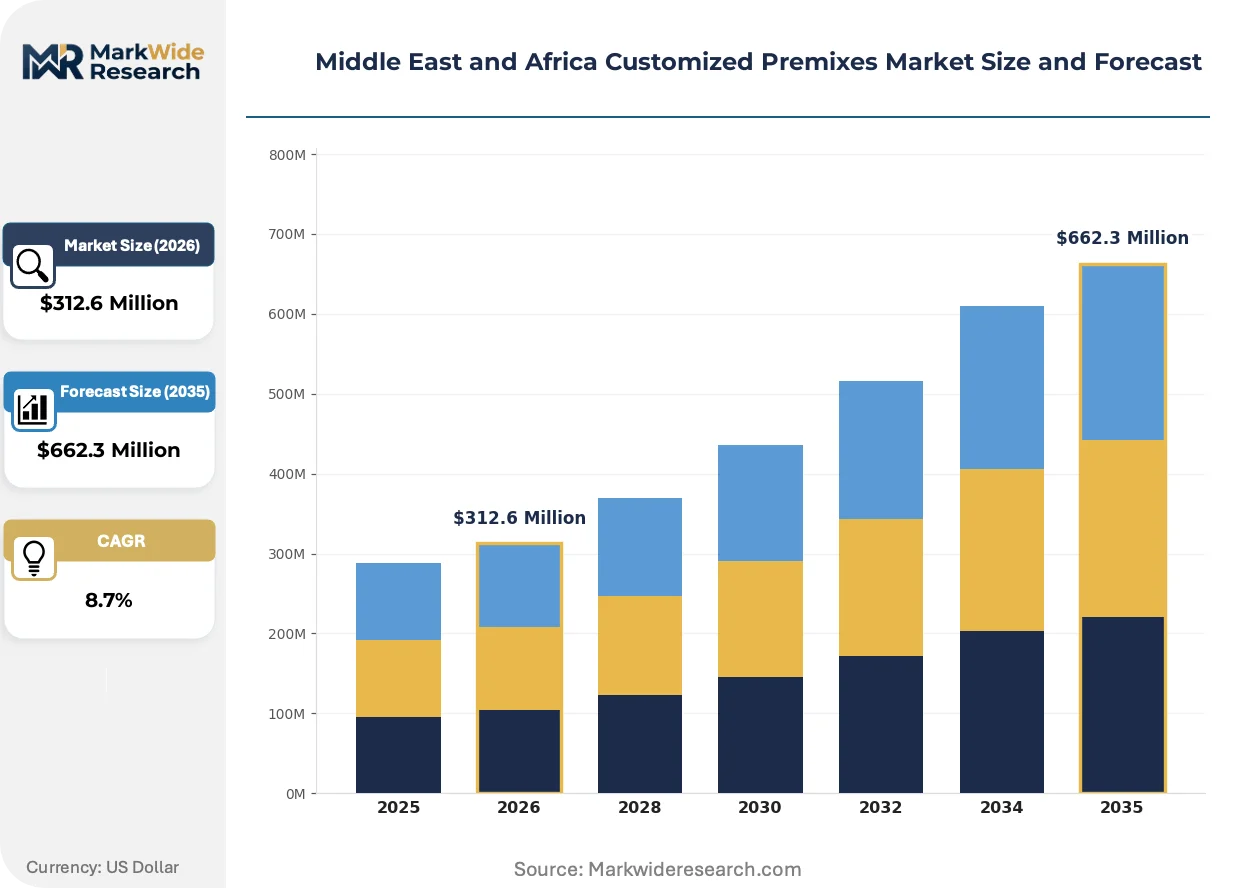
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fortified Blends, Nutritional Composites, Functional Mixes, Flavor Enhancers End User: Food Manufacturers, Beverage Producers, Dietary Supplement Firms, Bakery Sectors Application: Infant Nutrition, Sports Nutrition, Dietary Solutions, Convenience Foods Packaging Type: Bags, Jars, Pouches, Bulk Containers |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Koninklijke DSM NV, Glanbia plc, Kemin Industries Inc, Nutreco NV, De Heus Voeders BV, BASF SE, Prinova Group LLC, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Customized Premixes Market Shifts & Advancements
Digital formulation platforms and climate-adapted nutrient protection systems are compressing development cycles for region-specific premix portfolios while regulatory harmonization efforts reshape compliance architectures.
Encapsulation technologies using modified starch and lipid matrices are virtualizing traditional spray-drying infrastructure requirements for heat-sensitive vitamins. Dairy processors in UAE and Saudi Arabia are adopting these pre-engineered nutrient forms at accelerated procurement frequencies. The shift is virtualizing capital expenditure barriers that previously constrained mid-size manufacturers from entering fortified product categories.
South Africa's Department of Health is expanding micronutrient mandate coverage to include folic acid specification increases for wheat flour. Industrial millers must reformulate existing premix contracts to meet tightened analytical thresholds. The regulatory pressure concentrates compliance investment among Johannesburg and Cape Town blending facilities serving the national bread market.
Direct technical service engagements are displacing traditional distributor-mediated premix procurement across Nigeria's food manufacturing sector. Lagos-based processors now expect on-site formulation support and stability testing from suppliers rather than transactional ingredient purchasing. The behavioral shift is most pronounced among infant formula manufacturers seeking rapid recipe optimization for NAFDAC registration timelines.
Middle East and Africa Customized Premixes Market Segmentation
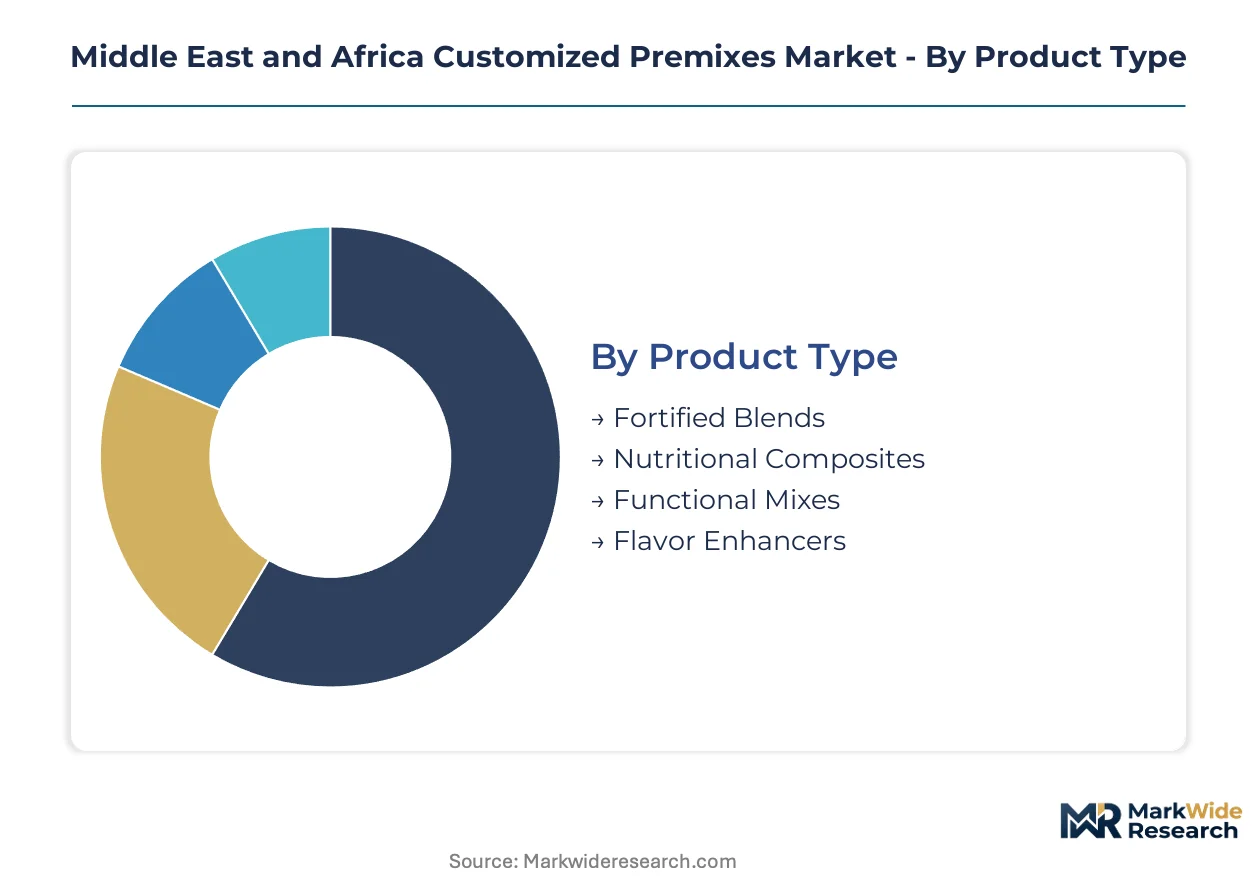
Segmentation in the Middle East and Africa customized premixes market reveals how regulatory mandates, climate logistics, and manufacturing scale reshape procurement patterns across distinct product categories and end-use channels. Understanding these divisions exposes where formulation complexity concentrates and where standardization dominates.
Product Type:
Mature fortification categories anchor volume procurement while emerging functional segments capture margin expansion and technical investment.
- Fortified Blends:Industrially blended concentrates of vitamins and minerals dosed at 0.1% to 2.0% for staple food matrices, achieving homogeneous distribution through precision dry-mixing. South African millers serving the national bread market source these premixes under tightened Department of Health folic acid specifications. These blends handle the majority of throughput; Functional Mixes are gaining share fastest.
- Nutritional Composites:Micronutrient assemblies engineered for infant formula and clinical nutrition with enhanced bioavailability matrices. Demand concentrates among Lagos-based infant formula manufacturers seeking rapid NAFDAC registration support from suppliers.
- Functional Mixes:Condition-specific concentrates targeting sports performance and metabolic health with branched-chain amino acids and adaptogenic compounds.
- Flavor Enhancers:Taste-masking and palatability systems integrating micronutrients without sensory degradation in finished products.
Fortified Blends handle the majority of throughput; Functional Mixes are expanding most quickly on share.
End User:
Procurement sophistication varies sharply across customer types, with regulatory exposure and technical service expectations defining supplier relationships.
- Food Manufacturers:Grain millers and dairy processors across Nigeria's Lagos-Kano corridor and South Africa's industrial belt outsource micronutrient blending to avoid raw material complexity. These manufacturers represent the dominant demand concentration; Dietary Supplement Firms are climbing the fastest.
- Beverage Producers:Fluid milk and alternative dairy processors in Saudi Arabia and UAE evaluating vitamin A and D fortification mandates.
- Dietary Supplement Firms:Sports nutrition and wellness brands in South African metropolitan markets sourcing condition-specific amino acid premixes with localization requirements.
- Bakery Sectors:Industrial bread and pastry manufacturers dependent on wheat flour fortification compliance.
Food Manufacturers absorb the largest procurement volumes; Dietary Supplement Firms show the steepest expansion trajectory.
Application:
Application segmentation tracks how disease burden demographics and lifestyle shifts redirect premix formulation priorities across the region.
- Infant Nutrition:Precision micronutrient assemblies for formula and complementary feeding with stringent stability requirements. Nairobi-based processors and Lagos manufacturers drive technical service intensity from premix suppliers.
- Sports Nutrition:Protein fortification and recovery-focused amino acid blends for fitness culture proliferation in South Africa and Gulf urban centers.
- Dietary Solutions:Clinical nutrition and malnutrition management protocols in Saudi Arabian and UAE hospital facilities.
- Convenience Foods:Shelf-stable fortified ready-to-eat products for urban African consumption patterns.
Infant Nutrition commands the highest specification intensity; Sports Nutrition is gaining momentum fastest.
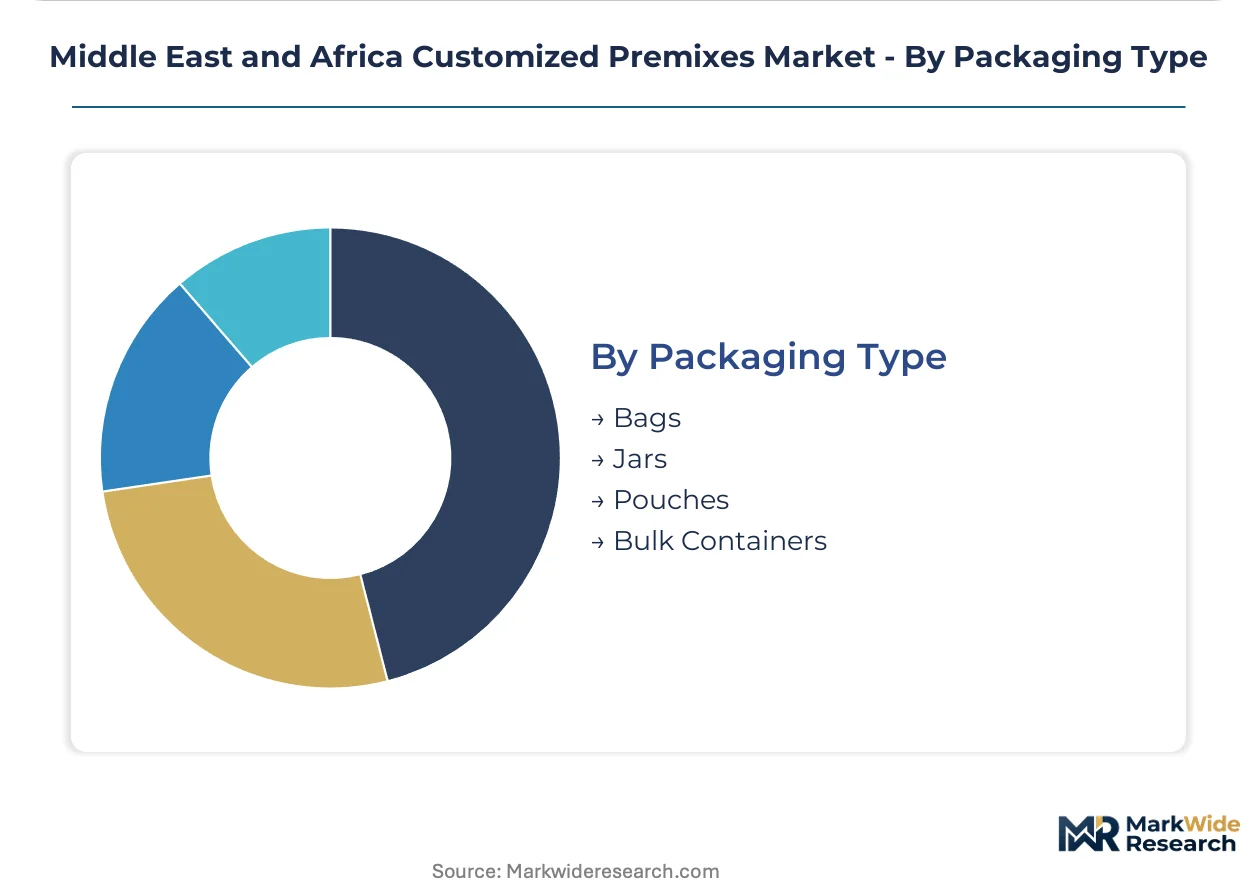
Packaging Type:
Packaging selection reflects supply chain length, climate exposure, and customer scale rather than branding considerations.
- Bulk Containers:Industrial totes and drums for high-throughput millers with established cold-chain or climate-controlled warehousing.
- Bags:Multi-layer laminated sacks with moisture barriers for regional distribution across Sub-Saharan Africa.
- Pouches:Flexible single-use formats for mid-size manufacturers and sampling protocols.
- Jars:Rigid containment for high-value, low-volume nutritional composites requiring extended shelf stability.
Bulk Containers move the largest tonnage; Pouches are advancing most quickly on adoption rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jebel Ali Port in Dubai anchors Gulf distribution networks for premix imports, while the Maputo Corridor rail link channels South African industrial output into Sub-Saharan markets. These infrastructure nodes determine where formulation partnerships concentrate and regulatory compliance investments flow.
South Africa
Industrial millers in Johannesburg and Cape Town scale gravimetric blending capacity to meet Department of Health folic acid specification increases for wheat flour. The national regulator tightens analytical thresholds quarterly, forcing contract reformulations among bread market suppliers. Cape Town's warehousing cluster now hosts climate-controlled nutrient storage facilities serving the Western Cape manufacturing belt.
Nigeria
Infant formula manufacturers in Lagos demand direct technical service engagements rather than distributor-mediated procurement, compressing NAFDAC registration timelines. The national food and drug administration enacts product registration requirements that elevate documentation burdens for premix imports. Kano's grain processing corridor concentrates fortified maize premix demand among domestic millers scaling packaged food lines.
Saudi Arabia
Dairy processors evaluate vitamin A and D fortification mandates under Saudi Food and Drug Authority consultation drafts, preempting formulation partnerships. The regulator specifies permissible nutrient forms and halal certification protocols that complicate cross-border shipments. Riyadh's food manufacturing zone attracts premix suppliers establishing localized technical service capabilities.
United Arab Emirates
Beverage producers in Dubai and Abu Dhabi adopt encapsulation technologies for heat-sensitive vitamins, reducing degradation losses through Gulf distribution. The Ministry of Health and Prevention aligns import specifications with Saudi standards, streamlining regional trade. Jebel Ali's free zone warehousing enables just-in-time premix delivery to UAE dairy processors.
Kenya
The Kenya Dairy Board's evaluation of mandatory fluid milk fortification drives preemptive vitamin A and D formulation partnerships with Nairobi-based processors. National regulatory consultations determine permissible nutrient concentrations and labeling requirements. Nairobi's industrial corridor concentrates technical service demand among mid-size dairy cooperatives scaling fortified product portfolios.
Middle East and Africa Customized Premixes Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision micronutrient assemblies. The vendor base organizes around three structural tiers: multinational nutrition platforms with dedicated regulatory affairs capacity, regional blending facilities serving single jurisdictions, and specialized encapsulation technology providers. Consolidation pressure intensifies as compliance costs escalate. Dominant competitive moves include strategic partnerships with industrial millers and geographic expansion through technical center establishment.
Within the multinational platform tier, Cargill Incorporated and BASF SE anchor supply relationships across Sub-Saharan Africa and Gulf markets respectively. Koninklijke DSM NV occupies a position emphasizing micronutrient stability technologies suited to hot-climate logistics. Archer Daniels Midland Company exemplifies the diversified nutrition conglomerate archetype with integrated premix and grain processing capabilities. These three entities represent distinct strategic postures: regulatory infrastructure depth, climate-adapted formulation expertise, and backward integration into agricultural inputs.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Koninklijke DSM NV |
| Glanbia plc |
| Kemin Industries Inc |
| Nutreco NV |
| De Heus Voeders BV |
| BASF SE |
| Prinova Group LLC |
| Others |
Supply & Pricing Matrix
The Maputo Corridor rail link's freight cost dynamics concentrate supply power among Johannesburg-based blenders while forcing Gulf importers into premium pricing tiers for climate-stabilized nutrient forms. This logistics bifurcation creates three distinct procurement cost structures across the Middle East and Africa premix landscape.
Pricing Analysis
Volume-discount tiering structures separate industrial millers purchasing bulk fortified blends from mid-size dietary supplement firms sourcing functional amino acid premixes in smaller lots. Pricing stratifies across premium, standard, and economy tiers based on certification grade and halal compliance level. Cost compression in the standard tier is intensifying because South African millers are consolidating procurement volumes to meet Department of Health folic acid specification increases. Food manufacturers represent the most price-sensitive segment due to thin margins on staple fortification, while clinical nutrition channels exhibit lowest sensitivity given reimbursement-backed procurement.
Supply Chain Analysis
Export-control regimes on vitamin A and D precursor technologies limit API flows from concentrated European and Asian manufacturers into regional blending facilities. Geographic supply concentration centers on China for lysine and methionine inputs, Switzerland for vitamin stability technologies, and India for botanical premix components. Raw material dependencies rest on retinol precursors, cholecalciferol concentrates, and encapsulated nutrient matrices. Single-source vulnerability runs through vitamin API manufacturers. Distribution feeds from Jebel Ali Port warehousing through distributor networks and direct technical service engagements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mandatory fortification expansions across Gulf and Sub-Saharan jurisdictions constitute a regulatory inflection disrupting established procurement patterns and compressing formulation development cycles. This disruption creates asymmetric opportunity windows across three stakeholder archetypes.
For Market Incumbents: Pre-empt encroachment from regional blenders scaling gravimetric capacity by locking exclusive formulation partnerships with Lagos-based infant formula manufacturers and Nairobi dairy cooperatives. Anchor defensive positioning through backward integration into vitamin encapsulation technologies that hot-climate logistics demand. Invest in dedicated regulatory affairs capacity spanning Saudi Food and Drug Authority and Nigeria's NAFDAC submission protocols to extend compliance cost advantages.
For New Entrants and Emerging Players: Mid-size South African sports nutrition manufacturers seeking localized branched-chain amino acid premixes represent the most penetrable entry point given limited domestic encapsulation expertise. Kenya's preemptive vitamin A and D dairy fortification partnerships offer second-mover formulation opportunities before mandate finalization. Pursue direct technical service engagements displacing distributor-mediated procurement to accelerate customer acquisition velocity.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agricultural conglomerates with underoptimized premix blending divisions lacking dedicated regulatory infrastructure. Long-term viability hinges on positioning within fortified staple food mandates expanding across African jurisdictions. Monitor Kenya Dairy Board consultation outcomes and South African folic acid specification enforcement intensity as inflection indicators for regional demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Harmonization | Unified Gulf standards reduce cross-border shipment delays and reformulation costs for premix suppliers. |
| Encapsulation Technology Licensing | Modified starch and lipid matrix protection extends vitamin potency through extended East African distribution chains. |
| Direct Technical Service Expansion | On-site formulation support in Lagos and Nairobi compresses NAFDAC registration timelines for infant formula clients. |
| Gravimetric Blending Capacity Addition | Johannesburg facilities achieving sub-5% coefficient of variation capture South African wheat fortification contract renewals. |
| Regulatory Affairs Talent Acquisition | Dual expertise in food chemistry and SFDA protocols accelerates product registrations across Saudi manufacturing zones. |
Research Methodology
Operator-level perspectives from premix formulation chemists, grain miller procurement directors, dairy processor technical managers, and regulatory affairs specialists anchored the qualitative base. Primary fieldwork combined structured interviews with these stakeholders and secondary validation through Saudi Food and Drug Authority consultation drafts, South African Department of Health fortification circulars, Nigeria NAFDAC registration guidelines, and customs trade data on vitamin precursor imports. Bottom-up demand modeling from end-use consumption patterns and top-down supply validation from manufacturer capacity disclosures were triangulated to establish market sizing.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling demand trajectories under varying mandate enforcement intensities and raw material price volatility assumptions. Segmentation dimensions included product type, end user category, application channel, packaging format, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to historical mandate adoption patterns and industrial capacity expansion timelines. Forecast inputs incorporated Kenya Dairy Board consultation progress and South African folic acid specification implementation schedules.
Practitioners should monitor regulatory mandate expansion announcements and vitamin API supply disruptions for early signals of forecast deviation. Forecasts reflect documented assumptions on enforcement consistency and raw material price stability. Material shifts in halal certification harmonization timelines or major vitamin manufacturer supply constraints would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Dessert Variegates Market
Specialty Ingredients
Mango Butter Market
Specialty Ingredients
Haitian Vetiver Oil Market
Specialty Ingredients
Global Sea Buckthorn Oil Market
Specialty Ingredients
Mangosteen Extract Market
Specialty Ingredients
Fermentation Products Market
Specialty Ingredients
Pomegranate Seed Oil Nutricosmetic Ingredients Market
Specialty Ingredients
South America Specialty Food Ingredient Market
Specialty Ingredients
Specialty Beverage Stabilizers Market
Specialty Ingredients
Tamanu Oil Market
Specialty Ingredients
Global Ayurvedic Herbs Market
Specialty Ingredients
Specialty Mint Oils Market
Specialty Ingredients
Specialty Carbohydrates Market
Specialty Ingredients
Personal Care Specialty Ingredients Market
Specialty Ingredients
Sun-Care Natural Oils Market
Specialty Ingredients
Mangosteen Market