
 Fruit Powder Market | 2026-2036
Fruit Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit Powder Market Analysis
Spray-drying energy intensity is narrowing the cost gap between conventional dehydration and freeze-drying technologies. SVZ International leverages its European sourcing network to sustain year-round supply consistency for beverage clients. Kanegrade Ltd anchors its position through deep specialization in tropical and exotic fruit varieties.
Fruit powder consists of dehydrated fruit material milled to fine particle size, typically retaining flavor compounds, natural sugars, and micronutrients through controlled thermal processing below degradation thresholds. Its primary commercial purpose centers on delivering stable, shelf-extended fruit identity to formulations where fresh pulp proves logistically impractical. Spray-dried powder leads volume output due to lower unit economics, while freeze-dried powder commands premium placement in nutraceutical applications where heat-sensitive bioactive preservation determines efficacy claims. The organic form segment is expanding fastest as clean-label procurement policies at major food and beverage manufacturers cascade through supplier qualification requirements.
FDA food additive regulations and USDA organic certification standards govern product identity and label claims in the United States, while EFSA novel food assessments and EU organic regulation shape market access for imported fruit powders into Europe. These frameworks elevate compliance costs for new entrants but simultaneously protect established suppliers with validated supply chain documentation and third-party certifications. Stakeholders must monitor evolving residue limits and origin traceability mandates as downstream customers harden supplier audit protocols.
Market Dynamics
Dehydration technology economics are restructuring competitive positioning across the fruit powder value chain, as energy costs compress margins for conventional spray-drying operators while freeze-drying unit economics improve through equipment efficiency gains.
Growth Catalysts
- Clean-label procurement mandates:Major beverage and nutraceutical formulators are hardening supplier qualification requirements around organic certification and residue documentation, pulling volume toward validated processors.
- EU Green Deal residue limits:Tightening import standards for fruit ingredients are accelerating investment in controlled-environment cultivation and third-party testing infrastructure among exporters targeting European markets.
- India PLI scheme incentives:Domestic processing capacity expansion is reducing import dependency for tropical fruit raw material, shortening supply chains for regional formulators.
Market Restraints
- Energy cost volatility:Natural gas and electricity price swings directly impact spray-drying unit economics, compressing margins for operators without long-term power purchase agreements.
- Raw material concentration:Seasonal tropical fruit sourcing clusters in Southeast Asian and Latin American growing regions, exposing processors to climate disruption and logistics bottlenecks.
- Freeze-drying capex barriers:Equipment intensity and batch processing limitations constrain capacity expansion for premium nutraceutical-grade output.
Strategic Opportunities
- Functional beverage formulation:Sports nutrition and ready-to-drink wellness brands are specifying fruit powders for natural flavoring and micronutrient fortification, opening volume channels beyond conventional food processing.
- India domestic market penetration:BIS standards harmonization and organized retail expansion are creating structured demand for packaged fruit powder in conventional and Ayurvedic applications.
- Precision fermentation convergence:Hybrid processing combining fruit-derived substrates with cellular agriculture is emerging as a pathway for bioactive compound standardization.
Industry Challenges
- Organic certification timeline compression:Three-year conversion periods and annual audit costs strain working capital for processors transitioning conventional orchards.
- Traceability system integration:Blockchain and ERP platform deployment requires technical talent scarce in traditional fruit processing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit Powder Market |
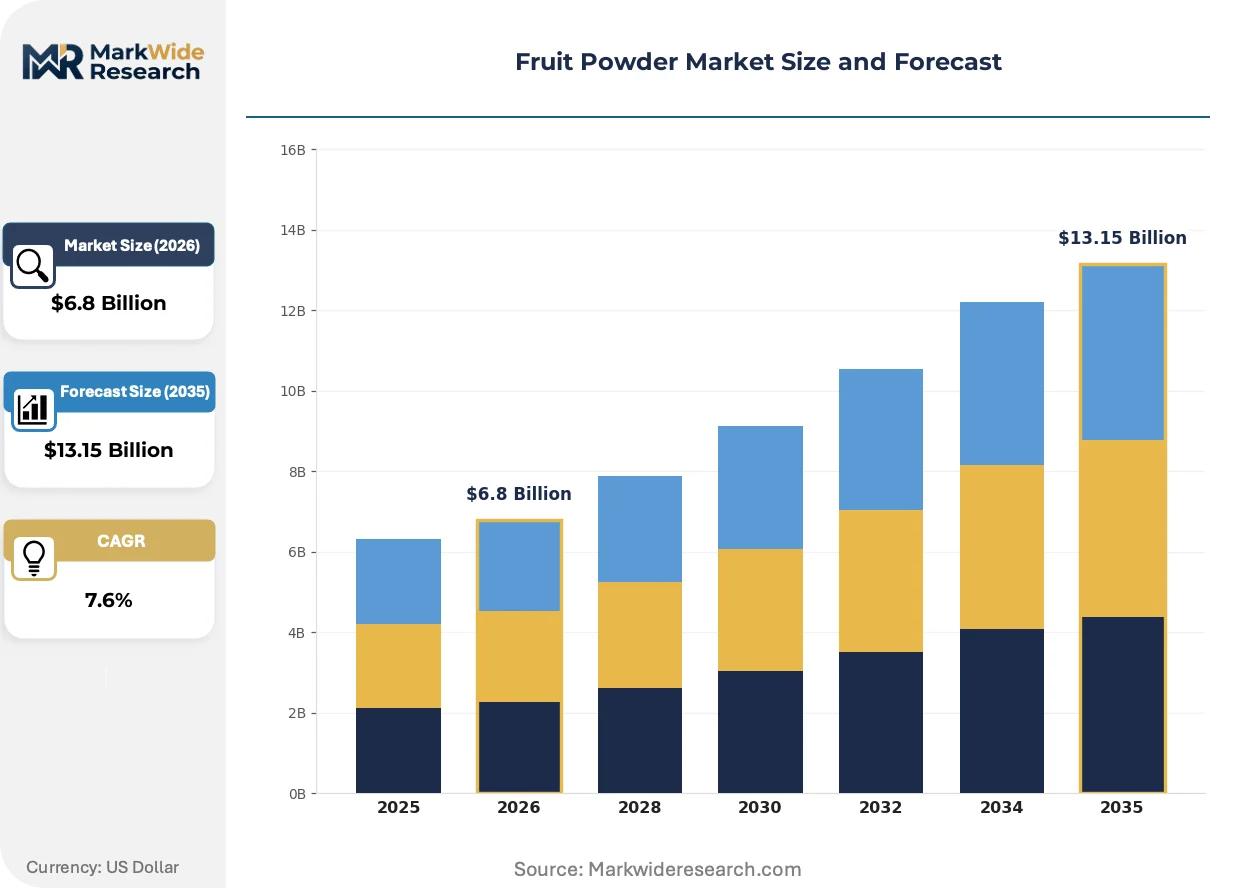
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freeze-Dried Powder, Spray-Dried Powder, Dehydrated Powder, Instant Powder End User: Food & Beverage Industry, Cosmetics Industry, Nutraceuticals, Dietary Supplements Form: Organic, Conventional, Blends, Single Fruit Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | SVZ International, Van Drunen Farms, Kanegrade Ltd, Aarkay Food Products Ltd, Nexira, Döhler Group SE, European Freeze Dry Ltd, Paradise Fruits, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit Powder Market Emerging Trajectories
Processing technology convergence and regulatory documentation requirements are elevating capital intensity while compressing supplier qualification cycles, reshaping how fruit powder moves from agricultural input to formulated ingredient.
Low-temperature vacuum microwave dehydration is virtualizing the traditional thermal processing sequence, enabling mid-tier processors to achieve bioactive retention profiles previously exclusive to freeze-drying equipment. Nutraceutical contract manufacturers are piloting this technology at commercial scale, attracted by throughput advantages and reduced energy intensity. The technology is virtualizing capital barriers between premium and standard product tiers, eroding the historical segmentation between spray-dried commodity supply and freeze-dried specialty output.
EFSA novel food assessments and EU organic regulation documentation requirements are extending supplier onboarding timelines for non-European processors, creating compliance moats around established European operators. The industrial consequence is accelerated backward integration by large formulators seeking captive supply security. Nutraceutical applications requiring efficacy substantiation face the tightest qualification protocols, driving consolidation toward processors with validated clinical-grade manufacturing infrastructure.
Direct procurement relationships between ingredient processors and end-use formulators are displacing traditional distributor intermediaries, compressing margin capture at the wholesale tier. Large beverage and nutrition brands are deploying technical sourcing teams to origin regions, conducting on-site audits of cultivation and processing facilities. This pattern is most visible in India and select Southeast Asian supply bases, where multinational formulators are establishing preferred supplier programs with multi-year volume commitments.
Fruit Powder Market Segmentation
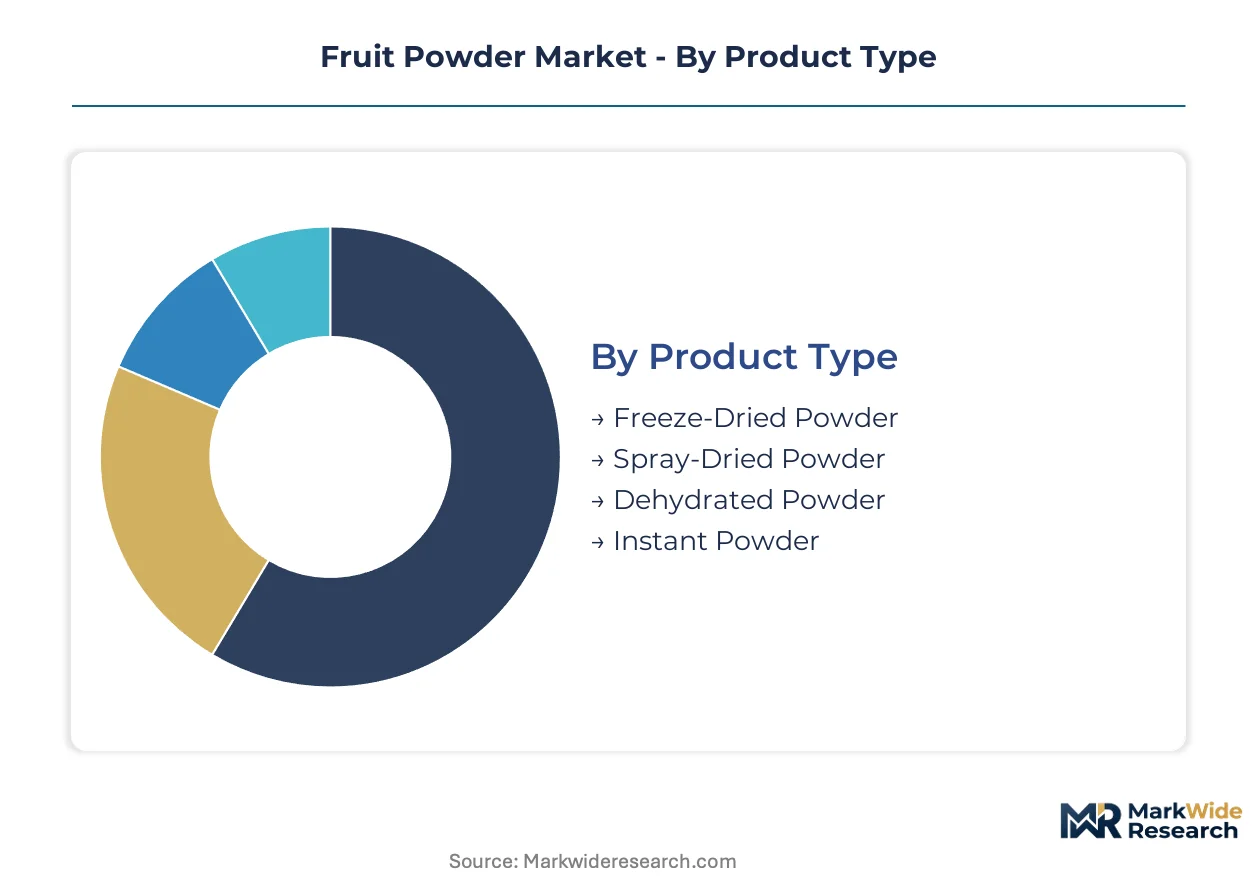
Fruit powder segmentation reflects divergent processing economics and end-use qualification requirements. Product type determines bioactive retention profiles and unit cost structures, while form and channel decisions cascade from downstream clean-label mandates and procurement protocols.
Product Type:
Spray-dried powder anchors volume supply through favorable unit economics, while freeze-dried variants command premium placement in efficacy-sensitive applications.
- Spray-Dried Powder:Thermal dehydration at elevated temperatures produces fine, flowable particles with moderate nutrient retention. Beverage manufacturers in India and Brazil specify this grade for cost-sensitive flavoring applications where heat-stable compounds suffice.
- Freeze-Dried Powder:Sublimation-based moisture removal preserves heat-labile vitamins and enzymatic activity intact. Nutraceutical formulators in Germany and Switzerland require this grade for clinical-grade dietary supplements where bioactive potency substantiates label claims.
- Dehydrated Powder:Conventional hot-air drying yields coarser particles at lowest capital intensity. Regional bakeries and confectioners across Southeast Asia source this grade for texture and color rather than micronutrient delivery.
- Instant Powder:Agglomerated particles engineered for rapid cold-water dispersibility. Ready-to-drink beverage brands specify this grade for consumer convenience in single-serve stick pack formats.
The dominant share belongs to Spray-Dried Powder, while Freeze-Dried Powder is gaining share fastest on nutraceutical qualification requirements.
End User:
Customer procurement sophistication spans commodity ingredient purchasing to validated clinical-grade supply chains.
- Food & Beverage Industry:Mass-market manufacturers prioritize year-round supply consistency and cost stability over bioactive retention. Major CPG houses maintain dual-source strategies across Indian and Latin American processors.
- Nutraceuticals:Contract manufacturers enforce stringent supplier audit protocols including third-party residue testing and organic certification verification. EFSA novel food dossier requirements extend onboarding timelines for non-European suppliers.
- Cosmetics Industry:Topical formulators specify fruit powders for antioxidant marketing claims and natural colorant functionality. Korean and French beauty brands drive demand for exotic tropical varieties with novel INCI nomenclature.
- Dietary Supplements:Direct-to-consumer brands require small-batch flexibility and custom blending capabilities. Amazon-native supplement sellers favor domestic US processors for shorter lead times and FDA-compliant labeling support.
Food & Beverage Industry retains volume leadership, though Nutraceuticals exhibits the steepest expansion trajectory on functional formulation trends.
Form:
Certification grade and fruit source complexity create four distinct procurement tiers with diverging margin structures.
- Organic:Three-year conversion protocols and annual audit costs elevate working capital requirements. EU Green Deal residue tightening is accelerating demand for certified organic supply as conventional import channels face rejection risk.
- Conventional:Standard cultivation without third-party certification supports lowest price positioning. Price-sensitive foodservice distributors in emerging markets specify this grade for bulk ingredient applications.
- Single Fruit:Pure-source powders enable precise formulation control and clean-label transparency. US beverage startups marketing single-ingredient positioning drive demand for traceable mono-varietal supply.
- Blends:Pre-formulated combinations reduce R&D burden for mid-tier manufacturers. Private-label supplement brands favor custom blends for differentiated SKU proliferation without in-house formulation investment.
Conventional form holds present volume dominance, while Organic climbs the fastest on retailer procurement mandates.
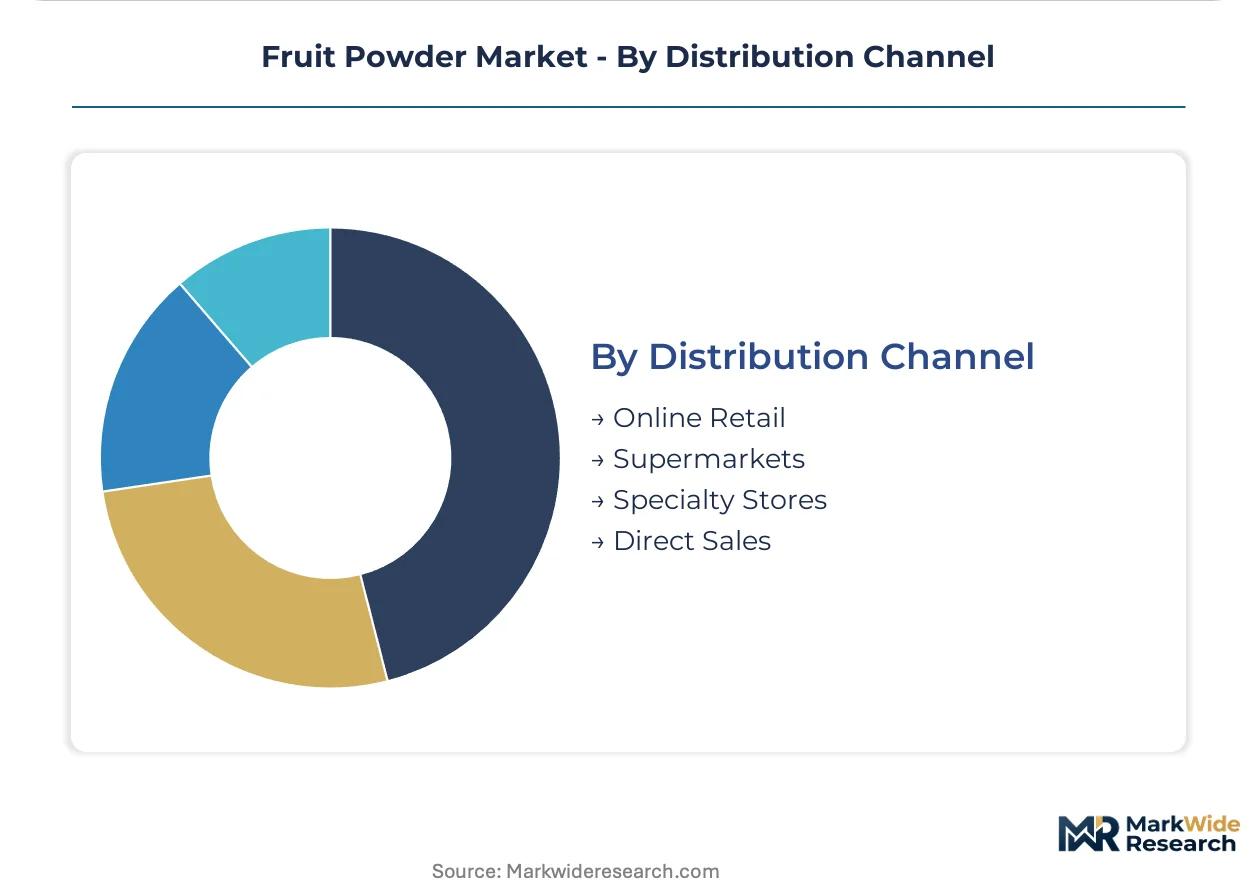
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic proximity to processing infrastructure.
- Direct Sales:Large formulators bypass intermediaries through multi-year preferred supplier agreements with technical audit provisions. Major beverage multinationals deploy sourcing teams to Indian and Vietnamese processing facilities.
- Online Retail:E-commerce platforms enable small-batch access for artisanal producers and R&D sampling. Alibaba and IndiaMART aggregate regional processors for international buyer discovery.
- Specialty Stores:Ingredient distributors with technical sales support serve mid-tier nutraceutical and cosmetics manufacturers. European hubs in Rotterdam and Hamburg concentrate specialty fruit powder wholesale.
- Supermarkets:Mass retail channels move consumer-packaged fruit powder for home baking and smoothie applications. Organized retail expansion in Indian cities is creating new shelf space for domestic brands.
Direct Sales commands the largest revenue share, though Online Retail is expanding most quickly on SME formulator market entry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports spray-dried tropical fruit powders to European beverage manufacturers under tightening EU Green Deal residue protocols. German nutraceutical formulators source freeze-dried variants from Swiss and domestic processors to meet EFSA novel food dossier requirements.
India
Domestic beverage brands and Ayurvedic medicine manufacturers drive demand for mango, amla, and pomegranate powders. BIS standards harmonization and PLI scheme incentives accelerate processing capacity expansion in Maharashtra and Karnataka. Pune-based facilities are scaling spray-drying output for regional CPG supply chains.
Germany
Nutraceutical contract manufacturers enforce stringent supplier audits for clinical-grade fruit powder procurement. EFSA novel food assessments and EU organic regulation documentation extend onboarding timelines for non-European suppliers. Hamburg concentrates specialty ingredient wholesale operations serving Central European formulators.
United States
Direct-to-consumer supplement brands and functional beverage startups specify organic-certified powders for clean-label positioning. FDA food additive regulations and USDA organic certification standards govern product identity and label claims. California processors dominate small-batch custom blending for Amazon-native sellers.
Switzerland
Premium nutraceutical brands command bioactive retention profiles substantiating efficacy label claims. Swissmedic oversight and EU organic regulation alignment protect established suppliers with validated supply chain documentation. Basel-area processors specialize in clinical-grade manufacturing infrastructure for European pharmaceutical clients.
Brazil
Acai, acerola, and cupuacu powder exports serve North American and European natural products channels. ANVISA food ingredient regulations and organic certification requirements shape export market access. São Paulo state processors integrate backward into controlled-environment cultivation to secure residue-compliant raw material.
Fruit Powder Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Large beverage multinationals deploy technical sourcing teams to origin regions, compressing distributor margin capture. Three archetypes dominate: European processors with validated clinical infrastructure, tropical-origin specialists with captive cultivation networks, and scale-driven commodity suppliers. Consolidation accelerates through multi-year preferred supplier agreements and captive processing investments.
Within the European-validated tier, SVZ International and European Freeze Dry Ltd represent processors with sustained year-round supply consistency for beverage and nutraceutical clients. Kanegrade Ltd anchors the tropical-specialist archetype through deep positioning in exotic fruit varieties. These three exemplify how documentation-heavy regulatory environments favor incumbents with multi-jurisdiction certification portfolios and audited supply chain traceability systems.
| Leading Market Players |
|---|
| SVZ International |
| Van Drunen Farms |
| Kanegrade Ltd |
| Aarkay Food Products Ltd |
| Nexira |
| Döhler Group SE |
| European Freeze Dry Ltd |
| Paradise Fruits |
| Kerry Group |
| Others |
Supply Flow & Price Mechanics
The Rotterdam-Hamburg freight corridor anchors cost dynamics for European-bound tropical fruit powders, with container rate volatility compressing margins at Indian spray-drying facilities while enabling price differentiation between validated organic supply and conventional commodity grades. Energy-intensive dehydration economics tether pricing power to power purchase agreement coverage, concentrating margin capture among processors with captive renewable contracts.
Pricing Analysis
Cost-plus contracts indexed to natural gas and electricity benchmarks dominate procurement between Indian processors and European beverage manufacturers. Three-tier pricing structure across premium freeze-dried, standard spray-dried, and economy hot-air grades separates nutraceutical-grade bioactive retention from mass-market flavoring applications. Pricing pressure stems from EU Green Deal residue tightening, which disqualifies conventional supply from premium channels. Foodservice distributors in emerging markets exhibit highest price sensitivity, while Swiss nutraceutical brands accept premium positioning for clinical-grade documentation.
Supply Chain Analysis
Supply-chain finance facilities extended by European beverage multinationals are stabilizing working capital for Maharashtra and Karnataka processors amid three-year organic conversion timelines. Raw material sourcing concentrates in India, Brazil, and Vietnam for tropical varieties, with spray-drying equipment and natural gas feedstock as critical inputs. Single-source vulnerability runs through Southeast Asian logistics chokepoints during monsoon disruption. Distribution runs through direct preferred supplier agreements displacing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive boundaries as direct procurement portals and blockchain traceability systems create two-sided market structures linking origin processors with end-use formulators. Interoperability between ERP platforms and third-party certification databases is emerging as the critical ecosystem infrastructure.
For Market Incumbents: Build compliance documentation moats through multi-jurisdiction organic certification portfolios and validated clinical-grade manufacturing infrastructure. Backward integration into controlled-environment cultivation in São Paulo state and Maharashtra secures residue-compliant raw material against EU Green Deal tightening. Channel control through technical sourcing team deployment to origin regions compresses distributor margin capture and locks in multi-year volume commitments.
For New Entrants and Emerging Players: Establish a beachhead in India's domestic Ayurvedic and conventional beverage segments where BIS standards harmonization is creating structured demand for packaged fruit powder. Precision fermentation convergence for bioactive standardization represents the most penetrable white-space, with hybrid processing combining fruit-derived substrates and cellular agriculture. A direct-to-consumer supplement brand go-to-market angle leverages Amazon-native seller infrastructure and FDA-compliant domestic US processors for shorter lead times.
For Investors and Strategic Acquirers: European-validated processors with EFSA novel food dossier capabilities and audited supply chain traceability systems represent the priority acquisition archetype for long-term viability across the 5-10 year window. Swiss and German clinical-grade infrastructure commands premium multiples as nutraceutical qualification protocols tighten. The signal to watch is accelerated backward integration announcements by large formulators seeking captive supply security.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | São Paulo state processors secure residue-compliant acai and acerola raw material against ANVISA export requirements. |
| Clinical-Grade Manufacturing Certification | Basel-area infrastructure meets Swissmedic oversight and EU organic regulation for European pharmaceutical clients. |
| Direct Procurement Portal Development | Beverage multinationals deploy technical sourcing teams to Pune facilities, compressing wholesale intermediary margins. |
| Low-Temperature Vacuum Microwave Deployment | Mid-tier processors achieve freeze-drying bioactive retention profiles without equipment intensity barriers. |
| Blockchain Traceability Integration | ERP platform deployment satisfies downstream customer audit protocols for origin documentation. |
Methodological Framework
Cross-validation between executive interviews at Indian spray-drying facilities and European nutraceutical contract manufacturers anchors the qualitative findings in operational reality. Primary discussions with plant managers in Maharashtra and Karnataka, procurement leads at German beverage houses, and regulatory affairs specialists navigating EFSA novel food assessments combined with secondary validation from BIS standards documentation, EU organic regulation filings, and PLI scheme incentive disclosures. Bottom-up capacity modeling and top-down demand aggregation triangulate volume estimates.
Calibration against historical customs data and processor capacity announcements refines the analytical framework across the projection horizon. Segmentation dimensions span dehydration technology tier, certification grade, end-use application, and regional regulatory cluster. CAGRs derive from slope analysis of year-over-year progression adjusted for technology substitution effects and energy cost trajectory assumptions. Forecast inputs incorporate spray-drying energy intensity trends and freeze-drying equipment efficiency gains.
Sensitivities concentrate around EU Green Deal residue limit revisions, natural gas price volatility, and precision fermentation technology maturation. Forecasts reflect documented assumptions on organic conversion timelines and certification audit cost structures. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
France Soy Protein Market
Ingredients
Peanut Ingredients Market
Ingredients
Europe Vegetable Oil Market
Ingredients
Low Fat Oil Market
Ingredients
Global Hydrolyzed Wheat Protein Market
Ingredients
Global Fresh Compressed Yeast Market
Ingredients
Global Apricot Oil Market
Ingredients
South America Soy Protein Ingredients Market
Ingredients
Native Starch Market
Ingredients
Yeast Flakes Market
Ingredients
Ingredients Market
Ingredients
North America Rice Bran Oil Market
Ingredients
High Oleic Oil Market
Ingredients
Energy Ingredients Market
Ingredients
Asia-Pacific Bakery Ingredients Market
Ingredients
Egg Albumin Protein Market