
 Tunisia Fruit and Vegetable Market | 2026-2036
Tunisia Fruit and Vegetable Market Size, Share, and Industry Trends Forecast 2026-2036
Tunisia Fruit and Vegetable Market Analytics
Hotel and restaurant buyers are unwinding traditional reliance on informal wholesale channels, redirecting volume toward certified suppliers with cold-chain guarantees. Les Jardins de Tunisie leverages integrated greenhouse operations to secure year-round tomato and pepper supply for hospitality clients. Esca'Rome Holding Company anchors its position through controlled-atmosphere storage investments in the Cap Bon peninsula. Groupement Interprofessionnel des Fruits (GIFRUITS) competes by aggregating smallholder citrus into export-grade lots that meet EU phytosanitary thresholds.
The Tunisia Fruit and Vegetable sector encompasses fresh and minimally processed plant products cultivated across rain-fed and irrigated agro-ecological zones, where shelf-life extension through hydrocooling and modified-atmosphere packaging determines export eligibility. Citrus and leafy greens dominate value pools, with citrus benefiting from established EU quota access and leafy greens capturing premium positioning in Gulf retail. Root vegetables and berries represent faster-expanding segments, as berries exploit greenhouse technology transfer from Spanish operators and root vegetables serve expanding North African food processing demand.
Tunisia's national agricultural regulator enforces conformity with Codex Alimentarius pesticide residue limits, while the country's central trade authority administers export phytosanitary certification required for EU market access. The national food safety agency periodically revises maximum residue levels, forcing growers to adopt integrated pest management or lose premium channel eligibility. Stakeholders must monitor regulatory alignment between Tunisian standards and evolving EU deforestation-free supply chain due diligence obligations.
Market Dynamics
The Sahel region's irrigated citrus and tomato clusters are consolidating supply under vertically integrated greenhouse operators, compressing the informal wholesale layer that historically dominated domestic distribution. This structural compression is redrawing procurement relationships between coastal growers and hospitality buyers.
Growth Catalysts
- EU Green Deal deforestation-free supply chain rules:The regulation is accelerating farm-level traceability investments across Cap Bon peninsula operations, qualifying Tunisian citrus for preferential quota access.
- Hospitality sector procurement centralization:Domestic restaurant chains are mandating cold-chain guarantees from certified suppliers, pulling volume away from traditional wholesale souks.
- Drip irrigation technology transfer:Spanish greenhouse operators are transferring berry cultivation protocols to Tunisian coastal farms, expanding export-grade production windows.
Market Restraints
- Phosphate fertilizer import dependency:Tunisia relies on Moroccan and Russian suppliers for critical inputs, exposing margins to commodity volatility and currency fluctuation.
- Cap Bon peninsula cold-storage concentration:Controlled-atmosphere infrastructure clusters in a narrow coastal band, creating single-point vulnerability for export-grade citrus.
- Water allocation rigidity:The national agricultural ministry's irrigation licensing framework limits expansion in interior governorates despite groundwater availability.
Strategic Opportunities
- Gulf retail premium channel penetration:Leafy greens from Sahel hydroponic operations are capturing shelf space in UAE and Saudi supermarket chains, commanding price premiums over Egyptian competitors.
- Food processing backward integration:Tunisian tomato paste manufacturers are contracting dedicated greenhouse supply, locking in raw material quality and traceability.
- Integrated pest management subsidy expansion:The national food safety agency's revised maximum residue enforcement is channeling grower investment into biocontrol adoption, opening technical service provider niches.
Industry Challenges
- Phytosanitary certification timeline compression:EU border inspection post changes are shortening acceptable documentation windows, straining exporter logistics coordination.
- Greenhouse construction capital intensity:Steel and polyethylene import costs are elevating payback periods for protected agriculture expansion beyond smallholder financing capacity.
- Cold-chain technician scarcity:Controlled-atmosphere storage operations face recruitment gaps for refrigeration maintenance and hydrocooling system calibration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tunisia Fruit and Vegetable Market |
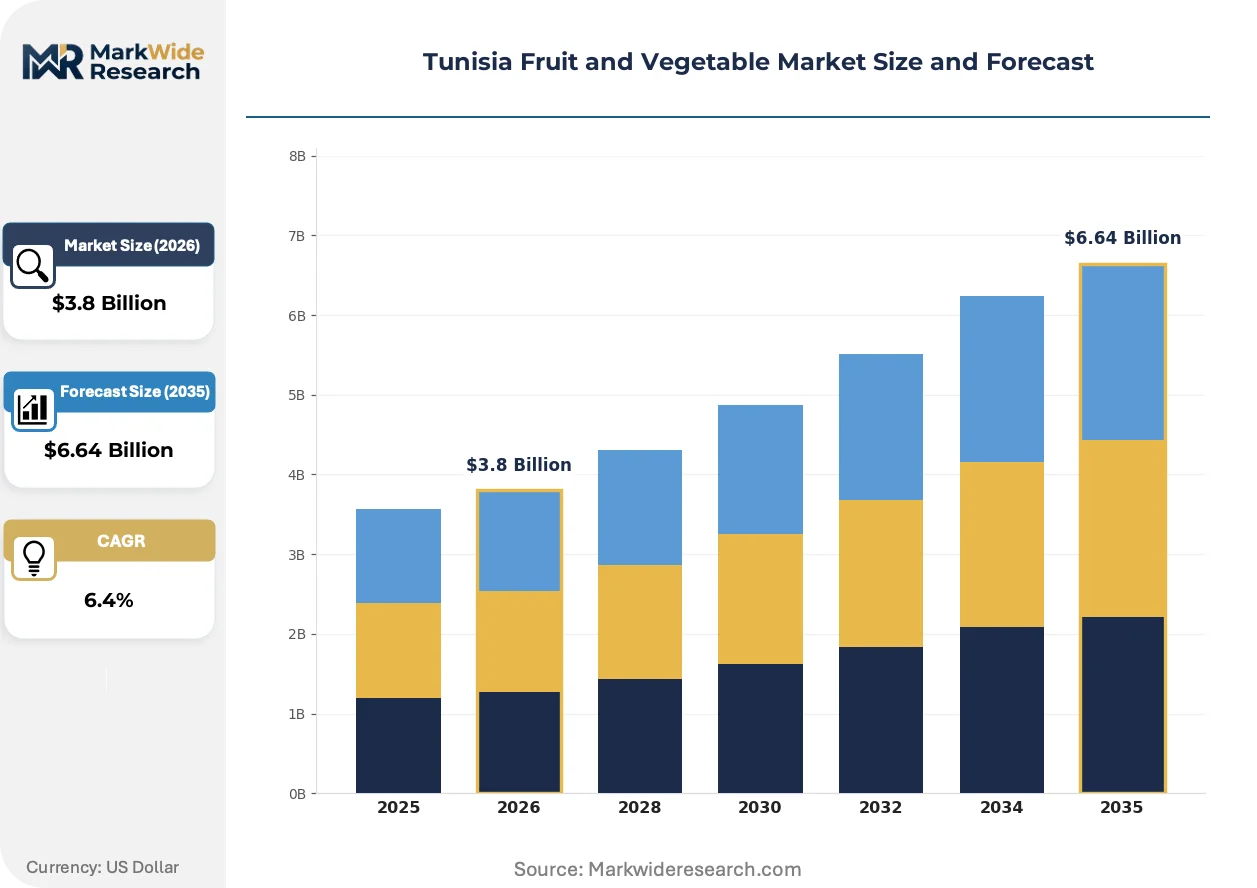
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citrus, Berries, Leafy Greens, Root Vegetables Distribution Channel: Supermarkets, Farmers' Markets, Online Retail, Food Service Packaging Type: Bags, Boxes, Trays, Cartons End User: Households, Restaurants, Food Processors, Exporters |
| Companies Covered | Les Jardins de Tunisie, Esca'Rome Holding Company, Groupement Interprofessionnel des Fruits (GIFRUITS), Vegetables Interprofessional Group (V.I.G), ECOFED, Dooda, Grown in Town, INSTAWARE, TerraSens, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tunisia Fruit and Vegetable Market Evolving Landscape
Greenhouse technology transfer and regulatory traceability mandates are converging to reshape how Tunisian produce reaches European and Gulf buyers. These shifts are compressing traditional intermediation layers while elevating capital requirements at the farm gate.
Spanish-developed substrate cultivation systems are decomposing the seasonal production limitations that historically constrained Tunisian berry exports. Hospitality procurement teams are specifying year-round strawberry and raspberry supply contracts that only hydroponic operations can fulfill. This technology adoption is concentrating volume among greenhouse-equipped growers and marginalizing open-field berry producers from premium channel access.
EU deforestation-free supply chain due diligence obligations are forcing farm-level geolocation documentation across Cap Bon citrus operations. The regulation requires polygon mapping of production plots and chain-of-custody verification through export channels. Smallholder aggregators are responding by deploying mobile data-collection applications that interface with central trade authority certification systems, compressing compliance timelines for export eligibility.
Hotel and restaurant buyers are unwinding decades-long relationships with informal wholesale intermediaries in favor of direct contracts with integrated greenhouse operators. This channel disintermediation is visible across Tunis and Sfax metropolitan areas, where procurement directors now mandate cold-chain temperature logs and pesticide residue testing as contract preconditions. Traditional souk-based traders are losing volume share to certified suppliers with in-house logistics capabilities.
Tunisia Fruit and Vegetable Market Segmentation
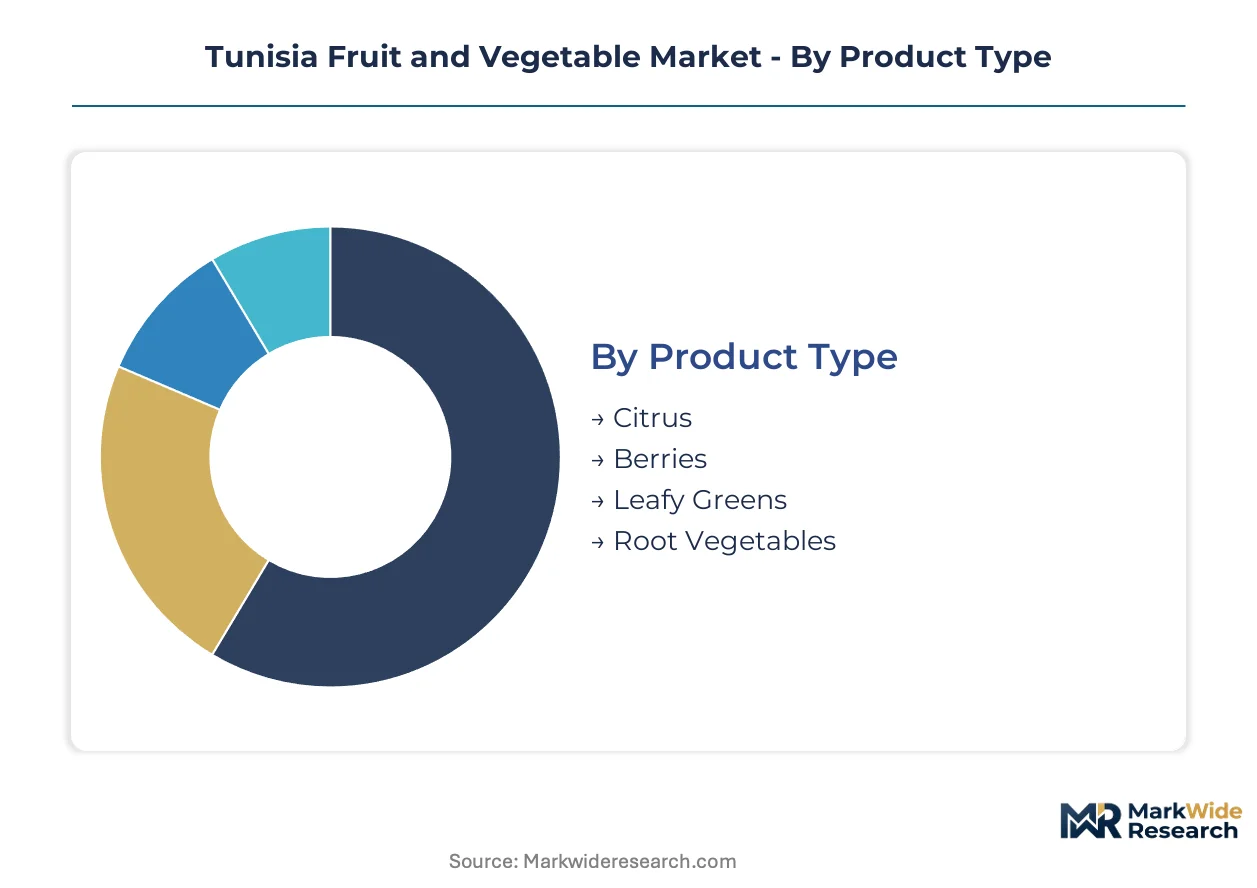
Segmentation in the Tunisia Fruit and Vegetable Market reveals how produce flows through diverging channels based on certification requirements, shelf-life demands, and buyer sophistication. Each dimension exposes structural fault lines between informal wholesale traditions and emerging formalized procurement.
Product Type:
Citrus and berries command premium cold-chain infrastructure while leafy greens and root vegetables serve distinct buyer tiers with varying traceability mandates.
- Citrus:Oranges, lemons, and clementines constitute the dominant export category, with Cap Bon peninsula growers supplying EU quota channels under phytosanitary certification from the central trade authority. Demand concentrates in European retail and processing, where EU Green Deal deforestation-free rules now require polygon-mapped farm geolocation for eligibility.
- Berries:Strawberries and raspberries from Sahel hydroponic operations exploit Spanish-transferred greenhouse protocols to extend production windows beyond traditional seasonal limits. Hospitality procurement in Tunis and Sfax metropolitan areas is capturing year-round supply contracts that exclude open-field competitors.
- Leafy Greens:Lettuce, spinach, and herbs from coastal hydroponic clusters serve Gulf retail premium positioning.
- Root Vegetables:Carrots, potatoes, and beets feed North African food processing demand with lower certification barriers.
Citrus dominates installed base. Berries is where expansion concentrates.
Distribution Channel:
Channel selection determines temperature control obligations, documentation requirements, and payment terms for Tunisian growers.
- Supermarkets:Carrefour, Monoprix, and Magasin Général operations mandate barcode traceability and hydrocooled delivery, favoring integrated greenhouse operators with in-house logistics over fragmented smallholder aggregators.
- Food Service:Domestic restaurant chains and hotel procurement teams now require cold-chain temperature logs and pesticide residue testing as contract preconditions, diverting volume from traditional wholesale souks toward certified suppliers like Les Jardins de Tunisie.
- Farmers' Markets:Traditional souk-based traders persist in interior governorates where irrigation licensing constraints limit formal channel development.
- Online Retail:Emerging platforms target urban households with modified-atmosphere packaged produce, though cold-chain last-mile capabilities remain concentrated in Greater Tunis.
Food Service captures margin expansion. Supermarkets anchor volume throughput.
Packaging Type:
Packaging specifications align with export eligibility requirements and retail presentation standards across diverging buyer segments.
- Trays:Modified-atmosphere trays with permeable film enable shelf-life extension for leafy greens and berries targeting Gulf retail premium channels, requiring capital investment beyond smallholder capacity.
- Cartons:Standardized citrus export cartons with hydrocooling compatibility dominate Cap Bon peninsula packinghouse output, configured for EU border inspection post documentation windows.
- Bags:Perforated polyethylene serves domestic informal channel root vegetable distribution with minimal cold-chain dependency.
- Boxes:Corrugated containers handle bulk food processor procurement with lower unit economics.
Cartons dominate export-grade throughput. Trays is climbing the fastest on premium channel penetration.
End User:
End-user categories stratify by traceability tolerance, volume scale, and price sensitivity across Tunisian production zones.
- Exporters:EU and Gulf-bound shipments require maximum residue level compliance enforced by the national food safety agency, plus phytosanitary certification from the central trade authority that smallholder aggregators like GIFRUITS coordinate through mobile data-collection applications.
- Restaurants:Hospitality procurement centralization in coastal cities is unwinding decades-long wholesale intermediary relationships, with procurement directors mandating direct contracts with integrated greenhouse operators for year-round tomato and pepper supply.
- Food Processors:Tunisian tomato paste manufacturers are contracting dedicated greenhouse supply to lock in raw material quality and traceability for export-oriented processing.
- Households:Traditional consumption persists through farmers' markets in interior governorates where water allocation rigidity constrains formal channel development.
Exporters anchor premium pricing. Restaurants is gaining share fastest on procurement centralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tunisian citrus and tomato exports flow primarily toward European Union markets under preferential trade agreements, while Gulf retail channels absorb expanding volumes of hydroponic leafy greens and berries from Sahel greenhouse operations.
Cap Bon Peninsula
Citrus cultivation dominates this northern coastal zone, where controlled-atmosphere storage investments support year-round export scheduling to France and Italy. The central trade authority administers phytosanitary certification from packinghouses concentrated around Nabeul and Menzel Bouzelfa. EU Green Deal deforestation-free supply chain rules are accelerating farm-level geolocation documentation across this cluster.
Sahel Region
Irrigated tomato and pepper production feeds both domestic processing and hospitality procurement in Tunis and Sfax metropolitan areas. Drip irrigation expansion incentivized by national agricultural modernization programs is consolidating supply under vertically integrated greenhouse operators. Sousse and Monastir harbor the cold-chain infrastructure enabling temperature-controlled delivery to restaurant chains.
Greater Tunis
Urban demand concentration is pulling produce sourcing away from traditional wholesale souks toward certified suppliers with hydrocooling capabilities. The national food safety agency's pesticide residue enforcement is disqualifying informal traders from hotel and restaurant contracts. Ariana and Ben Arous warehouse districts are emerging as logistics hubs for modified-atmosphere packaged distribution.
Sfax Governorate
Industrial tomato paste manufacturing anchors food processor backward integration into dedicated greenhouse supply contracts. Phosphate fertilizer dependency from Moroccan suppliers exposes margin volatility across this processing corridor. Kerkennah Islands and adjacent coastal zones maintain olive and citrus cultivation under stricter water allocation licensing than interior governorates.
Kairouan and Interior Governorates
Rain-fed cereal and olive cultivation persists where irrigation licensing rigidity constrains fruit and vegetable expansion despite groundwater availability. Traditional farmers' markets dominate distribution in these central zones, bypassing cold-chain requirements that coastal buyers mandate. The national agricultural ministry's licensing framework prioritizes coastal water access for export-oriented production.
Tunisia Fruit and Vegetable Market Competitive Landscape
Listed agribusinesses compete with private family-held specialists across greenhouse operations and cold-chain logistics, producing a tiered structure where scale-driven exporters coexist with regional procurement aggregators. Three archetypes dominate: integrated greenhouse operators with in-house logistics, smallholder aggregators coordinating phytosanitary compliance, and hospitality-focused suppliers with direct restaurant contracts. Capacity expansion in controlled-atmosphere storage and backward integration into dedicated crop supply represent the primary competitive moves reshaping procurement relationships.
Among Tunisia-based operators, Les Jardins de Tunisie exemplifies the integrated greenhouse archetype through its year-round tomato and pepper supply positioning for hospitality clients. Esca'Rome Holding Company occupies a position within the cold-chain infrastructure tier, while Groupement Interprofessionnel des Fruits (GIFRUITS) represents the smallholder aggregation model coordinating citrus export compliance. These three entities illustrate how certification capabilities and logistics ownership are separating formal channel suppliers from traditional wholesale intermediaries.
| Leading Market Players |
|---|
| Les Jardins de Tunisie |
| Esca'Rome Holding Company |
| Groupement Interprofessionnel des Fruits (GIFRUITS) |
| Vegetables Interprofessional Group (V.I.G) |
| ECOFED |
| Dooda |
| Grown in Town |
| INSTAWARE |
| TerraSens |
| Others |
Value Network & Pricing Analysis
Forty-eight-hour hydrocooling turnaround windows at Cap Bon peninsula packinghouses concentrate pricing power among controlled-atmosphere storage operators, while informal souk traders absorb margin compression from cold-chain bypass. EU phytosanitary certification timelines tether export-grade citrus premiums to logistics coordination capabilities that smallholder aggregators struggle to match.
Pricing Analysis
Greenhouse-generation pricing gaps separate Spanish-protocol hydroponic berry operations from open-field seasonal producers, with three-tier pricing structure across premium, standard, and economy levels anchored to cold-chain documentation completeness. Certification grade under EU Green Deal deforestation-free rules and volume scale through dedicated offtake contracts drive price differentiation, while phosphate fertilizer import volatility from Moroccan suppliers squeezes margins across processing-oriented root vegetable tiers. Hotel procurement teams show lowest price sensitivity, prioritizing year-round supply security over per-unit cost.
Supply Chain Analysis
Port congestion at La Goulette and Rades container terminals elevates inbound logistics costs for polyethylene greenhouse sheeting and Spanish-developed substrate systems, compressing deployment timelines for protected agriculture expansion. Supply concentrates in Tunisia, Morocco, and Spain for critical inputs, with steel framing and drip irrigation components drawing from EU manufacturing hubs. Single-source vulnerability clusters around Cap Bon peninsula cold-storage infrastructure, while distribution runs through vertically integrated greenhouse operators with direct hospitality contracts rather than traditional wholesale souks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tunisia's fruit and vegetable sector is cycling through agricultural modernization program maturation, with drip irrigation subsidy phases and greenhouse technology transfer waves creating recoverable expansion windows for capitalized operators.
For Market Incumbents: Shield market position through controlled-atmosphere capacity additions in Sfax and Monastir logistics corridors, countering Esca'Rome Holding Company's storage concentration risk. Deepen backward integration into dedicated tomato and pepper supply contracts with food processors, locking in volume against informal channel price undercutting. Prioritize biocontrol technical service investments as the national food safety agency tightens maximum residue enforcement.
For New Entrants and Emerging Players: Cold-chain technician recruitment gaps present service-layer white space for specialized refrigeration maintenance and hydrocooling calibration providers targeting Cap Bon and Sahel greenhouse clusters. Target interior governorate farmers' market digitization, where water allocation licensing constraints have stalled formal channel development. Deploy mobile data-collection applications for smallholder geolocation documentation, capturing EU deforestation-free compliance service fees from GIFRUITS-type aggregators.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hydroponic berry operations as Spanish technology transfer elevates polyethylene and substrate input requirements. Long-term viability over the next decade rests on irrigation licensing reform and Gulf retail premium channel penetration velocity. Monitor phosphate fertilizer price volatility signals from Moroccan supplier negotiations as margin compression indicator for processing corridor exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Atmosphere Storage Expansion | Esca'Rome-type investments in Sfax de-risk Cap Bon single-point vulnerability for export citrus scheduling. |
| Backward Integration into Greenhouse Supply | Tomato paste manufacturers contracting dedicated production lock in traceability for EU-bound processing exports. |
| Biocontrol Technical Service Development | Integrated pest management subsidy expansion opens recurring revenue niches for compliance support providers. |
| Mobile Geolocation Documentation Platforms | Smallholder aggregators deploying polygon-mapping applications compress EU deforestation-free certification timelines. |
| Gulf Retail Premium Channel Partnerships | Sahel hydroponic leafy greens operators capturing UAE and Saudi supermarket shelf space command price premiums over Egyptian competitors. |
Research Methodology
A spread of perspectives from greenhouse operations managers, hospitality procurement directors, central trade authority certification officers, and food processor supply chain leads converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through customs export records, national agricultural ministry irrigation licensing databases, and EU phytosanitary border inspection post documentation. Bottom-up volume modeling across Cap Bon citrus clusters and Sahel tomato operations triangulated against top-down trade flow analysis.
Segmentation dimensions modeled include product type, distribution channel, packaging format, and end-user category across the projection horizon. CAGRs derive from installed base expansion rates and technology adoption curves for Spanish-transferred greenhouse protocols, with forecast inputs incorporating water allocation licensing trajectory scenarios and phosphate fertilizer import price elasticity assumptions.
Material uncertainties — irrigation licensing reform timing, EU deforestation-free enforcement stringency, Gulf retail buyer consolidation patterns — sit outside the modeled envelope. Forecasts reflect documented assumptions about technology transfer velocity and subsidy program continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Banana Flakes Market
Fruits and Vegetables
Freeze-Dried Fruit Powder Market
Fruits and Vegetables
Dehydrated Beets Market
Fruits and Vegetables
Fresh Peaches Market
Fruits and Vegetables
Uruguay Fruits and Vegetables Market
Fruits and Vegetables
Kiwi Fruit Market
Fruits and Vegetables
Middle East and Africa Sweet Potatoes Market
Fruits and Vegetables
Global Fruit Concentrate Puree Market
Fruits and Vegetables
Aubergine Market
Fruits and Vegetables
Vegetable Puree Market
Fruits and Vegetables
Lingonberry Market
Fruits and Vegetables
Frozen Fruits Market
Fruits and Vegetables
Fresh Cherries Market
Fruits and Vegetables
Europe Freeze-Dried Fruits and Vegetable Market
Fruits and Vegetables
Kuwait Vegetables and Fruits Market
Fruits and Vegetables
United States Frozen Fruits and Vegetables Market