
 Fruit and Vegetable Pieces and Powders Market | 2026-2036
Fruit and Vegetable Pieces and Powders Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit and Vegetable Pieces and Powders Market Foresight
Subscription-based technical support and recipe formulation services is decoupling ingredient supply from finished-product development. Cargill leverages its global sourcing infrastructure to secure year-round raw material availability across temperate and tropical growing regions. SunOpta anchors its competitive position through certified organic and non-GMO processing lines that command premium positioning in North American retail channels. Olam Group dominates upstream procurement by operating integrated drying and milling facilities proximate to major fruit and vegetable cultivation zones in Asia and Africa.
Fruit and vegetable pieces and powders constitute dehydrated plant-derived materials processed through thermal, mechanical, or sublimation methods to achieve moisture levels typically below 7%, yielding shelf-stable inputs for formulated foods and beverages. Spray-dried powders retain volatile aromatic compounds and exhibit rapid rehydration kinetics, making them preferred for beverage applications and instant soup bases. Freeze-dried segments command superior price realization due to structural integrity preservation and minimal heat degradation of ascorbic acid and anthocyanin fractions. Convenience foods and nutraceutical applications absorb expanding volumes as manufacturers substitute synthetic additives with recognizable plant-derived colorants, flavor carriers, and fiber fortificants.
The FDA enforces Hazard Analysis Critical Control Point protocols and Food Safety Modernization Act traceability mandates that elevate capital requirements for domestic processors. EFSA and national regulators across European member states apply maximum residue limits for pesticides and heavy metals that constrain sourcing from non-compliant cultivation regions. Stakeholders must monitor evolving clean-label certification thresholds and carbon disclosure obligations that will progressively filter supplier eligibility and reshape procurement qualification criteria.
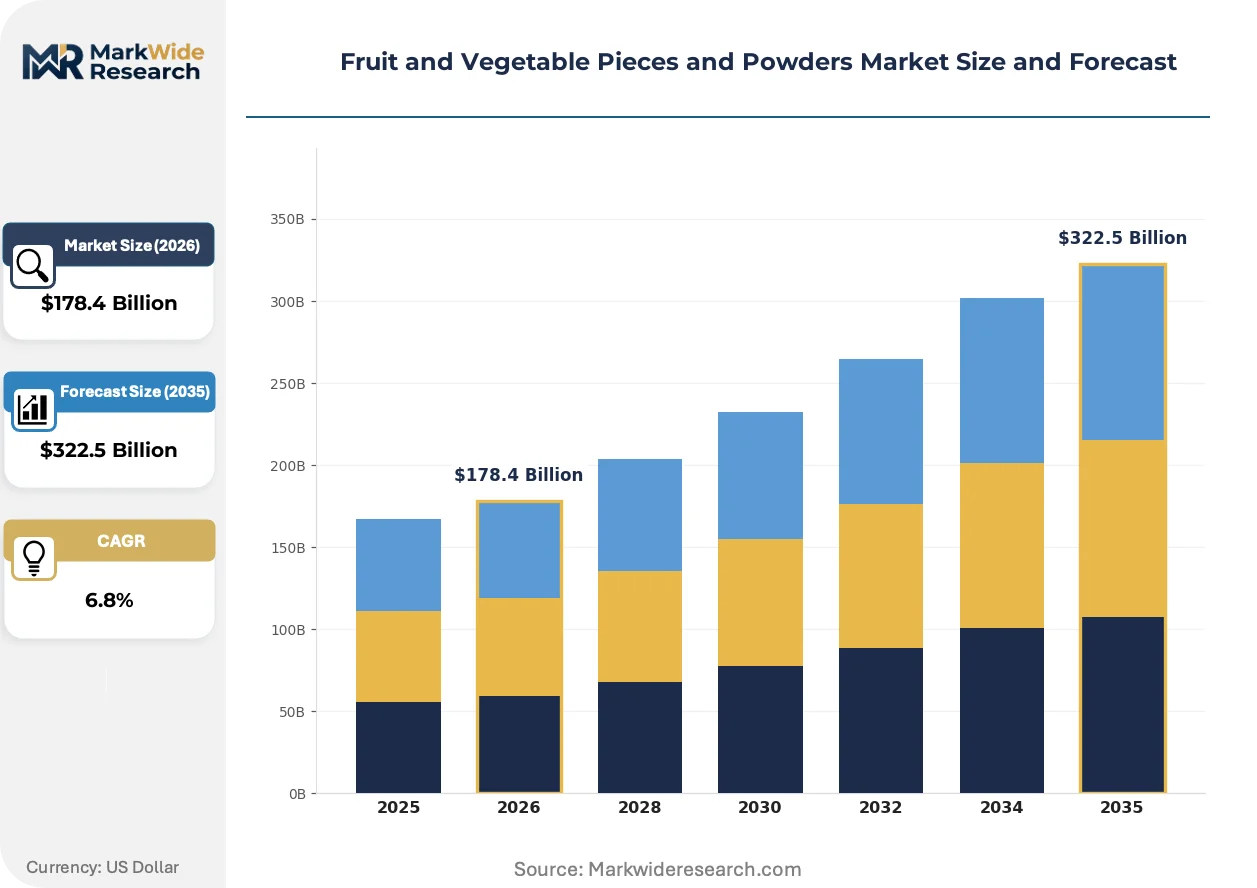
Market Dynamics
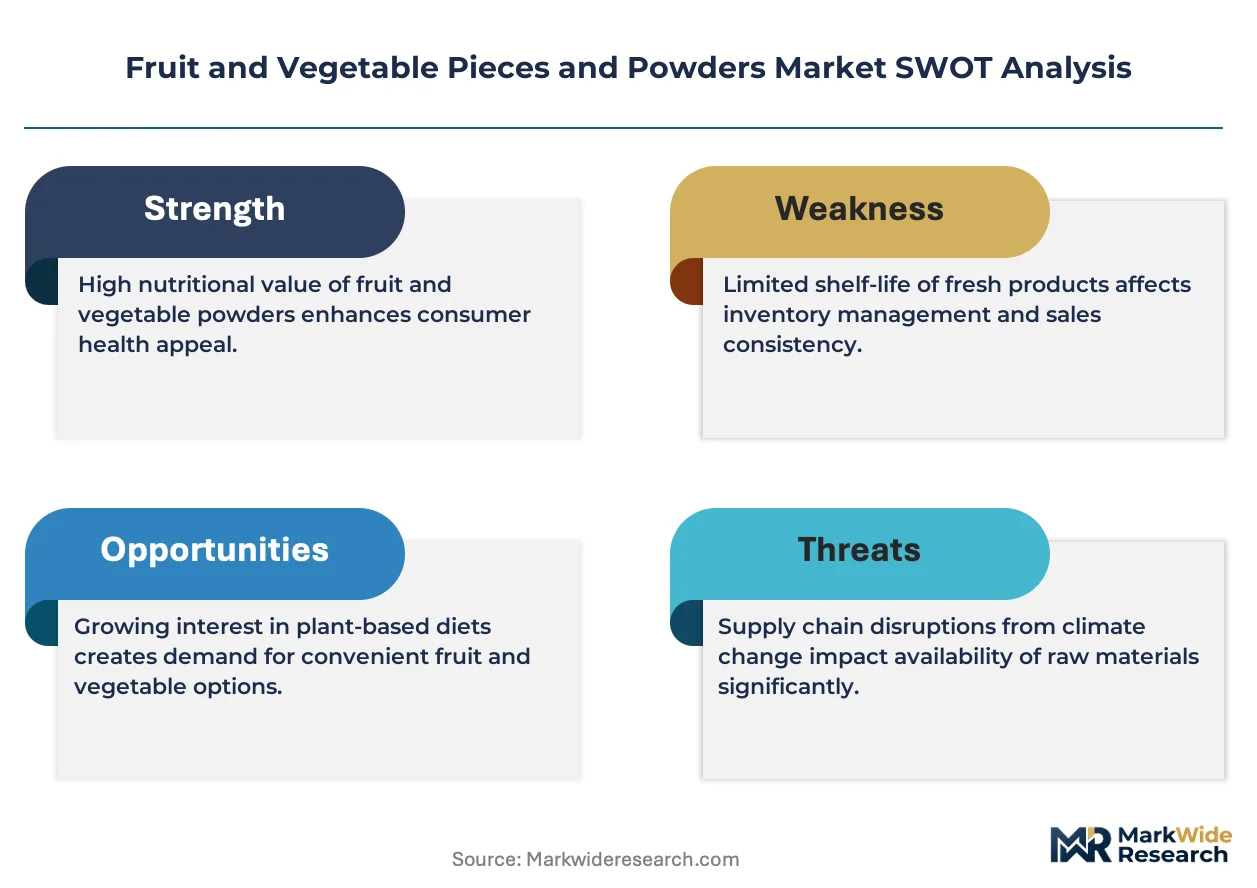
Clean-label procurement mandates from quick-service restaurant chains are compressing supplier qualification timelines and forcing capital upgrades across domestic processing facilities. This demand-side pressure is restructuring competitive positioning around certified organic capacity and third-party audit transparency rather than commodity scale alone.
Growth Catalysts
- FSMA traceability mandates:The FDA's enhanced record-keeping requirements are filtering out informal suppliers and consolidating volume with HACCP-certified processors capable of lot-level digital tracking.
- Beverage formulation demand:Instant drink mix manufacturers are absorbing expanding spray-dried powder volumes for rapid-dissolve applications in fortified hydration products.
- Freeze-drying technology diffusion:Substantial investment in lyophilization capacity across temperate growing regions is expanding supply of structurally intact fruit pieces for premium cereal and snack applications.
Market Restraints
- Input cost volatility:Energy-intensive thermal drying processes expose processors to natural gas price swings that compress margin at contract-renewal cycles.
- Regulatory friction:EFSA maximum residue limits for pesticides block sourcing from non-compliant cultivation zones in Eastern Europe and Central Asia, constraining raw material optionality.
- Substitution threat:Synthetic colorants and flavor systems retain cost advantages in economy-tier applications, limiting plant-derived powder penetration in private-label budget segments.
Strategic Opportunities
- Carbon disclosure tailwinds:The EU Green Deal's Scope 3 reporting requirements are creating preferential procurement channels for processors with verified low-emission drying operations.
- Nutraceutical convergence:Anthocyanin-rich berry powders are capturing new demand from dietary supplement formulators seeking standardized polyphenol content for capsule and tablet applications.
- Direct-to-manufacturer channels:E-commerce platforms are disintermediating traditional ingredient distributors for mid-sized craft food producers seeking smaller minimum order quantities.
Industry Challenges
- Certification timeline compression:USDA organic and non-GMO Project Verified audit cycles are extending 40-60 days due to inspector availability constraints, delaying new product launches.
- Legacy equipment integration:Retrofitting existing spray-dryer lines with real-time moisture sensors and automated CIP systems requires substantial downtime that conflicts with just-in-time contract obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit and Vegetable Pieces and Powders Market |
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $322.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Form: Freeze-Dried, Spray-Dried, Air-Dried, Vacuum-Dried, Dehydrated Pieces, Pulverized Powders Application: Bakery, Dairy Alternatives, Nutraceuticals, Convenience Foods, Infant Nutrition, Soup & Sauces End User: Food Manufacturers, Beverage Companies, Dietary Supplement Producers, Culinary Professionals, Foodservice Operators Packaging Type: Stand-Up Pouches, Sachets, Bulk Bags, Vacuum Sealed Packs, Resealable Jars |
| Companies Covered | Olam Group, SunOpta, Döhler Group, Archer Daniels Midland Company, Cargill, Sensient Technologies, Agrana Group, Symrise, Van Drunen Farms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit and Vegetable Pieces and Powders Market Shifts & Advancements
Processing technology convergence and regulatory transparency mandates are reconfiguring how dehydrated ingredients move from field to formulation. These shifts favor capital-intensive operators with integrated quality systems over fragmented toll processors.
Hybrid drying systems combining infrared pre-treatment with conventional air-drying are modularizing production layouts across mid-scale facilities. Snack manufacturers in the United States are adopting these configurations to reduce thermal degradation in delicate vegetable matrices. The technology is modularizing plant floor arrangements, enabling processors to switch between piece and powder formats without complete line shutdowns.
The EU Green Deal's corporate sustainability reporting directive is mandating granular carbon accounting across imported agricultural inputs. European processors must now document embodied emissions from cultivation through drying, reshaping supplier qualification criteria. Food and beverage manufacturers in Germany and France are responding by consolidating procurement with vertically integrated operators possessing farm-to-facility traceability systems.
Subscription-based technical support packages are displacing transactional ingredient sales in mid-market accounts. Recipe formulation services bundled with supply contracts allow smaller brands to access R&D capabilities previously reserved for multinational partners. This model is concentrating in North American metropolitan food innovation clusters where startup density justifies dedicated application laboratories.
Fruit and Vegetable Pieces and Powders Market Segmentation
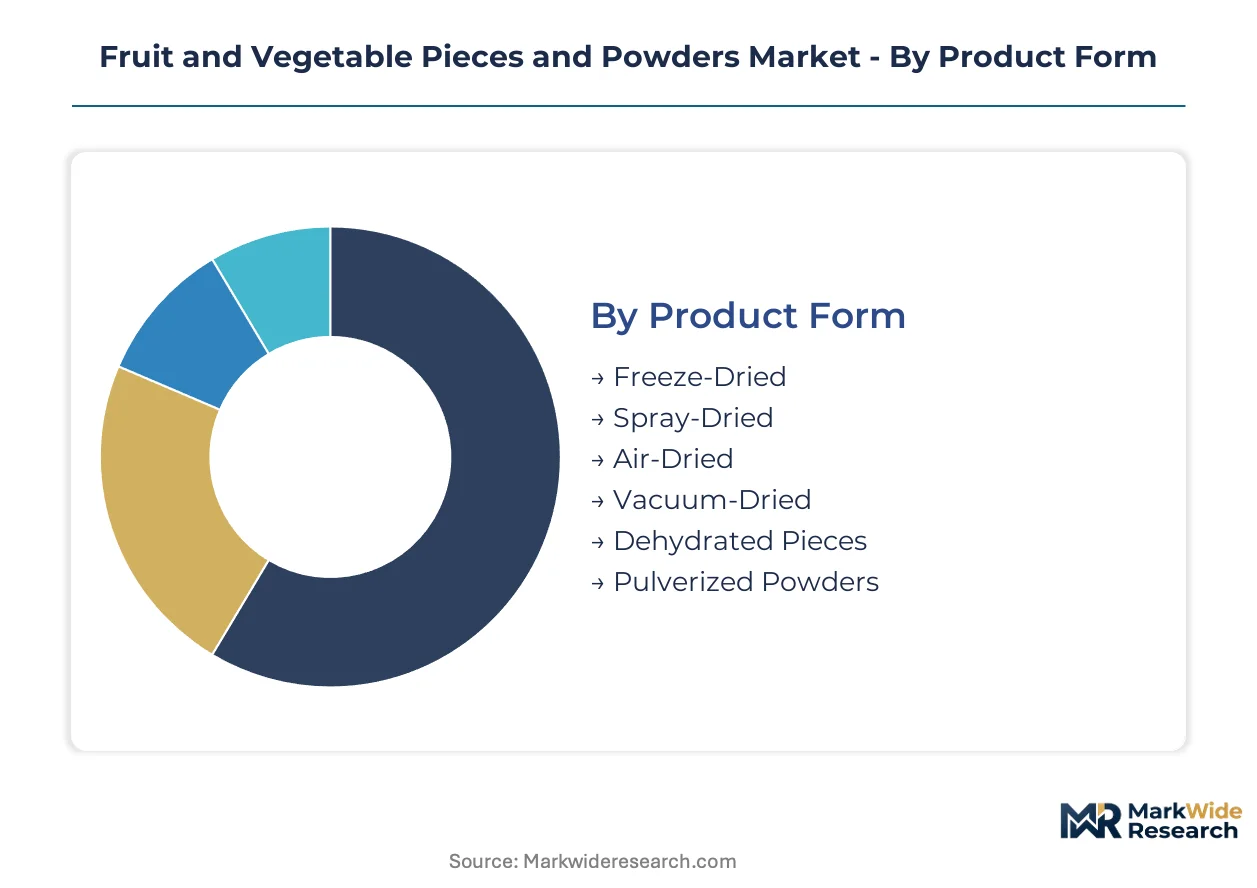
Processing technology and application requirements create distinct performance tiers across the Fruit and Vegetable Pieces and Powders Market. Each segment exhibits unique moisture specifications, rehydration kinetics, and shelf-stability profiles that dictate procurement patterns among food manufacturers and nutraceutical formulators.
Product Form:
Equipment upgrade cycles and drying technology maturation are reconfiguring capacity allocation across processing facilities. Facilities retiring legacy air-dryer lines face capital decisions between spray-drying speed advantages and freeze-drying quality premiums.
- Freeze-Dried:Sublimation removes ice crystals directly from frozen matrices, preserving cellular structure and volatile aromatic compounds. Premium cereal manufacturers in the United States absorb expanding volumes for intact fruit pieces that withstand mechanical handling during coating and packaging operations.
- Spray-Dried:Atomized liquid feeds encounter hot air streams, producing fine powders with rapid dissolution kinetics. Instant beverage mixers and soup base formulators specify these inputs for homogeneous dispersion without sedimentation.
- Air-Dried:Convective thermal processing yields economical pieces with moderate structural degradation. Budget snack seasoning applications tolerate texture compromise for cost containment.
- Vacuum-Dried:Reduced-pressure environments lower boiling points, protecting heat-sensitive pigments. Specialty nutraceutical extract processors favor this method for anthocyanin retention in berry matrices.
- Dehydrated Pieces:Belt or tray configurations produce irregular chunks for visual recognition in finished products. Trail mix and granola manufacturers specify these for consumer-perceived authenticity.
- Pulverized Powders:Post-dry milling achieves sub-100-micron particle sizes for seamless incorporation into extruded bars. Protein fortification brands demand these for mouthfeel neutrality.
Volume placements concentrate in Spray-Dried; the faster expansion belongs to Freeze-Dried.
Application:
Formulation complexity and clean-label mandates are elevating ingredient specification stringency across downstream categories. Procurement teams now audit supplier capabilities against finished-product positioning tiers rather than commodity availability alone.
- Convenience Foods:Ready-meal manufacturers substitute synthetic additives with recognizable vegetable powders for color and fiber fortification. Frozen pizza and pasta sauce producers drive specification volume for tomato and spinach derivatives.
- Nutraceuticals:Standardized polyphenol content in berry powders supports capsule and tablet claims. Dietary supplement contract manufacturers in Germany and France qualify suppliers against EFSA health claim substantiation requirements.
- Bakery:Fruit pieces distribute moisture differentially through dough matrices, requiring controlled water activity specifications. Artisan and industrial bakers specify vacuum-dried alternatives for reduced hydration interference.
- Dairy Alternatives:Oat and almond milk formulators leverage vegetable powders for natural coloring without carrageenan controversies. Barista-grade product lines demand batch-to-batch chromatic consistency.
- Infant Nutrition:Stringent contaminant thresholds per FDA infant formula regulations constrain qualified supplier pools. Organic carrot and sweet potato powders dominate first-food purees.
- Soup & Sauces:Rapid-reconstitution requirements favor fine-mesh powders with minimal lump formation. Foodservice pouch formats specify these for hot-hold buffet applications.
Procurement volume tilts toward Convenience Foods; Nutraceuticals command the steepest expansion trajectory.
End User:
Customer scale and technical service requirements are fragmenting sales channel configurations. Large accounts negotiate direct supply agreements with integrated processors while mid-tier buyers migrate toward distributor platforms with formulation support.
- Food Manufacturers:Cereal, snack, and baked goods producers constitute the dominant demand base. Quick-service restaurant supply chains impose HACCP documentation and lot-level traceability mandates.
- Beverage Companies:Powdered drink mix and functional hydration brands specify spray-dried inputs for turbidity control. Sports nutrition lines demand rapid-dissolve kinetics.
- Dietary Supplement Producers:Capsule and tablet formulators prioritize standardized marker compound content over flavor profiles. Third-party testing certificates determine supplier qualification.
- Culinary Professionals:Restaurant and catering operations source resealable formats for mise en place efficiency. Flavor intensity per unit volume drives purchasing decisions.
- Foodservice Operators:Institutional feeding programs balance cost containment against nutritional disclosure requirements. School meal programs specify USDA-compliant fruit and vegetable contribution equivalents.
Contract concentration resides with Food Manufacturers; Beverage Companies are gaining share fastest.
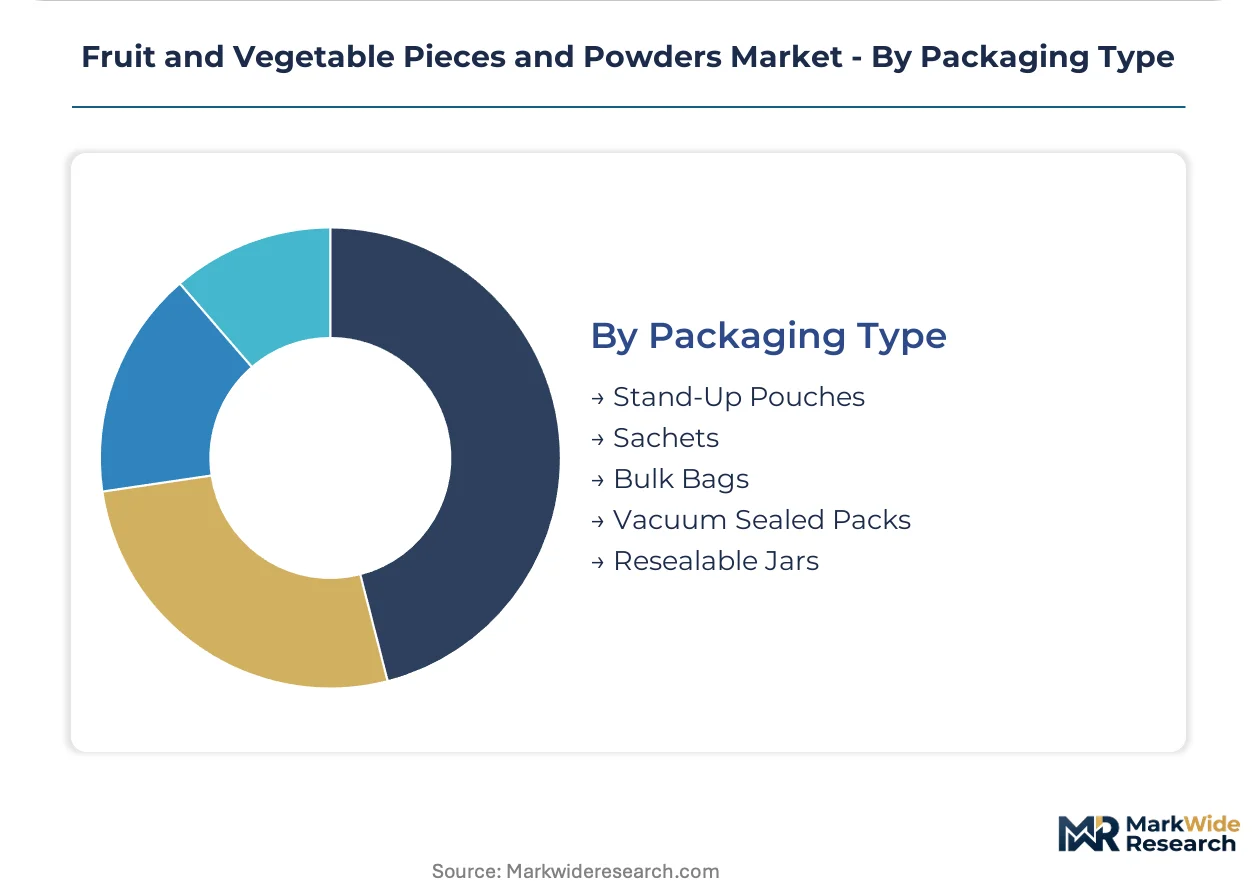
Packaging Type:
Distribution channel requirements and handling durability specifications are diversifying format portfolios. E-commerce penetration is accelerating demand for ship-ready configurations with minimal dimensional weight penalties.
- Bulk Bags:Food manufacturers with internal blending operations specify 25-50 kg formats for ingredient handling efficiency. Pneumatic conveying compatibility determines valve and spout configurations.
- Stand-Up Pouches:Retail-facing brands favor shelf presence and reseal functionality. Granola and trail mix producers specify these for club store multipacks.
- Vacuum Sealed Packs:Oxygen exclusion extends color stability in anthocyanin-rich powders. Premium nutraceutical direct-to-consumer brands specify these for oxidation-sensitive contents.
- Resealable Jars:Culinary professionals and home bakers prioritize access convenience and countertop storage. Spice and seasoning category conventions influence format expectations.
- Sachets:Single-serve portions support foodservice portion control and sampling programs. Instant beverage stick packs dominate hotel and airline amenity specifications.
Shipment volumes cluster in Bulk Bags; Stand-Up Pouches demonstrate the most rapid adoption curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States processes the majority of global fruit and vegetable pieces and powders, yet consumption spreads across Germany, China, and Brazil where food manufacturers import dehydrated inputs for finished goods production.
United States
Quick-service restaurant chains and retail private-label programs absorb the dominant share of domestic spray-dried and freeze-dried output. FDA Food Safety Modernization Act traceability mandates filter supplier pools toward HACCP-certified processors with lot-level digital tracking. California's Central Valley hosts integrated drying facilities proximate to tomato, strawberry, and spinach cultivation zones.
Germany
EFSA maximum residue limits constrain raw material sourcing to compliant cultivation regions, elevating procurement qualification stringency for berry powder imports. The EU Green Deal's corporate sustainability reporting directive mandates granular carbon accounting across imported agricultural inputs. Bavarian nutraceutical contract manufacturers consolidate procurement with vertically integrated operators possessing farm-to-facility traceability.
China
Domestic food and beverage manufacturers substitute synthetic additives with recognizable plant-derived colorants in convenience food formulations. National food safety standards enforced by SAMR govern microbial and contaminant thresholds for dehydrated vegetable powders. Shandong Province's processing clusters specialize in garlic, onion, and ginger derivatives for export markets.
India
FSSAI regulations on pesticide residues and heavy metals block informal suppliers from qualified procurement channels serving export-oriented food manufacturers. Maharashtra and Gujarat host integrated drying facilities serving mango, banana, and tomato powder production for Middle Eastern and European buyers. Contract manufacturers in these states upgrade spray-dryer lines to meet EU organic certification thresholds.
Brazil
ANVISA enforces contaminant thresholds for dehydrated fruit inputs used in infant nutrition and dietary supplement applications. São Paulo-based food manufacturers source açaí and acerola powders for natural coloring in dairy alternatives and functional beverages. Minas Gerais cultivation zones supply raw material to integrated processors with certified organic capacity.
Fruit and Vegetable Pieces and Powders Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Fruit and Vegetable Pieces and Powders Market. Integrated processors with captive drying and milling facilities control upstream procurement and command premium positioning through certified organic lines. Asset-light formulators and toll processors compete on recipe development services and flexible minimum order quantities. Strategic moves concentrate on backward integration into cultivation zones and third-party audit transparency investments that accelerate supplier qualification timelines.
Within the integrated processor tier, Olam Group and Cargill exemplify archetypes that anchor competitive positioning through global sourcing infrastructure and year-round raw material availability. SunOpta occupies a position among North American operators with certified organic and non-GMO processing lines that command premium retail channel placement. These three companies represent the dominant competitive anchors structuring procurement consolidation around traceability capabilities and clean-label certification depth.
| Leading Market Players |
|---|
| Olam Group |
| SunOpta |
| Döhler Group |
| Archer Daniels Midland Company |
| Cargill |
| Sensient Technologies |
| Agrana Group |
| Symrise |
| Van Drunen Farms |
| Others |
Supply & Pricing Matrix
Skilled lyophilization technicians concentrated in California's Central Valley widen cost spreads between freeze-dried premium tiers and air-dried economy grades. Labor-cost differentials between temperate-zone drying facilities and tropical processing clusters feed directly into three-tier pricing stratification across certification levels.
Pricing Analysis
Margin tightening in spray-dried commodity tiers traces to natural gas price volatility compressing thermal drying economics. Three-tier pricing structure across premium, standard, and economy levels separates freeze-dried organic lines from conventional spray-dried powders and budget air-dried pieces. Price differentiation rests on USDA organic certification depth and HACCP audit transparency rather than volume scale alone. Quick-service restaurant chains exhibit lowest price sensitivity for traceable supply, while private-label budget segments drive hardest cost negotiations.
Supply Chain Analysis
Single-source vulnerability sits with Egyptian onion and Chinese garlic concentrate supplies for European flavor houses. Raw material procurement draws from California's tomato belt, Maharashtra's mango zones, and Minas Gerais açaí cultivation. Supply chain risk centers on EFSA maximum residue limits blocking Eastern European sourcing alternatives. Distribution runs through integrated processors with captive drying capacity rather than fragmented toll processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freeze-drying technology diffusion is displacing legacy air-drying infrastructure across mid-scale facilities, creating capability gaps between technology leaders and laggards.
For Market Incumbents: Anchor competitive position through backward integration into certified organic cultivation zones in California and Minas Gerais. Defend against asset-light formulators by accelerating third-party audit transparency investments that compress supplier qualification timelines for quick-service restaurant chains. Prioritize retrofitting spray-dryer lines with real-time moisture sensors to meet FSMA traceability mandates without production downtime.
For New Entrants and Emerging Players: Begin with nutraceutical-grade berry powder segments where standardized anthocyanin content commands premium positioning. Target dietary supplement contract manufacturers in Germany and France seeking EFSA-compliant suppliers with farm-to-facility traceability. Pursue direct-to-manufacturer e-commerce channels that disintermediate traditional distributors for mid-sized craft food producers.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated processors possessing certified organic capacity given EU Green Deal Scope 3 reporting requirements. Long-term viability favors operators with captive supply chains spanning temperate and tropical growing regions. Monitor carbon disclosure verification rates as the inflection signal for procurement consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Freeze-Drying Capacity Expansion | Lyophilization investment in California and Bavaria captures premium cereal and nutraceutical demand. |
| Backward Integration into Cultivation | Farm-to-facility traceability systems satisfy EU Green Deal carbon accounting mandates. |
| Certified Organic Line Addition | USDA and non-GMO Project Verified capacity commands North American retail channel premiums. |
| Direct-to-Manufacturer E-Commerce Launch | Smaller minimum order quantities attract craft food producers in metropolitan innovation clusters. |
| Recipe Formulation Service Bundling | Subscription-based technical support displaces transactional sales in mid-market accounts. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with plant managers at integrated drying facilities, procurement leads at quick-service restaurant chains, category buyers at retail private-label programs, and regulatory affairs directors at multinational processors combined with FDA FSMA documentation, EFSA residue limit databases, and USDA organic certification records. Bottom-up capacity assessments across California, Maharashtra, and Minas Gerais processing clusters triangulated against top-down demand estimates from food manufacturer procurement surveys.
Segment-level modeling applied distinct growth assumptions across freeze-dried, spray-dried, and air-dried product forms; convenience foods, nutraceuticals, and infant nutrition applications; and food manufacturer, beverage company, and dietary supplement producer end users. CAGRs derived from historical volume trajectories adjusted for technology substitution rates and regulatory compliance cost escalations. Forecast inputs incorporated energy price sensitivity for thermal drying processes and organic certification penetration curves across regional markets.
Underlying measurement precision varies by segment; freeze-dried and nutraceutical categories carry tighter precision than commodity air-dried grades given consolidated supplier transparency. Forecasts reflect assumptions on FSMA enforcement intensity, EU carbon disclosure phase-in timing, and natural gas price stabilization that could materially revise trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Venezuela Fruits and Vegetable Market
Fruits and Vegetables
Uruguay Fruits and Vegetables Market
Fruits and Vegetables
Vietnam Fruits and Vegetables Market
Fruits and Vegetables
Ackee Market
Fruits and Vegetables
Dried Berries Market
Fruits and Vegetables
Europe Kiwi Fruit Market
Fruits and Vegetables
Brazil Fruits and Vegetables Market
Fruits and Vegetables
Fresh Strawberry Market
Fruits and Vegetables
Egypt Fruits and Vegetables Market
Fruits and Vegetables
Brined Vegetable Market
Fruits and Vegetables
Global IQF Fruits Market
Fruits and Vegetables
Global Jalapeno Pepper Market
Fruits and Vegetables
United Kingdom Berries Market
Fruits and Vegetables
Global Not from Concentrate (NFC) Puree Market
Fruits and Vegetables
Dragon Fruit Powder Market
Fruits and Vegetables
Mexico Fruits & Vegetables Market