
 Green Sic Market | 2026-2036
Green Sic Market Size, Share, and Industry Trends Forecast 2026-2036
Green Sic Market Analysis
The price-performance gap between automotive-grade SiC substrates and commodity abrasives is hardening as wafer manufacturers enforce stricter defect density thresholds. Wolfspeed anchors North American supply through captive crystal growth capacity in New York. STMicroelectronics differentiates via integrated device-and-substrate verticality from its Italian and Singapore facilities. ROHM Co., Ltd. dominates Japanese automotive qualification pipelines with tier-one OEM design-ins.
Green silicon carbide designates synthetically produced alpha-phase SiC crystals with purity exceeding 99% and hexagonal polytype structures optimized for high-breakdown-voltage applications. Manufacturers synthesize it via the Acheson process or chemical vapor deposition, then process it into wafers, power devices, substrates, and discrete components for energy conversion systems. SiC wafers command the dominant value pool due to substrate scarcity and long crystal growth cycles. SiC power devices for electric vehicles represent the fastest-expanding application segment as 800V architectures displace silicon IGBTs. LED lighting applications mature with slower growth but stable replacement demand from industrial luminaire OEMs.
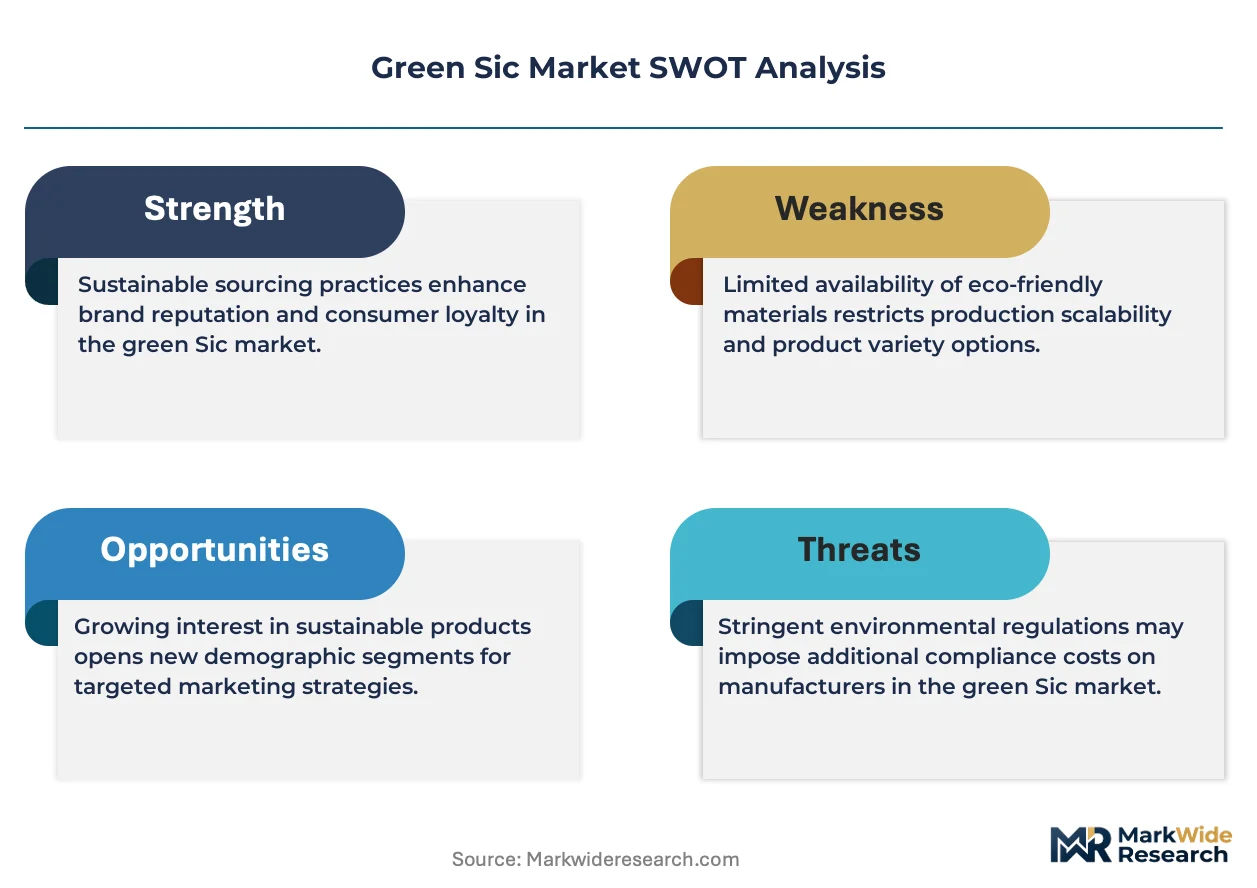
The EPA's emerging semiconductor facility emissions framework and the EU's CSRD supply-chain disclosure rules compel substrate producers to document carbon intensity per wafer. China's MIIT GB standards enforce domestic content ratios in state-backed EV platforms, reshaping vendor qualification criteria. Japan's METI subsidizes SiC foundry investments under its semiconductor revitalization roadmap. Stakeholders must monitor which regulatory jurisdiction certifies their customer's end-product first, as divergent testing protocols fragment market access timelines.
Market Dynamics
Automotive powertrain electrification is compressing qualification timelines for 150mm SiC substrates as OEMs race to certify 800V architectures ahead of model-year deadlines.
Growth Catalysts
- China's NMPA dual carbon goals:Domestic EV platforms must meet carbon intensity benchmarks that favor SiC efficiency gains over silicon IGBTs, accelerating foundry partnerships.
- EU F-Gas Regulation:Fluorinated gas phase-down mandates in semiconductor etching processes push manufacturers toward greener substrate production chemistries.
- 150mm wafer migration:Equipment makers in Germany's automotive corridor are retooling crystal growth furnaces for larger-diameter boules that cut device cost per ampere.
Market Restraints
- Feedstock purity bottlenecks:Acheson-grade petroleum coke and silica sand with sub-50ppm metallic contamination command 3-4x spot premiums over metallurgical silicon carbide inputs.
- Single-source crystal growth equipment:German and Japanese furnace OEMs control 90% of high-temperature reactor supply, creating capex queue risks for new entrants.
- Physical vapor transport yield limits:Defect-free micropipe densities below 1/cm² remain elusive in production-scale boules, culling usable wafer area.
Strategic Opportunities
- India's PLI scheme for semiconductors:Subsidies for compound semiconductor fabs create first-mover substrate qualification pathways outside established East Asian supply chains.
- Grid-scale inverter retrofit cycles:Aging silicon-based solar inverters in European utility portfolios face replacement windows that favor SiC module efficiency gains.
- GaN-SiC hybrid module convergence:Power designers are blending gallium nitride switches with SiC diodes for mid-voltage EV auxiliary systems, expanding addressable wafer demand.
Industry Challenges
- Crystal growth technician scarcity:PVT furnace operation and defect characterization require 5-7 year apprenticeship pipelines that outpace university materials science output.
- Automotive AEC-Q101 certification timelines:18-24 month qualification cycles for power discretes misalign with 12-month EV platform development sprints.
- Substrate-device co-design IP fragmentation:Foundries and IDMs hold conflicting patents on trench gate geometries, complicating vertical partnership negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Sic Market |
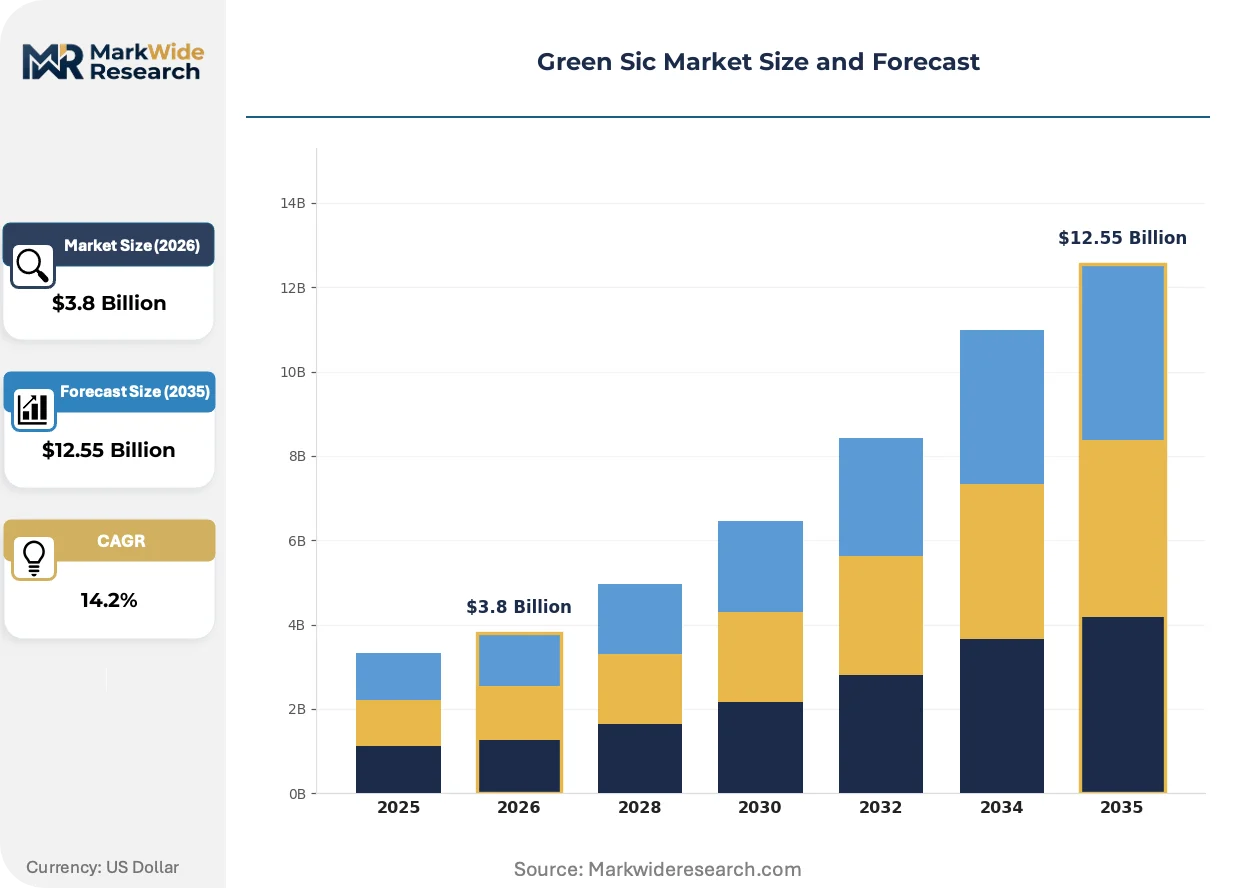
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SiC Wafers, SiC Power Devices, SiC Devices, SiC Substrates End User: Consumer Electronics, Automotive, Telecommunication, Energy Application: Power Amplifiers, Power Supply, Electric Vehicles, LED Lighting Technology: Manufacturing Processes, Crystal Growth, Layering Techniques, Fabrication Methods |
| Companies Covered | Infineon Technologies AG, STMicroelectronics, Wolfspeed, ROHM Co., Ltd., Semiconductor Components Industries, LLC, Mitsubishi Electric Corporation, Fuji Electric Co., Ltd., Renesas Electronics Corporation, Toshiba Electronic Devices & Storage Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Sic Market Emerging Trajectories
Wafer processing economics are forcing a recalibration of where value capture sits in the SiC supply chain, with substrate makers and device foundries contesting margin allocation through captive integration moves.
8-inch SiC crystal growth is electrifying the capital equipment landscape as furnace OEMs retool thermal zone configurations for 200mm boule diameters. Tier-one automotive semiconductor buyers in Germany and Japan are pre-booking 2027-2028 wafer output at fixed-price terms. This format migration is electrifying foundry competition for captive crystal growth capacity as a strategic moat.
The EPA's emerging semiconductor facility emissions framework is compelling substrate producers to document carbon intensity per wafer through verified lifecycle assessments. Facility siting decisions now weight power grid carbon content alongside water and labor availability. High-purity SiC producers with geothermal or nuclear power access in upstate New York and Scandinavia are securing preferential qualification status with EU automotive OEMs facing CSRD supply-chain disclosure mandates.
Long-term wafer supply agreements are displacing spot market purchases as dominant procurement mechanisms for automotive power module makers. Tier-one EV drivetrain suppliers are locking 5-7 year take-or-pay contracts directly with substrate growers, bypassing traditional distributor channels. This contract concentration is most visible in China's state-backed EV platform procurement, where MIIT GB standards enforce domestic content ratios that favor qualified local substrate vendors over import alternatives.
Green Sic Market Segmentation
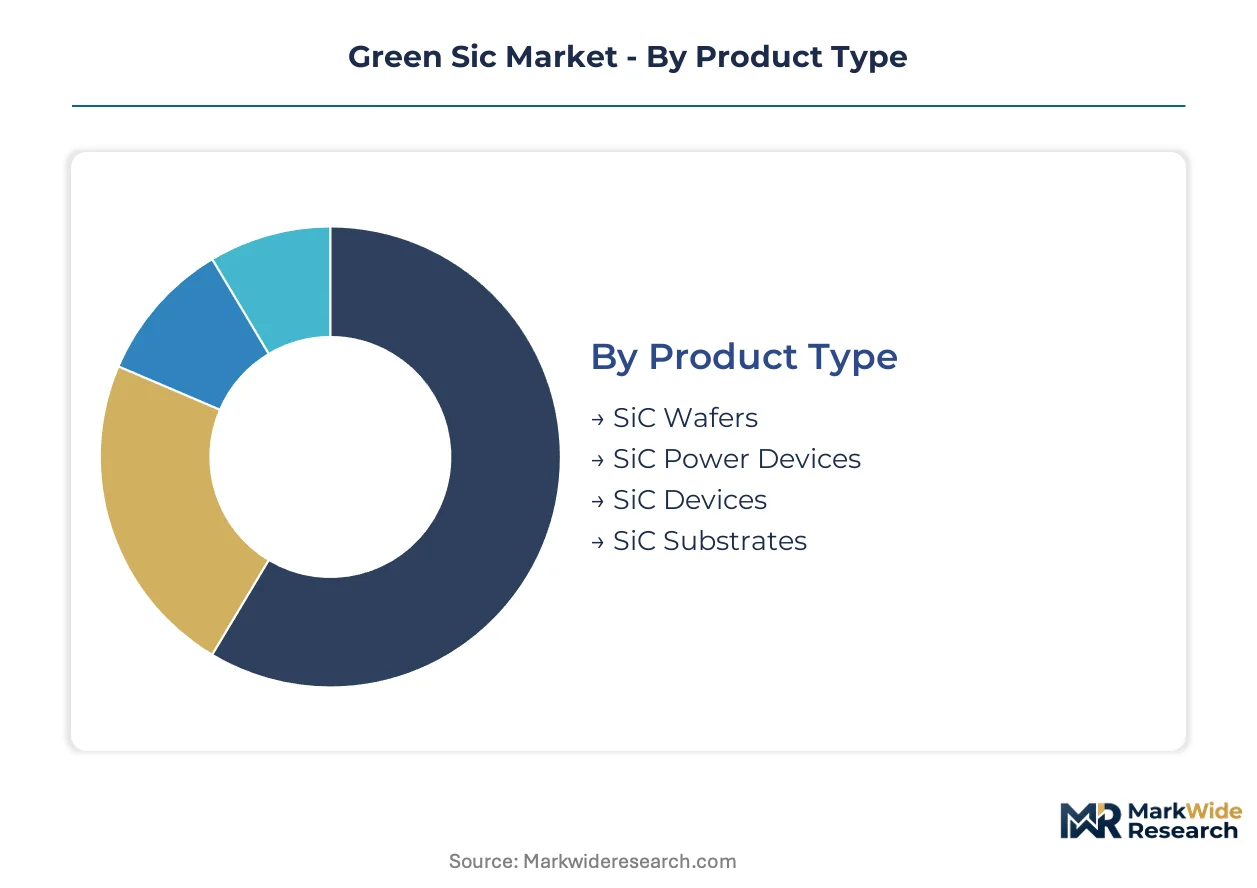
Segmentation in green SiC markets reveals how substrate scarcity, automotive qualification timelines, and power conversion efficiency requirements split demand across incompatible specification tiers. Buyers prioritize diameter migration, defect density thresholds, and end-product regulatory jurisdiction when selecting supply partners.
Product Type:
Purchasing decisions hinge on captive crystal growth capacity and wafer diameter roadmap alignment with foundry toolsets.
- SiC Wafers:These alpha-phase crystals with hexagonal polytype structures command the dominant value pool due to substrate scarcity and long physical vapor transport growth cycles. Demand concentrates in Germany's automotive semiconductor corridor where Bosch and Volkswagen-backed foundries prioritize 150mm qualification ahead of 800V EV platform deadlines.
- SiC Power Devices:Discrete components and modules for energy conversion systems face 18-24 month AEC-Q101 certification cycles that misalign with 12-month EV platform development sprints. China's MIIT GB standards enforce domestic content ratios that reshape vendor qualification criteria for state-backed EV procurement.
- SiC Devices:Broad category encompassing diodes, MOSFETs, and integrated modules for industrial and consumer applications.
- SiC Substrates:Foundational boule material sliced into wafers, with defect-free micropipe densities below 1/cm² remaining elusive in production-scale volumes.
SiC wafers lead on scale; SiC power devices lead on momentum.
End User:
Customer procurement patterns diverge sharply between long-horizon automotive qualification and shorter-cycle consumer electronics volume.
- Automotive:Tier-one EV drivetrain suppliers lock 5-7 year take-or-pay contracts directly with substrate growers, bypassing traditional distributor channels. Germany's automotive semiconductor corridor anchors this segment as 800V architectures displace silicon IGBTs.
- Energy:Grid-scale inverter retrofit cycles in European utility portfolios favor SiC module efficiency gains over aging silicon-based solar installations.
- Consumer Electronics:Power adapter and charger applications drive steady demand for mid-voltage SiC components.
- Telecommunication:Base station power supplies and RF applications require specialized thermal management specifications.
Automotive leads on scale; energy leads on momentum.
Application:
Application selection tracks voltage architecture migration and efficiency mandates from China's NMPA dual carbon goals and the EU Green Deal.
- Electric Vehicles:800V powertrain architectures anchor the fastest adoption curve as OEMs race to certify platforms ahead of model-year deadlines. China's state-backed EV platforms enforce carbon intensity benchmarks that favor SiC efficiency gains over legacy silicon.
- LED Lighting:Industrial luminaire OEMs generate stable replacement demand with mature technology and slower growth trajectories.
- Power Supply:Server, telecom, and industrial power conversion applications demand high-breakdown-voltage performance.
- Power Amplifiers:RF and communications infrastructure applications require specialized thermal and electrical characteristics.
Electric vehicles lead on scale; power supply leads on momentum.
Technology:
Technology selection determines capital intensity, yield rates, and regulatory compliance with emerging emissions frameworks.
- Crystal Growth:Physical vapor transport furnaces from German and Japanese OEMs control 90% of high-temperature reactor supply, creating capex queue risks. The EPA's emerging semiconductor facility emissions framework compels substrate producers to document carbon intensity per wafer through verified lifecycle assessments.
- Manufacturing Processes:Acheson process and chemical vapor deposition routes split on feedstock purity requirements and scale economics.
- Layering Techniques:Epitaxial deposition methods for device-grade surface preparation.
- Fabrication Methods:Trench gate geometries and device architectures subject to fragmented IP holdings between foundries and IDMs.
Crystal growth leads on scale; manufacturing processes lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized crystal growth technicians concentrate in Germany's automotive semiconductor corridor, China's state-backed EV manufacturing belts, and Japan's precision materials clusters, creating geographically anchored talent pipelines that constrain expansion timelines for new substrate facilities.
United States
Upstate New York hosts concentrated physical vapor transport furnace operations serving North American automotive qualification pipelines. The EPA's emerging semiconductor facility emissions framework compels substrate producers to document carbon intensity per wafer through verified lifecycle assessments. Wolfspeed anchors domestic supply through captive crystal growth capacity leveraging geothermal power access for preferential EU automotive OEM qualification.
Germany
Bosch and Volkswagen-backed foundries in the automotive semiconductor corridor prioritize 150mm SiC substrate qualification ahead of 800V EV platform deadlines. The EU F-Gas Regulation's fluorinated gas phase-down mandates push manufacturers toward greener substrate production chemistries. Equipment makers in Bavaria and Baden-Württemberg are retooling crystal growth furnaces for larger-diameter boules that cut device cost per ampere.
China
State-backed EV platforms enforce carbon intensity benchmarks under NMPA dual carbon goals that favor SiC efficiency gains over silicon IGBTs. MIIT GB standards enforce domestic content ratios in procurement criteria that reshape vendor qualification for local substrate vendors. Yangtze River Delta foundries accelerate partnerships with international crystal growth equipment suppliers to bypass single-source bottlenecks.
Japan
Tier-one OEM design-in pipelines concentrate qualification demand through established automotive semiconductor relationships. METI subsidizes SiC foundry investments under the country's semiconductor revitalization roadmap. Kyushu and Kansai industrial clusters host precision materials operations with 5-7 year apprenticeship pipelines for PVT furnace operation and defect characterization.
India
PLI scheme subsidies for compound semiconductor fabs create first-mover substrate qualification pathways outside established East Asian supply chains. The country's national semiconductor regulator frames incentive structures around domestic content thresholds for state procurement. Gujarat and Karnataka target automotive power module packaging investments to capture downstream value from imported wafer inputs.
Green Sic Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a market structure consolidating around captive crystal growth capacity as the primary competitive moat. German and Japanese furnace OEMs control 90% of high-temperature reactor supply, creating tiered access based on equipment queue position. Three archetypes dominate: integrated device-and-substrate verticalists, pure-play substrate growers with long-term automotive contracts, and fabless power module designers outsourcing wafer procurement. Competitive moves center on backward integration into boule production and 5-7 year take-or-pay contract pre-booking for 2027-2028 wafer output.
Among integrated verticalists, STMicroelectronics exemplifies the device-and-substrate combination model through European and Asian facilities, while Wolfspeed anchors North American supply chain independence. ROHM Co., Ltd. occupies a position within Japanese automotive qualification pipelines. These three represent distinct geographic anchoring strategies—European multi-site integration, North American captive supply, and Asian tier-one OEM design-in concentration—that shape competitive positioning without requiring specific technology or financial claims.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| STMicroelectronics |
| Wolfspeed |
| ROHM Co., Ltd. |
| Semiconductor Components Industries, LLC |
| Mitsubishi Electric Corporation |
| Fuji Electric Co., Ltd. |
| Renesas Electronics Corporation |
| Toshiba Electronic Devices & Storage Corporation |
| Others |
Supply Flow & Price Mechanics
Petroleum coke spot premiums with sub-50ppm metallic contamination command 3-4x multiples over metallurgical-grade inputs, cascading through Acheson-process economics into wafer pricing tiers that separate automotive-qualified substrates from commodity abrasives.
Pricing Analysis
The bundled-vs-unbundled service split separates captive crystal growth contracts from spot wafer purchases. Three-tier pricing structure across premium, standard, and economy levels stratifies by defect density thresholds and AEC-Q101 certification status. Cost compression in standard-grade wafers is intensifying because foundries are pre-booking 2027-2028 output at fixed-price terms. Automotive tier-one suppliers show least price sensitivity due to 800V platform deadlines, while industrial LED luminaire OEMs face greatest margin pressure.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese furnace OEMs controlling 90% of high-temperature reactor supply. Geographic supply concentration centers on upstate New York, Italy, and Singapore where integrated verticalists maintain captive boule production. Raw material dependencies draw from high-purity petroleum coke, silica sand, and graphite crucibles. Tariff exposure looms as China's MIIT GB standards enforce domestic content ratios that reshape import qualification. Distribution runs through long-term take-or-pay contracts directly between substrate growers and automotive power module makers, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where automotive OEMs are shifting procurement toward 150mm substrate specifications with defect densities below 1/cm².
For Market Incumbents: Hedge against single-source equipment bottlenecks by securing queue position with German and Japanese furnace OEMs before capex cycles tighten. Prioritize backward integration into 8-inch crystal growth capacity as Wolfspeed and STMicroelectronics contest margin allocation through captive boule production. Defend against emerging Chinese substrate vendors by accelerating AEC-Q101 certification pipelines ahead of MIIT GB domestic content enforcement. For New Entrants and Emerging Players: GaN-SiC hybrid module technology offers a technology-first wedge into mid-voltage EV auxiliary systems where established verticalists have not concentrated design-in resources. India's PLI scheme subsidies for compound semiconductor fabs represent the most penetrable geography outside East Asian supply chain lock-in. A foundry-partnership go-to-market angle bypasses the 5-7 year apprenticeship pipelines for PVT furnace technicians that constrain greenfield crystal growth. For Investors and Strategic Acquirers: Consolidation pressure builds where substrate-device co-design IP fragmentation complicates partnership negotiations between foundries and IDMs. Long-term viability over a multi-year window favors pure-play substrate growers with locked automotive contracts over fabless power module designers exposed to wafer spot volatility. Watch for 8-inch qualification milestones as the inflection signal indicating which captive capacity positions will dominate 800V platform procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crystal Growth | Captive boule production secures margin control against substrate scarcity driven by long PVT cycles. |
| Long-term Supply Agreement | 5-7 year take-or-pay contracts with automotive tier-ones bypass distributor channels and lock qualification pipelines. |
| Capacity Expansion | 8-inch wafer migration in Germany's automotive corridor cuts device cost per ampere for 800V architectures. |
| Green Manufacturing Transition | Geothermal or nuclear-powered facilities in upstate New York secure preferential EU OEM status under CSRD mandates. |
| Joint Venture | India's PLI scheme partnerships create first-mover qualification pathways outside established East Asian supply chains. |
Methodological Framework
Direct dialogue with crystal growth technicians, automotive power module procurement leads, PVT furnace OEM sales engineers, and EPA regulatory affairs specialists grounded qualitative insights in operational realities. Secondary validation drew from SEC 10-K filings of listed semiconductor firms, ECHA REACH substance dossiers, MIIT GB standard publications, and customs data on SiC wafer trade flows. Bottom-up and top-down triangulation cross-checked substrate capacity announcements against automotive platform production schedules.
The analytical lens combined bottom-up wafer supply modeling with top-down EV powertrain penetration assumptions across the projection horizon. Segmentation dimensions included wafer diameter migration, defect density tiers, end-use industry concentration, and regional regulatory cluster alignment. CAGRs were derived from fitted growth curves calibrated to equipment installation timelines and automotive qualification cycle data. Crystal growth furnace delivery backlogs and AEC-Q101 certification pipeline durations served as industry-specific forecast anchors.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to 8-inch yield breakthroughs, China domestic content enforcement timing, and EU F-Gas Regulation implementation stringency. Forecasts reflect documented assumptions about equipment delivery schedules, automotive platform launch cadence, and regulatory disclosure phase-in. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Specialty Beverage Stabilizers Market
Specialty Ingredients
Middle East and Africa Customized Premixes Market
Specialty Ingredients
Evening Primrose Oil Market
Specialty Ingredients
Gentian Market
Specialty Ingredients
Sun-Care Natural Oils Market
Specialty Ingredients
Pericarp Waste Market
Specialty Ingredients
Agarwood Essential Oil Market
Specialty Ingredients
Specialty Shortenings Market
Specialty Ingredients
Tea-Based Skin Care Products Market
Specialty Ingredients
Haitian Vetiver Oil Market
Specialty Ingredients
Middle East and Africa Specialty Food Ingredients Market
Specialty Ingredients
North America Grape Seed Extract Market
Specialty Ingredients
Tamanu Oil Market
Specialty Ingredients
Dessert Variegates Market
Specialty Ingredients
Cupuacu Butter Market
Specialty Ingredients
Vanilla Extract Alternatives Market