
 Flavanols Market | 2026-2036
Flavanols Market Size, Share, and Industry Trends Forecast 2026-2036
Flavanols Market Analytics
Multi-source procurement of high-purity extracts is broadening as buyers reduce dependency on single-origin cocoa supply chains. Archer-Daniels-Midland Company leverages its integrated agricultural sourcing network to secure raw material consistency across hemispheres. Koninklijke DSM-Firmenich anchors its position through synthetic biology capabilities that complement botanical extraction. Indena S.p.A. specializes in pharmaceutical-grade purification, serving contract manufacturers with stringent specification requirements.
Flavanols constitute a subclass of polyphenolic compounds characterized by a 2-phenyl-3,4-dihydro-2H-chromen-3-ol backbone, typically extracted via solvent-based methods or supercritical CO2 processing for applications demanding oxidative stability and bioactive retention. Cocoa flavanols dominate current volume flows due to established supply infrastructure and documented cardiovascular endpoints, while berry flavanols command premium positioning in cosmetic applications where anthocyanin co-extraction enhances topical antioxidant claims. The powder form maintains manufacturing-scale preference for functional food integration, though capsules are gaining traction in direct-to-consumer supplement channels where unit-dose standardization simplifies compliance with EFSA health claim thresholds.
EFSA evaluates health claim substantiation for flavanol-containing products under Regulation (EC) 1924/2006, while FDA exercises enforcement discretion over structure-function claims in dietary supplements. ISO 17025-accredited testing protocols for monomeric and oligomeric flavanol quantification increasingly determine supplier qualification status. Stakeholders must monitor evolving pharmacopeial monograph harmonization between USP and EP standards, as divergent analytical methods for procyanidin content create cross-border formulation complexity.
Market Dynamics
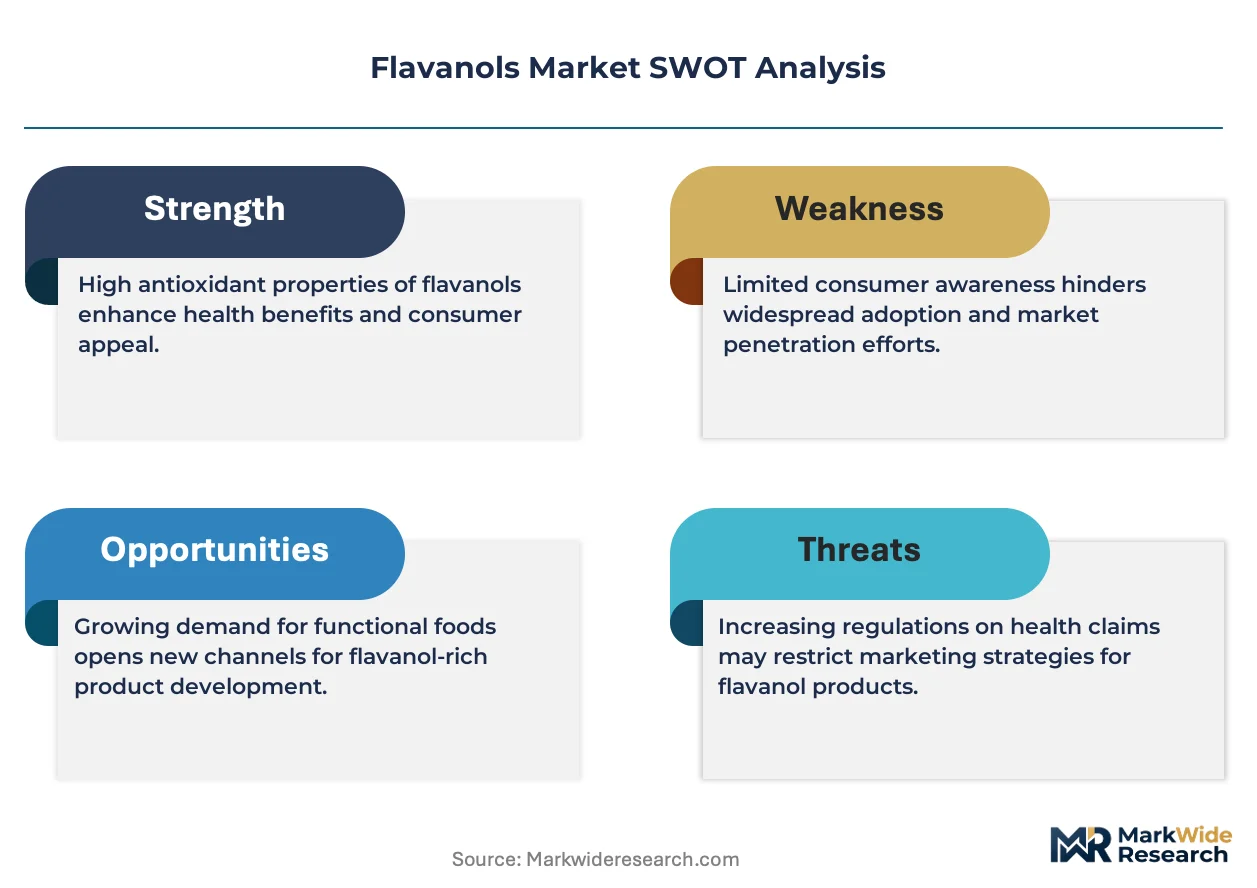
EFSA's ongoing refinement of cardiovascular health claim substantiation requirements is compressing formulation timelines and forcing nutraceutical manufacturers to front-load clinical validation investments before product launch.
Growth Catalysts
- EU Nutrition and Health Claims Regulation:EFSA's positive opinion on cocoa flavanol cardiovascular claims creates a regulatory pathway for functional food positioning in member states.
- Supercritical CO2 extraction:This solvent-free processing technology enables higher monomeric flavanol retention and cleaner label credentials for premium supplement formulations.
- German processing hub concentration:Standardized food-grade flavanol specifications from Bavarian extraction facilities reduce buyer qualification burdens across the continent.
Market Restraints
- Cocoa bean price volatility:West African supply disruptions and speculative commodity trading create input cost instability for botanical extract processors.
- Single-origin supply dependency:Ivory Coast and Ghana account for over 60% of global cocoa bean output, concentrating geopolitical and climate risk.
- Procyanidin analytical divergence:USP and EP monograph incompatibilities for oligomeric flavanol quantification generate cross-border formulation complexity and retesting costs.
Strategic Opportunities
- Indian functional food expansion:FSSAI's evolving health claim framework and rising cardiovascular health awareness create whitespace for cocoa extract fortification in dairy and beverages.
- Synthetic biology convergence:Microbial fermentation of flavanol precursors combined with enzymatic modification offers non-cocoa supply alternatives with batch-to-batch consistency.
- Direct-to-consumer capsule channels:E-commerce subscription models bypass traditional pharmaceutical distribution markups while enabling unit-dose compliance with EFSA thresholds.
Industry Challenges
- ISO 17025 accreditation timelines:Third-party laboratory qualification for monomeric and oligomeric flavanol testing extends supplier onboarding by 6-12 months.
- Pharmaceutical-grade purification capex:GMP-compliant extraction and chromatographic separation infrastructure demands substantial capital deployment before contract manufacturing revenue materializes.
- Legacy ERP integration:Batch record traceability requirements for botanical extracts clash with existing food-grade manufacturing software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flavanols Market |
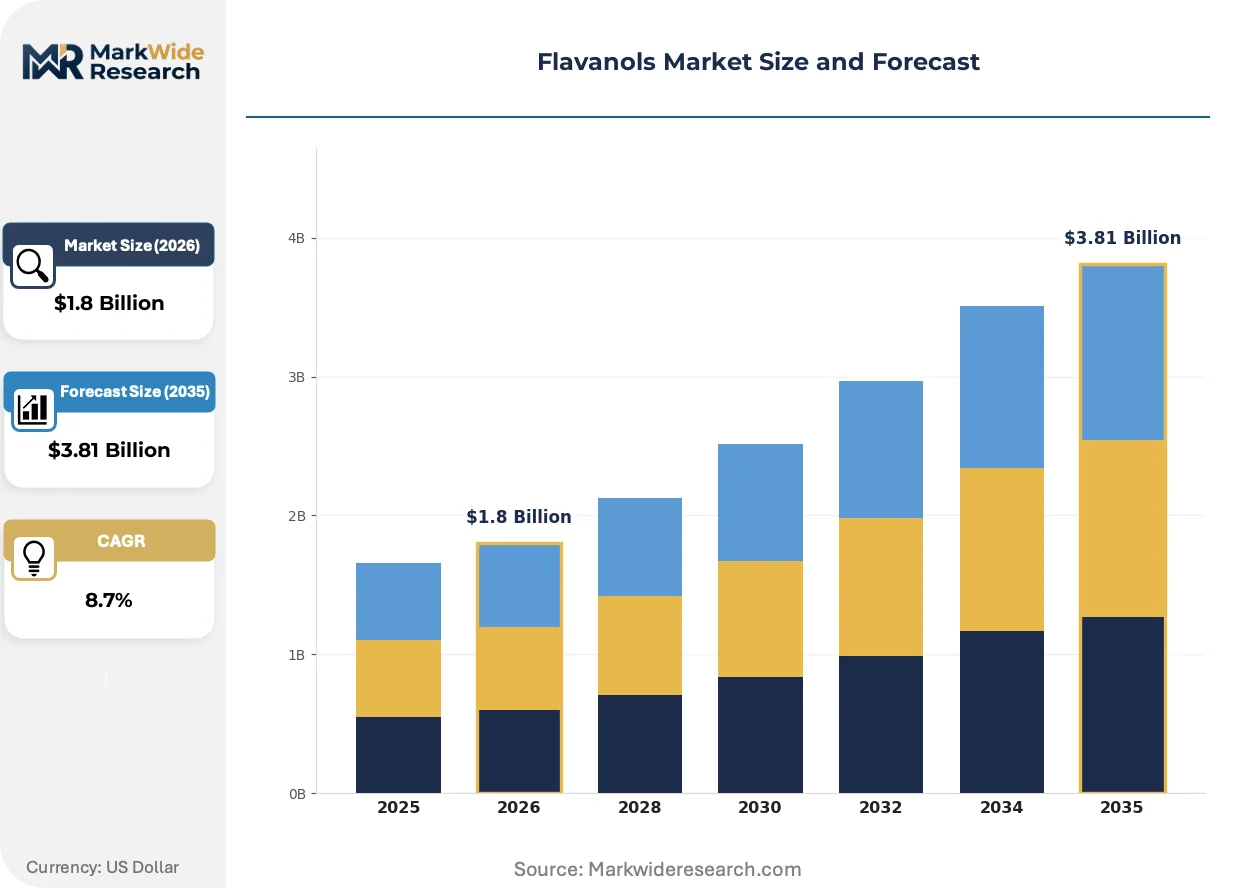
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cocoa Flavanols, Green Tea Flavanols, Berry Flavanols, Apple Flavanols Form: Powder, Liquid, Capsules, Tablets Application: Functional Foods, Supplements, Beverages, Cosmetics End User: Health-Conscious Consumers, Nutraceutical Companies, Beverage Manufacturers, Cosmetic Brands |
| Companies Covered | Cayman Chemical Company, Indena S.p.A., Layn Natural Ingredients, Merck KGaA, Archer-Daniels-Midland Company, Extrasynthese, Givaudan, Koninklijke DSM-Firmenich, Sensient Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flavanols Market Evolving Landscape
Processing technology maturation and regulatory claim standardization are compressing the gap between botanical extraction and pharmaceutical-grade production, reshaping competitive capability requirements.
Supercritical CO2 processing with integrated chromatographic fractionation is unifying antioxidant retention and solvent-free credentials in a single operational flow. Nutraceutical contract manufacturers in Germany and Switzerland are adopting these systems at replacement cycle pace. This technology convergence is compressing the premiumization window for conventional solvent-based extracts.
REACH registration requirements for novel extraction solvents are tightening purity specifications for ethyl acetate and ethanol grades used in botanical processing. The European Chemicals Agency's 2023-2025 substance evaluation roadmap specifically targets residual solvent limits in food-contact applications. Cocoa extract processors serving EU functional food brands are accelerating validation of supercritical alternatives to preempt authorization gaps.
Long-term offtake agreements with fixed-price escalators are displacing spot-market cocoa bean purchasing among major extract processors. This contractual shift transfers price risk upstream to agricultural cooperatives while securing volume certainty for cardiovascular health formulation pipelines. German and Dutch nutraceutical buyers are driving this structural change, with standard 3-5 year supply contracts now replacing annual tenders.
Flavanols Market Segmentation
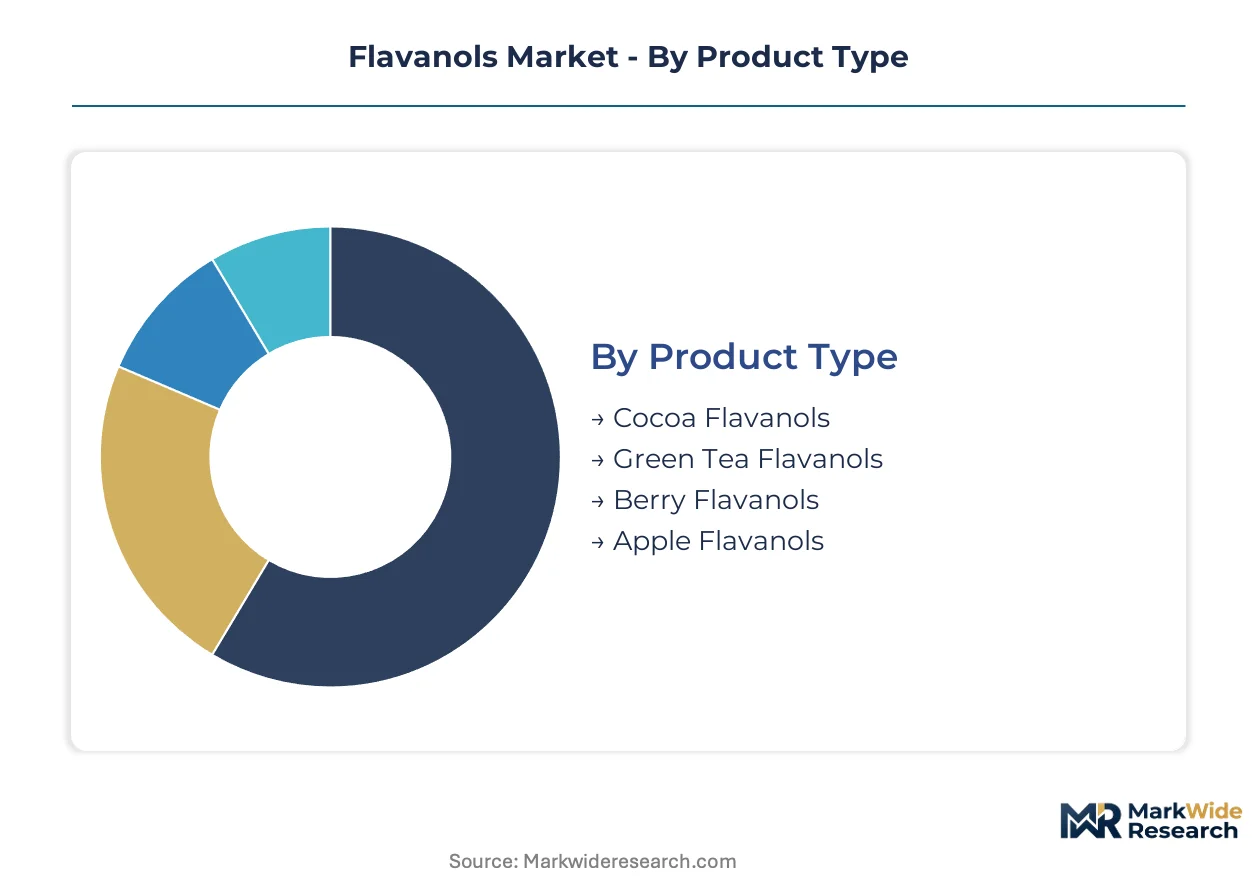
Flavanol procurement patterns diverge sharply across extraction source, delivery format, and end-use specification. Each segmentation dimension carries distinct capital requirements and margin profiles that reshape supplier competitive positioning.
Product Type:
Cocoa flavanol extraction demands the heaviest upstream infrastructure investment due to bean processing volume and solvent recovery systems.
- Cocoa Flavanols:These extracts contain epicatechin and procyanidin oligomers standardized to cardiovascular health claim thresholds. German nutraceutical buyers concentrate procurement through Bavarian extraction hubs to secure EFSA-compliant monomeric flavanol specifications.
- Green Tea Flavanols:EGCG-rich extracts require precision temperature control during solvent extraction to prevent catechin degradation. Japanese beverage manufacturers drive premium contract demand for decaffeinated, high-purity grades in functional drink applications.
- Berry Flavanols:Anthocyanin co-extraction from blueberry and cranberry sources serves cosmetic antioxidant claims in topical formulations.
- Apple Flavanols:Procyanidin B2 concentrates from apple peel waste streams support cost-positioned supplement entries.
Cocoa flavanol infrastructure absorbs the bulk of installed capacity; berry flavanols are expanding most quickly.
Form:
Unit-dose standardization requirements determine which formats command manufacturing investment priority.
- Powder:Spray-dried and agglomerated grades dominate functional food integration, requiring fluid bed processing and nitrogen blanketing for oxidative stability. Dutch dairy fortification programs and German bakery applications sustain volume demand despite compression from cleaner-label alternatives.
- Capsules:Hard-shell gelatin and vegetarian HPMC formats enable direct-to-consumer subscription models with precise EFSA threshold compliance per unit. Swiss contract manufacturers are expanding encapsulation lines to capture bypassed pharmaceutical distribution margins.
- Liquid:Aqueous glycerin extracts serve beverage fortification with simplified dispersion characteristics.
- Tablets:Compressed formats with binder systems target mass-market retail shelf presence in emerging Asian markets.
Powder formats retain the deepest installed base; capsules are gaining share fastest in premium channels.
Application:
Regulatory claim substantiation burden varies dramatically across end-use categories, reshaping R&D allocation.
- Functional Foods:EFSA Article 13.5 health claim authorization for cocoa flavanol cardiovascular endpoints drives formulation investment in chocolate, dairy, and baked goods. German processors lead in standardized food-grade specification development.
- Supplements:Capsule and tablet formats under FDA structure-function claim discretion enable faster market entry with reduced clinical validation burden compared to EU food applications.
- Beverages:Ready-to-drink fortification demands water-soluble, flavor-neutral extracts with thermal stability through pasteurization.
- Cosmetics:Topical antioxidant claims leverage berry flavanol anthocyanin synergy for premium skincare positioning.
Functional foods command the largest validation investment; supplements offer the most rapid commercialization pathway.
End User:
Procurement sophistication and specification stringency stratify sharply across buyer categories.
- Nutraceutical Companies:These buyers enforce ISO 17025-accredited testing protocols and GMP-compliant supply chains with 6-12 month supplier qualification timelines. German and Swiss contract manufacturers demand pharmaceutical-grade purification with batch record traceability.
- Health-Conscious Consumers:Direct purchasing through e-commerce subscription channels prioritizes unit-dose transparency and clean-label credentials over bulk pricing.
- Beverage Manufacturers:Scale procurement favors long-term offtake agreements with fixed-price escalators to transfer commodity risk upstream.
- Cosmetic Brands:Premium positioning drives demand for organic-certified and supercritical CO2-processed extracts with residual solvent guarantees.
Nutraceutical companies anchor specification development; health-conscious consumers are fragmenting demand toward direct channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cocoa bean sourcing from Ivory Coast and Ghana underpins extraction capacity deployment across major processing economies. Regulatory claim pathways and pharmaceutical-grade infrastructure determine regional competitive positioning.
Germany
Bavarian extraction facilities drive food-grade flavanol standardization for EFSA-compliant cardiovascular health claims. The Federal Ministry of Food and Agriculture enforces strict residual solvent limits under the German Food and Feed Code. Munich-based contract manufacturers supply standardized cocoa extracts to pan-European nutraceutical formulators.
United States
FDA structure-function claim discretion enables faster supplement commercialization compared to EU food applications. The Dietary Supplement Health and Education Act framework governs flavanol product positioning without pre-market authorization. New Jersey and California host the largest concentration of encapsulation and tablet manufacturing for direct-to-consumer channels.
Switzerland
Swissmedic pharmaceutical oversight elevates purification standards for contract manufacturers serving premium supplement brands. The Federal Food Safety and Veterinary Office harmonizes with EU Regulation 1924/2006 for cross-border health claim alignment. Basel and Geneva clusters specialize in GMP-compliant extraction with batch record traceability systems.
India
FSSAI's evolving health claim framework creates whitespace for cocoa extract fortification in dairy and beverages. The Food Safety and Standards Authority permits structure-function positioning pending formal cardiovascular substantiation pathways. Maharashtra and Karnataka processing hubs are installing supercritical CO2 capacity for export-grade botanical extracts.
Netherlands
Dutch dairy fortification programs sustain bulk powder demand despite cleaner-label compression. The Netherlands Food and Consumer Product Safety Authority enforces REACH-registered solvent compliance for extraction operations. Rotterdam's port infrastructure anchors cocoa bean import flows for redistribution to German and Swiss processors.
Flavanols Market Competitive Landscape
Global majors compete with regional champions across extraction technology and regulatory claim expertise. The vendor base stratifies between agricultural-integrated conglomerates, pharmaceutical-grade purification specialists, and synthetic biology platforms. Three archetypes dominate: cocoa supply chain integrators, botanical extraction specialists, and fermentation-based alternative producers. Capacity expansion and long-term offtake contracting represent the primary competitive vectors as price volatility reshapes procurement strategy.
Among agricultural-integrated conglomerates, Archer-Daniels-Midland Company exemplifies upstream supply chain control through hemispheric sourcing networks. Indena S.p.A. and Koninklijke DSM-Firmenich occupy positions at the pharmaceutical-grade and synthetic biology frontiers respectively, representing divergent technological pathways for bioactive standardization. These three anchors illustrate how competitive positioning fragments across extraction methodology and regulatory claim sophistication.
| Leading Market Players |
|---|
| Cayman Chemical Company |
| Indena S.p.A. |
| Layn Natural Ingredients |
| Merck KGaA |
| Archer-Daniels-Midland Company |
| Extrasynthese |
| Givaudan |
| Koninklijke DSM-Firmenich |
| Sensient Technologies Corporation |
| Others |
Value Network & Pricing Analysis
Supercritical CO2 extraction adoption simultaneously compresses production costs for premium-grade flavanol outputs and concentrates supply capability among German and Swiss processors with validated solvent-free infrastructure. This technological transition rewards early capital deployers with pricing power over conventional solvent-based competitors while locking in long-term offtake relationships with EFSA-compliant buyers.
Pricing Analysis
Residual solvent testing warranties and batch certification documentation are bundled into premium-tier supply contracts, while economy-grade spot purchases exclude these assurances. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels reflects divergent analytical rigor and GMP compliance investments. Cost compression in food-grade segments is intensifying because REACH-registered solvent alternatives command authorization premiums. Nutraceutical contract manufacturers exhibit lowest price sensitivity due to health claim substantiation requirements, while commodity feed buyers drive aggressive spot-market negotiation.
Supply Chain Analysis
ISO 17025 accreditation and GMP certification gate supplier qualification, extending onboarding timelines for new extraction entrants. Ivory Coast, Ghana, and Ecuador anchor raw cocoa bean flows, while Germany, Switzerland, and the Netherlands concentrate pharmaceutical-grade purification capacity. Supply chain risk centers on single-origin dependency for bean inputs, with West African climate volatility and geopolitical disruption threatening volume continuity. Distribution runs through Rotterdam port infrastructure for bean import, then diverges to Bavarian extraction hubs for processing and pan-European redistribution to nutraceutical formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flavanol extraction sector is consolidating into a vertical-integration race where upstream bean sourcing control and downstream pharmaceutical-grade purification capability determine margin capture. Players are pursuing captive supply relationships and GMP infrastructure buildout as the decisive competitive levers.
For Market Incumbents: Deploy long-term offtake contracting with fixed-price escalators to lock in bean supply before speculative commodity volatility intensifies. Synthetic biology platforms and fermentation-based flavanol alternatives represent substitution threats requiring R&D monitoring; incumbents should accelerate supercritical CO2 capacity expansion in Bavarian and Swiss clusters to maintain pharmaceutical-grade purification leadership against these emerging production methods. For New Entrants and Emerging Players: The premium-economy price-point gap in Indian functional food fortification creates immediate white-space opportunity. FSSAI's evolving cardiovascular health claim framework permits structure-function positioning with reduced clinical validation burden compared to EFSA Article 13.5 pathways. Target aqueous glycerin liquid extract formats for beverage fortification, where flavor-neutral dispersion characteristics and thermal stability command premium positioning in dairy and ready-to-drink applications. For Investors and Strategic Acquirers: Exit pathways concentrate in pharmaceutical-grade contract manufacturing roll-ups and synthetic biology platform acquisitions. The five-to-ten year viability window favors targets with validated GMP infrastructure and EFSA-compliant monomeric flavanol specifications. Watch for EFSA opinion refinement on berry flavanol cardiovascular claims as the inflection signal indicating expanded addressable market for non-cocoa extraction specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | German processors secure EFSA-compliant solvent-free credentials ahead of REACH authorization gaps. |
| Long-term Bean Offtake Agreements | Dutch and German buyers transfer price risk to Ivory Coast and Ghana agricultural cooperatives. |
| Synthetic Biology Platform Development | Microbial fermentation offers non-cocoa supply alternatives with batch-to-batch consistency guarantees. |
| Direct-to-Consumer Capsule Channel Launch | Swiss contract manufacturers capture bypassed pharmaceutical distribution margins through e-commerce subscriptions. |
| Indian Processing Hub Establishment | Maharashtra and Karnataka facilities target FSSAI-compliant export-grade botanical extract demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with extraction facility managers, nutraceutical procurement leads, pharmaceutical contract manufacturing executives, and EFSA regulatory affairs specialists. EFSA health claim opinions, FDA structure-function claim guidance documents, USP and EP pharmacopeial monographs, and ISO 17025 accreditation databases provided validation benchmarks. Bottom-up flavanol volume modeling triangulated against top-down functional food and supplement market sizing.
Production volume and value outputs reconciled shipment data, import-export statistics, and processor capacity utilization disclosures across the projection horizon. Segmentation dimensions encompassed extraction source, delivery format, application category, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from historical volume trajectories and category-specific demand elasticity assumptions, with cocoa bean price volatility and health claim authorization timelines incorporated as scenario variables.
Inputs from EFSA opinion databases and German Food and Feed Code enforcement records were available through the study window; gaps in real-time cocoa cooperative pricing data introduce uncertainty bands around short-term cost assumptions. Forecasts reflect documented substantiation thresholds and REACH substance evaluation timelines. A model refresh is warranted upon material change in EFSA cardiovascular health claim authorization scope or West African cocoa supply disruption severity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Specialty Shortenings Market
Specialty Ingredients
Mango Butter Market
Specialty Ingredients
Europe Specialty Food Ingredients Market
Specialty Ingredients
Vetiver Oil Market
Specialty Ingredients
Specialty Carbohydrates Market
Specialty Ingredients
Tea-Based Skin Care Products Market
Specialty Ingredients
Asia-Pacific Specialty Food Ingredient Market
Specialty Ingredients
Specialty Syrup Market
Specialty Ingredients
Madecassoside Market
Specialty Ingredients
Mangosteen Market
Specialty Ingredients
Abies Alba (Fir) Leaf Oil Market
Specialty Ingredients
Evening Primrose Oil Market
Specialty Ingredients
Specialty Mint Oils Market
Specialty Ingredients
Pericarp Waste Market
Specialty Ingredients
Grape Seed Extract in Pet Food Application Market
Specialty Ingredients
Food Decorations and Inclusions Market