
 Global Flue Gas Treatment Systems Market | 2026-2036
Global Flue Gas Treatment Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flue Gas Treatment Systems Market Intelligence
A growing concentration of projects within large-scale utility and waste-to-energy operators is rebalancing the competitive landscape for system integrators. General Electric leverages its extensive portfolio in power generation to offer integrated solutions. Babcock & Wilcox Enterprises Inc. specializes in advanced combustion and emissions control technologies for complex industrial applications. Mitsubishi Hitachi Power Systems Ltd. dominates key Asian projects through its engineering scale and established regional presence.
Flue gas treatment systems are engineered assemblies that remove pollutants like sulfur dioxide (SOx) and nitrogen oxides (NOx) from industrial exhaust streams. These systems are critical for enabling facilities to comply with stringent air quality regulations. Wet Scrubbers and Selective Catalytic Reduction (SCR) units are dominant product types, especially within the Power Generation application. Meanwhile, Fabric Filters are gaining share in cement production and waste incineration due to their effectiveness against particulate matter.
Regulatory mandates from bodies like the US EPA and the European Union's Industrial Emissions Directive set the primary demand floor for new and retrofit systems. In parallel, China's Ministry of Ecology and Environment (MEE) enforces strict emission limits that drive technology choices for new industrial plants. System selection will increasingly hinge on a technology's ability to handle multiple pollutants simultaneously and adapt to future tightening of emission standards.
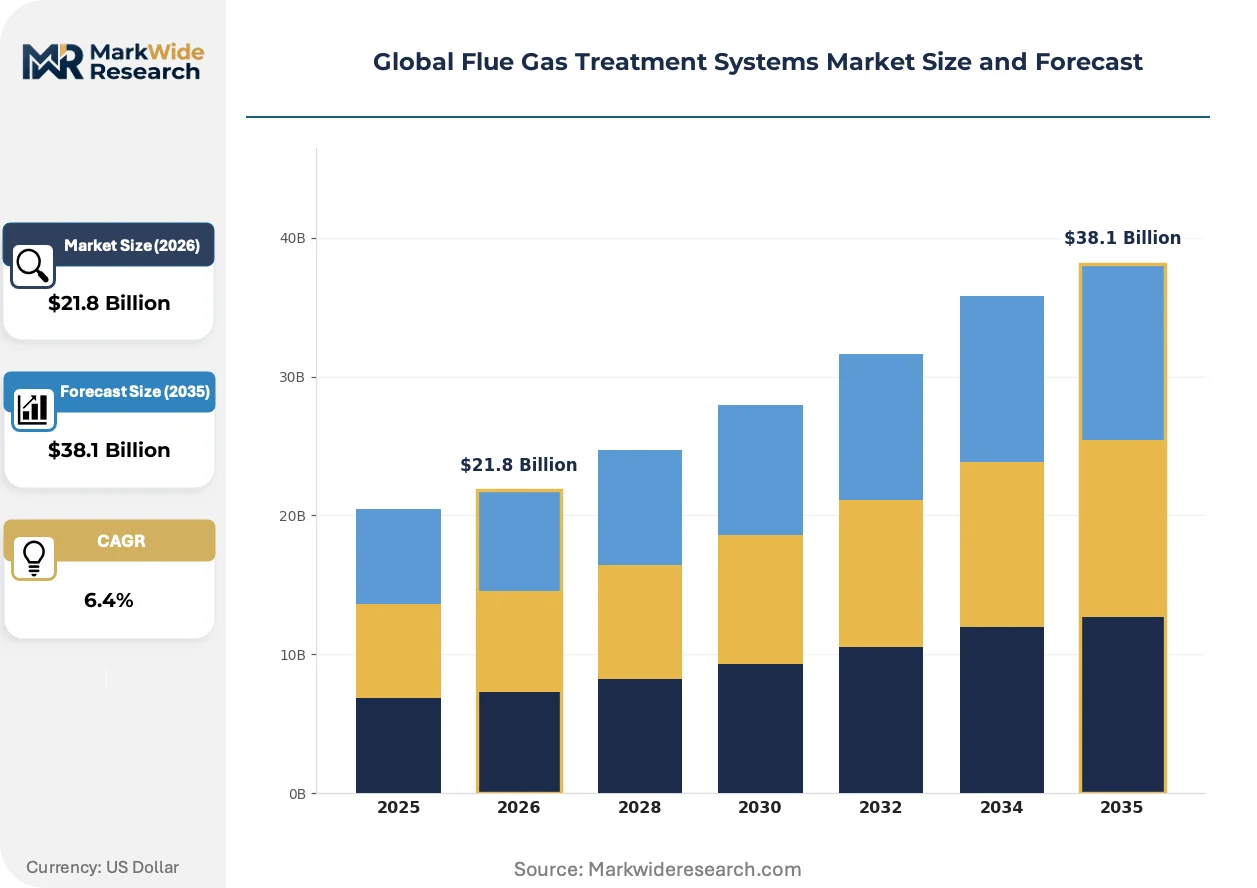
Market Dynamics
The imperative to meet progressively stricter air quality mandates, such as China's dual carbon goals and the EU's Industrial Emissions Directive, is the central force shaping technology selection and capital investment in the flue gas treatment systems market.
Growth Catalysts
- Stringent Chinese Regulations:China's Ministry of Ecology and Environment (MEE) enforces strict emission limits for industrial sectors like steel and cement, compelling widespread adoption of high-efficiency systems like Fabric Filters and SCR units.
- Waste-to-Energy Expansion:The global expansion of the waste incineration sector creates sustained demand for flue gas treatment to neutralize hazardous pollutants like dioxins and heavy metals, which are prevalent in municipal solid waste streams.
- Indian Power Sector Growth:India's ongoing development of new coal-fired power plants to meet energy needs requires significant investment in flue gas desulfurization (FGD) systems to control SOx emissions from high-sulfur coal.
Market Restraints
- High Capital Costs:The significant upfront investment required for advanced systems, particularly Selective Catalytic Reduction (SCR) units, can be prohibitive for smaller industrial operators or facilities in price-sensitive regions.
- Secondary Waste Generation:Wet Scrubber technologies, while effective for SOx removal, produce large volumes of sludge that require specialized, costly disposal methods, creating a secondary environmental and financial burden for operators.
- Catalyst Material Volatility:The performance and cost of SCR systems are tied to catalysts that often use vanadium and other specialty metals, exposing system operators to supply chain risks and price fluctuations.
Strategic Opportunities
- Integrated Carbon Capture:Combining flue gas treatment with emerging carbon capture and utilization (CCU) technologies offers a pathway for industrial emitters to address both criteria pollutants and greenhouse gases simultaneously.
- Multi-Pollutant Control Systems:There is a clear opportunity for hybrid systems capable of removing SOx, NOx, particulate matter, and mercury in a single, integrated unit, reducing footprint and operational complexity.
- Southeast Asian Industrialization:Nations like Vietnam and Indonesia are expanding their industrial bases, creating future demand for flue gas treatment systems as their environmental regulations mature and align with international standards.
Industry Challenges
- Retrofit Complexity:Integrating modern, large-scale flue gas treatment equipment into the constrained physical space of older industrial facilities presents significant engineering, downtime, and logistical challenges.
- Skilled Labor Shortages:A deficit of qualified engineers and technicians with expertise in the design, installation, and maintenance of complex chemical and catalytic systems can constrain project execution and system uptime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flue Gas Treatment Systems Market |
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $38.1 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrostatic Precipitators, Fabric Filters, Wet Scrubbers, Dry Scrubbers, Selective Catalytic Reduction Technology: Sorbent Injection, Non-Selective Catalytic Reduction, Flue Gas Desulfurization, Activated Carbon Injection, Denitrification Techniques Application: Power Generation, Cement Production, Waste Incineration, Refining Plants, Chemical Processing End User: Utilities, Manufacturing Facilities, Environmental Service Providers, Petrochemical Plants, Pulp & Paper Mills |
| Companies Covered | Babcock & Wilcox Enterprises Inc., Mitsubishi Hitachi Power Systems Ltd., General Electric, Doosan Lentjes, FLSmidth, Andritz AG, Thermax Limited, Clyde Bergemann Power Group, Marsulex Environmental Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flue Gas Treatment Systems Market Strategic Shifts & Innovations
A push toward greater operational efficiency and guaranteed regulatory compliance is driving the integration of digital tools and performance-based service models. This shift prioritizes asset lifecycle value over initial capital cost, altering how systems are sold and managed.
Digital twin technology creates virtual replicas of physical flue gas treatment systems to simulate performance and optimize operations. Power generation and waste-to-energy operators are adopting these platforms to improve reagent consumption, predict catalyst deactivation, and schedule maintenance proactively. The ability to model process changes in a risk-free environment is electrifying asset management, shifting it from a reactive to a predictive discipline.
The European Union's Industrial Emissions Directive (IED) requires industrial plants to adopt Best Available Techniques (BAT) to minimize pollution. This mandate creates a continuous upgrade cycle, particularly for facilities in the power generation and chemical processing industries. Consequently, the market for retrofits and advanced multi-pollutant systems is strong in Europe, as operators must invest to comply with BAT-associated emission limits.
A notable demand-side shift is occurring from one-time equipment sales toward long-term service agreements that guarantee system performance and uptime. This model, which includes consumables management and remote monitoring, is displacing purely transactional procurement. The trend is most visible within North American and European power and waste-to-energy sectors, where operators outsource non-core functions to ensure continuous compliance.
Global Flue Gas Treatment Systems Market Segmentation
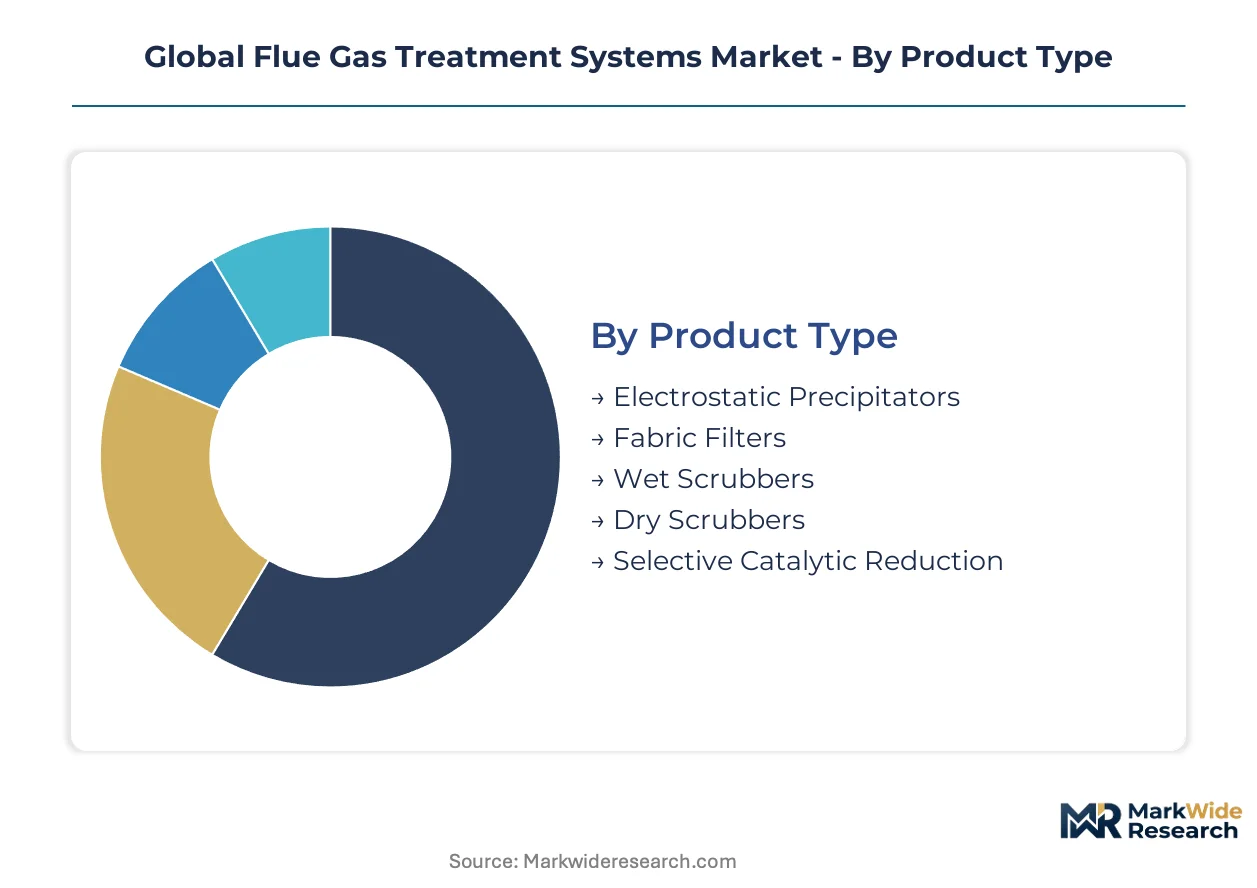
The global flue gas treatment systems market is segmented by product type, underlying technology, application, and end-user. Understanding these distinct segments reveals the specific drivers and compliance challenges influencing investment decisions across diverse industrial sectors.
Product Type:
System operators prioritize specific product types based on the pollutant profile, required removal efficiency, and operational footprint available at their facilities.
- Wet Scrubbers:These systems remove gaseous pollutants, primarily sulfur dioxide (SOx), by contacting the exhaust gas with a liquid absorbent. India's expanding power generation infrastructure drives demand for these systems to control SOx emissions from high-sulfur coal.
- Selective Catalytic Reduction:SCR units employ a catalyst and a reducing agent, such as ammonia, to convert nitrogen oxides (NOx) into harmless nitrogen and water vapor. China's Ministry of Ecology and Environment (MEE) mandates the widespread adoption of these high-efficiency systems for industrial facilities.
- Electrostatic Precipitators:Electrostatic precipitators remove particulate matter from industrial exhaust streams by charging particles and then collecting them on oppositely charged plates. Cement production facilities in Southeast Asia utilize these systems for dust control.
- Fabric Filters:Fabric filters, also known as baghouses, physically capture particulate matter through a filter medium, offering high removal efficiencies. Waste incineration plants in Europe adopt these for fine particulate control.
- Dry Scrubbers:Dry scrubbers inject a dry alkaline sorbent into the flue gas to neutralize acid gases, forming a dry reaction product for easier disposal. Chemical processing plants use dry scrubbers for various acid gas controls.
Wet Scrubbers lead on scale in SOx removal; Selective Catalytic Reduction leads on momentum for stringent NOx reduction.
Technology:
The selection of flue gas treatment technologies is often dictated by the specific industrial application and its unique emission challenges.
- Flue Gas Desulfurization:FGD technologies, including wet, dry, and semi-dry scrubbing, specifically target the removal of sulfur dioxide (SOx) from combustion exhaust. Power generation facilities in the United States extensively deploy FGD to comply with EPA regulations.
- Denitrification Techniques:These methods focus on reducing nitrogen oxides (NOx), encompassing technologies like Selective Catalytic Reduction (SCR) and Selective Non-Catalytic Reduction (SNCR). Industrial plants in Germany implement advanced denitrification to meet EU Industrial Emissions Directive limits.
- Sorbent Injection:Sorbent injection involves introducing a dry sorbent, typically hydrated lime or sodium bicarbonate, directly into the flue gas stream to react with and remove acid gases. Glass manufacturing plants use sorbent injection for acid gas abatement.
- Activated Carbon Injection:ACI systems inject powdered activated carbon into the flue gas to adsorb mercury, dioxins, and furans, which are then captured by particulate control devices. Waste-to-energy facilities employ ACI for hazardous pollutant removal.
- Non-Selective Catalytic Reduction:NSCR systems use a catalyst to simultaneously reduce NOx, carbon monoxide, and hydrocarbons, primarily in oxygen-poor exhaust streams. Engine exhaust applications often utilize NSCR for multi-pollutant control.
Flue Gas Desulfurization remains a foundational technology, while Denitrification Techniques are expanding quickly.
Application:
Industrial sectors with high emission volumes or particularly hazardous pollutants drive demand for specialized flue gas treatment solutions.
- Power Generation:This sector, encompassing coal, gas, and biomass-fired plants, requires extensive flue gas treatment for sulfur oxides, nitrogen oxides, and particulate matter. India's new coal-fired power plants are a significant market for FGD systems.
- Waste Incineration:Facilities burning municipal, industrial, and hazardous waste demand robust systems to neutralize dioxins, furans, heavy metals, and acid gases. The expansion of waste-to-energy projects in China fuels this demand.
- Cement Production:Cement kilns emit particulate matter, sulfur dioxide, and nitrogen oxides, necessitating treatment systems like fabric filters and dry scrubbers. Vietnamese cement manufacturers are upgrading systems for cleaner production.
- Refining Plants:Petroleum refineries generate complex exhaust streams containing SOx, NOx, and volatile organic compounds from various process units. Chemical processing plants require tailored solutions for diverse emission profiles.
- Chemical Processing:The chemical industry produces a wide array of gaseous pollutants, demanding highly customized flue gas treatment solutions for specific compounds. Petrochemical facilities in Saudi Arabia invest in advanced treatment for sulfur recovery units.
Power Generation represents the largest segment by volume, with Waste Incineration showing significant growth due to environmental mandates.
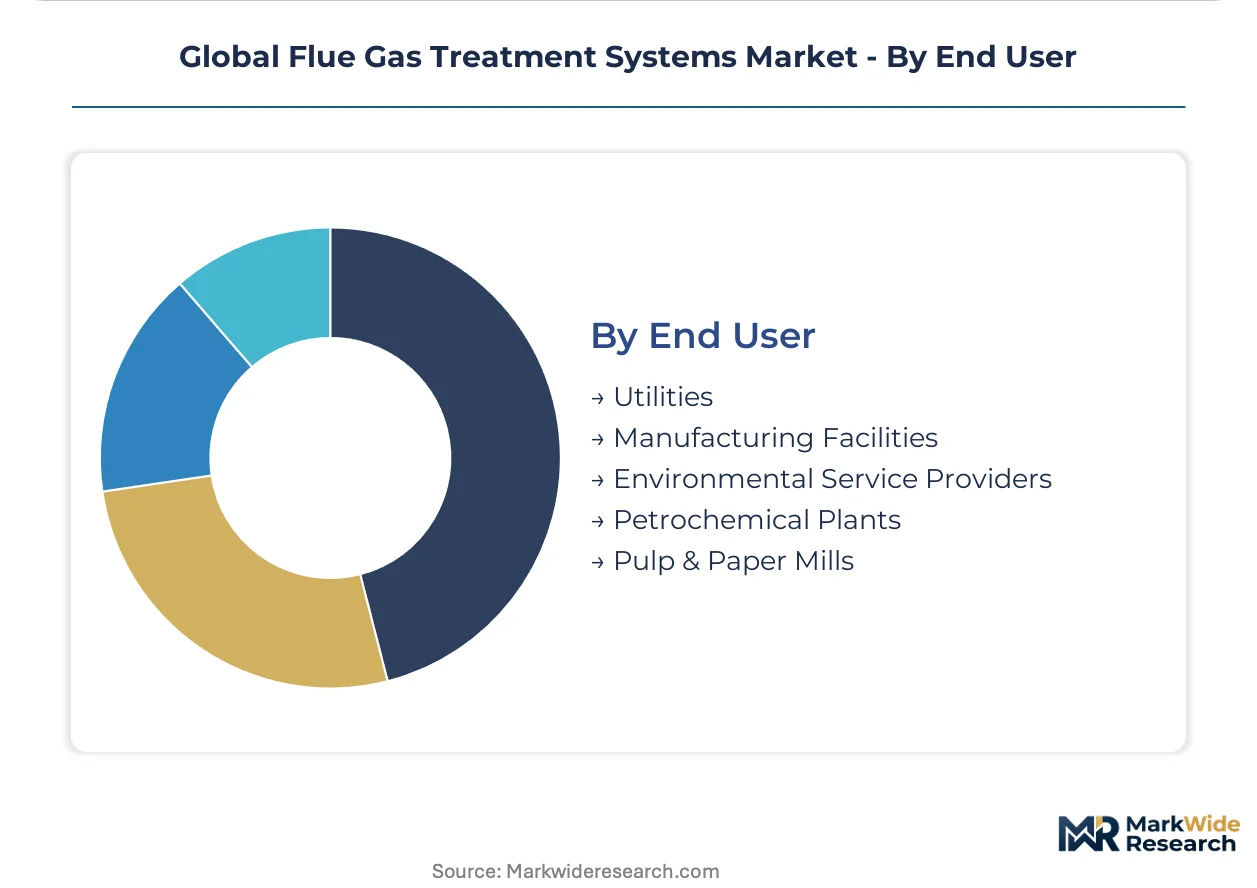
End User:
End-users evaluate flue gas treatment systems based on their operational scale, specific compliance obligations, and long-term cost efficiencies.
- Utilities:Large-scale power generation companies and public utility providers are major purchasers, driven by stringent national and regional emission standards. European utilities continuously upgrade systems to meet EU Industrial Emissions Directive requirements.
- Manufacturing Facilities:This broad category includes diverse industries like steel, glass, and automotive, each with unique emission profiles and localized regulatory pressures. Chinese steel mills are investing heavily in SCR and fabric filter technologies.
- Environmental Service Providers:Companies offering integrated environmental management and pollution control solutions procure systems for various industrial clients. These providers offer specialized expertise in complex installations.
- Petrochemical Plants:These facilities, involved in crude oil refining and chemical production, require advanced systems for SOx, NOx, and volatile organic compound abatement. Major petrochemical complexes in the Gulf Cooperation Council region are significant end-users.
- Pulp & Paper Mills:The pulp and paper industry utilizes flue gas treatment to control sulfur dioxide, particulate matter, and odor-causing compounds from boilers and recovery furnaces. Brazilian pulp mills focus on SOx reduction from their energy generation.
Utilities constitute the primary customer base, while Manufacturing Facilities increasingly seek customized solutions for diverse emission profiles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India and China represent significant contrasting forces in the global flue gas treatment systems market. India's rapid industrialization and power generation expansion drive demand for basic SOx controls, while China's stringent environmental mandates compel adoption of advanced multi-pollutant systems. Diverse regulatory frameworks across major economies shape technology adoption and investment patterns.
China
China's dual carbon goals and strict emission limits from the Ministry of Ecology and Environment (MEE) compel widespread adoption of high-efficiency flue gas treatment systems. Industrial facilities in sectors like steel and cement require advanced Fabric Filters and Selective Catalytic Reduction (SCR) units. Major industrial zones in the Yangtze River Delta continue to upgrade their pollution control infrastructure to meet these evolving standards.
India
India's expanding power generation infrastructure, particularly new coal-fired power plants, creates substantial demand for flue gas desulfurization (FGD) systems. The Central Electricity Authority (CEA) mandates SOx emission controls for these facilities, driving significant investment. Thermal power hubs in states like Maharashtra and Gujarat are key centers for the deployment of these large-scale systems.
United States
Compliance with US Environmental Protection Agency (EPA) regulations for sulfur dioxide (SOx), nitrogen oxides (NOx), and particulate matter drives demand for new and retrofit flue gas treatment systems. Power generation facilities extensively deploy FGD and SCR technologies to meet these federal and state-level standards. Older industrial sites in the Ohio River Valley region are implementing advanced controls to reduce legacy emissions.
Germany
Germany's industrial sector operates under the stringent requirements of the European Union's Industrial Emissions Directive (IED), which mandates the use of Best Available Techniques (BAT). This directive ensures continuous upgrades for advanced denitrification techniques and multi-pollutant control systems. Chemical processing and power generation facilities in the Rhine-Ruhr industrial region are consistently investing in state-of-the-art treatment technologies.
Japan
Japan maintains stringent air quality standards, propelling demand for sophisticated flue gas treatment systems across its industrial base. The Ministry of Economy, Trade and Industry (METI) promotes the adoption of advanced environmental technologies for both new and existing facilities. Industrial complexes in the Kanto region, including Tokyo and Yokohama, prioritize multi-pollutant control systems to manage emissions effectively.
Global Flue Gas Treatment Systems Market Key Industry Players
North American and European engineering firms anchor one tier of the flue gas treatment systems market, while Asian conglomerates hold significant sway in their regional projects. The competitive structure is tiered, with large integrated solution providers coexisting with specialized technology developers. Key strategic archetypes include global power generation specialists, advanced combustion technology experts, and regional engineering, procurement, and construction (EPC) players. Companies pursue portfolio diversification and geographic expansion to capture new opportunities.
Among global engineering conglomerates, General Electric and Mitsubishi Hitachi Power Systems Ltd. exemplify firms offering integrated power generation solutions that include flue gas treatment systems. Babcock & Wilcox Enterprises Inc. occupies a position as a specialized provider of advanced combustion and emissions control technologies for complex industrial applications. These companies leverage their extensive engineering capabilities and established client relationships to secure large-scale projects, particularly in the power generation and heavy industrial sectors.
| Leading Market Players |
|---|
| Babcock & Wilcox Enterprises Inc. |
| Mitsubishi Hitachi Power Systems Ltd. |
| General Electric |
| Doosan Lentjes |
| FLSmidth |
| Andritz AG |
| Thermax Limited |
| Clyde Bergemann Power Group |
| Marsulex Environmental Technologies |
| Others |
Cost & Logistics Intelligence
Multi-pollutant control systems are reshaping cost economics and supply concentration by demanding specialized components and integrated engineering expertise. This shift rewards solution providers capable of delivering complex, customized environmental compliance.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard flue gas treatment systems, particularly for fabric filters. The market primarily operates on a project-based pricing model, with differentiation stemming from customization level and integrated after-sales service. Pricing pressure stems from the increasing commoditization of basic SOx and NOx removal technologies. Smaller industrial operators are most price-sensitive, while large utilities prioritize guaranteed compliance and long-term operational efficiency.
Supply Chain Analysis
Logistics and freight costs significantly influence the delivered price of large-scale flue gas treatment equipment. Geographic supply concentration for core components centers on China for basic parts, and Germany and Japan for advanced technologies. The market relies on key raw materials like vanadium for SCR catalysts, specialized filter media, and high-grade steel alloys. Commodity price volatility, particularly for catalyst materials, represents a structural supply chain risk. Distribution runs through direct sales channels for major utility projects and specialized engineering firms for complex industrial installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global flue gas treatment systems market operates as a stable compounder, driven by the persistent and increasingly stringent environmental regulations worldwide. This market offers consistent opportunities for strategic investment and operational refinement.
For Market Incumbents:Anticipate the continuous upgrade cycle mandated by regulations like the EU's Industrial Emissions Directive by investing in multi-pollutant control systems. Diversify portfolios to include integrated carbon capture solutions, mitigating the threat from emerging standalone CCU technologies. Leverage extensive engineering capabilities and established client relationships to expand into Southeast Asian industrialization projects. Prioritize R&D in advanced hybrid systems to maintain a technological edge against specialized entrants.
For New Entrants and Emerging Players:Capture white-space opportunities by developing highly specialized, compact solutions for niche industrial applications or small-scale waste-to-energy facilities. The most penetrable segment lies with smaller industrial operators in rapidly industrializing nations like Vietnam and Indonesia. Offer compelling performance-based service agreements and remote monitoring capabilities as a go-to-market angle, reducing upfront capital expenditure for clients. Focus on multi-pollutant control in a single, integrated unit.
For Investors and Strategic Acquirers:Valuations sit cheapest among regional engineering firms with strong local project execution capabilities but limited technology portfolios. This market represents an essential infrastructure play with long-term viability, driven by non-discretionary environmental compliance. Target specialized technology developers focusing on advanced catalyst materials or digital twin platforms for strategic acquisitions. The key signal to watch as an inflection indicator is the implementation of new, stricter emission standards in previously unregulated or lightly regulated industrializing economies.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification into Multi-Pollutant Systems | Addresses evolving regulatory mandates for comprehensive emission control across diverse industrial sectors. |
| Geographic Expansion into Southeast Asia | Taps into future demand from industrialization and maturing environmental regulations in Vietnam and Indonesia. |
| Investment in Digital Twin Integration | Optimizes operational efficiency and predictive maintenance, improving asset lifecycle value for power generation operators. |
| Development of Integrated Carbon Capture Solutions | Enables industrial emitters to concurrently manage criteria pollutants and greenhouse gases, meeting dual compliance goals. |
| Long-term Performance-Based Service Contracts | Shifts procurement models from capital expenditure to operational expenditure, ensuring continuous compliance for European utilities. |
Research Approach
Bottom-up power generation modeling reconciled against top-down system integrators tracking forms the analytical core of this market assessment. Primary interviews with plant managers, environmental compliance officers, EPC contractors, and technology R&D directors provide qualitative insights. Secondary validation draws from US EPA reports, the EU Industrial Emissions Directive, China's MEE mandates, and specialized industry association publications. This approach triangulates data points for robust market sizing and forecasting.
Historical trendline analysis establishes the baseline for market projections across the analysis window. The quantitative model segments the market by product type, underlying technology, application, end-user, and regional regulatory stringency. Compound annual growth rates are derived from regression analysis on historical data and projected future demand. Key industry-specific forecast inputs include new power plant construction schedules and industrial capacity expansion plans in developing economies.
Geopolitical shifts, rapid technological breakthroughs in carbon capture, and economic downturns are the dominant revision risks for market forecasts. These forecasts reflect assumptions regarding regulatory enforcement and industrial investment cycles. A model refresh is warranted upon material change in global environmental policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Control Solutions
Modular Energy Control System Market
Environmental Control Solutions
Manufacturing Scale Electrostatic Precipitator Market
Environmental Control Solutions
North America Industrial Emission Control Systems Market
Environmental Control Solutions
Natural Refrigerants Market
Environmental Control Solutions
North America Nitrogen Oxide Control Systems Market
Environmental Control Solutions
Global Ballast Water Treatment Systems Market
Environmental Control Solutions
Global Leak Detection and Repair (LDAR) Market
Environmental Control Solutions
Gas Cleaning Technologies Market
Environmental Control Solutions
Bin Vent Filter Market
Environmental Control Solutions
Global Industrial Emission Control Systems Market
Environmental Control Solutions
Emission Control Technology Market
Environmental Control Solutions
Sailboat Ballast Water Treatment Technology Market
Environmental Control Solutions
Oil Water Separator Market
Environmental Control Solutions
Scrubber Market
Environmental Control Solutions
Global Flue Gas Desulphurization Market
Environmental Control Solutions
Scrubber System Market