
 Biomass Solid Fuel Market | 2026-2036
Biomass Solid Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Biomass Solid Fuel Market Analysis
Industrial power generators are reorganizing fuel procurement away from spot-market agricultural residues toward long-term pellet contracts with sustainability certification. Enviva Inc. leverages transatlantic export infrastructure to supply European utilities with industrial-scale wood pellet volumes. Drax Group plc anchors its generation portfolio through captive biomass conversion of former coal units in the United Kingdom. Stora Enso competes via integrated forest-to-fuel operations that control raw material flows across Nordic timber basins.
Biomass solid fuel comprises densified organic matter derived from lignocellulosic feedstocks, typically compressed to pellets with bulk densities exceeding 600 kg per cubic meter and moisture content below 10 percent, serving as a direct combustion substitute for coal in thermal power and heating systems. Wood pellets dominate fuel type revenue due to standardized calorific values and automated feed compatibility, while agricultural residues capture fastest growth in regions with established collection logistics for straw and husks. Pelletizing leads production method deployment for its energy efficiency and dust mitigation, though pyrolysis gains traction where biochar co-products command premium soil amendment prices.
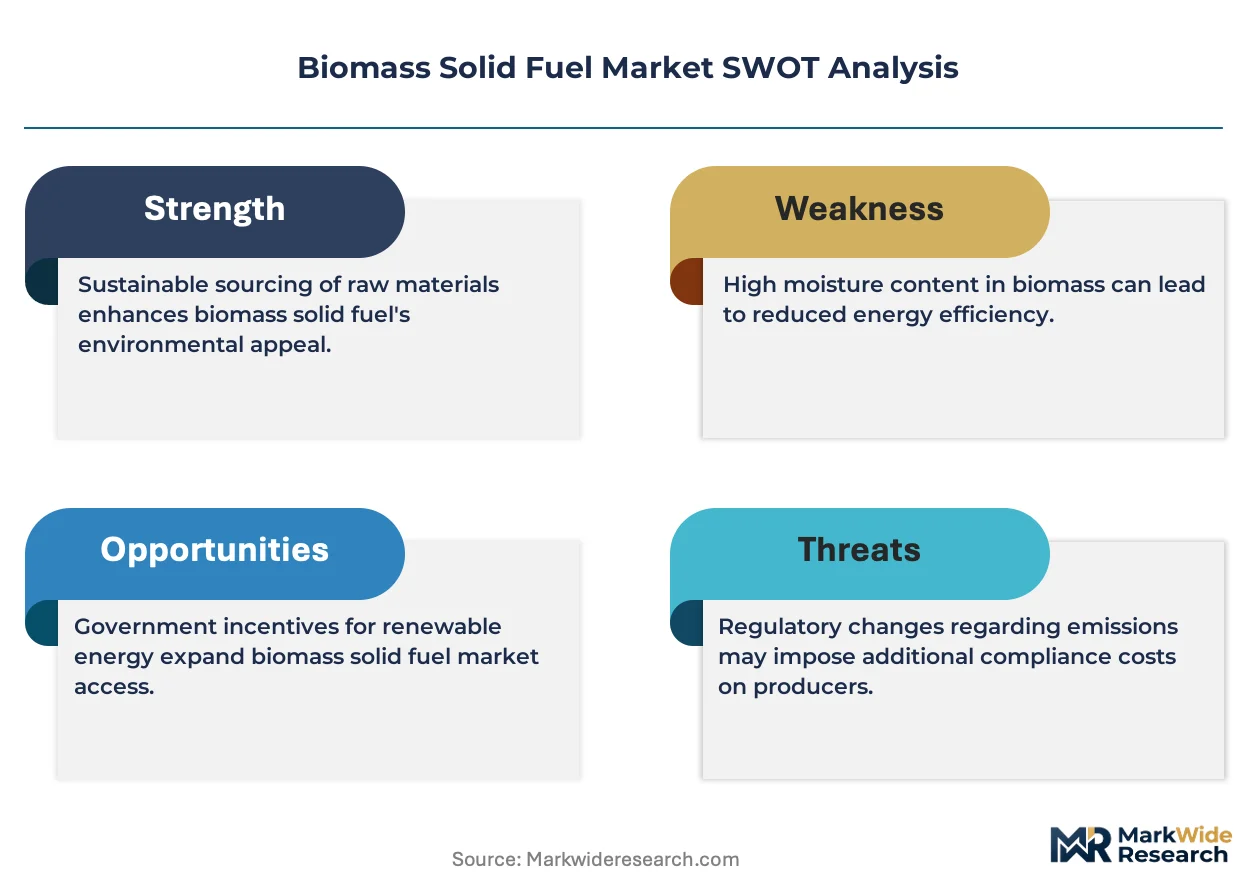
The EU Green Deal and F-Gas Regulation mandate progressive carbon intensity reductions for thermal generation, compelling boiler operators to source biomass with chain-of-custody certification under ENplus or Sustainable Biomass Program standards. The EPA in the United States enforces New Source Performance Standards that limit particulate emissions from industrial biomass combustors, filtering market access toward producers with advanced flue gas treatment. Stakeholders must monitor evolving sustainability criteria that threaten to disqualify feedstocks from high-carbon-payback land use categories.
Market Dynamics
District heating utilities across Northern Europe are consolidating procurement around certified wood pellet contracts, forcing suppliers to restructure logistics networks around sustainability verification and long-term offtake guarantees rather than spot-market trading.
Growth Catalysts
- EU Green Deal carbon intensity mandates:Boiler operators must source ENplus-certified biomass to meet progressive emissions benchmarks, redirecting capital toward pellet infrastructure.
- Coal-to-biomass retrofit programs:Combined heat and power plants in Germany, Sweden, and Finland are converting former coal units to biomass co-firing, creating baseload demand anchors.
- Pyrolysis technology maturation:Biochar co-production commands premium soil amendment prices in agricultural markets, improving project economics for integrated facilities.
Market Restraints
- Feedstock cost volatility:Sawmill residue prices fluctuate with construction cycles, compressing margins for pellet producers without captive timber supply.
- Transatlantic shipping concentration:Gulf Coast export terminals create single-point-of-failure risk for European utility supply security.
- High-carbon-payback land use disqualification:Draft sustainability criteria threaten to exclude whole-forest harvest feedstocks from certified supply pools.
Strategic Opportunities
- Agricultural residue collection networks:Straw and husk logistics in Poland and Romania remain underdeveloped, offering first-mover advantages for densified fuel producers.
- Industrial heat decarbonization mandates:F-Gas Regulation phase-down creates substitution demand for solid biomass in process steam applications.
- Automated feed system retrofits:Pellet handling technology convergence with legacy coal infrastructure reduces conversion capital for power generators.
Industry Challenges
- Chain-of-custody certification timelines:ENplus and Sustainable Biomass Program audits require 12-18 month implementation periods, delaying market access for new entrants.
- Flue gas treatment capex burdens:EPA New Source Performance Standards for particulate emissions demand precipitator or baghouse investments that strain project returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biomass Solid Fuel Market |
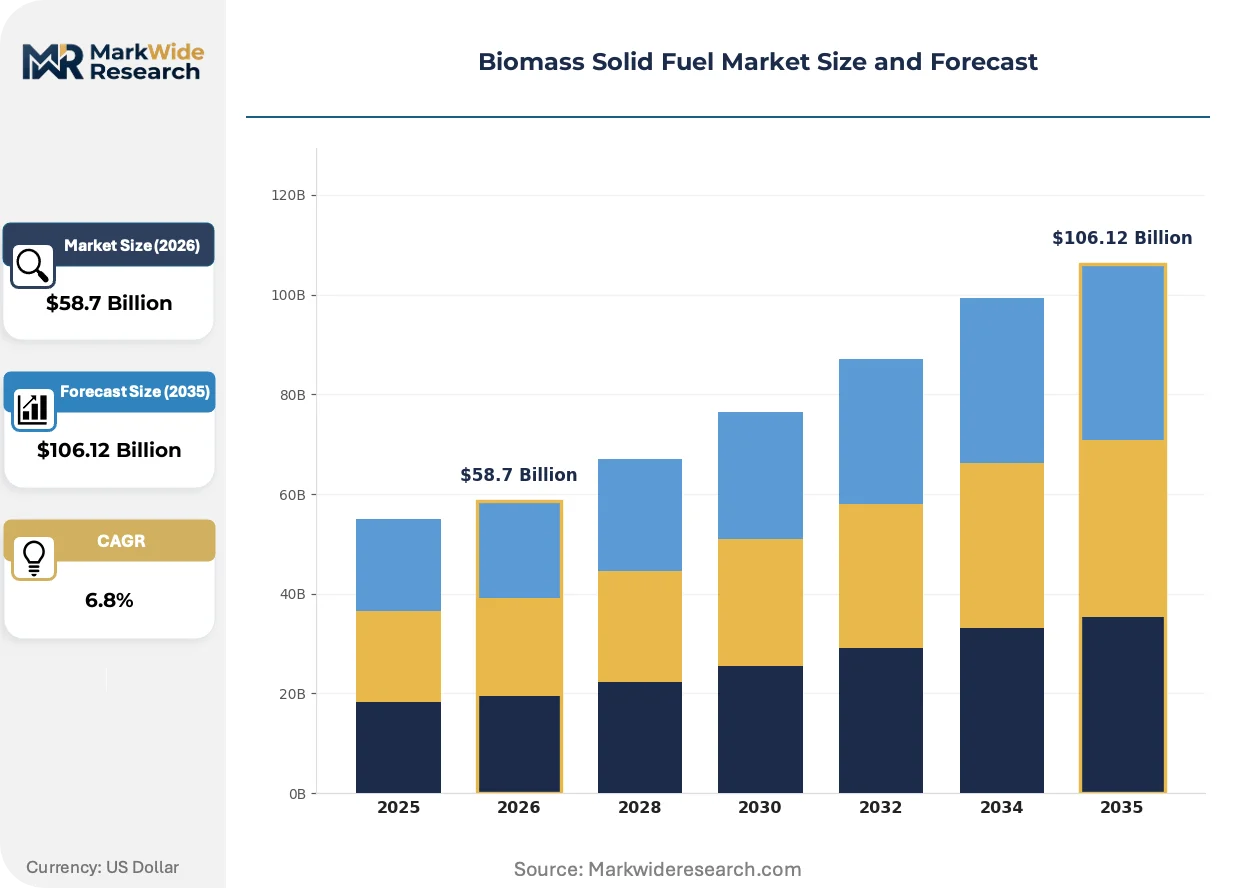
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Wood Pellets, Agricultural Residues, Sawdust, Charcoal Production Method: Pelletizing, Briquetting, Pyrolysis, Gasification Application: Power Generation, Residential Heating, Industrial Heating, Transportation Distribution Channel: Wholesale, Retail, E-commerce, Direct Sales |
| Companies Covered | Enviva Inc., Drax Group plc, Stora Enso, AS Graanul Invest, Andritz AG, Vattenfall AB, Lignetics, Inc., Pinnacle Renewable Energy, BTG Biomass Technology Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biomass Solid Fuel Market Emerging Trajectories
Torrefaction and steam explosion pre-treatment methods are reshaping fuel quality standards, enabling higher grindability and moisture resistance that expand biomass substitution rates in pulverized coal systems.
Torrefaction—mild pyrolysis at 200-300°C—is displacing conventional white pellets in cofiring applications above 20% thermal substitution. Drax Group and European utilities are piloting torrefied black pellets at scale. The technology is displacing moisture-sensitive white pellet supply chains in marine transport corridors where condensation degrades fuel performance.
The EU F-Gas Regulation's hydrofluorocarbon phase-down is tightening industrial refrigeration and heat pump pathways, redirecting process heat investment toward solid biomass combustion systems. Boiler manufacturers are engineering compact modular units for 10-50 MW industrial sites. Food processing and paper mills in the Netherlands and Denmark are most affected, accelerating tender activity for biomass heat supply contracts.
Long-term offtake contracting is replacing spot procurement for district heating utilities. Stockholm Exergi and Helsinki Energy have moved to 5-10 year pellet supply agreements with fixed escalation clauses. District heating cooperatives in Austria and the Czech Republic are consolidating purchasing through joint procurement platforms, compressing supplier margins but securing volume commitments for certified producers.
Biomass Solid Fuel Market Segmentation
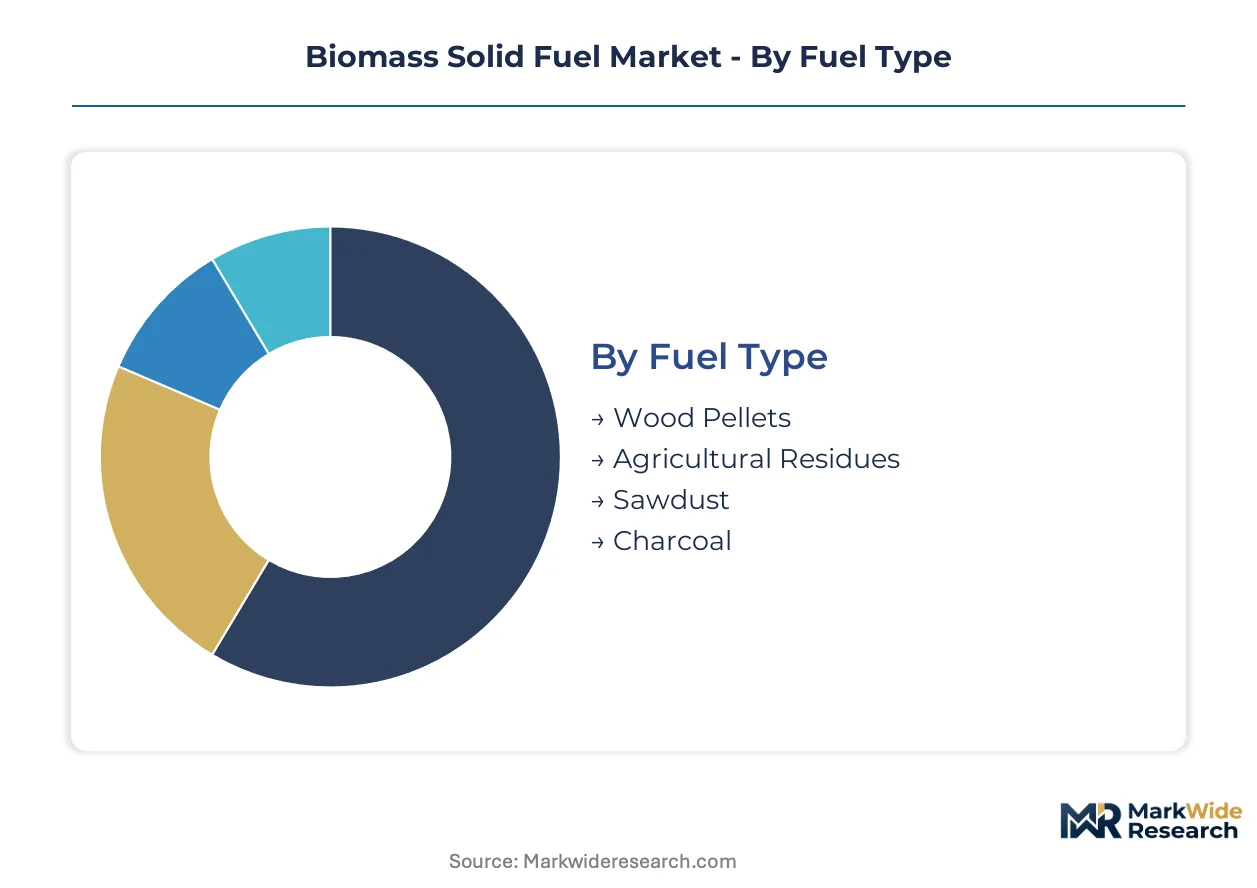
Segmentation in the biomass solid fuel market reveals how procurement patterns, certification requirements, and infrastructure investments concentrate value across distinct fuel forms, production technologies, and end-use applications. Understanding these divisions exposes where margin pools form and where competitive positioning shifts most rapidly.
Fuel Type:
Margin pools concentrate around certification tiers and moisture specifications, with premium grades commanding supply security premiums from district heating utilities.
- Wood Pellets:Densified lignocellulosic material compressed to bulk densities exceeding 600 kg per cubic meter with sub-10% moisture content. Demand clusters in Germany, Sweden, and Finland where ENplus-certified pellets serve as baseload supply for coal-converted CHP plants under EU Green Deal mandates.
- Agricultural Residues:Densified straw, husks, and crop waste requiring established collection logistics for economic viability. Poland and Romania present first-mover expansion opportunities as logistics networks for straw and husk aggregation remain underdeveloped relative to Nordic wood pellet infrastructure.
- Sawdust:Fine particulate wood waste requiring pelletizing or briquetting for combustion suitability.
- Charcoal:Carbonized biomass with high fixed-carbon content serving specialty industrial and residential applications.
Wood Pellets holds installed capacity. Agricultural Residues is rotating up the share rankings.
Production Method:
Technology selection tracks feedstock moisture, scale economics, and co-product revenue potential across thermal and mechanical processing routes.
- Pelletizing:Mechanical compression of dried biomass through ring or flat die extrusion, dominating deployment for energy efficiency and dust mitigation in automated feed systems. Drax Group and European utilities anchor demand through long-term offtake contracts requiring standardized fuel geometry.
- Pyrolysis:Thermal decomposition in oxygen-limited conditions producing biochar, bio-oil, and syngas fractions. Biochar co-production commands premium soil amendment prices in agricultural markets, improving integrated facility economics where carbon removal credits stack with fuel revenue.
- Briquetting:High-pressure compaction of biomass without binders, suited to lower-density feedstocks and manual handling applications.
- Gasification:Partial oxidation producing syngas for power generation or chemical synthesis, gaining traction in distributed industrial heat applications.
Pelletizing retains dominant share. Pyrolysis is climbing the fastest as biochar markets mature.
Application:
End-use segmentation reflects divergent fuel specifications, emission thresholds, and contract structures across utility-scale, residential, and industrial thermal demand.
- Power Generation:Utility-scale combustion and co-firing in converted coal units requiring consistent calorific value and low ash content. Combined heat and power plants in Germany, Sweden, and Finland drive retrofit investment as F-Gas Regulation phase-down redirects process heat toward solid biomass systems.
- Industrial Heating:Process steam and thermal applications in food processing and paper mills. Netherlands and Danish facilities accelerate tender activity as hydrofluorocarbon restrictions tighten industrial refrigeration pathways.
- Residential Heating:Stove and boiler combustion in single-family and multi-unit buildings, price-sensitive to pellet premiums over fossil alternatives.
- Transportation:Solid biomass-to-liquid pathways and biofuel feedstock applications, nascent relative to direct combustion markets.
Power Generation anchors volume commitments. Industrial Heating is gaining share fastest as F-Gas mandates bite.
Distribution Channel:
Channel structure tracks lot size, certification verification burden, and logistics infrastructure ownership across intermediary and direct procurement models.
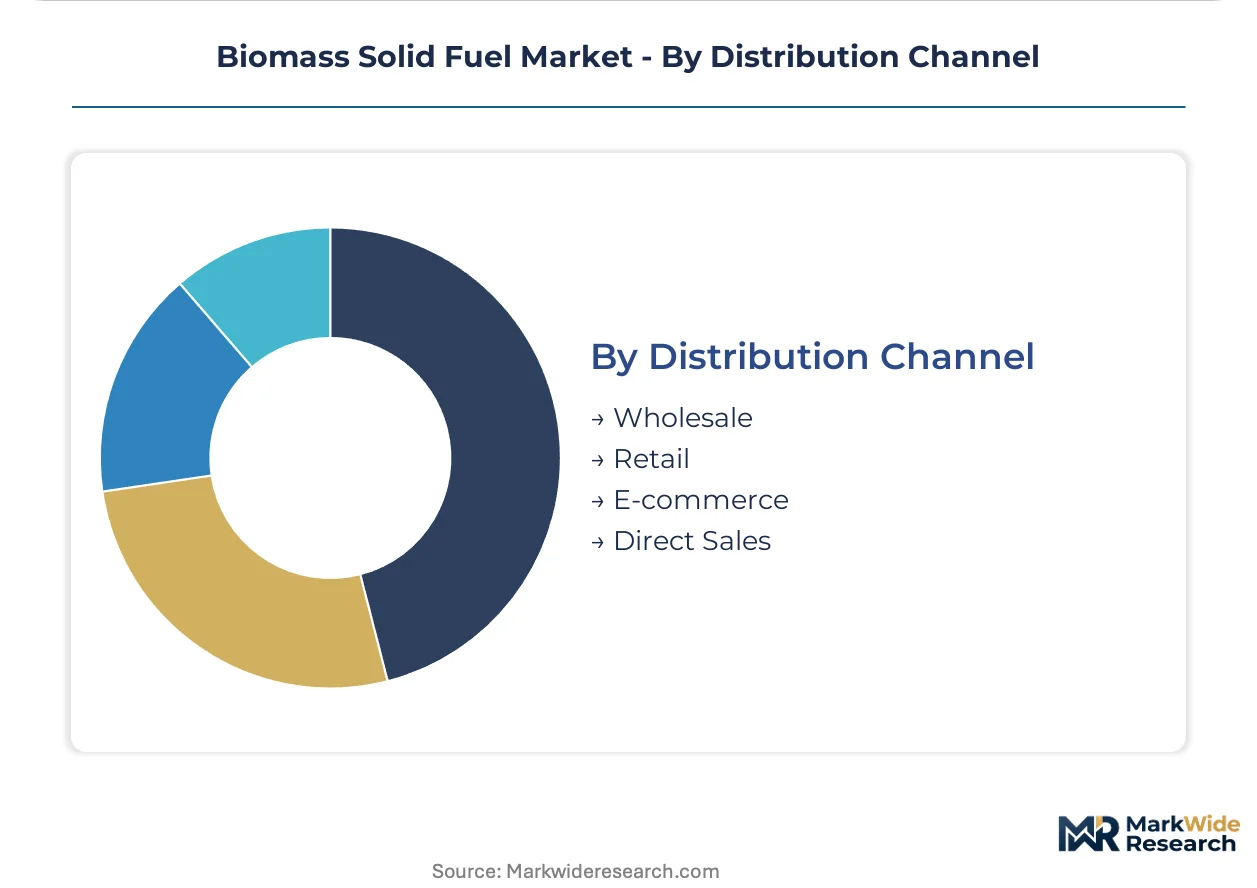
- Wholesale:Bulk procurement by district heating cooperatives and industrial consumers through consolidated purchasing platforms. Stockholm Exergi and Helsinki Energy have moved to 5-10 year supply agreements with fixed escalation clauses, compressing supplier margins but securing volume commitments for certified producers.
- Direct Sales:Long-term offtake contracts between pellet producers and utility buyers, displacing spot-market agricultural residue trading as sustainability verification requirements intensify.
- Retail:Bagged and loose pellet sales through building supply and agricultural merchants, serving residential and small commercial consumers.
- E-commerce:Digital ordering platforms for residential fuel delivery, limited by bulk density and shipping cost economics relative to local distribution.
Wholesale holds contracted volume. Direct Sales is rotating up the share rankings as procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transatlantic pellet flows from the United States Gulf Coast to Northern European utilities anchor the dominant trade corridor, with export terminal capacity determining supply security for district heating cooperatives across the Baltic and North Sea basins.
Germany
Coal-to-biomass retrofit programs at combined heat and power plants in Brandenburg and Saxony-Anhalt drive baseload pellet demand. The Federal Emission Control Act enforces strict particulate limits on solid fuel combustors. Industrial clusters around Berlin and Leipzig are converting former lignite units to biomass co-firing under EU Green Deal carbon intensity mandates.
Sweden
District heating utilities in Stockholm, Gothenburg, and Malmö have consolidated procurement around 5-10 year ENplus-certified pellet contracts. The Swedish Environmental Code mandates sustainability verification for biomass combustion subsidies. CHP plants in the Mälaren Valley region are retrofitting coal boilers for 100% biomass firing.
Finland
Helsinki Energy and other municipal utilities anchor long-term offtake agreements with fixed price escalation clauses. The Finnish Energy Authority enforces renewable heat obligations under the National Energy and Climate Strategy. Forest industry integration around Kajaani and Joensuu enables captive pellet supply from sawmill residue streams.
United States
Gulf Coast export terminals in Alabama, Mississippi, and Louisiana supply industrial-scale pellet volumes to European utilities. EPA New Source Performance Standards filter market access toward producers with advanced flue gas treatment. The Southeast timber belt provides sawmill residue feedstock for densified fuel production.
United Kingdom
Drax Group's Selby complex anchors national biomass power capacity through converted coal units. The UK Emissions Trading Scheme and Contracts for Difference mechanism support biomass generation economics. Yorkshire and Humberside industrial zones concentrate fuel handling infrastructure for utility-scale combustion.
Biomass Solid Fuel Market Vendor Landscape
Player mix skews toward integrated forest products companies and dedicated pellet producers with transatlantic export infrastructure. The competitive landscape tiers between large-scale utilities with captive fuel conversion, independent pellet producers with sustainability certification, and equipment suppliers engineering automated feed systems. Strategic moves concentrate on securing long-term offtake contracts with ENplus chain-of-custody verification and expanding torrefaction capacity for higher substitution rates in pulverized coal systems.
Within the integrated utility tier, Drax Group plc and Vattenfall AB occupy positions defined by captive biomass conversion of former coal generation assets. Among dedicated pellet producers, Enviva Inc. exemplifies the transatlantic export archetype through Gulf Coast terminal infrastructure, while Stora Enso represents Nordic forest-to-fuel integration controlling raw material flows across timber basins. AS Graanul Invest anchors Baltic production capacity with sustainability-certified supply to Northern European district heating networks.
| Leading Market Players |
|---|
| Enviva Inc. |
| Drax Group plc |
| Stora Enso |
| AS Graanul Invest |
| Andritz AG |
| Vattenfall AB |
| Lignetics, Inc. |
| Pinnacle Renewable Energy |
| BTG Biomass Technology Group |
| Others |
Supply Flow & Price Mechanics
Torrefaction's displacement of conventional white pellets simultaneously redraws supply geography toward humid subtidal corridors and compresses pricing premiums for moisture-resistant fuel grades. The technology shift forces Atlantic basin producers to absorb pre-treatment capital costs while Baltic utilities capture basis-point savings on reduced transport losses.
Pricing Analysis
White pellet-torrefied pellet-biochar pricing stratification separates ENplus-certified industrial grades from torrefied black pellets and premium soil-amendment co-products. Price differentiation hinges on certification tier under the Sustainable Biomass Program and moisture resistance specifications for marine transport. Cost compression in standard white pellets is intensifying because Drax Group and European utilities are piloting torrefied alternatives at scale. District heating cooperatives exhibit highest price sensitivity due to fixed-escalation contract structures, while industrial CHP plants show lowest sensitivity given carbon compliance cost avoidance.
Supply Chain Analysis
Transatlantic container availability constraints and Gulf Coast terminal congestion elevate landed costs for European utility buyers. Geographic supply concentration centers on the United States Southeast, Estonia, and Latvia, with feedstock flows drawing from Nordic sawmill residues and American timber belt harvests. Raw material dependencies rest on sawmill residue streams, straw aggregation networks, and forestry slash collection systems. Single-source vulnerability permeates the Alabama-Mississippi-Louisiana export terminal cluster. Distribution runs through long-term offtake contracts with sustainability verification rather than spot-market trading.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment moat where ENplus and Sustainable Biomass Program certification timelines create 12-18 month barriers to supply access. Switching costs lock district heating utilities into verified supplier relationships under multi-year procurement platforms.
For Market Incumbents: Consolidate backward integration into captive timber basins and sawmill residue streams to buffer construction-cycle price volatility. Expand torrefaction capacity in humid Gulf Coast corridors to capture moisture-resistance premiums. Threats from agricultural residue logistics in Poland and Romania demand preemptive certification investment to maintain supply pool eligibility.
For New Entrants and Emerging Players: Lead with agricultural residue collection networks in underdeveloped straw and husk logistics regions where Nordic wood pellet infrastructure has not penetrated. Poland and Romania present the most penetrable geographies for densified fuel production. A go-to-market angle anchored to F-Gas Regulation industrial heat substitution tenders bypasses entrenched utility supply relationships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed pellet producers holding Gulf Coast terminal infrastructure but lacking integrated forest supply. Long-term viability across a 5-10 year window hinges on sustainability criteria durability and carbon removal credit stacking potential. The signal to watch is draft high-carbon-payback land use disqualification language that would strand whole-forest harvest feedstock investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Torrefaction Capacity Buildout | Drax Group pilots black pellets to displace moisture-sensitive white pellet marine supply chains. |
| Backward Integration into Timber Basins | Stora Enso controls raw material flows across Nordic sawmill residue streams to compress feedstock volatility. |
| Long-term Offtake Contracting | Stockholm Exergi and Helsinki Energy secure 5-10 year ENplus-certified supply with fixed escalation clauses. |
| Agricultural Residue Logistics Investment | First-mover advantages emerge in Poland and Romania where straw and husk collection networks remain underdeveloped. |
| Sustainability Certification Program | ENplus and Sustainable Biomass Program audits filter market access toward verified chain-of-custody producers. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across district heating utility procurement officers, pellet plant operations managers, forest products procurement leads, and marine logistics coordinators. Secondary validation drew from EIA biomass fuel data, EU Green Deal implementation trackers, FERC export terminal filings, and sustainability certification registry disclosures. Bottom-up volume modeling triangulated against top-down carbon intensity mandate trajectories.
Across the projection horizon, the analytical framework modeled fuel type segmentation, production technology tiers, and end-use application splits alongside regulatory framework clusters and regional grid decarbonization pathways. CAGRs were derived from utility retrofit investment pipelines and sustainability mandate compliance schedules. Forecast inputs incorporated CHP conversion capital expenditure cycles and torrefaction technology maturation curves.
Forecasts assume regulatory continuity in EU Green Deal carbon intensity mandates and EPA New Source Performance Standards enforcement; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioenergy
Bioenergy Market
Bioenergy
Biomass Molding Fuel Market
Bioenergy
Biopellets Energy Market
Bioenergy
Biomass Wood Chip Market
Bioenergy
Europe Bioenergy Market
Bioenergy
Biopower Market
Bioenergy
Global Biomass Briquette Market
Bioenergy
Bio CHP Market
Bioenergy
Micro-Scale Biogas Plant Market
Bioenergy
Europe Biogas Market
Bioenergy
Organic Biogas Market
Bioenergy
Biogas Market