
 EV Charging Cables Market | 2026-2036
EV Charging Cables Market Size, Share, and Industry Trends Forecast 2026-2036
EV Charging Cables Market Intelligence
Modular cable-connector bundling is realigning how fleet operators and charging network architects specify procurement packages. Prysmian leverages its cable manufacturing scale to anchor European supply contracts for high-power charging corridors. TE Connectivity competes through connector specialization that integrates thermal management directly into plug assemblies. Huber+Suhner positions across the DC fast-charging segment with RF-shielded cable designs that address electromagnetic interference in dense urban installations.
EV charging cables are insulated conductor assemblies engineered to transmit electrical power between grid infrastructure and electric vehicle inlets, typically rated from 3.7 kW AC through 350 kW DC with liquid-cooled conductor configurations for extreme fast charging. Their primary commercial purpose is to enable safe, standardized energy transfer across varying duty cycles and environmental conditions while maintaining mechanical flexibility over thousands of insertion cycles. Type 2 and CCS connectors dominate European and North American deployments where interoperability mandates have locked in physical interface standards, while GB/T cables sustain captive demand within China's domestic charging ecosystem. The socket outlet versus fixed connector divergence reflects a structural split between consumer-facing flexibility priorities and fleet-operator preferences for vandal-resistant permanent installations.
The EU Green Deal and F-Gas Regulation are tightening material compliance for cable insulation and coolant formulations across European supply chains. In the United States, NHTSA and OSHA frameworks intersect with IRA domestic content requirements to reshape where and how charging cable assemblies qualify for federal project subsidies. China's MIIT and GB standards authorities enforce connector compatibility and fire-safety testing protocols that create distinct certification pathways for market entry. Stakeholders must monitor how divergent regional certification timelines and local content rules affect inventory positioning and manufacturing location decisions across major demand clusters.
Market Dynamics
Modular cable-connector bundling is compressing procurement cycles for fleet operators and charging network architects, forcing suppliers to reconfigure production lines around integrated assemblies rather than discrete components.
Growth Catalysts
- IRA domestic content mandates:US federal tax incentives now require 55% North American content for charging hardware subsidies, redirecting assembly capacity toward domestic copper processing and connector fabrication.
- Commercial fleet electrification:Logistics operators in Germany and California are specifying liquid-cooled 350 kW cables for depot charging, creating sustained demand for high-amperage conductor configurations.
- China's urban infrastructure buildout:Municipal governments in Shenzhen and Shanghai are mandating GB/T-compliant fast-charging density targets in new commercial developments.
Market Restraints
- Copper price volatility:Raw material swings exceeding 30% annually compress margin buffers for cable assemblers locked into fixed-price infrastructure contracts.
- Connector standard fragmentation:The divergence between CCS, CHAdeMO, and GB/T physical interfaces forces manufacturers to maintain redundant tooling and inventory across regional SKUs.
- F-Gas coolant restrictions:EU regulations are phasing out conventional dielectric fluids used in liquid-cooled high-power cables, requiring reformulation of thermal management systems.
Strategic Opportunities
- India's nascent charging corridor:The country's PLI scheme for auto component manufacturing offers tariff advantages for cable suppliers establishing local conductor extrusion capacity.
- RF-shielded urban installations:Electromagnetic interference mitigation is unifying cable design specifications for dense metropolitan deployments near cellular and broadcast infrastructure.
- Second-life battery integration:Stationary storage co-location with charging hubs creates demand for hybrid AC/DC cable assemblies serving dual grid-buffering functions.
Industry Challenges
- Cross-regional certification timelines:Divergent testing protocols between UL, CE marking, and GB standards authorities extend product launch cycles by 8-14 months for multi-market suppliers.
- Liquid-cooling system integration:Thermal management expertise from adjacent industries must be imported to meet reliability targets for 500+ kW charging sessions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Charging Cables Market |
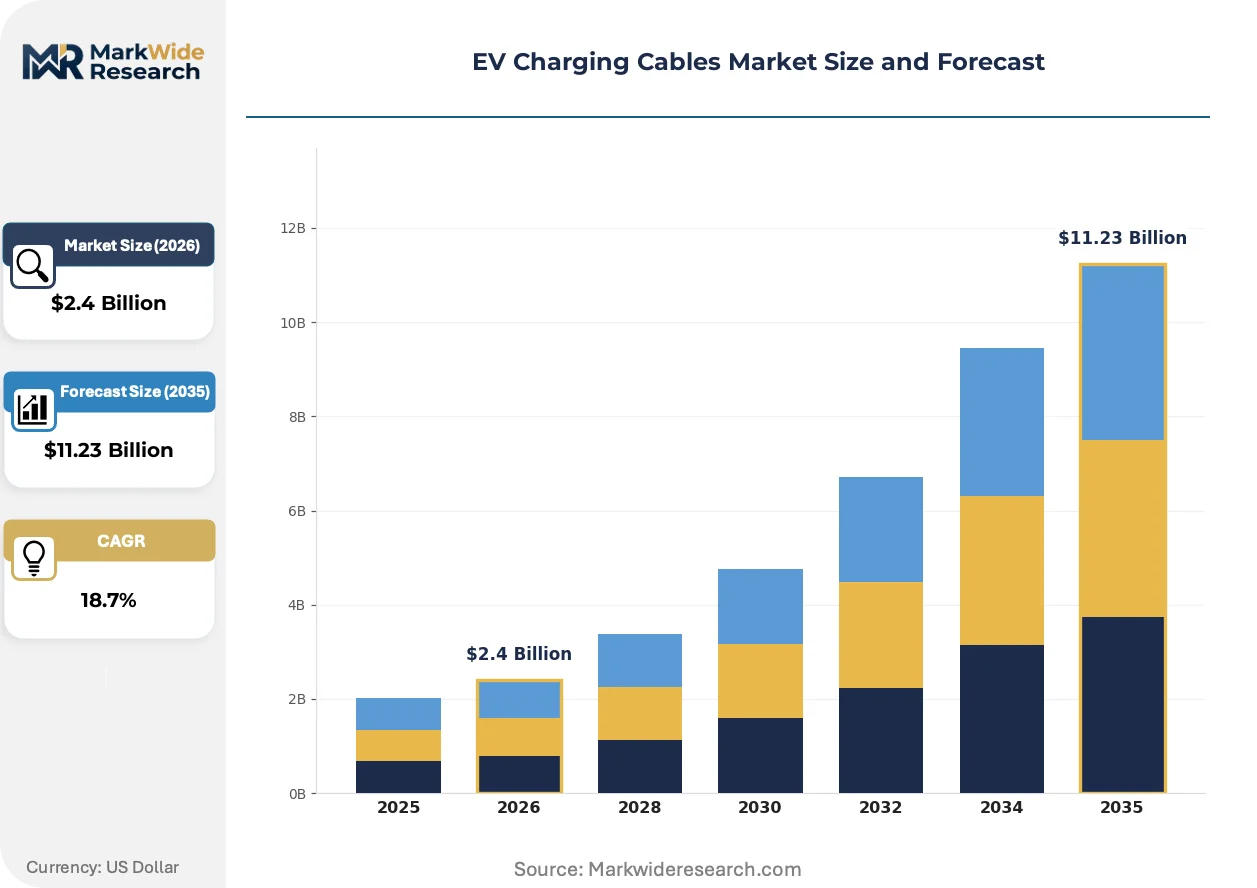
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $11.23 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Type 1, Type 2, CHAdeMO, CCS, GB/T Connector Type: Socket Outlet, Plug Lock, Fixed Connector, Detachable Connector End User: Public Charging Stations, Commercial EV Fleets, Residential Charging, Fleet Operators Application: Urban Infrastructure, Highway Fast Charging, Workplace Charging, Retail Locations |
| Companies Covered | Prysmian, Dyden, Phoenix Contact, Sinbon Electronics, Huber+Suhner, Aptiv, TE Connectivity, BRUGG, LEONI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Charging Cables Market Strategic Shifts & Innovations
Active material substitution and regulatory harmonization efforts are compressing design iteration cycles while expanding the performance envelope for extreme fast-charging applications.
Silicone rubber insulation compounds are unifying temperature rating specifications across AC and DC cable categories, enabling manufacturers to consolidate compound formulations. Tier-1 suppliers in South Korea and Germany are adopting these materials for corridor charging contracts above 150 kW. This unification is collapsing the traditional separation between residential and commercial cable product lines.
The EU F-Gas Regulation is prohibiting hydrofluorocarbon-based coolants in liquid-cooled charging cables from 2027, compelling reformulation toward synthetic ester alternatives. Cable assemblers serving German and Dutch highway corridor projects are accelerating qualification testing for biodegradable thermal fluids. High-power charging station deployments in Northern Europe face the most compressed compliance timelines.
Fleet operators are consolidating vendor relationships around full-system procurement packages that bundle cables, connectors, and installation services. Charging network architects in California and Texas are displacing component-only purchasing in favor of performance-guaranteed supply contracts. This consolidation is most visible among logistics operators managing 500+ vehicle electrification programs.
EV Charging Cables Market Segmentation
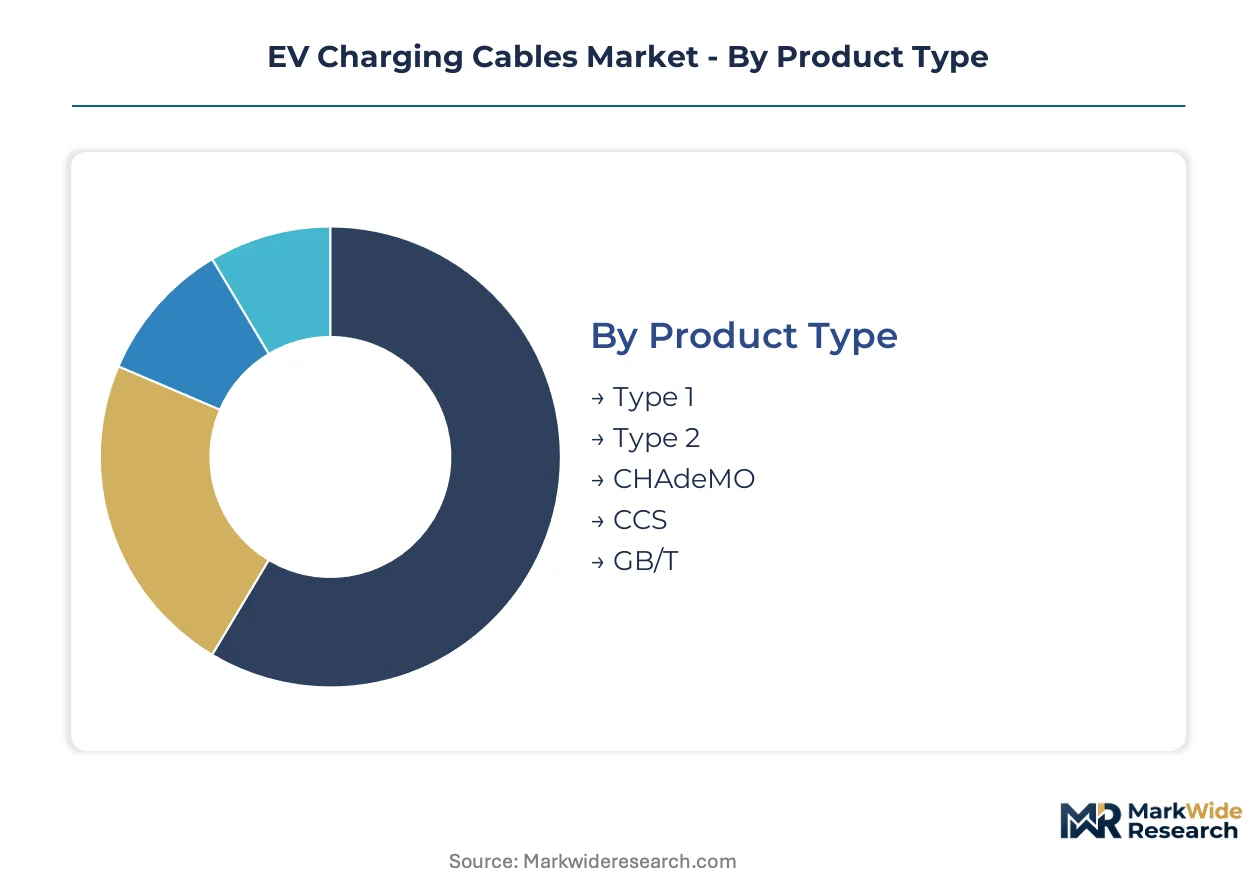
Segmentation in EV charging cables reveals how capital allocation, regulatory mandates, and infrastructure deployment patterns concentrate demand across distinct technical specifications. Procurement decisions by fleet operators and network architects hinge on matching connector standards, installation permanence, and duty-cycle requirements to specific deployment environments.
Product Type:
Capital intensity varies sharply across product types, with liquid-cooled high-power configurations demanding the heaviest upfront tooling and materials investment.
- CCS:Combined Charging System cables integrate AC and DC conductors within a single connector housing, rated up to 350 kW with liquid-cooled variants. European highway corridor deployments in Germany and Dutch charging networks specify CCS exclusively under EU interoperability mandates, creating concentrated demand for high-amperage conductor assemblies.
- Type 2:The Mennekes standard dominates European AC charging infrastructure with three-phase capability up to 43 kW. Scandinavian and German workplace charging installations favor Type 2 socket outlets for their compatibility with both private vehicles and light commercial fleets, sustaining steady procurement volumes across temperate climate specifications.
- Type 1:Single-phase AC connector standard primarily serving Japanese and early North American vehicle inlets with 7.4 kW maximum output.
- CHAdeMO:DC fast-charging standard maintaining installed base primarily in Japan and select legacy North American deployments.
- GB/T:Chinese national standard for AC and DC charging with distinct connector geometry enforced by MIIT certification requirements.
CCS absorbs the bulk of installed capacity across European and North American corridors; GB/T is expanding most quickly through China's municipal infrastructure mandates.
Connector Type:
Installation permanence dictates procurement economics, with fixed connector systems requiring higher initial capital outlay but lower lifecycle replacement costs.
- Fixed Connector:Permanently tethered cable-connector assemblies mounted directly to charging dispensers, engineered for vandal resistance and 10,000+ insertion cycles. California logistics depots and German fleet charging hubs specify fixed connectors to minimize theft exposure and maintenance intervals, accepting higher upfront hardware costs for operational reliability.
- Socket Outlet:Receptacle-based systems allowing users to supply their own cables, prevalent in European residential and workplace installations. German and French multi-unit dwelling regulations increasingly mandate socket outlets for tenant flexibility, creating fragmented but substantial demand across lower-power AC specifications.
- Plug Lock:Mechanically secured connector retention systems for high-vibration environments including commercial vehicle depots.
- Detachable Connector:Removable cable assemblies enabling field replacement and transport flexibility for temporary charging deployments.
Fixed connector systems dominate commercial fleet procurement; socket outlets retain volume leadership in European residential segment expansion.
End User:
Customer scale determines contract structure, with fleet operators consolidating procurement around multi-year supply agreements while residential channels fragment across retail distribution.
- Commercial EV Fleets:Logistics operators and delivery services specifying liquid-cooled 350 kW cables for depot-based overnight charging of heavy-duty vehicles. California and German last-mile delivery electrification programs are consolidating vendor relationships around performance-guaranteed full-system contracts bundling hardware, installation, and maintenance.
- Public Charging Stations:Network operators deploying high-utilization hardware across highway corridors and urban hubs, prioritizing mean-time-between-failure metrics and rapid cable replacement protocols.
- Residential Charging:Single-family and multi-unit dwelling installations, predominantly AC Level 2 specifications with shorter cable lengths and lower duty-cycle requirements.
- Fleet Operators:Dedicated vehicle management entities distinct from commercial fleets, often government or utility-affiliated, with standardized procurement processes.
Commercial EV fleets command the steepest expansion trajectory as electrification deadlines tighten; public charging stations maintain the largest installed base.
Application:
Environmental exposure and utilization intensity separate application segments, with highway installations demanding the most ruggedized cable specifications.
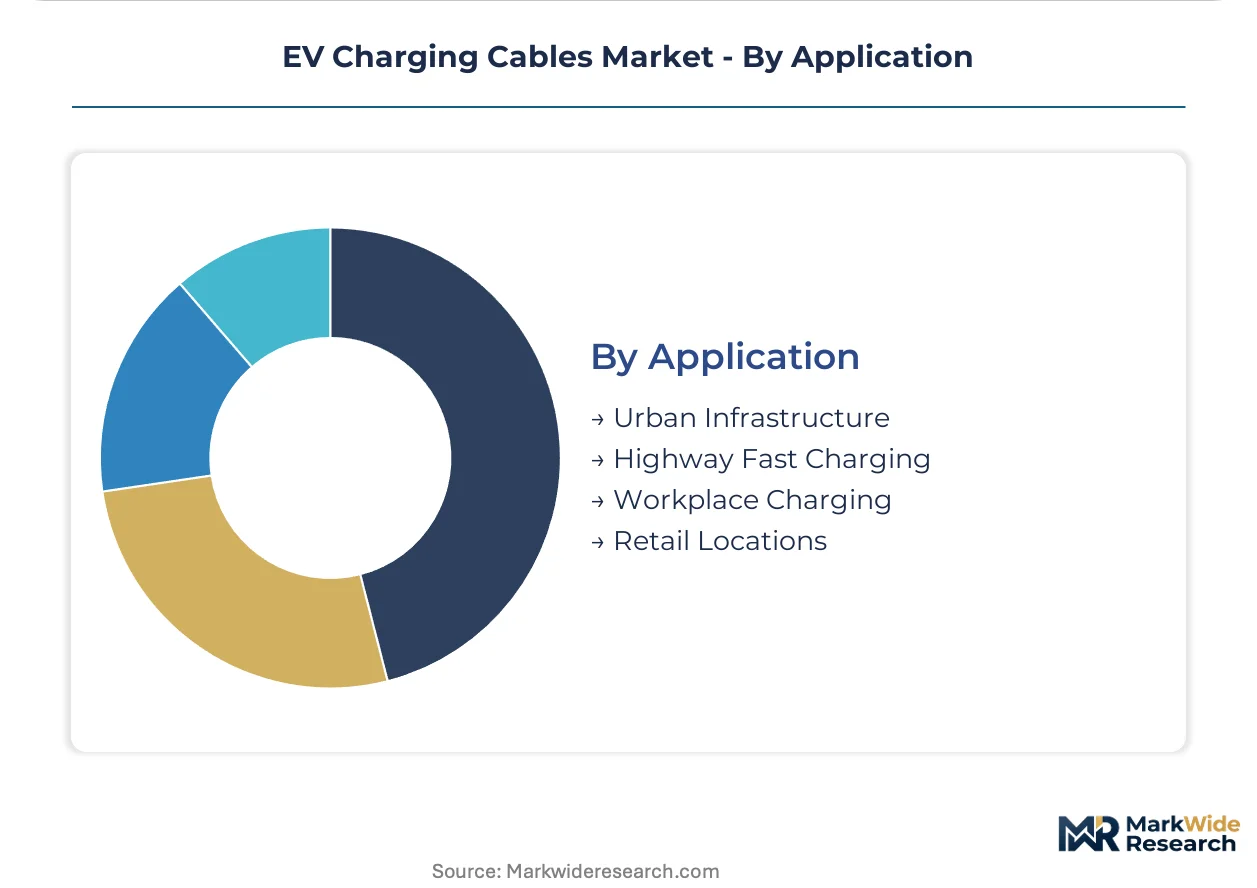
- Highway Fast Charging:Extreme-duty installations along major transport corridors requiring liquid-cooled cables rated for continuous 350 kW output in ambient temperatures from -30°C to +50°C. German Autobahn and Dutch highway corridor projects are specifying RF-shielded cable designs to mitigate electromagnetic interference near broadcast transmitters, adding material cost premiums.
- Urban Infrastructure:Street-side and parking structure deployments in dense metropolitan areas, balancing space constraints with vandal resistance requirements.
- Workplace Charging:Employer-sited installations with moderate duty cycles, predominantly AC specifications serving employee vehicles during standard business hours.
- Retail Locations:Customer-facing charging at shopping centers and service stations, prioritizing connector durability under intermittent public use.
Highway fast charging captures the premium pricing tier; urban infrastructure is scaling most rapidly through municipal mandate compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of EV charging cable assemblies while Germany and the United States absorb premium volumes for highway corridor and fleet depot installations. This production-consumption divide shapes inventory positioning and certification strategies across supplier networks.
China
Shenzhen and Shanghai municipal governments enforce GB/T-compliant fast-charging density mandates in new commercial developments. MIIT certification requirements create distinct technical pathways that domestic suppliers exploit for cost advantages. The Yangtze River Delta cluster concentrates extrusion and connector fabrication capacity serving both domestic buildout and export markets.
Germany
Autobahn highway corridor expansion and last-mile delivery electrification sustain demand for liquid-cooled 350 kW CCS cable assemblies. The EU Green Deal and F-Gas Regulation tighten material compliance timelines for insulation and coolant formulations through 2027. Bavaria and North Rhine-Westphalia host the densest concentrations of charging hardware procurement for fleet operator consolidation programs.
United States
California logistics depots and Texas charging network architects specify fixed-connector systems for vandal-resistant fleet installations. IRA domestic content mandates require 55% North American assembly for federal tax subsidy eligibility, redirecting copper processing and connector fabrication toward domestic facilities. The Southeast and Midwest are emerging as alternative assembly locations as suppliers diversify beyond traditional coastal manufacturing bases.
South Korea
Domestic automotive OEM electrification roadmaps drive procurement of high-amperage cable assemblies for proprietary charging networks. MFDS-equivalent industrial standards and METI-aligned technical specifications shape export-oriented production for Japanese and Southeast Asian markets. The Seoul Capital Area concentrates R&D-intensive cable design capabilities serving premium corridor charging contracts.
India
The PLI scheme for auto component manufacturing offers tariff advantages for cable suppliers establishing local conductor extrusion capacity. State-level electric mobility policies in Maharashtra and Gujarat mandate charging infrastructure readiness in new commercial construction. The Delhi-NCR corridor represents the most advanced deployment environment for pilot fast-charging networks ahead of national scale-up.
EV Charging Cables Market Key Industry Players
The competitive structure tilts toward diversified industrial conglomerates with captive cable manufacturing capabilities rather than pure-play specialists. Tier-1 suppliers anchor European and North American supply contracts through integrated connector-cable bundling and installation service offerings. Three archetypes dominate: scale-driven materials conglomerates, connector-specialized electronics manufacturers, and regional system integrators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as suppliers reposition assembly lines around integrated full-system procurement packages.
Among European-based industrial conglomerates, Prysmian and LEONI occupy positions anchored in large-scale conductor extrusion and materials science capabilities. TE Connectivity exemplifies the connector-specialized archetype, leveraging electronics manufacturing expertise to integrate thermal management functions directly into plug assemblies. Huber+Suhner represents the RF-shielding specialist segment, addressing electromagnetic interference requirements for dense urban installations near cellular and broadcast infrastructure. These three companies illustrate how technical specialization vectors—materials scale, connector integration, and signal integrity—structure competitive positioning without requiring uniform strategic approaches.
| Leading Market Players |
|---|
| Prysmian |
| Dyden |
| Phoenix Contact |
| Sinbon Electronics |
| Huber+Suhner |
| Aptiv |
| TE Connectivity |
| BRUGG |
| LEONI |
| Others |
Cost & Logistics Intelligence
Fleet operator consolidation around full-system procurement packages is forcing cable assemblers to absorb installation and maintenance costs into hardware pricing, compressing margin buffers and favoring suppliers with captive copper processing and connector fabrication capabilities.
Pricing Analysis
Margin tightening in liquid-cooled high-power configurations reflects copper price volatility exceeding thirty percent annually and the cost premium of F-Gas-compliant synthetic ester coolants. Pricing stratifies across liquid-cooled 350 kW corridor cables, standard AC Type 2 assemblies, and economy-grade residential tethered cables, with certification tier—UL versus CE marking versus GB standards—driving the steepest price differentiation. Cost compression accelerates in the AC residential segment as Chinese manufacturers expand export capacity. Fleet operators managing 500-plus vehicle electrification programs exhibit the lowest price sensitivity, prioritizing mean-time-between-failure guarantees over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Long Beach anchor hub-and-spoke patterns serving European, Asian, and North American demand clusters respectively. Manufacturing concentrates in China, Germany, and South Korea, with the Yangtze River Delta hosting the densest extrusion and connector fabrication capacity. Raw material sourcing draws from Chilean copper concentrate, South Korean silicone rubber compounds, and German precision connector components. Single-source vulnerability around liquid-cooling system integration—thermal management expertise imported from adjacent industries—creates bottleneck risk for 500-plus kW cable qualification. Distribution runs through Tier 1 industrial distributors and direct OEM supply contracts to charging network architects and fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Liquid-cooled conductor capacity scarcity props pricing for high-amperage assemblies, creating a supply-constrained environment where qualification timelines and thermal management expertise determine competitive access.
For Market Incumbents: Lock in long-term copper offtake agreements and backward integration into domestic extrusion capacity to defend margin position against IRA domestic content mandates and raw material volatility. Prioritize F-Gas-compliant coolant formulation R&D to preempt regulatory disqualification from German and Dutch highway corridor tenders. Certification investment in multi-standard UL-CE-GB qualification compresses launch cycles for multi-market suppliers. For New Entrants and Emerging Players: Charging network architects in India's Delhi-NCR corridor represent the most penetrable entry point, with PLI scheme tariff advantages reducing initial capital barriers for local conductor extrusion investment. Target second-life battery integration projects requiring hybrid AC/DC cable assemblies, a white-space segment with limited incumbent specialization. Pursue joint development agreements with municipal infrastructure planners rather than component-only sales to establish reference installations. For Investors and Strategic Acquirers: The window for entry favors connector-specialized electronics manufacturers with thermal management integration capabilities and RF-shielding design expertise. Mid-cap suppliers with captive silicone rubber compounding and established CE marking pathways offer the strongest five-to-ten year viability profiles as regulatory compliance timelines compress. Watch for F-Gas Regulation enforcement acceleration in Northern Europe as the inflection signal for coolant reformulation capability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Extrusion | IRA domestic content mandates require North American processing for federal subsidy eligibility. |
| Synthetic Ester Coolant Qualification | F-Gas Regulation prohibits hydrofluorocarbon dielectric fluids from 2027, compelling reformulation. |
| Multi-Standard Certification Investment | UL, CE marking, and GB qualification compresses product launch cycles by eight to fourteen months. |
| Fleet Operator Full-System Contracting | Performance-guaranteed supply agreements displace component-only purchasing in California and Germany. |
| RF-Shielded Cable Design Development | Electromagnetic interference mitigation unifies specifications for dense urban installations near broadcast infrastructure. |
Research Approach
Trade databases, customs records, and charging infrastructure deployment filings formed the secondary backbone, cross-referenced against primary interviews with charging network procurement directors, fleet operator electrification managers, cable assembler plant engineers, and thermal systems R&D leads. Bottom-up and top-down triangulation validated volume estimates across connector type, power rating, and regional regulatory cluster dimensions.
Bottom-up modeling segmented the market by product type, connector permanence, end-user scale, and application environment, while top-down analysis cross-checked against national electrification targets and fleet operator capex disclosures. CAGRs were derived from installation run-rate trajectories, municipal mandate compliance timelines, and copper price scenario modeling across the projection horizon. Forecast inputs incorporated IRA domestic content phase-in schedules, EU F-Gas Regulation enforcement calendars, and MIIT certification pathway timelines.
Caveats apply where copper price volatility, connector standard fragmentation, or cross-regional certification delays could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
EV Charging Kiosk Market
Electric Vehicle Charging
Heavy-Duty Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Charger Market
Electric Vehicle Charging
EV Charging Management Software Platform Market
Electric Vehicle Charging
Australia Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
EV DC Fast Charger Market
Electric Vehicle Charging
Electric Vehicle AC Charging Pile Market
Electric Vehicle Charging
High-Thermal-Conductivity Gap-Fill Adhesives for EV Battery Cooling Plates Market
Electric Vehicle Charging
US Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station Infrastructure Market
Electric Vehicle Charging
Smart EV Battery Charger Market
Electric Vehicle Charging
Metals in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station and Pile Operation and Management Market
Electric Vehicle Charging
HVAC Electronically Commutated Motor (ECM) Market
Electric Vehicle Charging
EV Charge Management Software Market
Electric Vehicle Charging
Electric Bus Charging Infrastructure Market