
 Global Waste-To-Energy Technologies Market | 2026-2036
Global Waste-To-Energy Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Global Waste-To-Energy Technologies Market Outlook
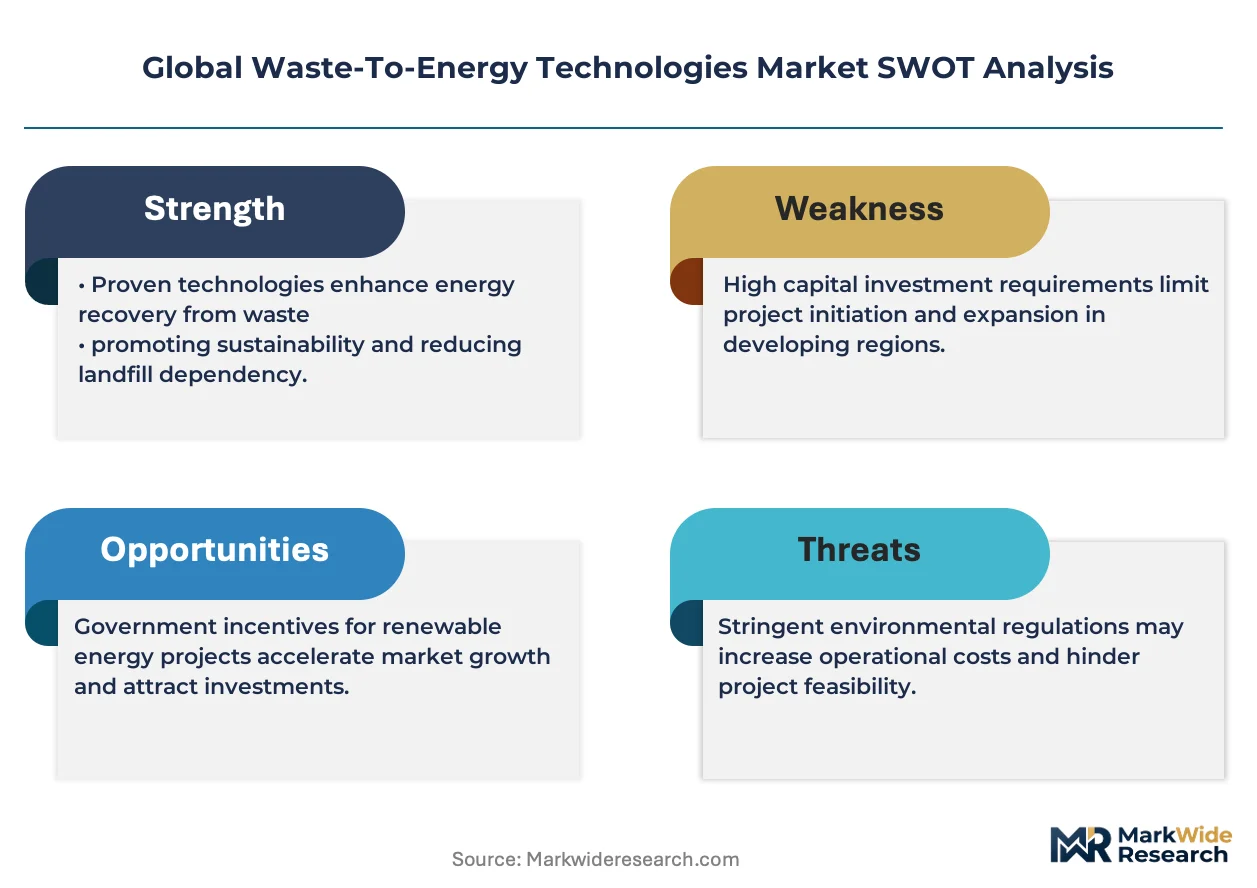
Multi-source equipment procurement is hardening across the waste-to-energy sector as project developers diversify engineering partners to mitigate construction risk. Veolia leverages its integrated service model across European municipal contracts. China Everbright Environment Group anchors expansion across Asia-Pacific with large-scale incineration deployments. Hitachi Zosen specializes in advanced stoker grate systems that sustain thermal efficiency in high-moisture waste streams.
Waste-to-energy technologies convert non-recyclable waste materials into usable heat, electricity, or fuel through thermochemical or biochemical processes, typically operating at combustion temperatures exceeding 850 degrees Celsius for complete flue gas oxidation. Incineration dominates current installed capacity due to proven reliability and grid-scale electricity output, while anaerobic digestion captures rising investment in organic waste streams where biomethane upgrades unlock renewable natural gas revenue. Gasification occupies a narrower but expanding niche in industrial waste applications requiring higher calorific value recovery.
The EU Green Deal and REACH frameworks enforce landfill diversion targets that directly mandate waste-to-energy capacity additions across member states. Japan's METI and China's MEE impose emission intensity standards that shape plant technology selection and air pollution control system specifications. Stakeholders must monitor evolving carbon accounting methodologies that could reclassify incineration emissions and redirect capital toward gasification and anaerobic digestion alternatives.
Market Dynamics
Stringent landfill diversion mandates under the EU Green Deal are forcing municipalities to accelerate incineration capacity procurement, while carbon accounting revisions threaten to reclassify emissions profiles and redirect capital toward gasification and anaerobic digestion alternatives.
Growth Catalysts
- EU Green Deal landfill targets:Member states must cut landfill disposal rates, compelling municipal procurement of thermal treatment capacity.
- Biomethane upgrading infrastructure:Organic waste streams now generate renewable natural gas revenue through anaerobic digestion with grid injection capability.
- Japan METI emission standards:Strict thermal efficiency requirements drive replacement of aging stoker systems with advanced grate configurations.
Market Restraints
- Construction cost volatility:Steel and specialized refractory material prices fluctuate, compressing developer margins on fixed-price EPC contracts.
- Residual ash disposal concentration:Hazardous bottom ash processing capacity clusters in Germany and the Netherlands, creating cross-border logistics bottlenecks.
- Electrostatic precipitator technical limits:Sub-10 micron particulate capture remains challenging for high-moisture municipal waste streams without activated carbon injection.
Strategic Opportunities
- Industrial waste gasification in China:Chemical and textile sectors seek higher calorific value recovery from sludge and solvent residues.
- Carbon capture retrofit readiness:New plants designed with post-combustion capture interfaces position operators for future compliance with evolving EU ETS methodologies.
- District heating integration:Scandinavian municipal utilities expand cogeneration tie-ins, displacing natural gas peaking capacity.
Industry Challenges
- Combustion engineering talent scarcity:Specialized stoker grate and flue gas treatment expertise concentrates among retiring European and Japanese technical staff.
- Air quality permitting timelines:Environmental impact assessments for greenfield sites extend 18-36 months in Germany and Japan.
- Legacy SCADA integration:Digital control upgrades for 1990s-vintage plants face protocol incompatibility with modern emissions monitoring networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Waste-To-Energy Technologies Market |
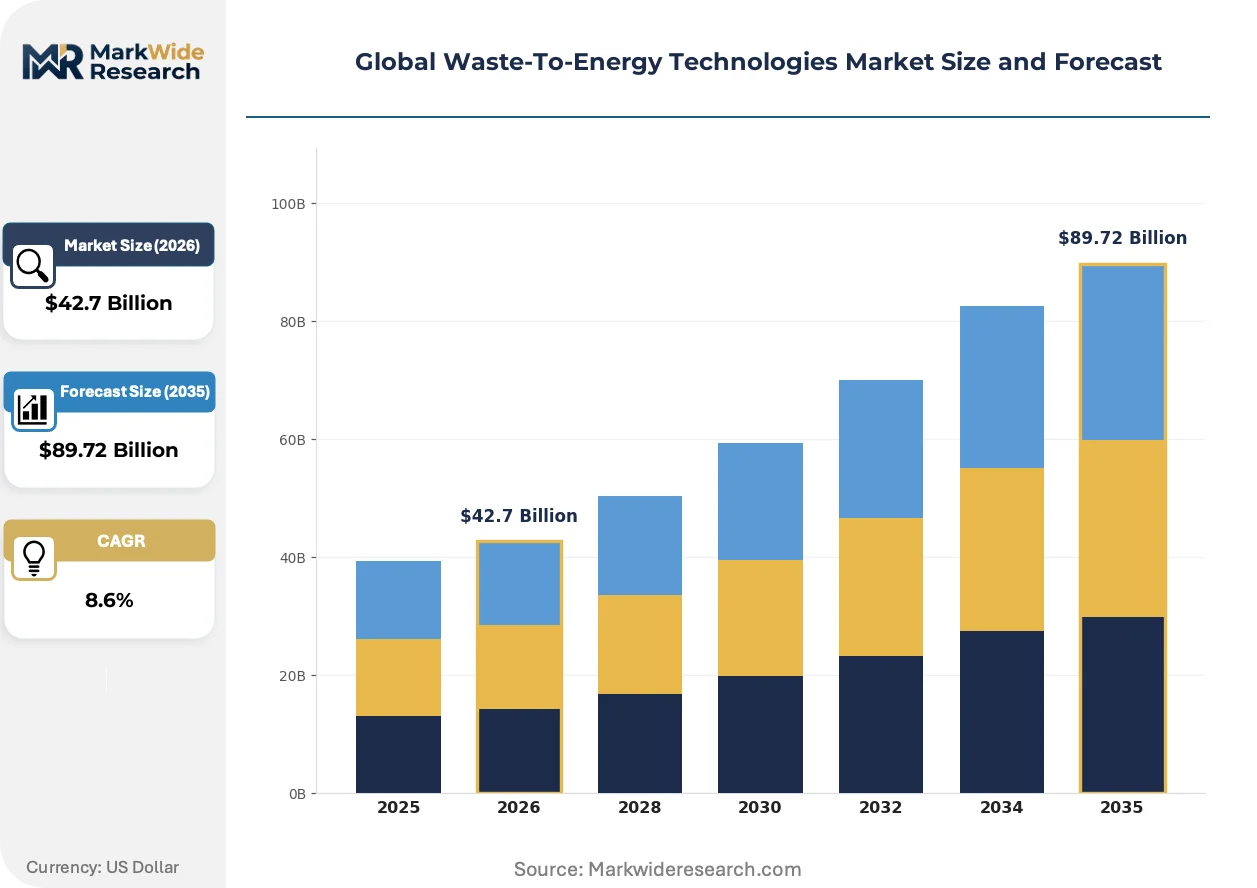
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $89.72 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Incineration, Anaerobic Digestion, Gasification, Pyrolysis Application: Municipal Solid Waste, Industrial Waste, Agricultural Residues, Hazardous Waste End User: Energy Producers, Waste Management Companies, Municipalities, Corporations Output Type: Electricity, Heat, Biofuels, Synthetic Natural Gas |
| Companies Covered | Veolia, Covanta, China Everbright Environment Group, SUEZ, AVR, Keppel Seghers, Hitachi Zosen, Wheelabrator Technologies, Ramboll Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Waste-To-Energy Technologies Market Strategic Shifts
Artificial intelligence is penetrating combustion control systems, enabling real-time thermal optimization that was previously impossible with manual operator adjustment.
Machine learning-based grate control is automating combustion air distribution across variable waste calorific inputs. German and Japanese operators deploy these systems to sustain thermal efficiency above 85% despite seasonal moisture fluctuations in municipal feedstock. The technology is compressing operator headcount requirements while improving emission stability.
REACH framework amendments are tightening persistent organic pollutant limits for flue gas residues. Industrial operators face mandatory activated carbon injection upgrades or alternative thermal treatment pathways. Medical waste incineration facilities in France and Belgium accelerate wet scrubber retrofits to meet revised dioxin thresholds.
Municipal procurement is consolidating toward 20-25 year service concessions with guaranteed throughput clauses. Single-source EPC contractors lose ground to consortiums pairing technology licensors with regional construction partners. This pattern concentrates in Poland and Italy where municipal debt capacity constraints favor off-balance-sheet project structures.
Global Waste-To-Energy Technologies Market Segmentation
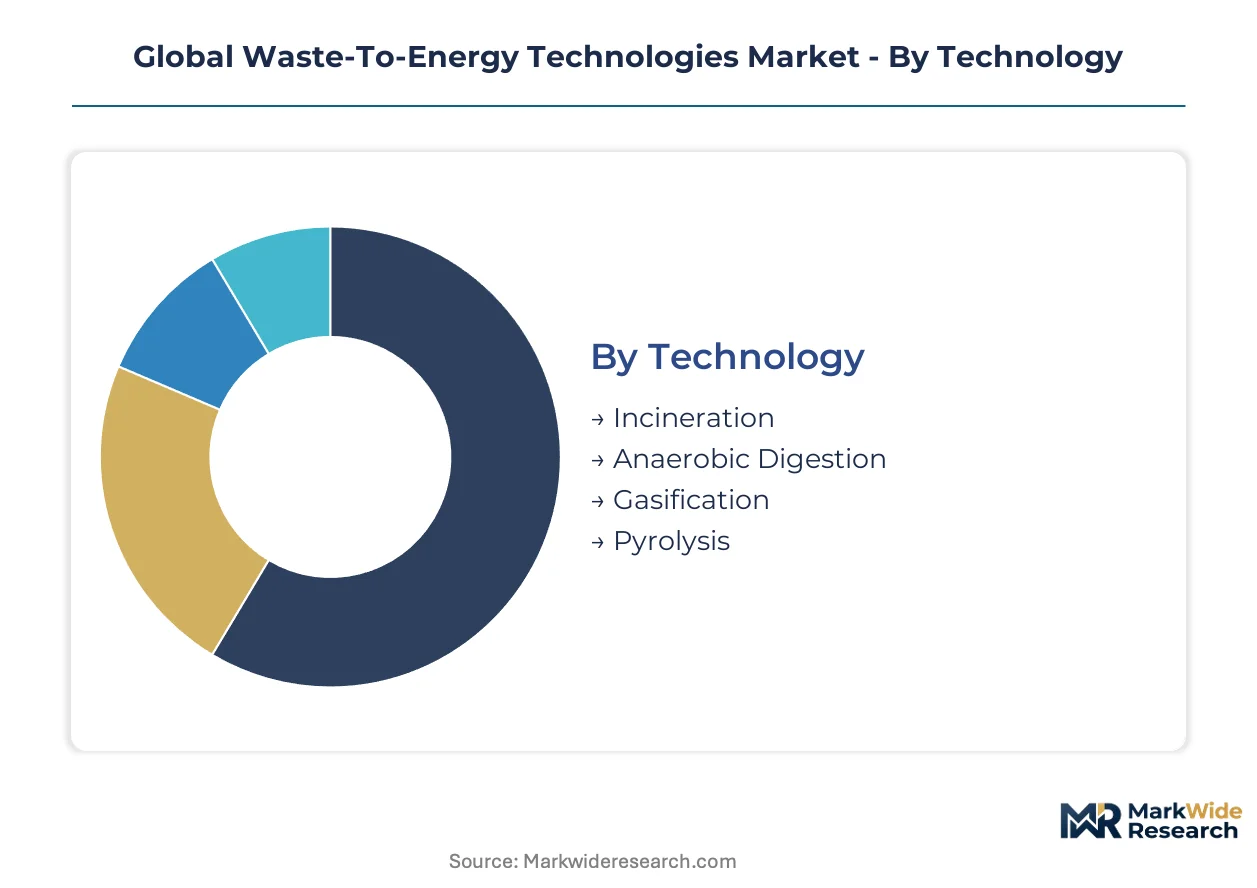
Waste-to-energy technologies fragment across four distinct dimensions that shape capital allocation and engineering procurement. Technology selection determines thermal efficiency and emission profiles. Application type dictates feedstock handling requirements and regulatory compliance burdens.
Technology:
Standardized grate configurations dominate municipal procurement, while specialized thermal pathways serve niche feedstock chemistries.
- Incineration:Mass-burn combustion with moving grate systems processes unsorted municipal solid waste at temperatures exceeding 850°C. Demand concentrates in Germany, Japan, and China where EU Green Deal landfill mandates and national emission standards enforce capacity additions. Thermal efficiency above 85% sustains project economics despite construction cost volatility.
- Anaerobic Digestion:Biochemical decomposition of organic waste streams produces biogas upgradable to biomethane for grid injection. Agricultural residues and food waste in France and Italy drive procurement, with renewable natural gas revenue streams improving project returns. Wet scrubber retrofits address REACH framework pollutant limits.
- Gasification:Partial oxidation converts carbonaceous materials into syngas for higher calorific value recovery. Industrial waste applications in China's chemical sector seek solvent residue processing.
- Pyrolysis:Thermal decomposition in oxygen-starved environments yields liquid bio-oil and char from plastic-rich waste streams. Pilot deployments focus on medical waste treatment in Belgium.
Most installed capacity flows through Incineration. Expansion is steepest in Anaerobic Digestion.
Application:
Volume concentration varies sharply by feedstock consistency and contamination levels.
- Municipal Solid Waste:Heterogeneous household and commercial refuse with moisture content fluctuating seasonally. Scandinavian district heating integration and Japanese METI efficiency standards drive grate system upgrades. Machine learning-based combustion control automates air distribution across variable calorific inputs.
- Industrial Waste:Manufacturing byproducts including sludge, solvents, and packaging residues with higher energy density. China's textile and chemical sectors seek gasification pathways for calorific value recovery. Hazardous classification triggers stricter air quality permitting timelines.
- Agricultural Residues:Crop straw, manure, and food processing waste with predictable seasonal availability. Italian and Polish biomethane upgrading infrastructure expands anaerobic digestion deployment.
- Hazardous Waste:Medical, pharmaceutical, and chemical discards requiring specialized thermal destruction. French and Belgian facilities accelerate wet scrubber retrofits to meet revised dioxin thresholds under REACH amendments.
Municipal Solid Waste commands the largest project pipeline. Industrial Waste applications are climbing the fastest.
End User:
Procurement sophistication divides between regulated utilities and merchant developers.
- Energy Producers:Grid-scale power generators seeking baseload renewable capacity. German municipal utilities prioritize cogeneration tie-ins displacing natural gas peaking plants.
- Waste Management Companies:Integrated service operators like Veolia leveraging long-term municipal concessions. Poland and Italy favor 20-25 year service contracts with guaranteed throughput clauses.
- Municipalities:Local governments mandated by EU Green Deal landfill diversion targets. Environmental impact assessments extend 18-36 months in Germany and Japan.
- Corporations:Industrial emitters securing captive waste disposal and energy recovery. Carbon capture retrofit readiness shapes technology selection for future EU ETS compliance.
Waste Management Companies control the dominant share of contracted capacity. Municipalities are gaining share fastest as procurement accelerates under regulatory mandates.
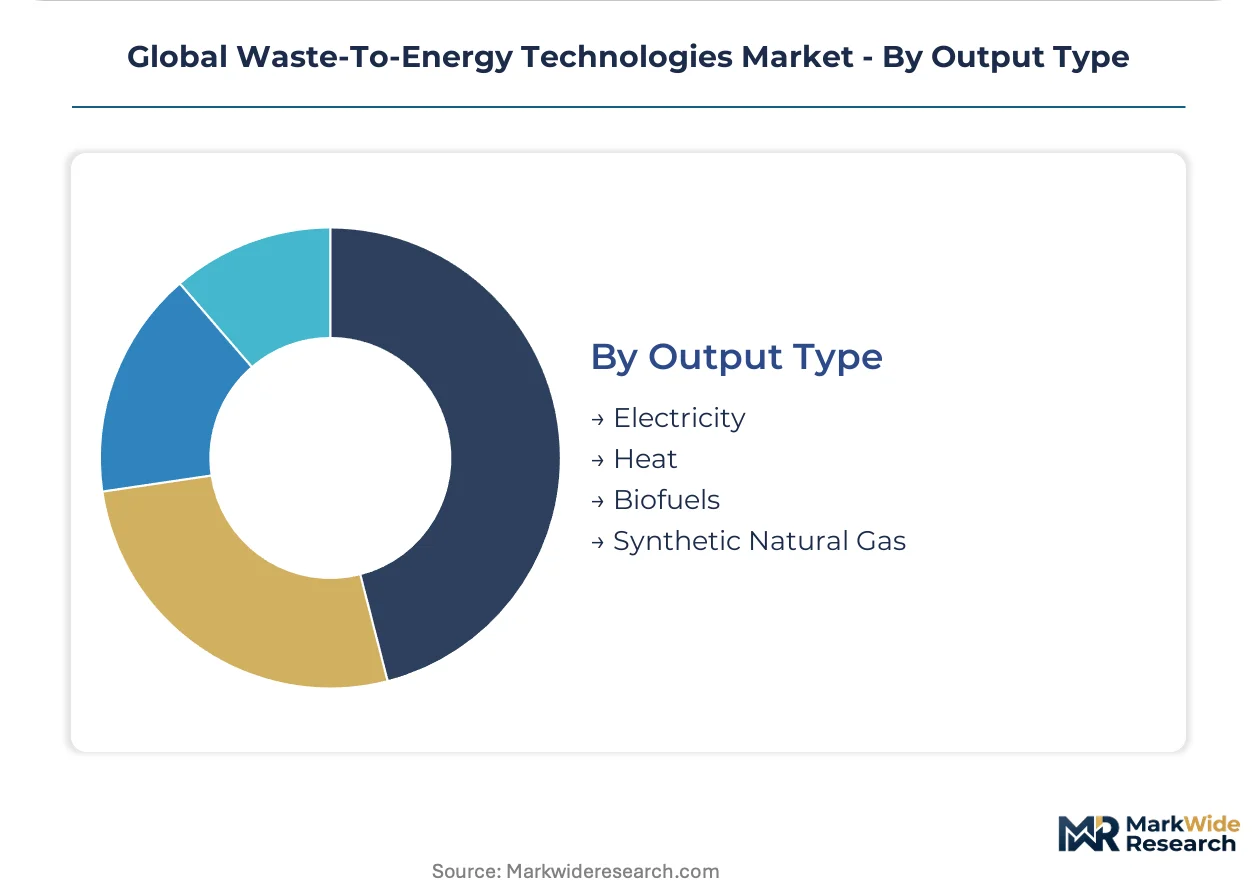
Output Type:
Revenue model stability differs between regulated grid sales and volatile commodity markets.
- Electricity:Grid-scale power generation with feed-in tariff or merchant pricing exposure. Incineration plants in Japan and China optimize for thermal efficiency under METI and MEE emission standards.
- Heat:District heating network supply with long-term municipal utility offtake. Scandinavian cogeneration expansion displaces natural gas peaking capacity.
- Biofuels:Liquid and gaseous fuel products from anaerobic digestion and pyrolysis pathways. Biomethane upgrading infrastructure in France and Italy enables renewable natural gas grid injection.
- Synthetic Natural Gas:Methanated syngas from gasification processes matching pipeline specifications. Industrial pilot projects in China test chemical sector integration.
Electricity dominates current revenue streams. Heat applications are expanding most quickly through district heating network tie-ins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting waste-to-energy investment toward jurisdictions where landfill diversion mandates create guaranteed offtake, while carbon accounting uncertainty in the EU is slowing some capital commitments relative to Asian markets with clearer operational frameworks.
Germany
Municipal utilities in North Rhine-Westphalia and Bavaria are expanding district heating tie-ins to existing incineration plants. The country's Federal Immission Control Act enforces emission standards that exceed EU baseline requirements. The Rhine-Ruhr metropolitan cluster hosts Europe's densest concentration of hazardous bottom ash processing capacity, creating cross-border logistics bottlenecks for neighboring states.
China
Provincial governments in Jiangsu and Zhejiang provinces are procuring large-scale grate systems under MEE emission intensity standards. The Ministry of Ecology and Environment imposes thermal efficiency benchmarks that shape plant technology selection. The Yangtze River Delta corridor anchors Asia-Pacific capacity expansion, with municipal contracts concentrating in Shanghai and Suzhou industrial zones.
Japan
Metropolitan Tokyo and Osaka prefectures are replacing aging stoker systems under METI efficiency mandates. The Ministry of Economy, Trade and Industry enforces strict thermal performance requirements that drive advanced grate configuration adoption. The Chubu region around Nagoya hosts specialized combustion engineering expertise concentrated among technical staff nearing retirement.
France
Waste management concessions in Île-de-France are consolidating toward 20-25 year service contracts with guaranteed throughput clauses. The country's environmental regulator enforces REACH framework amendments tightening persistent organic pollutant limits. Medical waste incineration facilities in the Paris basin are accelerating wet scrubber retrofits to meet revised dioxin thresholds.
United States
Merchant developers in the Northeast and Mid-Atlantic are pursuing carbon capture retrofit readiness for new plant designs. EPA emission standards under the Clean Air Act shape air pollution control system specifications. The New York metropolitan area hosts legacy SCADA infrastructure requiring digital control upgrades to interface with modern emissions monitoring networks.
Global Waste-To-Energy Technologies Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue gasification and anaerobic digestion specializations where carbon accounting advantages may emerge. The market structures around three tiers: integrated service operators with municipal concession depth, technology licensors with combustion engineering expertise, and regional construction consortiums pairing EPC capability with local permitting knowledge. Consolidation pressure favors multi-source equipment procurement as project developers diversify engineering partners. Dominant competitive moves include strategic partnerships between technology licensors and regional builders, plus capacity expansion into district heating integration.
Within the integrated service tier, Veolia and SUEZ exemplify operators leveraging long-term municipal relationships across European markets. Hitachi Zosen occupies a position among specialized combustion engineering licensors, with its company name indicating Japanese origin and technical focus on thermal treatment systems. China Everbright Environment Group represents the scale-driven archetype, with its naming structure indicating Chinese state-linked capacity for large-scale infrastructure deployment across Asia-Pacific markets.
| Leading Market Players |
|---|
| Veolia |
| Covanta |
| China Everbright Environment Group |
| SUEZ |
| AVR |
| Keppel Seghers |
| Hitachi Zosen |
| Wheelabrator Technologies |
| Ramboll Group |
| Others |
Value Chain & Pricing Dynamics
Municipal utility procurement concentration across Germany, Japan, and China anchors long-term offtake contracting as the dominant pricing model, with 20-25 year service concessions embedding guaranteed throughput clauses that insulate developers from commodity electricity price swings. Steel and specialized refractory material cost volatility feeds directly into EPC margin compression, forcing project developers toward multi-source equipment procurement to distribute construction risk.
Pricing Analysis
Direct-to-municipal contracting with zero intermediary margin layers dominates project economics, though EPC consortiums capture construction-phase value through technology licensing fees. Price differentiation rests on thermal efficiency certification tiers and district heating integration depth, with Scandinavian cogeneration tie-ins commanding premium valuations. Cost compression in fixed-price EPC contracts is intensifying because steel and refractory input volatility has eliminated contingency buffers. Municipalities in Poland and Italy exhibit highest price sensitivity due to debt capacity constraints, while German utilities demonstrate lowest sensitivity given guaranteed cost-pass-through mechanisms under Federal Immission Control Act frameworks.
Supply Chain Analysis
Cross-border freight costs for hazardous bottom ash concentrate flows between Germany and the Netherlands create logistics chokepoints that elevate disposal pricing for neighboring states. Manufacturing of advanced stoker grate systems concentrates in Japan and Germany, while China anchors steel superstructure and emissions control component fabrication. Raw material dependencies span nickel-alloy grate bars, ceramic refractory linings, and activated carbon injection media. Single-source vulnerability concentrates in specialized combustion engineering expertise among retiring European and Japanese technical staff. Distribution runs through EPC consortiums pairing technology licensors with regional construction partners possessing local permitting knowledge.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal landfill diversion mandate compounds procurement velocity across member states, creating regulatory-guaranteed demand visibility that distinguishes this market from merchant-driven energy infrastructure.
For Market Incumbents: Acquire district heating network infrastructure in Scandinavian municipalities to lock in cogeneration revenue streams. Integrate carbon capture retrofit interfaces into new plant designs to preempt EU ETS methodology shifts that could reclassify incineration emissions. Position against emerging gasification entrants by emphasizing proven grid-scale reliability under METI and MEE thermal efficiency benchmarks. For New Entrants and Emerging Players: Machine learning-based combustion control systems offer technology-first entry into municipal grate upgrade cycles. White-space targets concentrate in China's industrial waste gasification segment, where chemical and textile sectors seek higher calorific value recovery from solvent residues. Agricultural residue biomethane upgrading in Poland and Italy presents penetrable geography given renewable natural gas revenue stream maturity. Pursue licensing partnerships with regional EPC contractors to bypass 18-36 month air quality permitting timelines. For Investors and Strategic Acquirers: Integrated waste management operators are the most active acquirer in this space, consolidating municipal concession portfolios across European markets. Long-term viability hinges on carbon accounting methodology stability over the 5-10 year regulatory horizon. Target acquisition archetypes include anaerobic digestion technology licensors with biomethane grid injection capabilities. Monitor EU ETS carbon price trajectory as the critical inflection signal for capital redirection toward gasification and anaerobic digestion alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Readiness | New plant designs with post-combustion interfaces position operators for future EU ETS compliance methodologies. |
| District Heating Network Integration | Scandinavian municipal utilities expand cogeneration tie-ins, displacing natural gas peaking capacity. |
| Machine Learning Combustion Control | German and Japanese operators deploy automated grate systems to sustain thermal efficiency above 85%. |
| Biomethane Upgrading Infrastructure | French and Italian agricultural residue processors unlock renewable natural gas grid injection revenue. |
| Multi-Source EPC Consortium Formation | Project developers diversify engineering partners to mitigate construction cost volatility exposure. |
Study Parameters
Bottom-up municipal procurement tracking reconciled against top-down EPC contractor capacity pipelines forms the analytical core of this study. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators combined with secondary validation from EIA data, IEA reports, FERC filings, and project development databases. Triangulation across stakeholder inputs and regulatory filing analysis ensures segment-level precision.
Input-output matrices model waste throughput volumes against technology-specific conversion efficiencies and output revenue streams across the projection horizon. Segmentation dimensions span technology pathway, feedstock application, end-user procurement model, and output type, with regional regulatory framework clusters as an additional modeling layer. CAGRs derive from installed capacity addition trajectories under EU Green Deal, METI, and MEE mandate schedules, cross-referenced against construction cost indices and steel price volatility assumptions.
The model holds under continued landfill diversion mandate enforcement; deviation in carbon accounting reclassification timelines or EU ETS methodology shifts would redirect capital allocation forecasts. Stakeholders should weight assumptions against their own operating context and regulatory jurisdiction exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste to Energy Systems
Brazil Waste to Energy Market
Waste to Energy Systems
Nuclear Waste Recycling Market
Waste to Energy Systems
Germany Waste-To-Energy Market
Waste to Energy Systems
Waste to Energy (WTE) Market
Waste to Energy Systems
Japan Waste to Energy Market
Waste to Energy Systems
ORC Industrial Waste Heat to Power Market
Waste to Energy Systems
Anaerobic Digestion Equipment Market
Waste to Energy Systems
APAC Waste Heat Recovery Systems Market
Waste to Energy Systems
Agricultural Waste to Energy Market
Waste to Energy Systems
Waste to Diesel Market
Waste to Energy Systems
Nuclear Waste Management Market
Waste to Energy Systems
Asia-Pacific Waste-To-Energy Market
Waste to Energy Systems
Waste Heat to Power Market
Waste to Energy Systems
Shipboard Incineration Market
Waste to Energy Systems
North America Waste to Energy Market
Waste to Energy Systems
Austria Waste to Energy Market