
 Modular Energy Control System Market | 2026-2036
Modular Energy Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Modular Energy Control System Market Foresight
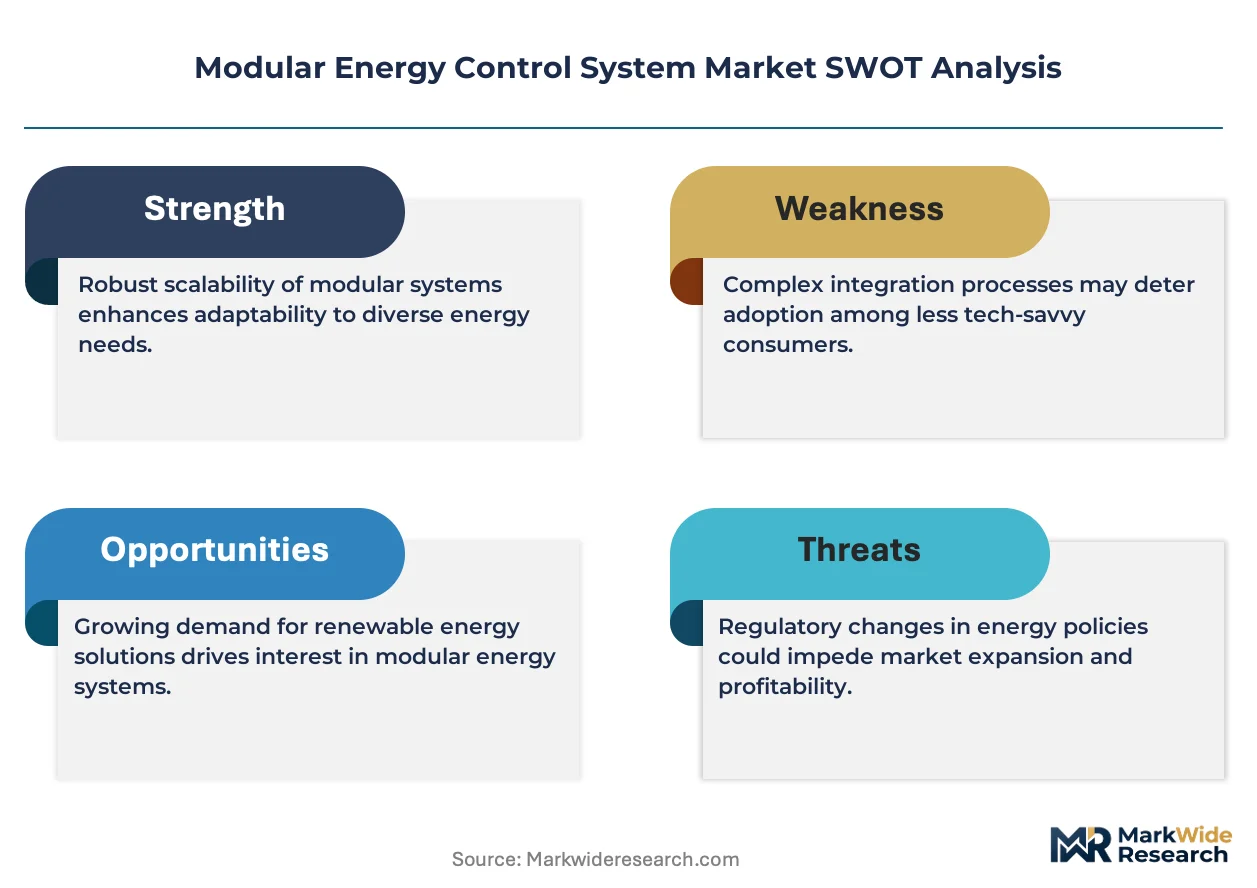
Product unbundling into interoperable hardware-software modules is broadening buyer choice across utility and industrial procurement teams. Siemens leverages its manufacturing scale to dominate European utility retrofit programs. Schneider Electric anchors its position through deep channel control in commercial building automation. ABB competes via technology leadership in marine and offshore microgrid configurations.
A modular energy control system integrates distributed sensing, communication gateways, and algorithmic load-balancing software within standardized enclosure formats, typically operating across 480V to 34.5kV interfaces to enable real-time coordination of generation, storage, and consumption assets. Energy Management Systems occupy the largest margin pool due to recurring software licensing and firmware update revenue attached to hardware deployments. IoT Platforms represent the fastest-expanding technology layer as edge computing architectures displace centralized SCADA polling cycles in utility-scale installations.
FERC Order 2222 in the United States mandates regional grid operators to accommodate aggregated distributed energy resources, directly expanding addressable demand for modular control interfaces. The EU Green Deal and F-Gas Regulation together enforce efficiency benchmarks and refrigerant-phaseout timelines that force building energy retrofits toward intelligent control retrofits. Stakeholders must monitor how NERC CIP cybersecurity standards evolve to determine whether compliance costs favor integrated platform vendors or specialized security module suppliers.
Market Dynamics
Grid decentralization is fragmenting control architectures into interoperable hardware-software modules, forcing incumbent vendors to unbundle vertically integrated platforms or surrender procurement decisions to systems integrators.
Growth Catalysts
- FERC Order 2222:This US mandate requires regional transmission organizations to accommodate aggregated distributed energy resources, directly expanding procurement volumes for modular control interfaces in Texas and California.
- EU Green Deal efficiency benchmarks:Building retrofit mandates across Germany and France are accelerating replacement of legacy building management systems with intelligent control modules.
- Edge computing architectures:Real-time load balancing at the substation level is displacing centralized SCADA polling cycles, creating pull for distributed sensing and communication gateways.
Market Restraints
- Semiconductor supply concentration:Power electronics and communication chip fabrication concentrates in East Asian foundries, exposing lead times to geopolitical friction.
- Copper and rare earth input volatility:Enclosure busbars and magnetic components face price swings that compress hardware margins.
- NERC CIP compliance complexity:Cybersecurity certification timelines for critical infrastructure applications extend sales cycles by twelve to eighteen months.
Strategic Opportunities
- India distributed solar integration:State-level renewable purchase obligations and CEA grid codes are creating virgin demand for rural microgrid control systems.
- Marine and offshore microgrids:Vessel electrification and port shore-power mandates are opening specialized application segments with premium pricing tolerance.
- IoT platform convergence:Digital twin and predictive maintenance software layers are attaching recurring revenue streams to hardware deployments.
Industry Challenges
- Cybersecurity talent scarcity:Embedded systems security engineering and firmware cryptography expertise remains concentrated among defense contractors and specialized consultancies.
- Legacy SCADA integration friction:Proprietary protocols in existing utility infrastructure resist standardization, forcing costly custom gateway development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular Energy Control System Market |
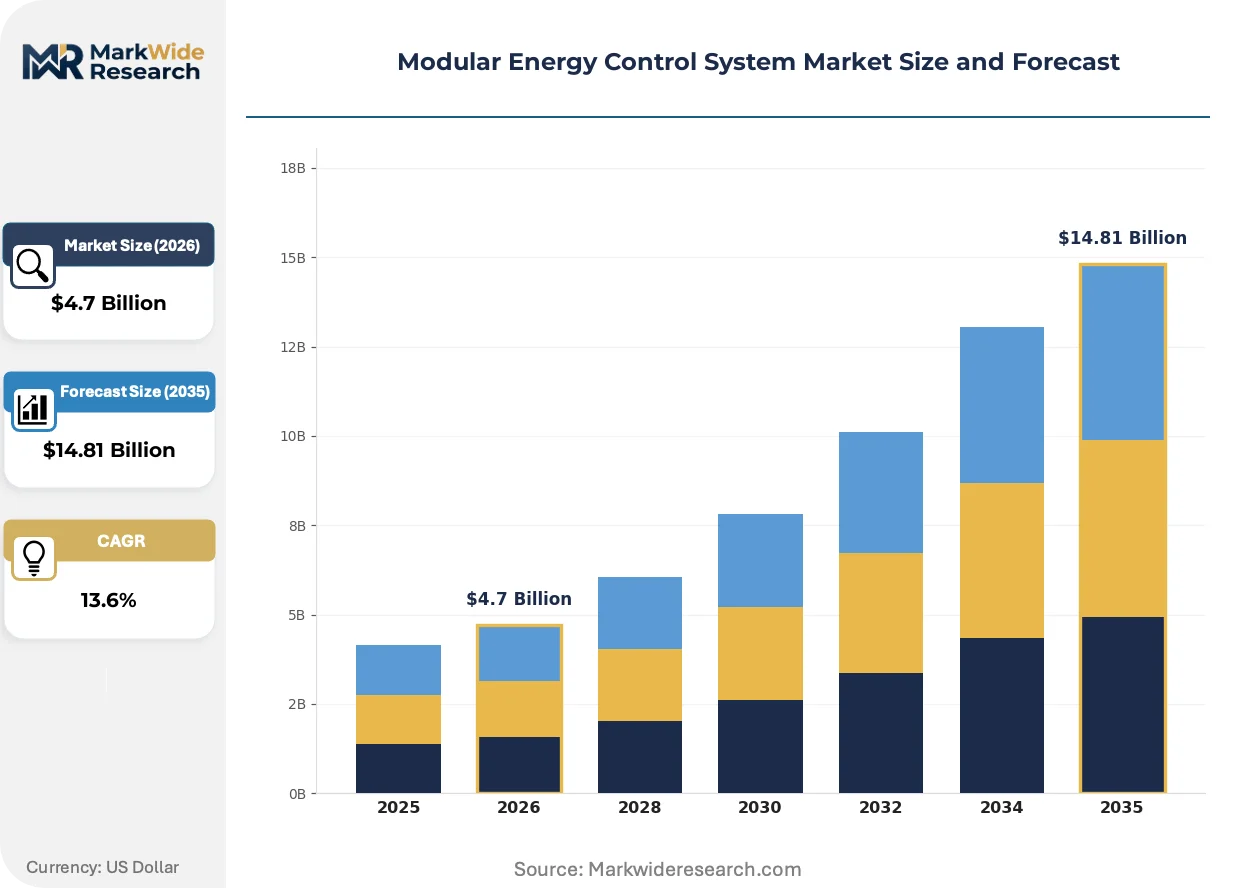
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $14.81 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Energy Management Systems, Smart Grid Solutions, Demand Response Systems, Distributed Energy Resources Technology: IoT Platforms, Artificial Intelligence, Blockchain, Cloud Computing End User: Commercial, Industrial, Residential, Utilities Installation: Onsite, Remote, Hybrid, Integrated |
| Companies Covered | Siemens, Schneider Electric, ABB, Honeywell, Johnson Controls, Emerson, Rockwell Automation, General Electric, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular Energy Control System Market Shifts & Advancements
Algorithmic load-balancing software is migrating from cloud data centers to edge devices, compressing response latency and enabling autonomous microgrid islanding decisions without upstream polling.
Distributed energy resource management systems are converging with building automation protocols, enabling commercial facility managers in California and Germany to coordinate on-site solar, storage, and HVAC loads through unified dashboards rather than siloed control planes.
The EU F-Gas Regulation is accelerating refrigerant-phaseout timelines that force building energy retrofits toward intelligent control retrofits, with German facility operators replacing pneumatic thermostats with digital valve actuators and zone-level sensors to maintain efficiency compliance.
Utility procurement teams are unbundling hardware specifications from software licensing, with Texas municipal utilities and California community choice aggregators separately sourcing enclosure hardware from electrical distributors while subscribing to firmware and optimization algorithms from specialized software vendors.
Modular Energy Control System Market Segmentation
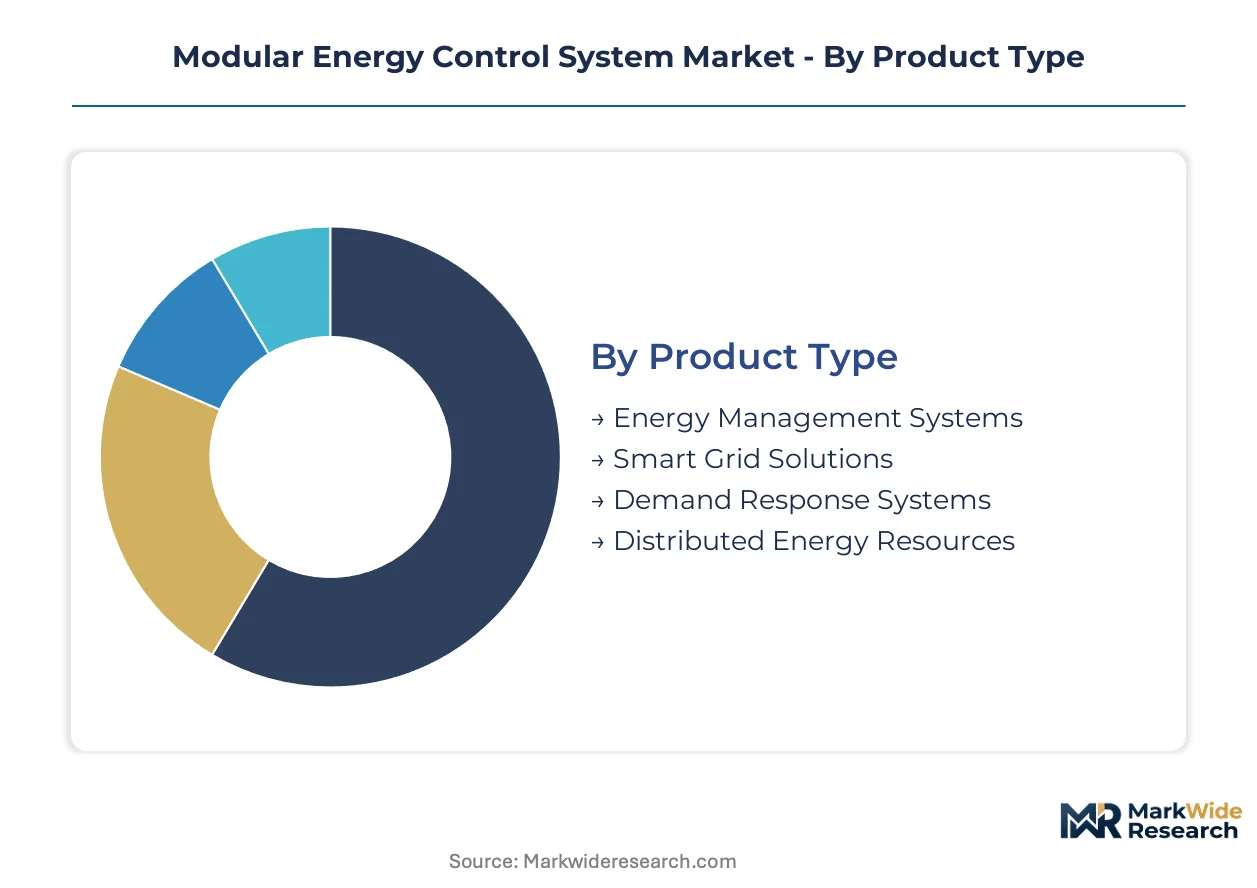
Modular energy control systems fragment into distinct procurement categories that reflect divergent upgrade cycles across hardware, software, and service layers. Buyers prioritize segments based on legacy infrastructure age, regulatory compliance deadlines, and the availability of interoperable replacement modules.
Product Type:
Replacement cycles vary dramatically across product categories, with software-intensive systems refreshing every 3-5 years while hardware enclosures persist for 15-20 years in utility substations.
- Energy Management Systems:These platforms integrate algorithmic load-balancing software with firmware update capabilities, generating recurring licensing revenue. Demand concentrates in German industrial facilities facing EU Green Deal efficiency mandates and Texas utilities responding to FERC Order 2222 aggregation requirements.
- Smart Grid Solutions:Communication gateways and distributed sensing modules enable real-time coordination across 480V to 34.5kV interfaces. California community choice aggregators and North American municipal utilities drive procurement as grid decentralization intensifies.
- Demand Response Systems:Automated curtailment controllers for commercial and industrial loads.
- Distributed Energy Resources:Modular interfaces for solar, storage, and backup generation asset coordination.
Energy Management Systems sits at the top of the volume ranking, with Smart Grid Solutions climbing the fastest.
Technology:
Technology selection hinges on latency requirements and cybersecurity posture, with edge architectures displacing centralized polling cycles in performance-critical applications.
- IoT Platforms:Edge computing architectures compress response latency for autonomous microgrid islanding decisions. German building automation retrofits and Texas utility-scale installations represent the primary demand concentration as edge devices displace centralized SCADA polling.
- Artificial Intelligence:Predictive maintenance algorithms and digital twin software layers attach recurring revenue to hardware deployments. Marine and offshore microgrid configurations leverage AI for vessel electrification and port shore-power optimization.
- Blockchain:Distributed ledger protocols for peer-to-peer energy trading verification.
- Cloud Computing:Centralized data aggregation and long-term analytics storage.
IoT Platforms commands the largest deployment base, while Artificial Intelligence gains share fastest through predictive maintenance attach rates.
End User:
End-user segments diverge in procurement sophistication, with utilities favoring unbundled hardware-software sourcing while commercial buyers prioritize unified dashboard integration.
- Commercial:Facility managers in California and Germany coordinate on-site solar, storage, and HVAC loads through converged building automation protocols. EU F-Gas Regulation refrigerant-phaseout timelines force pneumatic thermostat replacements with digital valve actuators and zone-level sensors.
- Utilities:Procurement teams unbundle enclosure specifications from software licensing, with Texas municipal utilities separately sourcing hardware from electrical distributors while subscribing to optimization algorithms from specialized vendors.
- Industrial:Manufacturing facilities with captive generation and high-reliability requirements.
- Residential:Single-home energy management through utility-sponsored demand response programs.
Utilities anchors procurement volume, with Commercial expanding most quickly through building retrofit mandates.
Installation:
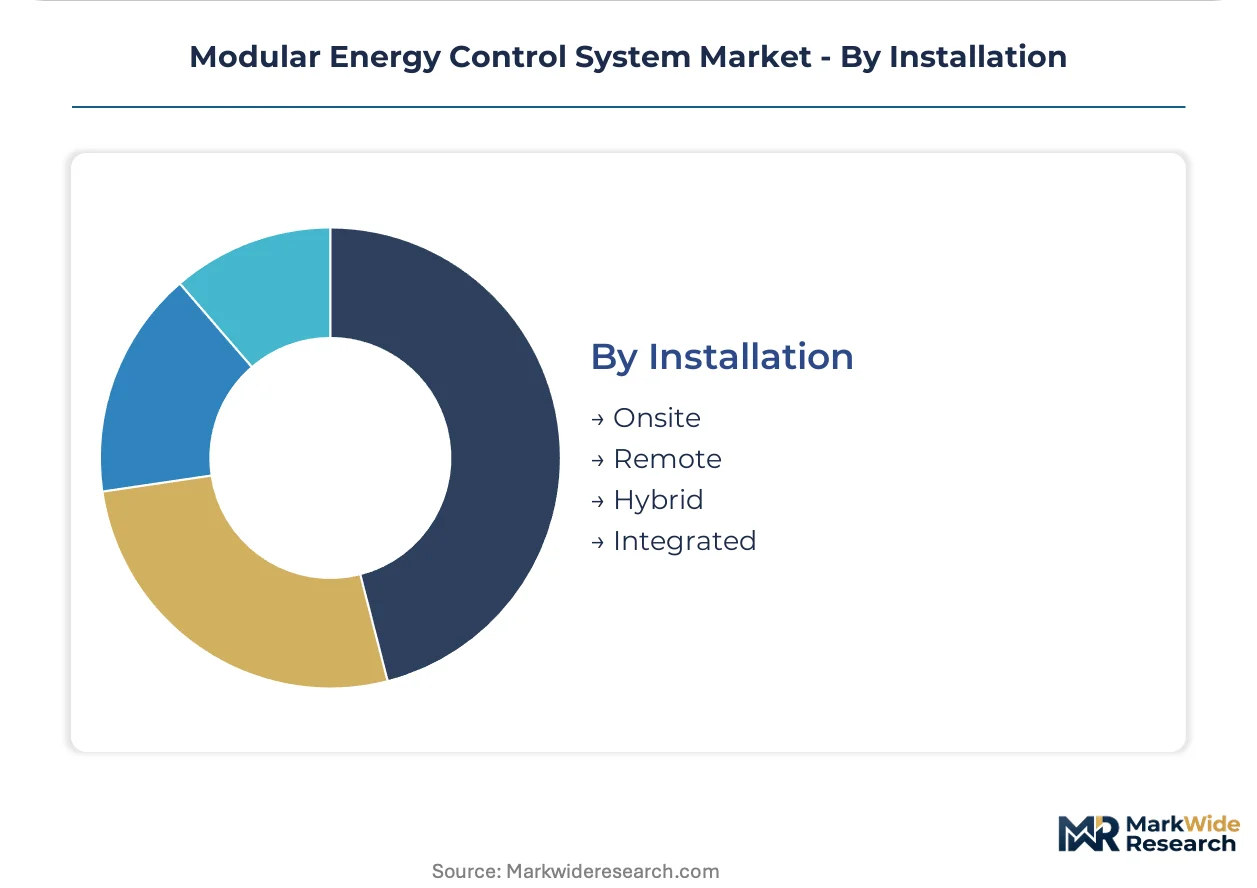
Installation modality selection reflects workforce availability, cybersecurity perimeter requirements, and the physical accessibility of target infrastructure.
- Onsite:Local hardware deployment with dedicated maintenance access. Critical infrastructure applications in Texas and California favor onsite configurations to satisfy NERC CIP cybersecurity perimeter requirements despite higher labor costs.
- Remote:Centralized monitoring with limited local intervention. German commercial building operators leverage remote installation for distributed facility portfolios where travel time dominates service economics.
- Hybrid:Edge processing with cloud backup and remote override capabilities.
- Integrated:Factory-preconfigured systems combining hardware, software, and commissioning services.
Onsite retains the largest installed base, with Hybrid gaining traction fastest through edge-cloud architecture convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The modular energy control system industry traces its commercial origins to German industrial automation clusters in the 1990s, where standardized enclosure formats for substation coordination first achieved scale. Utility procurement patterns subsequently diffused through North American and Asian markets as grid decentralization intensified.
United States
Texas municipal utilities and California community choice aggregators drive procurement volumes for distributed sensing modules. FERC Order 2222 mandates regional transmission organizations to accommodate aggregated distributed energy resources, expanding addressable demand. The ERCOT grid in Texas and CAISO territory in California concentrate deployment activity.
Germany
Industrial facilities across the Rhine-Ruhr and Bavaria regions retrofit legacy building management systems with intelligent control modules. The EU Green Deal and F-Gas Regulation enforce efficiency benchmarks and refrigerant-phaseout timelines. Stuttgart and Munich anchor demand for digital valve actuators and zone-level sensors.
China
State Grid Corporation procurement of substation automation equipment scales deployment of communication gateways and edge computing architectures. MIIT industrial internet standards and dual carbon goals accelerate intelligent grid investment. The Yangtze River Delta and Pearl River Delta clusters concentrate manufacturing and deployment.
India
State-level renewable purchase obligations and CEA grid codes create virgin demand for rural microgrid control systems. The national solar mission and rural electrification programs expand addressable infrastructure. Gujarat and Rajasthan concentrate distributed solar integration projects.
Japan
Island grid operators deploy autonomous microgrid islanding systems for resilience against natural disasters. METI strategic energy plan targets and JIS standardization frameworks shape procurement specifications. The Kanto and Kyushu regions concentrate demonstration projects and commercial deployment.
Modular Energy Control System Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive electrical distribution channels. Incumbent vendors maintain position through manufacturing scale and deep channel relationships rather than technology exclusivity. Three archetypes dominate: integrated automation platforms, specialized power management suppliers, and building controls specialists. Competitive dynamics center on portfolio unbundling to accommodate utility procurement preferences and strategic partnerships with systems integrators.
Among European-based industrial conglomerates, Siemens and ABB occupy positions representing integrated platform breadth, while Schneider Electric exemplifies channel-anchored building automation specialization. These three entities anchor the competitive landscape through distinct strategic postures rather than overlapping market pursuit.
| Leading Market Players |
|---|
| Siemens |
| Schneider Electric |
| ABB |
| Honeywell |
| Johnson Controls |
| Emerson |
| Rockwell Automation |
| General Electric |
| Eaton |
| Others |
Supply & Pricing Matrix
EU Green Deal efficiency benchmarks gate qualified supply and premium-tier pricing access by mandating certified intelligent control modules for building retrofits across Germany and France, restricting vendor participation to those with CE-marked firmware and validated interoperability protocols.
Pricing Analysis
Subscription-based SaaS tiering dominates procurement contracts, separating enclosure hardware from recurring firmware licensing and algorithm optimization fees. Price differentiation hinges on NERC CIP cybersecurity certification grade and volume scale, with Texas municipal utilities commanding standard-tier rates while California community choice aggregators absorb premium pricing for enhanced edge-computing capabilities. Cost compression in economy hardware tiers is intensifying because copper busbar and rare earth magnet input volatility compresses margins. Commercial facility managers in Germany exhibit highest price sensitivity due to F-Gas Regulation compliance deadlines, whereas marine and offshore microgrid operators demonstrate lowest sensitivity given premium pricing tolerance for specialized configurations.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale procurement for Texas and California grid operators, while electrical distributors serve fragmented commercial building demand across Germany. Manufacturing concentrates in China for communication gateways and edge computing hardware, Germany for precision enclosure fabrication, and the United States for NERC-certified cybersecurity modules. Power electronics and semiconductor components draw from Taiwanese foundries and South Korean memory suppliers. Single-source vulnerability in East Asian chip fabrication exposes lead times to geopolitical friction. Distribution runs through systems integrators for utility-scale deployments and building automation specialists for commercial retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where German industrial automation expertise commands premium pricing against cost-optimized Asian manufacturing, with regulatory compliance differentials between EU Green Deal mandates and US FERC Order 2222 creating divergent margin structures.
For Market Incumbents: Cement manufacturing scale advantages in European utility retrofit programs through captive channel relationships with German electrical distributors. Deepen backward integration into edge computing semiconductor sourcing to offset East Asian foundry concentration risk. Prioritize NERC CIP certification investment as cybersecurity talent scarcity threatens compliance timelines for critical infrastructure applications. For New Entrants and Emerging Players: The premium-to-economy pricing gap in IoT platform software licensing creates entry opportunity for specialized algorithm vendors unbundled from hardware incumbents. Target India rural microgrid control systems as the most penetrable geography given virgin demand from state-level renewable purchase obligations. Pursue partnership-based go-to-market angles with State Grid Corporation procurement channels in China. For Investors and Strategic Acquirers: Roll-up economics work for specialized cybersecurity module suppliers because NERC CIP compliance complexity extends sales cycles and favors consolidated vendors with dedicated certification expertise. Long-term viability centers on recurring software attach rates rather than hardware replacement cycles. Watch FERC Order 2222 implementation velocity across ERCOT and CAISO territories as the signal for modular control interface demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Architecture Migration | Texas utilities displace centralized SCADA polling with autonomous substation-level processing. |
| NERC CIP Certification Investment | Cybersecurity compliance timelines favor vendors with pre-validated firmware cryptography. |
| Building Automation Protocol Convergence | German facility operators unify HVAC and solar coordination through integrated dashboards. |
| Marine Microgrid Specialization | Vessel electrification mandates in European ports create premium pricing tolerance segments. |
| India Distribution Partnership | State-level renewable obligations in Gujarat and Rajasthan open virgin rural infrastructure demand. |
Research Methodology
Multiple input streams — primary interviews with utility planning officers, IPP project developers, and EPC contractors; secondary validation against FERC filings, EIA data, and IEA grid investment reports; and customs records for power electronics trade flows — were reconciled through bottom-up project pipeline enumeration and top-down market sizing triangulation.
Historical deployment trajectories were cross-referenced against expert panel inputs across product type, technology layer, end-user segment, installation modality, and regional regulatory framework dimensions. CAGRs were derived from segment-level growth rate reconciliation with macro grid investment indicators. Forecast inputs incorporated FERC Order 2222 aggregation mandate implementation schedules and EU Green Deal retrofit obligation timelines.
Caveats apply where semiconductor supply disruption, copper price volatility, or NERC CIP standard evolution could materially shift the outlook for hardware margin structures and vendor competitive positioning. Periodic stress-testing of base assumptions against regulatory implementation velocity and raw material input trajectories is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Control Solutions
Bin Vent Filter Market
Environmental Control Solutions
Natural Refrigerants Market
Environmental Control Solutions
Gas Cleaning Technologies Market
Environmental Control Solutions
Global Flue Gas Desulphurization Market
Environmental Control Solutions
Sailboat Ballast Water Treatment Technology Market
Environmental Control Solutions
Vapor Recovery Services Market
Environmental Control Solutions
Global Leak Detection and Repair (LDAR) Market
Environmental Control Solutions
Enclosed Waste Gas Flares Market
Environmental Control Solutions
CO2 Injector (CO2 Bubbler) Market
Environmental Control Solutions
Residential Water Softening Systems Market
Environmental Control Solutions
Flue Gas Analyzers Market
Environmental Control Solutions
Global Portable Emissions Measurement Systems (PEMS) Market
Environmental Control Solutions
Global Ballast Water Treatment Systems Market
Environmental Control Solutions
Manufacturing Scale Electrostatic Precipitator Market
Environmental Control Solutions
North America Nitrogen Oxide Control Systems Market
Environmental Control Solutions
Scrubber System Market